
 Italy Gluten-Free Foods and Beverages Market | 2026-2036
Italy Gluten-Free Foods and Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Gluten-Free Foods and Beverages Market Foresight
AOECS certification is reorganizing competitive access across Italy's gluten-free sector, raising the bar for cross-contamination protocols and supplier audits. Dr Schar AG / SPA leverages its dedicated Italian manufacturing footprint to sustain shelf presence in pharmacy and retail channels simultaneously. Barilla anchors premium pasta positioning through dedicated gluten-free production lines that isolate wheat allergens from conventional operations. NOVE ALPI Srl competes in the food-service private-label segment, supplying restaurant chains with bulk-format specialty flours.
Gluten-free foods and beverages comprise products formulated without wheat, barley, rye, or their crossbred variants, typically substituting rice flour, corn starch, or pseudocereals like buckwheat and quinoa to achieve comparable texture and taste profiles. These products serve both diagnosed celiac patients requiring strict lifelong avoidance and health-conscious consumers pursuing reduced-gluten dietary patterns. The pasta segment dominates Italian retail value due to deep cultural embedding of durum wheat alternatives, while beverages represent the fastest-growing category as functional hydration and oat-based drinks gain trial among younger demographics. Supermarkets control the bulk of volume throughput, though health food shops capture disproportionate margin through personalized service and dietitian-staffed consultation.
Italy's Ministry of Health maintains the national celiac disease register and funds gluten-free product distribution through regional health authorities, while AIC (Italian Celiac Association) licensing governs consumer-facing trust marks. EU Regulation 1169/2011 mandates allergen labeling that pushes manufacturers toward segregated supply chains and validated cleaning protocols. Stakeholders must monitor whether Italy's regional health budgets sustain full reimbursement for certified products or shift toward partial co-payment models that would redirect price-sensitive volumes toward retail channels.
Market Dynamics
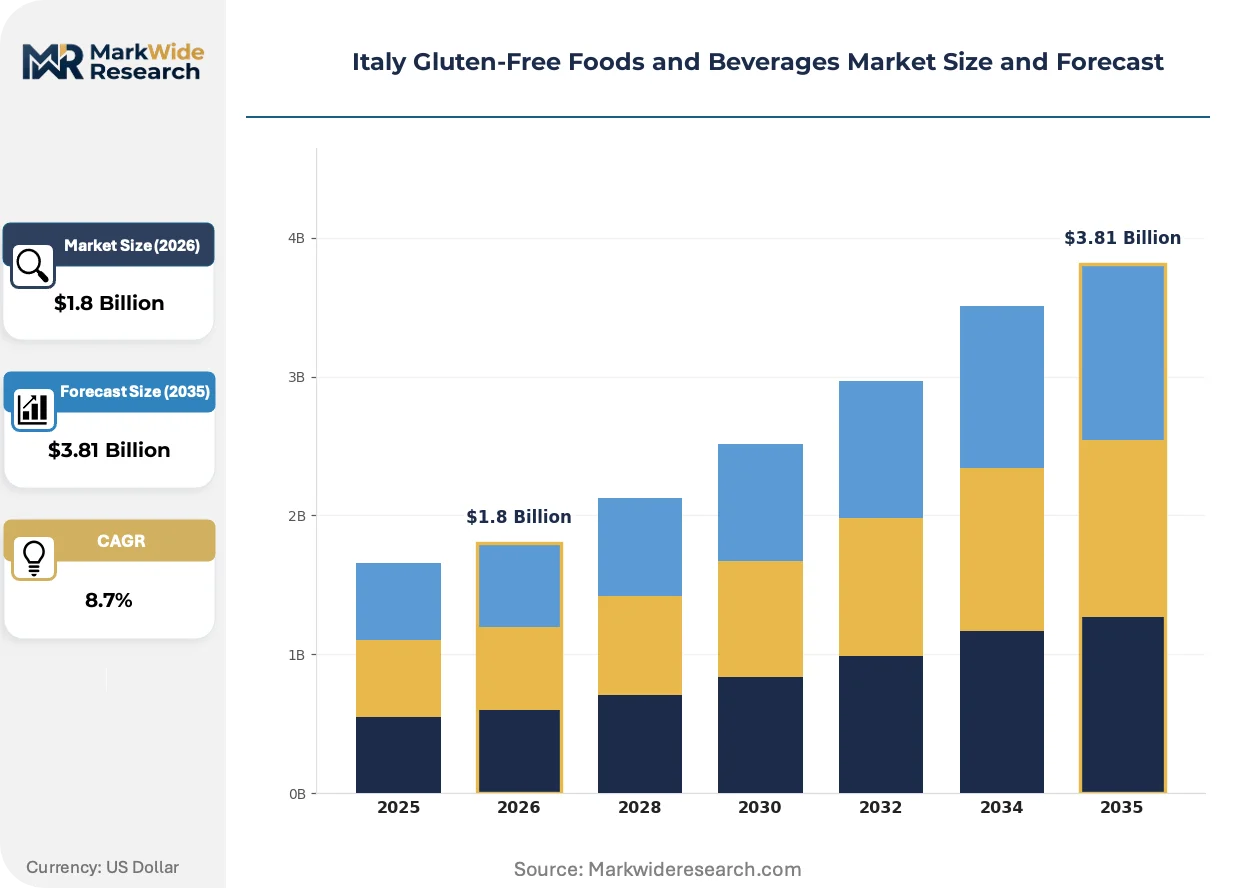
AOECS certification protocols are compressing supplier timelines while Italy's Ministry of Health reimbursement tightening forces manufacturers toward dual-channel pharmacy-retail strategies. This regulatory tightening intersects with Emilia-Romagna's pasta manufacturing concentration to reshape competitive access.
Growth Catalysts
- AIC Registry Protocols:Italy's Ministry of Health tightened national reimbursement eligibility in 2023, redirecting manufacturer investment toward certified production capacity and quality validation systems.
- Metropolitan Food Service Corridors:Milan's restaurant density creates concentrated demand pull for certified gluten-free menu development, accelerating distributor specialization in Northern Italy.
- Rice Flour Processing Advances:Improved enzymatic modification techniques are extending pasta texture parity with durum wheat alternatives, expanding consumer acceptance beyond diagnosed celiac populations.
Market Restraints
- Pseudocereal Input Volatility:Buckwheat and quinoa sourcing concentrates in limited South American and Asian supply basins, exposing Italian manufacturers to currency and climate-driven cost swings.
- Cross-Contamination Protocol Costs:AOECS audit requirements mandate dedicated production lines and validated cleaning systems that inflate capital intensity for mid-scale entrants.
- Oat-Based Beverage Substitution:Functional hydration products using conventional oat bases compete for shelf space and consumer trial among health-conscious demographics less committed to strict gluten avoidance.
Strategic Opportunities
- Southern Italy Underpenetration:Campania and Sicily retail channels show lower certified product density, creating whitespace for regional distributor partnerships and localized brand building.
- Food Service Private Label:Restaurant chains in Emilia-Romagna seek bulk-format specialty flour supply agreements, opening B2B volume contracts outside retail margin compression.
- EU Green Deal Alignment:Sustainability-linked procurement criteria favor domestic pseudocereal cultivation projects, potentially reducing import dependency for Italian manufacturers.
Industry Challenges
- Segregated Supply Chain Complexity:Maintaining wheat-free logistics from raw material intake through retail shelf requires specialized warehousing and transport assets that strain working capital.
- AOECS Certification Timeline Compression:Audit backlogs and documentation requirements extend product launch windows, delaying revenue realization for reformulated or line-extended offerings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Gluten-Free Foods and Beverages Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Breads, Pasta, Snacks, Beverages Distribution Channel: Supermarkets, Online Stores, Health Food Shops, Specialty Stores End User: Individuals, Restaurants, Bakeries, Cafés Packaging Type: Boxes, Bags, Tins, Jars |
| Companies Covered | The Kraft Heinz Company, Italian Fine Food Brokers, Dr Schar AG / SPA, NOVE ALPI Srl, PLASMON, Barilla, NT Food SpA, Timossi Commerciale Sp, FARMO S p A, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Gluten-Free Foods and Beverages Market Shifts & Advancements
Italy's gluten-free sector is experiencing accelerated product format diversification and channel reconfiguration as certification standards tighten and consumer trial expands beyond medical necessity. Three distinct movements are compressing traditional competitive positions.
Enzymatic protein modification technology is miniaturizing texture gaps between alternative and conventional pasta. Food service operators in Milan's metropolitan corridor are adopting these reformulated products at accelerated pace for certified menu deployment. The structural consequence is compressing the premium price differential that historically protected early-mover manufacturers.
Italy's Ministry of Health maintains the national celiac disease register and funds regional distribution through AIC-licensed channels. EU Regulation 1169/2011 allergen labeling mandates are pushing manufacturers toward segregated supply chains and validated cleaning protocols. Pasta manufacturers in Emilia-Romagna are responding by isolating dedicated production lines from conventional wheat operations.
Health food shops with dietitian-staffed consultation are capturing disproportionate margin through personalized service models. Supermarket volume throughput faces disintermediation pressure as younger demographics seek trial guidance and subscription-based replenishment. This channel shift is most visible in Northern Italy's metropolitan food service corridors where pharmacy-retail hybrid formats are expanding.
Italy Gluten-Free Foods and Beverages Market Segmentation
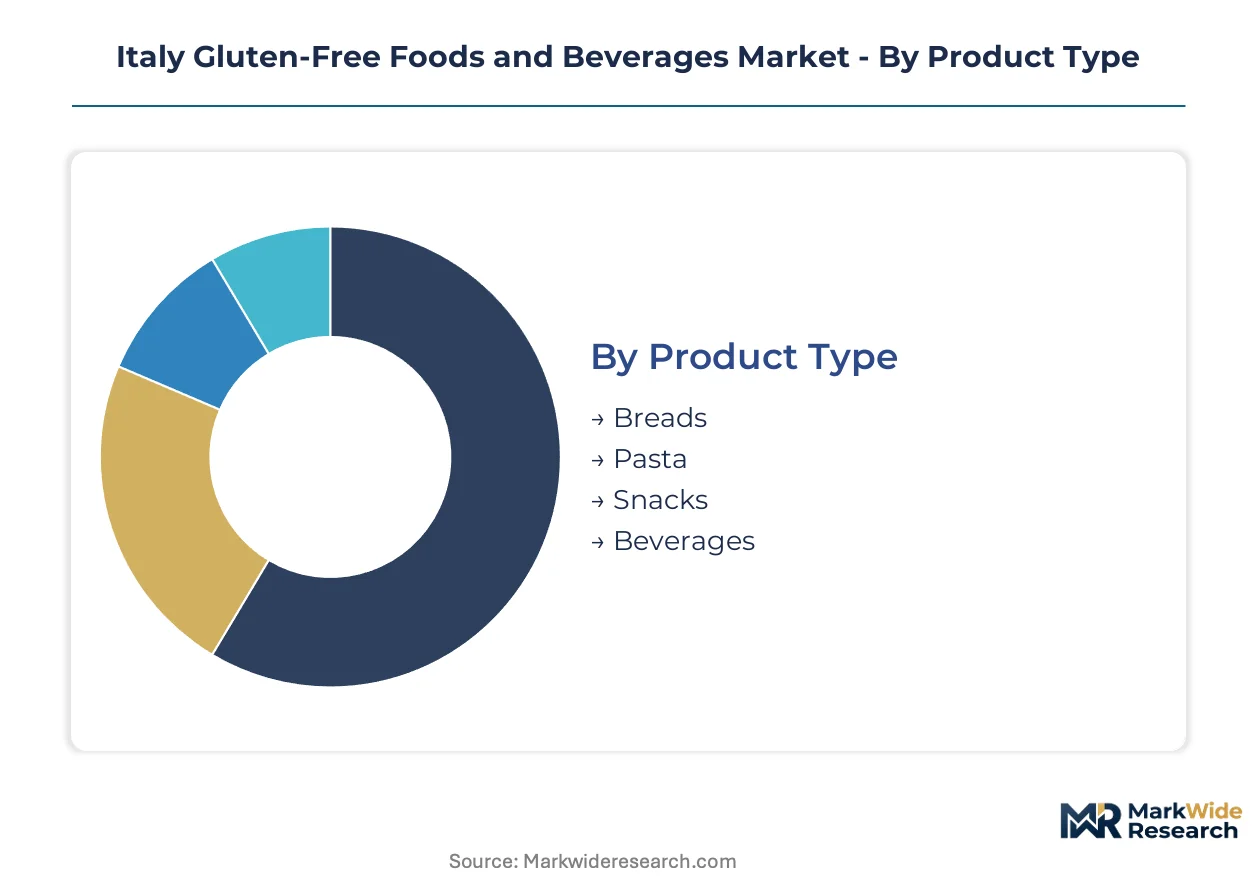
Segmentation reveals how certification requirements and reimbursement policies fragment Italy's gluten-free market across divergent commercial pathways. Each dimension exposes distinct margin structures and competitive intensity patterns.
Product Type:
Substitution pressure from conventional alternatives and adjacent free-from categories varies sharply across product formats, reshaping investment priorities for Italian manufacturers.
- Pasta:Formulations rely on rice flour, corn starch, and pseudocereal blends to replicate durum wheat texture and cooking behavior. Demand concentrates in Emilia-Romagna's manufacturing belt where dedicated production lines isolate wheat allergens from conventional operations; enzymatic modification advances are compressing the premium price differential that historically protected early movers.
- Beverages:Oat-based functional hydration products and pseudocereal drinks target younger demographics pursuing reduced-gluten dietary patterns rather than strict medical necessity. Milan's metropolitan food service corridor drives trial adoption as restaurant chains expand certified menu offerings; oat-based substitutes from conventional grain supply chains compete aggressively for shelf space and consumer attention.
- Breads:Rice and tapioca starch formulations dominate retail shelves, with AIC-licensed trust marks commanding pharmacy channel placement.
- Snacks:Extruded and baked formats using corn, rice, and legume flours serve impulse purchase occasions in supermarkets and health food shops.
Pasta retains volume leadership; beverages hold the steepest expansion curve.
Distribution Channel:
Channel selection determines margin capture and working capital intensity as reimbursement tightening redirects patient volumes toward retail pathways.
- Supermarkets:Control bulk volume throughput across Northern Italy's metropolitan corridors, with dedicated shelf space and promotional programming driving household penetration. Emilia-Romagna and Lombardy retail networks show highest certified product density; centralized procurement pressures supplier margins while accelerating private-label development.
- Health Food Shops:Dietitian-staffed consultation models capture disproportionate margin through personalized service and subscription-based replenishment. Milan and Turin corridors show fastest format expansion; younger demographics seek trial guidance that supermarket self-service cannot replicate.
- Online Stores:Direct-to-consumer platforms reduce geographic constraints for Southern Italy households with limited local certified product availability.
- Specialty Stores:Pharmacy-adjacent formats maintain reimbursement eligibility for diagnosed celiac patients under Ministry of Health protocols.
Supermarkets dominate volume throughput; health food shops expand share fastest through service differentiation.
End User:
End-use concentration shapes formulation specifications and packaging formats as food service operators demand bulk supply agreements outside retail margin structures.
- Individuals:Household purchasers span diagnosed celiac patients requiring strict lifelong avoidance and health-conscious consumers pursuing discretionary reduced-gluten patterns. Northern Italy shows highest per-capita expenditure; Southern regions remain underpenetrated with significant whitespace for regional distributor partnerships.
- Restaurants:Certified menu development in Milan's metropolitan corridor and Emilia-Romagna's hospitality belt creates concentrated demand pull for bulk-format specialty flours and pre-portioned ingredients. Chain operators seek private-label supply agreements that bypass retail markup layers.
- Bakeries:Artisan producers require consistent flour performance across varying humidity and temperature conditions.
- Cafés:Beverage-focused operators drive oat-based and pseudocereal drink trial among non-medical consumers.
Individuals anchor volume demand; restaurants climb fastest as certification requirements tighten.
Packaging Type:
Packaging selection intersects with shelf-life requirements and channel-specific handling protocols across Italy's fragmented retail landscape.
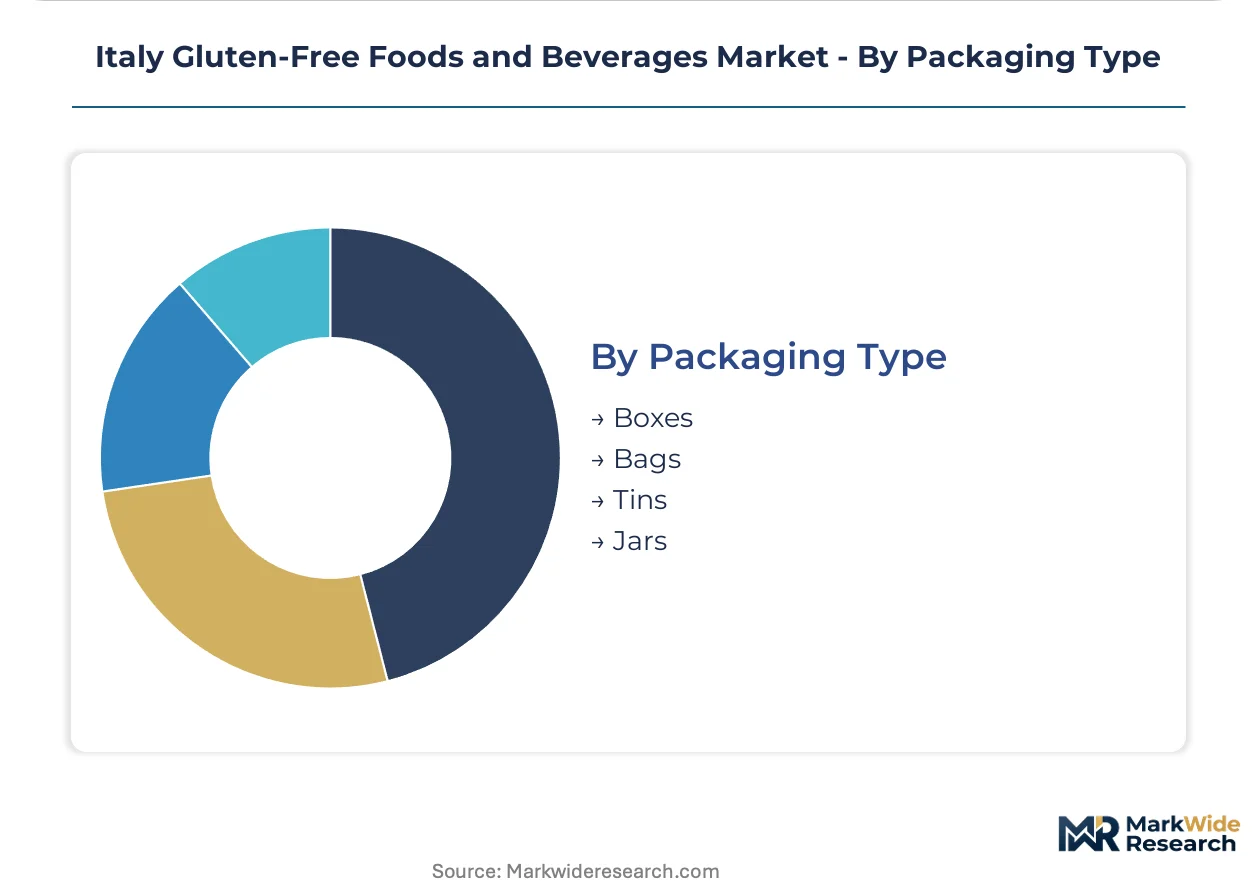
- Boxes:Rigid carton formats protect pasta and bread products through distribution networks requiring extended shelf presence. Supermarket and pharmacy channels favor this format for stacking efficiency; AIC licensing requirements mandate clear allergen labeling space that box structures accommodate readily.
- Bags:Flexible packaging reduces material cost and transport weight for high-velocity snack and flour products. Health food shops and specialty retailers prefer resealable variants; moisture barrier specifications vary by regional humidity exposure.
- Tins:Metal containers extend shelf stability for premium positioned products and gift-oriented formats.
- Jars:Glass packaging serves beverage and spread applications where visual product clarity supports purchase decisions.
Boxes dominate pasta and bread volume; bags gain fastest through snack category expansion and sustainability-linked material innovations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnosed celiac patients and health-conscious consumers cluster unevenly across Italian sub-regions, with Northern metropolitan corridors showing highest per-capita expenditure while Southern markets remain underpenetrated. Distribution infrastructure and reimbursement protocols vary sharply by regional health authority administration.
Lombardy
Milan's metropolitan food service corridor drives concentrated demand for certified gluten-free menu development among restaurant chains. The regional health authority maintains full reimbursement for AIC-licensed products through pharmacy channels. Production facilities in the Milan hinterland supply both retail and food service segments with dedicated gluten-free pasta lines.
Emilia-Romagna
Specialized pasta manufacturing belts around Bologna and Modena anchor national production capacity for rice flour and pseudocereal formulations. The Ministry of Health's 2023 reimbursement tightening has redirected manufacturer investment toward quality validation systems in this cluster. Food service private-label contracts from regional hospitality operators are expanding bulk-format specialty flour demand.
Piedmont
Turin's health food shop density exceeds national averages, with dietitian-staffed consultation formats capturing disproportionate margin through subscription-based replenishment. Regional retail networks show fastest format expansion for pharmacy-retail hybrid channels. Local distributors are building partnerships to address whitespace in adjacent Ligurian markets.
Veneto
Verona and Padua retail corridors demonstrate strong supermarket volume throughput for certified bread and snack products. The regional health authority's co-payment pilot programs are redirecting price-sensitive patient volumes toward retail channels. Manufacturing investment in enzymatic modification technology is compressing pasta price premiums in this zone.
Campania
Naples and surrounding provinces show lower certified product density, creating whitespace for regional distributor partnerships and localized brand building. Pharmacy channel reimbursement remains more generous than Northern regions, sustaining patient loyalty to traditional distribution. Import dependency for pseudocereal inputs exposes local manufacturers to currency volatility.
Italy Gluten-Free Foods and Beverages Market Competitive Landscape
Player mix skews toward multinational food conglomerates with dedicated Italian manufacturing footprints alongside domestic specialists serving food service private-label contracts. Market structure shows moderate consolidation at the premium tier with fragmentation among regional distributors and artisan producers. Two strategic archetypes dominate: integrated manufacturers controlling segregated supply chains from raw material through retail shelf, and specialized B2B suppliers anchoring restaurant chain procurement. Competitive moves center on AOECS certification acquisition and dual-channel pharmacy-retail positioning.
Among integrated manufacturers with Italian production presence, Dr Schar AG / SPA and Barilla occupy positions exemplifying the certified production archetype, while NOVE ALPI Srl represents the food service specialization tier. Dr Schar's dedicated manufacturing footprint sustains simultaneous shelf presence across pharmacy and retail channels. Barilla anchors premium positioning through production line isolation protocols that segregate wheat allergens from conventional operations. NOVE ALPI Srl competes in bulk-format specialty flour supply, serving restaurant chains seeking private-label agreements outside retail markup structures.
| Leading Market Players |
|---|
| The Kraft Heinz Company |
| Italian Fine Food Brokers |
| Dr Schar AG / SPA |
| NOVE ALPI Srl |
| PLASMON |
| Barilla |
| NT Food SpA |
| Timossi Commerciale Sp |
| FARMO S p A |
| Others |
Supply & Pricing Matrix
Rice flour substitution for durum wheat in Emilia-Romagna's pasta manufacturing simultaneously redraws raw material sourcing geography and compresses the premium pricing umbrella that historically protected early gluten-free entrants. This input shift forces manufacturers to index long-term supply contracts against South American and Asian pseudocereal benchmarks while AOECS certification costs push pricing stratification across pharmacy and retail channels.
Pricing Analysis
Cost-plus contracts with pseudocereal indexation anchor supplier agreements for Italian manufacturers sourcing buckwheat and quinoa from South American and Asian basins. Three-tier pricing structure across premium AOECS-certified, standard AIC-licensed, and economy retail tiers reflects certification grade and volume scale differentials. Pricing pressure stems from enzymatic modification advances compressing texture premiums in pasta segments. Diagnosed celiac patients through pharmacy channels show lowest price sensitivity; health-conscious supermarket trialists exhibit highest elasticity.
Supply Chain Analysis
Bolivian and Peruvian quinoa corridors and Chinese buckwheat processing zones constitute chokepoints for Italian pseudocereal-dependent manufacturers. Raw material flows draw from South American grain elevators, Asian flour mills, and domestic rice processors in Lombardy and Veneto. Single-source vulnerability concentrates in Andean climate exposure and currency fluctuation against the euro. Distribution runs through segregated warehousing networks with validated cleaning protocols before supermarket, pharmacy, and food service endpoints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
AOECS certification entrenchment creates defensive moats through regulatory switching costs that lock in patient loyalty and pharmacy channel access. Network effects concentrate among early certifiers whose production line investments now isolate competitors from food service procurement.
For Market Incumbents: Consolidate manufacturing scale in Emilia-Romagna's pasta belt to amortize dedicated line costs across pharmacy and retail volume pools. Deepen backward integration into domestic rice milling to offset South American pseudocereal volatility. AOECS audit backlogs threaten to delay competitor launches; accelerate certification maintenance investments to exploit timeline compression. For New Entrants and Emerging Players: Differentiate on Southern Italy regional distribution partnerships where Campania and Sicily show certified product whitespace. Target food service private-label contracts in Milan's metropolitan corridor where bulk-format specialty flour demand outpaces supply. Deploy dietitian-staffed consultation formats in Turin and Piedmont corridors to capture subscription-based replenishment margins. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-cap Italian manufacturers holding AIC licenses but lacking AOECS upgrade capital. Five-to-ten year viability hinges on certification completion rates and regional health authority reimbursement sustainability. Watch for Ministry of Health co-payment pilot expansions as inflection signals redirecting patient volumes toward retail channels.| Strategic Initiative | Industry Significance |
|---|---|
| AOECS Certification Completion | Unlocks pharmacy channel access and national reimbursement eligibility under Ministry of Health protocols. |
| Domestic Rice Milling Integration | Reduces import dependency and currency exposure from South American pseudocereal sourcing. |
| Food Service Private Label Expansion | Captures bulk-format volume contracts outside retail margin compression in Emilia-Romagna hospitality belt. |
| Enzymatic Modification R&D Investment | Compresses texture parity gaps with durum wheat to expand beyond diagnosed celiac populations. |
| Southern Italy Distributor Partnerships | Addresses Campania and Sicily whitespace before reimbursement tightening redirects Northern patient volumes. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with celiac association dietitians, regional health authority reimbursement officers, pasta manufacturing plant managers, and food service procurement leads at Milan restaurant chains. Secondary validation drew from AIC registry filings, Ministry of Health celiac disease statistics, EU Regulation 1169/2011 implementation guidance, and Emilia-Romagna industrial production records. Bottom-up patient population estimates and top-down manufacturing capacity assessments were triangulated against channel shipment data.
Across the analysis window, the forecasting framework modeled product type segmentation by pasta, beverage, bread, and snack formats alongside distribution channel dynamics across supermarkets, health food shops, online platforms, and pharmacy-adjacent specialty stores. CAGRs were derived from patient registry growth trajectories, reimbursement policy elasticity assumptions, and food service certification adoption curves. Enzymatic technology diffusion rates and Southern Italy penetration coefficients served as industry-specific demand shapers.
Material uncertainties — Ministry of Health reimbursement tier adjustments, AOECS audit timeline volatility, Andean climate shocks affecting quinoa yields — sit outside the modeled envelope. Forecasts reflect assumptions around certification completion rates and regional health budget sustainability. Practitioners should keep alternative scenarios live as EU Green Deal procurement criteria and domestic pseudocereal cultivation subsidies evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Intolerance Products
Allergen Free Food Products Market
Food Intolerance Products
South America Gluten Free Foods and Beverages Market
Food Intolerance Products
Germany Gluten-Free Foods and Beverages Market
Food Intolerance Products
Gluten-Free Soup Market
Food Intolerance Products
Dyspepsia Market
Food Intolerance Products
North America Gluten-Free Food and Beverage Market
Food Intolerance Products
Brazil Gluten-Free Food and Beverages Market
Food Intolerance Products
Japan Gluten-Free Food and Beverages Market
Food Intolerance Products
Asia-Pacific Gluten-Free Breakfast Cereals Market
Food Intolerance Products
Gluten-Free Popcorn Products Market
Food Intolerance Products
Food Allergy Market
Food Intolerance Products
Asia-Pacific Gluten-Free Food and Beverages Market
Food Intolerance Products
Citrus-Derived Gastrointestinal Comfort Blends Market
Food Intolerance Products
India Gluten-Free Food and Beverage Market
Food Intolerance Products
Egg Allergy Market
Food Intolerance Products
Reduced Salt Food Products Market