
 United States Over the Counter (OTC) Drugs Market | 2026-2036
United States Over the Counter (OTC) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
United States Over the Counter (OTC) Drugs Market Intelligence
Buyer concentration among pharmacy chains and mass retailers is shifting toward fewer, larger procurement networks with expanded private-label programs. Johnson & Johnson Services Inc. leverages its Tylenol and Motrin franchises to sustain shelf dominance across major retail banners. Bayer AG anchors the analgesic segment with aspirin and Aleve portfolios, while Perrigo Company plc competes aggressively in store-brand manufacturing.
Over the Counter (OTC) drugs comprise non-prescription pharmaceutical formulations regulated under FDA monograph standards, typically containing active ingredients at concentrations proven safe and effective for self-diagnosed conditions through specified dosing regimens. These products serve commercial purposes by reducing healthcare system burdens and enabling consumer-directed symptom management. Pain Relievers occupies the largest revenue pool due to chronic condition prevalence, while Vitamins & Supplements captures the fastest structural growth as preventive health behaviors expand. Online Retailers within the Distribution Channel segment is displacing traditional pharmacy foot traffic through subscription models and same-day delivery infrastructure.
FDA monograph reforms and the Drug Quality and Security Act shape product standards, labeling requirements, and facility compliance costs for domestic manufacturers. State-level pharmacy boards and the FTC jointly influence advertising claims and pricing transparency in retail environments. Stakeholders must monitor pending monograph updates and telehealth integration patterns that could redefine consumer access protocols.
Market Dynamics
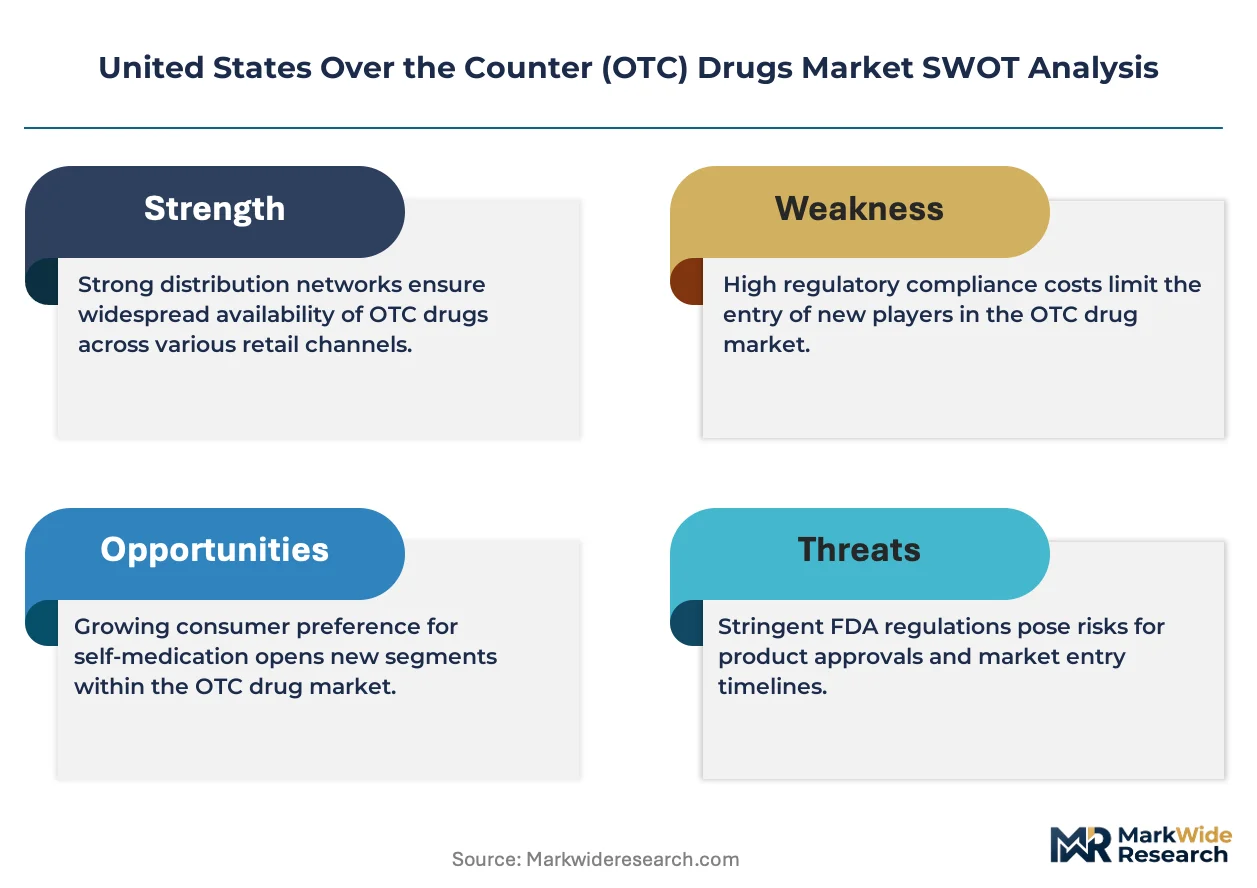
Pharmacy chain consolidation is compressing supplier margins while expanding private-label shelf space, forcing branded OTC manufacturers to defend position through direct-to-consumer channels and formulary exclusivity deals.
Growth Catalysts
- Sun Belt Demographics:Florida, Texas, and Arizona metropolitan areas exhibit rising self-medication rates among aging populations, expanding addressable demand for analgesic and digestive health categories.
- Drug Quality and Security Act:Track-and-trace mandates elevate compliance costs for smaller compounders, accelerating market share migration toward FDA-registered domestic manufacturers with established serialization infrastructure.
- Telehealth Integration:Virtual primary care platforms are incorporating OTC recommendation protocols, creating new prescription-to-OTC conversion pathways for chronic condition management.
Market Restraints
- API Import Concentration:Active pharmaceutical ingredient sourcing remains concentrated among Asian chemical manufacturers, exposing finished goods producers to tariff volatility and geopolitical supply interruptions.
- FDA Monograph Uncertainty:Pending reforms to the OTC monograph system create labeling and formulation compliance ambiguity, delaying new product launches and portfolio reconfigurations.
- Retail Buyer Consolidation:CVS Health, Walgreens Boots Alliance, and Walmart control a disproportionate share of shelf access, extracting slotting fee concessions that compress net margins for mid-tier suppliers.
Strategic Opportunities
- Subscription Commerce Models:Amazon Pharmacy and Capsule are building recurring revenue infrastructure for preventive health categories, enabling lifetime value capture beyond single-transaction retail economics.
- Pharmacy Desert Penetration:Rural Mississippi, Alabama, and New Mexico counties with limited retail pharmacy access present white-space demand for direct-ship and mobile clinic distribution partnerships.
- IRA Preventive Health Incentives:Medicare Advantage plan design changes are expanding supplemental benefit coverage for certain OTC categories, creating reimbursement-adjacent revenue streams.
Industry Challenges
- Serialization Infrastructure Capex:Unit-level traceability system deployment requires capital investment exceeding smaller manufacturers' balance sheet capacity, forcing strategic exits or contract manufacturing pivots.
- Monograph Update Timeline Compression:FDA's accelerated review schedule for sunscreen and antiseptic monographs demands rapid reformulation cycles that strain R&D bandwidth and stability testing resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Over the Counter (OTC) Drugs Market |
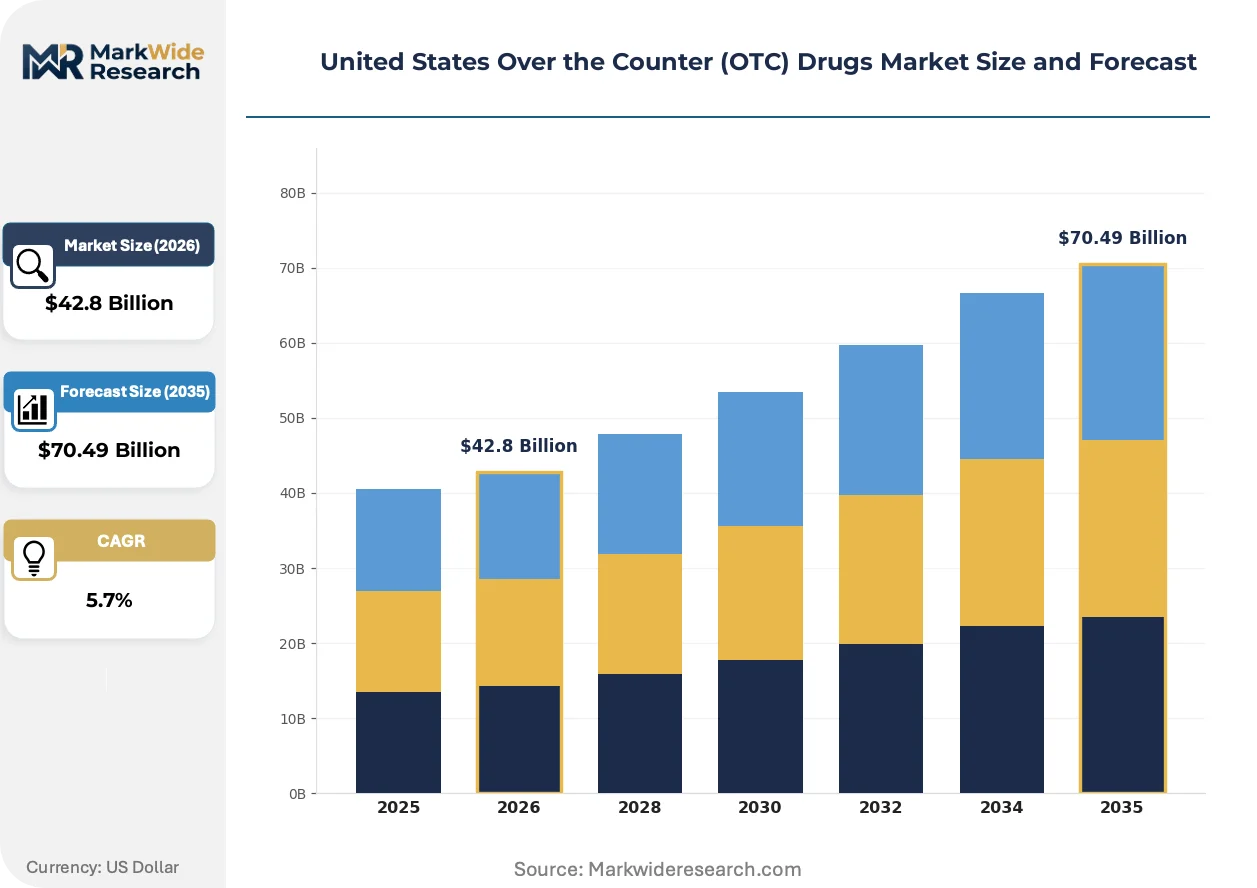
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $70.49 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pain Relievers, Cold & Allergy Medications, Digestive Aids, Vitamins & Supplements End User: Adults, Children, Elderly, Caregivers Distribution Channel: Pharmacies, Supermarkets, Online Retailers, Convenience Stores Packaging Type: Blister Packs, Bottles, Sachets, Jars |
| Companies Covered | Johnson & Johnson Services Inc., Bayer AG, Sanofi S.A., Novartis AG, Pfizer, GlaxoSmithKline PLC, Boehringer Ingelheim International GmbH, Perrigo Company plc, Reckitt Benckiser Group PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Over the Counter (OTC) Drugs Market Strategic Shifts & Innovations
Digital health platforms are rewiring how consumers discover, validate, and purchase self-care products, collapsing the traditional pharmacy consultation layer into algorithmic recommendation engines.
Connected packaging embedded with NFC tags and QR-linked dosing applications is unifying physical product consumption with digital adherence tracking. Pharmacy chains including CVS and Walgreens are piloting these interfaces in chronic pain management categories. This convergence is compressing the feedback loop between purchase behavior and repurchase triggers, enabling dynamic couponing and subscription conversion.
FDA's pending modernization of the OTC monograph system is mandating efficacy substantiation for grandfathered active ingredients, particularly in cough-cold and topical analgesic categories. Manufacturers must generate new clinical data or reformulate around approved monograph ingredients. The sunscreen and antiseptic segments face the most immediate compliance pressure, with several major brands already withdrawing non-compliant SKUs.
Consumer purchasing for preventive health categories is migrating toward auto-replenishment models through Amazon Subscribe and Save and Walmart Plus. This behavioral shift is displacing impulse-driven front-end pharmacy purchases with planned consumption patterns. The vitamins and supplements segment exhibits the most pronounced channel rotation, though analgesic and digestive health categories are following similar trajectories in suburban households with Prime membership penetration above sixty percent.
United States Over the Counter (OTC) Drugs Market Segmentation
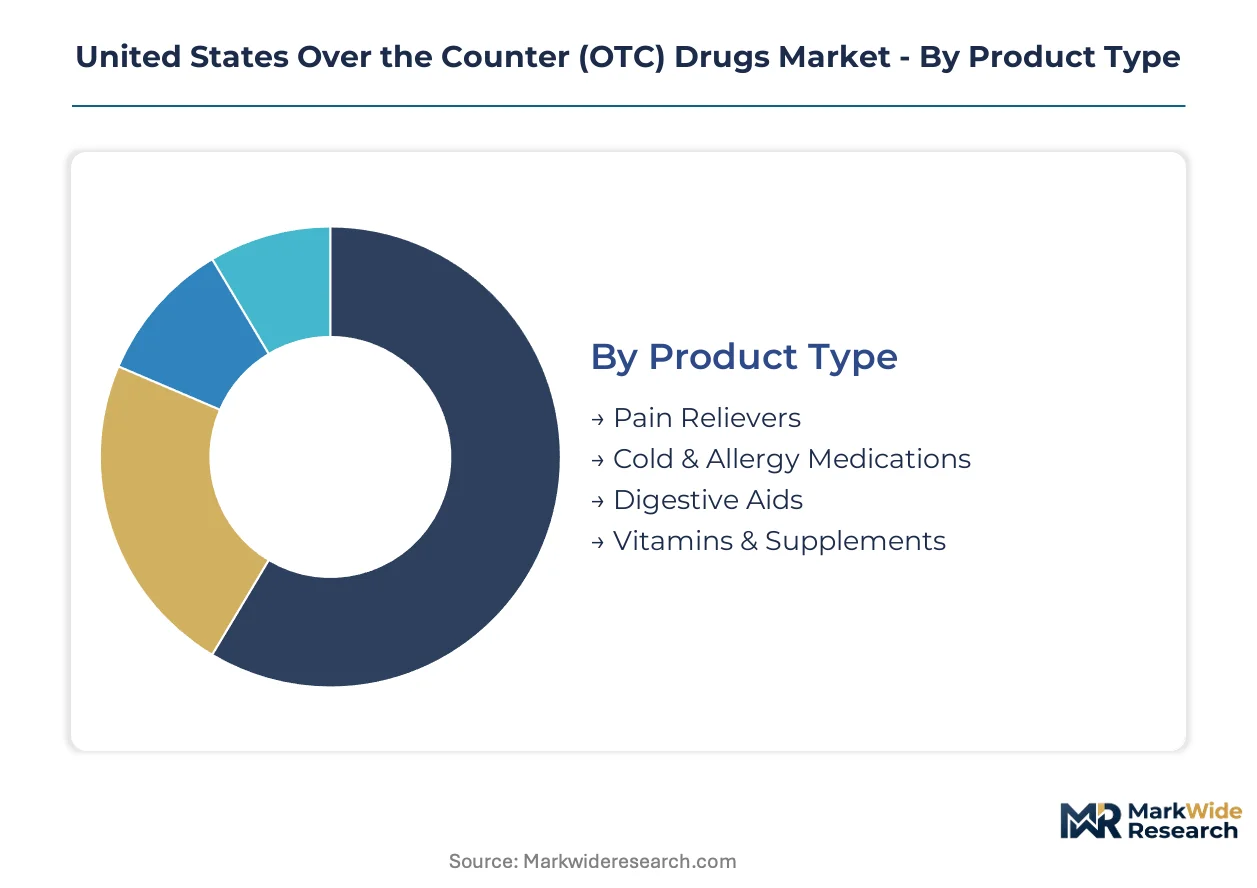
Consumer self-selection behavior and retail shelf economics determine how OTC manufacturers configure product portfolios across formulation, packaging, and channel strategies. Segmentation clarity enables targeted R&D allocation and pricing architecture that matches purchase occasion patterns.
Product Type:
Purchase frequency and symptom severity drive how consumers allocate spending across therapeutic categories, with chronic condition management commanding premium shelf positioning.
- Pain Relievers:Analgesic formulations containing acetaminophen, ibuprofen, or naproxen sodium address acute and chronic pain conditions. Demand concentrates in suburban Sun Belt metropolitan areas where aging demographics and pharmacy deserts elevate self-medication reliance. CVS and Walgreens maintain dedicated end-cap placements for these SKUs.
- Cold & Allergy Medications:Antihistamine and decongestant combinations target seasonal and perennial respiratory symptoms. Florida and Texas allergy corridors sustain year-round consumption above national baselines, with private-label substitution accelerating during peak pollen seasons.
- Digestive Aids:Antacid, laxative, and anti-diarrheal formulations serve episodic gastrointestinal distress. Retail buyers favor multi-SKU displays near pharmacy counters.
- Vitamins & Supplements:Preventive micronutrient and botanical formulations support wellness positioning. Amazon Subscribe and Save penetration is displacing front-end impulse purchases in suburban households.
Pain Relievers leads on scale; Vitamins & Supplements leads on momentum.
End User:
Regulatory labeling requirements and dosing precision standards segment formulation development across demographic risk profiles.
- Adults:Standard-strength monograph formulations serve the broadest addressable population with flexible dosing protocols. Mass retailers and pharmacy chains prioritize adult SKUs for inventory turnover velocity.
- Children:Weight-calibrated liquid suspensions and chewable formats require precise concentration controls and child-resistant packaging compliance. FDA pediatric labeling mandates elevate manufacturing complexity.
- Elderly:Polypharmacy-conscious formulations with drug interaction warnings address Medicare Advantage populations. Sun Belt retirement communities generate concentrated demand.
- Caregivers:Institutional and home-care purchasing agents buy in volume for dependent populations. Long-term care facilities negotiate formulary contracts directly with distributors.
Adults delivers volume concentration; Elderly shows the steepest expansion trajectory as demographic weight shifts.
Distribution Channel:
Foot traffic patterns and fulfillment economics determine where manufacturers invest trade promotion and direct-to-consumer infrastructure.
- Pharmacies:CVS Health, Walgreens Boots Alliance, and Rite Aid provide pharmacist consultation adjacency and insurance-adjacent purchasing. These chains extract slotting fees that compress supplier margins.
- Supermarkets:Kroger and Albertsons embed OTC within grocery shopping trips, capturing impulse demand through front-end placement. Private-label penetration runs highest here.
- Online Retailers:Amazon Pharmacy and Capsule deploy subscription models and same-day delivery infrastructure. Auto-replenishment is displacing traditional pharmacy foot traffic in Prime-heavy ZIP codes.
- Convenience Stores:7-Eleven and Circle K serve emergency and travel-oriented purchase occasions with limited SKU breadth. Higher per-unit pricing offsets lower basket values.
Pharmacies retains shelf dominance; Online Retailers gains share fastest through subscription conversion.
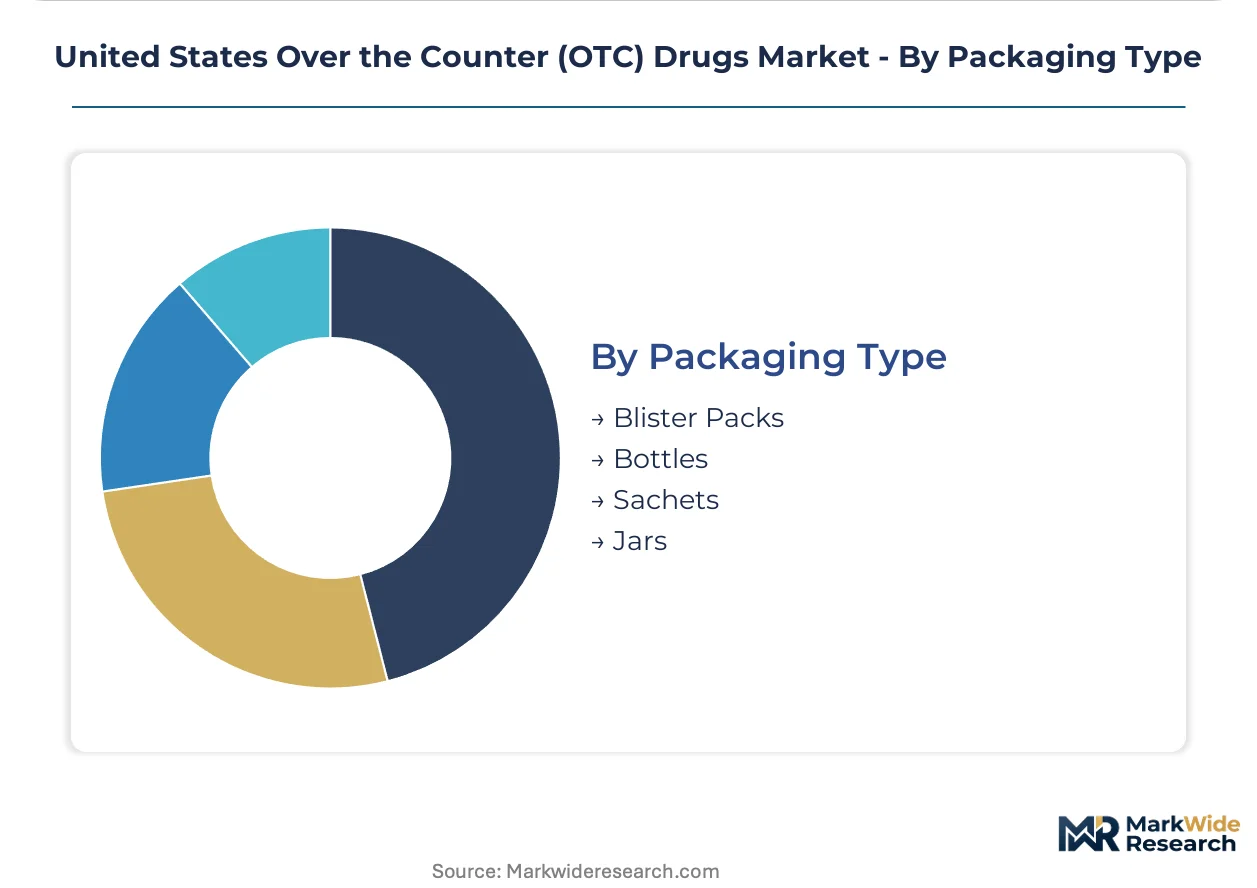
Packaging Type:
Unit economics and compliance requirements shape material selection and serialization infrastructure investment.
- Blister Packs:Individual-dose aluminum-plastic laminates enable precise unit-level tracking under Drug Quality and Security Act mandates. Senior-friendly peel-push designs reduce access barriers.
- Bottles:HDPE and PET containers with child-resistant closures dominate high-volume analgesic and vitamin categories. Serialization capex requirements favor larger manufacturers.
- Sachets:Single-use foil pouches serve travel and trial-size segments with minimal material cost. Convenience stores and airline retail favor this format.
- Jars:Wide-mouth containers accommodate bulk supplement powders and topical preparations. Club channel packaging scales toward this configuration.
Bottles commands production volume; Blister Packs shows the strongest compliance-driven growth as serialization deadlines approach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Florida and Texas metropolitan areas generate disproportionate OTC consumption intensity compared to Midwestern states, driven by divergent demographic trajectories and pharmacy access patterns. Sun Belt migration flows concentrate elderly populations in markets with fewer retail pharmacy locations per capita. FDA monograph enforcement and state-level pharmacy board regulations create uneven compliance landscapes across sub-regional markets.
Southeast
Florida retirement corridors sustain elevated analgesic and digestive health demand among Medicare Advantage enrollees. State pharmacy board regulations govern pharmacist consultation requirements for certain OTC categories. Miami-Dade and Broward counties exhibit pharmacy desert conditions where mobile clinic partnerships address access gaps.
Southwest
Texas metropolitan expansion generates self-medication demand across allergy corridors and chronic pain management. FDA track-and-trace mandates elevate compliance costs for regional distributors serving border markets. Houston and Dallas-Fort Worth anchor distribution hub concentration for national pharmacy chains.
West Coast
California preventive health behaviors drive vitamins and supplements consumption through subscription commerce channels. State-level labeling requirements exceed federal baselines for certain botanical ingredients. Los Angeles and San Francisco Bay Area metros lead online retailer penetration for auto-replenishment models.
Northeast
New York and Boston metropolitan areas concentrate retail pharmacy banner competition with elevated slotting fee pressures. State pharmacy boards enforce advertising claim scrutiny for cough-cold categories. Urban pharmacy density contrasts with rural upstate access limitations.
Midwest
Illinois and Ohio manufacturing bases host FDA-registered production facilities serving national distribution networks. Industrial cluster concentration supports serialization infrastructure investment for Drug Quality and Security Act compliance. Chicago anchors wholesale distribution for mass retailer procurement networks.
United States Over the Counter (OTC) Drugs Market Key Industry Players
Multinational pharmaceutical conglomerates anchor one tier; specialized store-brand manufacturers hold procurement-adjacent positions. Market structure consolidates around vertically integrated players with FDA-registered domestic manufacturing and established pharmacy chain formulary relationships. Three strategic archetypes dominate: branded portfolio incumbents with heritage consumer franchises, contract manufacturing specialists serving private-label programs, and diversified healthcare conglomerates leveraging distribution scale. Competitive dynamics center on direct-to-consumer channel expansion and formulary exclusivity negotiations with consolidated retail buyers.
Within the branded incumbent tier, Johnson & Johnson Services Inc. and Bayer AG exemplify heritage franchise defense through retail banner dominance. Perrigo Company plc occupies a position representing store-brand manufacturing specialization. These anchors illustrate how competitive positioning stratifies between proprietary brand equity and procurement-scale efficiency.
| Leading Market Players |
|---|
| Johnson & Johnson Services Inc. |
| Bayer AG |
| Sanofi S.A. |
| Novartis AG |
| Pfizer |
| GlaxoSmithKline PLC |
| Boehringer Ingelheim International GmbH |
| Perrigo Company plc |
| Reckitt Benckiser Group PLC |
| Others |
Cost & Logistics Intelligence
CVS Health, Walgreens Boots Alliance, and Walmart procurement networks command slotting fee concessions that compress supplier margins and enforce three-tier pricing stratification across premium, standard, and economy levels. This buyer concentration elevates private-label substitution while forcing branded manufacturers toward direct-to-consumer channel investments that bypass retail margin extraction.
Pricing Analysis
Capacity additions in domestic FDA-registered manufacturing facilities are reshaping price floors for store-brand analgesic and vitamin categories. Pricing stratifies across premium heritage brands, standard mid-tier offerings, and economy private-label tiers, with differentiation driven by FDA monograph compliance tier and vertical integration depth. Cost compression in economy tiers intensifies because Asian API sourcing faces tariff exposure. Medicare Advantage enrollees show lowest price sensitivity; convenience store emergency purchasers exhibit highest.
Supply Chain Analysis
Dual-sourcing requirements from major pharmacy chains now mandate qualified backup suppliers for critical analgesic and antihistamine APIs. Active pharmaceutical ingredient supply draws from India, China, and selected European chemical manufacturers. Raw material dependencies include acetaminophen bulk powder, ibuprofen acid, and gelatin capsule shells. Single-source vulnerability concentrates in specialized excipient categories. Distribution runs through regional wholesale distributors serving CVS, Walgreens, and Walmart consolidation centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States OTC drugs market functions as a regulatory compounder where FDA monograph modernization creates compliance-driven demand for reformulation services and serialization infrastructure. The Drug Quality and Security Act track-and-trace mandates alone have forced capital reallocations exceeding smaller manufacturers' balance sheet capacity.
For Market Incumbents:Cement formulary exclusivity through multi-year procurement contracts with CVS Health and Walgreens Boots Alliance that bundle shelf placement with data-sharing agreements. Deepen backward integration into API finishing capabilities to offset Asian sourcing tariff exposure. Defend against private-label substitution by deploying connected packaging with NFC-enabled adherence tracking in chronic pain categories.
For New Entrants and Emerging Players:The price-point gap between premium Tylenol-tier positioning and economy store-brand tiers creates white-space opportunity for mid-market differentiated entrants. Target pharmacy desert counties in rural Mississippi and Alabama with direct-ship subscription models partnered with mobile clinic networks. Pursue Medicare Advantage supplemental benefit reimbursement pathways as the primary go-to-market angle.
For Investors and Strategic Acquirers:Pharmacy chain private-label programs are the most active acquirer in this space, seeking FDA-registered contract manufacturers with established serialization infrastructure. The five-to-ten-year viability window favors targets with demonstrated track-and-trace compliance and regional distribution hub proximity. Acquisition target archetype: mid-tier store-brand manufacturers with captive API relationships. Monitor FDA monograph update acceleration as the signal indicating regulatory compliance premium expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Launch | Amazon Pharmacy and Capsule subscription models bypass CVS slotting fee extraction. |
| Serialization Infrastructure Investment | Unit-level traceability systems satisfy Drug Quality and Security Act compliance deadlines. |
| Private-Label Manufacturing Scale-Up | Perrigo-type contract manufacturers capture pharmacy chain consolidation procurement. |
| Connected Packaging Integration | NFC-enabled dosing applications enable dynamic couponing and subscription conversion. |
| Medicare Advantage Reimbursement Strategy | IRA preventive health incentives expand supplemental benefit coverage for OTC categories. |
Research Approach
Coverage spans the Southeast, Southwest, West Coast, Northeast, and Midwest regions, with primary inputs from each. Primary interviews incorporated formulary directors at CVS Health and Walgreens Boots Alliance, regulatory affairs leads at FDA-registered manufacturers, and procurement managers at mass retailer consolidation centers. Secondary validation drew from FDA monograph filings, Drug Quality and Security Act compliance databases, CMS Medicare Advantage plan documents, and Nielsen retail audit data. Bottom-up SKU-level demand modeling triangulated against top-down therapeutic category spending projections.
Rate-of-change decomposition anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type, end user demographic, distribution channel, and packaging format alongside regional regulatory cluster intensity. CAGRs derived from historical volume trajectories adjusted for demographic shift patterns and channel migration velocities. Forecast inputs incorporated Sun Belt population migration flows and telehealth platform OTC recommendation protocol adoption curves.
The model assumes a particular technology adoption path; alternative pathways for connected packaging NFC integration would alter the outlook. Forecasts reflect assumptions regarding FDA monograph update timelines and pharmacy chain consolidation velocity. Deviation in API import tariff policy would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Peptide Cancer Vaccine Market
Pharmaceuticals
SGLT2 Inhibitors Market
Pharmaceuticals
Fertility Drug and Surgery Market
Pharmaceuticals
Adrenocorticotropic Hormone [ACTH] Market
Pharmaceuticals
Global Travel Vaccines Market
Pharmaceuticals
Guanethidine Market
Pharmaceuticals
Palonosetron Hydrochloride Market
Pharmaceuticals
Lamotrigine API Market
Pharmaceuticals
Motilium Market
Pharmaceuticals
Anti-Obesity Drugs Market
Pharmaceuticals
Nefopam Hydrochloride Injection Market
Pharmaceuticals
Global Pediatric Drugs Market
Pharmaceuticals
Tuberculosis Therapeutics Market
Pharmaceuticals
Global Ebola Virus Vaccine Market
Pharmaceuticals
Global Online Pharmacy Market
Pharmaceuticals
Inotropic Agent Market