
 Flunarizine Hydrochloride Market | 2026-2036
Flunarizine Hydrochloride Market Size, Share, and Industry Trends Forecast 2026-2036
Flunarizine Hydrochloride Market Analysis
Hospital procurement of flunarizine hydrochloride for migraine prophylaxis is rotating toward specialty neurology centers with protocol-driven prescribing. Novartis AG leverages its historical formulation expertise to sustain brand recognition in European hospital formularies. Teva Pharmaceutical Industries Ltd. anchors its position through backward integration into active pharmaceutical ingredient supply. Sun Pharmaceutical Industries Ltd. competes on cost-adjusted manufacturing scale across emerging markets.
Flunarizine hydrochloride is a diphenylpiperazine calcium channel antagonist with selective vascular smooth muscle relaxation properties, typically formulated as 5 mg tablets or capsules for oral administration. It functions primarily as a prophylactic agent against migraine and vertigo disorders by inhibiting calcium influx across neuronal and vascular membranes. Tablet formulations dominate current volume due to established bioequivalence profiles and patient compliance familiarity, while injectable presentations capture margin in acute hospital settings where rapid therapeutic onset matters. The neurology therapy area leads absolute demand, though pain management applications extend utilization into broader prescriber bases.
FDA bioequivalence standards and EMA quality guidelines govern generic substitution pathways for flunarizine products across major markets. India's CDSCO and China's NMPA regulate local manufacturing and export certification for API producers serving international buyers. Stakeholders must monitor evolving pharmacovigilance requirements for off-patent neurological agents as regulators tighten post-market surveillance obligations.
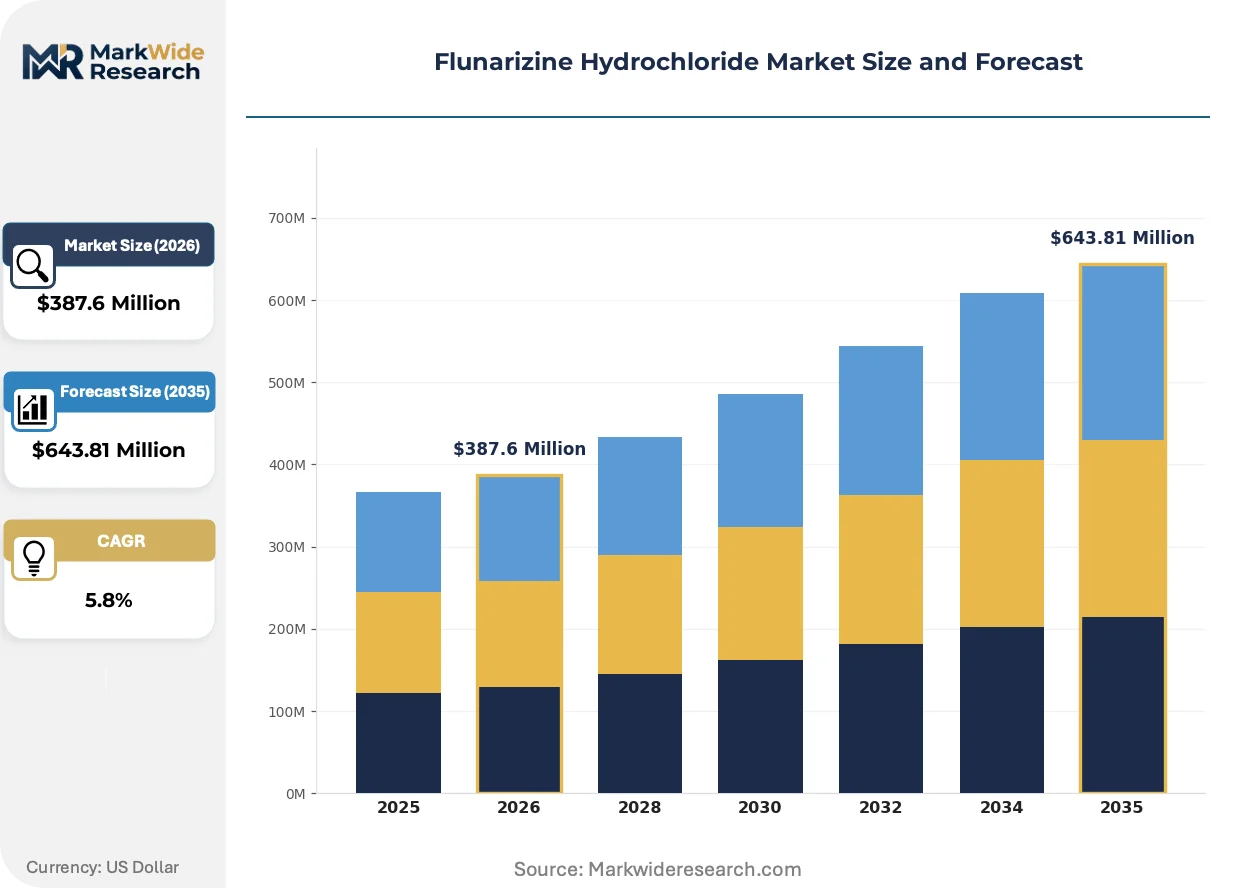
Market Dynamics
Hospital procurement consolidation for migraine prophylaxis is compressing supplier margins while elevating bioequivalence documentation requirements. FDA and EMA standards for generic calcium channel antagonists now demand expanded clinical endpoint studies, reshaping formulation investment priorities across manufacturers.
Growth Catalysts
- EMA bioequivalence guidelines:The European Medicines Agency's tightened standards for generic neurological agents are elevating quality barriers that favor established manufacturers with validated manufacturing processes.
- Neurology center concentration:Specialty hospital clusters in Germany, Italy, and Spain are standardizing flunarizine protocols for chronic migraine management, creating volume anchors for compliant suppliers.
- API manufacturing scale:Indian and Chinese bulk drug producers have achieved cost structures that sustain export competitiveness across regulated markets.
Market Restraints
- Raw material volatility:Piperazine derivative feedstock prices fluctuate with petrochemical indices, compressing margin predictability for finished-dose manufacturers.
- Single-source API risk:Concentration of active pharmaceutical ingredient production in specific Indian states creates geographic vulnerability to environmental compliance shutdowns.
- Substitution pressure:CGRP antagonist therapies are displacing calcium channel blockers in first-line prophylaxis protocols at major US academic medical centers.
Strategic Opportunities
- Brazil ANVISA pathway:Accelerated generic approval timelines for established bioequivalence dossiers create first-mover positioning in Latin America's largest hospital market.
- Extended-release formulations:Modified-release tablet technologies can differentiate commodity products through improved compliance profiles in chronic therapy settings.
- Direct hospital contracting:Bypassing wholesale distribution through dedicated supply agreements with neurology center networks captures margin otherwise lost to intermediaries.
Industry Challenges
- Bioanalytical capacity constraints:Validated CROs capable of flunarizine pharmacokinetic studies face booking backlogs that extend development timelines.
- Legacy equipment retrofit costs:Continuous manufacturing transitions require capital deployment that mid-scale generic houses struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flunarizine Hydrochloride Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $643.81 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablet, Capsule, Injectable, Powder End User: Hospitals, Clinics, Pharmacies, Homecare Therapy Area: Neurology, Cardiology, Psychiatry, Pain Management Distribution Channel: Direct Sales, Retail, Online, Wholesalers |
| Companies Covered | Novartis AG, Teva Pharmaceutical Industries Ltd., Mylan N.V., Sun Pharmaceutical Industries Ltd., Dr. Reddy's Laboratories, Johnson & Johnson Services Inc., Cipla Ltd., Torrent Pharmaceuticals Ltd., Alkem Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flunarizine Hydrochloride Market Emerging Trajectories
Formulation science and regulatory science are converging to redefine competitive differentiation in off-patent neurological agents. Three developments are reshaping how manufacturers capture value.
Modified-release matrix technologies are enabling once-daily dosing regimens that improve adherence in chronic migraine populations. European hospital pharmacies are adopting these formulations at accelerating rates for protocol-driven prophylaxis programs. The technology is miniaturizing production equipment footprints while expanding batch flexibility for contract manufacturers serving multiple markets.
REACH chemical safety registration requirements in Europe are extending compliance obligations to excipient suppliers and packaging materials. This regulatory expansion is forcing reformulation of legacy tablet compositions to eliminate restricted phthalates and colorants. Generic manufacturers serving German and French hospital markets are responding with accelerated stability studies for compliant alternatives.
Hospital buying consortiums are consolidating annual flunarizine tenders into multi-year framework agreements with stringent quality audit requirements. Traditional wholesale distribution channels are losing volume to direct manufacturer relationships with centralized procurement bodies. This pattern is most visible in Italy's regional health service clusters and Spain's autonomous community purchasing platforms.
Flunarizine Hydrochloride Market Segmentation
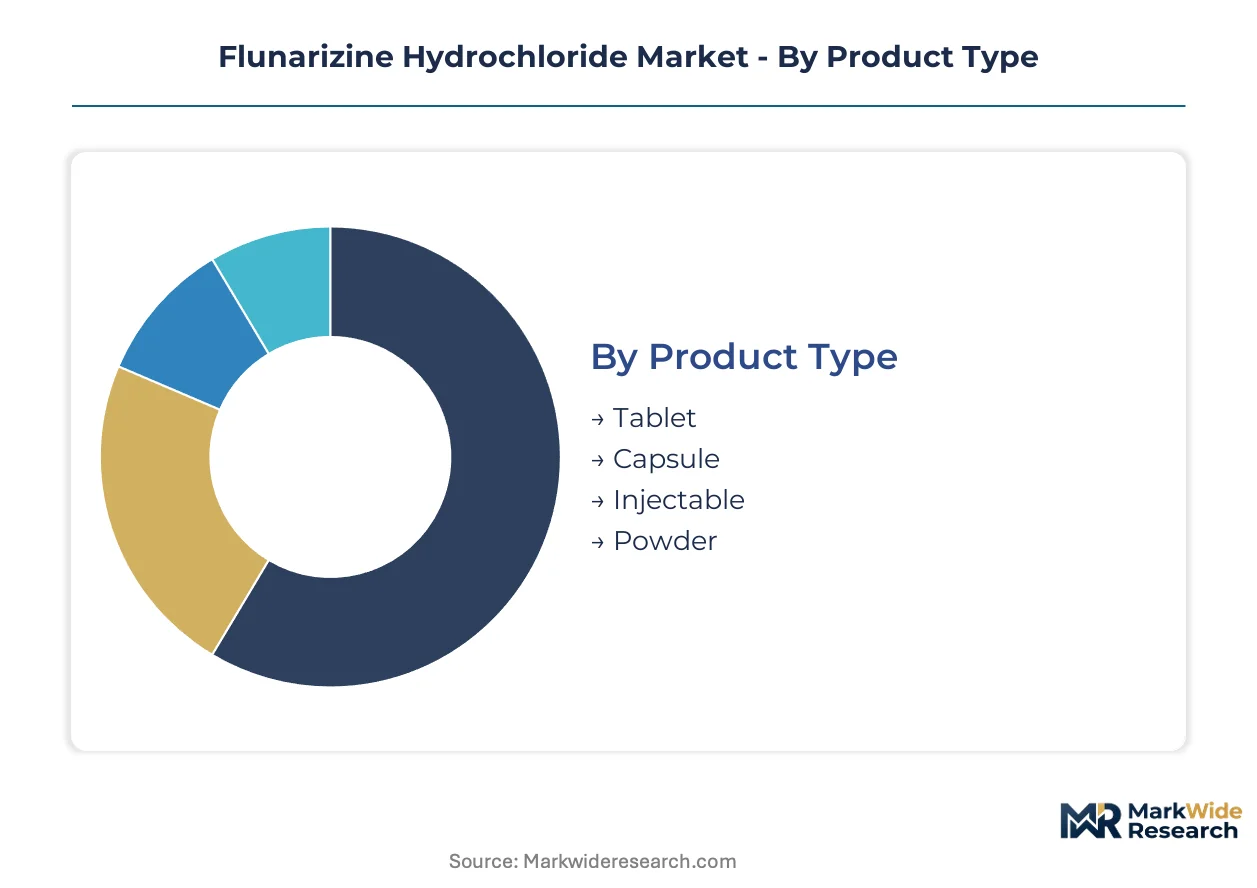
Segmentation in flunarizine hydrochloride markets reveals where CGRP antagonist substitution pressure concentrates most intensely. Product form and therapy area stratification expose which revenue pools face imminent erosion versus defensive moats.
Product Type:
Tablet formulations face the most acute substitution threat as CGRP antagonists displace oral calcium channel blockers in first-line migraine protocols at major hospital systems. Injectable presentations retain defensive positioning through acute-care dependence.
- Tablet:Standard 5 mg immediate-release tablets dominate outpatient prescription volumes with established bioequivalence profiles. Hospital formularies in Germany and Italy are standardizing tablet protocols for chronic migraine prophylaxis, though CGRP antagonist formularies are eroding share at academic medical centers.
- Capsule:Gelatin and HPMC capsule shells offer excipient flexibility for modified-release matrix technologies. Specialty neurology centers in Spain are adopting capsule formulations for protocol-driven compliance programs, differentiating through once-daily dosing regimens.
- Injectable:Parenteral presentations serve acute hospital settings where rapid therapeutic onset matters.
- Powder:Bulk API powder supplies compounding pharmacies and regional manufacturers.
Tablet anchors the volume base while capsule gains share at the steepest rate through modified-release differentiation.
End User:
Cost tier stratification separates centralized hospital procurement from fragmented retail pharmacy dispensing. High-volume contract purchasers extract price concessions that mid-tier clinics cannot match.
- Hospitals:Centralized procurement bodies in Italy's regional health service clusters and Spain's autonomous community platforms consolidate annual flunarizine tenders into multi-year framework agreements. Neurology center networks in Germany standardize protocol-driven prescribing for chronic migraine populations.
- Clinics:Outpatient neurology practices in France maintain independent prescribing autonomy outside hospital formulary constraints.
- Pharmacies:Retail dispensing faces generic substitution pressure under national reimbursement frameworks.
- Homecare:Long-term prophylaxis patients in chronic therapy settings drive recurring prescription volumes.
Hospitals concentrate purchasing power while homecare expands most quickly as chronic therapy protocols extend treatment duration.
Therapy Area:
Application maturity varies sharply across neurological versus cardiovascular indications, with migraine prophylaxis facing the most intense therapeutic substitution.
- Neurology:Migraine and vertigo prophylaxis constitute the dominant therapeutic application with established clinical protocols. Specialty hospital clusters in Germany, Italy, and Spain are standardizing flunarizine protocols, though CGRP antagonist therapies are displacing calcium channel blockers at major US academic medical centers.
- Cardiology:Vascular smooth muscle relaxation properties support peripheral vascular disorder management.
- Psychiatry:Off-label applications in mood stabilization occupy niche prescriber segments.
- Pain Management:Chronic pain protocols extend utilization into broader prescriber bases beyond neurology specialists.
Neurology retains the revenue core while pain management climbs the fastest as prescribing expands beyond specialty boundaries.
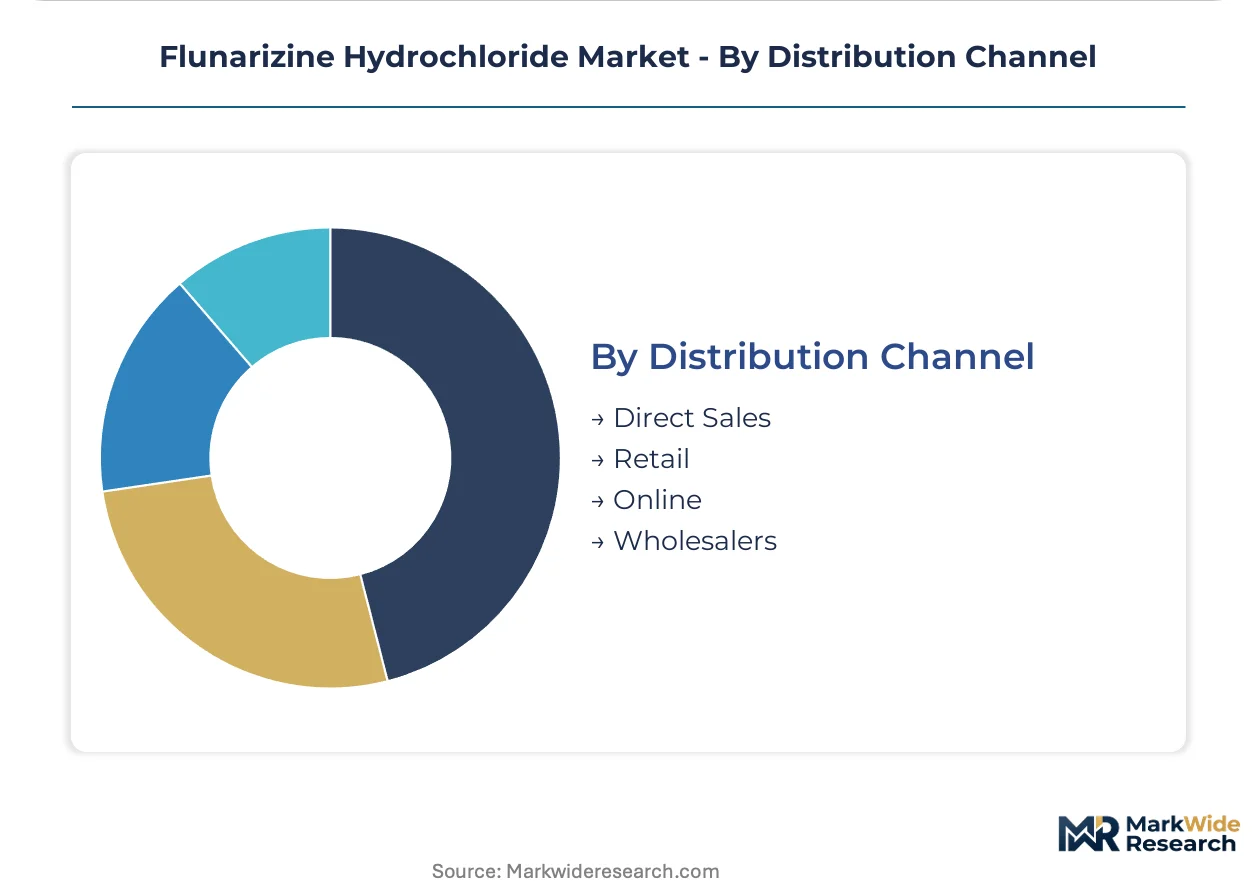
Distribution Channel:
Supply chain configuration separates direct manufacturer relationships from wholesale intermediaries, with margin capture shifting toward centralized procurement platforms.
- Direct Sales:Manufacturer agreements with hospital buying consortiums bypass wholesale distribution to capture margin otherwise lost to intermediaries. Italy's regional health service clusters and Spain's autonomous community purchasing platforms are consolidating volume through direct relationships.
- Retail:Community pharmacy networks serve outpatient prescription demand under national reimbursement schemes.
- Online:Digital pharmacy platforms face regulatory constraints for controlled substance equivalents.
- Wholesalers:Traditional distribution channels are losing volume to direct manufacturer contracting with centralized procurement bodies.
Direct sales anchors contract value while online channels face the steepest regulatory headwinds limiting expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement consolidation for migraine prophylaxis concentrates demand in neurology center clusters across Germany, Italy, and Spain. Specialty buying consortiums in these markets extract stringent bioequivalence documentation from suppliers. API manufacturing gravity sits with Indian and Chinese bulk producers serving regulated export markets.
Germany
Specialty neurology centers in Bavaria and North Rhine-Westphalia standardize flunarizine protocols for chronic migraine populations. EMA bioequivalence guidelines for generic neurological agents elevate quality barriers that favor established manufacturers with validated processes. Hospital buying consortiums in Baden-Württemberg consolidate annual tenders into multi-year framework agreements with direct manufacturer relationships.
Italy
Regional health service clusters in Lombardy and Emilia-Romagna drive centralized procurement volume for migraine prophylaxis. Italy's AIFA national reimbursement frameworks govern generic substitution pathways for calcium channel antagonists. Specialty hospital networks in Piedmont are adopting modified-release capsule formulations for protocol-driven compliance programs.
Spain
Autonomous community purchasing platforms in Catalonia and Madrid consolidate flunarizine volume through multi-year supply agreements. Spain's AEMPS pharmacovigilance requirements tighten post-market surveillance obligations for off-patent neurological agents. Neurology center clusters in the Basque Country standardize prescribing protocols that differentiate through once-daily dosing regimens.
India
API manufacturing concentrates in Maharashtra and Gujarat, where CDSCO regulates local production and export certification for bulk drug suppliers. India's PLI scheme for pharmaceutical manufacturing incentivizes capacity expansion among domestic producers. Finished-dose manufacturers in Telangana and Karnataka compete on cost-adjusted scale across emerging markets.
China
NMPA oversight governs API production in Jiangsu and Zhejiang provinces serving international buyers. China's dual carbon goals are reshaping environmental compliance requirements for chemical synthesis operations. Bulk drug producers in Shandong province have achieved export competitiveness through manufacturing scale and process optimization.
Flunarizine Hydrochloride Market Vendor Landscape
Player mix skews toward generic specialists with backward integration into API supply and multinational incumbents defending brand recognition in hospital formularies. The structure fragments across three tiers: research-origin multinationals with historical formulation expertise, mid-scale generic houses with manufacturing scale advantages, and API-forward integrated producers competing on cost. Dominant competitive moves include direct hospital contracting to bypass wholesale intermediaries and modified-release formulation differentiation to escape commodity pricing.
Among the multinational tier, Novartis AG occupies a position exemplifying historical formulation expertise and sustained brand recognition in European hospital channels. Teva Pharmaceutical Industries Ltd. anchors the integrated generic archetype through captive API supply and hospital formulary penetration. Sun Pharmaceutical Industries Ltd. represents the emerging-market scale vector, competing on cost-adjusted manufacturing across regulated and developing markets. These three patterns illustrate how competitive positioning fragments across origin-based differentiation, vertical integration depth, and geographic cost arbitrage.
| Leading Market Players |
|---|
| Novartis AG |
| Teva Pharmaceutical Industries Ltd. |
| Mylan N.V. |
| Sun Pharmaceutical Industries Ltd. |
| Dr. Reddy's Laboratories |
| Johnson & Johnson Services Inc. |
| Cipla Ltd. |
| Torrent Pharmaceuticals Ltd. |
| Alkem Laboratories Ltd. |
| Others |
Supply Flow & Price Mechanics
CGRP antagonist substitution in migraine prophylaxis simultaneously reshapes supply geography toward acute-care injectable presentations and compresses pricing economics for oral calcium channel blockers. Hospital buying consortiums in Germany and Italy exploit this therapeutic shift to extract steeper discounts from tablet manufacturers while maintaining premium positioning for parenteral formulations.
Pricing Analysis
Immediate-release tablet formulations command commodity pricing in outpatient markets while modified-release capsules capture modest premiums through compliance differentiation. Three-tier pricing structure across premium, standard, and economy levels separates patented originator brands from validated generics and unbranded commodity supply. Cost compression in standard-tier tablets is intensifying because CGRP antagonist formularies erode volume at academic medical centers. Retail pharmacy networks exhibit highest price sensitivity, whereas specialty neurology centers prioritize bioequivalence documentation over unit cost.
Supply Chain Analysis
Single-source piperazine derivative production in Gujarat and Maharashtra underwrites finished-dose manufacturing economics across regulated markets. API supply draws from Indian bulk chemical synthesis and Chinese intermediate processing, with formulation and packaging distributed to European hospital networks. Geographic concentration creates vulnerability to CDSCO environmental compliance actions. Distribution runs through direct manufacturer contracts with regional health service clusters, bypassing traditional wholesale intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
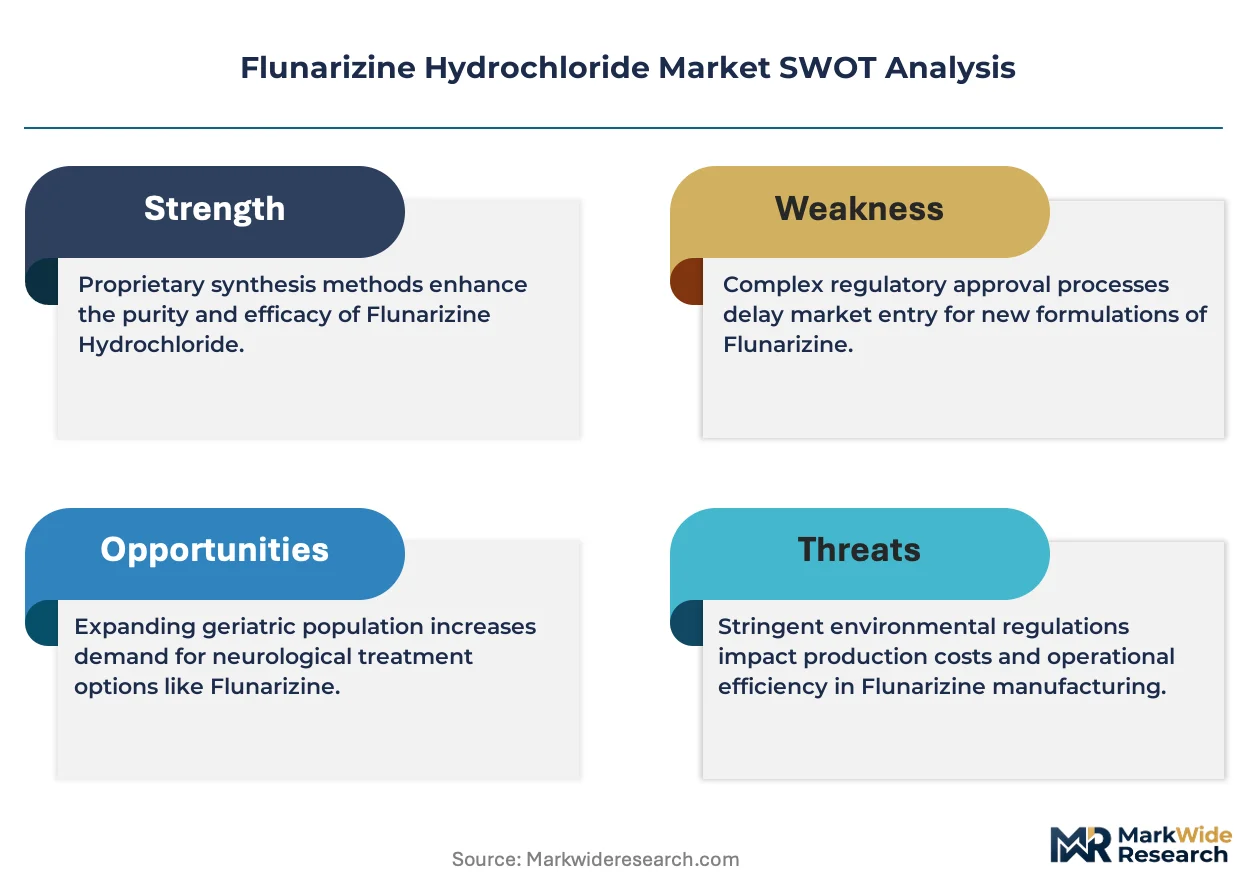
Flunarizine hydrochloride procurement is transitioning toward platform-economics consolidation as hospital buying consortiums standardize protocol-driven formularies across neurology center networks. Interoperability between EMA bioequivalence databases and national reimbursement systems accelerates generic substitution velocity.
For Market Incumbents: Fortify hospital formulary positioning through backward integration into piperazine API supply and accelerated modified-release capsule development. CGRP antagonist displacement threatens oral tablet volumes at US academic medical centers, demanding defensive investment in injectable presentation capacity and direct contracting with Italy's regional health service clusters. For New Entrants and Emerging Players: Brazil ANVISA certification fast-track opens first-mover positioning in Latin America's largest hospital market for established bioequivalence dossiers. Extended-release formulation differentiation in Spain's autonomous community purchasing platforms represents the most penetrable segment. Target direct supply agreements with centralized procurement bodies rather than wholesale channel penetration. For Investors and Strategic Acquirers: The market sits at a therapeutic substitution phase that favors API-integrated manufacturers with validated European supply chains. Long-term viability hinges on captive feedstock access and hospital contract tenure rather than brand equity. Watch CGRP antagonist formulary adoption rates at German and Italian academic medical centers as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Modified-Release Formulation Development | Once-daily dosing regimens improve adherence in chronic migraine populations across European hospital pharmacies. |
| Direct Hospital Contracting | Manufacturer agreements with Italy's regional health service clusters capture margin otherwise lost to wholesale intermediaries. |
| API Backward Integration | In-house piperazine derivative production insulates against CDSCO environmental compliance shutdowns in Gujarat. |
| Brazil ANVISA Regulatory Pathway | Accelerated generic approval timelines create first-mover positioning in Latin America's largest hospital market. |
| REACH Excipient Compliance Reformulation | Replacement of restricted phthalates and colorants maintains German and French hospital market access. |
Methodological Framework
Cross-validation between primary interviews with hospital procurement managers and secondary validation through EMA bioequivalence guidelines anchors the qualitative findings. Drug development executives, regulatory affairs leads, formulary directors, and payer access specialists provided forward-looking volume assumptions. FDA filings, EMA submissions, ClinicalTrials.gov records, and hospital procurement databases supplied quantitative benchmarks. Bottom-up patient-flow modeling and top-down therapeutic class sizing triangulated market estimates.
Sensitivity analysis tested forecast robustness across CGRP antagonist substitution scenarios and API supply disruption events. Segmentation dimensions included product form, therapy area, end-user concentration, and regional regulatory cluster. CAGRs were derived from normalized historical growth patterns adjusted for therapeutic substitution dynamics. Modeled inputs incorporated hospital tender consolidation velocity and REACH chemical safety compliance timelines.
Decision-makers should treat outputs as directional under stable CGRP antagonist formulary penetration and uninterrupted Indian API export certification; material deviation would warrant model refresh. Revision becomes warranted when CGRP antagonist share at major academic medical centers crosses thresholds that trigger wholesale protocol abandonment.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia-Pacific Adenomyosis Drugs Market
Pharmaceuticals
Nuclear Medicines Radioisotopes Market
Pharmaceuticals
Global Pharmaceutical Warehousing Market
Pharmaceuticals
Mail Order Pharmacy Market
Pharmaceuticals
Global Narcolepsy Drugs Market
Pharmaceuticals
North America Meglitinide Market
Pharmaceuticals
OTC Analgesic Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
Global Bispecific Antibody Therapeutics Market
Pharmaceuticals
Metoprolol Tartrate Market
Pharmaceuticals
Middle East and Africa Adenomyosis Drugs Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Global DNA Repair Drugs Market
Pharmaceuticals
Middle East and Africa Glucagon-Like Peptide-1 (GLP-1) Agonists Market
Pharmaceuticals
Exocrine Pancreatic Insufficiency Therapeutics Market