
 Lamotrigine API Market | 2026-2036
Lamotrigine API Market Size, Share, and Industry Trends Forecast 2026-2036
Lamotrigine API Market Insights
A capital-intensity divergence between large-scale chemical synthesizers and boutique API specialists is collapsing as mid-tier producers consolidate reactor capacity and automate purification trains. Polpharma leverages backward integration into key starting materials to sustain margin stability across European supply contracts. Cohance Lifesciences anchors its competitive stance through dedicated lamotrigine block production lines in India. Jai Radhe Sales competes on agile batch scheduling for generic formulation houses in emerging markets.
Lamotrigine API is the chemically synthesized active moiety, designated 6-(2,3-dichlorophenyl)-1,2,4-triazine-3,5-diamine, used primarily as an anticonvulsant and mood stabilizer in finished dosage forms; manufacturers typically employ dichlorophenylacetonitrile cyclization followed by triazine ring closure, with polymorph control critical for bioequivalence. Tablets dominate finished dosage demand due to established epilepsy maintenance therapy protocols, while oral suspension formats represent the fastest-expanding product type as pediatric and geriatric compliance requirements tighten. Epilepsy applications command the largest absolute volume, though bipolar disorder prescriptions are deepening the clinical addressable market for API suppliers.
US FDA enforces ICH Q7 guidelines through risk-based facility inspections, while India's CDSCO mandates BIS-equivalent process validation for export-oriented API sites; REACH compliance in Europe further constrains solvent discharge and impurity profiling thresholds. Regulatory convergence across these three jurisdictions is forcing manufacturers to unify quality management systems rather than operate geography-specific protocols. Stakeholders must monitor evolving pharmacopoeial monograph revisions and bioequivalence study requirements to anticipate specification-driven procurement shifts.
Market Dynamics
Regulatory convergence across FDA, EMA, and CDSCO jurisdictions is compressing quality management systems into unified protocols, forcing API manufacturers to abandon geography-specific compliance architectures and invest in single-platform validation infrastructure.
Growth Catalysts
- ICH Q7 harmonization:The FDA's risk-based inspection framework now aligns with India's CDSCO export mandates, reducing dual-audit burdens for multi-jurisdictional suppliers.
- Epilepsy maintenance protocols:Standardized tablet dosing regimens in neurology practices are stabilizing volume forecasts for long-term API procurement contracts.
- Polymorph control advances:Crystallization process automation is improving bioequivalence consistency across generic formulation batches.
Market Restraints
- Dichlorophenylacetonitrile cost volatility:The key starting material faces petrochemical feedstock price swings that transmit directly into lamotrigine API margin pressure.
- Indian supply concentration:Contract manufacturers in Hyderabad and Ahmedabad clusters dominate regulated-market output, creating geographic vulnerability to localized disruption.
- REACH solvent discharge limits:ECHA-mandated impurity profiling thresholds are elevating purification train capital requirements for European market access.
Strategic Opportunities
- Pediatric oral suspension formats:Geriatric and pediatric compliance requirements are opening formulation diversification paths beyond tablet-centric supply contracts.
- Bipolar disorder prescription expansion:Mood stabilizer applications are deepening the clinical addressable market beyond anticonvulsant demand alone.
- India PLI scheme alignment:Domestic API production incentives are enabling backward integration into key starting materials for export-oriented sites.
Industry Challenges
- Pharmacopoeial monograph revision tracking:USP, EP, and IP specification divergence demands dedicated regulatory intelligence functions to anticipate procurement-driven specification shifts.
- Reactor capacity reconfiguration:Mid-tier producers face capex intensity in automating purification trains to match consolidated large-scale chemical synthesizer throughput.
- Cross-functional quality talent scarcity:Unified ICH Q7 expertise spanning FDA, EMA, and CDSCO protocols remains concentrated among experienced regulatory affairs specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lamotrigine API Market |
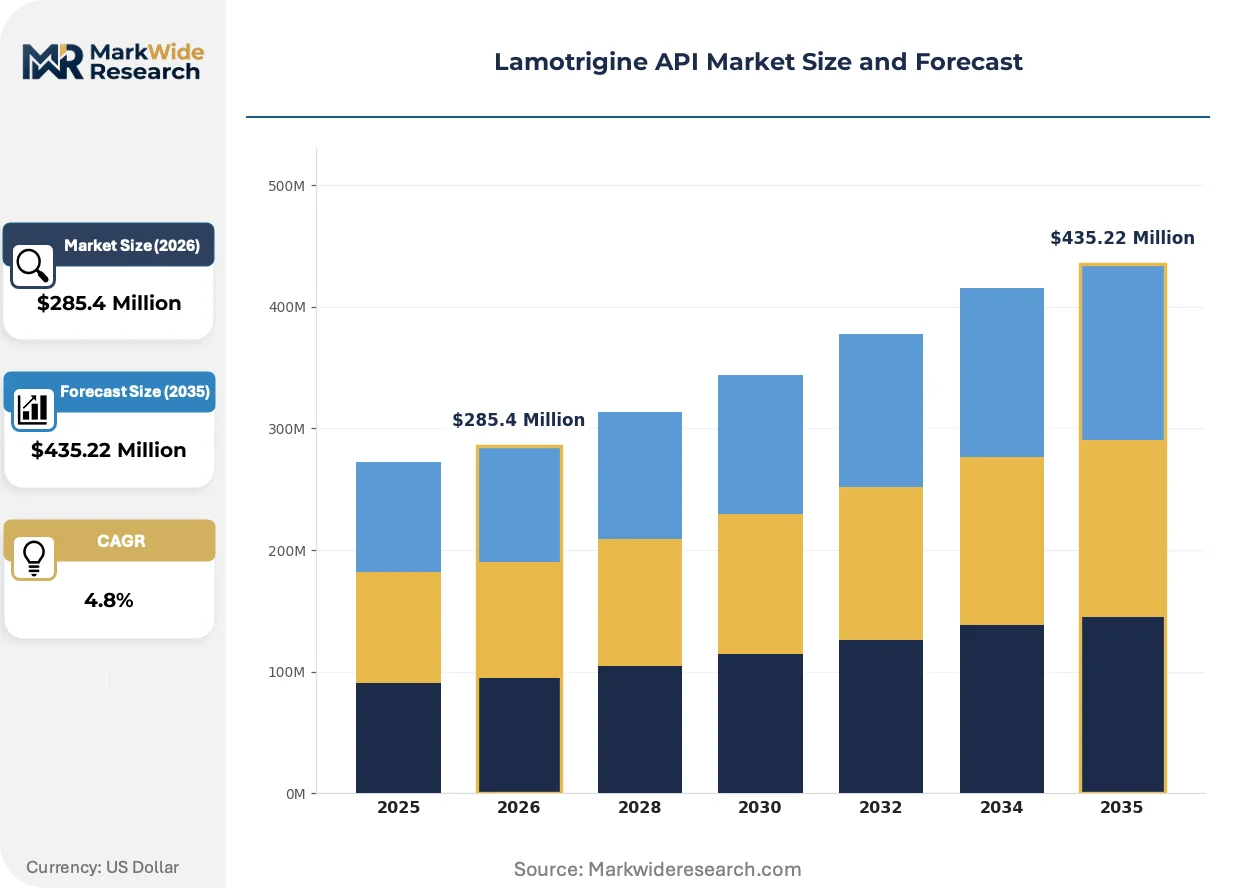
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $435.22 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Oral Suspension, Injectable End User: Hospitals, Pharmacies, Clinics, Home Care Application: Epilepsy, Bipolar Disorder, Depression, Anxiety Distribution Channel: Direct Sales, Wholesalers, Online Pharmacies, Retail Pharmacies |
| Companies Covered | Cohance Lifesciences, Jai Radhe Sales, IOL Chemicals and Pharmaceuticals, Tenatra Exports, HRV Pharma, Polpharma, CTX Lifesciences, Unichem Laboratories, LGM Pharma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lamotrigine API Market Trends and Innovations
Continuous processing technologies and real-time release testing are displacing batch-oriented manufacturing paradigms, compressing cycle times and enabling specification-driven procurement models that reward quality consistency over volume scale.
Flow chemistry reactor systems are miniaturizing traditional batch synthesis footprints while maintaining yield parity. European formulation houses are adopting these platforms for high-potency API production. The technology is miniaturizing capital barriers for mid-tier entrants seeking regulated-market compliance without billion-liter reactor investments.
EMA's revised GMP Annex 1 sterile manufacturing guidelines are extending contamination control requirements into API synthesis environments. Manufacturers serving European markets must now validate closed-system transfer protocols for lamotrigine intermediate handling. Oral suspension specialists face the steepest adaptation costs due to expanded bioburden testing mandates.
Formulation houses are consolidating supplier rosters around dual-source API contracts with embedded quality audits. Generic manufacturers in North America are displacing spot-market purchasing with multi-year procurement agreements that lock polymorph specifications and impurity profiles. This concentration is most visible among US-based epilepsy therapy marketers seeking supply security for maintenance therapy portfolios.
Lamotrigine API Market Segmentation
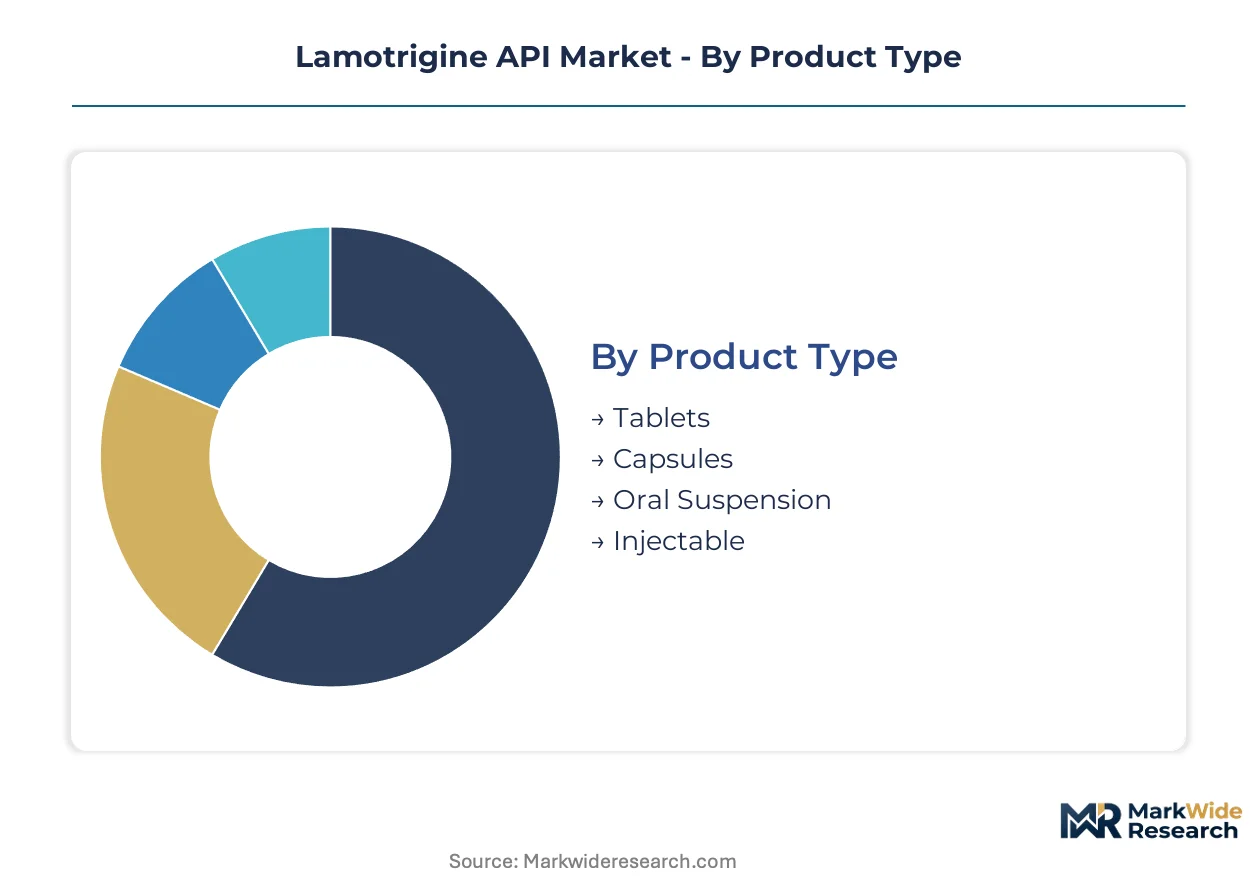
Lamotrigine API procurement patterns diverge sharply across formulation types and clinical settings, with regulatory filing requirements and bioequivalence protocols dictating supplier qualification criteria. Understanding these segment boundaries enables API manufacturers to align reactor capacity and polymorph control investments with specific downstream compliance burdens.
Product Type:
ICH Q7 validation intensity varies by finished dosage complexity, with sterile formats demanding closed-system manufacturing protocols that extend into API synthesis environments.
- Tablets:Compressed solid dosage forms dominate epilepsy maintenance therapy procurement due to established USP dissolution specifications and stability profiles. Hospital formularies in the United States and India anchor volume concentration, though pediatric compliance limitations constrain expansion in geriatric and adolescent segments.
- Oral Suspension:Liquid formulations with precise mg/mL dosing accommodate swallowing difficulties and titration flexibility. Demand concentrates in European pediatric markets where EMA palatability guidelines and Germany's BfArM dosing protocols drive formulation diversification beyond tablet-centric supply contracts.
- Capsules:Gelatin or HPMC shells encapsulate lamotrigine powder for patients requiring alternative excipient profiles. Niche positioning in Japan's PMDA-regulated markets where capsule dissolution rates accommodate specific bioequivalence study designs.
- Injectable:Parenteral formulations for acute seizure management require sterile API with endotoxin controls. Limited commercial penetration due to EMA Annex 1 contamination control capex and restricted clinical protocols in hospital emergency departments.
Established volume favors Tablets; emerging adoption favors Oral Suspension.
End User:
Procurement scale and quality documentation requirements separate institutional buyers from retail channels, with direct API supply relationships concentrating in high-volume hospital systems.
- Hospitals:Integrated health networks negotiate multi-year API supply agreements with embedded polymorph specifications. India's AIIMS Delhi and Christian Medical College Vellore anchor South Asian procurement concentration through centralized pharmacy and therapeutics committees.
- Pharmacies:Community and chain dispensaries source through wholesaler intermediaries with spot-market flexibility. Brazil's ANVISA-regulated retail networks and US independent pharmacies drive fragmented, specification-diverse demand patterns.
- Clinics:Outpatient neurological and psychiatric practices prescribe maintenance therapy with generic substitution protocols. Volume fragmentation across India's state-level clinic networks limits direct API manufacturer engagement.
- Home Care:Long-term therapy administration outside clinical settings emphasizes packaging stability and patient education materials. Germany's statutory health insurance reimbursement frameworks support adherence monitoring programs that extend API supply chain accountability.
Contract concentration favors Hospitals; patient access expansion favors Home Care.
Application:
Clinical indication determines API purity thresholds and impurity profiling stringency, with psychiatric applications requiring additional metabolite characterization for regulatory submissions.
- Epilepsy:Anticonvulsant applications command the largest absolute API volume through standardized monotherapy and adjunctive therapy protocols. FDA-approved labeling for Lennox-Gastaut syndrome and partial seizures sustains predictable procurement cycles across North American neurology practices.
- Bipolar Disorder:Mood stabilizer indications deepen the addressable market with maintenance therapy protocols that extend treatment duration. UK's NICE guidelines and Australia's TGA reimbursement listings are expanding prescriber familiarity beyond traditional anticonvulsant demand.
- Depression:Off-label and adjunctive use in treatment-resistant cases creates specification variability as formulation houses pursue differentiated bioequivalence positioning. Smaller batch requirements complicate API manufacturer production scheduling.
- Anxiety:Emerging prescriber experimentation with lamotrigine for generalized anxiety disorder generates exploratory demand without established dosing protocols. Regulatory uncertainty constrains committed API procurement contracts.
Volume stability anchors Epilepsy; prescription expansion drives Bipolar Disorder fastest.
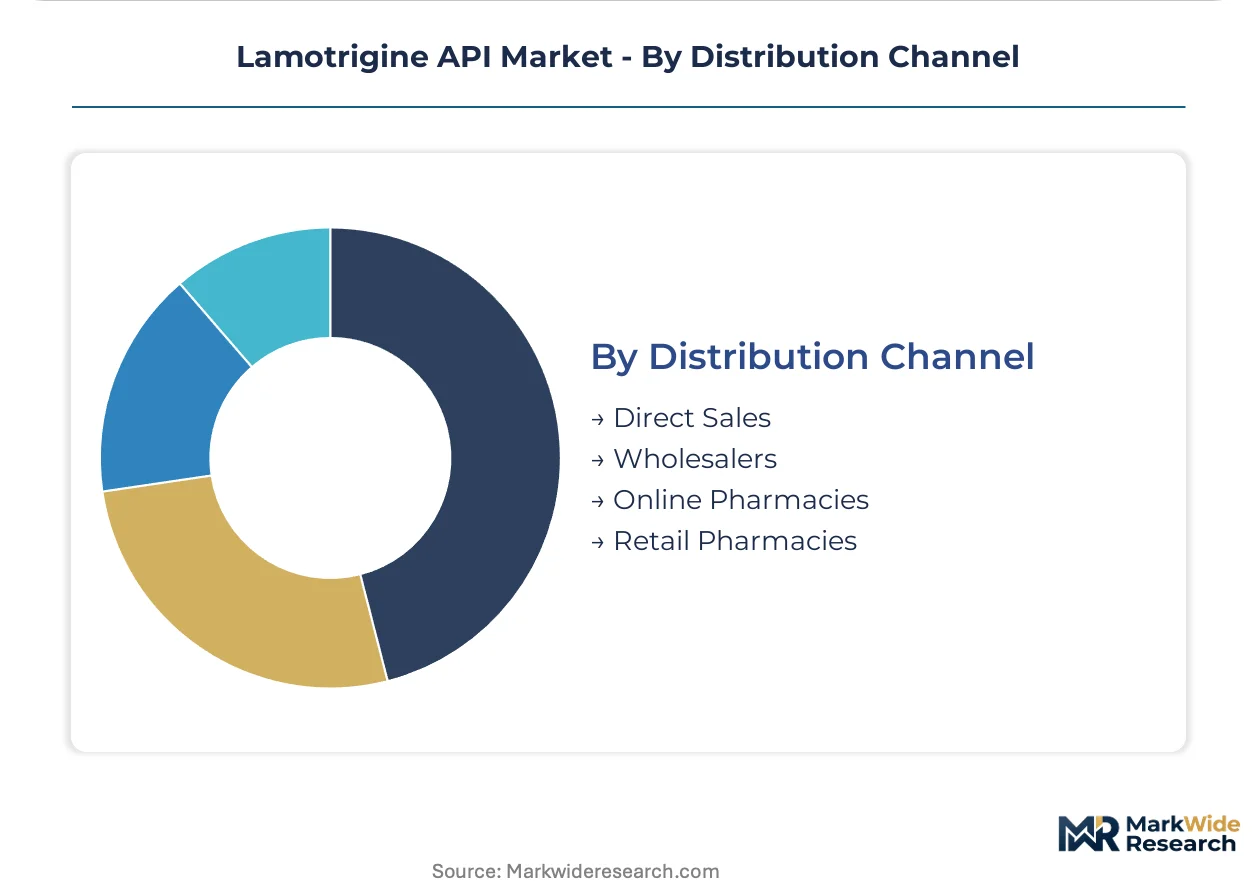
Distribution Channel:
Channel structure determines audit depth and quality agreement complexity, with direct relationships enabling real-time release testing integration.
- Direct Sales:API manufacturers supply finished dose formulators under master service agreements with dedicated polymorph specifications. India's Sun Pharmaceutical and Cipla maintain direct procurement relationships with Hyderabad-based API clusters for regulated-market export.
- Wholesalers:Aggregated distribution through McKesson and AmerisourceBergen in the United States buffers API manufacturers from pharmacy-level specification fragmentation. Inventory carrying costs and lot traceability requirements elevate working capital intensity.
- Online Pharmacies:Digital dispensaries in Germany's DocMorris network and India's 1mg platform create last-mile demand visibility challenges for API supply planning. Temperature excursion risks during shipping extend liability upstream.
- Retail Pharmacies:CVS Health and Walgreens Boots Alliance in the United States, plus India's Apollo Pharmacy chain, source through hybrid direct-wholesaler models. Generic substitution protocols at the point of sale decouple API manufacturer visibility from actual patient consumption.
Supply security concentrates in Direct Sales; patient convenience drives Online Pharmacies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry separates Indian contract manufacturers from European specialty chemical houses, with Hyderabad-based API clusters capturing volume contracts while Basel and Warsaw producers command specification premiums for polymorph-controlled supply.
United States
FDA's risk-based inspection framework and IRA drug pricing provisions reshape procurement calculus for epilepsy therapy marketers. Indianapolis and Research Triangle Park formulation houses consolidate supplier rosters around dual-source agreements with embedded ICH Q7 audit protocols. New Jersey distribution hubs buffer working capital intensity through McKesson and AmerisourceBergen aggregation.
India
CDSCO export mandates and PLI scheme incentives accelerate backward integration into dichlorophenylacetonitrile starting materials. Hyderabad and Ahmedabad manufacturing clusters dominate regulated-market output for North American and European formulation houses. Telangana's Genome Valley corridor anchors dedicated lamotrigine block production lines with automated purification trains.
Germany
EMA's revised GMP Annex 1 sterile guidelines extend contamination control requirements into API synthesis environments. Frankfurt and Ludwigshafen chemical parks validate closed-system transfer protocols for intermediate handling. BfArM dosing protocols for pediatric oral suspension drive formulation diversification beyond tablet-centric supply.
China
NMPA's alignment with ICH Q7 and dual carbon goals compress solvent discharge allowances for triazine ring closure processes. Zhejiang and Jiangsu province API manufacturers face REACH-equivalent impurity profiling thresholds for European market access. Shanghai chemical industrial zones invest in continuous processing technologies to match Indian batch scale economics.
United Kingdom
NICE guidelines for bipolar disorder maintenance therapy expand prescriber familiarity beyond anticonvulsant demand. London and Manchester hospital formularies negotiate multi-year supply agreements with polymorph specifications locked. MHRA post-Brexit divergence from EMA monographs demands dedicated regulatory intelligence functions for specification tracking.
Lamotrigine API Market Competitive Landscape
Concentration sits with mid-tier Indian contract manufacturers that have consolidated reactor capacity and automated purification trains to match large-scale chemical synthesizer throughput. The vendor base stratifies across three archetypes: integrated pharmaceutical conglomerates with captive API supply, standalone API specialists serving generic formulation houses, and emerging flow chemistry adopters miniaturizing capital barriers. Dominant competitive moves include backward integration into key starting materials and multi-year procurement agreements that lock polymorph specifications.
Among Indian API specialists, Cohance Lifesciences anchors dedicated lamotrigine production capacity in Hyderabad's industrial corridor, exemplifying the mid-tier consolidation archetype. Jai Radhe Sales occupies a position serving agile batch scheduling requirements for emerging market generic houses. Polpharma represents the European integrated model, with Warsaw-based operations leveraging upstream control over starting material supply chains for margin stability across continental contracts.
| Leading Market Players |
|---|
| Cohance Lifesciences |
| Jai Radhe Sales |
| IOL Chemicals and Pharmaceuticals |
| Tenatra Exports |
| HRV Pharma |
| Polpharma |
| CTX Lifesciences |
| Unichem Laboratories |
| LGM Pharma |
| Others |
Pricing and Supply Chain Analysis
Multi-year procurement agreements with embedded polymorph specifications lock in supply access for North American formulation houses while constraining spot-market price volatility. ICH Q7 audit protocols embedded in these contracts elevate supplier qualification costs, compressing margin flexibility for mid-tier Indian manufacturers serving FDA-regulated buyers.
Pricing Analysis
Configured-to-order pricing for polymorph-controlled lamotrigine API commands substantial premiums over standard-grade spot supply. Three-tier pricing structure across premium, standard, and economy levels stratifies by ICH Q7 certification tier and batch-specific impurity profiling depth. Cost compression in standard-grade supply is intensifying as Hyderabad manufacturers automate purification trains to match consolidated throughput. Hospital systems negotiating direct sales contracts exhibit lowest price sensitivity due to supply security priorities, while emerging market generic houses sourcing through distributors face acute margin pressure.
Supply Chain Analysis
India and China anchor global lamotrigine API production, with Hyderabad and Ahmedabad clusters dominating regulated-market output for Western formulation houses. Dichlorophenylacetonitrile starting material and specialized triazine cyclization catalysts constitute critical input dependencies. Single-source vulnerability concentrates in Indian contract manufacturers lacking backward integration into petrochemical feedstocks. Distribution runs through McKesson and AmerisourceBergen aggregation in North America, while European channels validate closed-system transfer protocols under EMA Annex 1 guidelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory convergence across FDA, EMA, and CDSCO jurisdictions fragments supplier qualification requirements, creating white-space opportunities for specialized compliance service providers and boutique API manufacturers.
For Market Incumbents: Shield margin stability through captive dichlorophenylacetonitrile production or long-term offtake agreements with petrochemical suppliers. Consolidate reactor capacity in Telangana's Genome Valley corridor to match throughput of large-scale chemical synthesizers. Certification investment in continuous processing technologies defends against flow chemistry entrants miniaturizing capital barriers. For New Entrants and Emerging Players: Anchor in pediatric oral suspension formats where EMA palatability guidelines and Germany's BfArM dosing protocols create specification complexity that favors agile batch schedulers. European formulation houses seeking dual-source security beyond Indian supply concentration represent the most penetrable buyer segment. Go-to-market positioning should emphasize real-time release testing integration and dedicated polymorph control capabilities. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier Indian API specialists with automated purification trains and existing ICH Q7 audit histories across multiple jurisdictions. Long-term viability hinges on backward integration economics and regulatory intelligence functions spanning pharmacopoeial monograph divergence. The signal to watch is CDSCO enforcement intensity on export-oriented sites, which would accelerate consolidation among compliance-constrained producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Key Starting Materials | Captive dichlorophenylacetonitrile supply insulates margin stability from petrochemical feedstock volatility. |
| Continuous Processing Technology Adoption | Flow chemistry reactor systems compress cycle times and enable real-time release testing for specification-driven procurement. |
| Multi-Jurisdictional ICH Q7 Certification | Unified quality management systems reduce dual-audit burdens for suppliers serving FDA, EMA, and CDSCO markets simultaneously. |
| Pediatric Oral Suspension Format Expansion | EMA palatability guidelines and geriatric compliance requirements deepen addressable market beyond tablet-centric supply contracts. |
| Dual-Source Procurement Agreement Structuring | Embedded polymorph specifications and quality audits lock in supply security for epilepsy maintenance therapy portfolios. |
Research Methodology
Cross-validation between primary interviews with regulatory affairs specialists and secondary validation through FDA 483 observation databases, EMA GMP inspection records, and CDSCO export approval registries anchors the qualitative findings. Conversations with API manufacturing plant managers, formulation house procurement directors, hospital pharmacy and therapeutics committee members, and generic drug regulatory consultants informed supply chain dynamics and procurement pattern assessment. Bottom-up volume modeling triangulates against top-down market sizing derived from customs trade data and pharmaceutical import statistics.
Sensitivity analysis around dichlorophenylacetonitrile cost volatility and ICH Q7 compliance capex intensity tests forecast robustness across the projection horizon. Segmentation dimensions modeled include finished dosage form complexity, clinical indication, distribution channel structure, and regional regulatory cluster. CAGRs derive from regression analysis of historical API procurement volumes against epilepsy and bipolar disorder prescription trends, with bipolar disorder maintenance therapy protocol expansion serving as a key demand-side inflection input.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory convergence and stable petrochemical feedstock pricing; material deviation in either would warrant model refresh. Recalibration cycles align with material shifts in pharmacopoeial monograph revisions, bioequivalence study requirement changes, and CDSCO export mandate enforcement intensity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Atypical Antipsychotic Market
Pharmaceuticals
Asia-Pacific Meglitinide Market
Pharmaceuticals
Flumazenil Market
Pharmaceuticals
Adapalene Products Market
Pharmaceuticals
Next-Generation Immunology Drugs Market
Pharmaceuticals
Antidiuretic Drugs Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Isoflurane Market
Pharmaceuticals
Global Prophylactic HIV Drugs Market
Pharmaceuticals
Global Liposome Drug Delivery Market
Pharmaceuticals
Japanese Encephalitis Vaccine Market
Pharmaceuticals
Paracetamol IV Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market
Pharmaceuticals
Pharmaceutical Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceuticals
Hepatitis - B Therapeutics Market