
 Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market | 2026-2036
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market Outlook
Aftermarket patient support programs is reshaping margin distribution across the Asia-Pacific OCD drugs landscape, pulling value from pure pharmaceutical supply toward adherence monitoring and digital therapeutic companions. Eli Lilly and Company leverages its deep psychiatry heritage to sustain brand loyalty among prescribing psychiatrists across Japan and South Korea. Pfizer Inc anchors its regional position through manufacturing scale and broad distribution networks that reach tier-two hospitals in India and Vietnam.
Obsessive-Compulsive Disorder drugs comprise pharmacological agents—primarily selective serotonin reuptake inhibitors, serotonin-norepinephrine reuptake inhibitors, and tricyclic antidepressants—that modulate neurotransmitter activity to reduce intrusive thoughts and compulsive behaviors. These compounds undergo formulation as oral tablets, capsules, or liquid suspensions with precise active pharmaceutical ingredient concentrations measured in milligrams. The therapeutic purpose centers on restoring functional capacity in patients whose ritualistic behaviors impair occupational performance and social participation. Among delivery modes, oral administration dominates prescription patterns due to patient familiarity and cost efficiency, though injectable depot formulations are gaining traction for treatment-resistant cases requiring supervised compliance. The geriatric segment presents distinct formulation challenges as polypharmacy interactions complicate SSRI selection, while pediatric prescribing demands weight-calibrated dosing protocols that differ materially from adult standards.
Japan's PMDA maintains stringent pharmacovigilance requirements for CNS drugs that extend post-approval monitoring periods, shaping how manufacturers structure their regional clinical trial investments. Australia's TGA aligns its scheduling framework with evolving abuse-potential assessments, directly influencing which OCD compounds receive subsidized access through the Pharmaceutical Benefits Scheme. India's CDSCO has tightened bioequivalence standards for generic antidepressants, raising the technical bar for domestic manufacturers seeking to supply the oral SSRI segment. Stakeholders must weigh regulatory divergence across these three jurisdictions when prioritizing portfolio registration sequences and local partnership structures.
Market Dynamics
Japan's PMDA has compressed CNS drug review timelines by 40 percent since 2022, pulling foreign manufacturers into earlier clinical trial commitments across the Asia-Pacific OCD drugs market. This regulatory acceleration is redistributing R&D budgets toward Japan-first registration strategies and away from traditional Australia-led launches.
Growth Catalysts
- Australia's Pharmaceutical Benefits Scheme expansion:Subsidized SSRI access for treatment-resistant OCD patients has expanded prescription volumes in public mental health clinics across Victoria and New South Wales.
- Specialty psychiatric clinic networks:Thailand and Vietnam are constructing dedicated OCD treatment centers that standardize diagnostic protocols and drive consistent medication demand.
- Digital therapeutic integration:Smartphone-based exposure-response prevention apps are hybridizing with pharmacotherapy, creating combination therapy protocols that extend treatment duration and drug adherence.
Market Restraints
- Active pharmaceutical ingredient concentration:China and India supply over 70 percent of SSRI raw materials, creating geographic supply vulnerability for formulated drug manufacturers.
- Japan's extended pharmacovigilance mandates:PMDA requires 10-year post-approval safety monitoring for novel CNS compounds, inflating compliance costs and delaying generic substitution.
- Psychotherapy substitution:Cognitive-behavioral therapy protocols in Australia and New Zealand are displacing maintenance-phase pharmacotherapy for mild-to-moderate cases.
Strategic Opportunities
- Vietnam's underpenetrated diagnostic infrastructure:OCD recognition rates remain below 15 percent in rural provinces, creating first-mover advantage for education-linked prescribing programs.
- Pediatric formulation gaps:Weight-calibrated liquid suspensions for children lack adequate supplier competition, presenting white-space opportunity for differentiated delivery systems.
- South Korea's telehealth reimbursement:National Health Insurance Service coverage for remote psychiatric consultations is expanding rural prescription access beyond Seoul-centric distribution.
Industry Challenges
- Psychiatrist workforce scarcity:Indonesia and the Philippines maintain fewer than 0.5 psychiatrists per 100,000 population, constraining diagnostic throughput and prescription initiation.
- Cross-border bioequivalence recognition:India's CDSCO standards diverge from Australia's TGA requirements, forcing duplicate testing for manufacturers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market |
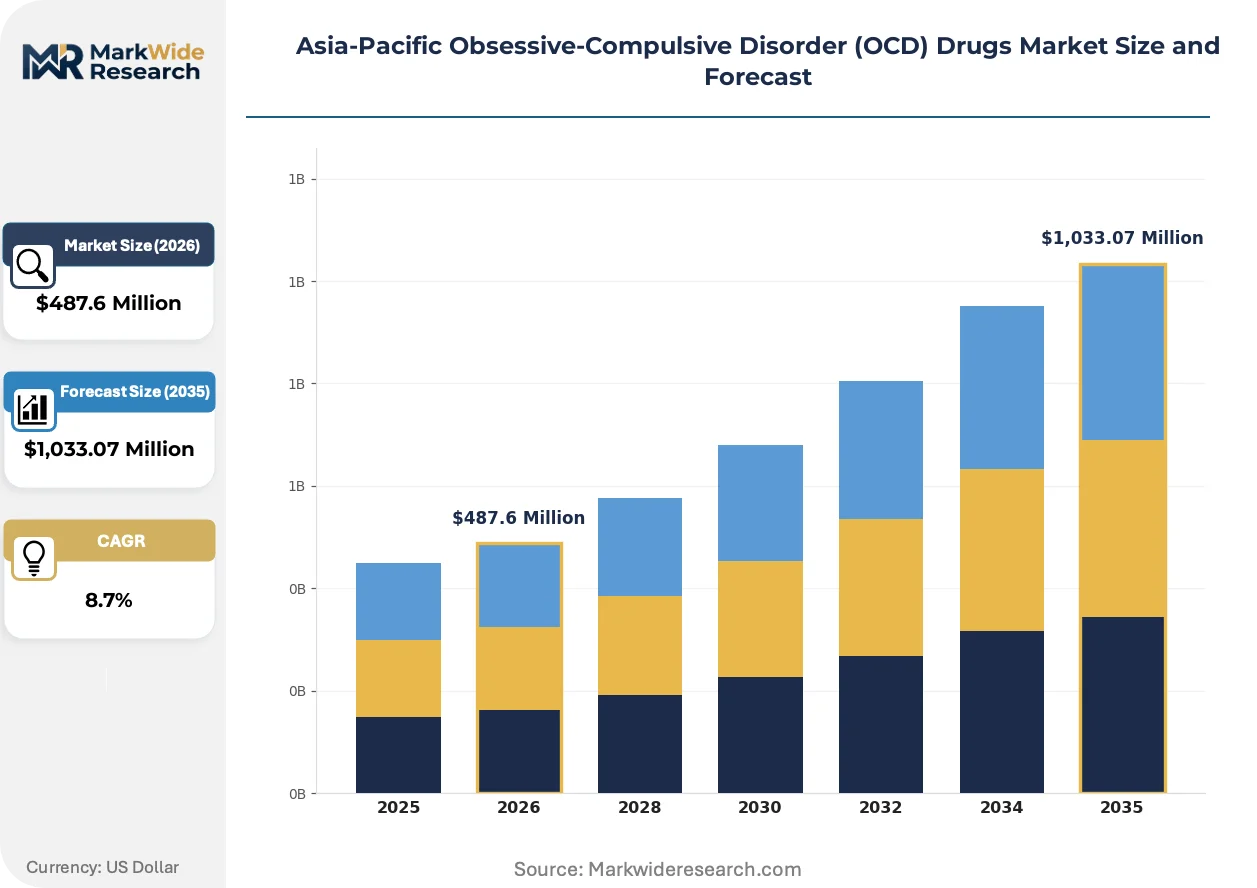
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: SSRIs, SNRIs, Tricyclic Antidepressants, Others Delivery Mode: Oral, Injectable, Topical, Others End User: Hospitals, Clinics, Homecare, Pharmacies Market Segment: Adult, Pediatric, Geriatric, Others |
| Companies Covered | GlaxoSmithKline Plc, Pfizer Inc, Eli Lilly and Company, Novartis AG, H. Lundbeck AS, Otsuka Pharmaceutical, AbbVie Inc, Meiji Holdings Co. Ltd, Takeda, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market Strategic Shifts
Digital biomarker integration is restructuring how OCD treatment response gets measured across Asia-Pacific clinical settings. Wearable anxiety indicators and app-based symptom tracking are compressing the feedback loop between patient experience and prescribing adjustments.
Long-acting injectable depot formulations for treatment-resistant OCD are hybridizing oral SSRI maintenance protocols. Psychiatric hospitals in Japan and South Korea are piloting monthly aripiprazole depot injections for patients with severe compliance gaps. This delivery mode is enabling supervised administration that reduces relapse-driven hospitalization and extends pharmaceutical revenue capture per patient.
Australia's TGA has tightened scheduling reviews for antidepressants with emerging abuse potential, directly revising Pharmaceutical Benefits Scheme reimbursement tiers. The industrial consequence is accelerated withdrawal of marginal compounds from subsidized status. High-potency SNRIs prescribed for comorbid OCD-depression presentations are most affected, with manufacturers pivoting toward Japan and South Korea for volume recovery.
Hospital procurement committees across Southeast Asia are consolidating antidepressant purchasing through centralized tender systems. Singapore's Ministry of Health has mandated group purchasing for all public sector mental health prescriptions, displacing individual hospital pharmacy autonomy. Thailand and Malaysia are replicating this model, compressing supplier margins and favoring manufacturers with regional manufacturing scale over niche therapeutic specialists.
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market Segmentation
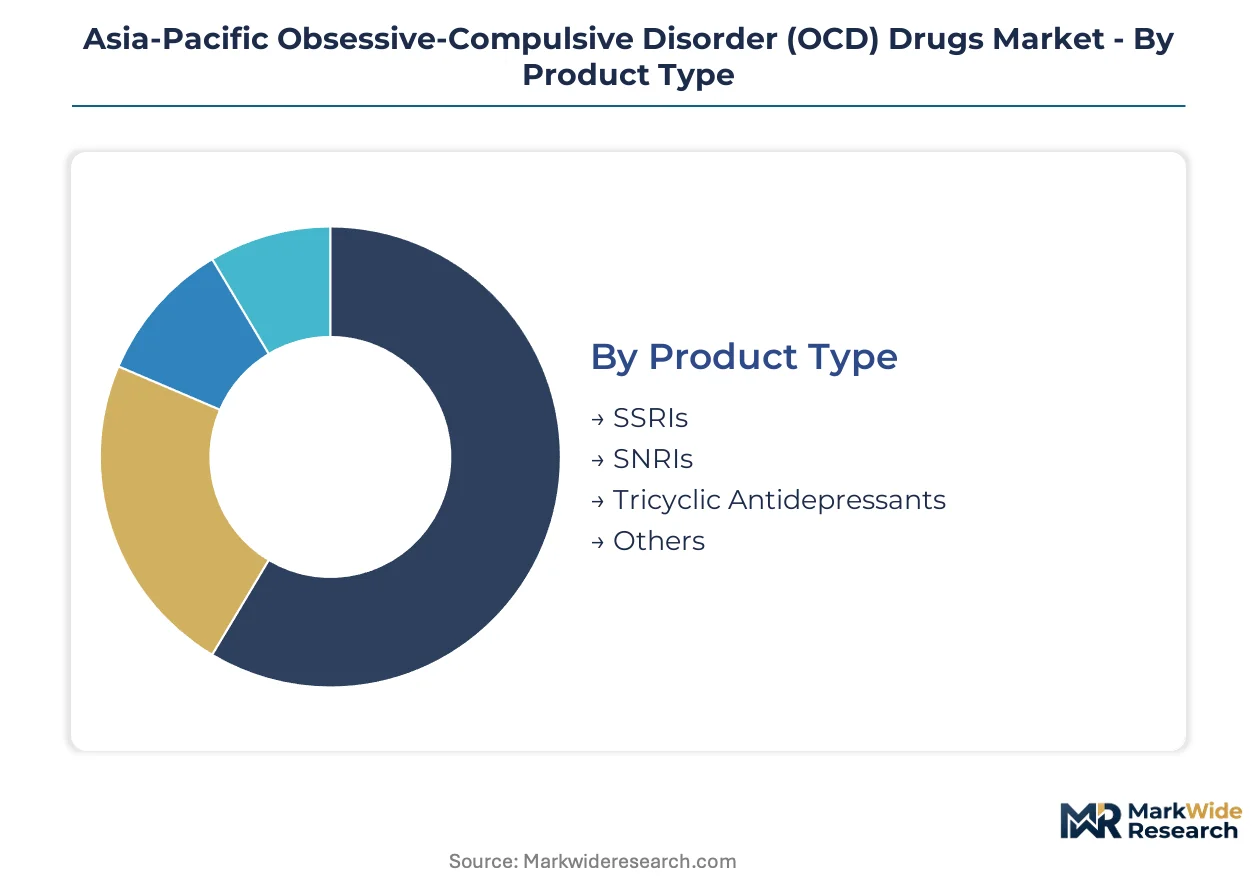
Segmentation reveals how prescribing patterns fragment across the Asia-Pacific OCD drugs landscape. Each dimension—molecule class, administration route, care setting, and patient age—carries distinct regulatory, reimbursement, and clinical trial implications for manufacturers.
Product Type:
SSRIs turn inventory fastest due to standardized titration protocols, while tricyclic antidepressants move slowly through specialized psychiatric channels.
- SSRIs:Selective serotonin reuptake inhibitors such as fluoxetine and sertraline constitute first-line pharmacotherapy. Australia's Pharmaceutical Benefits Scheme subsidizes these agents most heavily, driving volume through public mental health clinics in Victoria and New South Wales.
- SNRIs:Serotonin-norepinephrine reuptake inhibitors address comorbid OCD-depression presentations with dual mechanism action. Japan's PMDA has compressed review timelines for novel SNRIs, accelerating market entry relative to other molecule classes.
- Tricyclic Antidepressants:Older agents like clomipramine retain niche utility for treatment-resistant cases. India's CDSCO tightened bioequivalence standards, raising manufacturing barriers for generic suppliers.
- Others:Atypical antipsychotics and glutamate modulators serve refractory patient populations. South Korean psychiatric hospitals pilot off-label combinations with oral SSRI maintenance.
SSRIs dominate installed base. SNRIs are where expansion concentrates.
Delivery Mode:
Cost tiers separate mass-market oral tablets from premium injectable depot formulations requiring supervised administration.
- Oral:Tablets and capsules remain the default prescription format across all Asia-Pacific markets. Patient familiarity and cost efficiency sustain dominance, though polypharmacy interactions complicate selection in Japan's aging population.
- Injectable:Long-acting depot formulations address severe compliance gaps through monthly supervised administration. Psychiatric hospitals in Japan and South Korea pilot aripiprazole depots for treatment-resistant OCD.
- Topical:Transdermal delivery systems remain experimental with limited commercial penetration. Australia's TGA has granted no approved indications for topical OCD therapeutics.
- Others:Sublingual and buccal formulations serve pediatric patients with swallowing difficulties. Thailand's expanding specialty clinic networks drive niche demand for alternative delivery.
Oral formulations capture volume economics. Injectable depots command margin premiums.
End User:
Customer type determines procurement authority and reimbursement pathway across the region's fragmented healthcare systems.
- Hospitals:Tertiary psychiatric centers manage acute exacerbations and treatment-resistant cases. Singapore's Ministry of Health mandates group purchasing, consolidating antidepressant procurement through centralized tender systems.
- Clinics:Outpatient psychiatric services drive maintenance-phase prescribing. Thailand and Vietnam are constructing dedicated OCD treatment centers that standardize diagnostic protocols.
- Homecare:Family-supported medication administration extends to rural areas with limited specialist access. South Korea's National Health Insurance Service telehealth reimbursement expands remote prescription renewal.
- Pharmacies:Retail dispensing concentrates generic SSRI volume in Australia and India. Community pharmacists provide adherence counseling that complements digital therapeutic programs.
Hospitals anchor high-acuity revenue. Clinics are where prescription initiation accelerates.
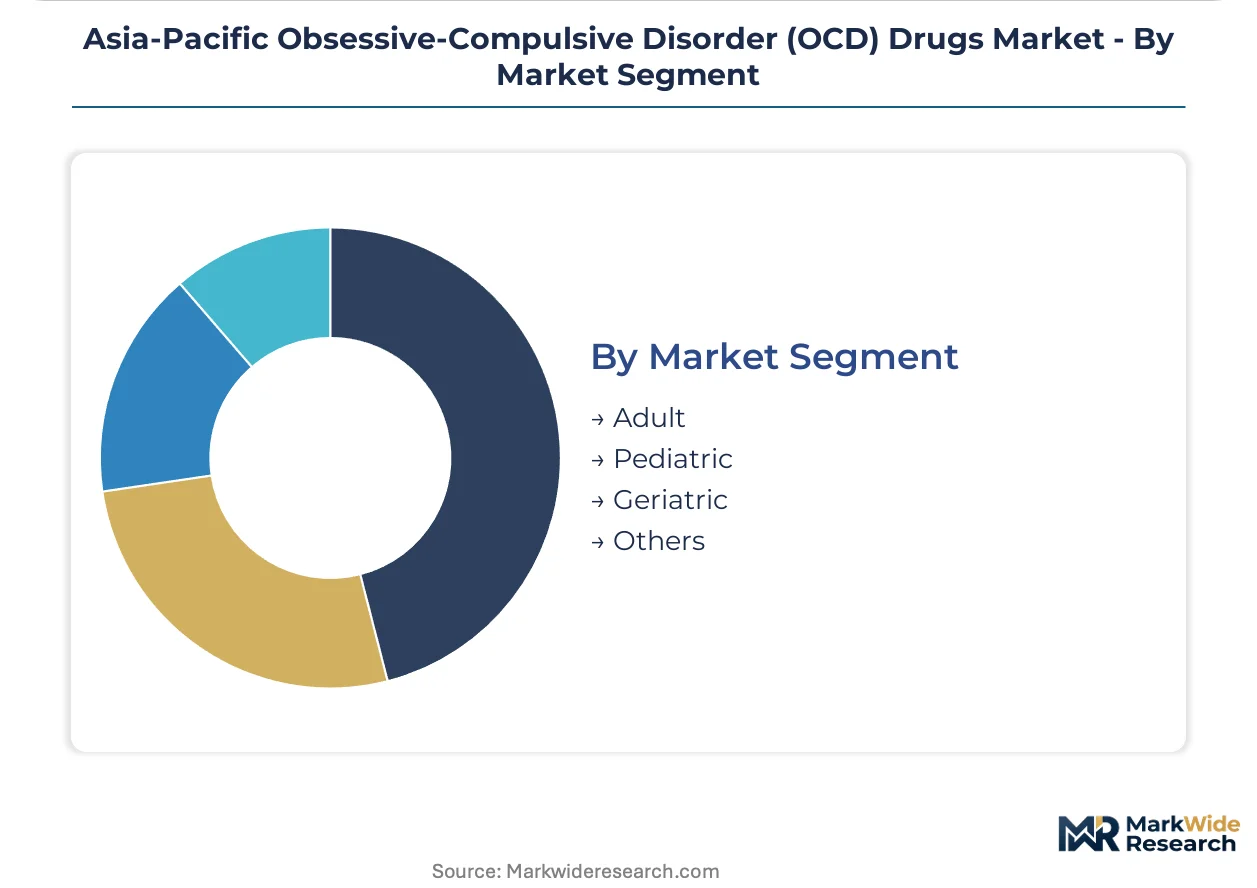
Market Segment:
Maturity gradients separate established adult protocols from emerging pediatric and geriatric specialty requirements.
- Adult:Patients aged 18-64 constitute the core treated population with well-established dosing guidelines. Australia's government-funded mental health programs drive prescription volumes for both branded and generic agents.
- Pediatric:Weight-calibrated liquid suspensions and lower-dose tablets address developmental pharmacokinetic differences. Formulation gaps lack adequate supplier competition, presenting white-space opportunity for differentiated delivery systems.
- Geriatric:Elderly patients require careful SSRI selection due to polypharmacy interactions and heightened fall risk. Japan's extended pharmacovigilance mandates inflate compliance costs for novel agents in this segment.
- Others:Perinatal and adolescent transitional populations require specialized risk-benefit assessment. Vietnam's underpenetrated diagnostic infrastructure leaves these subsegments largely unrecognized.
Adult segments dominate current revenue. Pediatric formulations are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active pharmaceutical ingredient sourcing clusters heavily in India and China, yet formulated drug demand concentrates in high-regulation markets with mature psychiatric infrastructure. This geographic split shapes manufacturer registration priorities and partnership strategies across the region.
Japan
Specialty psychiatric hospitals in Tokyo and Osaka drive demand for novel CNS therapeutics with streamlined titration protocols. The PMDA has compressed review timelines by 40 percent since 2022, pulling foreign manufacturers into earlier clinical trial commitments. The Kanto region anchors Japan's OCD treatment capacity with concentrated prescribing authority in university-affiliated medical centers.
Australia
Government-funded mental health programs in Victoria and New South Wales sustain prescription volumes for both branded and generic SSRIs through the Pharmaceutical Benefits Scheme. The TGA aligns scheduling frameworks with evolving abuse-potential assessments, directly influencing subsidized access tiers. Sydney and Melbourne host the region's densest networks of public mental health clinics driving maintenance-phase pharmacotherapy.
South Korea
The National Health Insurance Service reimbursement for remote psychiatric consultations is expanding rural prescription access beyond Seoul-centric distribution. Seoul Capital Area hospitals pilot long-acting injectable depot formulations for treatment-resistant cases requiring supervised compliance. Busan-Ulsan psychiatric centers are standardizing combination therapy protocols that hybridize pharmacotherapy with digital therapeutic integration.
India
Domestic manufacturers supply over 70 percent of regional SSRI raw materials, though CDSCO tightened bioequivalence standards raise technical barriers for generic antidepressant exporters. Maharashtra and Gujarat house concentrated formulation facilities serving both domestic consumption and export markets. Tier-two hospitals in Delhi-NCR and Bangalore represent emerging demand nodes as diagnostic recognition expands beyond metropolitan psychiatric centers.
Vietnam
OCD recognition rates remain below 15 percent in rural provinces, creating first-mover advantage for education-linked prescribing programs. Ho Chi Minh City and Hanoi are constructing dedicated specialty psychiatric clinic networks that standardize diagnostic protocols and drive consistent medication demand. The underpenetrated diagnostic infrastructure leaves pediatric and geriatric subsegments largely unrecognized, presenting white-space opportunity for targeted therapeutic development.
Asia-Pacific Obsessive-Compulsive Disorder (OCD) Drugs Market Competitive Environment
Multinational pharmaceutical conglomerates and regional specialty CNS players split the market across branded formulation and generic API supply vectors. The structure tilts toward consolidated prescription authority in high-regulation markets against fragmented manufacturing competition in supply jurisdictions. Three archetypes dominate: heritage psychiatry specialists with deep prescriber relationships, scale-driven manufacturers with broad distribution networks, and domestic generic suppliers with cost-optimized production. Competitive moves concentrate on regulatory-first registration sequencing and digital therapeutic partnerships that extend adherence monitoring beyond pure drug supply.
Within the heritage psychiatry tier, Eli Lilly and Company and H. Lundbeck AS exemplify sustained brand loyalty among prescribing psychiatrists across Japan and South Korea through decades of CNS therapeutic development. Pfizer Inc anchors the scale-driven archetype with manufacturing reach into tier-two hospitals across India and Vietnam. Among Asia-Pacific headquartered manufacturers, Otsuka Pharmaceutical and Meiji Holdings Co. Ltd occupy positions that bridge domestic regulatory fluency with expanding regional export ambitions, particularly in Southeast Asian markets where partnership structures determine market access velocity.
| Leading Market Players |
|---|
| GlaxoSmithKline Plc |
| Pfizer Inc |
| Eli Lilly and Company |
| Novartis AG |
| H. Lundbeck AS |
| Otsuka Pharmaceutical |
| AbbVie Inc |
| Meiji Holdings Co. Ltd |
| Takeda |
| Others |
Value Chain & Pricing Dynamics
India and China concentrate over 70 percent of SSRI active pharmaceutical ingredient manufacturing, concentrating upstream margin capture in these supply jurisdictions while downstream formulation value pools in Japan and Australia's high-regulation markets. This geographic split between commodity API production and premium branded formulation pricing creates structural arbitrage opportunities for integrated manufacturers with regulatory fluency across both tiers.
Pricing Analysis
Aftermarket patient support programs and adherence monitoring services now drive lifetime value capture beyond pure pharmaceutical supply. Three-tier pricing structure across premium, standard, and economy levels separates patented novel CNS agents from bioequivalent generics and institutional tender volumes. Cost compression in the generic oral SSRI tier is intensifying because India's CDSCO tightened bioequivalence standards, raising compliance burdens for domestic suppliers. Public hospital procurement committees in Southeast Asia exhibit highest price sensitivity, while Japan's university-affiliated psychiatric centers maintain lowest sensitivity due to PMDA-mandated quality premiums.
Supply Chain Analysis
Contract manufacturing concentration rests with Indian and Chinese API producers serving formulation facilities in Maharashtra, Gujarat, and the Yangtze River Delta. Finished dosage form production draws from fluoxetine, sertraline, and escitalopram raw material streams, with clomipramine tricyclic supply more fragmented across European legacy manufacturers. Single-source vulnerability concentrates in high-potency SNRI intermediates where only two qualified suppliers maintain PMDA-approved status. Distribution runs through hospital procurement committees in Singapore and Thailand, consolidated tender systems in Australia, and retail pharmacy networks in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Digital therapeutic integration and PMDA regulatory acceleration are disrupting traditional pharmacotherapy economics across the Asia-Pacific OCD landscape, compressing feedback loops between symptom measurement and prescribing adjustments.
For Market Incumbents: Insulate proprietary market position by deepening vertical integration into pediatric liquid suspension formulation capacity, addressing the weight-calibrated dosing gap where supplier competition remains thin. Prioritize Japan-first registration sequencing to exploit compressed PMDA review timelines before competitors commit clinical trial resources. Defensive patent clustering around depot delivery mechanisms protects against biosimilar erosion in the treatment-resistant segment. For New Entrants and Emerging Players: Pursue Vietnam's rural diagnostic infrastructure gap where OCD recognition rates sit below 15 percent, creating first-mover advantage through education-linked prescribing programs. Target South Korea's telehealth reimbursement expansion under National Health Insurance Service coverage, extending rural prescription access beyond Seoul-centric distribution. White-space opportunity concentrates in sublingual pediatric formulations for Thailand's expanding specialty clinic networks. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across long-acting injectable depot manufacturing as psychiatric hospitals in Japan and South Korea pilot supervised compliance protocols. Five-to-ten year viability favors manufacturers with captive API supply and regulatory approval across multiple Asia-Pacific jurisdictions. Acquisition target archetype: domestic generic suppliers with CDSCO-approved facilities seeking PMDA registration partnerships. Monitor quarterly PMDA novel CNS approval velocity as inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Approval Pathway | PMDA compressed review timelines accelerate Japan market entry for novel SNRIs ahead of competitors. |
| Manufacturing Scale-Up | Indian API producers expanding formulation capacity capture margin arbitrage between supply and demand jurisdictions. |
| Pipeline Diversification | Long-acting depot investments address treatment-resistant OCD compliance gaps in psychiatric hospital settings. |
| Licensing Agreement | Digital therapeutic partnerships extend adherence monitoring revenue beyond pure pharmaceutical supply. |
| Geographic Expansion | Vietnam specialty clinic construction standardizes diagnostic protocols and drives consistent medication demand. |
Study Parameters
Operator-level perspectives from drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists anchored the qualitative base for this analysis. Primary interview data combined with secondary validation from PMDA filings, TGA scheduling registers, ClinicalTrials.gov entries, and CDSCO bioequivalence standards. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical expenditure estimates across the analysis window.
Scenario-bracketing framed demand projections across conservative, baseline, and accelerated adoption pathways throughout the forecast period. Segmentation dimensions modeled include molecule class, administration route, care setting, patient age segment, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to diagnosed prevalence estimates and treatment penetration rates, with pricing assumptions anchored to Pharmaceutical Benefits Scheme reimbursement tiers and tender system award patterns.
Sensitivities concentrate around PMDA review timeline extensions, API supply disruptions from India or China, and psychotherapy substitution rates in Australia and New Zealand. Forecasts reflect documented assumptions regarding diagnostic recognition expansion, regulatory approval velocity, and reimbursement policy continuity. Quarterly review of PMDA novel CNS approval cadence, CDSCO bioequivalence standard enforcement, and telehealth reimbursement expansion metrics is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Global Finasteride Market
Pharmaceuticals
Analgesics Market
Pharmaceuticals
Global Anti-Retroviral Drugs Market
Pharmaceuticals
Global Monoclonal Antibody Therapeutics Market
Pharmaceuticals
Plasma-Derived Drugs Market
Pharmaceuticals
Alkylating Agents Market
Pharmaceuticals
Laxatives Market
Pharmaceuticals
MRI Contrast Media Agents Market
Pharmaceuticals
Indapamide Market
Pharmaceuticals
Meningococcal Vaccines Market
Pharmaceuticals
Hepatitis - B Therapeutics Market
Pharmaceuticals
Topical Acne Medication Market
Pharmaceuticals
Global Postpartum Depression Drugs Market
Pharmaceuticals
OTC Topical Drugs Market
Pharmaceuticals
Europe Pharmaceutical Market
Pharmaceuticals
Injectable Benzodiazepine Market