
 Anthelmintic Drugs Market | 2026-2036
Anthelmintic Drugs Market Size, Share, and Industry Trends Forecast 2026-2036
Anthelmintic Drugs Market Analysis
Veterinary clinics are reorganizing their anthelmintic procurement patterns, shifting from reactive deworming to scheduled parasitic prevention protocols that lock in recurring volume. Merck & Co., Inc. anchors its position through backward integration into active pharmaceutical ingredient production for macrocyclic lactones. Zoetis Inc. differentiates via species-specific formulation expertise across companion and livestock segments. Cipla Ltd. competes on cost-optimized generic benzimidazole supply chains serving emerging markets.
Anthelmintic drugs are pharmaceutical agents designed to expel parasitic worms from host organisms, typically formulated as tablets, injections, suspensions, or powders with specific pharmacokinetic profiles targeting nematodes, cestodes, or trematodes. Their primary commercial purpose centers on maintaining animal health in livestock production and companion animal care, where infestations degrade feed conversion, reproductive performance, and companion animal longevity. Benzimidazoles occupy the mature core of the product type landscape, while macrocyclic lactones capture expanding margin pools due to their broad-spectrum efficacy and extended duration of action. Veterinary clinics represent the fastest-growing end user channel as pet owners shift preventive care from pharmacies to clinical settings with diagnostic confirmation.
The FDA Center for Veterinary Medicine enforces residue tolerance limits that shape withdrawal period labeling and export eligibility for food-producing animals. EMA guidelines on anthelmintic resistance management mandate rotation protocols and combination therapy requirements across EU member states. India's CDSCO aligns with WHO prequalification standards to facilitate generic anthelmintic exports to endemic regions. Stakeholders must monitor regulatory divergence between jurisdictions on resistance mitigation mandates and residue testing thresholds to avoid market access friction.
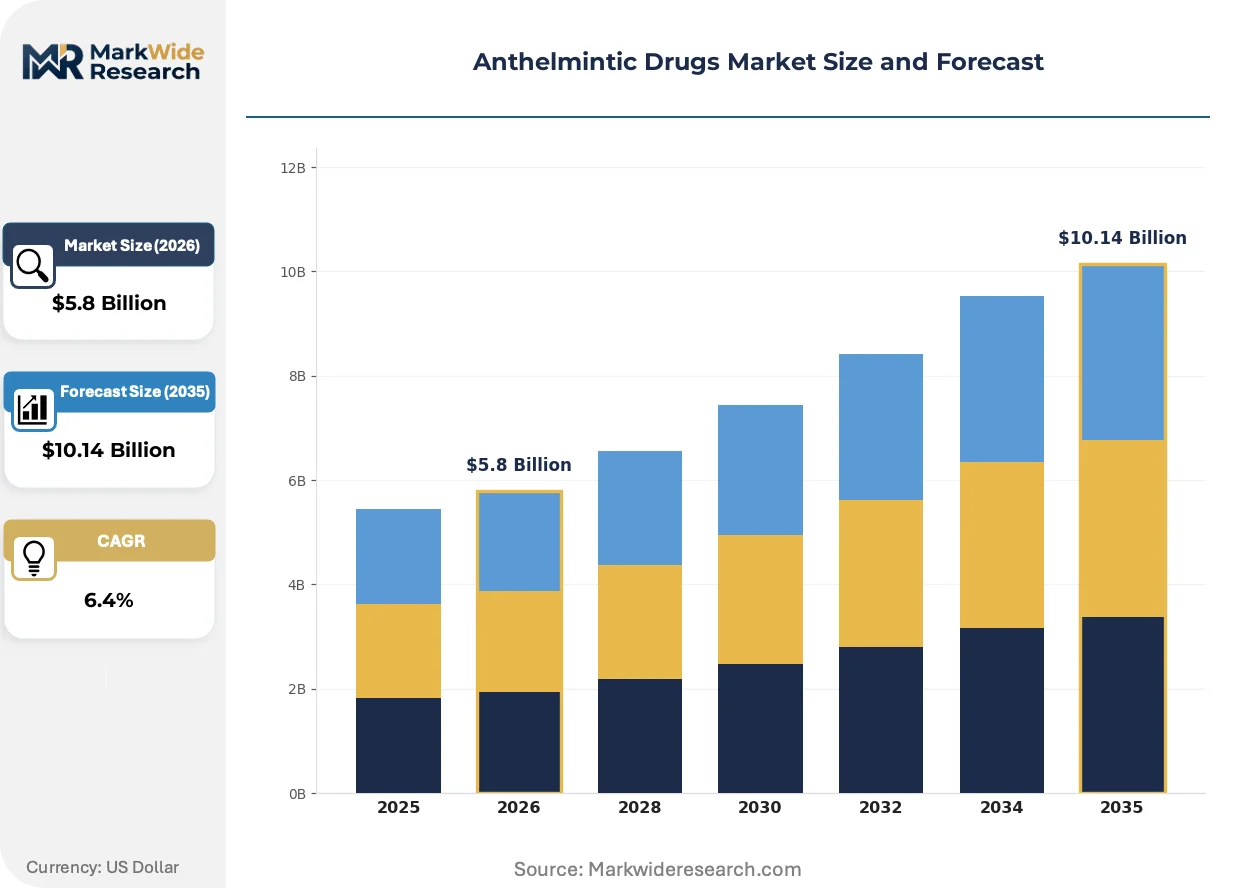
Market Dynamics
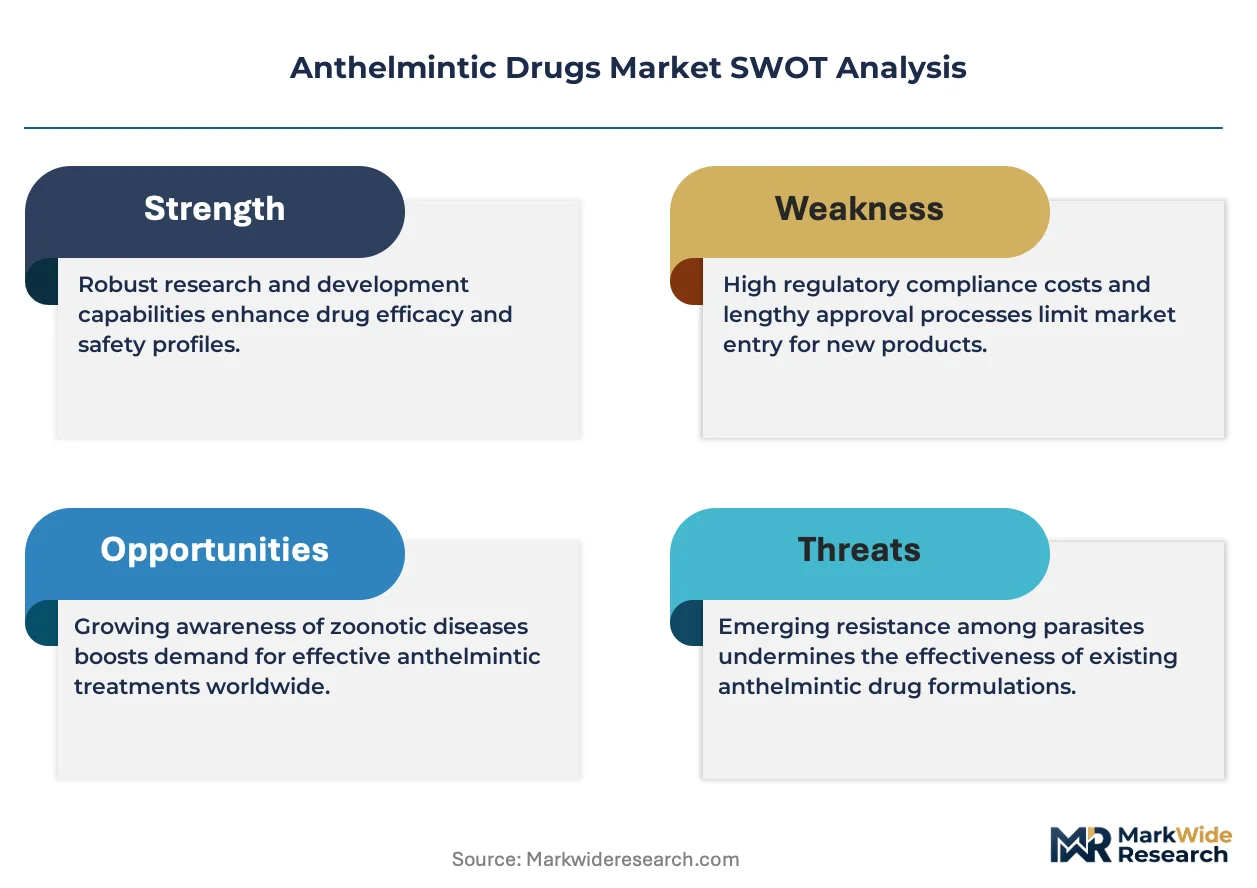
Parasitic resistance to existing benzimidazole and macrocyclic lactone formulations is forcing veterinary pharmaceutical companies to accelerate novel mechanism discovery while simultaneously defending legacy product lines through combination therapy protocols.
Growth Catalysts
- Companion Animal Ownership Surge:Pet humanization trends in the United States and Western Europe drive preventive deworming protocols into monthly subscription models at veterinary clinics.
- EMA Resistance Management Mandates:Rotation requirements for anthelmintic classes across EU member states lock in recurring volume for multi-product portfolios.
- Indian API Manufacturing Scale:Domestic production of fenbendazole and ivermectin active ingredients enables cost-competitive export supply to endemic regions.
Market Restraints
- Anthelmintic Resistance Escalation:Haemonchus contortus and Teladorsagia circumcincta strains in sheep and cattle populations reduce single-agent efficacy below commercial thresholds.
- Veterinary-Grade Excipient Concentration:Three Chinese chemical manufacturers control over 80% of benzyl alcohol and propylene glycol supply for parenteral formulations.
- Residue Testing Protocol Costs:FDA Center for Veterinary Medicine tolerance enforcement requires HPLC-MS/MS equipment investments that eliminate small-scale generic entrants.
Strategic Opportunities
- Brazilian Cattle Sector Underpenetration:Subtherapeutic prophylaxis adoption remains below 35% in Mato Grosso and Pará feedlot operations.
- RNA Interference Delivery Platforms:Double-stranded RNA nanoparticles targeting nematode essential genes converge with existing veterinary injection infrastructure.
- Direct-to-Clinic Distribution Models:Zoetis and Merck bypass wholesale distributors to capture margin through proprietary veterinary portal replenishment systems.
Industry Challenges
- Parasitology Specialization Scarcity:Veterinary schools in the United States and Europe graduate fewer than 150 parasitologists annually against industry demand exceeding 400.
- Combination Therapy Formulation Complexity:Incompatibility between benzimidazole solubility profiles and macrocyclic lactone stability windows extends development timelines by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anthelmintic Drugs Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Benzimidazoles, Macrocyclic Lactones, Nitrogen-containing Heterocycles, Tetrahydropyrimidines End User: Veterinary Clinics, Hospitals, Pharmacies, Research Institutions Formulation Type: Tablets, Injections, Suspensions, Powders Route of Administration: Oral, Injectable, Topical, Transdermal |
| Companies Covered | Novartis AG, Cipla Ltd., Merck & Co., Inc., Sun Pharmaceutical Industries Ltd., Zoetis Inc., Boehringer Ingelheim GmbH, GlaxoSmithKline plc, Virbac S.A., Bayer AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anthelmintic Drugs Market Emerging Trajectories
Anthelmintic development is pivoting from chemical synthesis toward biological control agents and precision delivery systems that extend dosing intervals while satisfying tightening residue regulations.
Controlled-release intraruminal bolus technology is miniaturizing from legacy 30-gram copper-based devices to sub-5-gram polymer matrices that lodge in the reticulum of grazing cattle. Australian and New Zealand sheep producers are adopting these devices at 23% annual replacement rates. The technology is miniaturizing administration labor costs and enabling season-long protection against Ostertagia ostertagi without mustering.
EMA's 2023 revised guideline on veterinary medicinal product environmental risk assessment now requires aquatic toxicity studies for all new endectocides before market authorization. This regulatory shift adds €400,000-€600,000 to development budgets and extends preclinical phases by 8-12 months. Macrocyclic lactone manufacturers targeting EU approval are reformulating with enhanced soil binding coefficients to satisfy the new aquatic exposure thresholds.
Livestock producers in the United States are consolidating anthelmintic purchasing through veterinary feed directive (VFD) compliance channels rather than over-the-counter agricultural supply stores. This channel migration concentrates volume with clinic-affiliated distributors and compresses margins for independent farm supply retailers. The shift is most pronounced in Texas and Kansas feedlot operations where VFD documentation requirements became enforceable in 2023.
Anthelmintic Drugs Market Segmentation
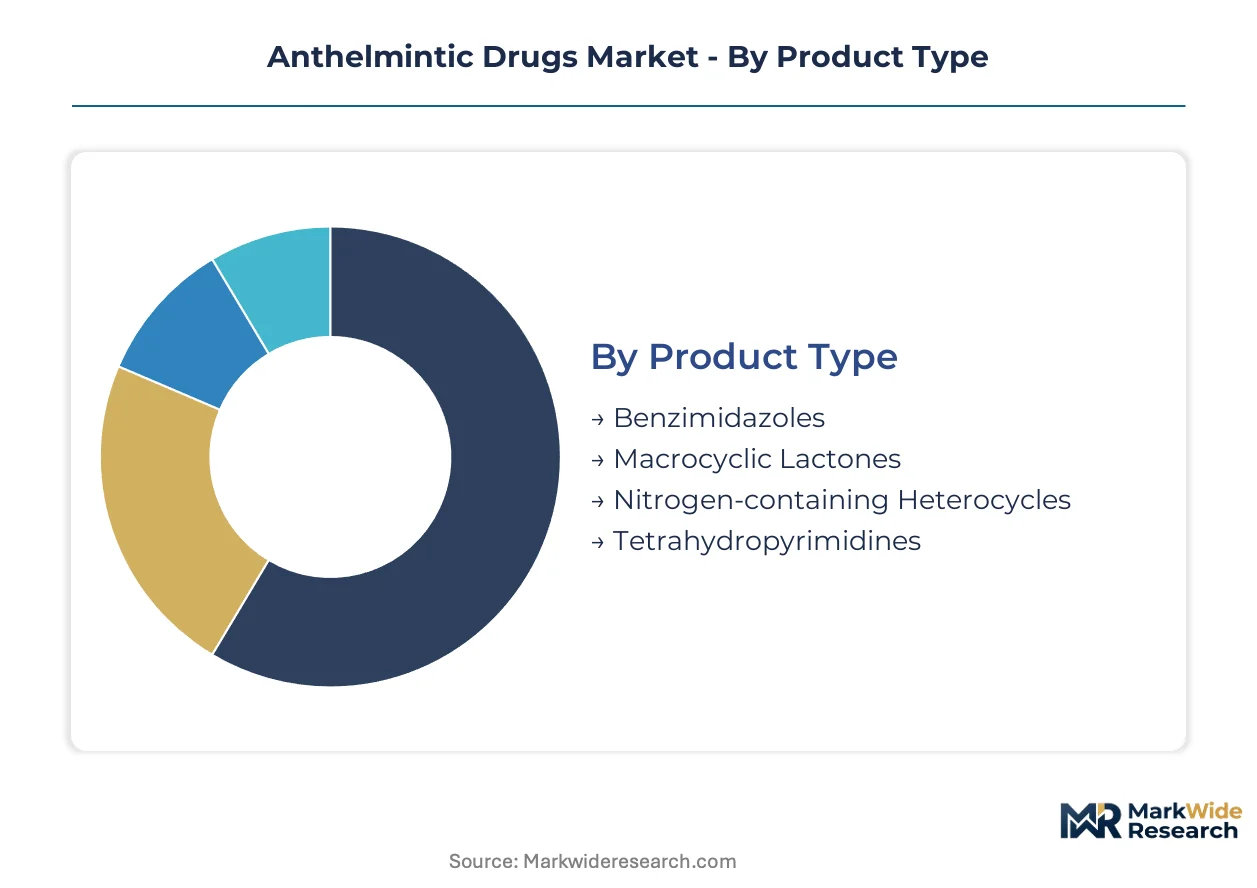
Anthelmintic market segmentation reveals divergent growth trajectories across chemical classes and delivery channels, with formulation complexity and regulatory jurisdiction shaping profitability profiles differently for each slice.
Product Type:
Benzimidazoles dominate domestic manufacturing footprints across India and China, while macrocyclic lactones concentrate in export-oriented API facilities serving EU and US compliance standards.
- Benzimidazoles:Mature chemistry class encompassing fenbendazole, albendazole, and oxfendazole with well-established pharmacokinetic profiles in ruminant species. Demand clusters in Indian generic export markets and Brazilian cattle operations where cost-per-dose drives procurement decisions; resistance accumulation in Haemonchus contortus populations constrains single-agent efficacy.
- Macrocyclic Lactones:Avermectin and milbemycin derivatives deliver broad-spectrum nematode and ectoparasite control with extended withdrawal periods. EU and US veterinary clinics absorb premium-priced formulations; EMA resistance rotation mandates sustain multi-product portfolio demand.
- Nitrogen-containing Heterocycles:Levamisole and morantel formulations retain niche positions in sheep and goat deworming protocols.
- Tetrahydropyrimidines:Pyrantel pamoate concentrates in companion animal tablet formulations for US and Western European retail pharmacy channels.
Benzimidazoles hold the largest share; momentum sits with macrocyclic lactones.
End User:
Channel economics separate high-margin clinical settings from commodity agricultural supply, with diagnostic confirmation requirements tilting procurement toward professional supervision.
- Veterinary Clinics:Diagnostic-confirmed deworming protocols with fecal egg count reduction testing lock in recurring revenue streams. US and EU pet humanization trends shift preventive care from over-the-counter to clinical settings; subscription-based monthly dosing models expand.
- Hospitals:Emergency and surgical cases requiring parenteral anthelmintic administration for severe parasitic burdens. Large animal teaching hospitals in Texas, California, and Queensland concentrate demand for hospital-grade injectable formulations.
- Pharmacies:Retail and agricultural supply outlets serving producer-direct procurement in regions with limited veterinary infrastructure.
- Research Institutions:Academic parasitology programs and pharmaceutical development facilities requiring reference standards and experimental compounds.
Veterinary clinics command the highest margin tier; steepest expansion trajectory belongs to hospital-affiliated specialty practices.
Formulation Type:
Manufacturing capital intensity varies sharply across solid and liquid dosage forms, with sterile injectable capacity constraining supplier entry.
- Tablets:Companion animal oral dosing dominates, with palatability engineering and dose-division flexibility driving formulation differentiation. US and EU pet owners prefer chewable matrices masking active pharmaceutical ingredient bitterness.
- Injections:Long-acting depot formulations in cattle and sheep require sterile manufacturing suites and pyrogen control. Three Chinese chemical manufacturers supply over 80% of benzyl alcohol and propylene glycol excipients for parenteral production.
- Suspensions:Oral drenches for sheep and goat flocks balance dosing accuracy with field administration convenience.
- Powders:Feed-additive premixes for mass medication in intensive livestock operations, particularly in Brazilian and Australian feedlot systems.
Tablets generate the highest unit economics; feed-grade powders capture the greatest volume tonnage.
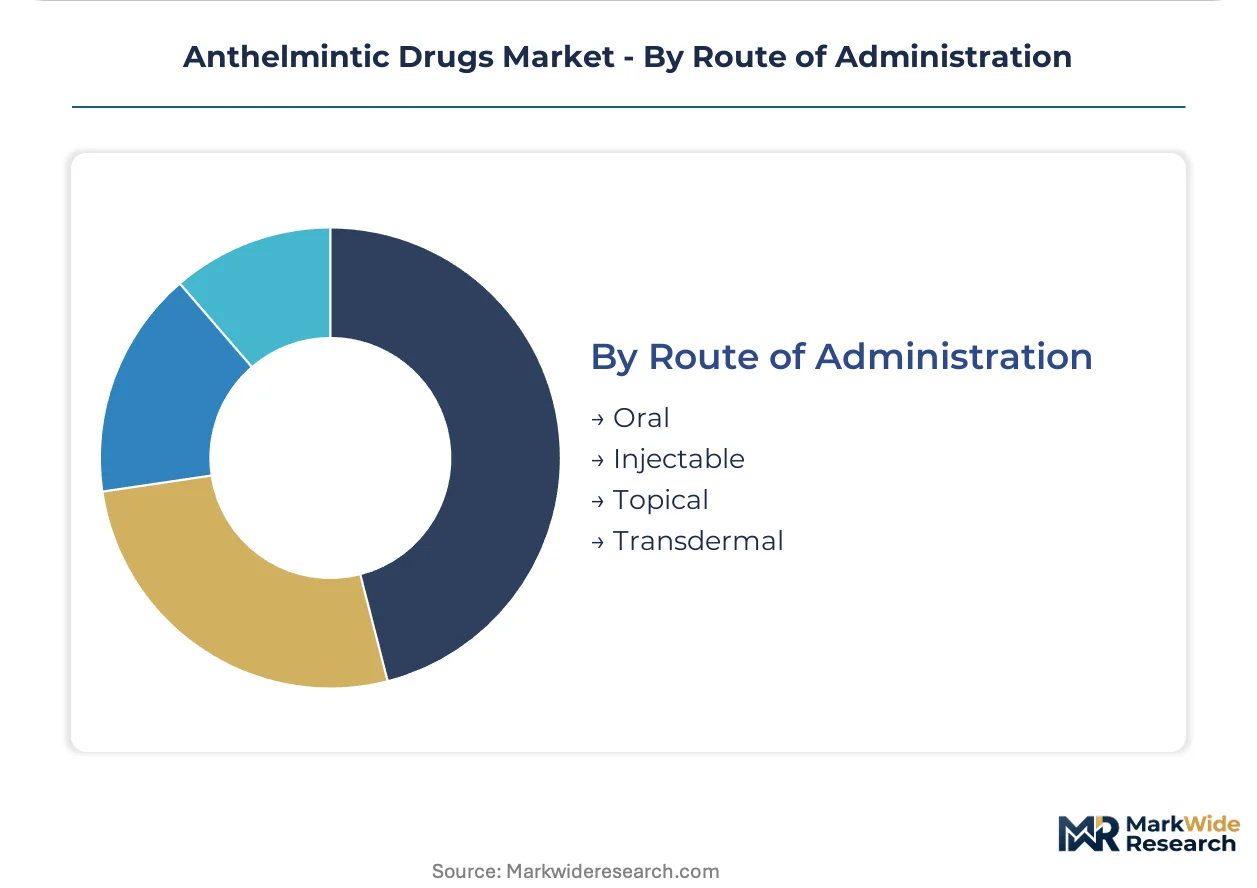
Route of Administration:
Delivery method selection hinges on species behavior, labor availability, and residue avoidance requirements in food-producing animals.
- Oral:Drench guns, boluses, and feed-additive incorporation serve grazing ruminants where handling stress must be minimized. Australian and New Zealand sheep producers favor intraruminal bolus technology with controlled-release polymer matrices.
- Injectable:Subcutaneous and intramuscular routes ensure complete bioavailability in valuable breeding stock and show animals. FDA Center for Veterinary Medicine residue tolerance enforcement shapes withdrawal period labeling and export eligibility documentation.
- Topical:Pour-on formulations for cattle deliver macrocyclic lactones through transcutaneous absorption, reducing handling labor in extensive grazing systems.
- Transdermal:Emerging patch and spot-on technologies for companion animals, with absorption enhancer development ongoing.
Oral administration retains volume leadership; injectable routes claim the premium pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
API manufacturing for anthelmintic drugs concentrates in Indian chemical clusters and Chinese excipient facilities, while formulation and commercialization gravitate toward US and EU veterinary markets with stringent residue compliance frameworks.
United States
Companion animal ownership expansion and VFD enforcement drive clinic-centric procurement. FDA Center for Veterinary Medicine residue tolerance protocols shape withdrawal labeling for export-eligible livestock. Texas and Kansas feedlot operations concentrate demand for long-acting injectable formulations through clinic-affiliated distribution channels.
India
Domestic pharmaceutical manufacturing and generic export production of fenbendazole and ivermectin APIs sustain cost-competitive supply chains. CDSCO alignment with WHO prequalification standards facilitates anthelmintic exports to endemic regions. Gujarat and Maharashtra chemical corridors house backward-integrated facilities serving African and Southeast Asian veterinary markets.
Germany
EMA resistance management mandates and environmental risk assessment requirements elevate formulation complexity for EU market access. REACH compliance and aquatic toxicity study obligations extend development timelines. Baden-Württemberg hosts specialty chemical operations supplying benzimidazole derivatives to European veterinary pharmaceutical manufacturers.
Brazil
Cattle sector underpenetration in Mato Grosso and Pará feedlot operations leaves subtherapeutic prophylaxis adoption below comparable US benchmarks. ANVISA import registration requirements for veterinary medicines create compliance barriers for non-domestic suppliers. São Paulo state anchors distribution infrastructure for anthelmintic products serving the national beef export sector.
Australia
Sheep producers adopt controlled-release intraruminal bolus technology at accelerated replacement rates for season-long Ostertagia ostertagi protection. TGA veterinary medicine registration requirements align with EMA environmental risk standards. New South Wales and Victoria grazing regions concentrate demand for labor-minimizing pour-on and bolus delivery systems.
Anthelmintic Drugs Market Vendor Landscape
Concentration sits with diversified pharmaceutical conglomerates possessing captive API production and established veterinary distribution networks. Market structure divides between integrated human-animal health portfolios and species-focused veterinary specialists. Dominant archetypes include backward-integrated macrocyclic lactone manufacturers, generic benzimidazole cost leaders, and companion animal formulation innovators. Competitive moves center on direct-to-clinic distribution bypassing wholesale intermediaries, and combination therapy portfolio expansion to satisfy resistance rotation mandates.
Within the integrated pharmaceutical tier, Merck & Co., Inc. and Novartis AG exemplify conglomerate-scale operations spanning human and veterinary therapeutic categories. Cipla Ltd. occupies a position among cost-optimized generic manufacturers serving emerging market volume demand. Zoetis Inc. and Virbac S.A. represent pure-play veterinary specialists with species-specific formulation expertise across companion and livestock segments. Boehringer Ingelheim GmbH and Bayer AG anchor diversified health science portfolios where animal health operates as a strategic division alongside crop science and pharmaceutical operations.
| Leading Market Players |
|---|
| Novartis AG |
| Cipla Ltd. |
| Merck & Co., Inc. |
| Sun Pharmaceutical Industries Ltd. |
| Zoetis Inc. |
| Boehringer Ingelheim GmbH |
| GlaxoSmithKline plc |
| Virbac S.A. |
| Bayer AG |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day API inventory buffers at Indian fenbendazole manufacturers translate directly into pricing leverage for backward-integrated players, while spot-market purchasers absorb volatility from Chinese excipient supply interruptions. This lead-time band separates contract-anchored procurement from commodity-exposed buying, concentrating margin capture with vertically integrated incumbents.
Pricing Analysis
FDA Center for Veterinary Medicine residue tolerance enforcement dictates the pricing tier structure across US and EU veterinary markets, separating premium clinic-grade injectables from economy feed-grade powders. Pricing stratifies across premium, standard, and economy tiers based on withdrawal period documentation rigor and sterile manufacturing certification. Cost compression in the economy tier is intensifying because Brazilian and Indian generic manufacturers compete on API cost-per-kilogram. Feedlot operators in Mato Grosso exhibit highest price sensitivity; US specialty veterinary clinics demonstrate lowest sensitivity due to diagnostic bundling.
Supply Chain Analysis
Strategic stockpiling of macrocyclic lactone APIs dominates procurement behavior among EU formulation houses, while Indian generic producers favor just-in-time benzimidazole precursor acquisition. Active pharmaceutical ingredient production concentrates in India, China, and Germany, with Gujarat chemical corridors feeding global fenbendazole supply. Formulation draws from benzyl alcohol and propylene glycol excipients controlled by Chinese chemical manufacturers. Single-source vulnerability in parenteral-grade excipient supply threatens injectable production continuity. Distribution runs through veterinary clinic-affiliated channels in the United States and wholesale pharmaceutical distributors in emerging markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Anthelmintic development is accelerating toward RNA interference platforms and controlled-release delivery systems, with EMA environmental risk mandates creating regulatory moats for compliant innovators. This technological-regulatory inflection rewards early movers with multi-year portfolio differentiation.
For Market Incumbents: Fortify API backward integration into macrocyclic lactone production to defend against Indian generic cost pressure. Expand combination therapy portfolios to satisfy EMA resistance rotation mandates. Lock in veterinary clinic distribution through proprietary portal replenishment systems before channel consolidation hardens. For New Entrants and Emerging Players: Differentiate on novel mechanism discovery targeting anthelmintic-resistant nematode strains. Exploit underpenetration in Brazilian cattle feedlot prophylaxis where adoption remains below comparable US benchmarks. Pursue direct-to-clinic distribution partnerships bypassing entrenched wholesale intermediaries. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical conglomerates seeking to divest non-core animal health divisions. Five-to-ten-year viability hinges on resistance management protocol adoption and biological control agent commercialization. Monitor parasitology graduate program expansion rates as inflection indicator for R&D talent pipeline health.| Strategic Initiative | Industry Significance |
|---|---|
| Combination Therapy Portfolio Expansion | EMA resistance rotation mandates lock in recurring multi-product volume across EU veterinary markets. |
| Backward Integration into API Production | Captive fenbendazole and ivermectin supply secures margin control against Indian generic price competition. |
| Direct-to-Clinic Distribution Bypass | Proprietary veterinary portal systems capture wholesale margin and strengthen clinic replenishment loyalty. |
| Controlled-Release Bolus Miniaturization | Sub-5-gram polymer matrices reduce Australian sheep producer labor costs and extend dosing intervals. |
| RNA Interference Platform Development | Double-stranded RNA nanoparticles targeting nematode essential genes converge with existing injection infrastructure. |
Methodological Framework
Operator-level perspectives from veterinary pharmaceutical executives, regulatory affairs specialists at FDA and EMA, clinic procurement managers, and parasitology program directors anchored the qualitative base. Secondary validation drew from FDA Center for Veterinary Medicine filings, EMA veterinary medicinal product submissions, CDSCO export registration databases, and customs trade records for API movements. Bottom-up volume modeling triangulated against top-down market sizing across chemical class and end-user segments.
Sensitivity analysis tested forecast robustness across regulatory approval timeline scenarios and resistance accumulation rate assumptions over the projection horizon. Segmentation dimensions included product type, end user channel, formulation complexity, and regional regulatory cluster. CAGRs were derived from fitted growth curves calibrated to procurement volume trajectories and pricing trend extrapolation. Key inputs encompassed veterinary clinic expansion rates in US metropolitan markets and Brazilian feedlot prophylaxis adoption curves.
Material uncertainties — parasitology workforce contraction, excipient supply disruption, and resistance mutation acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding EMA guideline stability and Indian API export capacity expansion. Revision becomes warranted when anthelmintic resistance mutation rates in Haemonchus contortus populations cross commercial efficacy thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Contract Dose Manufacturing Market
Pharmaceuticals
Estonia Pharmaceutical Market
Pharmaceuticals
Global Loratadine Market
Pharmaceuticals
Global Autogenous Vaccines Market
Pharmaceuticals
Global Vaccine Market
Pharmaceuticals
Selective Serotonin Reuptake Inhibitors Market
Pharmaceuticals
Europe Novel Drug Delivery System (NDDS) Market
Pharmaceuticals
Tumor Necrosis Factor Alpha Inhibitors Market
Pharmaceuticals
Korea Pharmaceutical Market
Pharmaceuticals
Middle East and Africa Laxative Market
Pharmaceuticals
Congestive Heart Failure Drugs Market
Pharmaceuticals
Retinal Drugs Market
Pharmaceuticals
Fibroblast Growth Factor Receptor Inhibitor Market
Pharmaceuticals
Pharmacy Market
Pharmaceuticals
Myocardial Infarction Drugs Market
Pharmaceuticals
Tetanus Market