
 Retinal Drugs and Biologics Market | 2026-2036
Retinal Drugs and Biologics Market Size, Share, and Industry Trends Forecast 2026-2036
Retinal Drugs and Biologics Market Analytics
The EU Green Deal is decoupling retinal biologics procurement from carbon-intensive supply chains, compelling European hospital networks to audit pharmaceutical manufacturing footprints. Regeneron Pharmaceuticals anchors North American anti-VEGF supply through integrated manufacturing campuses. Roche leverages its diagnostics-therapeutics linkage to sustain competitive positioning in neovascular retinal disease. Novartis differentiates through gene therapy pipeline depth, particularly in inherited retinal dystrophies.
Retinal drugs and biologics comprise therapeutic agents engineered to modulate vascular endothelial growth factor signaling, inflammatory cytokine cascades, or defective gene expression within the posterior segment, typically formulated for intravitreal or subretinal delivery to achieve therapeutic concentrations at the retina-choroid interface. Anti-VEGF biologics dominate current prescribing patterns due to established efficacy in neovascular age-related macular degeneration, while gene therapy represents the fastest-expanding development category as one-time interventions for inherited conditions advance through regulatory pipelines. Corticosteroid implants occupy a narrower niche in chronic uveitis and diabetic macular edema where sustained inflammation suppression outweighs intraocular pressure risks.
The FDA, EMA, and WHO exert overlapping influence on retinal biologics through divergent gene therapy approval standards, Good Manufacturing Practice requirements for viral vector production, and post-market pharmacovigilance protocols that collectively extend development timelines and inflate capital barriers. The EU AI Act and FDA guidance on real-world evidence are converging to reshape how ophthalmic drug developers validate surrogate endpoints and monitor long-term safety. Stakeholders must track how regulatory divergence on gene therapy durability data will partition market access between jurisdictions.
Market Dynamics
The retinal drugs and biologics market is being fundamentally restructured by the FDA's accelerated approval pathways for gene therapies, which compress clinical development timelines while raising durability evidence requirements that reshape capital allocation across therapeutic modalities.
Growth Catalysts
- Intravitreal anti-VEGF protocols:Ophthalmology clinics in the United States are expanding biologic adoption for wet age-related macular degeneration, driven by favorable reimbursement structures and established efficacy data.
- EU Green Deal supply chain mandates:European hospital networks are auditing pharmaceutical manufacturing footprints, compelling procurement decoupling from carbon-intensive production corridors.
- Gene therapy regulatory frameworks:The FDA's breakthrough therapy designation and EMA's PRIME scheme are expediting one-time intervention candidates for inherited retinal dystrophies through priority review channels.
Market Restraints
- Viral vector production bottlenecks:Good Manufacturing Practice requirements for adeno-associated virus manufacturing concentrate supply among limited contract development organizations, inflating capital barriers for pipeline entrants.
- Intraocular pressure liability:Corticosteroid implants face prescribing hesitation in diabetic macular edema due to glaucoma risk, restricting addressable populations relative to anti-VEGF alternatives.
- Reimbursement compression:Payer formulary restrictions on ranibizumab and aflibercept biosimilars in European markets are narrowing price differentiation between originator and follow-on biologics.
Strategic Opportunities
- Subretinal delivery automation:Surgical robotics convergence with micro-catheter systems is enabling precision gene therapy administration that reduces operator-dependent variability in inherited retinal disease treatment.
- Real-world evidence validation:The FDA's guidance on electronic health record-derived endpoints permits post-approval efficacy confirmation through patient registries rather than extended placebo-controlled trials.
- India's specialty ophthalmology expansion:Metro hospital networks in Mumbai and Delhi are constructing dedicated retinal biologics infusion centers to capture medical tourism flows from Southeast Asian markets.
Industry Challenges
- Vitreoretinal surgical subspecialty scarcity:Fellowship-trained surgeons capable of subretinal injection procedures remain concentrated in academic medical centers, constraining gene therapy rollout velocity.
- Cold chain integrity at last mile:Temperature excursions during intravitreal biologic transport to ambulatory surgery centers compromise protein stability, requiring redundant monitoring infrastructure investment.
- Pharmacovigilance signal detection:Long-term safety surveillance for one-time gene therapies demands patient tracking across decades, exceeding traditional adverse event reporting system architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Retinal Drugs and Biologics Market |
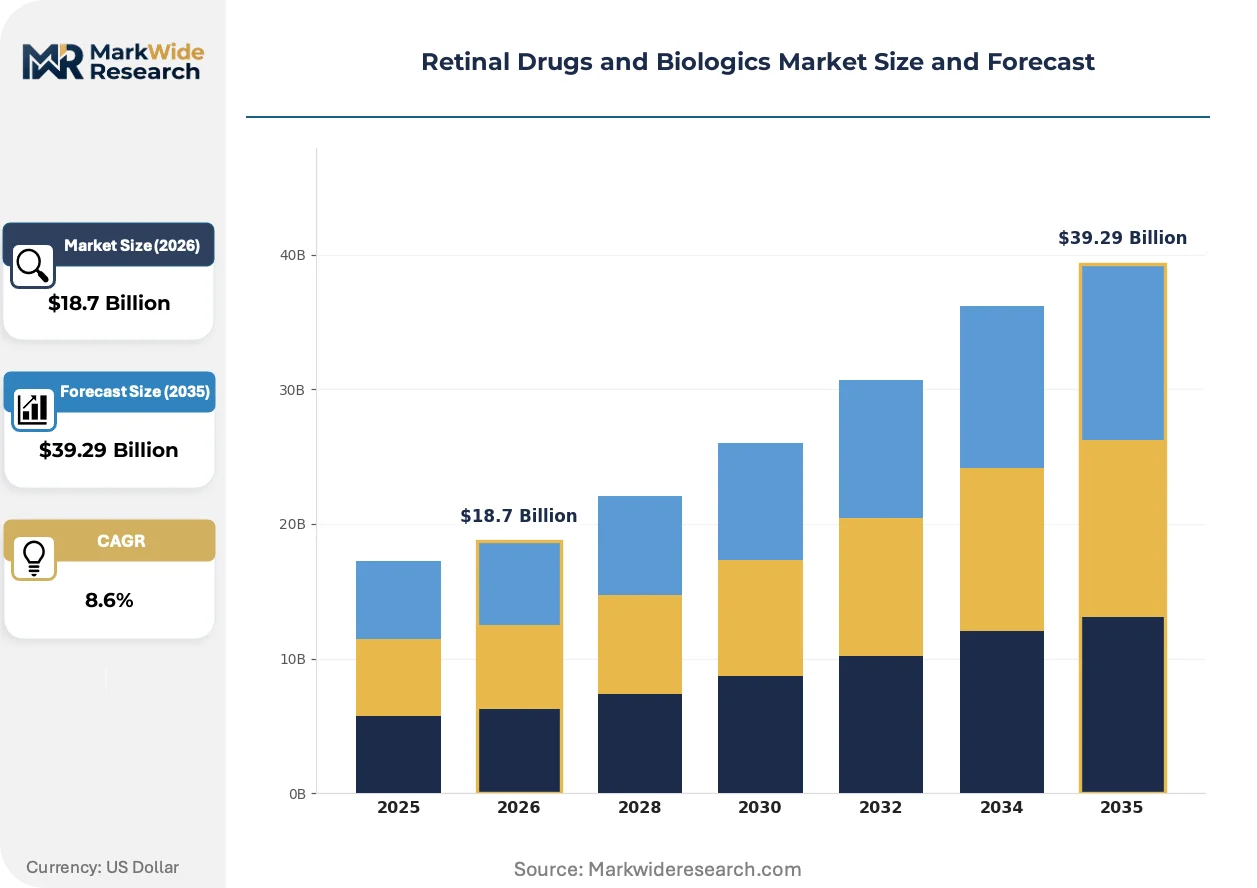
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $39.29 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
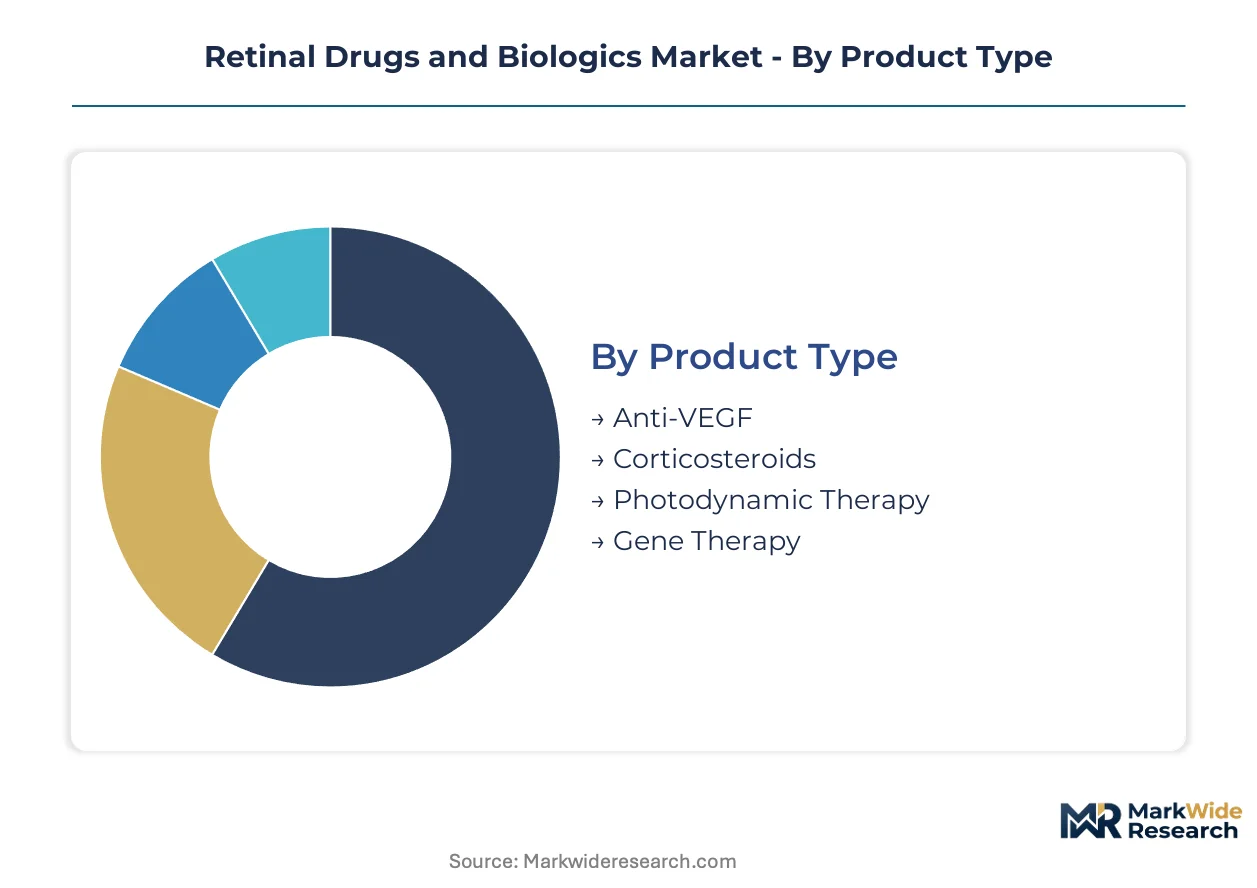
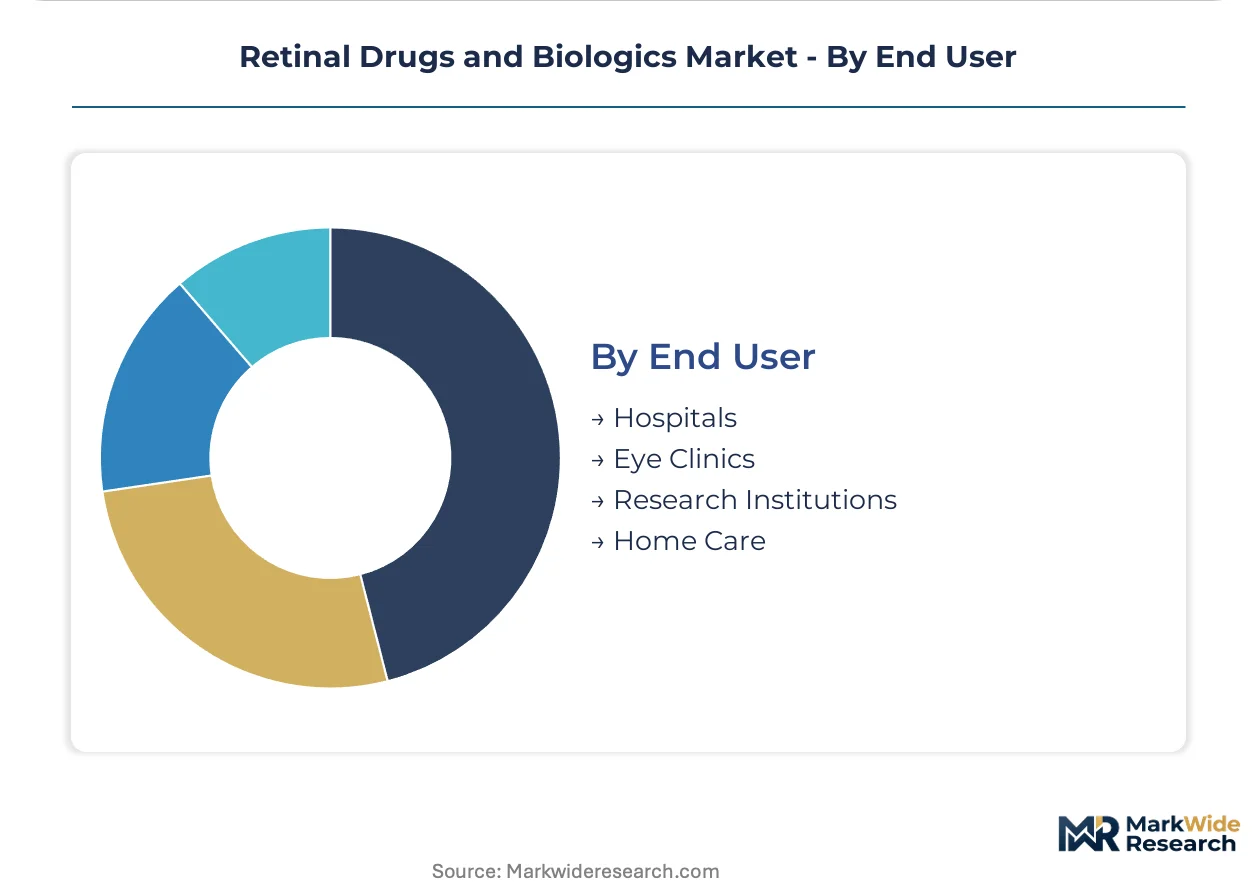
| Segmentation | Product Type: Anti-VEGF, Corticosteroids, Photodynamic Therapy, Gene Therapy Indication: Age-related Macular Degeneration, Diabetic Retinopathy, Retinal Vein Occlusion, Uveitis Delivery Mode: Intravitreal Injection, Subretinal Implant, Systemic Administration, Topical End User: Hospitals, Eye Clinics, Research Institutions, Home Care |
| Companies Covered | Regeneron Pharmaceuticals Inc., Roche, Novartis AG, AbbVie Inc., Bayer AG, Santen Pharmaceutical Co., Ltd, Genentech, Alcon Inc., Ocular Therapeutix, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Retinal Drugs and Biologics Market Evolving Landscape
Extended-duration anti-VEGF formulations are compressing injection frequencies and reshaping clinic throughput economics, while regulatory convergence on real-world evidence standards accelerates surrogate endpoint validation across ophthalmic drug development.
Sustained-release anti-VEGF implants incorporating tyrosine kinase inhibitors or bispecific antibodies are consolidating treatment paradigms from monthly intravitreal injections toward semi-annual or annual administration intervals. Retina specialists in high-volume United States practices are adopting these platforms fastest, prioritizing patient compliance gains and surgical schedule optimization. The technology is consolidating market share around formulations that minimize treatment burden rather than maximize acute efficacy metrics.
The EU AI Act's risk classification framework for medical device software is imposing conformity assessment requirements on diagnostic-therapeutic linkage platforms used to predict anti-VEGF response. Roche's integrated ophthalmology systems face expanded notified body scrutiny for algorithmic patient stratification tools. European markets are responding by segregating regulatory submissions for companion diagnostic components from therapeutic marketing authorization dossiers.
Hospital purchasing consortia in Germany and France are consolidating retinal biologics procurement through tender mechanisms that weight total cost of care against unit price, displacing traditional volume rebate structures. Academic medical centers in the Netherlands are piloting outcome-based contracts where manufacturer payments tie to sustained visual acuity gains at 24 months. This restructuring is most visible in Benelux markets where health technology assessment bodies mandate comparative effectiveness evidence for formulary inclusion.
Retinal Drugs and Biologics Market Segmentation
Retinal therapeutics fragment across molecular mechanism, anatomical target, and care setting. Each segmentation axis reveals distinct capital intensity, reimbursement dynamics, and patient access constraints.
Product Type:
Standardization dominates anti-VEGF manufacturing while gene therapy retains bespoke viral vector engineering.
- Anti-VEGF:Monoclonal antibodies and fusion proteins targeting vascular endothelial growth factor-A. United States ophthalmology clinics concentrate demand for ranibizumab and aflibercept due to CMS reimbursement certainty.
- Gene Therapy:Adeno-associated virus vectors delivering functional gene copies to retinal pigment epithelium. Subretinal delivery automation in academic medical centers is compressing procedure variability.
- Corticosteroids:Intravitreal implants releasing dexamethasone or fluocinolone acetonide.
- Photodynamic Therapy:Verteporfin-activated laser protocols for polypoidal choroidal vasculopathy.
Most installed capacity flows through Anti-VEGF. Expansion is steepest in Gene Therapy.
Indication:
Volume concentrates in chronic degenerative conditions while acute inflammatory states command premium pricing.
- Age-related Macular Degeneration:Neovascular and atrophic subtypes driving anti-VEGF and complement inhibitor development. United States Medicare claims data show intravitreal injection volumes clustering in Florida and Arizona retirement corridors.
- Diabetic Retinopathy:Proliferative and diabetic macular edema manifestations. CMS expanded coverage for anti-VEGF in non-proliferative disease is broadening addressable populations.
- Retinal Vein Occlusion:Branch and central subtypes requiring rapid macular edema resolution.
- Uveitis:Intermediate, posterior, and panuveitis variants.
Procedure volumes concentrate in Age-related Macular Degeneration. Pipeline investment is climbing fastest in Diabetic Retinopathy.
Delivery Mode:
Patient compliance requirements differentiate invasive intravitreal protocols from emerging sustained-release platforms.
- Intravitreal Injection:Trans-scleral needle delivery to vitreous cavity. Ambulatory surgery centers in Texas and California are optimizing throughput through dedicated retina injection suites.
- Subretinal Implant:Surgical micro-catheter placement beneath photoreceptor layer. Vitreoretinal fellowship scarcity constrains rollout velocity.
- Systemic Administration:Oral or intravenous routes for inflammatory retinal disease.
- Topical:Drops and ointments with limited posterior segment penetration.
Most administered doses move through Intravitreal Injection. Technical development is accelerating most rapidly in Subretinal Implant.
End User:
Capital equipment requirements and reimbursement complexity stratify access between institutional settings.
- Hospitals:Academic medical centers and community hospital systems. German hospital purchasing consortia are consolidating retinal biologics procurement through tender mechanisms weighting total cost of care.
- Eye Clinics:Dedicated ophthalmology practices and multispecialty ambulatory centers. India's metro hospital networks in Mumbai are constructing dedicated infusion centers for medical tourism capture.
- Research Institutions:Clinical trial sites and gene therapy development programs.
- Home Care:Self-administered topical and emerging sustained-release options.
Biologic volume concentrates in Eye Clinics. Infrastructure investment is expanding most quickly in Hospitals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The retinal drugs and biologics industry traces its commercial origins to Genentech's 2004 FDA approval of ranibizumab in South San Francisco, establishing the intravitreal anti-VEGF treatment paradigm that now generates procedure volumes concentrated in aging population corridors worldwide.
United States
Medicare claims data show intravitreal injection volumes clustering in Florida and Arizona retirement corridors, where ophthalmology clinics optimize throughput through dedicated retina injection suites. The FDA's breakthrough therapy designation and accelerated approval pathways compress gene therapy development timelines while raising durability evidence requirements. Academic medical centers in Boston and Baltimore concentrate vitreoretinal surgical subspecialists capable of subretinal delivery procedures.
Germany
Hospital purchasing consortia consolidate retinal biologics procurement through tender mechanisms weighting total cost of care against unit price. The EU Green Deal compels pharmaceutical manufacturing footprint audits, decoupling procurement from carbon-intensive supply chains. Benelux markets pilot outcome-based contracts where manufacturer payments tie to sustained visual acuity gains at 24 months.
Japan
PMDA regulatory frameworks align with EMA standards on gene therapy durability data requirements, partitioning market access timelines between jurisdictions. METI industrial policy supports domestic viral vector manufacturing capacity expansion to reduce import dependence. Tokyo and Osaka academic medical centers anchor clinical trial site networks for inherited retinal dystrophy interventions.
India
Metro hospital networks in Mumbai and Delhi construct dedicated retinal biologics infusion centers to capture medical tourism flows from Southeast Asian markets. CDSCO streamlined approval pathways for biosimilars accelerate ranibizumab and aflibercept follow-on market entry. Specialty ophthalmology expansion concentrates in Maharashtra and Karnataka state healthcare infrastructure upgrades.
Switzerland
Swissmedic maintains stringent Good Manufacturing Practice requirements for viral vector production that concentrate contract development organization relationships among established European suppliers. Geneva and Basel pharmaceutical clusters integrate diagnostics-therapeutics linkages for neovascular retinal disease patient stratification. Pricing negotiations with compulsory health insurance funds emphasize comparative effectiveness evidence for formulary inclusion.
Retinal Drugs and Biologics Market Competitive Landscape
Premium-margin players sit above commodity-margin players across therapeutic modality and manufacturing integration depth, with gene therapy developers commanding valuation multiples distinct from anti-VEGF commodity biologics. The competitive structure fragments across three strategic archetypes: integrated biopharmaceutical conglomerates with diagnostics linkages, specialized retinal therapeutics developers with viral vector manufacturing captive, and ophthalmic surgical device-biologic combination platforms. Dominant competitive moves include M&A targeting subretinal delivery automation capabilities and strategic partnerships securing contract development organization capacity for adeno-associated virus production.
Within the integrated biopharmaceutical tier, Regeneron Pharmaceuticals Inc. and Roche exemplify archetypes anchoring North American anti-VEGF supply through distinct strategic positions. Novartis AG occupies a position representing gene therapy pipeline depth specialization, particularly in inherited retinal dystrophies where one-time intervention candidates advance through regulatory pipelines. These three entities collectively illustrate how competitive positioning fragments across manufacturing integration, diagnostic-therapeutic linkage, and developmental modality focus rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Regeneron Pharmaceuticals Inc. |
| Roche |
| Novartis AG |
| AbbVie Inc. |
| Bayer AG |
| Santen Pharmaceutical Co., Ltd |
| Genentech |
| Alcon Inc. |
| Ocular Therapeutix, Inc. |
| Others |
Value Network & Pricing Analysis
Biopharmaceutical conglomerates with captive viral vector manufacturing anchor supply-side concentration, translating GMP certification depth into pricing power that resists commoditization pressure from ranibizumab biosimilars. Their integrated production campuses in Massachusetts and Basel sustain premium positioning against contract-reliant competitors facing CDMO capacity bottlenecks.
Pricing Analysis
Three-tier pricing structure across originator biologics, biosimilar follow-ons, and gene therapy one-time interventions stratifies the market. Price differentiation rests on FDA breakthrough designation status and EMA PRIME eligibility as quality signals. Cost compression in anti-VEGF originator tiers intensifies because European tender mechanisms weight total cost of care over unit rebates. Hospital purchasing consortia in Germany exhibit highest price sensitivity; academic medical centers in the United States show least.
Supply Chain Analysis
Returns and temperature excursion protocols for intravitreal biologics impose reverse-logistics infrastructure requirements that concentrate distribution among specialized cold-chain providers. Manufacturing gravity centers on the United States, Switzerland, and Japan for viral vector GMP compliance. Raw material dependencies include adeno-associated virus plasmid banks, cell culture media, and single-use bioreactor components. Single-source vulnerability in contract development organization relationships for AAV production elevates supply risk. Distribution runs through hospital purchasing consortia and specialty pharmacy networks to ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story where visual acuity durability endpoints now command premium reimbursement over injection frequency metrics. Demand is shifting toward gene therapy candidates with decade-long efficacy signals.
For Market Incumbents: To counter biosimilar price erosion in anti-VEGF markets, anchor defensive positioning through backward integration into viral vector manufacturing and exclusive CDMO capacity reservations. Prioritize subretinal delivery automation acquisitions that compress procedure variability and extend addressable populations beyond academic medical center catchments. For New Entrants and Emerging Players: The EU AI Act's risk classification framework for diagnostic-therapeutic linkage platforms opens a window for algorithmic patient stratification tools that predict anti-VEGF response. White-space targets include India's medical tourism corridors and sustained-release implant formulations for diabetic macular edema. Go-to-market leverage centers on real-world evidence validation partnerships with European health technology assessment bodies. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap gene therapy developers with inherited retinal dystrophy pipelines but without manufacturing integration. Long-term viability over a five-to-ten year horizon hinges on durability data maturation and regulatory convergence on surrogate endpoints. Monitor FDA guidance evolution on electronic health record-derived efficacy confirmation as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Subretinal Delivery Automation | Surgical robotics convergence reduces operator-dependent variability in gene therapy administration. |
| Viral Vector Manufacturing Scale-Up | Captive AAV production capacity insulates against CDMO bottlenecks and accelerates clinical timelines. |
| Real-World Evidence Infrastructure | FDA guidance on EHR-derived endpoints permits post-approval efficacy confirmation through patient registries. |
| EU Green Deal Compliance Certification | Carbon footprint auditing unlocks European hospital network procurement access under sustainability mandates. |
| Gene Therapy Durability Tracking Systems | Long-term patient surveillance platforms address pharmacovigilance requirements for one-time interventions. |
Research Methodology
Bottom-up ophthalmology clinic throughput modeling reconciled against top-down pharmaceutical manufacturing capacity tracking forms the analytical core. Primary interviews with vitreoretinal surgeons, formulary directors at German hospital purchasing consortia, regulatory affairs leads, and payer access specialists cross-validated secondary sources including FDA breakthrough therapy designations, EMA PRIME scheme submissions, ClinicalTrials.gov entries, and CMS Medicare claims data.
Historical trendline analysis of intravitreal injection volumes across United States retirement corridors established baseline growth patterns. The projection framework segments by molecular mechanism, anatomical target, delivery mode sophistication, and care setting capital intensity. CAGRs derive from elasticity-adjusted demand curves incorporating reimbursement policy shifts and regulatory approval velocity across the modeling period. Forecast inputs include vitreoretinal fellowship training pipeline data and viral vector manufacturing capacity expansion announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under gene therapy durability signal failures or abrupt reimbursement compression in European tender markets. Practitioners should monitor FDA guidance evolution on surrogate endpoint validation and EMA PRIME scheme admission rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Ramipril Market
Pharmaceuticals
Metastatic Cancer Treatment Drug Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Cytomegalovirus Treatment Market
Pharmaceuticals
Cholinesterase Inhibitors Market
Pharmaceuticals
Global Zika Vaccines Market
Pharmaceuticals
Collagenase Clostridium Histolyticum Market
Pharmaceuticals
Antiglaucoma Drugs Market
Pharmaceuticals
Fusion Inhibitors Market
Pharmaceuticals
Mitotane Market
Pharmaceuticals
Europe Contraceptives Market
Pharmaceuticals
Global Pneumococcal Vaccines Market
Pharmaceuticals
Gonorrhea Therapeutics Market
Pharmaceuticals
Global Systemic Lupus Erythematosus Drugs Market
Pharmaceuticals
BRAF-MEK Inhibitors Market
Pharmaceuticals
Germany Pharmaceutical 3PL Market