
 Global Pharmaceutical Warehousing Market | 2026-2036
Global Pharmaceutical Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Pharmaceutical Warehousing Market Foresight
European cold storage infrastructure is shifting toward automated pharmaceutical warehouses as biologics volumes surge. DHL Supply Chain leverages its pan-European network of GDP-certified facilities to anchor temperature-sensitive distribution across the continent. Kuehne + Nagel sustains competitive positioning through specialized pharma corridors linking Swissmedic-regulated hubs to emerging production zones. FedEx Corp. differentiates via integrated cold chain monitoring that extends visibility from manufacturer to patient delivery points.
Pharmaceutical warehousing encompasses climate-controlled facilities designed to maintain product integrity through temperature bands spanning minus eighty degrees Celsius to controlled room temperature, supported by validated equipment and continuous monitoring systems. These facilities serve as critical nodes in drug supply chains, ensuring stability for active pharmaceutical ingredients, finished formulations, and clinical trial materials prior to distribution. Cold storage warehouses command premium positioning within the warehouse type segment as biologics and mRNA therapies displace small-molecule dominance, while automated warehouses capture margin pools through labor cost reduction and error-rate suppression. Third-party logistics providers within the operational model segment are consolidating share as pharmaceutical companies outsource capital-intensive compliance infrastructure.
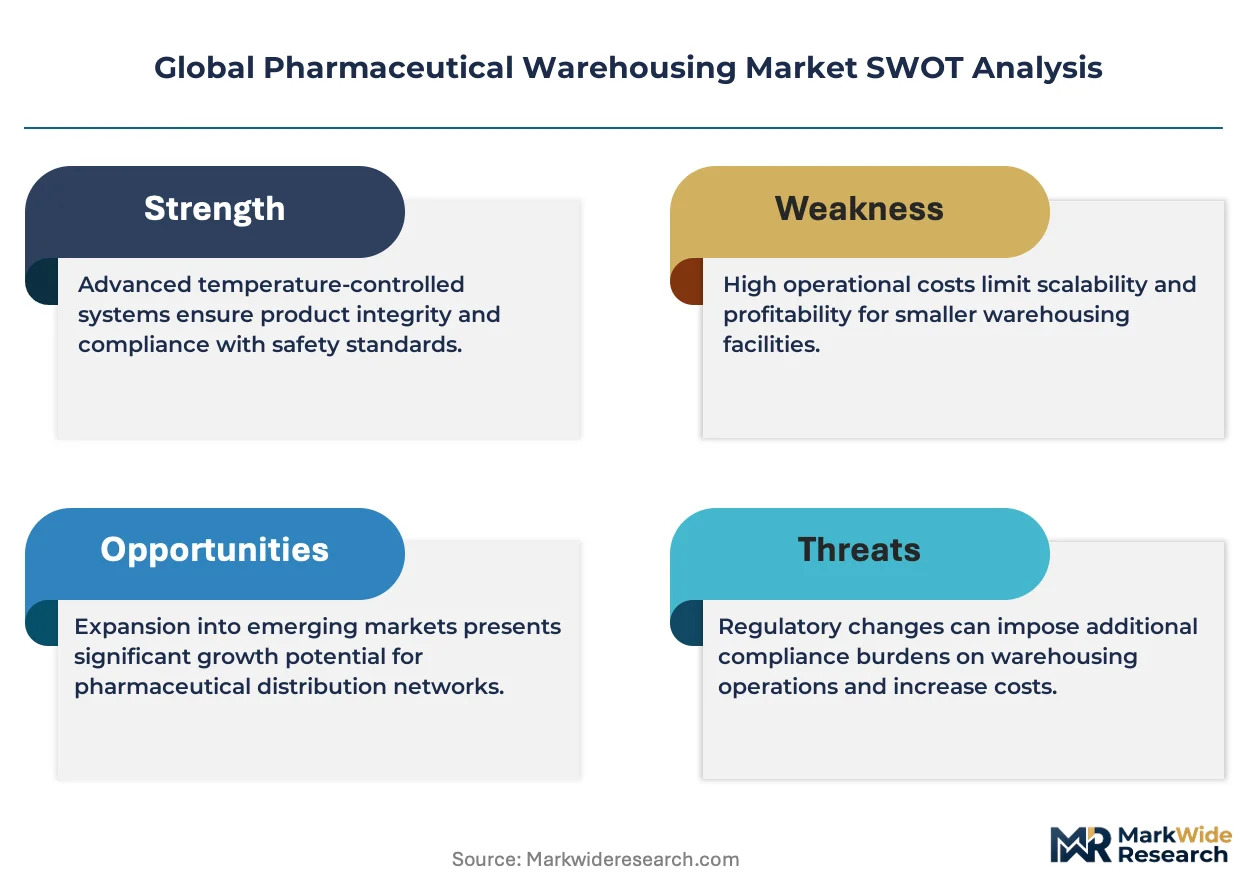
FDA enforcement of the Drug Supply Chain Security Act serialisation mandates is reshaping track-and-trace infrastructure investments across US pharmaceutical warehouses. The EU's Good Distribution Practice guidelines and the EU AI Act's risk classification framework for automated quality systems are simultaneously elevating compliance costs and technology barriers for warehouse operators serving European markets. Stakeholders must evaluate whether captive in-house logistics or outsourced third-party partnerships offer superior risk-adjusted returns as regulatory fragmentation between FDA, EMA, and national competent authorities intensifies.
Market Dynamics
Biologics and cell therapies are compressing temperature tolerances across pharmaceutical supply chains, forcing warehouse operators to deploy ultra-low temperature infrastructure at scale while maintaining GDP compliance across fragmented national frameworks.
Growth Catalysts
- EMA serialization mandates:The EU's Falsified Medicines Directive and its delegated regulation on safety features are compelling pharmaceutical manufacturers to upgrade warehouse track-and-trace systems, generating sustained demand for integrated compliance infrastructure.
- Cell therapy commercialization:CAR-T and gene therapy approvals are multiplying the volume of minus eighty degrees Celsius storage requirements, pulling investment into specialized cryogenic warehouse capacity.
- India's pharmaceutical manufacturing expansion:CDSCO regulatory harmonization and export-oriented production clusters in Hyderabad and Ahmedabad are concentrating demand for temperature-controlled warehousing serving regulated markets.
Market Restraints
- Specialized equipment supply concentration:Ultra-low temperature freezer production concentrates among a limited set of European and Japanese OEMs, exposing warehouse operators to extended lead times and parts scarcity.
- Energy cost volatility:Cold storage facilities consume three to six times the electricity of ambient warehouses, making operators vulnerable to grid price spikes and carbon pricing mechanisms under the EU Green Deal.
- Regulatory fragmentation:Divergent GDP interpretations between Germany's BfArM, France's ANSM, and Italy's AIFA create compliance friction for pan-European distribution networks.
Strategic Opportunities
- Brazil's ANVISA cold chain upgrade:Latin America's largest pharmaceutical market is tightening temperature monitoring requirements, creating first-mover advantages for GDP-certified operators establishing regional hubs.
- AI-driven predictive maintenance:Convergence of IoT sensor networks and machine learning algorithms is enabling warehouse operators to shift from scheduled to condition-based equipment servicing, compressing downtime.
- Saudi Arabia's SFDA localization push:The kingdom's pharmaceutical sector strategy is incentivizing domestic manufacturing and distribution infrastructure, opening warehouse development opportunities in Riyadh and Jeddah clusters.
Industry Challenges
- Qualified personnel scarcity:GDP certification and cold chain validation expertise remains concentrated among a limited pool of specialists, constraining expansion timelines for new market entrants.
- Legacy WMS integration:Pharmaceutical warehouses are struggling to overlay real-time temperature monitoring and serialization compliance onto decades-old warehouse management architectures without operational disruption.
- Validation protocol compression:Accelerated product launches are squeezing the duration of IQ/OQ/PQ qualification processes, elevating risk of temperature excursion events during facility commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Pharmaceutical Warehousing Market |
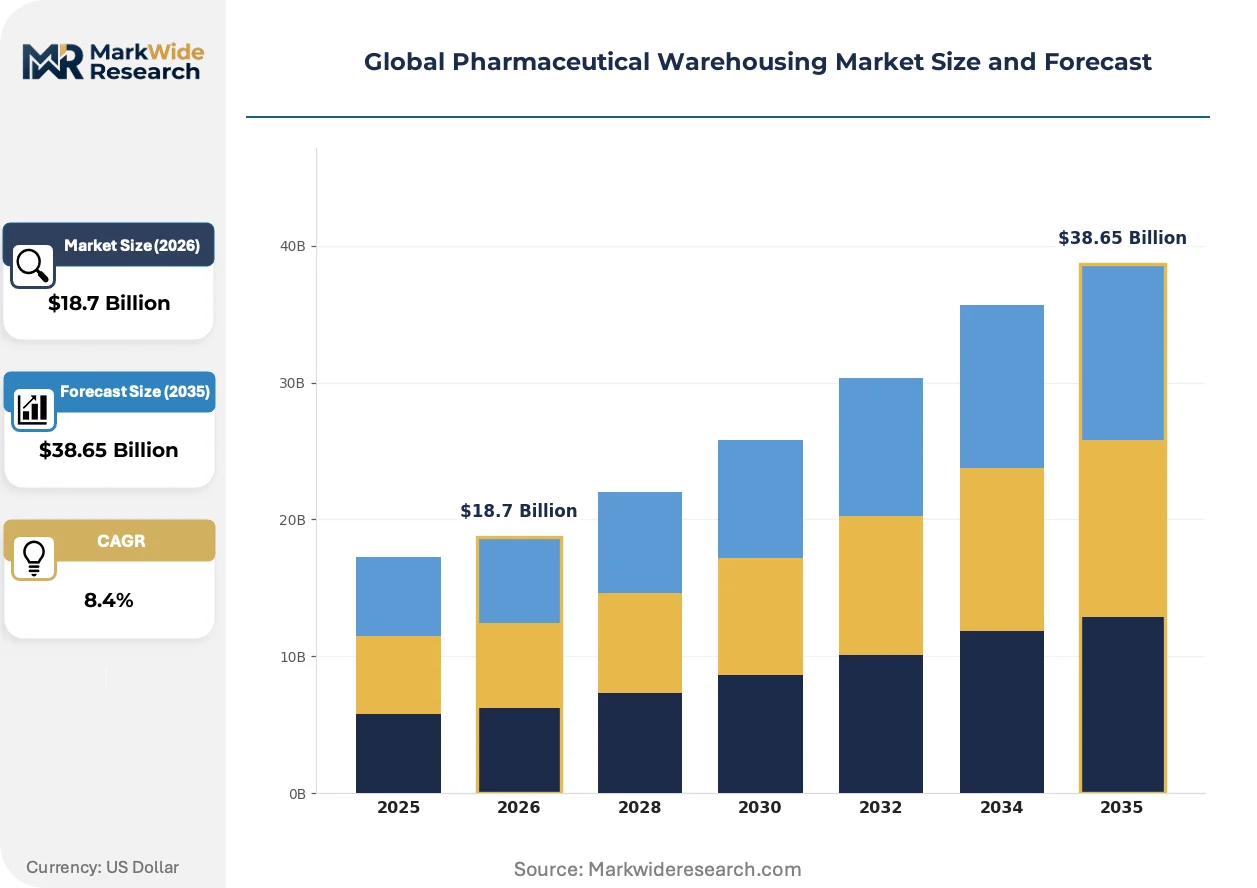
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Warehouse Type: Cold Storage, Ambient Storage, Controlled Environment, Automated Warehouse Service Type: Value-Added Services, Inventory Management, Transportation, Packaging Solutions End User: Pharmaceutical Companies, Biotechnology Firms, Contract Manufacturers, Research Institutions Operational Model: Third-Party Logistics, In-House Logistics, Hybrid Model, Just-In-Time |
| Companies Covered | CEVA Logistics, DB Schenker, United Parcel Service, XPO Logistics, GEODIS, DHL Supply Chain, Kuehne + Nagel, Americold Logistics, FedEx Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Pharmaceutical Warehousing Market Shifts & Advancements
Autonomous systems and predictive analytics are penetrating pharmaceutical warehousing faster than adjacent logistics sectors, driven by the cost of temperature excursions and the complexity of multi-modal cold chain handoffs.
Automated storage and retrieval systems equipped with robotic shuttles and crane mechanisms are automating pallet movement within minus twenty degrees Celsius environments previously restricted to manual handling. Large molecule manufacturers and vaccine distributors are deploying these systems at greenfield sites across Germany and the Netherlands. This automation is compressing labor requirements in high-wage European markets while eliminating human error in temperature-sensitive picking operations.
The EU AI Act's risk classification framework is mandating human oversight protocols for automated quality inspection systems deployed in pharmaceutical warehouses. Warehouse operators serving European markets must now document algorithmic decision trails and maintain override capabilities for AI-driven batch release checks. Cold chain facilities with integrated computer vision for damage detection are reconfiguring control architectures to satisfy these conformity requirements.
Consolidation of buying power among specialty pharmacy distributors is compressing contract renewal cycles and demanding outcome-based service level agreements with financial penalties for temperature excursions. Third-party logistics providers are responding with guaranteed availability commitments and real-time shipment visibility portals. This procurement evolution is most pronounced in the United States, where CVS Health and Cigna subsidiary Accredo are consolidating specialty pharmaceutical distribution relationships.
Global Pharmaceutical Warehousing Market Segmentation
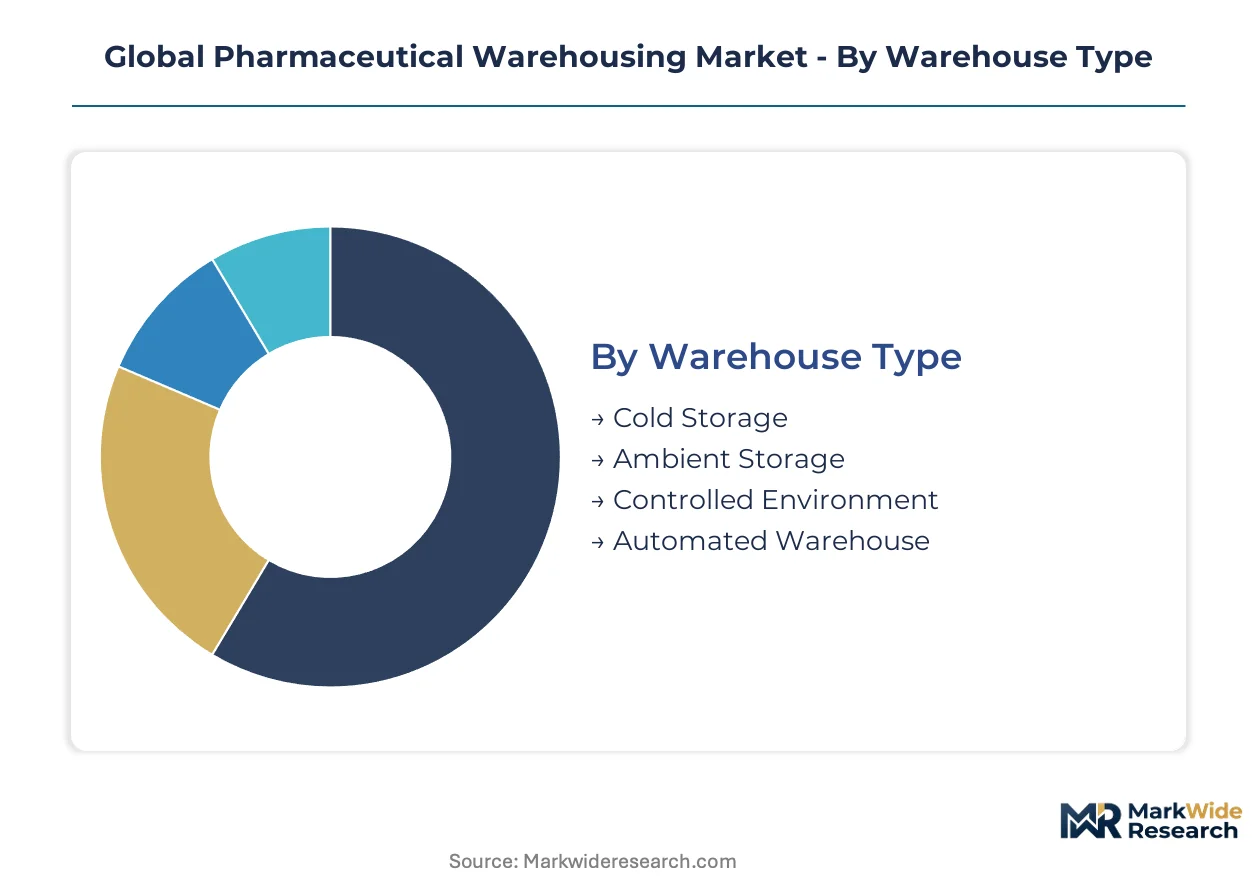
Pharmaceutical warehousing segmentation reveals how infrastructure investments align with product temperature sensitivity and regulatory compliance burdens. Each category captures distinct capital deployment patterns as operators balance automation against specialized cold chain requirements.
Warehouse Type:
Facility upgrade cycles accelerate where temperature tolerances compress and labor costs rise, reshaping capital allocation across warehouse archetypes.
- Cold Storage:Ultra-low temperature infrastructure maintains minus eighty degrees Celsius for cell therapies and mRNA vaccines through redundant freezer banks and liquid nitrogen backup systems. Demand concentrates in Germany and the United States as EMA and FDA tighten GDP validation requirements for cryogenic handling.
- Automated Warehouse:Robotic storage and retrieval systems operate across temperature bands from minus twenty degrees Celsius to controlled room temperature, eliminating human error in picking operations. European operators in the Netherlands and Switzerland deploy these systems fastest where wage premiums and serialization mandates elevate automation returns.
- Ambient Storage:Standard climate-controlled facilities handle small-molecule formulations and stable packaging materials with validated HVAC monitoring.
- Controlled Environment:Intermediate temperature bands serve biologics requiring two to eight degrees Celsius with continuous data logger verification.
Cold Storage sits at the top of the volume ranking, with Automated Warehouse climbing the fastest.
Service Type:
Service bundling intensity varies by customer sophistication, with large pharmaceutical manufacturers demanding integrated solutions that compress vendor counts.
- Value-Added Services:Labeling, kitting, and serialization compliance activities transform bulk shipments into market-ready units. Biotechnology firms in Boston and Basel outsource these functions to avoid captive investment in track-and-trace infrastructure.
- Inventory Management:Real-time stock visibility and expiry date tracking through WMS-ERP integration reduces write-offs. Contract manufacturers in India leverage these services to manage multi-product campaigns without dedicated warehouse assets.
- Transportation:Multi-modal cold chain coordination extends warehouse control through last-mile handoffs.
- Packaging Solutions:Qualified thermal shippers and phase-change materials protect temperature integrity during transit.
Inventory Management commands the largest share of recurring revenue, while Value-Added Services expands most quickly.
End User:
End-user procurement patterns diverge sharply between research-phase flexibility demands and commercial-scale compliance requirements.
- Pharmaceutical Companies:Large manufacturers operate captive warehouses for high-volume products while outsourcing specialty and launch-phase inventories. Pfizer and Roche maintain hybrid footprints across Germany, Switzerland, and Singapore to balance control against capital efficiency.
- Biotechnology Firms:Emerging therapy developers lack logistics scale and prefer fee-for-service arrangements that convert fixed costs to variable. Cell therapy specialists in California and Massachusetts drive demand for cryogenic third-party capacity.
- Contract Manufacturers:CDMOs require flexible warehousing to accommodate shifting client portfolios and campaign durations.
- Research Institutions:Academic and clinical trial sites need small-lot handling with chain-of-custody documentation.
Pharmaceutical Companies anchor demand volumes, though Biotechnology Firms gain share fastest.
Operational Model:
Outsourcing depth correlates with regulatory complexity and asset utilization uncertainty, pushing even large manufacturers toward hybrid structures.
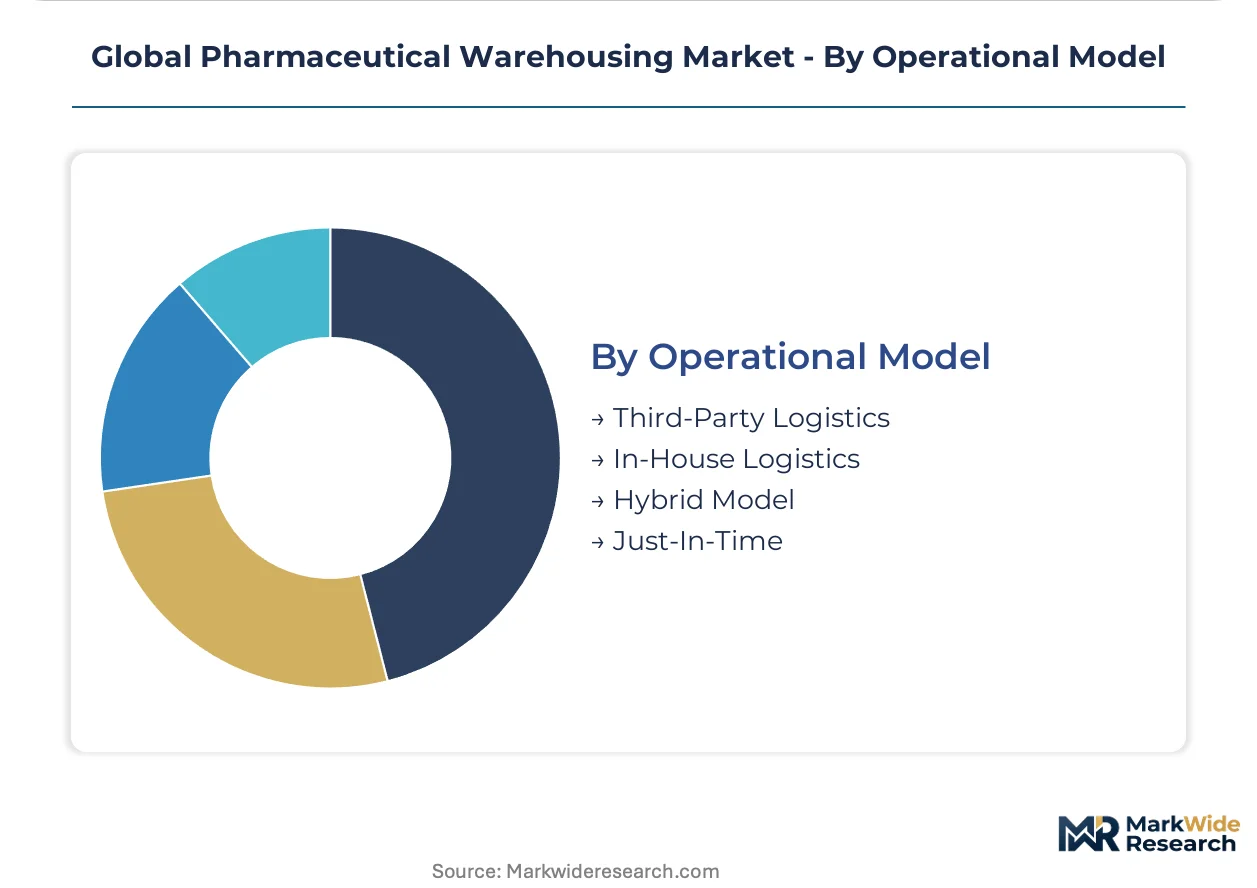
- Third-Party Logistics:Specialized providers like DHL and Kuehne + Nagel operate GDP-certified networks that pharmaceutical companies access without capital commitment. The model dominates in Europe where regulatory fragmentation between BfArM, ANSM, and AIFA rewards pan-regional expertise.
- In-House Logistics:Captive warehousing persists for blockbuster products with predictable demand and high margins. Indian pharmaceutical exporters in Hyderabad maintain owned facilities to satisfy CDSCO and US FDA inspection requirements directly.
- Hybrid Model:Strategic combination of captive capacity for core products and outsourced surge handling.
- Just-In-Time:Minimal inventory positioning responsive to demand signals, rare in pharmaceuticals due to stockout risks.
Third-Party Logistics holds dominant share, with Hybrid Model ascending fastest as manufacturers rebalance control against flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands denser GDP-certified warehouse networks than India, though Indian operators now match German cold storage volumes for export-bound biologics.
United States
FDA serialization deadlines under the Drug Supply Chain Security Act are forcing warehouse upgrades across the country. The agency's enforcement of track-and-trace infrastructure is accelerating capital deployment. Indianapolis and Memphis clusters concentrate automated pharmaceutical distribution centers serving specialty pharmacy networks.
Germany
BfArM inspections are tightening validation protocols for minus eighty degrees Celsius cell therapy storage. The EU's Good Distribution Practice guidelines create compliance benchmarks that German operators export across the continent. Rhine-Ruhr logistics corridors host the densest concentration of EMA-aligned cold chain facilities in Europe.
India
CDSCO regulatory harmonization with US FDA and EMA standards is elevating warehouse qualification requirements for export manufacturers. The government's PLI scheme for pharmaceuticals is incentivizing temperature-controlled infrastructure in production zones. Hyderabad and Ahmedabad anchor specialized cold storage capacity serving regulated markets in North America and Europe.
Switzerland
Swissmedic's stringent batch release verification is concentrating high-value biologics warehousing around Basel and Zurich. The country's bilateral recognition agreements with FDA and EMA position its warehouses as tri-regional distribution hubs. Geneva-area facilities specialize in clinical trial material storage with chain-of-custody documentation for multinational sponsors.
Brazil
ANVISA cold chain regulations are tightening temperature monitoring requirements for imported pharmaceuticals. The regulator's upgraded GDP enforcement is disqualifying ambient storage operators from handling temperature-sensitive products. São Paulo state concentrates the country's expanding network of validated pharmaceutical warehouses serving Latin American distribution.
Global Pharmaceutical Warehousing Market Competitive Landscape
European logistics providers anchor one tier through pan-regional GDP-certified networks; North American express carriers hold another through integrated cold chain visibility systems. The market structures around asset-heavy cold storage specialists and technology-enabled third-party platforms. Three archetypes dominate: integrated express networks, dedicated healthcare logistics divisions, and cold chain real estate operators. Capacity expansion in cryogenic infrastructure and strategic partnerships with cell therapy manufacturers represent the dominant competitive moves.
Among integrated logistics providers, DHL Supply Chain, Kuehne + Nagel, and FedEx Corp. exemplify distinct positioning archetypes. DHL Supply Chain represents the pan-European healthcare logistics model with GDP-certified facility networks spanning multiple regulatory jurisdictions. Kuehne + Nagel occupies a position linking Swissmedic-regulated precision with emerging market access capabilities. FedEx Corp. anchors the North American integrated express tier, where cold chain monitoring extends from manufacturer through last-mile patient delivery. These three entities collectively illustrate how geographic regulatory specialization and technology integration define competitive differentiation in pharmaceutical warehousing.
| Leading Market Players |
|---|
| CEVA Logistics |
| DB Schenker |
| United Parcel Service |
| XPO Logistics |
| GEODIS |
| DHL Supply Chain |
| Kuehne + Nagel |
| Americold Logistics |
| FedEx Corp. |
| Others |
Supply & Pricing Matrix
Specialty pharmacy distributors consolidating procurement through CVS Health and Accredo are compressing contract cycles and demanding outcome-based service level agreements with financial penalties for temperature excursions. This buyer concentration is shifting pharmaceutical warehousing toward performance-guaranteed pricing models where operators absorb excursion risk in exchange for multi-year volume commitments.
Pricing Analysis
Capacity additions in Germany and the Netherlands are reshaping price floors for automated cold storage as robotic shuttle systems reduce labor dependency in high-wage markets. Three-tier pricing structure across GDP-certified premium, standard validated, and economy ambient tiers reflects certification grade and temperature band complexity. Cost compression in standard controlled-environment warehousing is intensifying because Indian exporters are expanding qualified capacity for regulated markets. Biotechnology firms with cell therapy pipelines show least price sensitivity due to irreplaceable cryogenic requirements, while generic small-molecule distributors drive hardest bargaining on ambient storage rates.
Supply Chain Analysis
Freight cost volatility in pharmaceutical cold chain logistics is elevating total landed cost sensitivity as air cargo rates for temperature-controlled lanes fluctuate with pharmaceutical export volumes from India and Germany. Ultra-low temperature freezer production concentrates among European and Japanese OEMs, creating single-source vulnerability for minus eighty degrees Celsius infrastructure. Warehouse construction materials and qualified insulation panels draw from specialized chemical feedstock suppliers in Germany and Belgium. Distribution runs through third-party logistics networks where DHL and Kuehne + Nagel maintain pan-European GDP-certified corridors linking manufacturing clusters to patient delivery points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical warehousing offers margin expansion through automation-driven labor cost reduction and premium-tier cryogenic capacity where cell therapy demand outstrips qualified supply. Operators capturing EMA and FDA dual-certification premiums can sustain pricing power against commoditized ambient competitors.
For Market Incumbents: Anticipate regulatory fragmentation between BfArM, ANSM, and AIFA compliance interpretations by investing in modular warehouse architectures that adapt to divergent national GDP enforcement. Consolidate backward integration into ultra-low temperature equipment servicing capabilities to reduce OEM parts scarcity exposure. Capture margin pools through captive supply of liquid nitrogen backup systems rather than relying on third-party cryogen vendors. For New Entrants and Emerging Players: Capture white-space in Brazil's ANVISA-upgraded cold chain where incumbent presence remains thin and temperature monitoring mandates are disqualifying ambient operators. Target Saudi Arabia's SFDA localization push in Riyadh and Jedd clusters where domestic pharmaceutical manufacturing incentives are outpacing qualified warehouse supply. Enter through joint venture structures with established European logistics providers to transfer GDP certification expertise without decade-long qualification timelines. For Investors and Strategic Acquirers: Third-party logistics providers with integrated cold chain visibility platforms are the most active acquirer in this space, seeking technology-enabled targets that compress temperature excursion detection response times. Cell therapy-focused warehouse operators with validated minus eighty degrees Celsius capacity represent the priority acquisition archetype as CAR-T commercialization accelerates. Watch for FDA enforcement patterns on Drug Supply Chain Security Act serialization deadlines as the inflection signal distinguishing compliant premium-tier operators from stranded legacy facilities.| Strategic Initiative | Industry Significance |
|---|---|
| GDP Certification Investment | EMA-aligned validation protocols unlock pan-European distribution contracts with Pfizer and Roche. |
| Cryogenic Capacity Buildout | Minus eighty degrees Celsius infrastructure captures CAR-T therapy storage demand from Boston and Basel biotech clusters. |
| AI-Driven Predictive Maintenance | IoT sensor networks with machine learning algorithms shift equipment servicing from scheduled to condition-based. |
| Serialization Compliance Integration | Track-and-trace infrastructure satisfies FDA Drug Supply Chain Security Act mandates for US market access. |
| Regional Hub Development | São Paulo and Riyadh facilities exploit ANVISA and SFDA regulatory upgrades with first-mover positioning. |
Research Methodology
Bottom-up biotechnology firm and pharmaceutical manufacturer demand modeling reconciled against top-down cold storage capacity tracking forms the analytical core of this study. Primary interviews with warehouse operations directors, regulatory affairs leads at CDMOs, GDP compliance officers, and specialty pharmacy procurement managers combined with secondary validation from FDA filings, EMA inspection records, ClinicalTrials.gov logistics requirements, and national pharmaceutical regulator enforcement databases. Cross-referencing bottom-up facility utilization rates against top-down biologics production volumes ensures segmentation integrity across temperature bands and operational models.
Historical trendline analysis of cold storage construction permits and automated warehouse capital expenditure patterns established baseline growth trajectories. The projection framework segments by warehouse type, service bundling intensity, end-user procurement sophistication, and operational model outsourcing depth, with treatment temperature requirements and regional regulatory cluster alignment as cross-cutting dimensions. CAGRs derive from fitted growth curves adjusted for EMA serialization mandate phase-ins and cell therapy approval trajectories across the analysis window.
Regulatory enforcement delays, ultra-low temperature equipment supply bottlenecks, and energy price volatility are the dominant revision risks that could compress or extend forecast outcomes. Stakeholders should weight assumptions against their own operating context and captive infrastructure requirements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
US Emergency Contraceptive Pills Market
Pharmaceuticals
Prescription Stimulants Market
Pharmaceuticals
Asia-Pacific Contraceptive Drugs and Devices Market
Pharmaceuticals
Ophthalmic Drug Delivery Systems Market
Pharmaceuticals
Global Nizatidine Market
Pharmaceuticals
Dual Migraine Treatment Market
Pharmaceuticals
Global Transdermal Drug Delivery Systems Market
Pharmaceuticals
Pharma PLM Market
Pharmaceuticals
Italy Healthcare Market
Pharmaceuticals
Bisphosphonates Market
Pharmaceuticals
Oncology Small Molecule Drugs Market
Pharmaceuticals
Asia Pacific Multiple Sclerosis Drugs Market
Pharmaceuticals
Cancer Therapeutics and Biotherapeutics Market
Pharmaceuticals
Intravenous Pegloticase Market
Pharmaceuticals
Global Small Molecule Sterile Injectable Drugs Market