
 Europe Sodium-Dependent Glucose Cotransporter 2 Market | 2026-2036
Europe Sodium-Dependent Glucose Cotransporter 2 Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Sodium-Dependent Glucose Cotransporter 2 Market Foresight
Hospital formularies is reorganizing Europe's SGLT2 procurement patterns as integrated care systems gain purchasing leverage over retail pharmacies. AstraZeneca dominates the dapagliflozin segment through its FORXIGA brand presence across European hospital networks. Boehringer Ingelheim anchors the empagliflozin category with sustained cardiovascular outcome data supporting reimbursement negotiations. Eli Lilly and Company differentiates through its positioning at the intersection of diabetes and obesity therapy areas.
Sodium-dependent glucose cotransporter 2 inhibitors function as selective renal SGLT2 protein blockers, reducing glucose reabsorption in the proximal tubule to lower blood glucose while producing natriuresis and osmotic diuresis; these agents now serve dual therapeutic purposes in glycemic control and cardiorenal protection. Empagliflozin and dapagliflozin command the dominant product positions, with empagliflozin holding established cardiovascular indication depth and dapagliflozin extending into heart failure with preserved ejection fraction populations. The therapy area dimension shows diabetes management as the mature revenue base while cardiovascular health applications generate the fastest label expansion and pricing premium capture.
The European Medicines Agency's cardiovascular outcome trial requirements and the EU Medical Device Regulation's companion diagnostic standards shape product development timelines and market access pathways for combination therapies. REACH compliance for active pharmaceutical ingredient manufacturing and the F-Gas Regulation's solvent restrictions influence production cost structures across European supply chains. Stakeholders must monitor EMA label expansions into chronic kidney disease without diabetes and national health technology assessment bodies' willingness to pay for preventive cardiorenal indications.
Market Dynamics
Hospital procurement consolidation across Germany and France is restructuring Europe's SGLT2 distribution architecture, concentrating purchasing power within integrated care networks and marginalizing traditional retail pharmacy channels.
Growth Catalysts
- EMA cardiovascular outcome label expansions:The European Medicines Agency's broadened indication requirements for heart failure with preserved ejection fraction are opening reimbursement pathways previously restricted to diabetes populations.
- France's hospital-centric reimbursement structure:The French national health insurance system's preference for hospital-based prescribing creates volume concentration in institutional channels.
- Cardiorenal protection protocols:Nephrology departments across European university hospitals are integrating SGLT2 inhibitors into chronic kidney disease treatment algorithms independent of glycemic status.
Market Restraints
- Active pharmaceutical ingredient concentration:SGLT2 API manufacturing concentrates in Chinese and Indian contract manufacturers, exposing European formulators to supply disruption risk and REACH compliance verification burdens.
- F-Gas Regulation solvent restrictions:The EU F-Gas Regulation's phasedown of hydrofluorocarbon solvents used in crystallization processes is forcing reformulation investments and capacity relocation.
- Biosimilar glucose-lowering alternatives:GLP-1 receptor agonists with demonstrated cardiovascular benefit are capturing overlapping patient populations in obesity management.
Strategic Opportunities
- Poland and Eastern European hospital networks:Underpenetrated integrated care systems in Poland, Hungary, and the Czech Republic present first-mover advantages for formulary inclusion negotiations.
- EU Green Deal pharmaceutical manufacturing mandates:Sustainability certification requirements for API production create differentiation opportunities for European-based manufacturing investments.
- Fixed-dose combination convergence:Pairing SGLT2 inhibitors with SGLT1 blockers or non-steroidal mineralocorticoid antagonists addresses polypharmacy compliance in elderly heart failure populations.
Industry Challenges
- Health technology assessment timeline compression:National reimbursement bodies in Germany, France, and Italy are accelerating evidence review cycles while demanding real-world data post-launch.
- EU Medical Device Regulation companion diagnostic integration:Biomarker-guided patient selection tools require synchronized regulatory submissions, complicating development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Sodium-Dependent Glucose Cotransporter 2 Market |
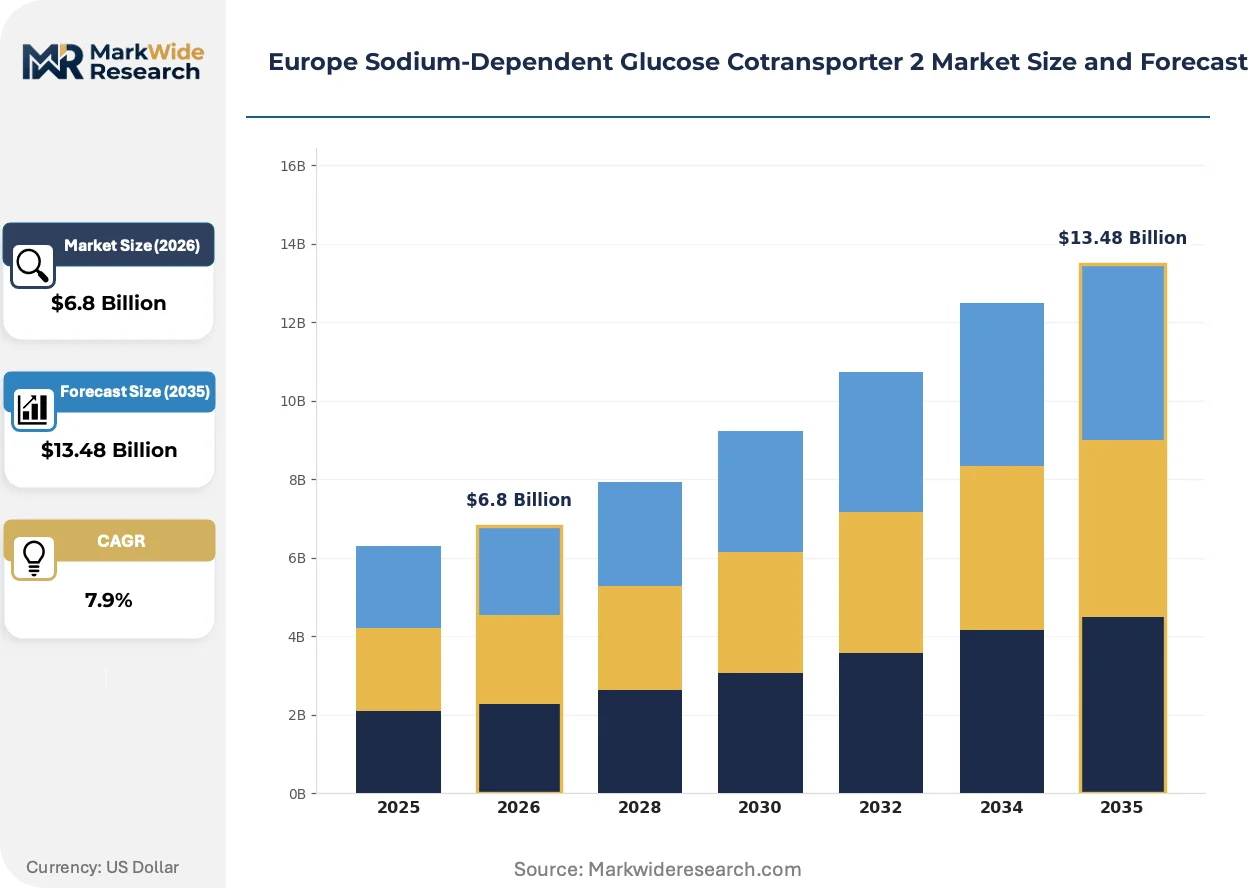
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $13.48 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dapagliflozin, Empagliflozin, Canagliflozin, Ipragliflozin End User: Hospitals, Clinics, Pharmacies, Homecare Administration Route: Oral, Subcutaneous, Intravenous, Transdermal Therapy Area: Diabetes Management, Obesity, Cardiovascular Health, Renal Protection |
| Companies Covered | AstraZeneca, Boehringer Ingelheim, Bristol-Myers Squibb, Eli Lilly and Company, Janssen Pharmaceuticals, Merck & Co., Sanofi, Novartis, Pfizer, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Sodium-Dependent Glucose Cotransporter 2 Market Shifts & Advancements
Formulation sustainability and digital therapeutics integration are restructuring how SGLT2 inhibitors are manufactured, prescribed, and monitored across European healthcare systems.
Continuous manufacturing technologies for API synthesis are supplanting traditional batch processing in European production facilities. Boehringer Ingelheim and AstraZeneca are retrofitting legacy plants in Germany and Sweden to reduce solvent waste and energy intensity. This transition is compressing cost structures for high-volume dapagliflozin and empagliflozin production while satisfying EU Green Deal reporting requirements.
REACH compliance for active pharmaceutical ingredient sourcing is tightening supplier qualification standards. The European Chemicals Agency's expanded substance of very high concern candidate list now captures intermediates used in gliflozin synthesis. Formulators are responding by auditing Indian and Chinese API manufacturers against European environmental standards, with some relocating crystallization steps to facilities in Ireland and Switzerland.
Integrated care networks in Germany are unbundling pharmacy dispensing from clinical decision-making. Hospital formularies now direct SGLT2 prescribing through electronic health record order sets, bypassing retail pharmacist consultation. This channel consolidation is most advanced in Bavaria and North Rhine-Westphalia, where sickness funds have negotiated preferential pricing for network-committed volume.
Europe Sodium-Dependent Glucose Cotransporter 2 Market Segmentation
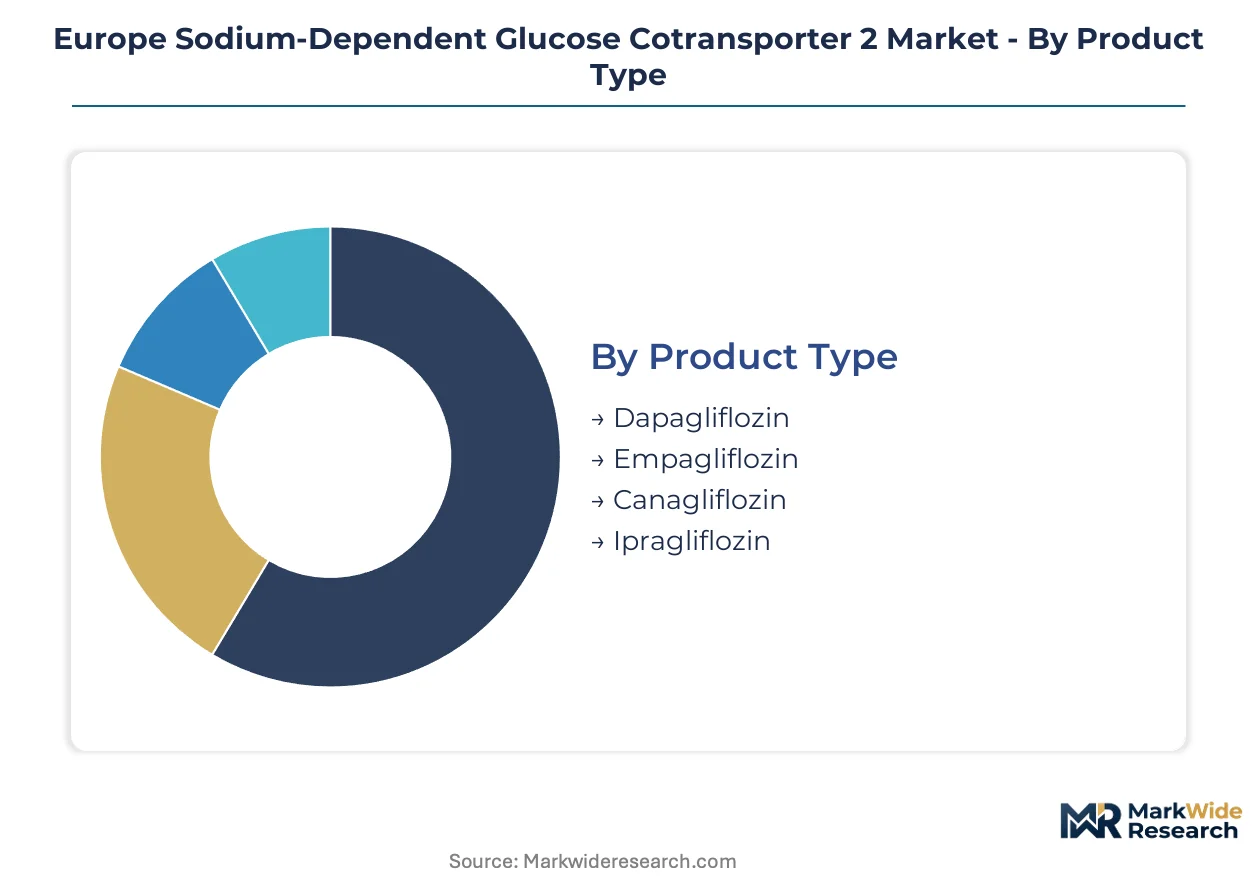
Channel configuration across Europe's SGLT2 market varies sharply by segment. Hospital procurement networks in Germany and France concentrate volume for cardiovascular and renal indications, while retail pharmacies retain diabetes prescribing in Southern Europe.
Product Type:
Distribution architecture differs markedly across the four molecule classes, with hospital formularies favoring agents with established cardiovascular outcome data and retail channels handling legacy diabetes prescriptions.
- Dapagliflozin:Selective SGLT2 inhibitor with established heart failure with preserved ejection fraction labeling. German integrated care networks and French hospital formularies drive procurement concentration for cardiorenal protocols.
- Empagliflozin:First SGLT2 inhibitor to demonstrate cardiovascular mortality reduction in outcome trials. Reimbursement negotiations across German sickness funds and French HAS assessments anchor its institutional channel dominance.
- Canagliflozin:Earlier-generation agent with concentrated diabetes prescribing in Southern European retail pharmacies. EMA safety monitoring for lower-limb amputation risk has shifted new prescriptions toward newer alternatives.
- Ipragliflozin:Japan-originated molecule with limited European market penetration. Niche positioning in specific national formularies where local regulatory pathways accelerated approval.
Empagliflozin dominates installed base across cardiovascular indications. Dapagliflozin is where expansion concentrates for heart failure populations.
End User:
Customer-type segmentation reveals institutional purchasing power consolidation reshaping margin structures and access requirements.
- Hospitals:University medical centers and acute care facilities across Germany, France, and Italy drive SGLT2 volume for inpatient heart failure protocols. Electronic health record order sets embed prescribing guidelines, bypassing traditional pharmacy consultation.
- Clinics:Outpatient cardiology and nephrology practices in France and the Netherlands manage chronic therapy initiation. Reimbursement pathways favor clinic-based prescribing for renal protection indications independent of diabetes status.
- Pharmacies:Community pharmacies retain diabetes maintenance prescribing in Spain, Portugal, and Greece. Retail margin compression from generic gliflozin entry is accelerating channel consolidation toward hospital networks.
- Homecare:Specialized infusion services and chronic disease management programs in Nordic countries support elderly polypharmacy patients. Compliance packaging and remote monitoring integration differentiate this channel.
Hospitals command pricing leverage through volume commitment. Homecare is climbing the fastest as aging populations shift chronic disease management outside institutional settings.
Administration Route:
Formulation technology and patient compliance requirements segment the market by delivery mechanism, with oral dominance giving way to novel routes in specific clinical scenarios.
- Oral:Once-daily tablet formulations dominate prescribing across all therapeutic areas. German and Swedish manufacturing facilities produce the majority of European supply under EU Green Deal sustainability mandates.
- Subcutaneous:Investigational depot formulations in development for heart failure populations with medication adherence challenges. Clinical trial activity concentrates in UK and Netherlands research networks.
- Intravenous:Acute care settings in French and Italian hospitals utilize IV formulations for inpatient decompensated heart failure. Limited to hospital-only administration under national formularies.
- Transdermal:Early-stage patch development for elderly patients with swallowing difficulties. Regulatory pathway complexity through EMA's MDR companion diagnostic requirements constrains commercial timeline.
Oral formulations dominate installed base. Subcutaneous delivery is where pipeline investment concentrates for adherence-critical populations.
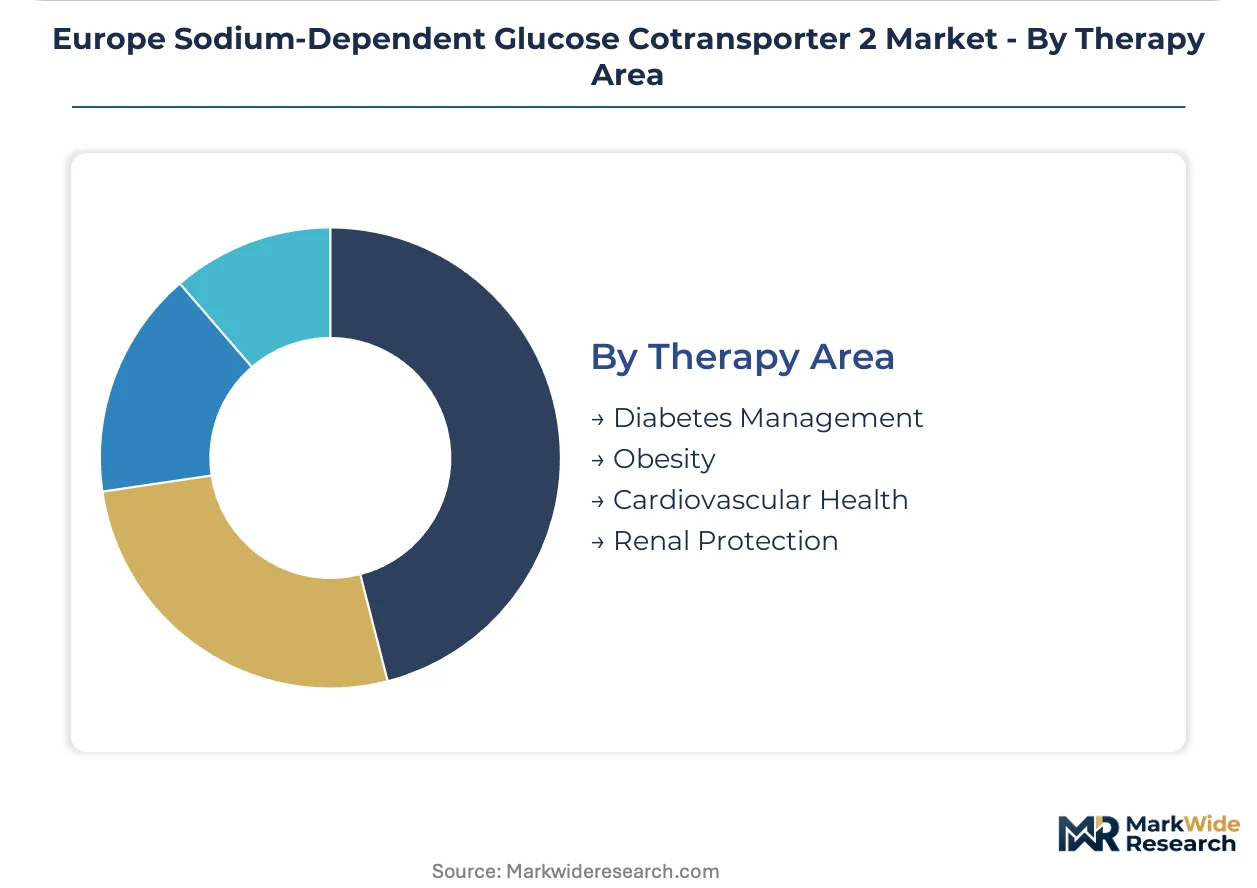
Therapy Area:
Application segmentation tracks the expanding indication footprint beyond glycemic control into cardiorenal protection, with reimbursement body willingness-to-pay varying sharply by clinical outcome.
- Diabetes Management:Mature revenue base with established HbA1c reduction endpoints. German and French retail pharmacies retain significant volume for type 2 diabetes maintenance despite hospital channel encroachment.
- Obesity:Adjunctive therapy positioning where SGLT2 inhibitors complement GLP-1 receptor agonists. Nordic countries and Netherlands demonstrate highest per-capita prescribing for weight management protocols.
- Cardiovascular Health:Fastest-expanding indication category driven by EMA label extensions for heart failure with reduced and preserved ejection fraction. Hospital formularies in Germany and France prioritize agents with proven mortality benefit.
- Renal Protection:Chronic kidney disease progression slowing independent of glycemic status. Nephrology departments across European university hospitals integrate SGLT2 inhibitors into standard-of-care algorithms.
Diabetes management anchors installed base. Cardiovascular health represents the steepest expansion trajectory as outcome-based reimbursement spreads across national health systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine Corridor's pharmaceutical logistics network underwrites Central Europe's dominance in SGLT2 distribution, with temperature-controlled freight routes connecting API facilities to hospital formularies across the continent.
Germany
Bavarian integrated care networks and North Rhine-Westphalian sickness funds drive hospital procurement concentration for cardiovascular indications. The Federal Joint Committee's (G-BA) early benefit assessment framework accelerates reimbursement decisions for heart failure therapies. Mannheim and Ludwigshafen host API formulation clusters where Boehringer Ingelheim operates production facilities under REACH compliance mandates.
France
Parisian university hospitals anchor nephrology department adoption for renal protection protocols independent of diabetes status. The Haute Autorité de Santé's (HAS) hospital-centric reimbursement structure channels SGLT2 volume through institutional pharmacies. The Lyon-Grenoble pharmaceutical belt concentrates manufacturing investments responding to EU Green Deal sustainability reporting requirements.
Italy
Lombardy's chronic disease management programs in Milan and Bergamo integrate SGLT2 inhibitors into elderly polypharmacy protocols. The Italian Medicines Agency's (AIFA) regional pricing negotiations create geographic variation in hospital formulary access. The Emilia-Romagna cluster around Bologna specializes in continuous manufacturing technology retrofits for oral solid dose production.
United Kingdom
London and Manchester research networks lead clinical trial activity for subcutaneous depot formulations in heart failure populations. The National Institute for Health and Care Excellence's (NICE) technology appraisals set precedent for cardiovascular outcome-based reimbursement across European health systems. The Cambridge-Norwich biotech corridor attracts formulation development investment targeting medication adherence challenges.
Poland
Warsaw and Kraków hospital networks present underpenetrated integrated care systems for first-mover formulary inclusion negotiations. The Polish Office for Registration of Medicinal Products's (URPL) accelerated pathways for cardiovascular therapies shorten market access timelines. The Wrocław pharmaceutical zone attracts contract manufacturing organization investment serving Eastern European distribution.
Europe Sodium-Dependent Glucose Cotransporter 2 Market Competitive Landscape
Listed leaders compete with private specialists across cardiovascular outcome data depth and hospital formulary anchoring. The European SGLT2 market exhibits concentrated structure around three multinational pharmaceutical groups with established EMA label expansions, while mid-tier players compete through regional licensing arrangements and combination therapy pipelines. Strategic archetypes include cardiovascular outcome trial sponsors, integrated diabetes-obesity portfolio builders, and nephrology-focused indication expanders. Dominant competitive moves center on EMA label extension submissions for chronic kidney disease without diabetes and manufacturing capacity relocation to satisfy EU Green Deal mandates.
Within the cardiovascular outcome sponsor tier, AstraZeneca and Boehringer Ingelheim exemplify divergent positioning strategies. AstraZeneca anchors the dapagliflozin category through FORXIGA brand presence across German and French hospital networks. Boehringer Ingelheim occupies a position defined by empagliflozin's established mortality benefit data and sustained reimbursement negotiations with German sickness funds. Eli Lilly and Company represents the integrated portfolio archetype, sitting at the intersection of diabetes and obesity therapy areas with positioning that addresses overlapping patient populations.
| Leading Market Players |
|---|
| AstraZeneca |
| Boehringer Ingelheim |
| Bristol-Myers Squibb |
| Eli Lilly and Company |
| Janssen Pharmaceuticals |
| Merck & Co. |
| Sanofi |
| Novartis |
| Pfizer |
| Others |
Supply & Pricing Matrix
REACH compliance for active pharmaceutical ingredient manufacturing gates both supplier qualification and price differentiation across European SGLT2 procurement. German and French hospital networks leverage volume commitment to extract preferential pricing from formulators with verified European environmental certification, while uncertified Asian API sources face margin compression from audit costs and supply exclusion.
Pricing Analysis
Volume-discount tiering structures dominate SGLT2 procurement across German integrated care networks and French hospital formularies. Three-tier pricing separates originator brands with cardiovascular outcome data from standard-tier generics and economy-tier unbranded alternatives. Price differentiation hinges on EMA label breadth and EU Green Deal manufacturing certification. Cost compression in the economy tier is intensifying because of Indian and Chinese API oversupply. Retail pharmacies in Southern Europe exhibit highest price sensitivity; university hospital networks command lowest net pricing through exclusive contracting.
Supply Chain Analysis
Strait of Hormuz transit risk and Red Sea disruption exposure concentrate European SGLT2 supply vulnerability in maritime API logistics. Active pharmaceutical ingredient production draws from China, India, and limited European facilities in Ireland and Switzerland. Key inputs include gliflozin synthesis intermediates, hydrofluorocarbon solvents facing F-Gas Regulation phase-down, and crystallization-grade reagents. Single-source vulnerability persists for specialized chiral catalysts used in empagliflozin production. Distribution runs through temperature-controlled Rhine-Alpine freight corridors connecting Mannheim formulation plants to hospital formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European SGLT2 markets sit in early-cycle expansion as EMA label extensions for chronic kidney disease without diabetes unlock reimbursement pathways previously restricted to diabetes populations. Cardiorenal protocol adoption across university hospital networks accelerates penetration beyond traditional glycemic control indications.
For Market Incumbents: Compound cardiovascular outcome data advantages through EMA submissions for heart failure with preserved ejection fraction combination therapies. Deepen backward integration into API synthesis to mitigate REACH compliance verification burdens and capture margin from Asian contract manufacturers. Prioritize capacity addition in German and Swedish facilities to satisfy EU Green Deal sustainability mandates and defend formulary position against emerging biosimilar glucose-lowering alternatives.
For New Entrants and Emerging Players: EMA accelerated assessment pathways for cardiovascular therapies create fast-track entry for molecules with mortality benefit data. Target Polish and Czech hospital networks where integrated care system penetration remains underdeveloped and formulary negotiation windows remain open. Pursue fixed-dose combination strategies pairing SGLT2 inhibitors with non-steroidal mineralocorticoid antagonists to differentiate in elderly polypharmacy populations.
For Investors and Strategic Acquirers: EMA label expansions into renal protection without diabetes reshape the acquisition landscape toward nephrology-focused indication expanders. Five-to-ten year viability favors formulators with European-based API production and established hospital formulary anchoring. Target acquisition archetype: mid-tier players with combination therapy pipelines and underexploited Eastern European distribution. Monitor EMA chronic kidney disease label decisions as primary inflection signal for reimbursement body willingness-to-pay shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| EMA Label Extension Submission | Chronic kidney disease without diabetes indication opens new reimbursement pathways across German sickness funds. |
| EU Green Deal Manufacturing Certification | Sustainability reporting compliance differentiates European API production against Asian contract manufacturers. |
| Fixed-Dose Combination Development | Pairing SGLT2 inhibitors with SGLT1 blockers addresses polypharmacy compliance in elderly heart failure populations. |
| Hospital Formulary Partnership | Electronic health record order set integration embeds prescribing guidelines and bypasses retail pharmacy channels. |
| Continuous Manufacturing Retrofit | Boehringer Ingelheim and AstraZeneca facilities in Germany and Sweden reduce solvent waste and energy intensity. |
Research Methodology
Desk research of EMA regulatory filings, ClinicalTrials.gov outcome databases, and national formulary directories preceded structured interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists. Secondary validation drew from SEC 10-K pharmaceutical disclosures, EU customs trade data, and German sickness fund reimbursement bulletins. Bottom-up prescription volume modeling and top-down market value triangulation cross-validated segment estimates.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics and mix-shift effects. Segmentation dimensions modeled include molecule type, administration route, therapy area, end-user channel, and regional regulatory cluster. CAGRs were derived from fitted growth curves anchored to historical prescription trajectories and adjusted for EMA label expansion probability. Forecast inputs incorporate hospital formulary adoption curves and health technology assessment timeline compression factors.
Underlying assumptions cover EMA approval timelines for renal indications, REACH compliance enforcement intensity, and GLP-1 receptor agonist competitive displacement rates, with deviation risk concentrated in biosimilar entry timing and Eastern European reimbursement harmonization. Practitioners should keep alternative scenarios live as cardiovascular outcome trial readouts and EU pharmaceutical sustainability mandates evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Asia Pacific SGLT2 Inhibitors Market
Pharmaceuticals
Secondary Myelofibrosis Therapeutics Market
Pharmaceuticals
North America Hormone Replacement Therapy Market
Pharmaceuticals
Viral Conjunctivitis Pipeline Drugs Market
Pharmaceuticals
B7-H3 Antibody Market
Pharmaceuticals
Carbetocin Injection Market
Pharmaceuticals
TNF Inhibitors Market
Pharmaceuticals
Global Aminoglycosides Market
Pharmaceuticals
Vaccine Contract Development and Manufacturing Organization Market
Pharmaceuticals
Prescription Drugs Market
Pharmaceuticals
Narcotic Analgesics Market
Pharmaceuticals
Hard Empty HPMC Capsule Market
Pharmaceuticals
Asia-Pacific Vaccines Market
Pharmaceuticals
Injectable Targeted Therapy Market
Pharmaceuticals
South Korea Diabetes Drugs Market
Pharmaceuticals
Amoxicillin Sodium Clavulanate Potassium for Injection Market