
 Artificial Implants Market | 2026-2036
Artificial Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Artificial Implants Market Analysis
The premium-commodity split in artificial implants is rebalancing as titanium 3D-printed custom geometries command price multiples over standard cobalt-chrome hip stems. Medtronic plc leverages its cardiac rhythm management infrastructure to dominate electrophysiology implant channels. Zimmer Biomet Holdings Inc. anchors reconstructive joint replacement through surgeon training networks and instrument tray standardization. Cochlear Limited differentiates with perimodiolar electrode arrays that sustain premium positioning in the hearing implant segment.
Artificial implants are biocompatible devices surgically placed to replace or support damaged biological structures, typically fabricated from titanium alloys, medical-grade ceramics, or ultra-high molecular weight polyethylene with surface porosities engineered for osseointegration. These devices restore physiological function in applications ranging from load-bearing joint reconstruction to neural signal transduction. Orthopedic implants occupy the largest revenue pool due to volume-driven knee and hip arthroplasty, while cardiovascular implants generate superior per-unit margins through transcatheter delivery systems and tissue valve technologies. Cochlear implants represent the fastest-expanding category as expanded pediatric screening protocols and adult candidacy broadening activate previously untapped patient cohorts.
FDA premarket notification and EU MDR notified body conformity assessments impose escalating clinical evidence requirements that filter subscale manufacturers from commercial participation. Japan's PMDA and China's NMPA maintain distinct biocompatibility testing standards that fragment regulatory strategy for multinational portfolios. Stakeholders must monitor reimbursement parity between robotic-assisted and conventional implant placement procedures as this divergence will determine capital allocation across surgical automation platforms.
Market Dynamics
Titanium additive manufacturing is compressing the supply chain for orthopedic implants while simultaneously fragmenting production geography as hospital-based 3D printing labs bypass traditional instrument sterilization and logistics networks entirely.
Growth Catalysts
- Ambulatory Surgery Center Expansion:Medicare reimbursement parity for outpatient joint replacement in the United States is pulling hip and knee arthroplasty from inpatient settings. Titanium 3D-printed patient-specific instrumentation reduces surgical time and supports same-day discharge economics.
- EU MDR Conformity Assessment Streamlining:Notified body capacity expansion under the Medical Device Regulation is accelerating market access for established manufacturers with robust quality management systems. Biocompatibility documentation standardization reduces redundant testing across member states.
- Pediatric Cochlear Screening Mandates:Universal newborn hearing screening programs in Japan and Germany are activating early intervention pathways. Expanded candidacy criteria for asymmetric hearing loss are extending implantation to adolescent and adult cohorts previously excluded.
Market Restraints
- Titanium Powder Supply Concentration:Plasma atomization capacity for medical-grade Ti-6Al-4V ELI concentrates among three North American and European suppliers. Aerospace demand spikes create allocation priority conflicts that delay orthopedic production schedules.
- EU MDR Clinical Evidence Escalation:The Medical Device Regulation's stricter equivalence pathways now require manufacturer-owned clinical data for implantable devices. Legacy predicate devices lose grandfathered status, forcing costly prospective studies for line extensions.
- Revision Surgery Liability Exposure:Metal-on-metal bearing surface litigation has elevated product liability insurance premiums for joint replacement manufacturers. Surgeon training documentation requirements for new implant systems extend sales cycles.
Strategic Opportunities
- India's Orthopedic Volume Gap:Domestic production of standard hip and knee implants meets under 15 percent of procedural demand. Joint replacement surgery centers in Mumbai and Delhi are expanding capacity faster than local supply can match.
- Neural Interface Convergence:Cochlear implant electrode array engineering expertise transfers to emerging brain-computer interface applications. Deep brain stimulation and spinal cord stimulation manufacturers seek perimodiolar electrode geometries for improved signal fidelity.
- Japan PMDA Sakigake Pathway:The regenerative medicine and device fast-track designation compresses review timelines for breakthrough technologies. Early approval commitments enable pricing negotiations before full pivotal trial completion.
Industry Challenges
- Additive Manufacturing Technician Scarcity:Hospital-based 3D printing labs require personnel trained simultaneously in biomedical engineering, quality systems, and powder bed fusion operation. Certification programs through ASTM F42 and ISO/ASTM 52900 remain underdeveloped relative to deployment timelines.
- Legacy Electronic Health Record Integration:Implant registry data capture for EU MDR post-market surveillance conflicts with proprietary hospital information system architectures. Automated device identifier transmission to national joint registries requires middleware development that stretches IT budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Artificial Implants Market |
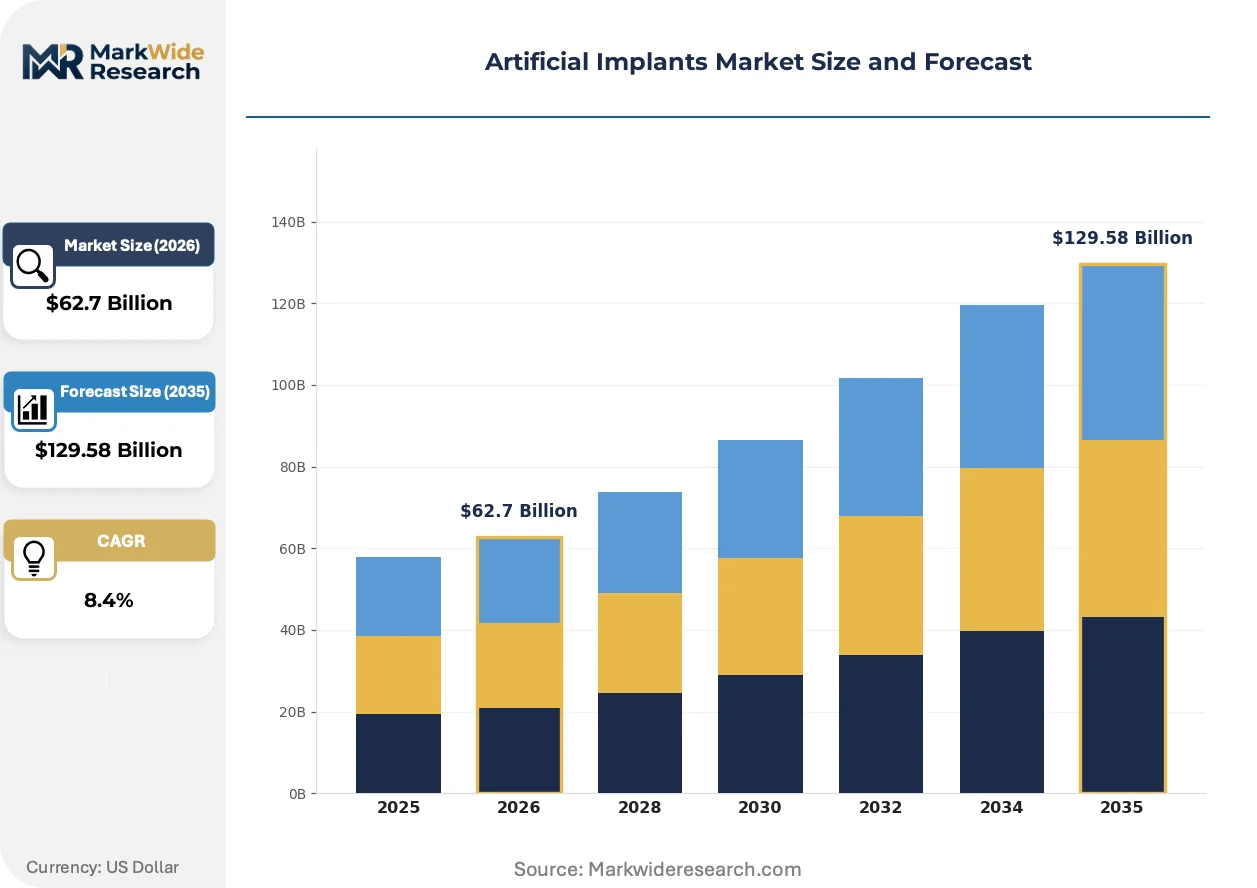
| Market Size in 2026 | $62.7 Billion |
| Market Size in 2035 | $129.58 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cochlear Implants, Dental Implants, Orthopedic Implants, Cardiovascular Implants Material: Titanium, Ceramic, Polyethylene, Composite End User: Hospitals, Clinics, Research Labs, Specialty Centers Application: Hearing Loss, Bone Fractures, Cardiac Issues, Cosmetic Enhancement |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Zimmer Biomet Holdings Inc., Johnson & Johnson, Stryker Corporation, Edwards Lifesciences Corporation, Cochlear Limited, Smith & Nephew plc, Ekso Bionics Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Artificial Implants Market Emerging Trajectories
Point-of-care manufacturing is dissolving the traditional separation between implant production and surgical delivery, enabling same-day customization that reconfigures inventory economics and sterilization workflows across orthopedic supply chains.
Patient-specific instrumentation generated from preoperative CT scans is decentralizing the location of implant manufacturing value creation. Ambulatory surgery centers in Germany and the United States are installing titanium powder bed fusion systems that produce surgical guides and trial implants overnight. This capability compresses instrument tray logistics from weeks to hours while shifting quality responsibility from original equipment manufacturers to facility-based operators.
The EU MDR's Unique Device Identification mandate and enhanced post-market clinical follow-up requirements are restructuring competitive advantage toward data infrastructure ownership. Manufacturers with established implant registries in Sweden and the United Kingdom now possess defensible evidence generation platforms that newer entrants cannot replicate without decade-long investment. Cardiovascular implant segments face the steepest compliance gradient due to long-term follow-up obligations for transcatheter valve durability.
Surgeon preference for robotic-assisted implant placement is fragmenting procurement authority away from hospital materials management toward physician-owned ambulatory facilities. United States orthopedic groups are consolidating into specialty-focused enterprises that self-fund MAKO or ROSA robotic systems, bypassing traditional capital equipment sales cycles through direct equipment financing. This shift concentrates procedural volume in lower-cost settings while demanding implant vendors provide instrumentation compatibility across multiple robotic platforms.
Artificial Implants Market Segmentation
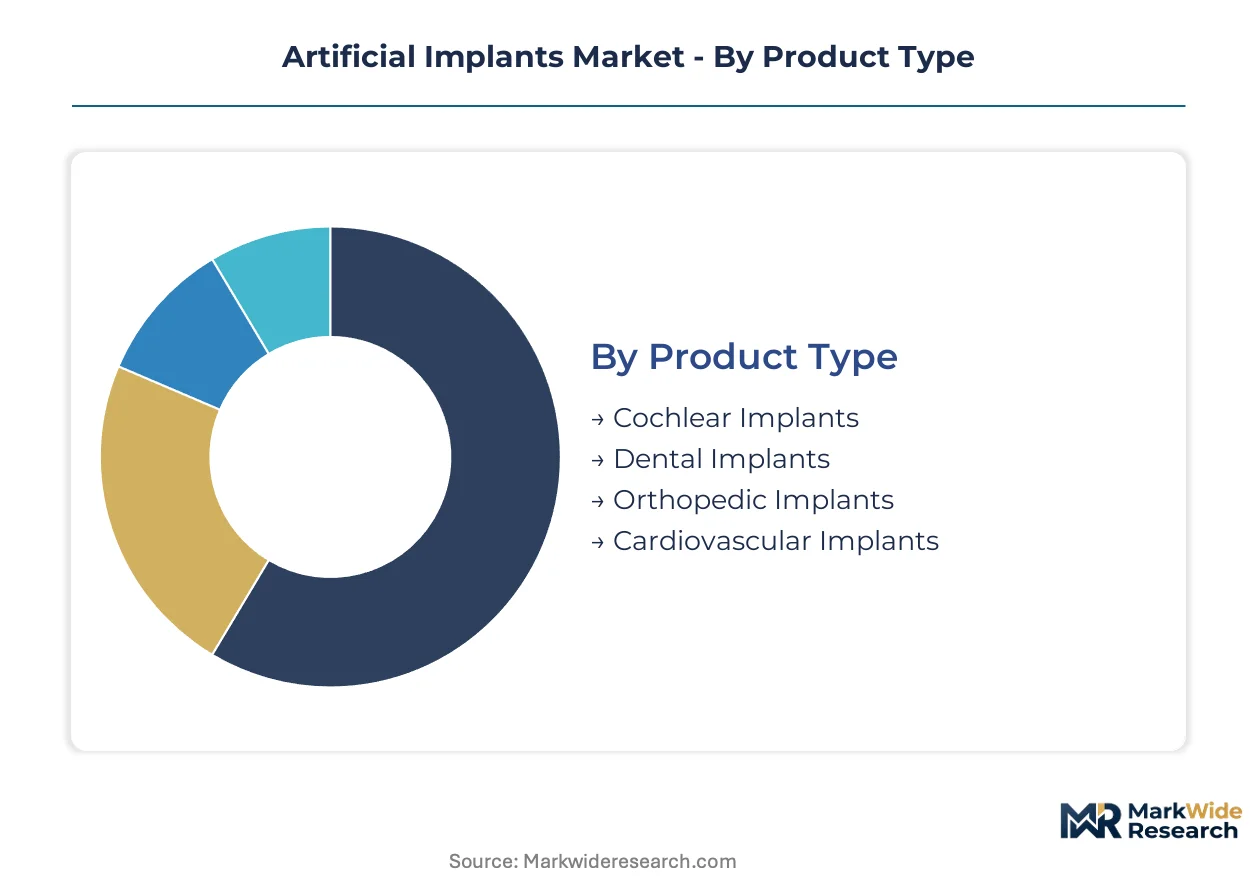
Segmentation in artificial implants reveals divergent margin structures and regulatory intensities across product categories. Material selection drives biocompatibility certification pathways, while end-user concentration shapes distribution economics and post-market surveillance obligations.
Product Type:
Buyer differentiation hinges on procedure reimbursement tiers and revision risk tolerance.
- Orthopedic Implants:Fabricated from Ti-6Al-4V ELI titanium alloys with trabecular surface architectures engineered for osseointegration. Demand concentrates in ambulatory surgery centers across the United States and Germany, where Medicare parity for outpatient joint replacement compresses surgical timelines and elevates same-day discharge requirements.
- Cardiovascular Implants:Transcatheter valve frames and cardiac rhythm management devices utilize nitinol superelasticity and platinum-iridium electrode configurations. Japanese and German hospitals drive procurement volume through established electrophysiology infrastructure, though EU MDR clinical evidence escalation for long-term durability follow-up strains manufacturer compliance budgets.
- Cochlear Implants:Perimodiolar electrode arrays with 22-channel signal processing restore auditory nerve transduction. Pediatric screening mandates in Japan and Germany activate early intervention pathways.
- Dental Implants:Root-form titanium fixtures with threaded geometries anchor prosthetic crowns and bridges. Private-pay cosmetic demand in urban United States and German markets supports premium pricing.
Volume sits with Orthopedic Implants; growth tilts toward Cochlear Implants.
Material:
Cost tier stratification separates aerospace-grade feedstock from commodity medical polymers.
- Titanium:Ti-6Al-4V ELI and commercially pure grades dominate load-bearing applications through fatigue resistance and bone conductivity. Plasma atomization capacity constraints in North America and Europe create allocation priority conflicts with aerospace demand.
- Ceramic:Alumina and zirconia-toughened alumina bearings reduce wear debris in hip arthroplasty. Japanese manufacturers lead bioinert oxide processing for dental and orthopedic segments.
- Polyethylene:Cross-linked ultra-high molecular weight polyethylene liners articulate against metal or ceramic femoral heads. Standardized compression molding supports cost-competitive knee replacement economics.
- Composite:Carbon fiber-reinforced PEEK and bioactive glass hybrids address modulus-matching requirements in spinal fusion cages. Niche applications in cranial reconstruction and trauma plating.
Titanium commands the installed base; composite formulations are gaining share fastest in spinal and trauma segments.
End User:
Procurement authority fragmentation distinguishes capital-equipped health systems from physician-owned facilities.
- Hospitals:Integrated delivery networks in the United States and Germany maintain implant registries for EU MDR post-market surveillance compliance. Robotic-assisted surgery capital commitments concentrate procedural volume in tertiary centers.
- Specialty Centers:Orthopedic-focused ambulatory surgery centers in Texas, Florida, and Bavaria bypass traditional sterilization logistics through point-of-care 3D printing labs. Direct surgeon ownership accelerates technology adoption decisions.
- Clinics:Dental implantology practices and hearing rehabilitation centers manage lower-acuity procedures with reduced regulatory documentation burdens.
- Research Labs:Academic medical centers in Boston, Heidelberg, and Tokyo conduct pivotal trials for FDA premarket approval and PMDA Sakigake pathway submissions.
Procedure volume concentrates in Hospitals; Specialty Centers show the steepest expansion trajectory.
Application:
Patient candidacy criteria and reimbursement clarity separate acute intervention from elective enhancement.
- Hearing Loss:Sensorineural impairment treatment spans congenital pediatric cases to adult-onset presbycusis. Expanded asymmetric loss candidacy in Japan and Germany extends implantation to previously excluded adolescent cohorts.
- Cardiac Issues:Structural heart disease and arrhythmia management require transcatheter delivery expertise concentrated in United States and German interventional cardiology programs.
- Bone Fractures:Trauma plating and intramedullary nailing address acute orthopedic injury. Volume correlates with aging demographics and osteoporosis prevalence.
- Cosmetic Enhancement:Elective dental and craniofacial reconstruction operates outside statutory reimbursement frameworks. Private-pay elasticity constrains volume in economic downturns.
Hearing Loss applications are expanding most quickly; Bone Fractures maintain the largest procedural base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Minneapolis-St. Paul corridor anchors North American artificial implant innovation through dense concentrations of cardiac rhythm management and orthopedic reconstruction expertise.
United States
Medicare reimbursement parity for outpatient joint replacement pulls hip and knee arthroplasty into ambulatory surgery centers across Texas and Florida. FDA premarket approval pathways tighten biocompatibility documentation requirements for titanium additive manufacturing. The Research Triangle in North Carolina hosts specialized training networks for robotic-assisted implant placement.
Germany
Universal newborn hearing screening programs activate early cochlear intervention pathways in Bavarian pediatric centers. EU MDR notified body conformity assessments escalate clinical evidence requirements for implantable devices. The Stuttgart-Tübingen corridor concentrates perimodiolar electrode array engineering and 3D-printed patient-specific instrumentation development.
Japan
Aging demographics and expanded asymmetric hearing loss candidacy extend cochlear implantation to adolescent cohorts previously excluded. PMDA Sakigake fast-track designation compresses review timelines for breakthrough regenerative medicine devices. Tokyo and Osaka academic medical centers conduct pivotal trials for neural interface convergence applications.
India
Domestic production of standard hip and knee implants meets under 15 percent of procedural demand in Mumbai and Delhi joint replacement centers. CDSCO medical device regulations fragment import approval timelines for multinational portfolios. Hyderabad and Bangalore specialty hospitals expand capacity faster than local supply chains can match orthopedic volume growth.
China
NMPA maintains distinct biocompatibility testing standards that complicate regulatory strategy for multinational implant portfolios. Shanghai and Beijing tertiary hospitals concentrate transcatheter valve delivery expertise and cardiac rhythm management infrastructure. Provincial procurement consortiums drive price compression on standard orthopedic implants while premium 3D-printed custom geometries retain margin protection.
Artificial Implants Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material certification tiers and regulatory submission sophistication. Consolidated revenue pools concentrate among integrated device manufacturers with captive surgeon training networks and instrument tray standardization capabilities. Three archetypes dominate: diversified conglomerates spanning cardiac and orthopedic segments, pure-play cochlear specialists leveraging electrode array IP, and emerging point-of-care manufacturing enablers. Competitive moves center on M&A for registry data assets and strategic partnerships for titanium powder supply security.
Within the diversified conglomerate tier, Medtronic plc and Johnson & Johnson exemplify scale-driven positioning across multiple implant categories. Zimmer Biomet Holdings Inc. occupies a reconstructive joint replacement anchor position through instrument standardization and ambulatory surgery center channel penetration. Cochlear Limited represents the pure-play specialist archetype with concentrated expertise in auditory nerve signal transduction engineering.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Zimmer Biomet Holdings Inc. |
| Johnson & Johnson |
| Stryker Corporation |
| Edwards Lifesciences Corporation |
| Cochlear Limited |
| Smith & Nephew plc |
| Ekso Bionics Holdings Inc. |
| Others |
Supply Flow & Price Mechanics
EU MDR biocompatibility documentation mandates gate qualified supply access and premium-tier pricing eligibility, compressing margins for manufacturers lacking established quality management systems while rewarding incumbents with grandfathered clinical data assets.
Pricing Analysis
Value-based pricing anchored to revision-rate outcomes and same-day discharge economics dominates orthopedic implant procurement. Three-tier pricing structure across premium, standard, and economy levels separates titanium 3D-printed custom geometries from cobalt-chrome standard stems and cross-linked polyethylene commodity liners. Cost compression in standard joint replacement tiers intensifies because provincial procurement consortiums in China and hospital group purchasing organizations in the United States extract volume discounts. Ambulatory surgery centers exhibit highest price sensitivity due to thin episode-of-care margins, while academic medical centers tolerate premium positioning for registry-eligible implant systems.
Supply Chain Analysis
Single-source vulnerability sits with plasma atomization capacity for medical-grade Ti-6Al-4V ELI powder concentrated among North American and European suppliers. Production draws from Germany, the United States, and Japan for precision-machined instrumentation and electrode array assembly. Aerospace demand spikes for titanium feedstock create allocation priority conflicts that strain orthopedic production schedules. Tariff exposure runs through China-sourced ceramic bearings and nitinol wire for cardiovascular applications. Distribution runs through original equipment manufacturer direct sales forces to hospital materials management and specialty distributor networks serving ambulatory surgery centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a consolidation play as EU MDR clinical evidence escalation filters subscale manufacturers unable to fund prospective studies for legacy predicate devices.
For Market Incumbents: Anchor registry data ownership as the primary defensive moat against emerging point-of-care manufacturing enablers. Deepen backward integration into titanium powder supply through long-term offtake agreements with plasma atomization specialists. Prioritize software companion development for robotic-assisted implant placement to maintain instrumentation compatibility across MAKO and ROSA platforms. For New Entrants and Emerging Players: Physician-owned ambulatory surgery centers in Texas and Florida represent the most penetrable buyer archetype bypassing traditional hospital procurement committees. Target neural interface convergence applications leveraging cochlear electrode array engineering expertise for brain-computer interface signal fidelity improvements. Pursue PMDA Sakigake pathway submissions to compress regulatory timelines before full pivotal trial completion. For Investors and Strategic Acquirers: Notified body capacity expansion completion is the leading indicator that EU MDR market access bottlenecks will ease for quality-system-mature manufacturers. Long-term viability favors diversified conglomerates with captive surgeon training networks and instrument tray standardization capabilities. Monitor titanium powder supply allocation announcements as the inflection signal for production constraint resolution.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Accelerates conformity assessment timelines for implantable device portfolios through dedicated reviewer allocation. |
| Titanium Powder Supply Security Agreement | Locks medical-grade Ti-6Al-4V ELI allocation priority against aerospace demand spikes through contractual volume commitments. |
| Point-of-Care 3D Printing Lab Deployment | Compresses instrument tray logistics from weeks to hours while shifting quality responsibility to facility-based operators. |
| Implant Registry Data Platform Acquisition | Captures decade-long post-market surveillance assets that new entrants cannot replicate for EU MDR compliance. |
| Robotic Platform Instrumentation Compatibility Program | Secures implant vendor positioning across MAKO, ROSA, and emerging surgical automation systems through standardized interfaces. |
Methodological Framework
Multi-period observation of Medicare reimbursement parity implementation, EU MDR notified body capacity expansion, and PMDA Sakigake pathway utilization anchored the trend analysis, supplemented by interviews with orthopedic surgeons, hospital purchasing committee directors, biomedical engineers specializing in additive manufacturing, GPO contracts managers, and regulatory affairs leads at multinational device manufacturers. Secondary validation drew from FDA premarket notification databases, EUDAMED device registration records, CMS outpatient procedure volume reports, and national joint registry annual statistics. Bottom-up implant unit demand estimates triangulated against top-down healthcare expenditure projections.
Segment-weighting approaches applied product type, material certification tier, end-user procurement authority, and application candidacy criteria dimensions across the modeling period. CAGRs derived from procedure volume elasticity to demographic aging patterns, reimbursement policy shifts, and technology substitution rates. Forecast inputs incorporated titanium powder supply allocation cycles, robotic-assisted surgery capital equipment deployment trajectories, and pediatric cochlear screening mandate expansion timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to aerospace demand spikes diverting titanium feedstock, EU MDR equivalence pathway reinterpretations, and reimbursement parity reversals for outpatient joint replacement. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Active Implantable Devices Market
Medical Devices
Asia Pacific Reprocessed Medical Devices Market
Medical Devices
Sweden Minimally Invasive Surgery Devices Market
Medical Devices
Global Over-The-Wire Micro-Guide Catheter Market
Medical Devices
Smart Medical Devices Market
Medical Devices
Cervical Traction Devices for Home Use Market
Medical Devices
Computer Assisted Surgical (CAS) Systems Market
Medical Devices
Biologic Injectors Market
Medical Devices
Global Anastomosis Devices Market
Medical Devices
Mexico Electrocardiograph (ECG) Market
Medical Devices
Americas Medical Suction Device Market
Medical Devices
Consumer Grade EEG Device Market
Medical Devices
Medical Fiber Optics Market
Medical Devices
Waterproof Orthotics Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Medical Device and Accessories Market