
 North America Glucagon-Like Peptide-1 Agonists Market | 2026-2036
North America Glucagon-Like Peptide-1 Agonists Market Size, Share, and Industry Trends Forecast 2026-2036
North America Glucagon-Like Peptide-1 Agonists Market Analytics
Recombinant peptide manufacturing is pivoting from traditional E. coli expression systems toward yeast-based platforms that cut production costs and improve glycosylation fidelity. Novo Nordisk leverages its Danish-North American manufacturing footprint to sustain supply security for high-volume GLP-1 products. Eli Lilly and Company anchors its competitive position through R&D intensity in dual and triple incretin agonists.
Glucagon-like peptide-1 agonists are synthetic analogs of the endogenous incretin hormone GLP-1, typically 30-31 amino acid peptides with N-terminal modifications that resist dipeptidyl peptidase-4 degradation and extend half-life to 12-168 hours depending on formulation; they stimulate glucose-dependent insulin secretion and suppress glucagon release to manage metabolic disease. Semaglutide dominates prescription volumes across retail and institutional channels, while oral tablet delivery modes capture patient segments with injection aversion and expand addressable populations beyond traditional diabetes management. Cardiovascular risk reduction indications are emerging as the fastest-growing segment as payers reorient reimbursement around outcomes-based contracts.
FDA review standards under the Endocrinologic and Metabolic Drugs Advisory Committee shape trial design requirements and label expansion pathways for new molecular entities. Health Canada and the FDA coordinate through the Orbis Project to align oncology and metabolic drug reviews, though GLP-1 sponsors still navigate separate manufacturing inspections and post-market surveillance obligations in each jurisdiction. Stakeholders must monitor how CMS national coverage determinations for obesity indications will reshape prescribing economics and pharmacy benefit design across Medicare Advantage plans.
Market Dynamics
Yeast-based expression platforms are compressing manufacturing economics for recombinant peptides while FDA accelerated approval pathways compress development timelines. Supply security concerns concentrate around Danish-North American manufacturing corridors.
Growth Catalysts
- Medicare coverage expansion:CMS national coverage determinations for obesity indications are unlocking reimbursement in Medicare Advantage plans across multiple states.
- Employer-sponsored health plans:Large self-insured employers are integrating GLP-1 therapies into metabolic disease management programs as a cost-containment lever.
- Oral tablet formulations:Non-injectable delivery modes are capturing patient segments with needle aversion and expanding addressable populations beyond diabetes.
Market Restraints
- Recombinant peptide input costs:Fermentation-grade amino acids and specialized chromatography resins face price volatility from concentrated Asian suppliers.
- Single-region manufacturing concentration:Active pharmaceutical ingredient production clusters heavily in Denmark and the United States, creating geopolitical supply risk.
- Medicaid access fragmentation:State-level coverage determinations for obesity indications create uneven patient access across the United States.
Strategic Opportunities
- Canadian provincial expansion:Health Canada alignment with FDA review standards through the Orbis Project accelerates market entry timelines.
- Cardiovascular risk reduction labeling:Outcomes-based contracts with payers are reorienting reimbursement around hard endpoint data.
- Dual incretin convergence:Combination GLP-1/GIP agonist platforms are opening differentiated positioning in metabolic disease portfolios.
Industry Challenges
- Peptide synthesis expertise scarcity:Biologics manufacturing talent pools are insufficient for scaled recombinant production demands.
- Post-market surveillance complexity:FDA and Health Canada maintain separate pharmacovigilance reporting requirements that duplicate compliance burden.
- Cold chain distribution scale:Temperature-controlled logistics networks require capital-intensive expansion to match prescription volume growth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Glucagon-Like Peptide-1 Agonists Market |
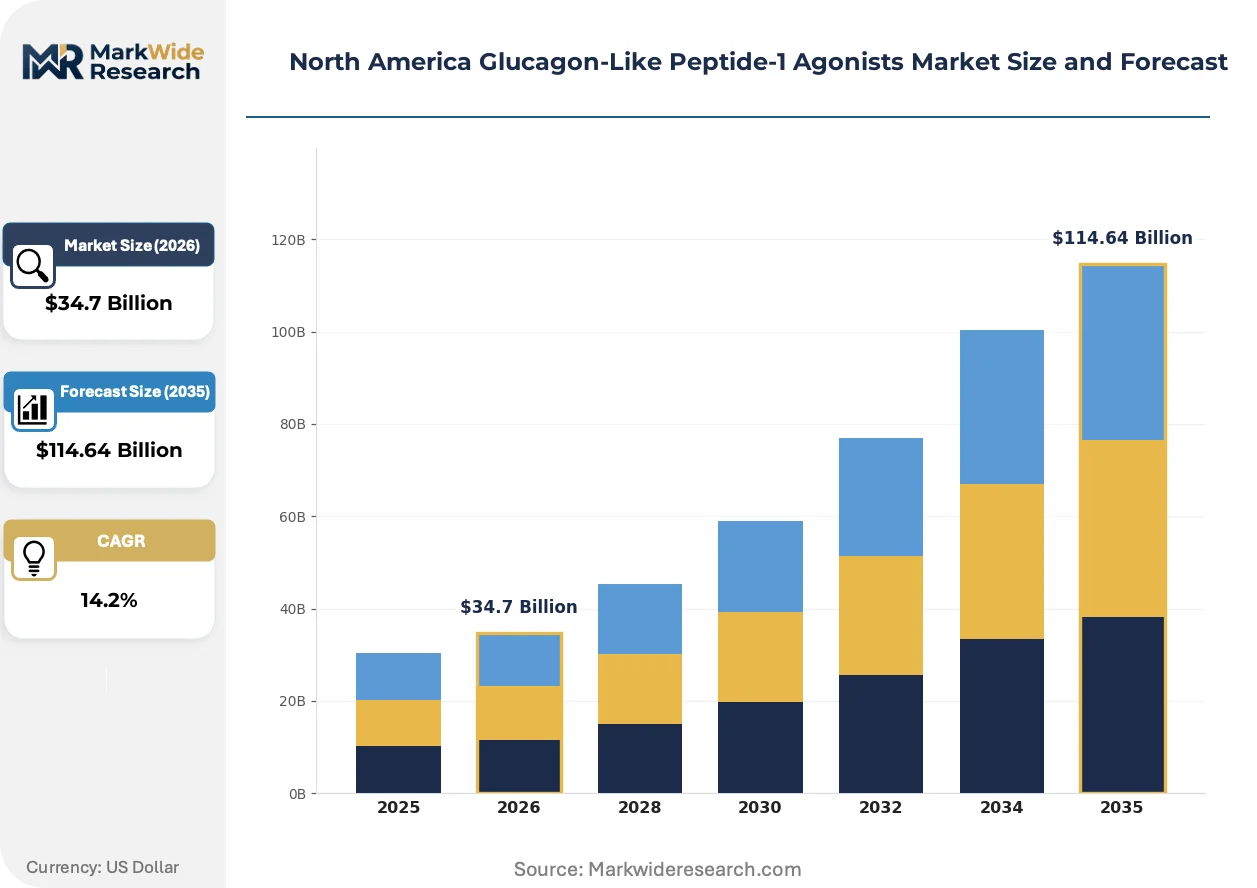
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $114.64 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liraglutide, Semaglutide, Dulaglutide, Exenatide Indication: Type 2 Diabetes, Obesity, Cardiovascular Risk Reduction, Non-alcoholic Fatty Liver Disease Delivery Mode: Subcutaneous Injection, Oral Tablet, Pen Injector, Continuous Infusion End User: Hospitals, Clinics, Home Care, Research Institutions |
| Companies Covered | Novo Nordisk, Eli Lilly and Company, Sanofi, AstraZeneca, Pfizer, Boehringer Ingelheim, Amgen, Merck and Co., GlaxoSmithKline, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Glucagon-Like Peptide-1 Agonists Market Evolving Landscape
Biologic manufacturing technology and regulatory science are converging to reshape how metabolic therapies reach patients. Three forces dominate this transformation.
Yeast-based expression systems are rewriting production economics for long-acting peptides. Contract development and manufacturing organizations are adopting Pichia pastoris platforms to achieve human-compatible glycosylation patterns at lower cost than E. coli systems. This shift is compressing cost-per-gram metrics and enabling higher-volume supply security.
FDA's Endocrinologic and Metabolic Drugs Advisory Committee has tightened cardiovascular outcomes trial requirements for new molecular entities. Sponsors must now demonstrate MACE reduction in pre-approval or post-approval studies to secure obesity labeling. Cardiometabolic therapeutic categories face the steepest compliance burden as trial designs expand in duration and patient numbers.
Pharmacy benefit managers are unbundling traditional formulary placement from outcomes guarantee contracts. Large employers and regional health plans now negotiate rebate structures tied to weight loss thresholds and diabetes progression prevention. This restructuring is most visible in self-insured employer plans across the Midwest and Southeastern United States.
North America Glucagon-Like Peptide-1 Agonists Market Segmentation
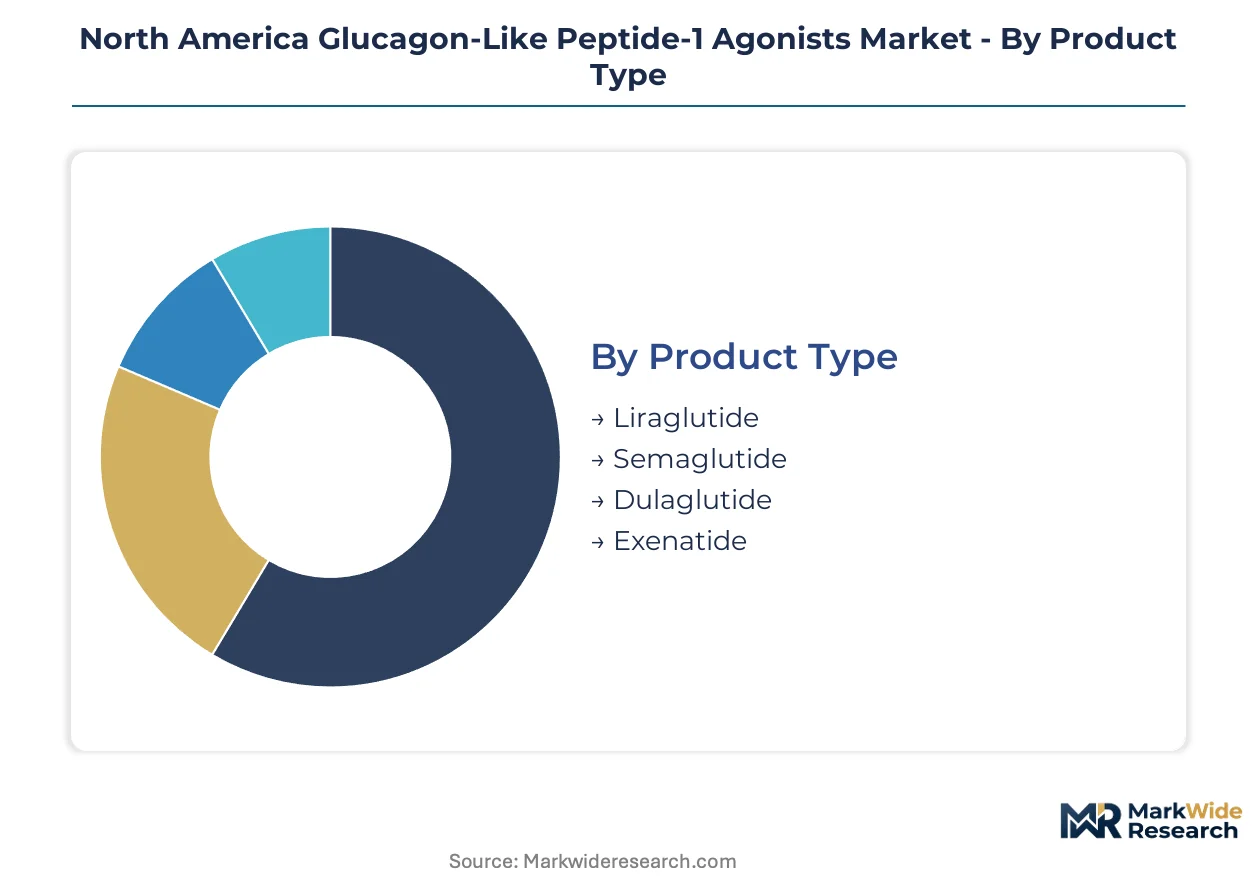
GLP-1 agonist markets fragment across molecular platforms, therapeutic targets, and administration convenience. Each dimension carries distinct reimbursement economics and patient adherence profiles that shape commercial strategy.
Product Type:
Upgrade cycles accelerate as longer-acting analogs displace earlier-generation peptides from formularies.
- Semaglutide:Engineered with a C-18 fatty diacid side chain and albumin-binding properties extending half-life to 165 hours. Demand concentrates in Medicare Advantage plans across Florida and Texas where obesity coverage expansion drives prior authorization volumes.
- Liraglutide:Acylated GLP-1 analog with once-daily dosing via 31-amino acid backbone modified at lysine-26. Volume placements remain strongest in employer-sponsored health plans with established diabetes management contracts in the Midwest.
- Dulaglutide:Fc-fusion construct with two GLP-1 analog peptides linked to human IgG4 heavy chain for weekly administration.
- Exenatide:Synthetic exendin-4 peptide requiring twice-daily or extended-release weekly formulations from microsphere encapsulation.
Volume placements concentrate in Semaglutide; the faster expansion belongs to Dulaglutide as Fc-fusion manufacturing scales.
Indication:
Cost tier stratification separates diabetes reimbursement from emerging metabolic indications with evolving coverage determination.
- Type 2 Diabetes:Established glycemic control indication with standardized HbA1c endpoints and mature prior authorization pathways across commercial and government payers.
- Obesity:Body mass index threshold-driven prescribing with CMS national coverage determinations unlocking Medicare Advantage reimbursement in select states. Steepest expansion trajectory as employer plans integrate weight management into benefit design.
- Cardiovascular Risk Reduction:MACE outcome labeling from FDA's Endocrinologic and Metabolic Drugs Advisory Committee enabling outcomes-based contracts with regional health plans.
- Non-alcoholic Fatty Liver Disease:Emerging indication with fibrosis staging requirements and evolving biomarker surrogates for regulatory approval.
Prescription volumes cluster in Type 2 Diabetes; reimbursement innovation is concentrating in Cardiovascular Risk Reduction.
Delivery Mode:
Patient-type differentiation separates injection-capable populations from needle-averse segments requiring oral alternatives.
- Subcutaneous Injection:Traditional vial-and-syringe administration with cold chain requirements and pharmacy benefit manager rebate structures tied to volume commitments.
- Pen Injector:Pre-filled, multi-dose devices with dose-titration features capturing home care segments and reducing clinic nursing burden.
- Oral Tablet:Semaglutide absorption enhanced with sodium N-[8-(2-hydroxybenzoyl)amino]caprylate enabling gastric permeability. Fastest-growing share as employer plans expand coverage for non-diabetic obesity.
- Continuous Infusion:Investigational pump-based delivery for hospitalized patients with acute metabolic decompensation.
Device preference concentrates in Pen Injector; oral alternatives are climbing fastest as Medicaid programs pilot obesity coverage.
End User:
Supply concentration varies across institutional procurement channels versus direct-to-patient distribution models.
- Hospitals:Inpatient formulary placement driven by pharmacy and therapeutics committees with emphasis on glycemic emergency protocols and perioperative management.
- Clinics:Endocrinology and bariatric specialty practices with prior authorization support staff managing step-therapy requirements from commercial payers.
- Home Care:Mail-order pharmacy distribution with temperature-controlled logistics networks expanding across the Southeastern United States.
- Research Institutions:Academic medical centers conducting cardiovascular outcomes trials under FDA-mandated post-approval commitments.
Script volume concentrates in Home Care; site-of-care expansion is gaining share fastest in Clinics as retail health networks scale metabolic services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Prescription volumes concentrate in the United States, where Medicare Advantage penetration and employer-sponsored coverage create the densest reimbursement infrastructure for metabolic therapies. Canada and Mexico present contrasting access models shaped by single-payer negotiations and emerging private insurance frameworks respectively.
United States
Medicare national coverage determinations for obesity indications are unlocking prior authorization volumes in Florida and Texas Medicare Advantage plans. The FDA's Endocrinologic and Metabolic Drugs Advisory Committee shapes cardiovascular outcomes trial requirements that determine label expansion pathways. The Research Triangle Park corridor in North Carolina anchors clinical trial operations for post-market surveillance commitments.
Canada
Provincial formulary negotiations in Ontario and Quebec create staggered access timelines that lag FDA approvals by 12-24 months. Health Canada coordinates with the FDA through the Orbis Project to align metabolic drug reviews while maintaining separate manufacturing inspection protocols. The Montreal-Toronto corridor concentrates biologics manufacturing investment from multinational sponsors seeking North American supply diversification.
Mexico
Private insurance expansion in Mexico City and Monterrey is creating out-of-pocket demand for branded GLP-1 therapies ahead of public sector inclusion. COFEPRIS regulatory pathways for biologics are converging toward FDA reference standards to accelerate market entry timelines. The Querétaro pharmaceutical cluster is attracting fill-finish investment from sponsors seeking proximity to US distribution networks.
North America Glucagon-Like Peptide-1 Agonists Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbents extend molecular platforms across metabolic indications. The vendor base concentrates around three integrated pharmaceutical conglomerates with established biologics manufacturing footprints, supplemented by mid-scale specialists pursuing partnership-dependent market entry. Strategic archetypes separate vertically integrated peptide manufacturers from Fc-fusion platform licensees and oral formulation specialists. Capacity expansion in Danish-North American corridors and cardiovascular outcomes trial commitments represent the dominant competitive moves reshaping positioning.
Within the integrated pharmaceutical tier, Novo Nordisk and Eli Lilly and Company exemplify divergent platform strategies that anchor competitive dynamics. Novo Nordisk occupies a position centered on yeast-based expression systems and albumin-binding peptide engineering, while Eli Lilly and Company represents the dual and triple incretin convergence archetype through GIP co-agonist development. Sanofi sits within the Fc-fusion manufacturing specialist category with established weekly dosing platforms.
| Leading Market Players |
|---|
| Novo Nordisk |
| Eli Lilly and Company |
| Sanofi |
| AstraZeneca |
| Pfizer |
| Boehringer Ingelheim |
| Amgen |
| Merck and Co. |
| GlaxoSmithKline |
| Others |
Value Network & Pricing Analysis
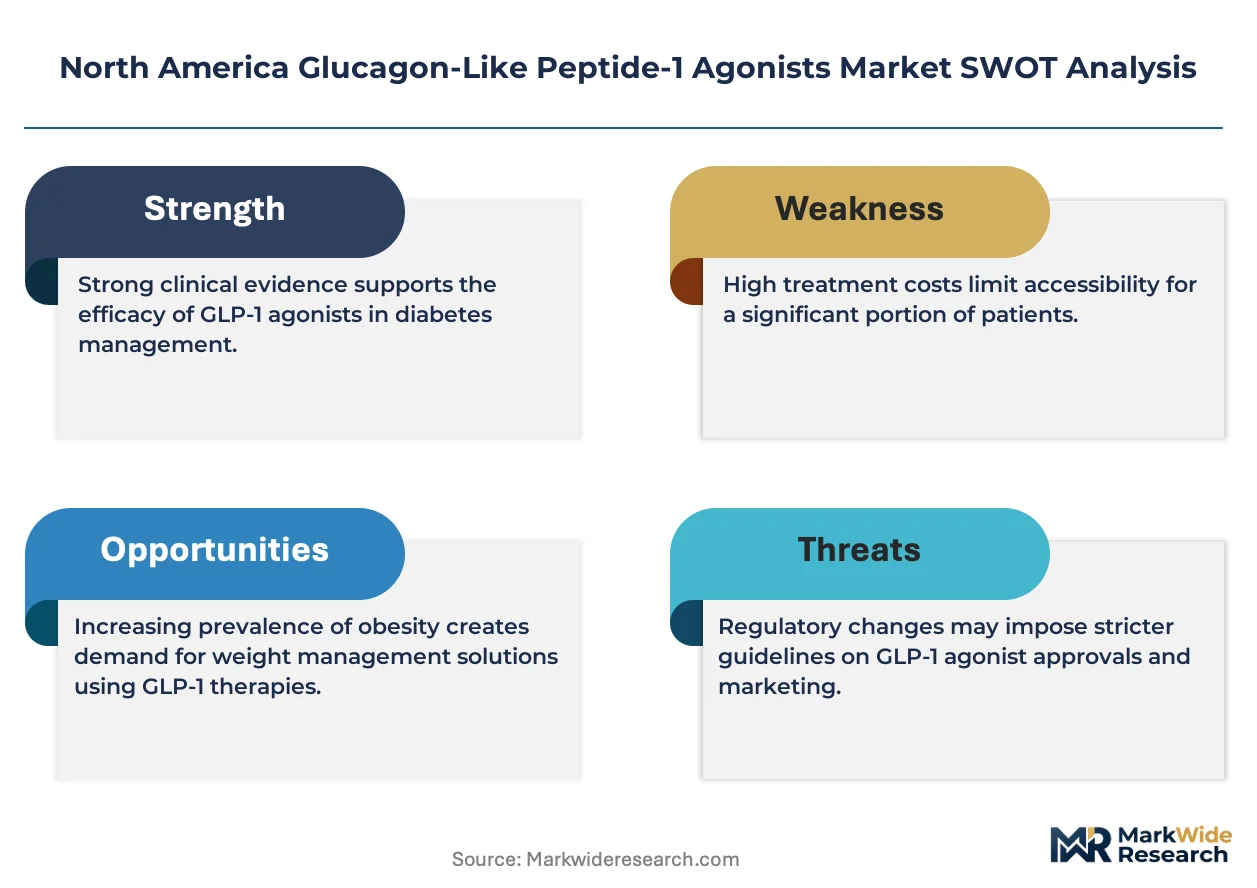
Albumin-binding peptide engineering separates premium-tier therapeutics from earlier-generation analogs, with this molecular sophistication commanding differential reimbursement from Medicare Advantage plans and self-insured employers while simultaneously demanding specialized fermentation infrastructure concentrated in Denmark and the Research Triangle Park corridor. The interplay between glycosylation fidelity requirements and cold chain logistics costs creates pricing power for vertically integrated manufacturers with captive yeast-based expression platforms.
Pricing Analysis
Volume placements cluster in high-dose pen injector formats where manufacturing scale compresses per-unit costs, while oral tablet formulations capture margin premiums from needle-averse patient segments despite lower bioavailability. Price differentiation hinges on cardiovascular outcomes labeling from FDA's Endocrinologic and Metabolic Drugs Advisory Committee and albumin-binding half-life extension technology. Cost compression in employer-sponsored plan negotiations is intensifying as pharmacy benefit managers unbundle traditional rebate structures from outcomes guarantees. Medicaid programs demonstrate highest price sensitivity due to state-level coverage fragmentation, while Medicare Advantage plans show lowest sensitivity where obesity indication coverage unlocks prior authorization volumes.
Supply Chain Analysis
FDA and Health Canada manufacturing inspections create dual qualification requirements that gate active pharmaceutical ingredient sourcing from Denmark and the United States. Fermentation-grade amino acids and specialized chromatography resins draw from concentrated Asian suppliers, creating input cost volatility. Single-region manufacturing concentration in Danish-North American corridors presents geopolitical supply risk from trade policy shifts. Distribution runs through temperature-controlled logistics networks expanding across the Southeastern United States, with mail-order pharmacy channels capturing growing home care script volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America GLP-1 agonist market sits in a technology-transition phase as yeast-based expression platforms displace legacy E. coli systems, compressing cost structures while raising glycosylation fidelity barriers for new entrants.
For Market Incumbents: Anchor supply security through backward integration into fermentation-grade amino acid sourcing and expansion of Danish-North American manufacturing corridors. Prioritize cardiovascular outcomes trial commitments to secure MACE-reduction labeling from FDA's Endocrinologic and Metabolic Drugs Advisory Committee, defending against dual incretin convergence threats from GIP co-agonist competitors. For New Entrants and Emerging Players: Enter via Canadian provincial formulary negotiations where Health Canada-FDA Orbis Project alignment accelerates review timelines relative to staggered United States access. Target employer-sponsored health plans in the Midwest with oral tablet formulations, leveraging non-injectable delivery modes as the most penetrable wedge against established pen injector dominance. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of contract development and manufacturing organizations with Pichia pastoris platform expertise and FDA-inspected facilities. Five-to-ten year viability hinges on cardiovascular risk reduction label expansion and outcomes-based contract penetration; monitor CMS national coverage determination timelines for obesity indications as the primary inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Yeast-Based Manufacturing Scale-Up | Pichia pastoris adoption cuts recombinant peptide production costs while improving glycosylation fidelity for albumin-binding analogs. |
| Cardiovascular Outcomes Trial Advancement | MACE reduction data from FDA-mandated studies unlocks outcomes-based contracts with Medicare Advantage plans and regional health systems. |
| Oral Formulation Development | Sodium N-[8-(2-hydroxybenzoyl)amino]caprylate absorption enhancers expand addressable populations beyond injection-capable diabetes patients. |
| Canadian Regulatory Alignment | Health Canada Orbis Project participation accelerates market entry timelines relative to standalone FDA review pathways. |
| Cold Chain Distribution Expansion | Temperature-controlled logistics networks in the Southeastern United States match prescription volume growth in employer-sponsored obesity programs. |
Research Methodology
FDA filings, CMS national coverage determination documents, and ClinicalTrials.gov records formed the secondary backbone, cross-referenced with primary interviews involving drug development executives at integrated pharmaceutical conglomerates, regulatory affairs leads navigating Health Canada-FDA coordination, formulary directors at large self-insured employers, and pharmacy benefit manager rebate negotiators. Bottom-up prescription volume modeling and top-down reimbursement infrastructure analysis provided triangulation across data sources.
Historical trendline analysis of semaglutide, liraglutide, dulaglutide, and exenatide prescription volumes established baseline growth patterns across the projection horizon. The analytical framework segmented by molecular platform, therapeutic indication, delivery mode, and end-user channel, with CAGRs derived from fitted growth curves adjusted for Medicare coverage expansion trajectories and employer plan benefit design shifts. Forecast inputs incorporated yeast-based manufacturing adoption curves and cardiovascular outcomes trial completion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under FDA advisory committee composition changes or state-level Medicaid coverage reversals for obesity indications. Model assumptions reflect documented reimbursement pathways and manufacturing capacity expansion plans. A model refresh is warranted upon material change in CMS national coverage determination scope or Health Canada manufacturing inspection protocol harmonization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceuticals
Omeprazole Market
Pharmaceuticals
Respiratory Virus Infection Drug Market
Pharmaceuticals
Beta Blockers Market
Pharmaceuticals
Glycerol Fructose and Sodium Chloride Injection Market
Pharmaceuticals
Global Lidocaine Transdermal Patch Market
Pharmaceuticals
Loxoprofen Market
Pharmaceuticals
Urban Pharma Micro-Depot and Delivery Network Market
Pharmaceuticals
Alprazolam Powder Market
Pharmaceuticals
Global Nasal Drug Delivery Market
Pharmaceuticals
Computer-Aided Drug Discovery Market
Pharmaceuticals
Anticonvulsants Market
Pharmaceuticals
Intravenous (IV) Iron Drugs Market
Pharmaceuticals
Europe Dipeptide Peptidase 4 (DPP-4) Inhibitors Market
Pharmaceuticals
Asia-Pacific Alpha-Glucosidase Inhibitors Market
Pharmaceuticals
Global Vero Cell Rabies Vaccine Market
Pharmaceuticals
North America Novel Drug Delivery Systems (NDDS) Market