
 US Radiation Oncology Market | 2026-2036
US Radiation Oncology Market Size, Share, and Industry Trends Forecast 2026-2036
US Radiation Oncology Market Intelligence
Texas is reconfiguring its radiation oncology infrastructure through major proton therapy center investments in the Houston and Dallas medical corridors. Varian Medical Systems anchors the linear accelerator segment through extensive service networks and training ecosystems. Elekta AB competes in stereotactic platforms with integrated workflow software that reduces treatment planning time. Mevion Medical Systems specializes in compact proton systems that lower the capital footprint for mid-sized cancer centers.
Radiation oncology encompasses the clinical discipline and technical systems that deploy ionizing radiation to destroy malignant cells while sparing healthy tissue, utilizing megavoltage photon beams, proton particle streams, or sealed radioactive sources delivered with sub-millimeter geometric accuracy. The primary purpose is curative and palliative tumor control across solid malignancies including prostate, lung, breast, and central nervous system cancers. External beam radiation therapy dominates installed base value due to reimbursement familiarity and linear accelerator ubiquity, while proton therapy captures the fastest expansion trajectory despite capital intensity. Hospitals retain the largest end-user share, though cancer treatment centers are gaining procedure volume through focused disease-site specialization and faster patient throughput.
FDA clearance pathways under 21 CFR 892 govern radiation therapy device safety and effectiveness, while CMS reimbursement determinations directly shape provider investment cycles and technology adoption speed. State-level certificate-of-need regulations in approximately three dozen jurisdictions constrain equipment duplication and influence competitive geography. OSHA and NRC standards govern technician exposure limits and radioactive materials handling, adding compliance layers to operational economics. Stakeholders must monitor whether Medicare radiation oncology alternative payment models accelerate site-of-care shifts toward outpatient cancer treatment centers.
Market Dynamics
FDA's software-as-a-medical-device framework is compressing clearance timelines for AI-enabled treatment planning systems, forcing vendors to restructure regulatory submissions around continuous learning algorithms rather than static hardware validations.
Growth Catalysts
- Radiation Oncology Alternative Payment Model:CMS bundled reimbursement structures incentivize hospital outpatient departments to consolidate fractionated therapy volumes, accelerating capital deployment toward integrated linear accelerator networks.
- Proton beam therapy:Compact single-room systems reduce facility footprint requirements, enabling mid-sized cancer centers in Texas and Florida to enter particle therapy without billion-dollar campus investments.
- Artificial intelligence:Auto-contouring algorithms slash treatment planning time from hours to minutes, allowing physicists to scale case throughput without proportional staffing expansion.
Market Restraints
- Certificate-of-need regulations:Thirty-six US states restrict linear accelerator duplication through CON programs, creating artificial scarcity in metropolitan corridors and entrenching incumbent provider market positions.
- Helium supply concentration:Superconducting magnet cooling depends on helium sourced from Qatar and Russia, exposing proton therapy centers to price volatility and potential supply interruption.
- Technical limitation:Motion management for lung and abdominal tumors remains imperfect, limiting stereotactic ablative radiotherapy penetration in thoracic oncology despite curative potential.
Strategic Opportunities
- Rural cancer center penetration:Telemedicine-integrated radiation oncology hubs in Montana, Idaho, and Alaska remain underserved, presenting acquisition targets for metropolitan health systems seeking volume growth.
- Theranostic convergence:Lutetium-177 radioligand therapy paired with diagnostic gallium-68 imaging creates unified nuclear medicine-radiation oncology service lines requiring cyclotron infrastructure.
- IRA Medicare drug pricing provisions:Reduced pharmaceutical reimbursement uncertainty stabilizes hospital capital allocation, indirectly freeing budget for radiation therapy equipment refresh cycles.
Industry Challenges
- Medical physicist shortage:ABR certification pathways produce fewer than two hundred board-qualified physicists annually, creating recruitment bottlenecks for new center startups in competitive labor markets.
- Legacy RIS-PACS integration:Vendor-neutral archive migration for decades of DICOM-RT treatment records delays AI deployment as institutions reconcile incompatible data schemas.
- Cyclotron licensing complexity:NRC materials license amendments for isotope production require eighteen-to-twenty-four month review cycles, extending theranostic service line launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Radiation Oncology Market |
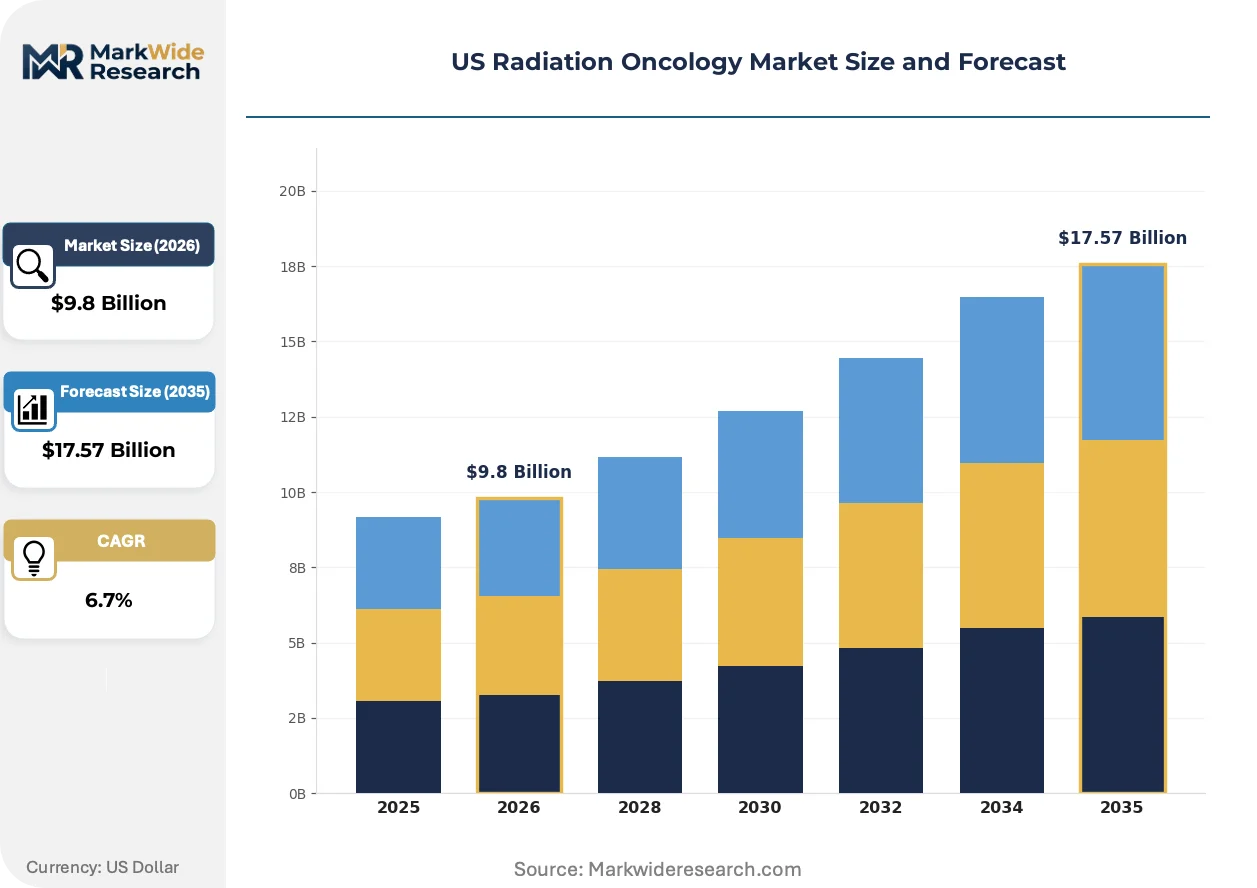
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: External Beam Radiation Therapy, Brachytherapy, Proton Therapy, Stereotactic Radiosurgery End User: Hospitals, Cancer Treatment Centers, Research Institutions, Specialty Clinics Delivery Mode: Teletherapy, Intracavitary, Interstitial, Placement Technology: Graphite-Carbon, Linear Accelerators, CyberKnife, Tomotherapy |
| Companies Covered | Siemens Healthineers, Elekta AB, Accuray Incorporated, Varian Medical Systems, Ion Beam Applications SA, Mevion Medical Systems, ViewRay Technologies, Becton Dickinson and Co, Provision Healthcare, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Radiation Oncology Market Strategic Shifts & Innovations
Adaptive radiation therapy workflows are compressing the gap between simulation and treatment delivery, replacing static planning with fractional re-optimization based on daily anatomy changes. This shift demands real-time computational infrastructure and redefined clinical staffing models.
Magnetic resonance-guided linear accelerator technology is migrating from academic flagship institutions to community hospital networks as vendor service contracts reduce the specialized physics burden. Community cancer centers in Arizona and North Carolina are piloting MR-linac programs for prostate and gynecologic malignancies. The technology is migrating from high-complexity tertiary care toward standard-of-care deployment, compressing the historical decade-long adoption lag between research and community practice.
FDA's evolving 21 CFR 892 enforcement discretion for machine learning-based contouring tools is creating parallel clearance pathways for locked versus continuously learning algorithms. Device manufacturers must now submit predetermined change control plans describing anticipated algorithm modifications. Linear accelerator vendors with integrated software stacks face heightened documentation burdens compared to standalone AI contouring startups.
Hospital procurement committees are unbundling equipment purchase from long-term service agreements, negotiating separate competitive bids for hardware, software licenses, and maintenance coverage. This disintermediation pressures vendor margin structures while empowering in-house biomedical engineering teams. The pattern is most visible in California and Massachusetts health systems with established clinical engineering depth.
US Radiation Oncology Market Segmentation
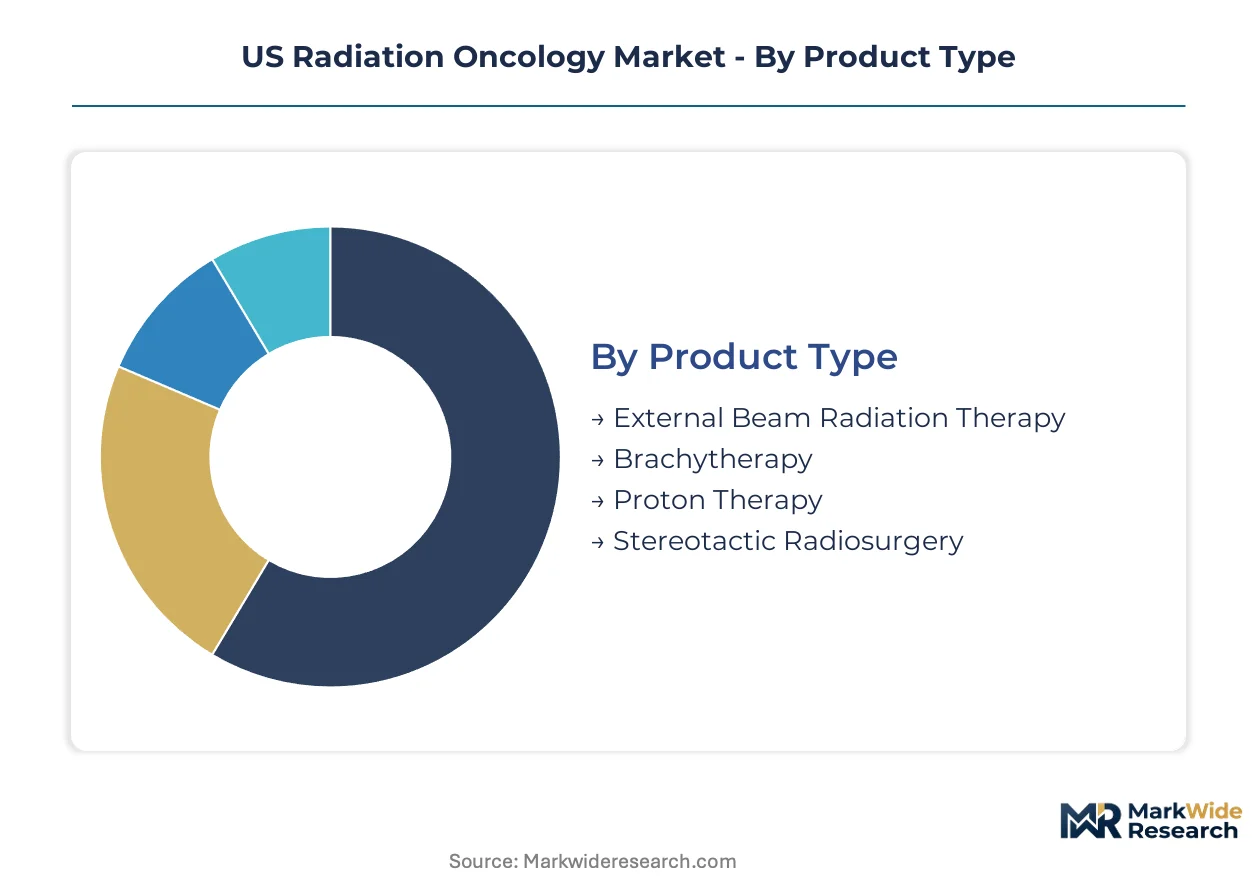
US radiation oncology segmentation reveals how clinical workflow complexity and capital intensity shape purchasing decisions across provider types. Product and technology categories reflect distinct reimbursement profiles and physics staffing requirements that determine market penetration patterns.
Product Type:
Clinical use-cases span curative intent through palliative care, with modality selection driven by tumor location, fractionation requirements, and facility infrastructure.
- External Beam Radiation Therapy:Megavoltage photon delivery systems utilizing cobalt-60 or linear accelerator sources dominate installed base value. Texas hospital networks anchor demand through high-volume prostate and lung protocols, constrained by certificate-of-need regulations in thirty-six states.
- Proton Therapy:Charged particle beams exploit the Bragg peak effect to spare distal tissue, requiring cyclotron or synchrotron infrastructure. Houston and Dallas medical corridors concentrate new investments as compact single-room systems reduce billion-dollar campus requirements.
- Brachytherapy:Sealed radioactive source placement enables dose escalation for cervical, prostate, and ocular malignancies.
- Stereotactic Radiosurgery:Sub-millimeter precision ablation targets intracranial and extracranial lesions with hypofractionated regimens.
The dominant share belongs to External Beam Radiation Therapy, while Proton Therapy is closing the gap fastest.
End User:
Procurement authority concentrates in capital-allocation committees with distinct reimbursement exposure and patient throughput priorities.
- Hospitals:Integrated health systems command the largest installed base through bundled payment acceptance and residency training programs. California and Massachusetts networks are unbundling equipment purchase from service agreements to empower in-house biomedical engineering teams.
- Cancer Treatment Centers:Disease-site specialization drives faster patient throughput and focused disease protocols. Florida outpatient facilities gain procedure volume through radiation oncology alternative payment model participation.
- Specialty Clinics:Urology and neurosurgery-integrated practices target specific anatomical sites.
- Research Institutions:Academic medical centers pilot adaptive radiation therapy workflows and MR-linac integration.
Hospitals retain procurement dominance, though Cancer Treatment Centers are expanding share most rapidly.
Delivery Mode:
Physical source placement and beam geometry determine shielding requirements and clinical staffing models.
- Teletherapy:External beam delivery from distant radiation sources requires heavily shielded vault construction and NRC materials licensing. Montana, Idaho, and Alaska hubs remain underserved, presenting acquisition targets for metropolitan health systems.
- Interstitial:Direct source insertion into tumor parenchyma demands surgical collaboration and real-time imaging guidance.
- Intracavitary:Source placement within body cavities enables gynecologic and esophageal dose escalation.
- Placement:Surface mold or plaque applications target ocular and cutaneous malignancies.
Teletherapy commands the largest procedure volume, while Interstitial methods are gaining traction in combined-modality protocols.
Technology:
Hardware specifications differentiate throughput capacity, beam modulation complexity, and integration with treatment planning software.
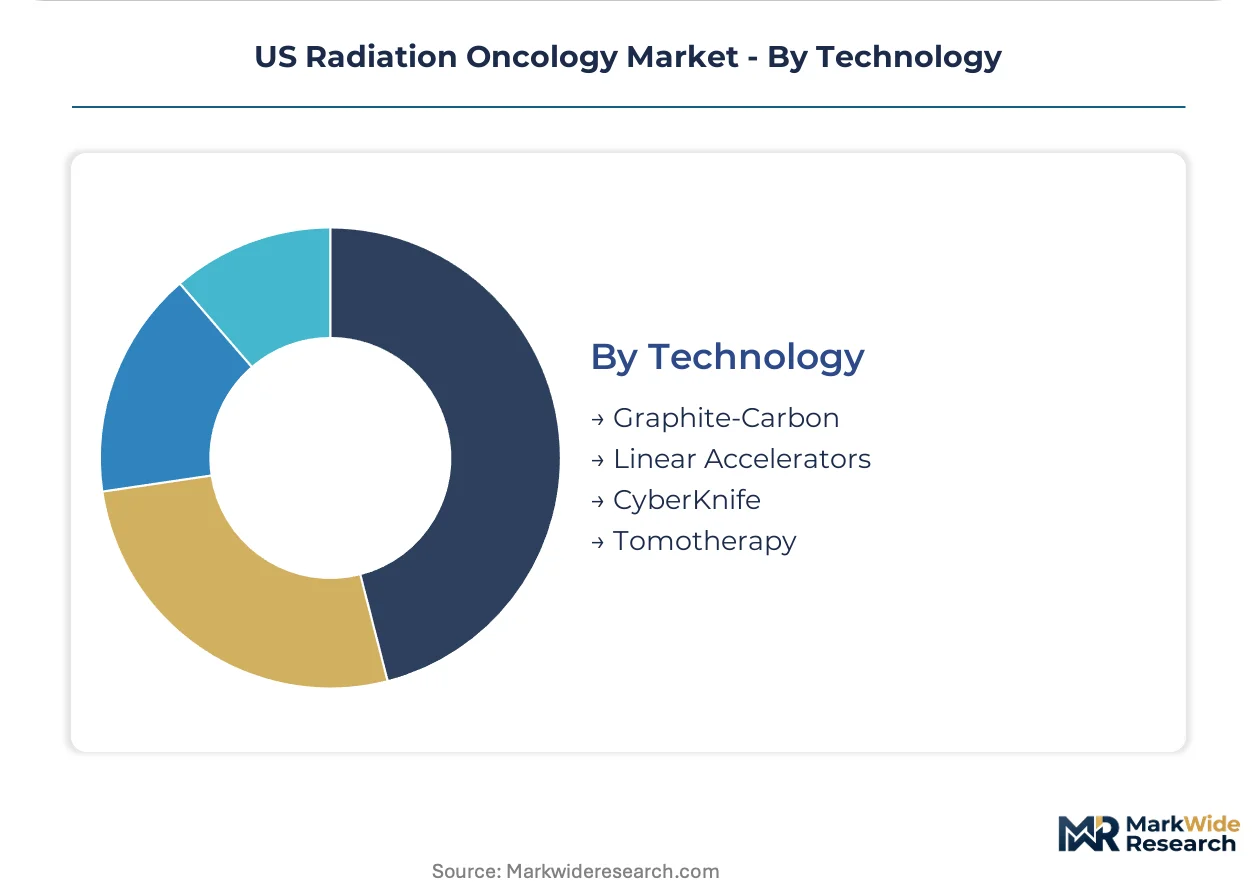
- Linear Accelerators:Megavoltage X-ray generation through microwave-accelerated electrons forms the backbone of external beam infrastructure. Varian Medical Systems anchors the segment through extensive service networks and training ecosystems across Texas and Florida.
- CyberKnife:Robotic arm-mounted linac enables non-isocentric beam delivery with real-time tumor tracking. Arizona and North Carolina community centers pilot programs for prostate and gynecologic applications.
- Tomotherapy:Helical delivery geometry combines CT imaging with fan-beam modulation for complex target shapes.
- Graphite-Carbon:Beam flattening filter and collimator materials optimize dosimetric characteristics.
Linear Accelerators hold the dominant installed position, while CyberKnife is expanding fastest into community hospital networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Equipment vendors concentrate service infrastructure and training ecosystems in states with certificate-of-need flexibility and high Medicare procedure density. Texas, California, and Florida anchor installed base value through distinct reimbursement and regulatory configurations.
Texas
Houston and Dallas medical corridors drive proton therapy capital deployment through compact single-room systems that reduce billion-dollar campus requirements. Texas maintains no certificate-of-need restrictions on linear accelerator placement, enabling faster market entry for cancer treatment centers. The Texas Medical Center anchors the nation's largest concentration of particle therapy research capacity.
California
Hospital procurement committees in Los Angeles and San Francisco Bay Area networks unbundle equipment purchase from long-term service agreements, negotiating separate competitive bids for hardware and maintenance coverage. California's Office of Statewide Health Planning and Development enforces CON regulations that constrain equipment duplication in metropolitan corridors. Stanford and UCSF academic medical centers pilot MR-linac integration for prostate and gynecologic applications.
Florida
Outpatient cancer treatment centers in Miami, Tampa, and Orlando gain procedure volume through radiation oncology alternative payment model participation, consolidating fractionated therapy volumes. Florida's Agency for Health Care Administration administers CON programs that restrict linear accelerator placement in oversaturated counties. The Moffitt Cancer Center in Tampa anchors stereotactic platform adoption in the Southeast.
Arizona
Community hospital networks in Phoenix and Tucson pilot CyberKnife programs for prostate and gynecologic malignancies as vendor service contracts reduce specialized physics burdens. Arizona exempts linear accelerators from certificate-of-need review, attracting metropolitan health system expansion from neighboring states. Banner Health and Mayo Clinic Arizona anchor adaptive radiation therapy workflow development.
North Carolina
Research Triangle Park institutions and Duke University Medical Center drive MR-linac migration from academic flagship to community deployment. North Carolina's State Health Coordinating Council reviews major medical equipment applications through CON processes that vary by county population density. Atrium Health and Wake Forest Baptist Health anchor linear accelerator network consolidation across the Piedmont region.
US Radiation Oncology Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in beam generation and detection subsystems. The vendor structure concentrates around three to five full-stack radiation therapy system providers with extensive service networks and training ecosystems. Two strategic archetypes dominate: diversified medical technology conglomerates with cross-modal imaging integration and pure-play radiation oncology specialists with focused disease-site protocols. Competitive moves center on unbundling hardware-software-service contracts and acquiring AI-enabled treatment planning capabilities.
Among diversified medical technology conglomerates, Siemens Healthineers and Becton Dickinson occupy positions spanning imaging, therapy, and interventional systems. Varian Medical Systems and Elekta AB exemplify pure-play radiation oncology specialists with anchored linear accelerator and stereotactic platform portfolios. Accuray Incorporated sits within the robotic delivery segment with non-isocentric beam architectures. These five entities represent the competitive core, with Ion Beam Applications, Mevion Medical Systems, ViewRay Technologies, and Provision Healthcare occupying specialized niches in particle therapy and MR-guided systems.
| Leading Market Players |
|---|
| Siemens Healthineers |
| Elekta AB |
| Accuray Incorporated |
| Varian Medical Systems |
| Ion Beam Applications SA |
| Mevion Medical Systems |
| ViewRay Technologies |
| Becton Dickinson and Co |
| Provision Healthcare |
| Others |
Cost & Logistics Intelligence
The I-10 freight corridor connecting Houston proton therapy component manufacturers to California hospital networks transmits cost volatility from helium supply disruptions directly into capital equipment pricing tiers, while Texas certificate-of-need exemptions concentrate purchasing power among metropolitan health systems capable of extracting unbundled service contract concessions.
Pricing Analysis
CMS radiation oncology alternative payment model dictates the pricing tier structure across bundled reimbursement categories, separating academic medical center premium rates from community hospital standard tiers and cancer treatment center economy positioning. Price differentiation rests on physicist staffing ratios and adaptive therapy workflow capability, with hospital networks in California and Massachusetts least sensitive due to consolidated GPO leverage while independent Florida outpatient centers face acute margin compression from capital intensity.
Supply Chain Analysis
Tariff exposure between Qatar and the United States dominates supply chain risk planning for superconducting magnet cooling systems, with helium sourcing concentrated in Russia and Algeria as secondary feedstocks. Beam generation subsystems draw from German precision manufacturing, Japanese sensor arrays, and domestic linear accelerator fabrication in California and Texas. Distribution runs through Varian and Elekta direct service organizations rather than independent distributors, locking spare parts availability to vendor-controlled logistics networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital network consolidation across Texas and Florida, with metropolitan health systems extracting unbundled hardware-software-service contracts that compress vendor margins and reshape procurement committee authority structures.
For Market Incumbents: Harden service network density in CON-restricted states to defend against compact proton system entrants targeting mid-sized cancer centers. Lock in multi-year physics staffing contracts to neutralize the ABR certification bottleneck threat. Prioritize FDA predetermined change control plans for AI contouring modules to accelerate clearance timelines against standalone software competitors. For New Entrants and Emerging Players: Establish a beachhead in Montana, Idaho, and Alaska telemedicine-integrated radiation oncology hubs where metropolitan health system acquisition appetite runs strongest. Target CyberKnife community deployment in Arizona and North Carolina as vendor service contracts reduce specialized physics burdens. Lead with MR-linac pilot programs for prostate protocols to bypass incumbent linear accelerator installed base advantages. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified medical technology conglomerates seeking to divest non-core radiation oncology assets amid reimbursement uncertainty. Long-term viability hinges on adaptive therapy workflow integration and AI-enabled treatment planning capabilities. Watch FDA enforcement discretion patterns for continuously learning algorithms as the inflection signal for software valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission for AI Contouring | Predetermined change control plans under 21 CFR 892 reshape clearance economics for linear accelerator vendors. |
| Hospital System Partnership | GPO contract consolidation in California and Massachusetts demands unbundled procurement negotiations. |
| Software Companion Development | Auto-contouring algorithms reduce treatment planning time from hours to minutes for physicist throughput scaling. |
| Reimbursement Strategy | CMS alternative payment model participation determines outpatient cancer center procedure volume capture. |
| Geographic Expansion | CON-exempt states like Texas and Arizona enable faster linear accelerator network buildout than restricted markets. |
Research Approach
A spread of perspectives from radiation oncology physicists, hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and CMS policy analysts converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation against FDA 510(k) filings, CMS Medicare cost report data, hospital procurement databases, and state certificate-of-need records. Bottom-up equipment shipment tracking and top-down reimbursement flow analysis triangulated market sizing across the projection horizon.
Demand-supply balance modeling anchored the forecast framework, with segmentation across product type, end user, delivery mode, and technology dimensions. The analytical framework incorporated proton therapy capacity buildout timelines, linear accelerator replacement cycles, and physicist workforce production constraints. CAGRs were derived from procedure volume growth trajectories and capital expenditure patterns across the modeling period.
Sensitivities concentrate around helium supply disruption scenarios, FDA algorithm enforcement discretion shifts, and Medicare bundled payment expansion decisions. Forecasts reflect documented assumptions on CON regulation stability and ABR certification throughput. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Global Cancer Profiling Market
Oncology
Asia-Pacific Cancer Therapy Market
Oncology
Europe Tumor Ablation Market
Oncology
Asia-Pacific Cancer Biomarkers Market
Oncology
AI in Oncology Market
Oncology
PD1 Non-Small Cell Lung Cancer Treatment Market
Oncology
Radiation Oncology Market
Oncology
North America Proton Therapy Market
Oncology
Low-Grade Central Osteosarcoma Treatment Market
Oncology
Asia-Pacific Tumor Ablation Market
Oncology
Oncology Apoptosis Modulators Market
Oncology
Laser Cancer Therapy Market
Oncology
Colorectal Cancer Treatment Market
Oncology
South America Bladder Cancer Therapeutics and Diagnostics Market
Oncology
Tumor Ablation Market
Oncology
Europe Radiotherapy Patient Positioning Market