
 Asia-Pacific Nuclear Medicine Market | 2026-2036
Asia-Pacific Nuclear Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nuclear Medicine Market Outlook
Multi-source procurement of technetium-99m generators is consolidating into long-term supply agreements with domestic converters. GE HealthCare anchors reactor-to-patient logistics through its network of regional radiopharmacies. Siemens Healthineers leverages cyclotron-based positron emitter production to reduce import dependency for fluorine-18 tracers. China Isotope & Radiation Corp. dominates domestic molybdenum-99 processing, sustaining vertical control from irradiation to finished generator dispatch.
Asia-Pacific nuclear medicine encompasses the clinical use of unsealed radioactive sources for diagnosis and therapy, where radiopharmaceuticals such as technetium-99m exhibit half-lives calibrated to organ-specific imaging windows while alpha-emitters like radium-223 target bone metastases with precision dose deposition. Radiopharmaceuticals command the largest value pool due to recurring isotope decay necessitating continuous replenishment cycles, whereas oncology applications outpace cardiology and neurology in growth velocity driven by PSMA-targeted lutetium therapies for prostate cancer staging. Imaging centers represent a structurally expanding end-user channel as outpatient PET-CT capacity decentralizes from hospital campuses across Southeast Asian metropolitan clusters.
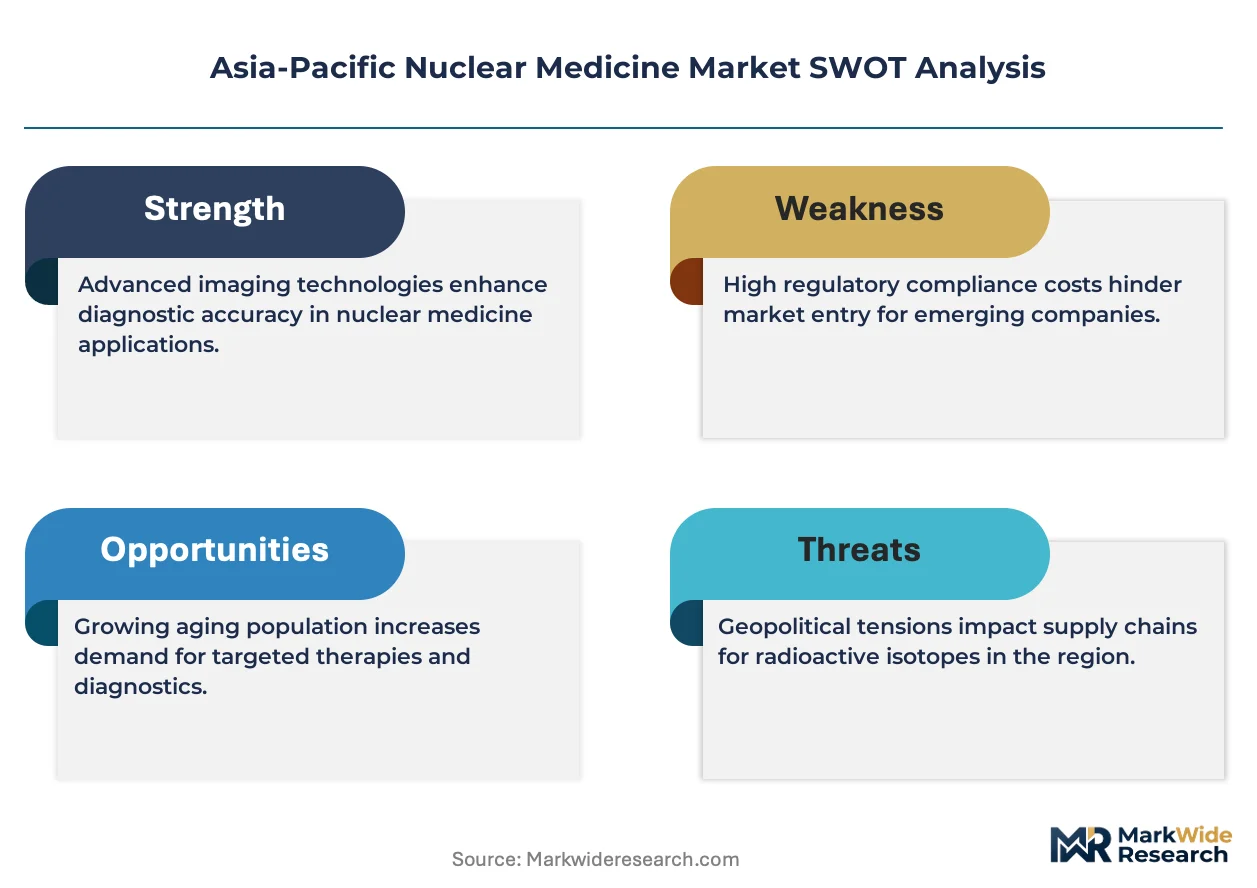
Japan's PMDA governs radioisotope manufacturing facility licensing while Australia's TGA enforces GMP standards for imported radiopharmaceuticals, with both frameworks elevating compliance costs for new market entrants. India's CDSCO and BIS jointly regulate diagnostic tracer quality, creating dual-certification requirements that shape domestic production incentives. Stakeholders must monitor cyclotron infrastructure buildouts against reactor decommissioning schedules to secure isotope supply continuity.
Market Dynamics
Reactor decommissioning schedules across Australia and South Korea are forcing radiopharmaceutical suppliers to accelerate cyclotron infrastructure buildouts, reshaping isotope sourcing economics for diagnostic tracers throughout the region.
Growth Catalysts
- PMDA Streamlined Approval Pathways:Japan's pharmaceutical regulator reduced radioisotope licensing timelines, accelerating domestic tracer availability for PET-CT diagnostics in tertiary oncology departments.
- Proton Therapy Center Expansion:China's eastern seaboard cities are commissioning gallium-68 and lutetium-177 supplies, creating concentrated demand hubs for therapeutic radiopharmaceuticals.
- Cyclotron-Based Production:Positron emitter manufacturing at hospital-based cyclotrons is reducing import dependency for fluorine-18 tracers across metropolitan Australian clusters.
Market Restraints
- Molybdenum-99 Supply Concentration:China Isotope & Radiation Corp.'s vertical control from irradiation to finished generator dispatch creates single-source vulnerability for technetium-99m availability.
- Dual-Certification Burden:India's CDSCO and BIS jointly regulate diagnostic tracer quality, elevating compliance costs and extending market entry timelines for foreign suppliers.
- Short Half-Life Logistics:Technetium-99m's six-hour decay window necessitates continuous replenishment cycles that compress distribution margins and limit geographic reach.
Strategic Opportunities
- Southeast Asian Outpatient Expansion:Imaging centers in Bangkok, Kuala Lumpur, and Jakarta are decentralizing PET-CT capacity from hospital campuses, creating new radiopharmacy service points.
- Alpha-Emitter Therapeutics:Radium-223 and lutetium-177 therapies for bone metastases represent underpenetrated therapeutic categories beyond diagnostic applications.
- Long-Term Supply Agreements:Multi-year contracts between tertiary hospitals and domestic converter facilities are replacing spot procurement, locking in volume commitments for reactor-derived isotopes.
Industry Challenges
- Radiochemist Talent Scarcity:Cyclotron operations and radiopharmaceutical synthesis require specialized nuclear pharmacy expertise that outpaces regional training program output.
- GMP Facility Capex Intensity:Radioisotope manufacturing cleanrooms and shielded production suites demand capital deployment that exceeds mid-scale hospital budget cycles.
- Import-Export Permit Complexity:Cross-border movement of radioactive materials requires TGA, PMDA, and CDSCO coordination that extends delivery timelines for time-sensitive tracers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nuclear Medicine Market |
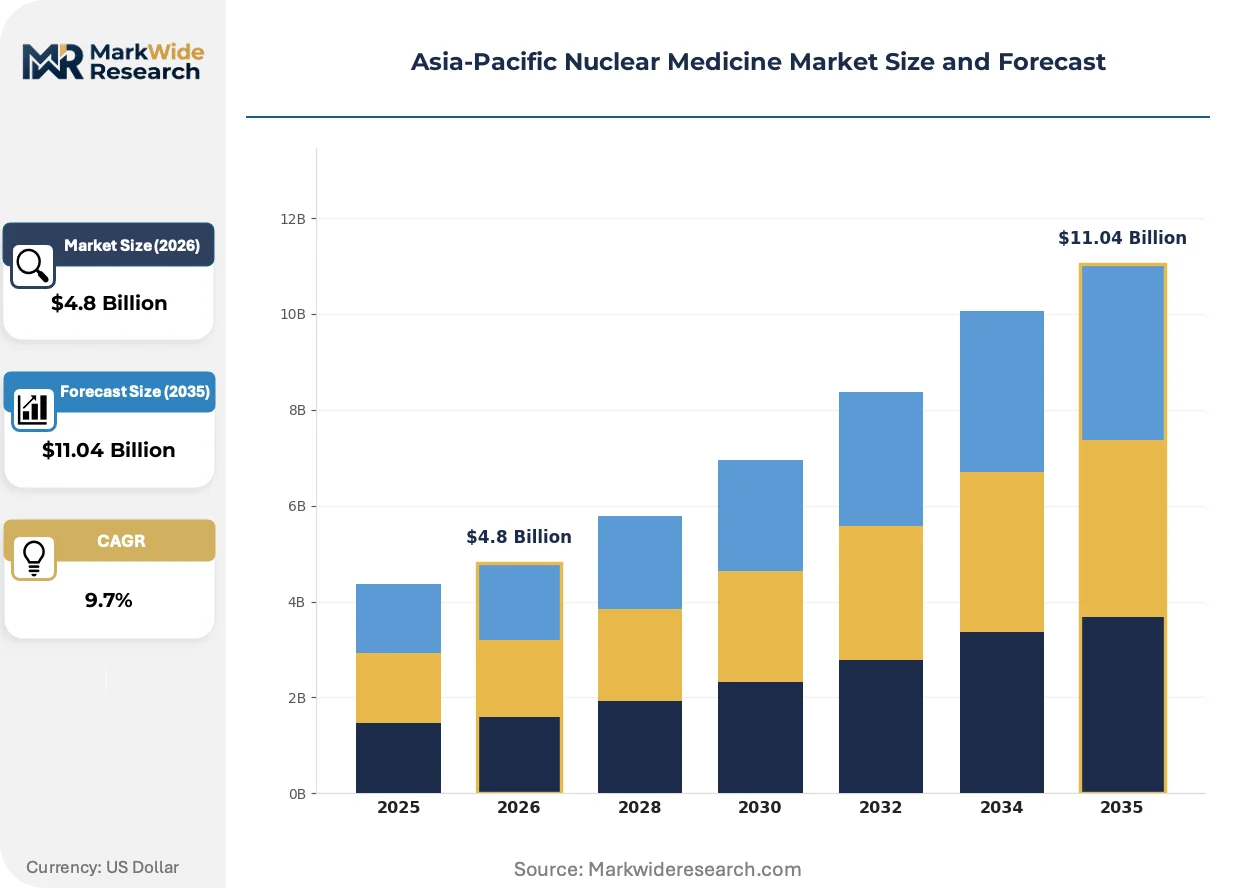
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radiopharmaceuticals, Imaging Agents, Instruments, Software End User: Hospitals, Diagnostic Laboratories, Research Institutes, Imaging Centers Application: Oncology, Cardiology, Neurology, Thyroid Disorders Delivery Mode: Intravascular, Oral, Intramuscular, Intranasal |
| Companies Covered | GE HealthCare, Curium, Cardinal Health, Siemens Healthineers, Lantheus Holdings, China Isotope & Radiation Corp., Telix Pharmaceuticals, Jubilant Pharmova, Bracco Imaging, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nuclear Medicine Market Strategic Shifts
Automation and decentralized production architectures are compressing the distance between isotope generation and patient administration, reducing cold-chain dependency for short-lived tracers.
Artificial intelligence-assisted dosimetry calculation software is automating personalized radiopharmaceutical dosing for lutetium-177 PSMA therapies. Oncology departments in Australian tertiary hospitals are deploying these platforms to reduce nuclear medicine physician calculation burden. The technology is automating treatment planning workflows that previously required manual absorbed-dose estimation, compressing patient throughput timelines.
Australia's TGA enforcement of GMP standards for imported radiopharmaceuticals is elevating quality documentation requirements for foreign suppliers. The regulation is disqualifying non-certified converters from hospital procurement shortlists. Japanese and South Korean manufacturers are responding by upgrading facility certifications to maintain Asia-Pacific market access.
Hospital radiopharmacies are consolidating generator procurement into direct converter relationships, bypassing traditional distributor intermediaries. Tertiary oncology centers in Japan and Australia now negotiate supply agreements directly with molybdenum-99 processing facilities. This channel restructuring is most visible in metropolitan clusters where proton therapy centers require guaranteed isotope availability for scheduled patient loads.
Asia-Pacific Nuclear Medicine Market Segmentation
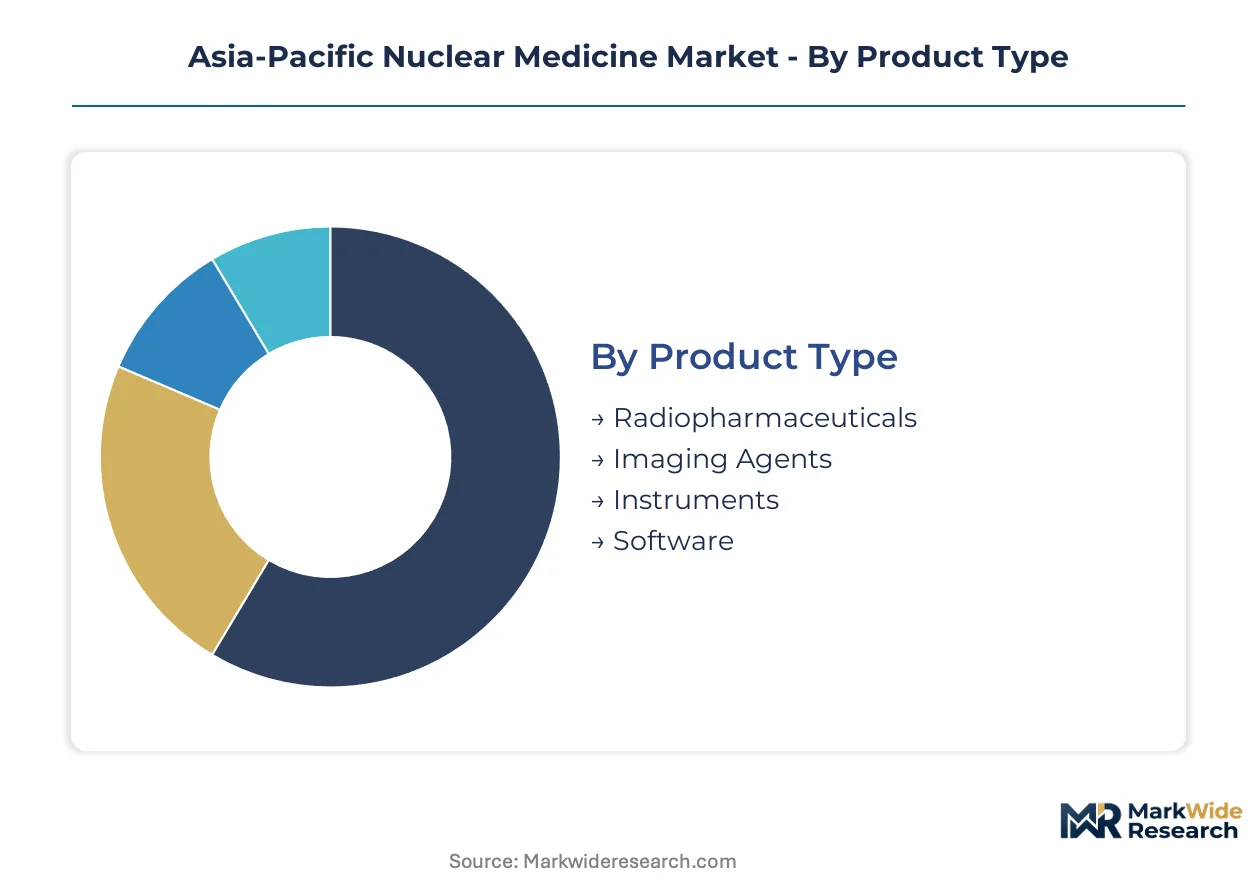
Radiopharmaceutical decay half-lives and regulatory compliance intensity create divergent procurement patterns across buyer categories. Segment-level analysis reveals where cyclotron infrastructure investments concentrate versus reactor-dependent supply chains.
Product Type:
Buyers differentiate by replenishment frequency and cold-chain dependency, with continuous decay driving recurring procurement versus capital-equipment acquisition cycles.
- Radiopharmaceuticals:Unsealed radioactive compounds including technetium-99m, gallium-68, and lutetium-177 require generator-based or cyclotron-produced replenishment. Demand concentrates in Japan's tertiary oncology departments where PMDA streamlining accelerates tracer availability for scheduled PET-CT diagnostics.
- Imaging Agents:Contrast-enhanced diagnostic compounds paired with nuclear imaging modalities. Procurement tilts toward China's eastern seaboard proton therapy centers commissioning gallium-68 supplies for PSMA-targeted prostate cancer staging.
- Instruments:Gamma cameras, PET-CT scanners, and SPECT systems represent capital-intensive infrastructure with decade-long depreciation schedules.
- Software:AI-assisted dosimetry platforms automating personalized radiopharmaceutical dosing calculations for lutetium-177 therapies.
Volume sits with radiopharmaceuticals; growth tilts toward software as Australian tertiary hospitals deploy automated treatment planning workflows.
End User:
Procurement scale and regulatory sophistication separate institutional buyers, with GMP certification requirements filtering market access.
- Hospitals:Tertiary oncology departments in Japan and Australia negotiate direct converter relationships for molybdenum-99 generator supply, bypassing distributor intermediaries to secure isotope availability for scheduled patient loads.
- Diagnostic Laboratories:High-throughput processing centers requiring continuous technetium-99m replenishment face margin compression from six-hour decay windows limiting geographic distribution reach.
- Research Institutes:Cyclotron-based positron emitter production facilities reducing import dependency for fluorine-18 tracers.
- Imaging Centers:Outpatient PET-CT capacity decentralizing from hospital campuses across Bangkok, Kuala Lumpur, and Jakarta metropolitan clusters.
Procurement volume concentrates in hospitals; expansion tilts most quickly toward imaging centers as Southeast Asian outpatient capacity decentralizes.
Application:
Clinical outcome economics and reimbursement pathways determine radiopharmaceutical investment prioritization across therapeutic areas.
- Oncology:PSMA-targeted lutetium-177 therapies for prostate cancer staging and radium-223 for bone metastases represent therapeutic categories extending beyond diagnostic applications into precision dose deposition.
- Cardiology:Myocardial perfusion imaging using technetium-99m sestamibi maintains stable demand from aging demographics across Australian metropolitan clusters.
- Neurology:Amyloid-beta PET tracers for Alzheimer's disease staging face reimbursement uncertainty limiting adoption velocity.
- Thyroid Disorders:Iodine-131 therapies for hyperthyroidism and differentiated thyroid carcinoma represent established radioisotope applications with predictable demand curves.
Revenue concentration rests with oncology; steepest expansion trajectory emerges in neurology as diagnostic criteria evolve.
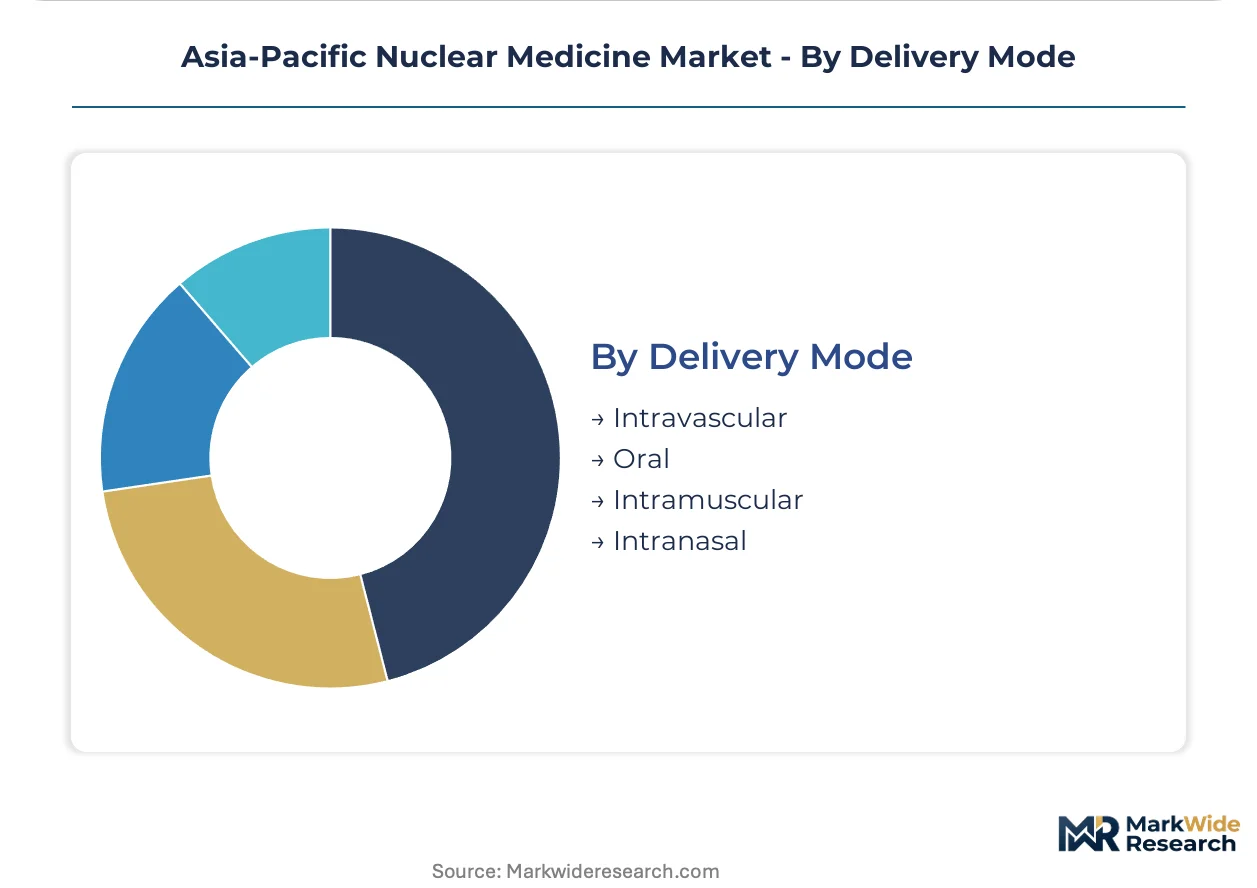
Delivery Mode:
Route selection balances bioavailability requirements against radioprotection protocols and administration infrastructure.
- Intravascular:Direct bloodstream injection of technetium-99m and fluorine-18 tracers dominates diagnostic nuclear medicine, requiring shielded injection suites and specialized nuclear pharmacy expertise.
- Oral:Iodine-131 capsules for thyroid uptake studies and hyperthyroidism treatment permit outpatient administration with reduced handling complexity.
- Intramuscular:Limited application for specific therapeutic radiopharmaceuticals requiring depot release kinetics.
- Intranasal:Experimental delivery pathway for neurological tracers crossing the blood-brain barrier, currently confined to research protocols.
Procedure volume anchors intravascular administration; clinical development tilts toward intranasal routes for blood-brain barrier penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Reactor-derived molybdenum-99 supplies from Australia and South Korea anchor regional isotope availability, while cyclotron infrastructure buildouts across metropolitan Japan and eastern China are displacing import-dependent sourcing models for positron-emitting diagnostic tracers.
Japan
Tertiary oncology departments in Tokyo and Osaka are expanding gallium-68 and lutetium-177 procurement for PSMA-targeted prostate cancer diagnostics. PMDA streamlining of radioisotope licensing timelines in 2023 accelerated domestic tracer availability for scheduled PET-CT procedures. The Kanto region around Tokyo concentrates cyclotron-based fluorine-18 production facilities reducing import dependency.
China
Proton therapy centers in Shanghai, Beijing, and Guangzhou are commissioning therapeutic radiopharmaceutical supplies for precision oncology applications. NMPA oversight of radioisotope manufacturing facilities enforces GMP standards that elevate compliance costs for new market entrants. The Yangtze River Delta corridor sustains China Isotope & Radiation Corp.'s vertical control from irradiation through finished generator dispatch.
Australia
Hospital-based cyclotron networks in Sydney and Melbourne are manufacturing positron emitters to offset reactor decommissioning impacts on technetium-99m availability. TGA enforcement of GMP standards for imported radiopharmaceuticals is disqualifying non-certified converters from hospital procurement shortlists. The Southeast Queensland cluster around Brisbane is decentralizing outpatient PET-CT capacity from traditional hospital campuses.
India
CDSCO and BIS dual-certification requirements for diagnostic tracer quality are shaping domestic production incentives while extending market entry timelines for foreign suppliers. Mumbai and Delhi-NCR metropolitan areas concentrate demand for myocardial perfusion imaging using technetium-99m sestamibi. The country's national pharmaceutical regulator maintains stringent radioisotope facility licensing protocols that filter market access.
South Korea
Reactor decommissioning schedules are forcing radiopharmaceutical suppliers to accelerate cyclotron infrastructure buildouts for diagnostic tracer sourcing. MFDS governance of radioisotope manufacturing standards aligns with international GMP frameworks. The Seoul Capital Area anchors metropolitan demand for oncology and cardiology nuclear medicine applications.
Asia-Pacific Nuclear Medicine Market Competitive Environment
Long-term supply agreement consolidation dominates the current landscape as multi-source procurement of technetium-99m generators shifts toward direct converter relationships. The vendor base spans multinational health technology conglomerates, state-affiliated isotope processors, and specialized radiopharmaceutical developers. Three archetypes anchor competitive positioning: reactor-to-patient logistics operators, cyclotron-based positron emitter manufacturers, and vertically integrated domestic converters. Capacity expansion and strategic partnerships represent the dominant competitive moves as stakeholders secure isotope supply continuity against reactor decommissioning headwinds.
Among multinational health technology conglomerates, GE HealthCare and Siemens Healthineers exemplify divergent sourcing strategies—one anchoring regional radiopharmacy networks, the other leveraging cyclotron infrastructure to reduce import dependency. Curium occupies a position within the reactor-derived isotope specialist tier, while China Isotope & Radiation Corp. represents state-affiliated vertical integration from irradiation through finished generator dispatch. Telix Pharmaceuticals sits within the theranostic developer archetype targeting precision radioligand therapies.
| Leading Market Players |
|---|
| GE HealthCare |
| Curium |
| Cardinal Health |
| Siemens Healthineers |
| Lantheus Holdings |
| China Isotope & Radiation Corp. |
| Telix Pharmaceuticals |
| Jubilant Pharmova |
| Bracco Imaging |
| Others |
Value Chain & Pricing Dynamics
Molybdenum-99 irradiation costs cascade through generator conversion fees, cold-chain logistics premiums, and hospital procurement tiering that separates scheduled oncology centers from spot-market diagnostic laboratories across Japan and Australia.
Pricing Analysis
Generator warranty and calibration service bundling separates premium converter relationships from unbundled spot procurement in the Asia-Pacific nuclear medicine market. Three-tier pricing structure across premium, standard, and economy levels reflects GMP certification grade and volume commitment scale. Pricing pressure stems from reactor decommissioning schedules forcing cyclotron infrastructure capex absorption. Diagnostic laboratories exhibit highest price sensitivity due to compressed margins from technetium-99m decay windows, while tertiary oncology centers accept premium tiering for supply security.
Supply Chain Analysis
Short-lived tracer returns and generator refurbishment flows create reverse logistics complexity that concentrates service capabilities near metropolitan cyclotron clusters. Australia, South Korea, and China anchor regional molybdenum-99 supply, with China Isotope & Radiation Corp. sustaining upstream control over irradiation and finished generator dispatch. The supply chain draws from enriched uranium targets, specialized radiochemist labor pools, and shielded transport cassettes. Single-source vulnerability in molybdenum-99 processing creates structural risk. Distribution runs through hospital-direct converter agreements bypassing traditional distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Reactor decommissioning timelines across Australia and South Korea constrain isotope availability, propping pricing power for cyclotron-based positron emitter manufacturers and vertically integrated domestic converters.
For Market Incumbents: Extend long-term supply agreement coverage to lock in volume commitments from proton therapy centers commissioning gallium-68 and lutetium-177 supplies. Deepen cyclotron infrastructure deployment across Southeast Asian metropolitan clusters to preempt emerging entrant cyclotron buildouts. Secure radiochemist talent pipelines through university partnership programs to defend operational capability against workforce scarcity. For New Entrants and Emerging Players: Begin with outpatient imaging center radiopharmacy services in Bangkok, Kuala Lumpur, and Jakarta where PET-CT capacity decentralization creates white-space demand. Target alpha-emitter therapeutics for bone metastases as the most penetrable therapeutic category beyond established diagnostic applications. Pursue direct hospital contracting models bypassing distributor intermediaries as the primary go-to-market angle. For Investors and Strategic Acquirers: PMDA licensing timeline acceleration is the leading indicator that Japanese cyclotron infrastructure investments will outpace reactor-dependent returns. Five-to-ten year viability favors theranostic developers with radioligand therapy pipelines over pure diagnostic tracer suppliers. Target acquisition archetype: cyclotron-equipped radiopharmacy networks with established hospital-direct relationships. Monitor cyclotron infrastructure buildout announcements against reactor decommissioning schedules as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Infrastructure Buildout | Hospital-based positron emitter production reduces import dependency for fluorine-18 tracers across Australian metropolitan clusters. |
| Long-Term Supply Agreement | Multi-year contracts between tertiary hospitals and domestic converter facilities lock in volume commitments for reactor-derived isotopes. |
| GMP Facility Certification Upgrade | Japanese and South Korean manufacturers upgrade facility certifications to maintain Asia-Pacific market access under TGA enforcement. |
| AI-Assisted Dosimetry Platform Deployment | Australian tertiary hospitals automate personalized radiopharmaceutical dosing calculations for lutetium-177 PSMA therapies. |
| Radiochemist Training Program Expansion | University partnerships address specialized nuclear pharmacy expertise scarcity outpacing regional training program output. |
Study Parameters
Regulatory filings from PMDA, TGA, and MFDS, hospital procurement databases, and cyclotron infrastructure development records formed the secondary backbone of this analysis. Primary interviews with nuclear medicine physicians, hospital GPO contracts managers, radiopharmacy operations directors, and cyclotron facility engineers combined with secondary validation. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored market sizing across the analysis window.
Historical trendline analysis of reactor-derived isotope availability and cyclotron commissioning rates informed projection frameworks. Segmentation dimensions modeled include product type, end-user institution scale, application area, and delivery mode alongside regional regulatory cluster differentiation. CAGRs were derived from supply-constrained demand elasticity curves and infrastructure investment trajectories. Forecast inputs incorporated PMDA licensing pathway timelines and proton therapy center expansion pipelines.
Underlying measurement precision varies by segment; radiopharmaceutical volume data carries tighter precision than emerging alpha-emitter therapeutic categories. Forecasts reflect documented assumptions regarding reactor decommissioning schedules and cyclotron buildout completion rates. Practitioners should monitor PMDA radioisotope approval velocity, TGA GMP enforcement actions, and CDSCO dual-certification processing timelines for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Neurophotonics Market
Medical Imaging
Mammography Detectors Market
Medical Imaging
Medical Imaging Software Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Mexico Digital X-Ray Devices Market
Medical Imaging
Radiographic Film Processor Market
Medical Imaging
Germany Digital Radiology Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Digital Telepathology Market
Medical Imaging
Medical Digital Imaging Systems Market
Medical Imaging
Europe Medical Imaging Market
Medical Imaging
Ultrasound-Based Imaging Market