
 Italy Mammography Market | 2026-2036
Italy Mammography Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Mammography Market Foresight
Hospital procurement channels in Italy are tilting toward multi-year service-inclusive contracts rather than standalone equipment purchases. Siemens Healthineers AG leverages its established service footprint to anchor long-term agreements with regional health authorities. Fujifilm Holdings Corporation competes through specialized digital breast tomosynthesis configurations tailored to Italian screening protocols. Metaltronica sustains its position by manufacturing compact systems that navigate space constraints in older diagnostic clinics.
Mammography encompasses X-ray-based breast imaging systems designed to detect microcalcifications and tissue masses, with modern units employing tungsten-target tubes and selenium-based digital detectors to achieve spatial resolution below 100 micrometers. The equipment serves population-scale screening programs and diagnostic workup of symptomatic patients across Italy's Servizio Sanitario Nazionale. Fully digital systems now dominate new installations, while 3D mammography segments capture expanding margin pools as regions upgrade from 2D protocols. Screening service contracts represent the most stable revenue stream, though diagnostic and therapeutic evaluation segments grow faster among private imaging centers seeking differentiation.
Italy's Ministry of Health screening directives and CE marking requirements under the EU Medical Device Regulation shape product eligibility and reimbursement pathways for mammography systems. Regional health agencies in Lombardy and Veneto enforce additional quality assurance protocols that filter market access toward vendors with proven local service infrastructure. Stakeholders must monitor how Italy's planned national recovery investments in oncology infrastructure reshape equipment allocation between public hospitals and private diagnostic networks.
Market Dynamics
Italy's mammography sector is reconfiguring around the Servizio Sanitario Nazionale's push toward fully digital screening protocols, with regional health authorities consolidating procurement through multi-year service contracts that bundle equipment, maintenance, and software upgrades into single agreements.
Growth Catalysts
- EU Medical Device Regulation (MDR):CE marking requirements under MDR are filtering market access toward vendors with robust quality systems, accelerating replacement of legacy analog systems in public hospitals.
- Dense screening networks:Lombardy and Emilia-Romagna maintain population-scale programs with shorter rescreening intervals, sustaining premium system demand.
- Tungsten-target tube technology:Selenium-based digital detectors achieving sub-100-micrometer resolution are enabling earlier microcalcification detection, justifying upgrade investments.
Market Restraints
- Capital intensity:Fully digital breast tomosynthesis systems require substantial upfront investment, limiting deployment in smaller diagnostic clinics with constrained budgets.
- Service infrastructure concentration:Proven local service capabilities concentrate among established vendors, creating barriers for new entrants lacking regional technician networks.
- Space constraints:Older diagnostic clinics in historic urban centers face physical limitations accommodating larger 3D mammography platforms.
Strategic Opportunities
- Private imaging center expansion:Diagnostic and therapeutic evaluation segments among private networks in northern Italy seek differentiation through advanced imaging capabilities.
- AI-assisted image analysis:Integration of machine learning algorithms with digital breast tomosynthesis is reducing radiologist reading time while improving detection accuracy.
- National recovery investments:Italy's planned oncology infrastructure allocations are reshaping equipment distribution between public hospitals and private diagnostic networks.
Industry Challenges
- Radiologist workforce constraints:Specialized breast imaging interpretation requires dedicated training, and screening program expansion strains existing specialist pools.
- Legacy system integration:PACS connectivity and data migration from analog archives complicate transition timelines for regional health authorities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Mammography Market |
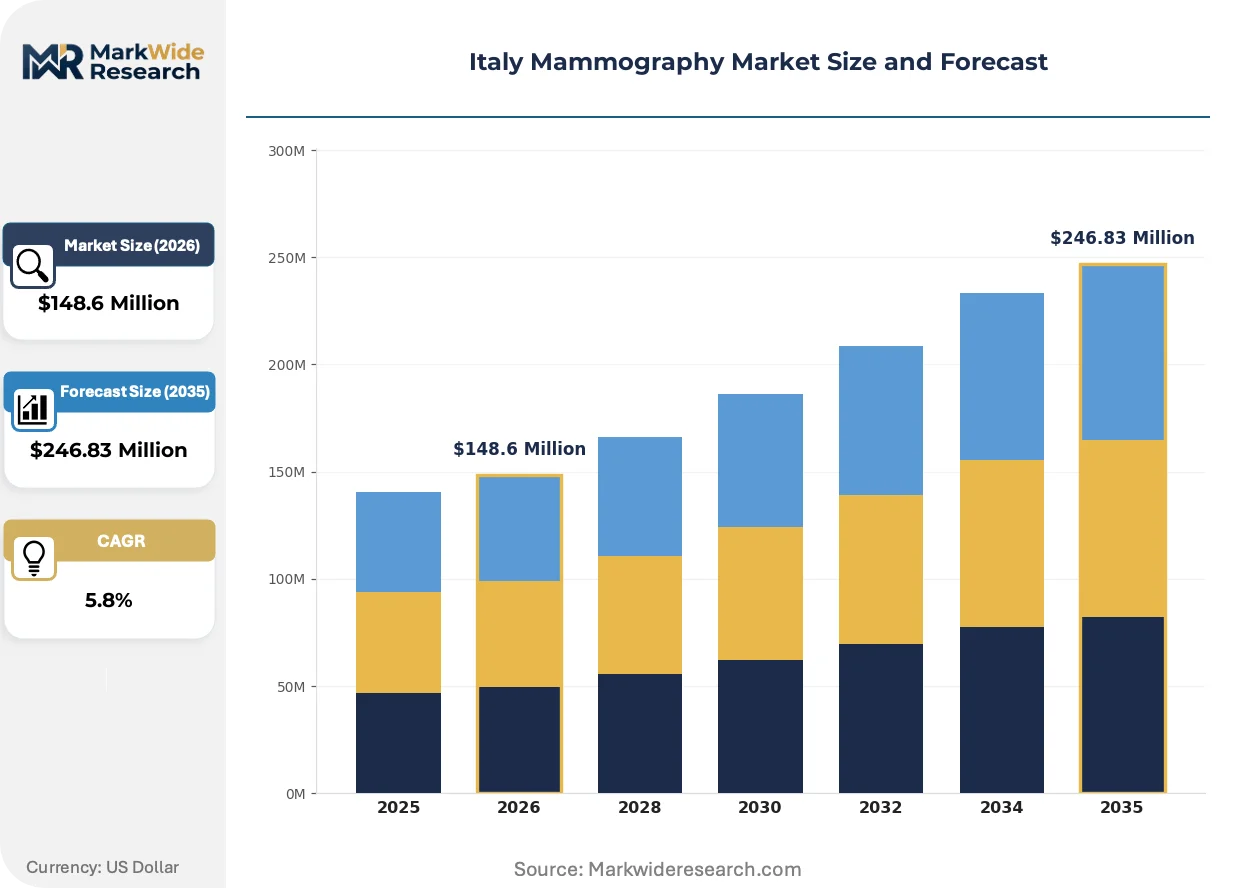
| Market Size in 2026 | $148.6 Million |
| Market Size in 2035 | $246.83 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fully Digital Systems, Analog Systems, 3D Mammography, Portable Units End User: Hospitals, Imaging Centers, Diagnostic Clinics, Research Institutions Technology: X-ray, Tomosynthesis, Contrast-Enhanced, Ultrasound Service Type: Screening, Diagnostic, Therapeutic, Evaluation |
| Companies Covered | Koninklijke Philips NV, Carestream Health Inc, GE Healthcare, IMS Giotto S.p.A., Metaltronica, Siemens Healthineers AG, Fujifilm Holdings Corporation, Planmed, Hologic Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Mammography Market Shifts & Advancements
Digital breast tomosynthesis is displacing conventional 2D mammography as the standard of care, while artificial intelligence tools and consolidated procurement models are compressing vendor margins and reshaping competitive positioning across Italy's peninsula.
Selenium-based digital detector technology is digitizing image acquisition workflows in screening centers throughout Lombardy and Veneto. Regional health authorities in these northern provinces are mandating full digital conversion ahead of national timelines. This technology shift is digitizing film-based archives and enabling remote radiologist consultation networks that span multiple provinces.
Italy's Ministry of Health screening directives are tightening quality assurance protocols that regional agencies in Veneto enforce through additional technical specifications. Equipment vendors must now demonstrate local calibration capabilities and Italian-language training programs before contract eligibility. Public hospital networks are responding by extending evaluation periods and requiring reference site visits within the peninsula.
Multi-year service-inclusive contracts are displacing standalone equipment purchases across Tuscany and Piedmont. Regional health authorities bundle preventive maintenance, software updates, and replacement part guarantees into single agreements spanning five to seven years. This contracting evolution is most visible in Emilia-Romagna, where procurement offices prioritize total cost of ownership over initial capital expenditure in vendor selection criteria.
Italy Mammography Market Segmentation
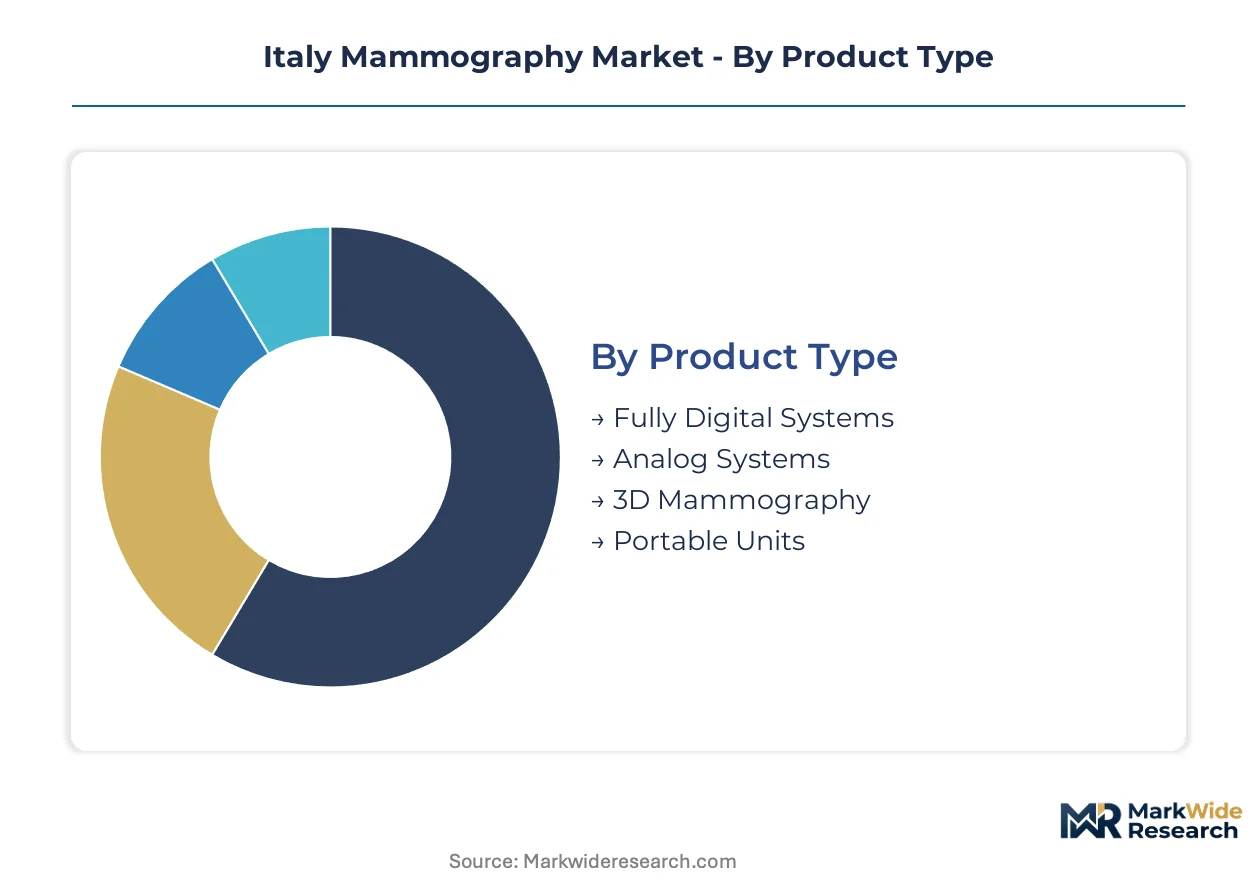
Segmentation in Italy's mammography market reveals how procurement patterns, clinical workflows, and regulatory requirements fragment demand across distinct technology tiers and service models. Understanding these divides exposes where margin pools concentrate and which configurations align with regional health authority priorities.
Product Type:
Cost tier differentiation separates capital-intensive installations from budget-constrained replacements across Italy's Servizio Sanitario Nazionale.
- Fully Digital Systems:Tungsten-target tubes paired with selenium-based detectors achieve sub-100-micrometer spatial resolution for microcalcification detection. Lombardy and Emilia-Romagna health authorities mandate these configurations for population-scale screening programs, with procurement offices prioritizing total cost of ownership over initial capital expenditure in multi-year service contracts.
- 3D Mammography:Digital breast tomosynthesis reconstructs multiple slice images to reduce tissue overlap artifacts in dense breast tissue. Private imaging centers in northern Italy deploy these systems to differentiate diagnostic capabilities, though physical footprint constraints limit adoption in historic urban clinics with restricted room dimensions.
- Analog Systems:Legacy film-based units persist in smaller diagnostic clinics with constrained capital budgets, particularly in southern regions with delayed digital conversion timelines.
- Portable Units:Compact mobile configurations serve temporary screening campaigns and rural outreach programs where fixed infrastructure is unavailable.
Fully Digital Systems hold installed capacity. 3D Mammography is rotating up the share rankings.
End User:
Customer type determines contracting structure, with public networks consolidating procurement while private operators seek technology differentiation.
- Hospitals:Public hospital networks anchor equipment demand through regional health authority procurement offices, bundling preventive maintenance and software updates into five-to-seven-year service-inclusive agreements. These contracts filter vendor eligibility toward established service footprints with proven Italian-language training capabilities.
- Imaging Centers:Private diagnostic networks concentrate in northern Italy's dense healthcare corridors, purchasing advanced tomosynthesis configurations to attract specialist referrals and justify premium pricing for complex diagnostic workups.
- Diagnostic Clinics:Smaller facilities face space constraints in historic urban centers, driving demand for compact system footprints from manufacturers with modular installation options.
- Research Institutions:Academic medical centers pilot AI-assisted image analysis integration and novel contrast-enhanced protocols, though volume remains limited compared to clinical service providers.
Hospitals dominate procurement volume. Imaging Centers are expanding fastest as private networks proliferate.
Technology:
Maturity curves separate established X-ray modalities from emerging tomosynthesis and adjunct imaging approaches.
- X-ray:Conventional 2D projection mammography remains the baseline for screening program compliance, with tungsten-target technology replacing molybdenum in newer installations to reduce dose while maintaining image quality.
- Tomosynthesis:Three-dimensional image reconstruction is displacing conventional 2D mammography as the standard of care in premium screening segments, with regional authorities in Veneto mandating full digital conversion ahead of national timelines.
- Contrast-Enhanced:Iodinated contrast protocols combined with mammography improve lesion characterization in dense breast tissue, deployed primarily in diagnostic workup rather than population screening.
- Ultrasound:Adjunct handheld imaging supplements mammography for dense breast evaluation and biopsy guidance, though reimbursement pathways limit standalone screening deployment.
X-ray maintains the largest installed base. Tomosynthesis is climbing the fastest as regions upgrade from 2D protocols.
Service Type:
Application purpose segments revenue stability, with screening contracts providing predictable cash flows against faster-growing diagnostic and interventional segments.
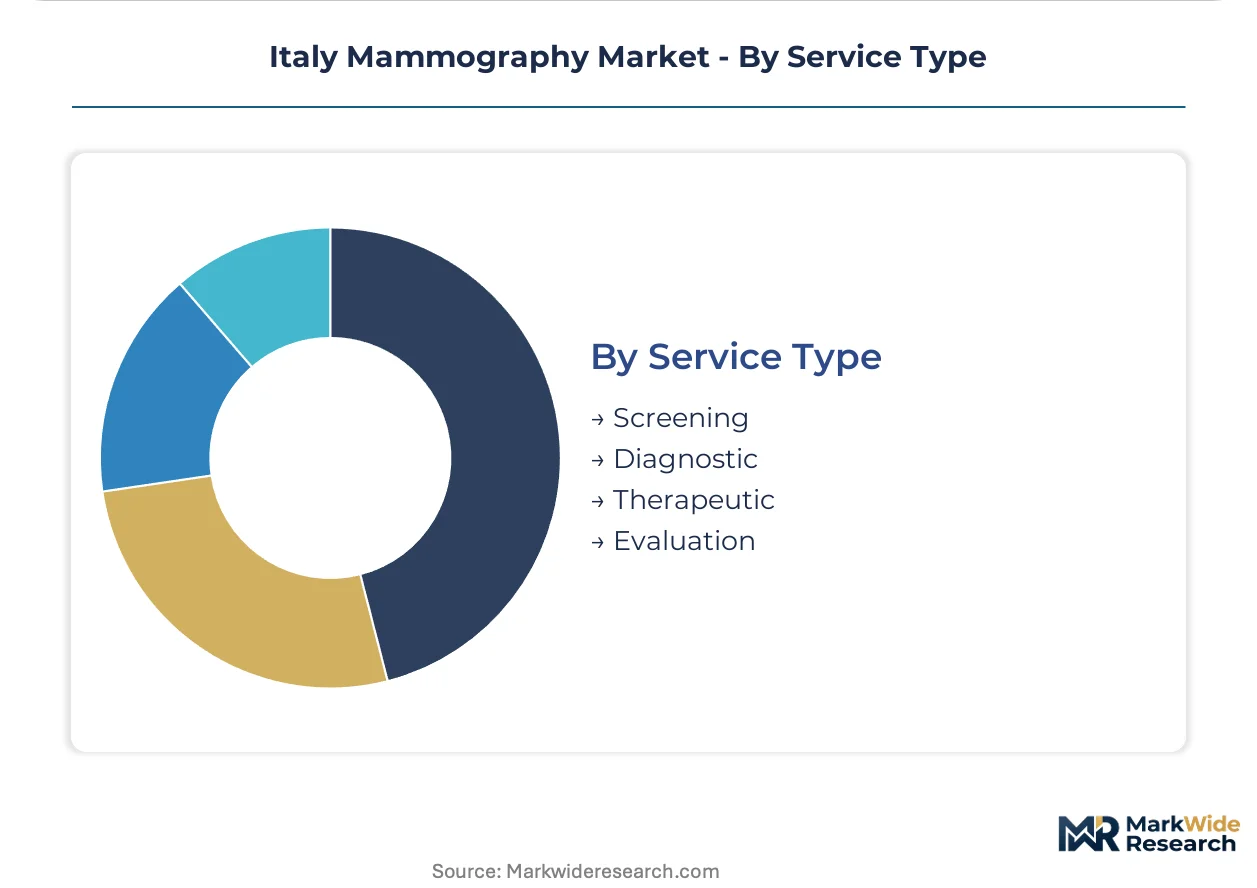
- Screening:Population-scale asymptomatic examination programs generate the most stable revenue streams through government-contracted service agreements, with Lombardy and Emilia-Romagna maintaining dense networks with shorter rescreening intervals.
- Diagnostic:Symptomatic patient evaluation and abnormal screening follow-up commands premium pricing in private imaging centers, expanding most quickly as networks seek differentiation beyond commodity screening.
- Therapeutic:Pre-operative localization and post-treatment surveillance services integrate mammography with interventional procedures, capturing higher margins through bundled care pathways.
- Evaluation:Second opinion and complex case consultation leverages remote radiologist networks enabled by fully digital image distribution across provincial boundaries.
Screening commands contract volume. Diagnostic is gaining share fastest among private network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's national oncology plan updates are channeling recovery investments toward digital breast imaging infrastructure. Regional health authorities in northern provinces enforce quality assurance protocols that accelerate equipment replacement cycles. Procurement consolidation through multi-year service contracts is reshaping vendor access across the peninsula.
Lombardy
Milan's dense screening networks and elevated per-capita healthcare spending sustain premium digital system deployments. Regional health authorities mandate CE marking compliance under EU MDR for all new installations. The metropolitan cluster anchors population-scale programs with shorter rescreening intervals that justify tungsten-target tube investments.
Emilia-Romagna
Bologna-based procurement offices prioritize total cost of ownership over initial capital expenditure in vendor selection criteria. The region's screening directives filter market access toward manufacturers with proven Italian-language training capabilities. Dense diagnostic networks across the province are converting from 2D protocols to digital breast tomosynthesis configurations.
Veneto
Verona and Padua health agencies enforce additional technical specifications beyond national minimums for quality assurance. CE marking requirements under EU MDR are accelerating replacement of legacy analog systems in public hospitals. The region's medical device service infrastructure concentrates among established vendors with regional technician networks.
Piedmont
Turin's regional health authority bundles preventive maintenance and software updates into five-to-seven-year service-inclusive agreements. Space constraints in historic urban centers drive demand for compact system footprints from manufacturers with modular installation options. Private imaging networks in the province seek differentiation through advanced diagnostic capabilities.
Tuscany
Florence-based diagnostic clinics face physical limitations accommodating larger 3D mammography platforms in older facilities. The region's procurement evolution favors multi-year contracts that combine equipment, maintenance, and replacement part guarantees. Screening program expansion strains existing radiologist specialist pools across the provincial network.
Italy Mammography Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with established service footprints and proven local calibration capabilities. Siemens Healthineers AG leverages its infrastructure to anchor long-term agreements with regional health authorities. Fujifilm Holdings Corporation competes through specialized configurations. Metaltronica sustains position by manufacturing compact systems. Strategic moves center on multi-year service contract capture and AI-assisted image analysis integration.
Among diversified medical technology conglomerates, Koninklijke Philips NV and GE Healthcare occupy positions that span imaging modalities beyond mammography. Siemens Healthineers AG exemplifies the service-anchored archetype through its regional technician networks. Specialized breast imaging manufacturers including Hologic Inc and Metaltronica represent focused players that navigate space constraints and screening protocol requirements. IMS Giotto S.p.A. and Planmed sit within the European specialist tier, while Fujifilm Holdings Corporation and Carestream Health Inc anchor trans-Pacific supply positions.
| Leading Market Players |
|---|
| Koninklijke Philips NV |
| Carestream Health Inc |
| GE Healthcare |
| IMS Giotto S.p.A. |
| Metaltronica |
| Siemens Healthineers AG |
| Fujifilm Holdings Corporation |
| Planmed |
| Hologic Inc |
| Others |
Supply & Pricing Matrix
Overcapacity in southern Italy's legacy analog system installed base is compressing vendor margins and forcing manufacturers to absorb service costs within multi-year contract structures across the peninsula.
Pricing Analysis
Volume-discount tiering structures dominate procurement negotiations, with regional health authorities leveraging population-scale screening commitments to extract bundled service concessions. Three-tier pricing separates premium tomosynthesis configurations from standard digital units and economy analog replacements, with CE marking tier under EU MDR filtering eligibility. Cost compression in the economy tier is intensifying as southern regions delay digital conversion timelines. Smaller diagnostic clinics in historic urban centers exhibit highest price sensitivity, while Lombardy and Emilia-Romagna health authorities prioritize total cost of ownership over capital expenditure.
Supply Chain Analysis
Upstream feedstock for selenium-based digital detectors draws from specialized semiconductor foundries concentrated in Germany, Japan, and the United States. Tungsten-target tube manufacturing rests on rare earth processing capabilities anchored in China and refined metal supplies from Russian and Kazakh sources. Single-source vulnerability in selenium wafer supply creates exposure to export restriction shocks. Distribution runs through authorized service networks requiring Italian-language technical certification, filtering market access toward vendors with proven local calibration infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across Italy's regional health authorities creates niche opportunities for specialized service providers and compact system manufacturers as procurement decentralization accelerates.
For Market Incumbents: Harden service infrastructure density in Veneto and Tuscany to preempt regional quality assurance mandates. Deepen backward integration into predictive maintenance software to offset margin compression from extended warranty terms. Counter emerging entrant pressure by anchoring five-to-seven-year replacement part guarantees within existing hospital network contracts.
For New Entrants and Emerging Players: Establish a beachhead in southern Italy's delayed digital conversion corridor, where capital constraints among smaller diagnostic clinics favor compact system footprints and flexible financing structures. Penetrate the portable screening unit segment serving rural outreach programs with modular deployment capabilities. Pursue direct relationships with provincial procurement offices rather than national tender processes.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among service-anchored vendors with proven Italian-language training capabilities and multi-year regional health authority agreements. Long-term viability over the next decade favors acquisition targets with installed base density in northern provinces and AI-assisted image analysis integration roadmaps. Monitor radiologist workforce expansion rates as an inflection indicator for screening program scalability.
| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance filters vendor eligibility toward established quality system investments. |
| Hospital System Partnership | Multi-year service contracts with Lombardy and Emilia-Romagna anchor predictable revenue streams. |
| Software Companion Development | AI-assisted image analysis integration reduces radiologist reading time while improving detection accuracy. |
| Reimbursement Strategy | Alignment with Italy's Ministry of Health screening directives secures public procurement eligibility. |
| Geographic Manufacturing Footprint | Regional technician networks in Veneto and Piedmont satisfy local calibration capability requirements. |
Research Methodology
A standing panel of hospital procurement managers, biomedical engineers, GPO contracts managers, and regional health authority planning officers provided ongoing calibration throughout the study. Primary interviews with Siemens Healthineers service technicians and Fujifilm clinical application specialists were cross-referenced against secondary sources including EU MDR compliance databases, Italian Ministry of Health screening directives, and hospital procurement records from Lombardy and Emilia-Romagna. Bottom-up equipment installation tracking and top-down healthcare expenditure modeling were triangulated to validate market sizing.
Scenario-bracketing framed sensitivity analysis across the projection horizon, with baseline, accelerated digital conversion, and delayed replacement cycle variants tested. Segmentation dimensions modeled include product type tier, end-user contracting structure, technology maturity curve, and service application purpose. CAGRs were derived from equipment replacement cycle analysis and regional health authority capital allocation patterns, with inputs from radiologist workforce growth projections and AI integration adoption curves.
Stress conditions across EU MDR implementation timelines, selenium wafer supply disruptions, and regional budget allocation shifts were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding screening program expansion rates and private imaging center proliferation. Cross-checking against Italian National Health Service expenditure reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
China Digital Radiology Market
Medical Imaging
France Digital X-Ray Devices Market
Medical Imaging
Europe Fluoroscopy Market
Medical Imaging
Cone Beam CT Scanner Market
Medical Imaging
Mobile Radiography Systems Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Next Generation Ultrasound Systems Market
Medical Imaging
Radiology Services Market
Medical Imaging
Medical Videoscope Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Global Surgical Imaging Arms Market
Medical Imaging
Medical Imaging Agent-Producing System Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Digital Mammography Market
Medical Imaging
Medical X-Ray Films Market