
 Global Medical Imaging Phantoms Market | 2026-2036
Global Medical Imaging Phantoms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Medical Imaging Phantoms Market Intelligence
The procurement landscape for medical imaging phantoms is pivoting from individual hospital radiology departments towards consolidated purchasing by large diagnostic center networks. Biodex Medical Systems leverages its strong relationships with these large networks in the North American market. PTW Freiburg GmbH specializes in high-precision phantoms for radiation therapy, a niche where quality assurance is paramount. Computerized Imaging Reference Systems differentiates through its extensive catalog of anthropomorphic phantoms for research applications.
Medical imaging phantoms are manufactured objects that simulate the radiological properties and geometry of human tissues and organs. These devices are crucial for calibrating and testing imaging modalities, ensuring consistent performance by using materials with known densities and characteristics. While CT phantoms and MRI phantoms constitute the largest product segments, the ultrasound phantoms category is expanding due to the proliferation of point-of-care ultrasound systems. Among applications, quality assurance remains the dominant use case, mandated by regulatory standards for all imaging equipment.
Compliance with standards from the U.S. FDA and the EU's Medical Device Regulation (MDR) dictates market access and product design. International Organization for Standardization (ISO) guidelines further inform the requirements for phantom manufacturing and quality control protocols. Future vendor success will depend on developing phantoms that can validate the performance of AI-driven diagnostic algorithms.
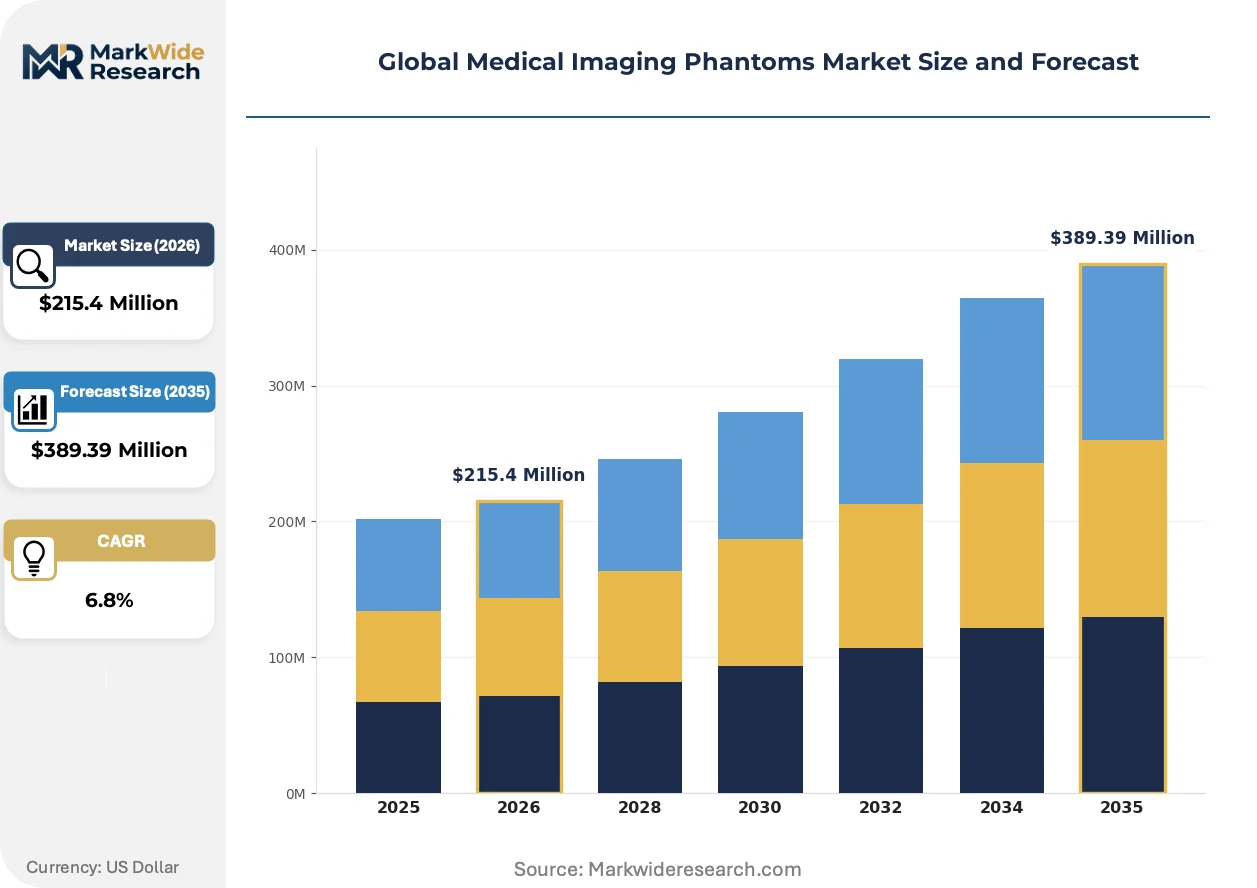
Market Dynamics
The primary force shaping the market is the intensification of regulatory oversight, particularly from the EU's Medical Device Regulation. This mandate for stricter calibration and quality assurance protocols is elevating the phantom's role from a testing tool to a required compliance device.
Growth Catalysts
- Regulatory Mandates:The EU's Medical Device Regulation (MDR) is tightening quality assurance protocols, making certified phantom use a compliance necessity for imaging centers.
- Point-of-Care Expansion:The proliferation of portable ultrasound systems in emergency medicine creates a distinct need for durable phantoms for operator training.
- Advanced Academic Training:Medical universities require anthropomorphic phantoms for realistic simulation in radiology education programs.
Market Restraints
- High Capital Cost:The expense of advanced anthropomorphic phantoms restricts acquisition by smaller clinics and facilities in developing economies.
- Material Limitations:Current materials cannot perfectly replicate the dynamic radiological properties of living tissue, limiting utility in some advanced research.
- Software Substitution:The emergence of digital simulation tools presents a long-term substitution threat for physical phantoms in early-stage research.
Strategic Opportunities
- AI Algorithm Validation:A significant opportunity exists in developing phantoms with known targets to validate the accuracy of new AI-powered diagnostic software.
- Multi-Modality Devices:Phantoms compatible with both CT and MRI streamline quality assurance programs, offering workflow efficiencies for hospitals.
- Emerging Market Compliance:As regulators like Brazil's ANVISA tighten standards, opportunities arise to supply compliant phantoms to Latin American markets.
Industry Challenges
- AI Validation Standards:A lack of global standards for phantoms used in AI validation creates market uncertainty and complicates performance comparisons between algorithms.
- Complex Fabrication:Manufacturing patient-specific 3D-printed phantoms involves intricate processes and specialized materials, creating production bottlenecks.
- Certification Timelines:The lengthy certification pathway under the EU's MDR can delay market entry for innovative phantom designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Medical Imaging Phantoms Market |
| Market Size in 2026 | $215.4 Million |
| Market Size in 2035 | $389.39 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: CT Phantoms, MRI Phantoms, Ultrasound Phantoms, PET Phantoms, X-ray Phantoms Application: Quality Assurance, Equipment Calibration, Training & Education, Research & Development, Performance Testing Technology: Anthropomorphic, Geometric, Tissue-Equivalent, Dynamic, Pediatric End User: Diagnostic Centers, Research Institutes, Medical Universities, Radiology Departments, Imaging Device Manufacturers |
| Companies Covered | Gold Standard Phantoms, PTW Freiburg GmbH, Kyoto Kagaku Co., Ltd., Biodex Medical Systems, Computerized Imaging Reference Systems, Carville Limited, Leeds Test Objects, Pure Imaging Phantoms, Modus Medical Devices Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Medical Imaging Phantoms Market Strategic Shifts & Innovations
The market's innovation trajectory is defined by a push towards greater realism and functional complexity. Phantoms are evolving from simple geometric test objects into sophisticated systems designed to challenge and validate the next generation of data-intensive imaging technologies and AI algorithms.
Multi-part, configurable phantoms feature interchangeable inserts that simulate various tissue types or pathological conditions. Research institutions and medical device manufacturers are adopting these for developing and testing new imaging sequences. This evolution is modularizing the phantom, shifting the market from single-use test objects to adaptable platforms for diverse quality assurance protocols.
International Organization for Standardization (ISO) guidelines for medical device manufacturing are becoming more influential in phantom design. These standards compel manufacturers to implement rigorous quality control and provide extensive documentation on material properties and traceability. This trend most directly impacts vendors targeting the European market, where adherence to both ISO standards and the MDR is non-negotiable for market access.
A notable demand-side shift involves acquiring phantoms as part of comprehensive quality assurance service packages from equipment OEMs or third-party providers. This service-based model is displacing the traditional, one-off purchase of a device by an individual hospital department. This pattern is most visible in the United States and Germany, where large diagnostic networks seek to standardize QA processes across all facilities.
Global Medical Imaging Phantoms Market Segmentation
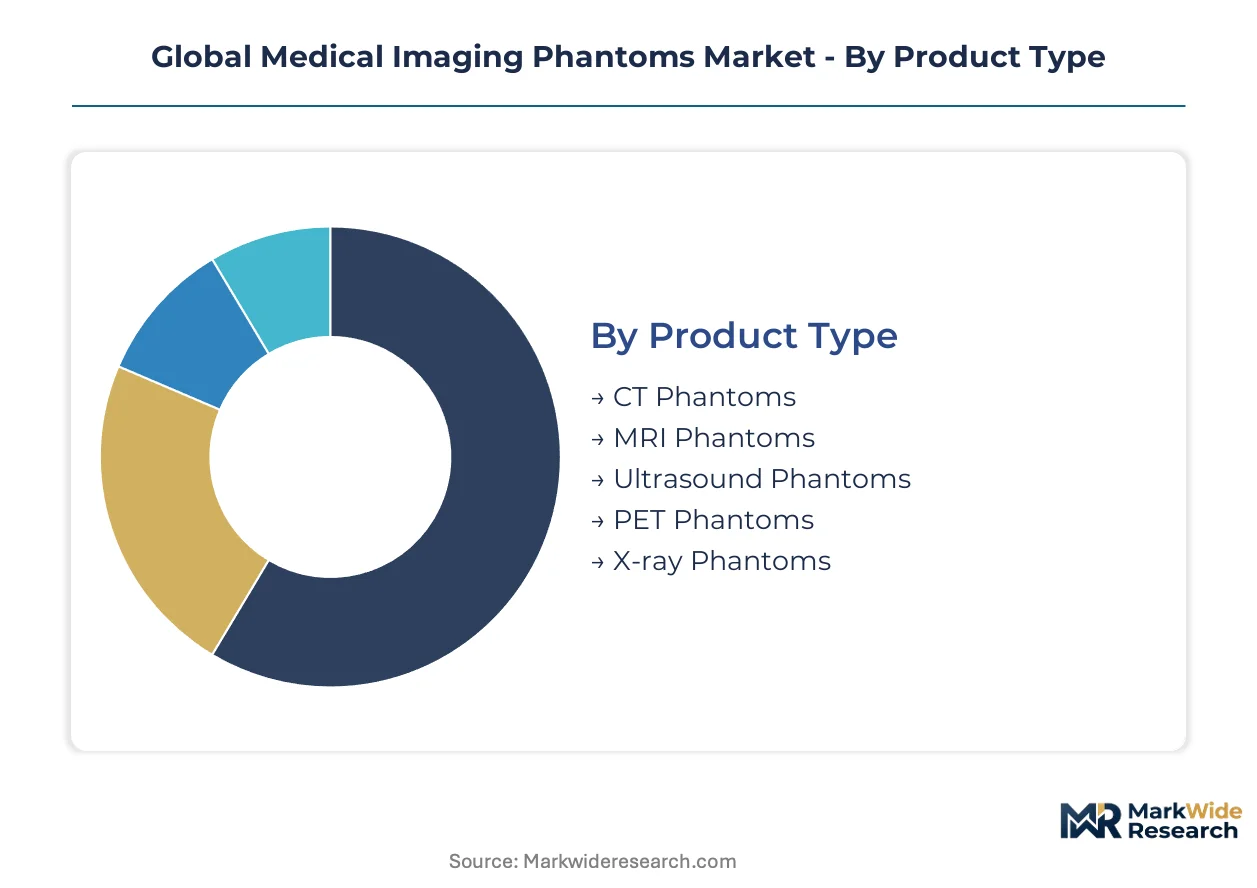
The Global Medical Imaging Phantoms Market segmentation reflects the diverse requirements for validating and optimizing medical imaging systems. Understanding these distinct categories provides clarity on procurement patterns and technological priorities across various clinical and research settings. Each segment addresses specific needs for accuracy, realism, and compliance within the imaging workflow.
Product Type:
The regulatory landscape significantly influences medical imaging phantom development and adoption, with specific product types requiring stringent approvals from bodies like the U.S. FDA and the EU's MDR.
- CT Phantoms:These phantoms simulate tissue attenuation for computed tomography systems. Demand concentrates in large diagnostic networks in Germany and the United States, where precise calibration is critical.
- MRI Phantoms:Mimicking magnetic resonance characteristics of biological tissues, MRI phantoms are essential for evaluating image quality and sequence optimization. Research institutions utilize these for new imaging protocol development.
- Ultrasound Phantoms:Simulating acoustic properties, these phantoms are vital for calibrating ultrasound machines.
- PET Phantoms:Contain radioactive isotopes to replicate tracer uptake in positron emission tomography.
- X-ray Phantoms:Used for conventional radiography, they assess image resolution and dose optimization.
Leading the category by volume: CT Phantoms. Growing fastest: Ultrasound Phantoms.
Application:
The utility of medical imaging phantoms spans diverse applications, each demanding specific phantom characteristics to ensure accurate, reliable outcomes across clinical and research settings.
- Quality Assurance:This involves routine checks to ensure imaging equipment performs within specified parameters, mandated by regulatory standards like the EU's MDR. Diagnostic centers prioritize these for consistent output.
- Research & Development:Phantoms in R&D are critical for developing new imaging sequences, validating AI-driven diagnostic algorithms, and understanding tissue interactions. Academic institutions utilize these for prototyping.
- Equipment Calibration:Focuses on precisely adjusting imaging systems to standardized performance metrics.
- Training & Education:Provides realistic simulation environments for medical students and radiology technicians to practice techniques.
- Performance Testing:Evaluates new or upgraded imaging systems against established benchmarks to confirm operational efficacy.
Quality Assurance represents the largest segment, with Research & Development demonstrating significant expansion.
Technology:
Technological advancements in phantom design drive greater realism and functional complexity, moving beyond simple geometric shapes to sophisticated models that accurately mimic human physiology.
- Anthropomorphic:These phantoms replicate human external and internal anatomy, providing realistic simulations for training, surgical planning, and dosimetry studies. Medical universities widely adopt these for advanced radiology education.
- Tissue-Equivalent:Composed of materials matching human tissue radiological properties, these phantoms are crucial for accurate dose measurements and image quality assessment. Research institutions use them to validate new imaging sequences.
- Geometric:Simple, standardized shapes define geometric phantoms, primarily used for basic calibration and uniformity checks.
- Dynamic:These phantoms simulate physiological motion, enabling evaluation of imaging systems under realistic conditions.
- Pediatric:Mimicking children's smaller size and tissue compositions, pediatric phantoms support specialized imaging protocols.
Anthropomorphic phantoms remain a foundational technology, while dynamic phantoms are gaining traction for advanced research.
End User:
The end-user landscape for medical imaging phantoms is evolving, with procurement patterns shifting as large networks consolidate purchasing and specialized institutions seek tailored solutions.
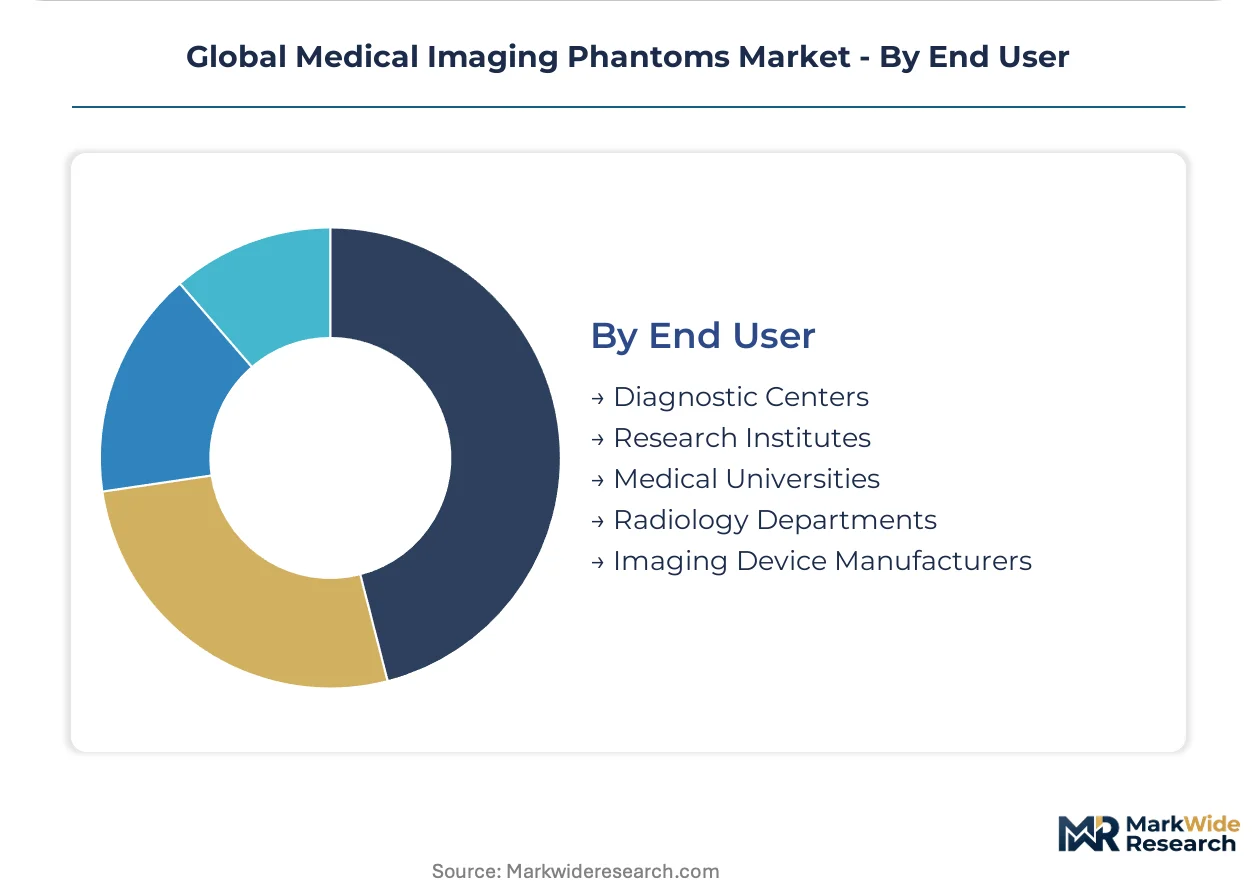
- Diagnostic Centers:These facilities are a primary end-user, acquiring phantoms for routine quality assurance and equipment calibration across high-volume imaging procedures. Large diagnostic networks in the United States and Germany drive demand.
- Medical Universities:These institutions utilize phantoms extensively for advanced academic training, simulating clinical scenarios for radiology residents and medical students. They require anthropomorphic phantoms for realistic educational experiences.
- Research Institutes:These organizations employ phantoms for developing new imaging techniques and validating novel diagnostic approaches.
- Radiology Departments:Individual hospital radiology departments use phantoms for localized quality control and equipment training.
- Imaging Device Manufacturers:OEMs integrate phantoms into product development cycles for testing and validating imaging systems.
Diagnostic Centers constitute the largest end-user segment, and Medical Universities are expanding their phantom acquisition for training.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for medical imaging phantoms is concentrating in advanced healthcare markets with substantial investments in diagnostic infrastructure. Large diagnostic center networks are consolidating procurement, particularly in North America and Western Europe. Regulatory mandates further compel increased adoption across these key geographies.
United States
Large diagnostic networks in the United States drive significant demand for medical imaging phantoms, particularly for CT and MRI modalities. U.S. FDA guidelines mandate rigorous quality assurance protocols for all medical imaging equipment, making phantom use a compliance necessity. Major medical technology hubs like Boston and San Francisco actively develop and deploy advanced imaging phantom solutions for research and clinical validation.
Germany
Germany exhibits high demand for medical imaging phantoms, supported by its extensive installed base of advanced imaging equipment and research capabilities. The EU's Medical Device Regulation (MDR) enforces stringent calibration and quality assurance requirements, impacting phantom design and market access. Research institutions in cities like Munich and Berlin utilize phantoms for validating new imaging sequences and AI-driven diagnostic algorithms.
United Kingdom
Medical universities in the United Kingdom increasingly acquire anthropomorphic phantoms for advanced radiology education programs and realistic simulation. The MHRA, the UK's medical device regulator, ensures compliance with essential performance and safety requirements for imaging devices and their calibration tools. London's academic medical centers are at the forefront of adopting realistic simulation tools for operator training and research.
Brazil
Brazil presents a strategic opportunity as its regulatory environment, led by ANVISA, tightens standards for medical devices and diagnostic imaging. This regulatory shift necessitates compliant phantoms for quality assurance and equipment calibration in diagnostic centers. São Paulo's burgeoning healthcare sector is actively seeking advanced imaging calibration solutions to meet evolving national standards.
Global Medical Imaging Phantoms Market Key Industry Players
North American producers anchor one tier, focusing on broad diagnostic center networks and academic institutions. European specialists hold another tier, emphasizing high-precision phantoms for radiation therapy and adherence to stringent EU regulations. The market structure exhibits a blend of established players with diversified portfolios and niche providers specializing in specific modalities or applications. Strategic partnerships with imaging equipment OEMs and continuous product innovation are dominant competitive moves.
Specialists in high-precision phantoms include PTW Freiburg GmbH, a German-based company operating within the European regulatory framework. This firm often exemplifies providers focused on quality assurance for radiation therapy, a segment requiring paramount accuracy. Biodex Medical Systems, a North American entity, represents suppliers with strong relationships within large diagnostic networks, catering to broad market demands. Kyoto Kagaku Co., Ltd., a Japanese manufacturer, occupies a position among firms focusing on advanced anthropomorphic phantoms for research and intricate training applications. These entities collectively anchor different segments of the market by offering distinct specialized solutions.
| Leading Market Players |
|---|
| Gold Standard Phantoms |
| PTW Freiburg GmbH |
| Kyoto Kagaku Co., Ltd. |
| Biodex Medical Systems |
| Computerized Imaging Reference Systems |
| Carville Limited |
| Leeds Test Objects |
| Pure Imaging Phantoms |
| Modus Medical Devices Inc. |
| Others |
Cost & Logistics Intelligence
The EU's Medical Device Regulation (MDR) mandates for stringent quality assurance protocols gate both qualified phantom supply and premium-tier pricing access. This regulatory environment elevates compliance as a critical cost component, influencing manufacturing processes and market entry strategies.
Pricing Analysis
Volume-driven segments like basic CT phantoms exhibit transactional pricing, while specialized anthropomorphic phantoms command project-based rates. Price differentiation stems from certification levels, particularly ISO and MDR compliance, and the extent of after-sales service bundles. Pricing pressure stems from the long-term threat of digital simulation tools, especially in early-stage research. Smaller clinics and facilities in developing economies are highly price-sensitive, contrasting with large diagnostic networks that prioritize certified quality over cost.
Supply Chain Analysis
Specialized material supply rests on a limited number of chemical and polymer manufacturers, primarily in Germany, Japan, and the United States. Key raw material dependencies include tissue-equivalent gels, specialized plastics, and radioactive isotopes for PET phantoms. Complex fabrication processes for patient-specific 3D-printed phantoms introduce a structural supply chain risk, creating production bottlenecks. Distribution runs through a combination of direct sales to large diagnostic networks and integration into OEM equipment sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story, with the EU's Medical Device Regulation (MDR) creating a significant barrier-to-entry moat for compliant players.
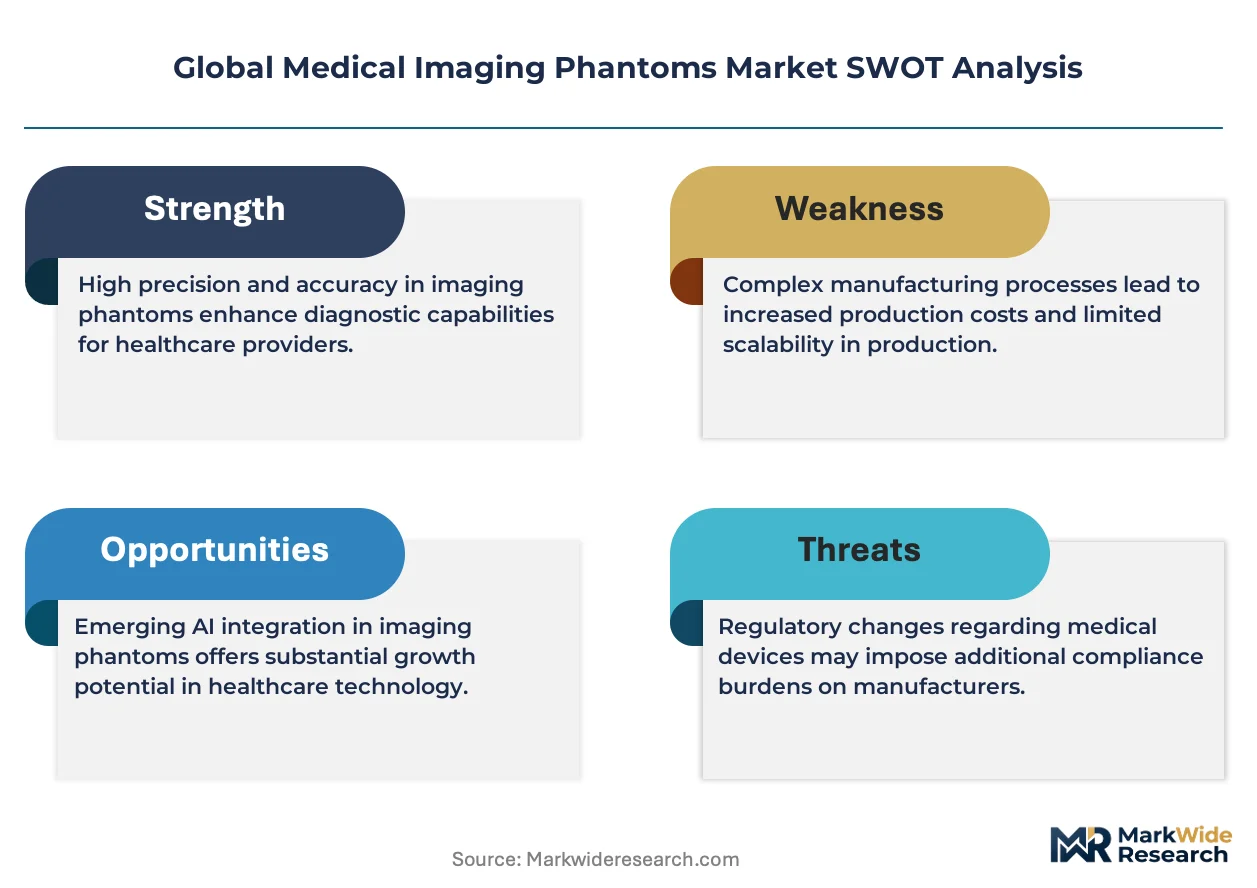
For Market Incumbents: To counter the long-term threat of digital simulation software, incumbents must deepen vertical integration into specialized material science and advanced manufacturing. Expanding multi-modality phantom offerings, compatible with both CT and MRI, streamlines hospital quality assurance programs. Investment in R&D for phantoms designed to validate AI-driven diagnostic algorithms remains a critical lever for future growth. For New Entrants and Emerging Players: Online marketplaces and direct-to-customer e-commerce platforms offer a viable route for market entry. Target the underpenetrated point-of-care ultrasound phantom segment, particularly for operator training in emergency medicine. A go-to-market angle emphasizing durability, ease of use, and cost-effectiveness for training applications in emerging markets like Brazil holds significant potential. For Investors and Strategic Acquirers: The proliferation of AI-driven diagnostic algorithms is the leading indicator that specialized phantom solutions for AI validation will drive future market value. Long-term viability hinges on acquiring firms with unique intellectual property in dynamic or anthropomorphic phantom design. Watch for increased regulatory clarity on AI validation standards as a key inflection signal, prompting further consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Develop AI Validation Phantoms | Validates new diagnostic algorithms, ensuring accuracy and regulatory compliance for AI software. |
| Expand Multi-Modality Offerings | Streamlines quality assurance workflows for hospitals using diverse imaging equipment. |
| Acquire Advanced Material Specialists | Secures proprietary access to cutting-edge tissue-equivalent materials for next-gen phantoms. |
| Target Emerging Market Compliance | Captures growth in regions like Brazil as local regulatory standards for medical devices tighten. |
| Integrate with Imaging Equipment OEMs | Establishes phantoms as essential components within broader diagnostic system packages. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this market analysis. Primary interviews with radiologists, biomedical engineers, quality assurance managers, and R&D scientists provided crucial qualitative insights. This approach combined bottom-up market sizing with top-down validation against industry reports and academic journals.
The data-stream reconciliation process integrated various market dimensions across the analysis window. Segmentation dimensions modeled included product type, application, technology, end-user, and regional regulatory compliance. Compound annual growth rates were derived through a proprietary statistical model, incorporating inputs such as imaging equipment installed base and regulatory adoption rates.
The model holds under current regulatory and technological development conditions; deviation in AI validation standards or material science breakthroughs would shift long-term projections. Forecasts reflect assumptions regarding continued regulatory enforcement and healthcare infrastructure investments. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
Argentina Mammography Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Contrast Agents Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
China Mammography Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
United Kingdom Mammography Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Medical Radiation Detection Market