
 Dental Sleep Medicine Market | 2026-2036
Dental Sleep Medicine Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Sleep Medicine Market Analysis
North American manufacturing capacity for custom oral appliances is reconfiguring supply dynamics across the dental sleep medicine value chain. SomnoMed leverages its digital workflow infrastructure to sustain production scale across multiple continents. ResMed anchors its position through integrated sleep-disordered breathing portfolios spanning diagnosis to therapy. Henry Schein, Inc. competes via distribution density that reaches independent dental practices with sleep medicine training support.
Dental sleep medicine encompasses the diagnosis and treatment of sleep-disordered breathing through oral appliance therapy, typically employing mandibular repositioning devices fabricated from medical-grade polymethyl methacrylate or copolymer materials with adjustable titration mechanisms. The field bridges dental prosthodontics with polysomnography-driven sleep medicine, delivering non-surgical intervention primarily for obstructive sleep apnea and primary snoring. Oral appliances command the product type landscape due to superior patient adherence compared to positive airway pressure modalities, while sleep clinics represent the fastest-expanding end user channel as integrated care models consolidate diagnosis and device fitting. Obstructive sleep apnea applications concentrate the majority of clinical utilization and reimbursement authorization, though snoring disorders present accessible entry points for general dental practitioners.
FDA 510(k) premarket notification requirements govern oral appliance clearance in the United States, while the EU Medical Device Regulation imposes strengthened clinical evidence standards for mandibular advancement devices marketed in Europe. The American Academy of Sleep Medicine clinical practice guidelines and Medicare Local Coverage Determinations shape reimbursement accessibility and prescriber behavior across key markets. Stakeholders must monitor evolving dental board scope-of-practice regulations and sleep medicine credentialing requirements that determine provider eligibility and market addressability.
Market Dynamics
The dental sleep medicine market is restructuring around digital manufacturing workflows that compress fabrication timelines from weeks to days while reducing labor dependency in dental laboratories.
Growth Catalysts
- FDA 510(k) Streamlining:The premarket notification pathway for mandibular advancement devices accelerates clearance timelines, enabling faster commercialization of novel oral appliance designs.
- Sleep Clinic Integration:Integrated care models combining polysomnography with same-day oral appliance fitting expand addressable patient populations beyond traditional CPAP-intolerant cohorts.
- Biocompatible Copolymer Advances:Medical-grade thermoplastic elastomers with adjustable titration mechanisms improve patient comfort metrics and reduce device return rates.
Market Restraints
- Reimbursement Fragmentation:Medicare Local Coverage Determinations vary by jurisdiction, creating authorization complexity that delays patient access to oral appliance therapy.
- Polymethyl Methacrylate Cost Volatility:Acrylic resin supply chains concentrate among specialty chemical producers, exposing device manufacturers to input price swings.
- Positive Airway Pressure Substitution:Auto-titrating CPAP devices with humidification and pressure relief algorithms retain first-line status for severe obstructive sleep apnea cases.
Strategic Opportunities
- Pediatric Sleep-Disordered Breathing:Craniofacial growth modification protocols for adolescent obstructive sleep apnea represent an underserved application with limited approved interventions.
- Remote Monitoring Convergence:Integration of embedded sensors with cloud-based adherence tracking enables outcome-based reimbursement models.
- General Dental Practice Penetration:American Academy of Dental Sleep Medicine certification expansion creates qualified prescriber density in suburban and rural markets.
Industry Challenges
- Polysomnography Interpretation Training:Dental practitioners require cross-credentialing in sleep medicine diagnostics to meet collaborative care standards.
- CAD/CAM Capital Intensity:Intraoral scanner and milling system investments strain independent dental laboratories transitioning from analog workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Sleep Medicine Market |
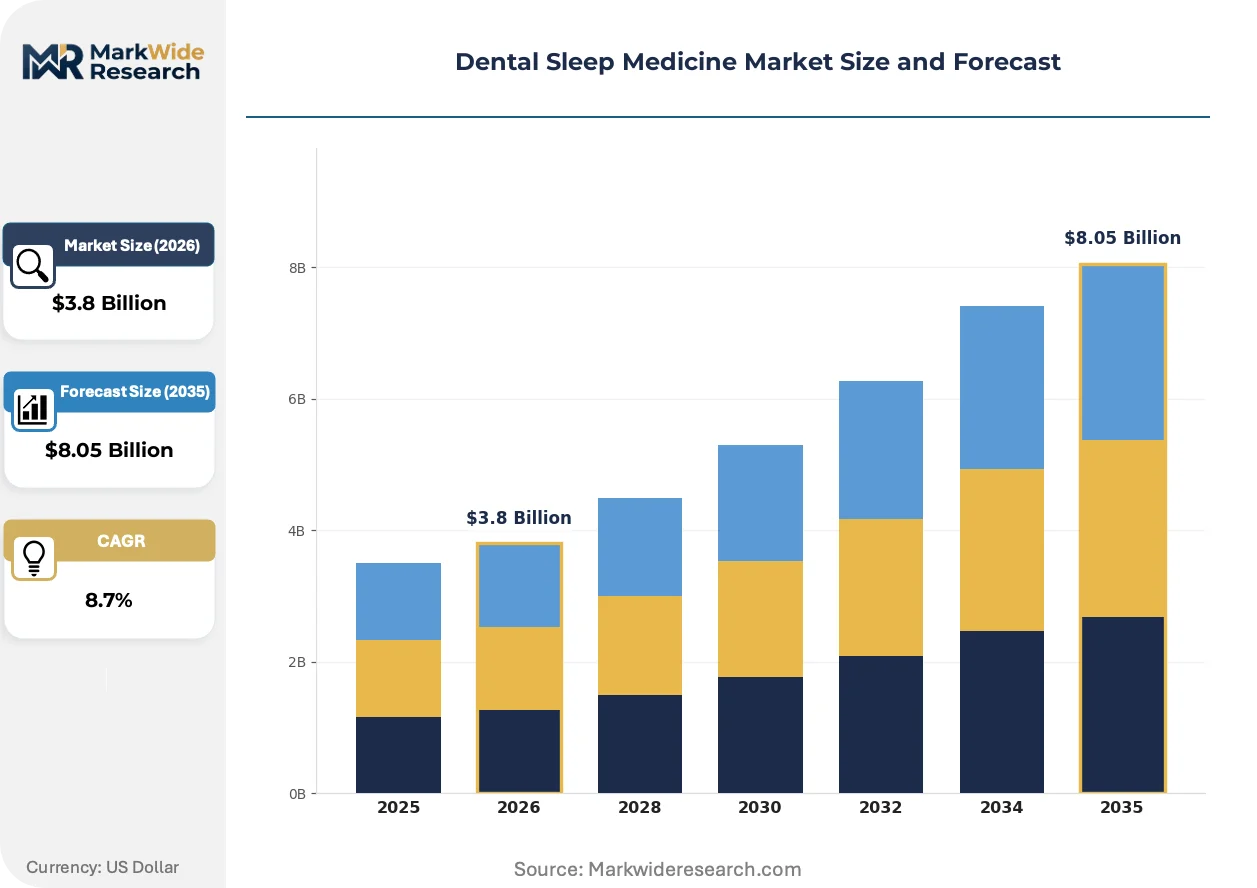
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Oral Appliances, CPAP Devices, Bi-Level Devices, Accessories End User: Dentists, Sleep Clinics, Hospitals, Home Care Providers Distribution Channel: Online, Retail Pharmacies, Medical Supply Stores, Direct Sales Application: Obstructive Sleep Apnea, Snoring Disorders, Sleep Disorders Diagnosis, Oral Health |
| Companies Covered | SomnoMed, Henry Schein, Inc., ResMed, Braebon Medical Corporation, Drive DeVilbiss Healthcare, Koninklijke Philips N.V., ProSomnus Inc., Apex Dental Sleep Lab, Fisher & Paykel Healthcare Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Sleep Medicine Market Emerging Trajectories
Digital dentistry infrastructure is reconfiguring how oral appliances move from prescription to patient, with cloud-based design platforms and distributed manufacturing nodes replacing centralized laboratory networks.
Intraoral scanning technology is migrating from high-volume prosthodontic practices into sleep medicine workflows, with sleep clinics and general dental offices adopting chairside capture systems to eliminate physical impression shipping. The technology compresses turnaround times from two weeks to seventy-two hours. This shift is migrating from premium metropolitan practices toward mid-market independent dentists, forcing traditional dental laboratories to reposition as digital design centers or risk disintermediation.
The EU Medical Device Regulation strengthened clinical evidence requirements for mandibular advancement devices marketed in Europe, mandating post-market surveillance systems and notified body recertification. Manufacturers must now compile clinical data packages beyond traditional equivalence arguments. Small and mid-sized device producers face compliance cost burdens that favor larger competitors with established quality management systems.
Patient preference for non-tethered sleep solutions is compressing switching cycles between positive airway pressure and oral appliance modalities. Sleep medicine practices report accelerated device trials as patients seek alternatives to mask-based therapy. This pattern concentrates in United States markets where high-deductible health plans increase out-of-pocket sensitivity to equipment costs and replacement schedules.
Dental Sleep Medicine Market Segmentation
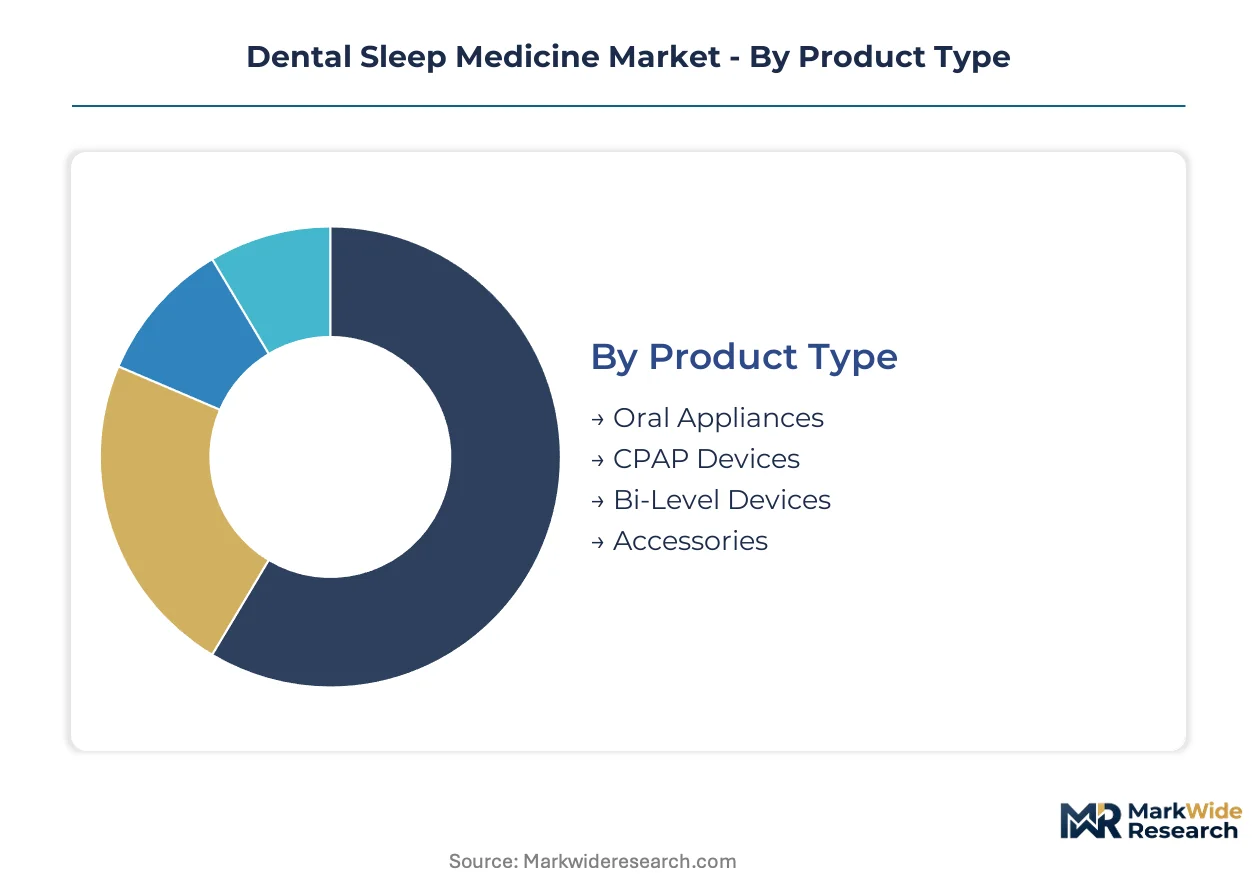
Segmentation in dental sleep medicine reveals distinct procurement patterns across clinical settings and patient acuity levels. Device specifications, reimbursement pathways, and prescriber credentialing requirements vary sharply by product category and end-user type.
Product Type:
Mature mandibular repositioning platforms coexist with emerging sensor-integrated designs across the maturity spectrum.
- Oral Appliances:Mandibular advancement devices fabricated from medical-grade polymethyl methacrylate or copolymer materials with adjustable titration mechanisms. Demand concentrates in United States sleep clinics as first-line intervention for mild-to-moderate obstructive sleep apnea, driven by superior patient adherence versus positive airway pressure modalities.
- CPAP Devices:Auto-titrating positive airway pressure systems with humidification and pressure relief algorithms. United States hospital sleep centers anchor procurement volume for severe obstructive sleep apnea cases where oral appliance efficacy drops, constrained by patient intolerance rates and mask fit complications.
- Bi-Level Devices:Bilevel positive airway pressure systems delivering distinct inspiratory and expiratory pressure settings.
- Accessories:Replacement cushions, tubing assemblies, cleaning systems, and compliance monitoring peripherals.
Oral appliances handle the majority of throughput; CPAP devices are expanding most quickly in integrated diagnostic-therapy models.
End User:
Volume concentration shifts from hospital-based polysomnography toward outpatient channels with lower capital overhead.
- Sleep Clinics:Integrated diagnostic and therapeutic facilities combining polysomnography with same-day oral appliance fitting. United States metropolitan markets show steepest expansion trajectory as collaborative care models consolidate under single-roof operations, reducing patient navigation friction.
- Dentists:General and prosthodontic practices with American Academy of Dental Sleep Medicine certification. Suburban United States markets concentrate demand growth as certification programs expand qualified prescriber density beyond traditional sleep medicine specialists.
- Hospitals:Academic medical centers and community hospital sleep disorder centers with full diagnostic capabilities.
- Home Care Providers:Durable medical equipment suppliers managing device delivery and adherence monitoring.
Sleep clinics capture the steepest share gains; dentists handle the largest absolute prescription volume for oral appliances specifically.
Distribution Channel:
Margin structure varies from high-touch direct sales to low-overhead digital fulfillment.
- Direct Sales:Manufacturer field representatives contracting with sleep clinics and hospital systems. United States group purchasing organizations concentrate procurement leverage, compressing unit economics for device producers without established institutional contracts.
- Medical Supply Stores:Specialty durable medical equipment distributors with respiratory therapy expertise. United States regional chains maintain inventory depth for same-day patient fittings, though digital workflows are eroding this advantage.
- Online:E-commerce platforms and manufacturer-direct portals with remote fitting support.
- Retail Pharmacies:Chain and independent pharmacy networks with limited sleep medicine inventory.
Direct sales handles the majority of high-acuity device throughput; online channels are climbing the fastest on accessory and replacement volume.
Application:
Clinical utilization concentrates where reimbursement authorization pathways are clearest.
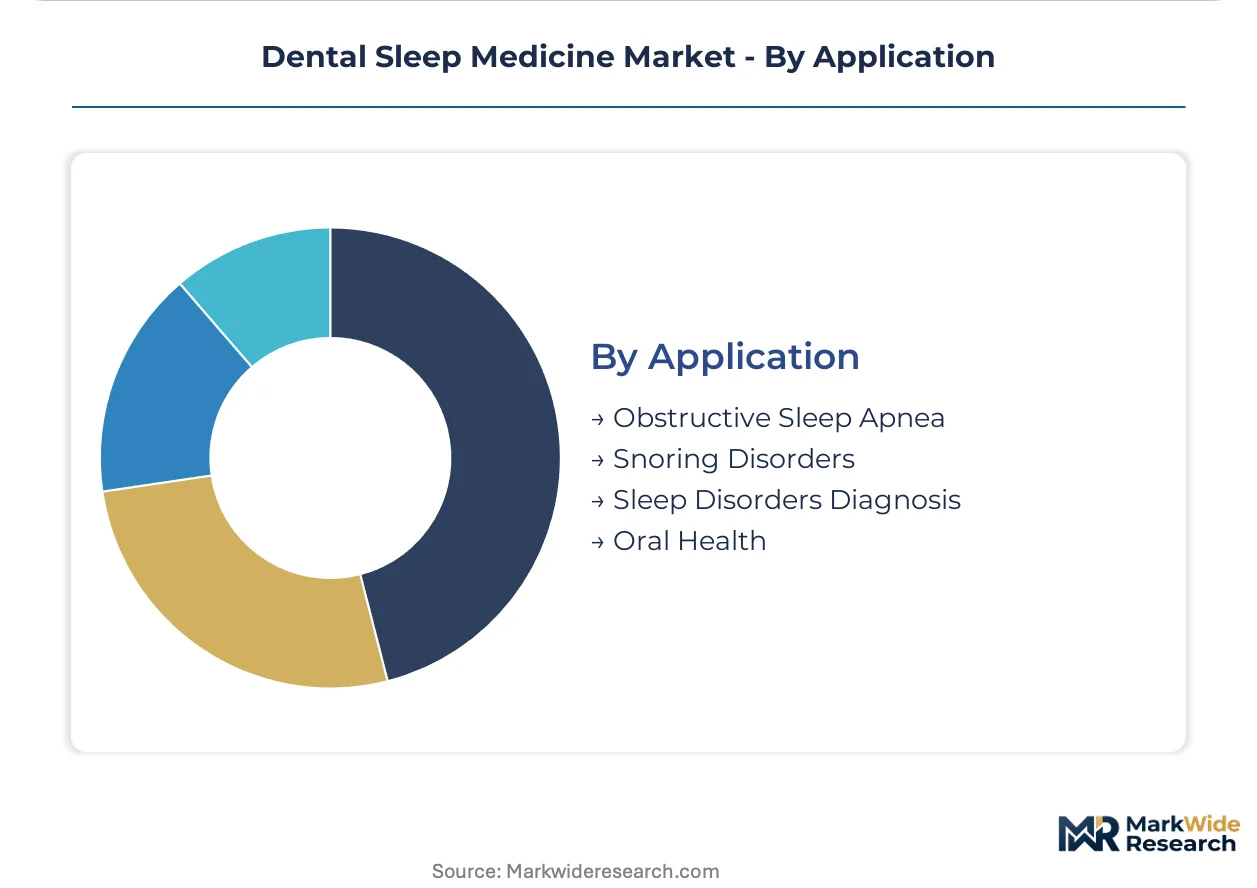
- Obstructive Sleep Apnea:Primary indication for mandibular advancement devices and positive airway pressure systems. United States Medicare Local Coverage Determinations shape prescriber behavior, with prior authorization requirements varying by jurisdiction and severity classification.
- Snoring Disorders:Primary snoring without documented apnea represents accessible entry point for general dental practitioners. United States cash-pay markets concentrate demand as insurance reimbursement excludes purely symptomatic treatment, driving direct-to-consumer marketing intensity.
- Sleep Disorders Diagnosis:Polysomnography and home sleep apnea testing services.
- Oral Health:Temporomandibular joint considerations and dental occlusion management in appliance therapy.
Obstructive sleep apnea handles the majority of reimbursed throughput; snoring disorders are gaining share fastest in cash-pay and direct-access models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Interstate 95 corridor's dense concentration of sleep medicine centers underwrites the United States' outsized role in dental sleep medicine demand generation and device innovation.
United States
FDA 510(k) clearance pathways for mandibular advancement devices accelerate commercialization timelines for domestic manufacturers. Medicare Local Coverage Determinations vary by jurisdiction, creating authorization complexity that shapes prescriber behavior across state lines. The Boston-to-Washington corridor concentrates sleep clinic expansion and dental sleep medicine certification programs.
Germany
The EU Medical Device Regulation imposes strengthened clinical evidence standards for mandibular advancement devices marketed across member states. German dental laboratories are migrating toward CAD/CAM workflows to compress fabrication timelines for custom oral appliances. The Rhine-Ruhr metropolitan region anchors manufacturing capacity for medical-grade polymethyl methacrylate components.
Japan
PMDA regulatory frameworks govern oral appliance approval pathways with distinct clinical data requirements from Western markets. METI industrial policy supports digital dentistry infrastructure deployment across prosthodontic practices. The Kanto region surrounding Tokyo concentrates sleep medicine specialist density and polysomnography capacity.
United Kingdom
NICE clinical guidelines shape National Health Service reimbursement authorization for obstructive sleep apnea interventions. Post-Brexit regulatory divergence from EU MDR frameworks creates dual compliance obligations for device manufacturers. London and the Southeast England corridor concentrate private sleep clinic investment and dental sleep medicine training programs.
Australia
TGA medical device regulations require local conformity assessment for imported mandibular advancement devices. The country's national pharmaceutical regulator maintains distinct evidentiary standards for oral appliance therapeutic claims. Sydney and Melbourne anchor sleep medicine practice consolidation and dental sleep medicine certification expansion.
Dental Sleep Medicine Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in a market structure that fragments across device fabrication, distribution density, and diagnostic-therapy integration. The competitive terrain separates vertically integrated sleep-disordered breathing portfolios from focused oral appliance manufacturers and dental supply distributors. Three archetypes dominate: digital workflow platform operators, medical-grade polymer device fabricators, and practice-facing distribution networks. M&A activity concentrates on digital dentistry infrastructure assets, while strategic partnerships bridge sleep clinic operators with dental laboratory networks.
Among platform integrators, ResMed occupies a position exemplifying diagnostic-to-therapy portfolio breadth, while SomnoMed represents the digital workflow archetype with multi-continental production scale. Henry Schein, Inc. anchors the distribution-intensive tier, reaching independent dental practices with sleep medicine training support.
| Leading Market Players |
|---|
| SomnoMed |
| Henry Schein, Inc. |
| ResMed |
| Braebon Medical Corporation |
| Drive DeVilbiss Healthcare |
| Koninklijke Philips N.V. |
| ProSomnus Inc. |
| Apex Dental Sleep Lab |
| Fisher & Paykel Healthcare Limited |
| Others |
Supply Flow & Price Mechanics
The Port of Los Angeles-Long Beach freight corridor's congestion-driven rate volatility compresses margins for medical-grade polymer shipments, amplifying cost differentiation between United States domestic fabricators and offshore competitors while forcing tiered pricing stratification across premium FDA-cleared devices, standard CE-marked alternatives, and economy-grade direct-to-consumer appliances.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Medicare-reimbursed mandibular advancement devices from cash-pay dental alternatives and direct-access snoring appliances. Price differentiation hinges on FDA 510(k) clearance tier and sleep clinic distribution density. Cost compression in the economy tier intensifies because Asian manufacturers bypass domestic laboratory networks. Hospital sleep centers show lowest price sensitivity; independent dental practices face highest out-of-pocket equipment constraints.
Supply Chain Analysis
Medical-grade polymethyl methacrylate feedstock concentrates among German, Japanese, and United States specialty chemical producers, with copolymer elastomer formulations anchored in South Korean and Belgian manufacturing sites. Device fabrication draws from dental laboratory networks in the United States, Germany, and Australia, though digital workflows are disintermediating traditional nodes. Single-source vulnerability sits with acrylic resin suppliers exposed to petrochemical price swings. Distribution runs through manufacturer field representatives and dental supply distributors reaching certified practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified dental sleep medicine practitioners represent the scarcest capability layer, with American Academy of Dental Sleep Medicine certification bottlenecks constraining addressable market expansion faster than device manufacturing capacity can respond.
For Market Incumbents: Insulate market position by deepening backward integration into medical-grade polymer compounding to neutralize acrylic resin cost volatility, while expanding proprietary CAD/CAM platform licensing to independent dental laboratories threatened by chairside scanner displacement from sleep clinics and general practices. For New Entrants and Emerging Players: Suburban United States dental practices without sleep medicine certification represent the most penetrable entry point, offering training-partnership routes that bypass saturated metropolitan sleep clinic channels. Pediatric craniofacial growth modification protocols deliver uncontested white-space positioning with limited approved interventions. For Investors and Strategic Acquirers: Digital workflow platform operators with multi-continental laboratory networks present the highest-value acquisition archetype, capturing infrastructure assets that compress fabrication timelines from weeks to days. Watch FDA 510(k) clearance velocity for novel sensor-integrated designs as the inflection signal indicating platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates commercialization timelines for mandibular advancement device manufacturers seeking United States market entry. |
| Digital Workflow Platform Integration | Enables sleep clinics to execute same-day oral appliance fitting, collapsing traditional laboratory turnaround cycles. |
| American Academy of Dental Sleep Medicine Certification Expansion | Builds qualified prescriber density in suburban and rural United States markets beyond traditional specialist concentration. |
| Remote Monitoring Sensor Development | Creates cloud-based adherence tracking infrastructure for outcome-based reimbursement authorization with Medicare. |
| Biocompatible Copolymer Material Advancement | Improves patient comfort metrics and reduces device return rates through adjustable titration mechanism refinement. |
Methodological Framework
A spread of perspectives from dental sleep medicine clinicians, American Academy of Dental Sleep Medicine certification directors, hospital purchasing committee members, biomedical engineers at oral appliance manufacturers, and durable medical equipment distribution executives converged on the working assumptions. Primary interview insights combined with secondary validation from FDA 510(k) clearance databases, Medicare Local Coverage Determination filings, dental laboratory industry association reports, and medical device trade customs records. Bottom-up prescription volume modeling and top-down market sizing triangulated across the analysis window.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product type, end user channel, application severity, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to base-year estimates. Forecast inputs incorporated polysomnography capacity expansion trajectories and dental sleep medicine certification program graduation rates as industry-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in United States Medicare reimbursement rates, EU Medical Device Regulation compliance cost inflation, or medical-grade polymer feedstock pricing would shift the trajectory. Cross-checking against American Academy of Sleep Medicine clinical practice guideline revisions is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sleep Medicine
Asia Pacific Sleep Tech Devices Market
Sleep Medicine
Parasomnia Treatment Market
Sleep Medicine
Excessive Daytime Sleepiness Market
Sleep Medicine
Sleeping Bruxism Treatment Market
Sleep Medicine
Hypoventilation Management Market
Sleep Medicine
Sleep Aid Devices Market
Sleep Medicine
Global Sleep Tech Devices Market
Sleep Medicine
Sleep Studies Market
Sleep Medicine
Sleep Soother Market
Sleep Medicine
Idiopathic Hypersomnia (IH) Treatment Market
Sleep Medicine
Global Hypersomnia Treatment Market
Sleep Medicine
Asia Pacific Insomnia Market
Sleep Medicine
Sleep Movement Disorders Market
Sleep Medicine
Sleep Screening Devices Market
Sleep Medicine
Americas Insomnia Market
Sleep Medicine
Insomnia Market