
 Angiography Imaging Systems Market | 2026-2036
Angiography Imaging Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Angiography Imaging Systems Market Outlook
High-resolution flat-panel detector specifications is collapsing the installed base of legacy image intensifier systems across developed markets. Siemens Healthineers leverages in-house detector manufacturing to sustain margin control on premium system configurations. GE Healthcare anchors North American service contracts through its extensive field engineering network. Canon Medical Systems Corporation differentiates via specialized cardiovascular imaging protocols that reduce contrast dye volumes.
Angiography imaging systems employ X-ray fluoroscopy with iodinated contrast media to visualize vascular anatomy during interventional procedures, typically operating at 15-30 frames per second with spatial resolution below 200 micrometers. Catheterization systems dominate current revenue pools due to their centrality in percutaneous coronary intervention workflows, while 3D imaging technology represents the fastest-expanding segment as rotational angiography enables intraoperative three-dimensional roadmapping without patient transfer. Digital technology platforms command premium positioning over analog and hybrid configurations, with hospitals representing the most concentrated end-user channel despite outpatient clinics capturing growing procedural volumes.
FDA 510(k) premarket notification requirements govern system clearance in the United States, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards for Class IIa and above devices across European markets. Japan's Pharmaceuticals and Medical Devices Agency (PMDA) maintains distinct quality management system inspections that shape market access timelines for foreign manufacturers. Stakeholders must monitor convergence between AI-enabled image guidance and regulatory frameworks for software-as-medical-device classifications.
Market Dynamics
Flat-panel detector technology is collapsing the installed base of legacy image intensifier systems across developed markets, forcing replacement cycles and compressing margins for manufacturers lacking in-house detector fabrication capabilities.
Growth Catalysts
- Aging demographics in Japan, Germany, and the United States:Expanding elderly populations require escalating volumes of percutaneous coronary intervention and peripheral vascular procedures, sustaining equipment replacement demand in tertiary cardiac catheterization laboratories.
- FDA 510(k) clearance pathways for AI-enhanced image reconstruction:Streamlined premarket notification processes compress time-to-market for algorithm-integrated angiography platforms, accelerating commercialization of next-generation systems.
- Rotational angiography enabling intraoperative 3D roadmapping:Three-dimensional imaging protocols eliminate patient transfer requirements during complex interventional procedures, driving premium positioning for digital technology configurations.
Market Restraints
- Capital intensity of flat-panel detector manufacturing:Concentrated supply of amorphous silicon and cesium iodide scintillator materials among Asian component fabricators creates input cost volatility and margin pressure for system assemblers.
- EU Medical Device Regulation clinical evidence requirements:Stricter MDR standards for Class IIa and above devices impose extended certification timelines and documentation burdens on manufacturers seeking European market access.
- Limited substitutability for iodinated contrast media:Persistent reliance on nephrotoxic contrast agents in X-ray fluoroscopy workflows constrains procedural expansion among chronic kidney disease patient populations.
Strategic Opportunities
- Outpatient clinic channel expansion:Ambulatory surgical centers in the United States capture growing shares of diagnostic angiography volumes, creating demand for compact, mobile-compatible system configurations.
- Software-as-medical-device regulatory convergence:Emerging frameworks for AI-enabled image guidance classification in Japan and the United States open pathways for algorithm-centric revenue models beyond hardware sales.
- Contrast volume reduction protocols:Specialized cardiovascular imaging sequences that minimize iodinated dye administration address nephrology concerns and expand addressable patient populations.
Industry Challenges
- Field service engineer scarcity:Maintenance of digital subtraction angiography platforms demands hybrid skill sets spanning X-ray physics, software diagnostics, and detector calibration that outpace vocational training pipeline outputs.
- Legacy system integration complexity:Hospital information system connectivity requirements and PACS interoperability standards create friction during digital platform deployments in mixed-technology catheterization laboratories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Angiography Imaging Systems Market |
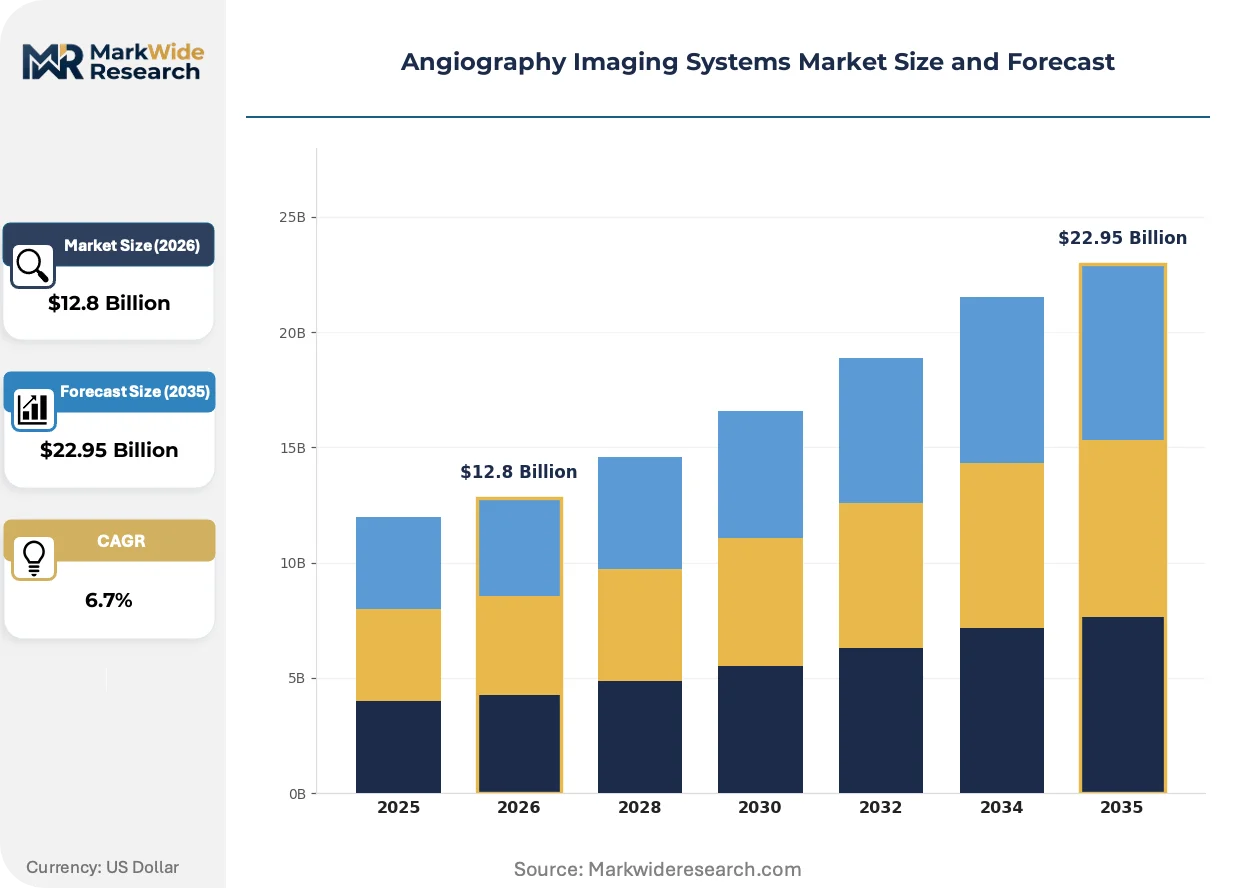
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fluoroscopy Systems, Catheterization Systems, MRI Systems, CT Angiography Systems End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Technology: Digital, Analog, Hybrid, 3D Imaging Application: Cardiology, Neurology, Oncology, Peripheral Vascular |
| Companies Covered | GE Healthcare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Boston Scientific Corporation, Medtronic plc, Shimadzu Corporation, Abbott Laboratories, AngioDynamics, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Angiography Imaging Systems Market Strategic Shifts
Artificial intelligence integration is fundamentally restructuring competitive positioning in angiography imaging, compressing the value chain from hardware manufacturing toward algorithm development and clinical workflow optimization.
Photon-counting detector technology is displacing conventional energy-integrating flat-panel architectures in premium system configurations. Tertiary hospital cardiac catheterization laboratories in Germany and Japan are piloting these platforms for reduced radiation dose and improved soft-tissue contrast. This displacement is collapsing the premium pricing power of manufacturers dependent on legacy scintillator-based detector supply chains.
Japan's Pharmaceuticals and Medical Devices Agency has tightened quality management system inspection protocols for foreign-manufactured angiography systems. These PMDA requirements extend market access timelines by six to twelve months for non-domestic applicants. European and North American manufacturers are responding by establishing local technical documentation subsidiaries and Japan-specific regulatory affairs functions.
Service contract unbundling is accelerating as hospital procurement departments separate hardware acquisition from maintenance agreements. Academic medical centers in the United States increasingly negotiate multi-vendor service arrangements or insource preventive maintenance through biomedical engineering departments. This behavioral shift is most visible in metropolitan hospital systems with centralized capital equipment procurement functions.
Angiography Imaging Systems Market Segmentation
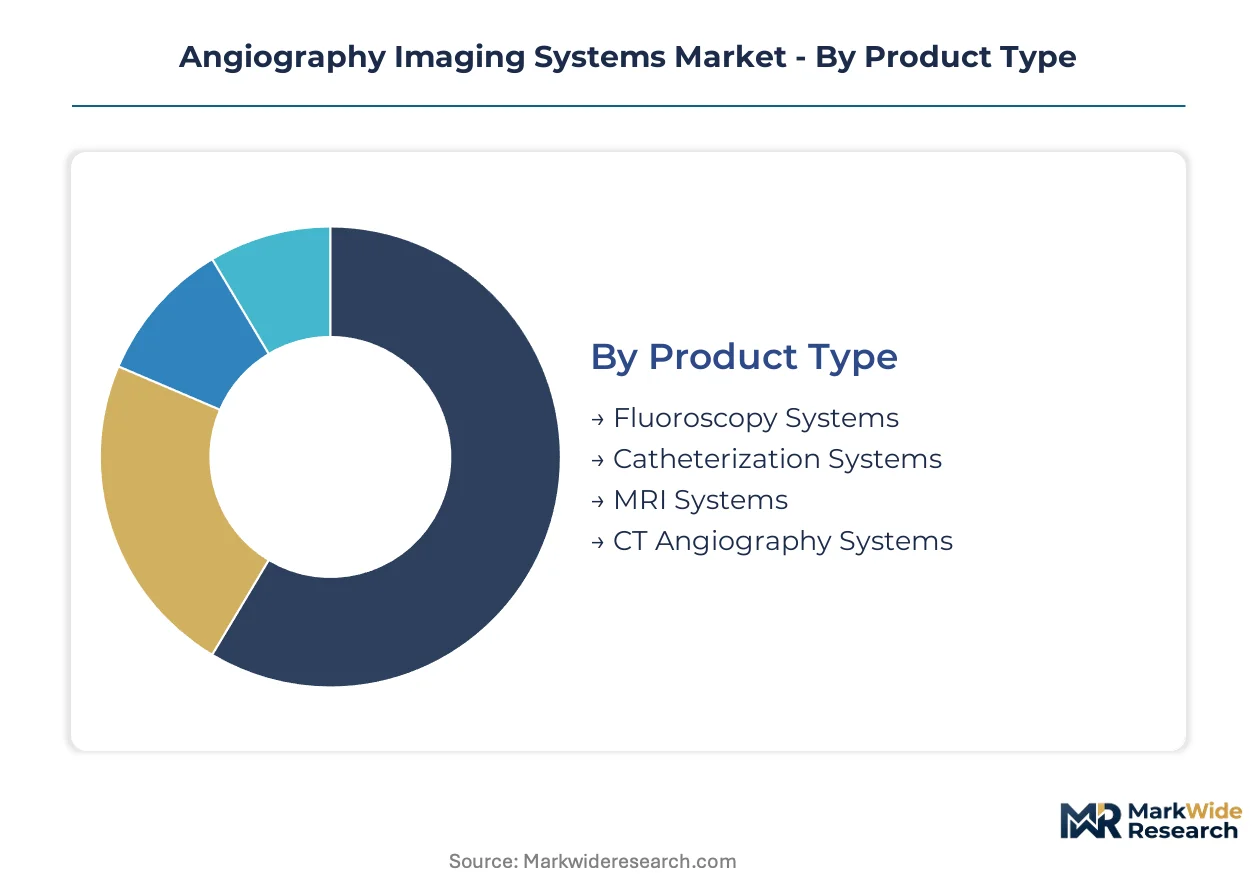
Angiography imaging systems fragment across four critical dimensions that determine procurement patterns and margin structures. Product type and technology choices dictate capital intensity, while end-user channel and application specificity shape service contract terms and software licensing models.
Product Type:
Substitution pressure intensifies between catheterization platforms and CT angiography systems as hospitals evaluate workflow efficiency against capital outlay requirements.
- Catheterization Systems:These integrated X-ray fluoroscopy platforms with motorized C-arm geometry dominate interventional cardiology suites. Demand concentrates in tertiary hospitals across the United States, Germany, and Japan where PCI volumes sustain premium digital configurations and 24/7 service coverage requirements.
- CT Angiography Systems:Multidetector computed tomography platforms with cardiac gating capabilities offer non-invasive vascular assessment. Diagnostic centers in metropolitan United States markets favor these systems for outpatient throughput, though iodinated contrast requirements and radiation dose concerns constrain expansion in chronic kidney disease populations.
- Fluoroscopy Systems:Mobile C-arm units with flat-panel detectors serve hybrid operating rooms and emergency departments requiring intraoperative imaging flexibility.
- MRI Systems:Magnetic resonance angiography platforms eliminate ionizing radiation exposure but face longer acquisition times and contraindication restrictions that limit interventional utility.
Catheterization systems retain volume leadership; CT angiography holds the steepest expansion curve.
End User:
Channel cost structures diverge sharply as procurement sophistication varies across facility types and reimbursement environments.
- Hospitals:Integrated delivery networks with centralized biomedical engineering departments negotiate multi-system contracts and demand 99.5% uptime guarantees. These institutions in the United States, Germany, and Japan anchor replacement cycles for premium digital subtraction angiography platforms.
- Outpatient Clinics:Ambulatory surgical centers capture shifting diagnostic angiography volumes from inpatient settings. United States metropolitan markets show particular concentration where Medicare reimbursement for ASC-based procedures creates favorable economics for compact, mobile-compatible system configurations.
- Diagnostic Centers:Independent imaging facilities prioritize throughput metrics and lease financing structures over capital purchase arrangements.
- Research Institutions:Academic medical centers drive early adoption of photon-counting detector technology and AI-enhanced reconstruction algorithms through investigator-initiated studies.
Hospitals dominate absolute installed base; outpatient clinics are expanding most quickly.
Technology:
Platform maturity gradients separate legacy analog infrastructure from digitally native architectures that command pricing premiums.
- Digital:Flat-panel detector systems with amorphous silicon or cesium iodide scintillator layers deliver 15-30 frames per second fluoroscopy with sub-200 micrometer spatial resolution. These platforms command premium positioning across developed markets as image intensifier obsolescence accelerates replacement demand.
- 3D Imaging:Rotational angiography systems with cone-beam CT reconstruction enable intraoperative three-dimensional roadmapping. Tertiary cardiac catheterization laboratories in Germany and Japan pilot these configurations to eliminate patient transfer during complex structural heart interventions.
- Hybrid:Dual-modality systems combining angiography with intravascular ultrasound or optical coherence tomography face integration complexity that extends installation timelines.
- Analog:Image intensifier-based systems persist in emerging markets and rural facilities where capital constraints override image quality requirements.
Digital platforms anchor revenue concentration; 3D imaging is climbing the fastest.
Application:
Clinical workflow specificity determines software protocol customization and contrast agent utilization patterns that shape operating economics.
- Cardiology:Percutaneous coronary intervention workflows demand 30 frames per second acquisition rates and specialized cardiac gating algorithms. These applications concentrate demand in the United States and Japan where aging demographics and stable reimbursement sustain equipment refresh cycles in high-volume catheterization laboratories.
- Peripheral Vascular:Lower-extremity and carotid interventions require extended field-of-view capabilities and specialized table positioning. Outpatient clinics in the United States increasingly perform these procedures, driving demand for systems with reduced footprint and simplified operator interfaces.
- Neurology:Neurointerventional procedures for stroke and aneurysm treatment demand biplane geometry and high-resolution roadmap subtraction.
- Oncology:Tumor embolization and chemoembolization procedures utilize angiography for delivery confirmation, though oncology-specific software protocols remain less differentiated than cardiovascular applications.
Cardiology commands installed base dominance; peripheral vascular is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net trade flows in angiography imaging systems favor established manufacturing hubs over emerging assembly locations, with component fabrication concentrated in East Asia and system integration anchored in Western Europe and North America.
United States
Medicare reimbursement stability for cardiac catheterization procedures sustains replacement demand in tertiary hospitals. FDA 510(k) premarket notification pathways compress regulatory timelines for AI-enhanced reconstruction algorithms. The Cleveland Clinic and Mayo Clinic anchor early adoption of photon-counting detector platforms through investigator-initiated studies.
Germany
Aging demographics and statutory health insurance coverage for PCI procedures drive equipment refresh cycles in university hospitals. EU Medical Device Regulation imposes extended clinical evidence requirements for Class IIa angiography systems. The Munich-Berlin corridor concentrates catheterization laboratory procurement decisions for integrated delivery networks.
Japan
PMDA quality management system inspections extend market access timelines for foreign manufacturers by six to twelve months. Super-aging society demographics sustain procedural volumes in cardiovascular interventions. Tokyo-Osaka metropolitan areas pilot rotational angiography configurations for structural heart procedures.
China
Domestic substitution policies accelerate local manufacturing of flat-panel detector components under NMPA oversight. Provincial centralized procurement programs compress pricing premiums for imported systems. The Yangtze River Delta region concentrates hospital group purchasing organization headquarters directing multi-facility equipment tenders.
India
CDSCO medical device rules impose registration requirements on angiography system imports while domestic production incentives expand under PLI schemes. Private hospital chains in metropolitan markets drive demand for refurbished digital subtraction platforms. Maharashtra and Karnataka states anchor cardiac care network expansion into tier-two cities.
Angiography Imaging Systems Market Competitive Environment
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded conglomerates commanding premium positioning through integrated detector manufacturing while private specialists carve niches in mobile C-arm configurations. Siemens Healthineers and GE Healthcare anchor the consolidated tier through captive supply chains and extensive field service networks. Three archetypes dominate: diversified medical technology conglomerates with in-house detector fabrication, imaging specialists leveraging cardiovascular protocol differentiation, and interventional device manufacturers bundling systems with consumable ecosystems. Competitive moves concentrate on M&A for AI algorithm portfolios and strategic partnerships for photon-counting detector supply.
Among diversified conglomerates, Siemens Healthineers and GE Healthcare exemplify scale-driven archetypes with integrated manufacturing footprints. Canon Medical Systems Corporation occupies a position within the imaging specialist tier, differentiated by protocol-level software capabilities. Koninklijke Philips N.V. sits within the interventional ecosystem bundling archetype, representing convergence between device and imaging platform strategies.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Boston Scientific Corporation |
| Medtronic plc |
| Shimadzu Corporation |
| Abbott Laboratories |
| AngioDynamics, Inc. |
| Others |
Value Chain & Pricing Dynamics
Photon-counting detector substitution for conventional energy-integrating flat-panel architectures is redrawing supply geography toward specialized semiconductor foundries while collapsing premium pricing tiers previously sustained by legacy scintillator-based detector supply chains. This displacement simultaneously compresses margins for assemblers lacking captive detector fabrication and redirects procurement power toward buyers with technical specification sophistication.
Pricing Analysis
Hospital procurement departments anchor a three-tier pricing structure across premium, standard, and economy levels, with integrated delivery networks extracting volume discounts through multi-system contracts. Price differentiation hinges on detector resolution specifications and FDA 510(k) clearance status for AI-enhanced reconstruction modules. Pricing pressure stems from provincial centralized procurement programs in China compressing premiums for imported configurations. Academic medical centers demonstrate lowest price sensitivity due to investigator-initiated study budgets, while outpatient clinics in United States metropolitan markets exhibit highest sensitivity to capital outlay requirements.
Supply Chain Analysis
Strategic stockpiling of amorphous silicon and cesium iodide scintillator materials persists among Japanese and German system integrators buffering against Asian component fabricator lead time volatility. Supply concentration rests on Taiwan and South Korea for flat-panel detector substrates, Germany for precision C-arm mechanical assemblies, and Japan for high-voltage X-ray tube manufacturing. Raw material dependencies include rare earth phosphors, tungsten-rhenium target materials, and medical-grade aluminum housings. Single-source vulnerability characterizes photon-counting detector semiconductor supply. Distribution runs through direct manufacturer sales forces for tertiary hospital contracts and specialized imaging equipment distributors for outpatient clinic channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hybrid skill scarcity spanning X-ray physics, software diagnostics, and detector calibration outpaces vocational training pipeline outputs, constraining field service scalability and amplifying maintenance contract pricing power for incumbents with established technical workforces.
For Market Incumbents: Shield premium positioning by deepening in-house production of flat-panel detector components and securing exclusive photon-counting semiconductor supply agreements. Establish Japan-specific regulatory affairs subsidiaries to compress PMDA quality management system inspection timelines. Service contract unbundling by academic medical centers threatens recurring revenue stability; counter through outcome-based uptime guarantee structures. For New Entrants and Emerging Players: Differentiate on AI-enhanced image reconstruction algorithms seeking FDA 510(k) clearance through streamlined premarket notification pathways. Ambulatory surgical centers in United States metropolitan markets represent the most penetrable channel, capturing shifting diagnostic angiography volumes from inpatient settings. Pursue software-as-medical-device revenue models decoupled from hardware manufacturing capital intensity. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed mobile C-arm specialists lacking rotational angiography capabilities. Five-to-ten year viability hinges on algorithm portfolio depth rather than detector fabrication scale. Watch for FDA 510(k) clearance velocity for AI-enhanced reconstruction platforms as inflection indicator for competitive repositioning timing.| Strategic Initiative | Industry Significance |
|---|---|
| Photon-Counting Detector Supply Agreement | Secures semiconductor allocation from Taiwan foundries ahead of rotational angiography platform launches. |
| FDA 510(k) Algorithm Submission | Compresses time-to-market for AI-enhanced image reconstruction through streamlined premarket notification. |
| Japan Regulatory Affairs Subsidiary | Reduces PMDA quality management system inspection delays for foreign manufacturers. |
| Hospital System Partnership | Locks multi-year service contracts with integrated delivery networks demanding 99.5% uptime guarantees. |
| Contrast Volume Reduction Protocol Development | Addresses nephrology concerns to expand addressable patient populations in chronic kidney disease segments. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with interventional cardiologists, catheterization laboratory directors, biomedical engineers, hospital procurement committee members, and GPO contracts managers. Secondary validation drew from FDA 510(k) premarket notification databases, PMDA quality management system inspection records, CMS Medicare reimbursement schedules, hospital procurement databases, and SEC 10-K filings of listed medical technology conglomerates. Bottom-up equipment shipment tracking and top-down healthcare capital expenditure analysis were triangulated to anchor volume estimates.
Across the projection horizon, the analytical framework modeled segmentation across product type, technology platform, end-user channel, and clinical application specificity. CAGRs were derived from replacement cycle analysis of legacy image intensifier obsolescence and procedural volume elasticity to aging demographic trends. Forecast inputs included PCI procedure volumes by country, flat-panel detector manufacturing capacity expansion announcements, and AI-enhanced reconstruction algorithm regulatory clearance trajectories.
Material uncertainties — reimbursement rate revisions, PMDA inspection protocol changes, photon-counting detector yield rates — sit outside the modeled envelope. Forecasts reflect assumptions regarding stable statutory health insurance coverage in Germany and Medicare cardiac catheterization reimbursement stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Diagnostic Imaging Equipment Market
Medical Imaging
India Ultrasound Devices Market
Medical Imaging
United States Computed Tomography Market
Medical Imaging
Portable MRI Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Multiphoton Microscopy Market
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Global Medical Cameras Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Global Spinal Imaging Treatment Market
Medical Imaging
United States Mammography Market
Medical Imaging
Cardiology PACS Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market