
 Alpha Emitter Market | 2026-2036
Alpha Emitter Market Size, Share, and Industry Trends Forecast 2026-2036
Alpha Emitter Market Intelligence
Oncology demand is consolidating around metastatic bone cancer and hematologic malignancies as the primary clinical pull for alpha emitters. Bayer AG anchors its position through Ra-223 dichloride manufacturing scale and established urology-oncology channels. Novartis AG differentiates via its radioligand therapy platform and pipeline expansion into actinium-based constructs. Actinium Pharmaceuticals specializes in Ac-225 supply chain development and generator technology for next-generation therapeutics.
Alpha emitters are high-linear-energy-transfer radionuclides that deposit intense energy over extremely short path lengths, typically 40-100 micrometers, enabling precise destruction of malignant cells while sparing adjacent healthy tissue. Their primary commercial purpose centers on targeted radionuclide therapy for cancers resistant to beta-emitter or external-beam approaches. Radium-223 dominates current revenue flows due to mature reimbursement and proven survival benefit in prostate cancer, while actinium-227 represents the fastest-expanding product type driven by antibody-radionuclide conjugate development. Therapeutic methods command the deepest margin pools as pharmaceutical companies pursue vertical control over conjugation, dosing, and patient selection protocols.
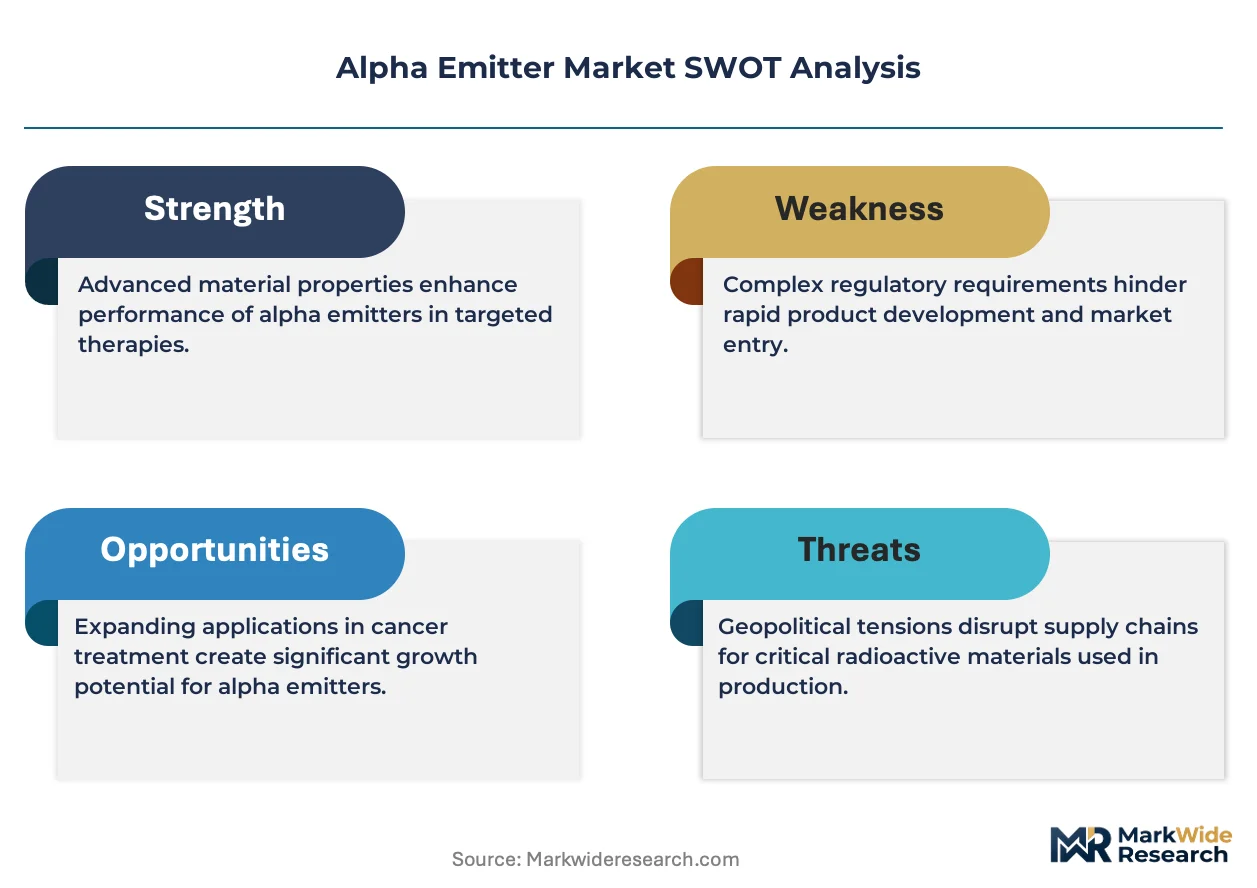
FDA and EMA frameworks govern radiopharmaceutical manufacturing, clinical trial endpoints, and post-market pharmacovigilance for alpha-emitting therapies, with both agencies accelerating review pathways for breakthrough-designated oncology agents. ISO standards and national nuclear regulators, including the NRC in the United States and BfS in Germany, impose stringent handling, transport, and waste disposal requirements that shape facility investment and geographic distribution capacity. Stakeholders must monitor regulatory convergence on alpha-therapy dosing standards and manufacturing consistency to anticipate which supply chain configurations will secure preferential market access.
Market Dynamics
Targeted alpha therapy is consolidating around metastatic bone cancer and hematologic malignancies as the central structural force, with FDA and EMA breakthrough designations compressing clinical trial timelines and reshaping competitive positioning across radiopharmaceutical supply chains.
Growth Catalysts
- Regulatory Acceleration:FDA breakthrough therapy designation and EMA priority medicines pathways compress development timelines for alpha-emitting radiopharmaceuticals, reducing time-to-market for novel constructs.
- Antibody-Radionuclide Conjugate Development:Bioconjugation chemistry advances enable precise tumor targeting with actinium-225 and lead-212, expanding addressable patient populations beyond beta-emitter limitations.
- Specialized Nuclear Medicine Infrastructure:Germany, Japan, and the United States concentrate cyclotron and reactor capacity, creating geographic anchors for clinical trial execution and commercial distribution.
Market Restraints
- Actinium-225 Supply Concentration:Thorium-229 decay chain dependency and limited high-flux reactor availability create single-source vulnerability for the fastest-expanding alpha emitter category.
- Radiation Handling Infrastructure Costs:Hot cell installation, shielded transport logistics, and specialized waste disposal impose facility investment thresholds that exclude smaller treatment centers.
- Reimbursement Uncertainty:CMS national coverage determination processes and German G-BA benefit assessments create payment lag for novel alpha therapies beyond radium-223's established pathway.
Strategic Opportunities
- Generator Technology Deployment:Ac-225/Bi-213 generator systems enable decentralized production, reducing dependency on centralized reactor supply and expanding treatment access to community oncology settings.
- Combination Therapy Protocols:Alpha emitter integration with immune checkpoint inhibitors and PARP inhibitors creates synergistic efficacy signals for resistant tumor microenvironments.
- Alpha Emitter Diagnostics Pairing:Theranostic platforms combining alpha therapy with matched PET imaging agents enable personalized dosing and patient selection, differentiating service offerings.
Industry Challenges
- Radiochemistry Talent Scarcity:GMP radiopharmaceutical manufacturing and alpha emitter handling require specialized expertise that outpaces current training program output.
- Cold Chain Integrity Requirements:Short half-lives demand precise coordination between production, transport, and administration, with temperature excursions destroying therapeutic value.
- Cross-Border Licensing Complexity:Divergent national nuclear transport regulations and import licensing create friction for multi-site clinical trials and commercial distribution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Alpha Emitter Market |
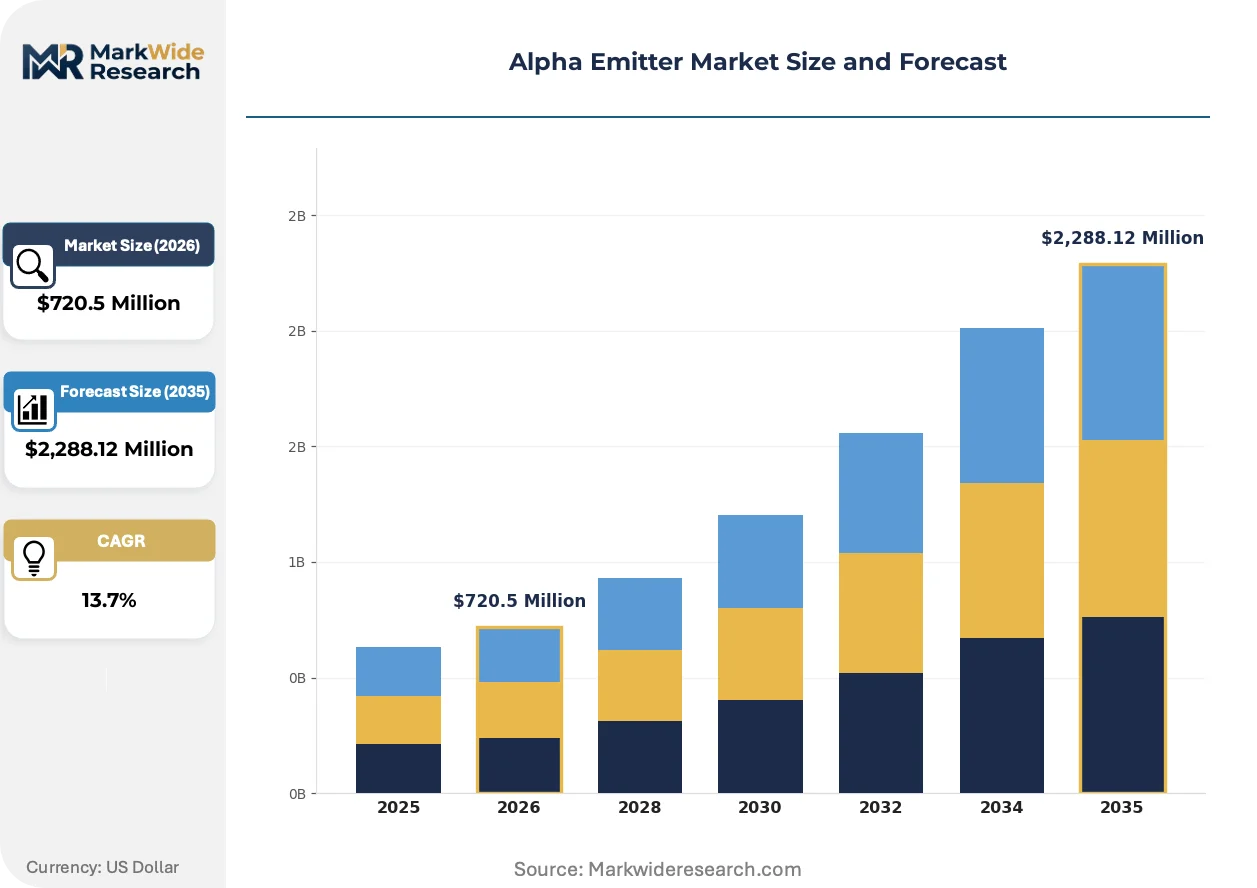
| Market Size in 2026 | $720.5 Million |
| Market Size in 2035 | $2,288.12 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radium-223, Actinium-227, Bismuth-213, Polonium-210 Application: Cancer Treatment, Industrial Radiography, Nuclear Medicine, Research Activities End User: Hospitals, Research Institutions, Nuclear Facilities, Diagnostic Centers Technology: Therapeutic Methods, Detection Systems, Imaging Techniques, Radiation Safety Equipment |
| Companies Covered | Orano Med, NorthStar Medical Radioisotopes, Bayer AG, Eckert & Ziegler, IBA Worldwide, Novartis AG, Alpha Tau Medical, Curium Pharma, Actinium Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Alpha Emitter Market Strategic Shifts & Innovations
Alpha emitter development is pivoting from single-isotope platforms toward integrated theranostic systems, with regulatory frameworks and manufacturing modalities co-evolving to support precision dosing and expanded patient access.
Ac-225 radiolabeling chemistry is integrating automated synthesis modules that standardize chelation efficiency and reduce batch-to-batch variability. Academic medical centers and contract manufacturing organizations are adopting these systems to support multi-patient dosing from single generator elutions. This integration is compressing production timelines and enabling same-day therapy administration that was previously logistically impossible.
EMA's revised radiopharmaceutical guidance and FDA's emerging technology program are creating harmonized quality standards for alpha-emitting drug substances. Manufacturers must now demonstrate real-time release testing capabilities and container closure integrity under radiation stress. European production facilities are responding with dedicated alpha-handling suites, while US sites pursue concurrent validation strategies to maintain supply continuity across regulatory jurisdictions.
Oncology procurement is fragmenting from hospital pharmacy bulk purchasing toward patient-specific unit dosing managed by nuclear medicine specialists. This shift disintermediates traditional pharmaceutical distribution and creates direct relationships between manufacturers and certified treatment centers. Germany's university hospital networks and Japan's designated cancer care hospitals are most advanced in this transition, with reimbursement codes adapting to per-patient administration models.
Alpha Emitter Market Segmentation
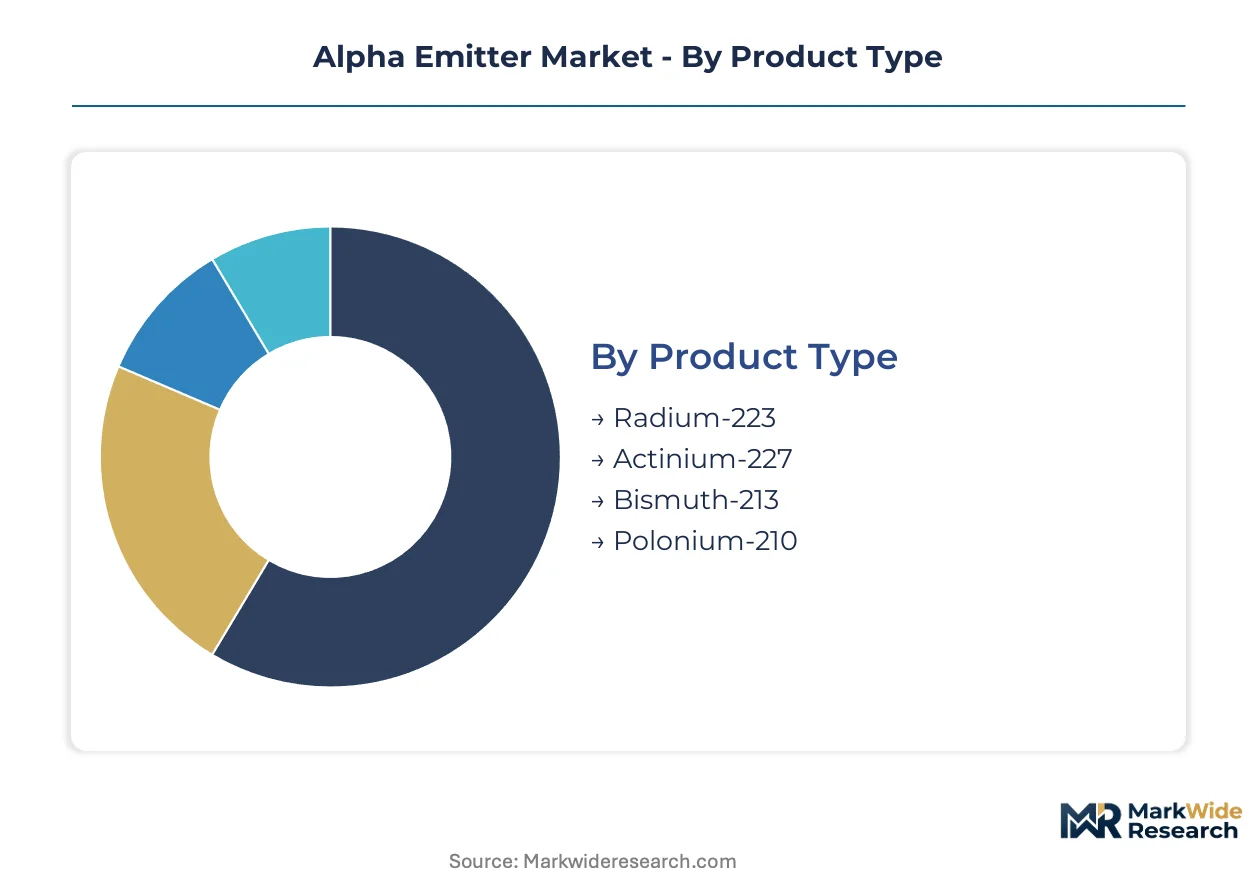
Alpha emitter segmentation reflects divergent regulatory pathways and infrastructure requirements across therapeutic versus non-therapeutic applications. FDA and EMA frameworks impose distinct certification burdens on radiopharmaceutical manufacturing compared to industrial radiography equipment.
Product Type:
Radium-223 carries established FDA approval for prostate cancer bone metastases, while actinium-227 navigates accelerated review pathways under breakthrough therapy designation. Bismuth-213 and polonium-210 face varying classification across jurisdictions.
- Radium-223:Alpha-emitting calcium mimetic that selectively targets bone metastases with proven survival benefit in castration-resistant prostate cancer. Demand concentrates in the United States and Germany, where urology-oncology networks and mature reimbursement codes support clinical adoption. Bayer AG's manufacturing scale anchors supply security.
- Actinium-227:Decays to bismuth-213 and delivers high linear energy transfer over 40-100 micrometers, enabling antibody-radionuclide conjugate applications. Demand is accelerating in Japan's designated cancer care hospitals and US academic medical centers pursuing hematologic malignancy protocols. Generator technology development is expanding access beyond centralized reactor supply.
- Bismuth-213:Generator-produced alpha emitter used in targeted alpha therapy clinical trials for acute myeloid leukemia.
- Polonium-210:High-specific-activity alpha emitter with specialized applications in neutron source initiation and research.
Radium-223 sits at the top of the volume ranking, with actinium-227 climbing the fastest.
Application:
Cancer treatment commands premium pricing and vertical integration incentives, while industrial radiography operates under entirely different regulatory frameworks.
- Cancer Treatment:Targeted radionuclide therapy for metastatic bone cancer and hematologic malignancies requiring GMP manufacturing, batch release testing, and pharmacovigilance. FDA and EMA oversight shapes clinical trial design and commercial distribution.
- Industrial Radiography:Non-destructive testing applications in pipeline inspection and weld verification governed by national nuclear regulators rather than pharmaceutical agencies.
- Nuclear Medicine:Diagnostic and therapeutic radiopharmaceutical production in cyclotron and reactor facilities.
- Research Activities:Preclinical alpha emitter studies in radiobiology and targeted therapy development.
Cancer treatment dominates revenue contribution, with nuclear medicine expanding most quickly through theranostic platform development.
End User:
Hospital procurement patterns diverge sharply from research institution purchasing, with reimbursement codes determining accessible patient volumes.
- Hospitals:Integrated cancer centers with nuclear medicine departments, hot cell infrastructure, and radiation safety protocols. Reimbursement through DRG and APC mechanisms in the United States, with Germany's G-BA assessments and Japan's fee-for-service models creating geographic variation in treatment access.
- Research Institutions:Academic medical centers and national laboratories conducting preclinical and early-phase clinical studies.
- Nuclear Facilities:Reactor and cyclotron sites producing alpha emitters for downstream distribution.
- Diagnostic Centers:Imaging facilities integrating theranostic approaches with alpha therapy patient selection.
Hospitals anchor installed base, with diagnostic centers gaining share fastest through theranostic service expansion.
Technology:
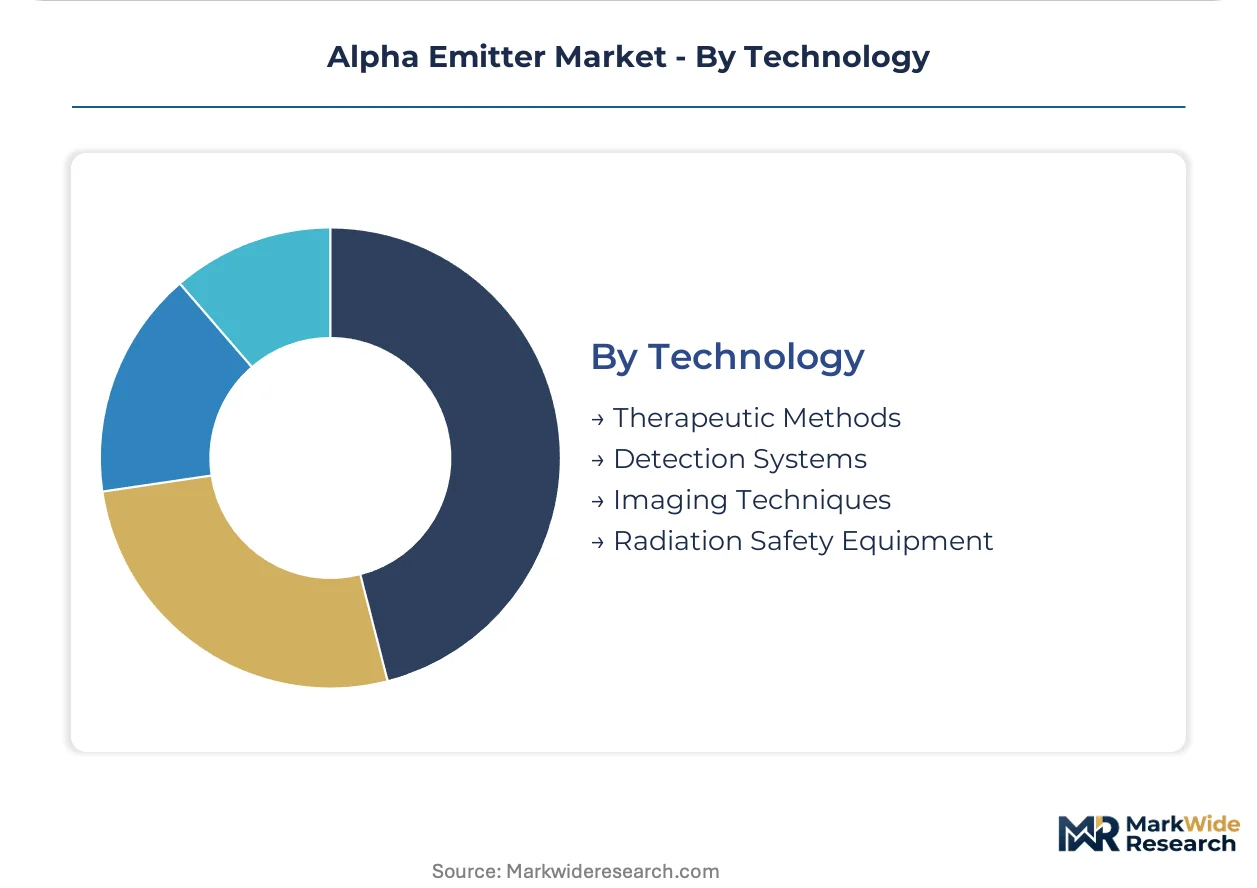
Therapeutic methods capture deepest margins through conjugation chemistry and dosing protocol control, while detection systems face commoditization pressure.
- Therapeutic Methods:Antibody-radionuclide conjugates, peptide-targeted radiopharmaceuticals, and bone-seeking alpha emitters. Novartis AG's radioligand therapy platform and Actinium Pharmaceuticals' generator systems exemplify vertical control strategies.
- Detection Systems:Alpha spectroscopy and liquid scintillation counting for radiochemical purity verification.
- Imaging Techniques:PET and SPECT diagnostics paired with alpha therapy for patient selection and response monitoring.
- Radiation Safety Equipment:Hot cells, shielded transport containers, and waste handling systems required for regulatory compliance.
Therapeutic methods lead margin pools, with imaging techniques showing steepest expansion trajectory through theranostic integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting alpha emitter production toward jurisdictions with streamlined nuclear licensing and established reimbursement pathways. The United States, Germany, and Japan concentrate cyclotron and reactor capacity, while emerging production clusters in Canada and France exploit cross-border supply efficiencies.
United States
FDA breakthrough therapy designations for actinium-based radiopharmaceuticals accelerate clinical trial enrollment at Memorial Sloan Kettering and MD Anderson. The NRC governs reactor licensing and transport security protocols for thorium-229 decay chain materials. NorthStar Medical Radioisotopes anchors domestic Ac-225 supply through its Beloit, Wisconsin production facility.
Germany
EMA centralized marketing authorizations enable pan-European distribution from Bavarian production hubs. The BfS enforces stringent radiation handling standards that favor consolidated hot cell investments at university hospital networks. Heidelberg and Munich anchor the continent's largest radium-223 patient volumes through established urology-oncology referral pathways.
Japan
PMDA sakigake designation pathways compress review timelines for alpha-emitting antibody conjugates targeting hematologic malignancies. METI funding for designated cancer care hospitals expands actinium therapy access beyond Tokyo and Osaka. The Chiba cyclotron facility supplies domestic generator production for decentralized clinical administration.
Canada
Health Canada streamlined radiopharmaceutical approval frameworks attract US-sponsored trials seeking parallel regulatory submissions. The Canadian Nuclear Safety Commission harmonizes transport rules with US DOT regulations, enabling seamless cross-border distribution. TRIUMF in Vancouver anchors academic production partnerships for thorium-229 source material.
France
ANSM fast-track ATU (temporary use authorization) pathways enable early patient access ahead of formal EMA approval. The country's national nuclear research infrastructure at Saclay supports Orano Med's radioligand development programs. Lyon and Paris concentrate clinical trial execution through coordinated hospital pharmacy networks.
Alpha Emitter Market Key Industry Players
Strategic partnerships dominate the current landscape as manufacturers secure reactor access and generator technology licenses. The vendor base stratifies across three tiers: integrated pharmaceutical conglomerates with radioligand platforms, specialized radiopharmaceutical contract manufacturers, and academic spin-offs pursuing novel chelation chemistry. Archetypes include vertical integrators controlling conjugation-through-dosing value chains, reactor-dependent suppliers locked into thorium-229 decay chain sourcing, and technology licensors monetizing automated synthesis modules. Capacity expansion and regulatory co-development agreements constitute the dominant competitive moves.
Among integrated pharmaceutical conglomerates, Bayer AG and Novartis AG exemplify divergent strategic positions—Bayer anchoring scale manufacturing of bone-seeking alpha emitters, Novartis representing radioligand therapy platform diversification. Actinium Pharmaceuticals occupies a specialist tier focused on generator technology and Ac-225 supply chain development. These three entities collectively illustrate the competitive tension between established therapeutic franchises and emerging targeted alpha therapy constructs.
| Leading Market Players |
|---|
| Orano Med |
| NorthStar Medical Radioisotopes |
| Bayer AG |
| Eckert & Ziegler |
| IBA Worldwide |
| Novartis AG |
| Alpha Tau Medical |
| Curium Pharma |
| Actinium Pharmaceuticals |
| Others |
Cost & Logistics Intelligence
Patient-specific unit dosing procurement by Germany's university hospital networks and Japan's designated cancer care hospitals is forcing manufacturers to abandon bulk pharmaceutical distribution in favor of direct certified-center relationships, compressing channel margins while elevating logistics premiums for cold-chain integrity.
Pricing Analysis
Direct-to-treatment-center contracting eliminates traditional distributor markups in the alpha emitter market. Pricing stratifies across GMP-certified radiopharmaceutical tiers, with batch release testing and real-time quality verification commanding substantial premiums over research-grade material. Cost compression in reactor-sourced actinium-227 is intensifying because generator technology deployment is expanding decentralized production alternatives. Academic medical centers exhibit the highest price sensitivity due to constrained research budgets, while commercial oncology networks prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with thorium-229 decay chain dependency anchored in United States and Russian high-flux reactor capacity. Production draws from thorium-229 parent material, specialized hot cell infrastructure, and automated synthesis modules for radiolabeling. Regulatory restriction across divergent national nuclear transport frameworks creates friction for cross-border clinical trial supply. Distribution runs through certified radiopharmaceutical logistics providers with shielded transport and real-time temperature monitoring capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage opportunities concentrate in Canada and France, where streamlined Health Canada radiopharmaceutical frameworks and ANSM temporary use authorization pathways offer faster patient access than FDA breakthrough timelines at comparable development cost.
For Market Incumbents: Extend manufacturing scale advantages through backward integration into generator technology and thorium-229 source material control. Lock in exclusive supply agreements with university hospital networks before reimbursement codes shift to per-patient administration models. Defend against emerging radioligand therapy platforms by accelerating actinium-based antibody conjugate pipeline advancement. For New Entrants and Emerging Players: Capture white-space in community oncology settings underserved by centralized reactor supply through portable Ac-225/Bi-213 generator deployment. Target diagnostic centers integrating theranostic patient selection protocols, where imaging-therapy pairing creates service differentiation. Pursue licensing partnerships with established nuclear medicine specialists rather than greenfield facility investment. For Investors and Strategic Acquirers: Asymmetric upside sits with automated synthesis module developers and generator technology licensors positioned for decentralized production expansion. Long-term viability hinges on regulatory co-development capabilities across FDA, EMA, and PMDA jurisdictions. Watch for EMA-FDA convergence on alpha-therapy dosing standards as the inflection signal for supply chain configuration winners.| Strategic Initiative | Industry Significance |
|---|---|
| Generator Technology Licensing | Decentralized Ac-225 production reduces thorium-229 reactor dependency for community oncology access. |
| Regulatory Co-Development Agreement | Parallel FDA-EMA quality standard harmonization accelerates cross-border commercial distribution pathways. |
| Hospital System Partnership | Direct relationships with Heidelberg and Munich university networks secure radium-223 volume commitments. |
| Automated Synthesis Module Deployment | Standardized radiolabeling chemistry reduces batch-to-batch variability for multi-patient dosing efficiency. |
| Reimbursement Strategy Investment | Early CMS national coverage determination engagement shapes payment codes for novel alpha therapies. |
Research Approach
Bottom-up hospital procurement modeling reconciled against top-down reactor capacity tracking forms the analytical core of this study. Primary interviews with nuclear medicine department heads, radiopharmaceutical manufacturing executives, regulatory affairs specialists at FDA and EMA, and hospital formulary directors combined with secondary validation against ClinicalTrials.gov entries, EMA centralized marketing authorization databases, NRC reactor licensing records, and national health reimbursement code filings. Triangulation across these sources ensures demand-side patient volume estimates align with supply-side production constraints.
Historical trendline analysis of FDA breakthrough therapy designations and EMA priority medicines approvals established baseline regulatory acceleration patterns across the projection horizon. Segmentation modeling incorporated product type, application, end user, and technology dimensions with treatment line and regional regulatory cluster overlays. CAGRs were derived from patient population epidemiology, reimbursement pathway maturation timelines, and infrastructure investment trajectories. Forecast inputs included cyclotron and reactor capacity expansion announcements, generator technology adoption curves, and theranostic platform integration rates.
Thorium-229 supply disruption, reimbursement code revision delays, and radiochemistry talent scarcity are the dominant revision risks to the forecast framework. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South Africa Minimally Invasive Surgical Devices Market
Medical Devices
North America Refractive Surgery Devices Market
Medical Devices
Graft Delivery Devices Market
Medical Devices
North America Cataract Surgery Devices Market
Medical Devices
Global Medical Tricorder Device Market
Medical Devices
Concentrator O2 Devices Market
Medical Devices
Implantable Pump Catheter Market
Medical Devices
China Diabetes Devices Market
Medical Devices
Nonablative Laser Resurfacing Devices Market
Medical Devices
Global Blood Banking Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Global Artificial Organs and Bionics Market
Medical Devices
High Frequency Ventilators Market
Medical Devices
Pathology Devices Market
Medical Devices
Chronic Total Occlusion Devices Market
Medical Devices
Functional Electrical Stimulation Market