
 Europe Intraoperative Imaging Market | 2026-2036
Europe Intraoperative Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Intraoperative Imaging Market Insights
CE marking under the EU Medical Device Regulation is unwinding the competitive field for intraoperative imaging suppliers. Siemens Healthcare GmbH leverages its imaging heritage to anchor premium fixed-system installations across German university hospitals. Brainlab AG specializes in software-integrated navigation platforms that extend surgical precision beyond hardware alone. Ziehm Imaging GmbH dominates mobile C-arm manufacturing from its Nuremberg base, controlling mid-tier price points in orthopedic applications.
Intraoperative imaging denotes real-time image acquisition systems deployed during surgical procedures to guide instrument placement, verify resection margins, or confirm anatomical alignment, typically operating at 30-120 kV for fluoroscopic modalities or utilizing superconducting magnets up to 3 Tesla for MRI-guided interventions. Mobile systems lead volume sales across European surgical centers where capital budgets constrain fixed-room investments, while software solutions capture expanding margin pools through recurring license architectures. MRI-guided technology occupies the fastest-expanding segment in neurosurgical suites, though fluoroscopy retains the broadest installed base across cardiovascular and orthopedic applications.
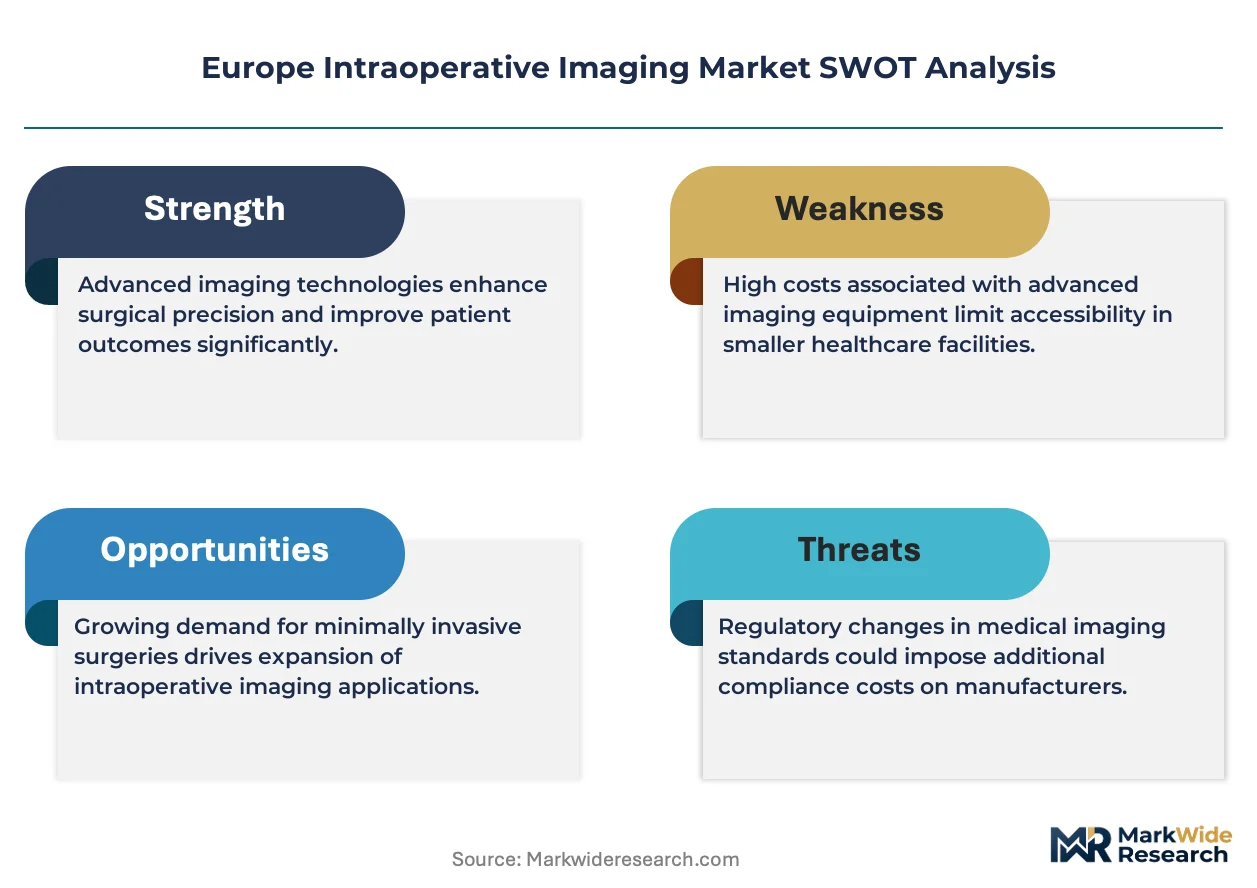
The EU Medical Device Regulation and EMA oversight of device-software combinations shape product development timelines and clinical evidence requirements for intraoperative imaging manufacturers. REACH compliance for electronic component materials and the F-Gas Regulation governing MRI coolant systems add layered environmental obligations to hardware supply chains. Stakeholders must weigh conformity assessment costs against the strategic imperative of maintaining access to European hospital procurement frameworks as regulatory stringency intensifies.
Market Dynamics
The EU Medical Device Regulation's tightened conformity requirements are compressing product development timelines and elevating clinical evidence thresholds for intraoperative imaging manufacturers serving European surgical centers.
Growth Catalysts
- MDR Conformity Pressure:The EU Medical Device Regulation's stricter active implantable device standards are accelerating hospital replacement cycles for aging intraoperative MRI systems across German neurosurgical suites.
- Orthopedic Procedure Volumes:Rising spinal fusion and trauma surgery caseloads in France and the United Kingdom are expanding installed base demand for mobile C-arm fluoroscopy systems in ambulatory surgical centers.
- Superconducting Magnet Advances:3 Tesla MRI-guided intervention platforms are penetrating neurosurgical departments previously constrained by 1.5 Tesla performance limitations.
Market Restraints
- Helium Supply Concentration:MRI coolant dependency on concentrated helium sourcing from Algeria and Qatar exposes system manufacturers to input cost volatility and supply disruption risk.
- Capital Intensity Thresholds:Fixed-room intraoperative MRI installations require €3-8 million capital commitments that exclude community hospitals and smaller orthopedic clinics from acquisition.
- F-Gas Regulatory Friction:The EU F-Gas Regulation's phasedown schedule for fluorinated greenhouse gases complicates cooling system design and extends engineering validation timelines for MRI manufacturers.
Strategic Opportunities
- Software-Integrated Navigation:Surgical planning platforms converging with augmented reality visualization are creating recurring revenue architectures beyond hardware-only sales models.
- Central and Eastern Europe:Underpenetrated Polish and Romanian hospital networks present first-mover expansion potential as EU cohesion funds modernize surgical infrastructure.
- REACH Compliance Services:Environmental material documentation requirements are opening consultative service revenue streams for suppliers with established ECHA regulatory expertise.
Industry Challenges
- Clinical Engineering Talent Scarcity:Specialized MRI physicist and biomedical engineer shortages constrain hospital deployment velocity for complex intraoperative imaging systems.
- Legacy PACS Integration Complexity:Interoperability failures between new mobile C-arm systems and entrenched hospital picture archiving infrastructure delay go-live schedules and inflate implementation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Intraoperative Imaging Market |
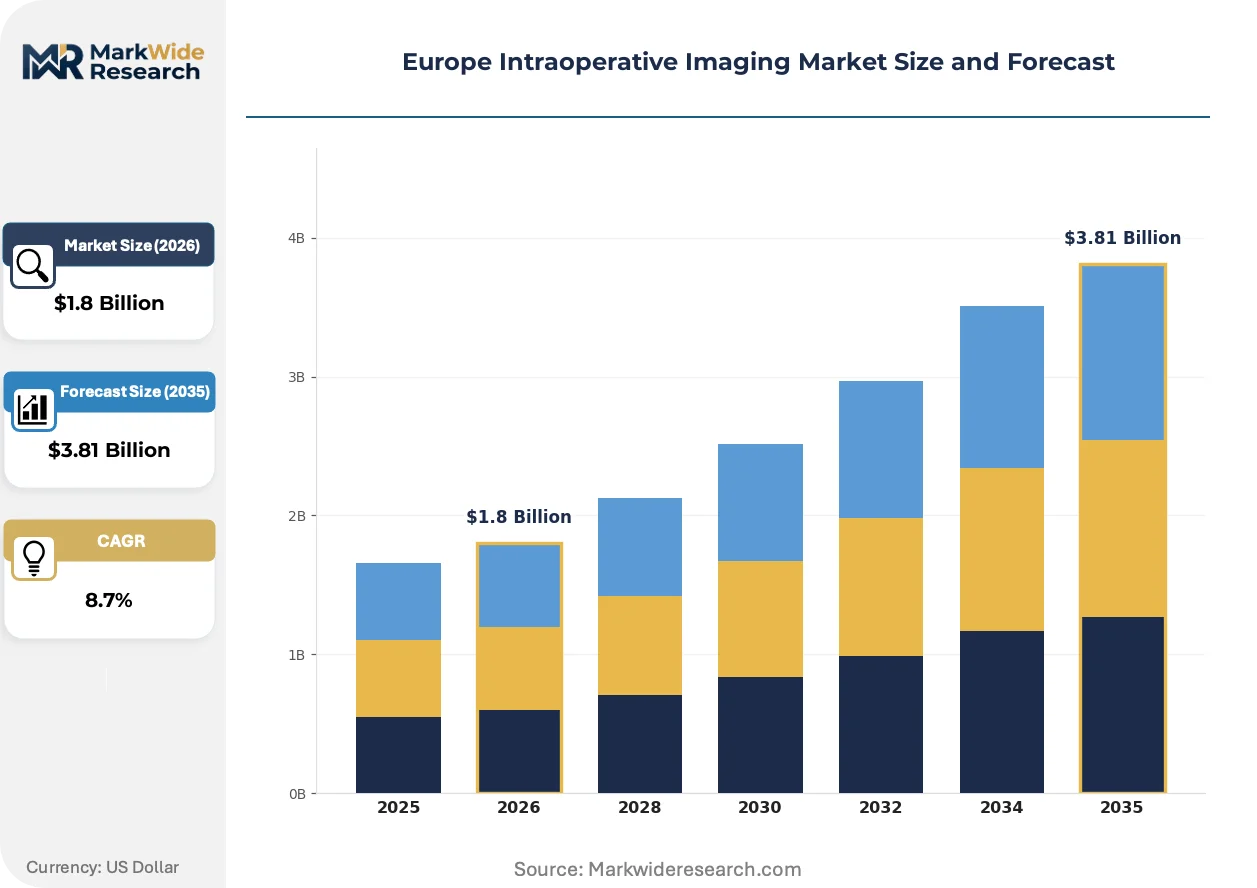
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: CT, MRI, Ultrasound, Fluoroscopy End User: Hospitals, Surgical Centers, Clinics, Research Institutions Application: Neurosurgery, Orthopedic Surgery, Cardiovascular Surgery, Oncology Surgery Product Type: Mobile Systems, Fixed Systems, Software Solutions, Accessories |
| Companies Covered | Medtronic plc, Brainlab AG, Siemens Healthcare GmbH, Canon Medical Systems Corporation, Shimadzu Corporation, GE HealthCare, Ziehm Imaging GmbH, Carl Zeiss Meditec AG, Koninklijke Philips N.V., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Intraoperative Imaging Market Trends and Innovations
Open MRI architectures and artificial intelligence-enhanced image reconstruction are converging to reduce procedural interruption times while expanding real-time surgical guidance capabilities across European operating theaters.
Intraoperative MRI magnet design is fragmenting from fixed-room installations toward compact, shielded configurations that enable adjacent-OR deployment without dedicated surgical suite construction. German university hospitals are piloting these systems to preserve neurosurgical workflow continuity. The technology is fragmenting historical capital allocation patterns that previously concentrated imaging investments in single specialized suites.
The EU Medical Device Regulation's software classification requirements are forcing navigation platform vendors to establish quality management systems for algorithm-based surgical guidance tools. This regulatory expansion captures previously unregulated decision-support functionalities under notified body oversight. Neurosurgical device-software combinations face the steepest compliance cost escalation as clinical evidence requirements extend development timelines.
Hospital procurement committees are unbundling after-sales service contracts from hardware acquisition agreements to drive competitive tension on multi-year maintenance pricing. Independent service organizations are capturing MRI coil and gradient amplifier repair volumes previously held by original equipment manufacturers. This disintermediation is most visible in the United Kingdom's National Health Service supply chain rationalization programs.
Europe Intraoperative Imaging Market Segmentation
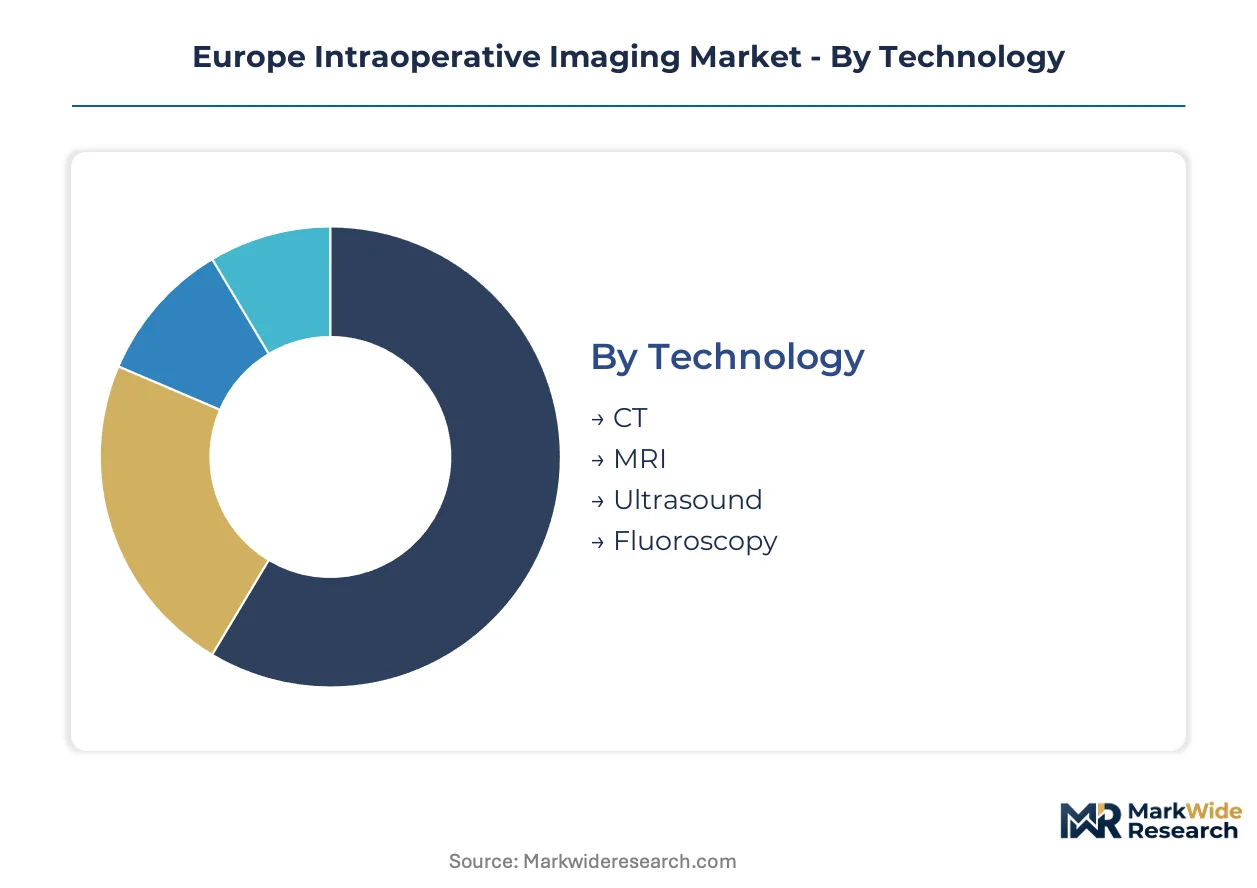
Intraoperative imaging procurement patterns diverge sharply across European healthcare systems. German university hospitals favor fixed-room MRI installations while French and British ambulatory centers prioritize mobile fluoroscopy units. Software-integrated platforms are capturing margin expansion through recurring license architectures independent of hardware replacement cycles.
Technology:
Channel distribution varies by modality complexity—MRI systems flow through specialized capital equipment distributors, fluoroscopy through orthopedic device suppliers, and software directly from vendors to hospital IT procurement.
- MRI:Superconducting magnets operating at 1.5-3 Tesla enable real-time neurosurgical guidance with sub-millimeter resolution. Demand concentrates in German neurosurgical suites as MDR conformity requirements accelerate replacement of aging 1.5 Tesla installations.
- Fluoroscopy:Mobile C-arm systems operating at 30-120 kV dominate orthopedic and spinal fusion procedures. French and United Kingdom surgical centers are expanding installed base demand for mid-tier systems as ambulatory surgery volumes rise.
- CT:Intraoperative cone-beam configurations provide rapid 3D reconstruction during trauma and complex orthopedic interventions. Adoption remains concentrated in Level I trauma centers with hybrid operating room infrastructure.
- Ultrasound:Portable transducer arrays enable soft-tissue visualization without ionizing radiation exposure. Cardiovascular applications in Italian and Spanish hospitals are driving niche demand for transesophageal and intracardiac echocardiography platforms.
Fluoroscopy dominates installed base across European surgical centers. MRI is where expansion concentrates as neurosurgical departments upgrade to 3 Tesla platforms.
End User:
Capital intensity thresholds create distinct customer tiers—university hospitals absorb €8 million MRI investments while community surgical centers operate within €500,000 equipment budgets.
- Hospitals:Academic medical centers with neurosurgical departments anchor demand for fixed-room intraoperative MRI systems. German university hospitals are piloting compact shielded magnet configurations that enable adjacent-OR deployment without dedicated suite construction.
- Surgical Centers:Ambulatory facilities in France and the United Kingdom concentrate procurement of mobile C-arm fluoroscopy systems. These centers prioritize rapid patient turnover and same-day discharge protocols that favor portable imaging modalities.
- Clinics:Smaller orthopedic and pain management practices utilize refurbished or entry-level mobile systems. Procurement committees in these settings unbundle service contracts from hardware acquisition to drive competitive maintenance pricing.
- Research Institutions:Preclinical imaging laboratories and surgical innovation centers source specialized configurations for procedure development. These facilities operate outside standard hospital procurement frameworks with extended validation timelines.
Hospitals absorb the highest capital commitments per installation. Surgical centers are gaining share fastest as ambulatory procedure volumes expand across Western Europe.
Application:
Procedure reimbursement levels determine technology selection—neurosurgery justifies premium MRI investments while orthopedic surgery operates within fluoroscopy-dominated cost structures.
- Neurosurgery:Brain tumor resection and epilepsy surgery require real-time margin verification that only MRI-guided platforms provide. German neurosurgical suites are accelerating purchases as MDR tightens conformity requirements for active implantable devices used in functional neurosurgery.
- Orthopedic Surgery:Spinal fusion, trauma fixation, and joint replacement procedures rely predominantly on mobile C-arm fluoroscopy. Rising caseloads in France and the United Kingdom are expanding installed base demand across ambulatory surgical centers.
- Cardiovascular Surgery:Hybrid operating rooms combine surgical capabilities with interventional cardiology workflows. These installations require integrated fluoroscopy and transesophageal echocardiography platforms with specialized table and anesthesia configurations.
- Oncology Surgery:Image-guided tumor ablation and sentinel lymph node mapping utilize ultrasound and CT modalities. Adoption remains concentrated in comprehensive cancer centers with multidisciplinary tumor board infrastructure.
Orthopedic surgery commands the broadest installed base. Neurosurgery represents the steepest expansion trajectory as 3 Tesla platforms penetrate previously constrained departments.
Product Type:
Margin architecture separates hardware from software—mobile and fixed systems generate one-time revenue while navigation platforms capture recurring license streams.
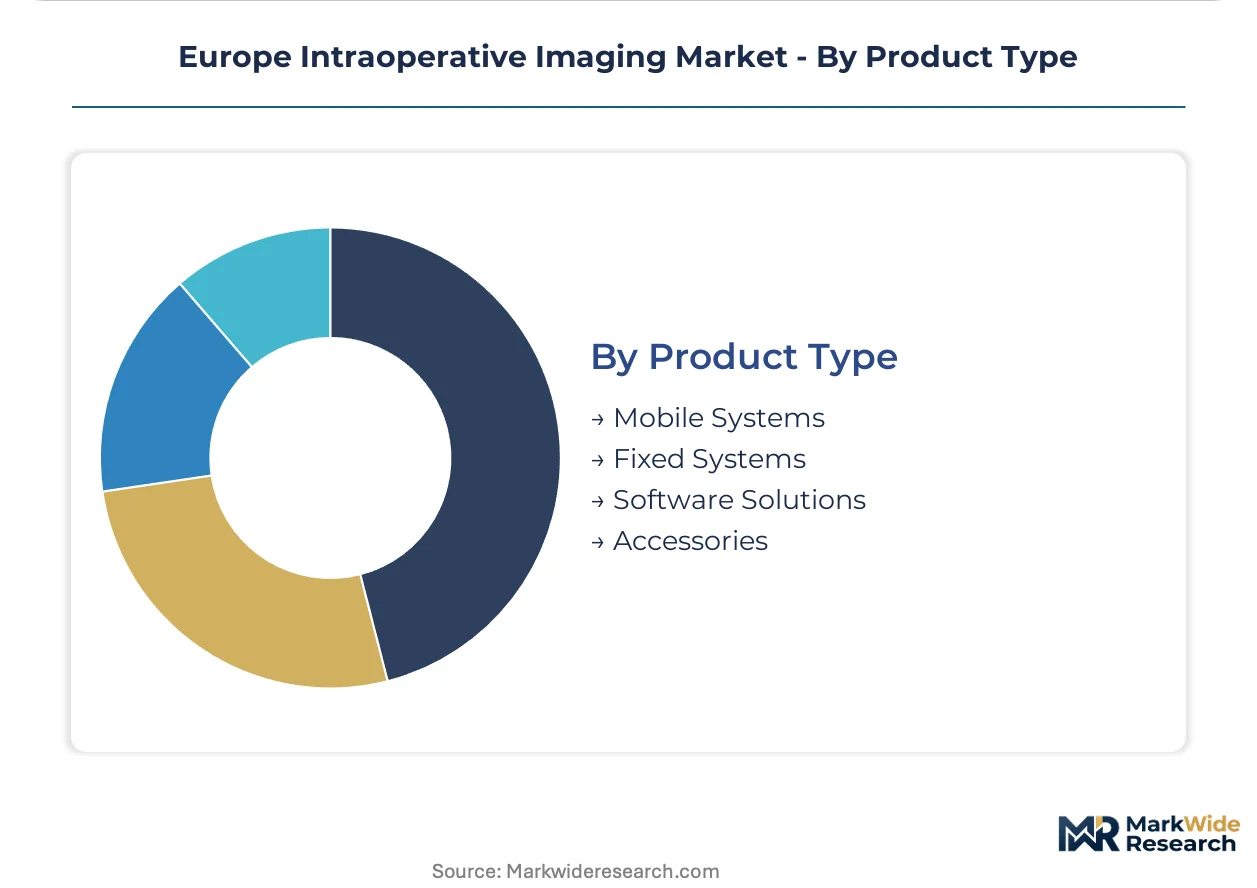
- Mobile Systems:C-arm fluoroscopy units and portable CT scanners enable intraoperative imaging without dedicated suite construction. These systems lead volume sales across European surgical centers where capital budgets constrain fixed-room investments.
- Fixed Systems:Intraoperative MRI installations require specialized magnet shielding, surgical table integration, and anesthesia gas evacuation infrastructure. German university hospitals anchor demand despite €3-8 million capital commitments that exclude community facilities.
- Software Solutions:Surgical navigation platforms with augmented reality visualization extend precision beyond hardware capabilities. EMA oversight of device-software combinations is forcing vendors to establish quality management systems for algorithm-based guidance tools.
- Accessories:MRI-compatible instruments, specialized coils, and disposable sterile drapes complete system configurations. Independent service organizations are capturing coil and gradient amplifier repair volumes previously held by original equipment manufacturers.
Mobile systems dominate unit volume. Software solutions are where margin expansion concentrates through recurring license architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University hospital procurement committees in Germany absorb the highest capital commitments per installation, while French and British ambulatory surgical centers concentrate demand for mobile fluoroscopy systems with rapid patient turnover protocols.
Germany
Neurosurgical suites in Bavaria and North Rhine-Westphalia are accelerating replacement cycles for aging intraoperative MRI systems as MDR conformity requirements tighten. The EU Medical Device Regulation's stricter active implantable device standards compress product development timelines for manufacturers serving German academic medical centers. Berlin-Brandenburg university hospitals pilot compact shielded magnet configurations enabling adjacent-OR deployment without dedicated suite construction.
United Kingdom
NHS supply chain rationalization programs drive unbundling of after-sales service contracts from hardware acquisition agreements. The Medicines and Healthcare products Regulatory Agency oversees device-software combinations for navigation platforms used in spinal fusion procedures. London and Southeast England ambulatory centers prioritize mobile C-arm systems supporting same-day discharge protocols for orthopedic interventions.
France
ANSM oversight shapes quality management requirements for surgical planning platforms converging with augmented reality visualization. The country's regional hospital networks concentrate procurement of mid-tier mobile fluoroscopy units for trauma and joint replacement caseloads. Île-de-France academic centers anchor demand for integrated hybrid operating room infrastructure combining surgical and interventional cardiology workflows.
Italy
Lombardy and Emilia-Romagna cardiovascular departments drive niche demand for transesophageal and intracardiac echocardiography platforms without ionizing radiation exposure. REACH compliance documentation requirements for electronic component materials add layered environmental obligations to hardware supply chains serving Italian comprehensive cancer centers. Milan-area hospitals specialize in image-guided tumor ablation utilizing ultrasound modalities for sentinel lymph node mapping.
Poland
EU cohesion funds modernizing surgical infrastructure create first-mover expansion potential for mobile imaging system suppliers. The country's national pharmaceutical regulator aligns device classification with EMA frameworks for software-integrated navigation tools. Warsaw and Krakow hospital networks remain underpenetrated relative to Western European installed base densities for intraoperative MRI platforms.
Europe Intraoperative Imaging Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with imaging heritage, compact-specialist manufacturers dominating mid-tier price points, and software-integrated navigation platform vendors. Strategic archetypes separate into premium fixed-system installers, mobile fluoroscopy fabricators, and recurring-revenue software licensors. Competitive moves concentrate on M&A for regulatory expertise consolidation and strategic partnerships for PACS interoperability integration.
Within the diversified imaging conglomerate tier, Siemens Healthcare GmbH and GE HealthCare exemplify capital-intensive fixed-system positioning across university hospital procurement frameworks. Among German-based specialists, Brainlab AG and Ziehm Imaging GmbH occupy distinct archetype positions—software-integrated navigation versus mobile C-arm manufacturing. Koninklijke Philips N.V. represents the pan-European diversified alternative with hybrid operating room integration capabilities.
| Leading Market Players |
|---|
| Medtronic plc |
| Brainlab AG |
| Siemens Healthcare GmbH |
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| GE HealthCare |
| Ziehm Imaging GmbH |
| Carl Zeiss Meditec AG |
| Koninklijke Philips N.V. |
| Others |
Pricing and Supply Chain Analysis
Helium-to-alternative-coolant substitution in MRI magnet systems is simultaneously relocating supply geography toward Qatar and Algeria while compressing pricing power for European original equipment manufacturers facing F-Gas Regulation compliance deadlines. This input transition forces hardware vendors to renegotiate long-term service contracts as thermal management costs destabilize established margin architectures.
Pricing Analysis
Cost-plus contracts with helium indexation clauses dominate MRI system procurement between German university hospitals and superconducting magnet suppliers. Three-tier pricing structure across premium 3 Tesla installations, standard 1.5 Tesla configurations, and economy refurbished platforms separates academic medical centers from community hospitals by capital intensity threshold. Cost compression in mid-tier mobile C-arm segments is intensifying because Polish and Romanian distributors are unbundling service agreements from hardware acquisition. Ambulatory surgical centers in France and the United Kingdom exhibit the highest price sensitivity, while German neurosurgical suites absorb premium fixed-system investments with limited negotiation leverage.
Supply Chain Analysis
Strait of Hormuz transit underwrites helium supply security for European MRI manufacturers sourcing from Qatar, with Algerian pipeline deliveries providing secondary redundancy. Superconducting wire production concentrates in Germany, Japan, and the United States, while gradient amplifier assemblies feed from South Korean and Chinese electronics clusters. Single-source vulnerability in liquid helium refining exposes system manufacturers to input cost volatility and geopolitical disruption. Distribution runs through specialized capital equipment distributors for MRI platforms, orthopedic device suppliers for mobile C-arms, and direct vendor-to-hospital IT procurement for software-integrated navigation tools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
European intraoperative imaging represents an early-cycle expansion story as 3 Tesla MRI platforms penetrate neurosurgical departments previously constrained by 1.5 Tesla performance limitations, with MDR conformity requirements accelerating replacement timelines across German academic centers.
For Market Incumbents: Fortify installed base retention by embedding software-integrated navigation platforms with recurring license architectures that extend beyond hardware replacement cycles. Acquire regulatory expertise in EMA device-software combination oversight to compress development timelines for algorithm-based surgical guidance tools. Defend against independent service organizations capturing MRI coil and gradient amplifier repair volumes by unbundling maintenance pricing in NHS supply chain rationalization programs. For New Entrants and Emerging Players: Post-sales clinical engineering training services represent a service-layer gap where incumbents under-serve hospital deployment velocity for complex intraoperative imaging systems. Target underpenetrated Polish and Romanian hospital networks as EU cohesion funds modernize surgical infrastructure, positioning compact shielded magnet configurations for adjacent-OR deployment without dedicated suite construction. Pursue consultative REACH compliance services revenue streams leveraging ECHA regulatory expertise as environmental material documentation requirements intensify. For Investors and Strategic Acquirers: Capital is best deployed toward software-integrated navigation platform vendors with established quality management systems for algorithm-based surgical guidance tools. Long-term viability over a multi-year horizon hinges on recurring revenue architectures independent of hardware replacement cycles. Watch for inflection signals in independent service organization market share capture within United Kingdom National Health Service supply chain rationalization programs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | MDR conformity requirements compress timelines for active implantable device software combinations. |
| Hospital System Partnership | German university hospitals pilot compact shielded magnets enabling adjacent-OR deployment flexibility. |
| Software Companion Development | Augmented reality visualization platforms create recurring license architectures beyond hardware sales. |
| Reimbursement Strategy | Procedure reimbursement levels determine technology selection between MRI and fluoroscopy modalities. |
| Regulatory Expertise Acquisition | EMA oversight of device-software combinations forces quality management system establishment. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with neurosurgeons, hospital procurement committee members, biomedical engineers, and GPO contracts managers. Secondary validation drew from EMA device-software combination filings, EU MDR conformity assessment databases, hospital procurement records, and F-Gas Regulation implementation reports. Bottom-up installed base enumeration triangulated against top-down capital expenditure flow analysis across the projection horizon.
Across the analysis window, the forecasting framework modeled technology segmentation by magnet strength and mobility configuration, end-user tiering by capital intensity threshold, application differentiation by procedure reimbursement level, and product type separation between hardware and recurring-revenue software. CAGRs were derived from replacement cycle acceleration patterns and ambulatory surgery volume trajectories. Industry-specific inputs included MDR implementation timelines, helium supply contract renegotiation schedules, and EU cohesion fund disbursement trajectories for Central and Eastern European hospital infrastructure.
Material uncertainties — MDR enforcement variability, helium supply disruption events, and F-Gas Regulation phasedown acceleration — sit outside the modeled envelope. Forecasts reflect assumptions around regulatory compliance cost absorption and hospital capital budget elasticity. Practitioners should keep alternative scenarios live as EMA device-software combination oversight scope and NHS supply chain rationalization program depth evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Ultrasound Consoles and Transducers Market
Medical Imaging
Italy Diagnostic Imaging Equipment Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Medical Digital Imaging Devices Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
South America Nuclear Imaging Market
Medical Imaging
Surgical Imaging Robots Market
Medical Imaging
US Magnetic Resonance Imaging Coils Market
Medical Imaging
3D Medical and Surgical Imaging Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Retinal Imaging Devices Market
Medical Imaging
Japan Nuclear Imaging Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Specimen Radiography Systems Market