
 Japan Nuclear Imaging Market | 2026-2036
Japan Nuclear Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Nuclear Imaging Market Foresight
The PMDA's tightened quality standards for radiopharmaceutical manufacturing is restructuring capital requirements for domestic producers. GE Healthcare leverages its cyclotron network to sustain isotope supply security across Honshu. Siemens Healthineers anchors its position through hybrid imaging R&D partnerships with Japanese university hospitals. Canon Medical Systems Corporation differentiates via integrated detector technology that competes on spatial resolution metrics.
Japan nuclear imaging encompasses diagnostic systems utilizing gamma-emitting radioisotopes to visualize metabolic and functional processes, with SPECT systems typically employing technetium-99m at 140 keV photon energy and PET systems detecting 511 keV annihilation photons from fluorine-18 decay. The technology serves primarily for cancer staging, myocardial perfusion assessment, and neurodegenerative disease diagnosis. Positron Emission Tomography equipment commands premium positioning due to its superior quantitative capabilities in oncology applications. Hybrid Imaging configurations integrating PET with MRI are gaining fastest traction among research institutions seeking soft-tissue contrast without ionizing radiation from CT. Radiopharmaceuticals represent the margin-intensive segment where domestic production capabilities determine supply security.
PMDA oversight of radiopharmaceutical GMP compliance, METI coordination of medical isotope infrastructure, and JIS standards for equipment safety collectively elevate compliance costs while protecting patient safety standards. These frameworks channel procurement toward vendors with established domestic regulatory track records. Stakeholders must weigh cyclotron investment timelines against import dependency risks as geopolitical isotope supply patterns shift.
Market Dynamics
METI's domestic isotope production initiative is compressing import dependency timelines while PMDA's tightened GMP standards are elevating capital barriers for radiopharmaceutical manufacturing. This dual regulatory pressure is restructuring competitive positioning between cyclotron-equipped integrated suppliers and import-reliant distributors.
Growth Catalysts
- Hybrid PET-MRI Configurations:Research institutions at Osaka University and Keio University are accelerating adoption for neuro-oncology applications requiring soft-tissue contrast without CT radiation exposure.
- METI Medical Isotope Infrastructure:Government coordination of domestic cyclotron networks is reducing supply chain vulnerability to North American reactor maintenance schedules.
- Precision Oncology Staging Protocols:Tokyo metropolitan university hospitals are expanding FDG-PET utilization for treatment response monitoring in immunotherapy regimens.
Market Restraints
- Technetium-99m Generator Supply Concentration:Import dependency on Canadian and European molybdenum-99 sources creates vulnerability to reactor maintenance cycles.
- PMDA GMP Compliance Costs:Radiopharmaceutical manufacturing facility upgrades require capital deployment exceeding mid-tier distributor capacity.
- Short Half-Life Logistics:Fluorine-18's 110-minute decay window constrains distribution radius from cyclotron facilities to metropolitan corridors.
Strategic Opportunities
- Kansai Biocluster Expansion:Osaka's pharmaceutical corridor offers underpenetrated demand for contract radiopharmaceutical manufacturing services.
- Theranostics Convergence:Integration of diagnostic imaging with lutetium-177 radioligand therapy is creating unified service delivery models at specialized oncology centers.
- AI-Assisted Image Reconstruction:Deep learning algorithms are reducing PET acquisition times, enabling throughput expansion without additional scanner deployment.
Industry Challenges
- Qualified Cyclotron Engineer Scarcity:Domestic training programs produce insufficient personnel for expanding isotope production facility operations.
- Legacy SPECT System Replacement Cycles:Hospital capital committees face extended approval timelines for hybrid imaging upgrades amid budget constraints.
- Radiopharmaceutical Cold Chain Integrity:Temperature excursion risks during metropolitan traffic congestion compromise dose viability for scheduled procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Nuclear Imaging Market |
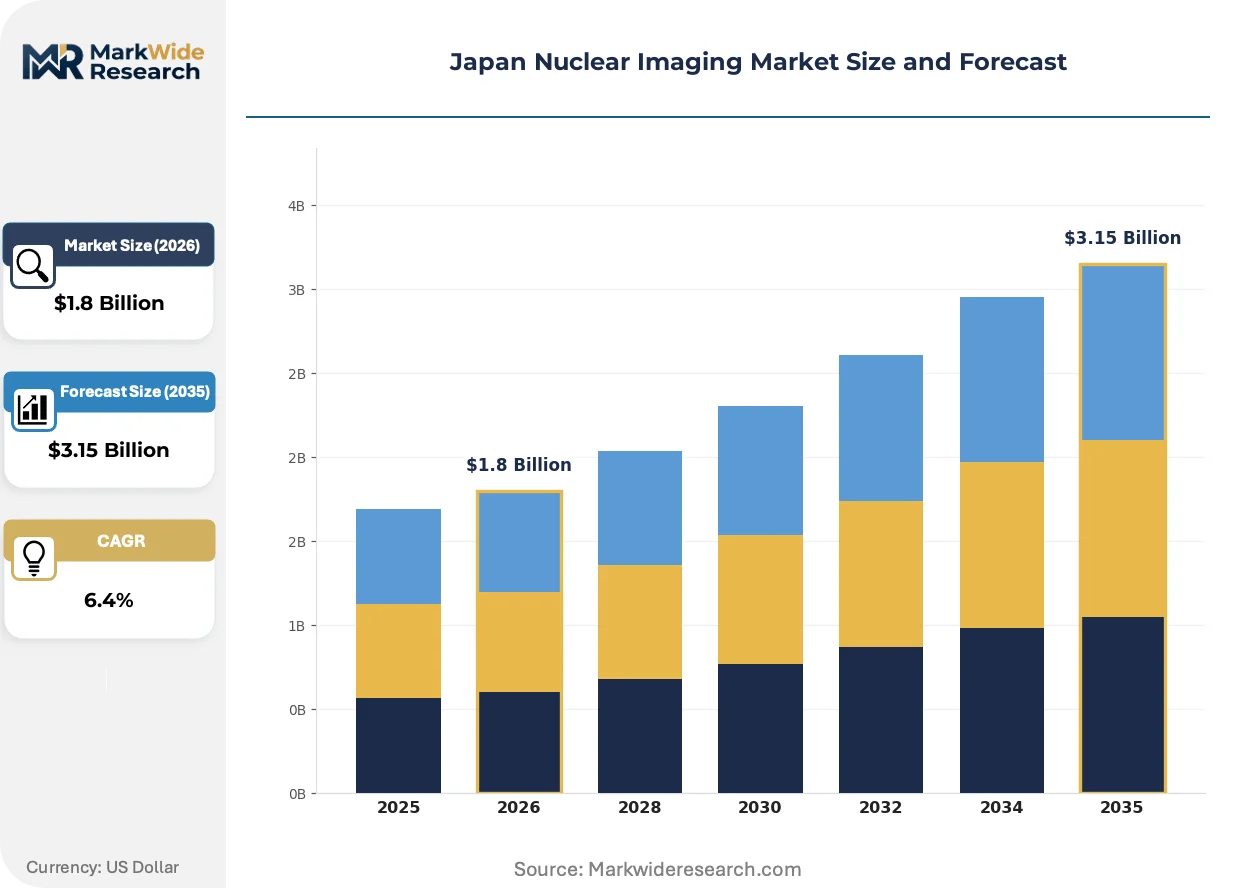
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Photon Emission Computed Tomography, Positron Emission Tomography, Radioisotope, Radiopharmaceuticals Application: Oncology, Cardiology, Neurology, Thyroid End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics Technology: Hybrid Imaging, Computed Tomography, Magnetic Resonance Imaging, Digital PET |
| Companies Covered | GE Healthcare, Siemens Healthineers, Canon Medical Systems Corporation, Koninklijke Philips, Fujifilm Healthcare Corporation, Nihon Medi-Physics Co., Ltd., Shimadzu Corporation, Bracco Imaging, ATOX Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Nuclear Imaging Market Shifts & Advancements
Digital silicon photomultiplier detectors are displacing conventional photomultiplier tubes across new system installations. This sensor transition is compressing scanner form factors while expanding quantitative imaging capabilities.
Digital silicon photomultiplier arrays detect 511 keV annihilation photons with higher photon detection efficiency than legacy vacuum tube technology. University hospitals in Tokyo and Osaka are specifying this detector architecture for new PET-CT procurements. The technology is rewriting spatial resolution benchmarks, forcing incumbent suppliers to accelerate detector roadmaps or cede premium positioning.
PMDA's 2023 radiopharmaceutical GMP guideline revision mandates real-time environmental monitoring and automated batch record systems. Domestic manufacturers must retrofit existing cleanroom infrastructure or construct greenfield facilities. Small-scale compounders in the Kansai region face consolidation pressure as compliance costs exceed standalone operational viability.
Hospital procurement committees are unbundling equipment acquisition from radiopharmaceutical supply contracts. Previously integrated ten-year service agreements are fragmenting into separate capital equipment and per-dose supply arrangements. This pattern is most visible at prefectural cancer centers seeking operational flexibility amid isotope supply uncertainty.
Japan Nuclear Imaging Market Segmentation
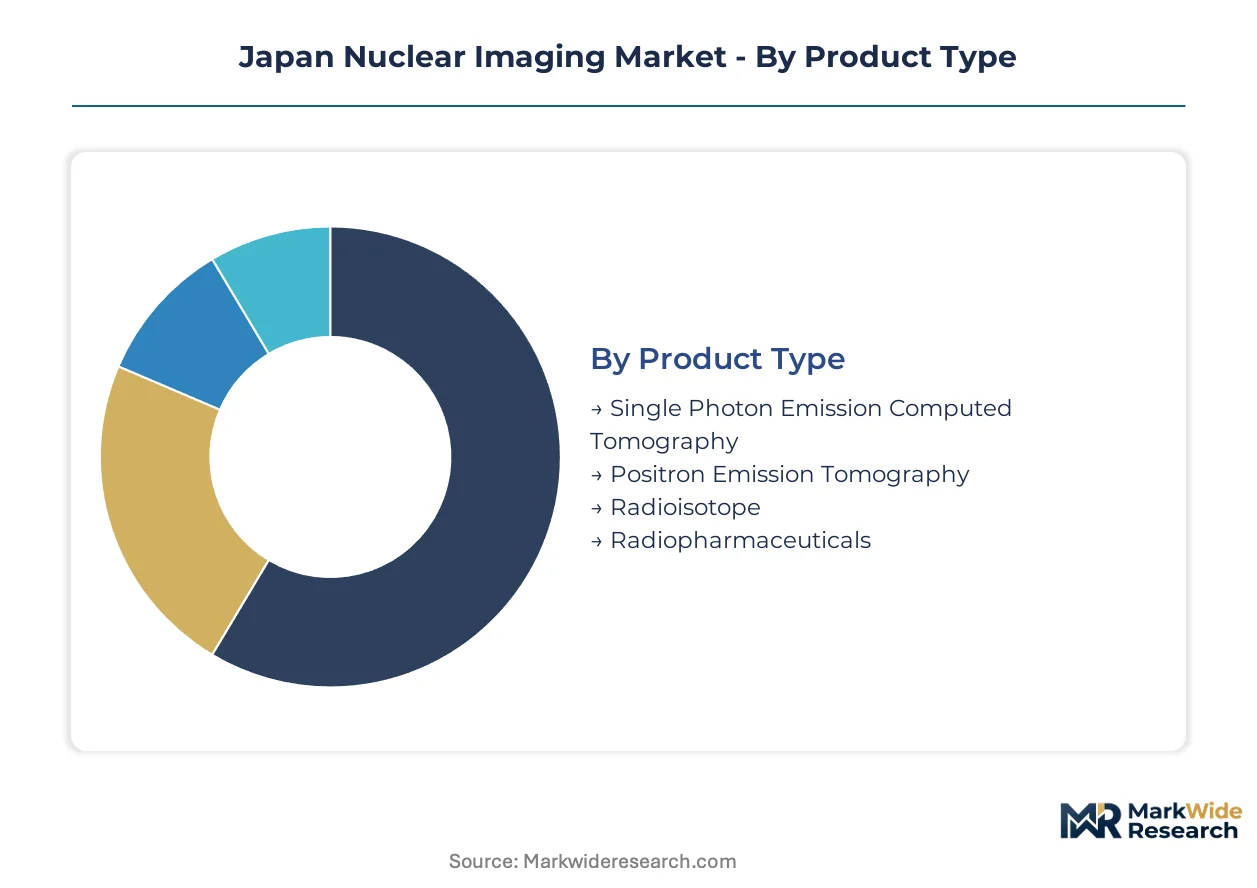
Segmentation in Japan's nuclear imaging market reveals distinct procurement patterns across equipment types and clinical settings. METI's domestic isotope initiative and PMDA's GMP enforcement are reshaping how facilities prioritize capital deployment across these categories.
Product Type:
Standalone systems dominate capital budgets while integrated radiopharmaceutical production capabilities determine supply security for hybrid configurations.
- Positron Emission Tomography:PET systems detect 511 keV annihilation photons from fluorine-18 decay, delivering quantitative metabolic imaging for oncology staging. Tokyo metropolitan university hospitals are prioritizing these systems for immunotherapy response monitoring, though cyclotron proximity constraints limit deployment to facilities within the 110-minute FDG distribution radius.
- Radiopharmaceuticals:This margin-intensive segment encompasses FDG, technetium-99m labeled compounds, and emerging theranostic agents. Domestic production capabilities under METI's infrastructure push are reducing exposure to North American reactor maintenance schedules at Osaka's Kansai biocluster facilities.
- Single Photon Emission Computed Tomography:SPECT systems utilizing 140 keV technetium-99m photons serve myocardial perfusion and bone imaging applications at prefectural hospitals.
- Radioisotope:Bulk isotope supply including molybdenum-99 generators and fluorine-18 precursors flows through cyclotron networks and import channels.
PET equipment leads volumes today; radiopharmaceuticals are gaining share fastest.
Application:
Clinical utility varies sharply by disease area, with reimbursement pathways and guideline adoption driving facility-level investment decisions.
- Oncology:Cancer staging and treatment response assessment commands the largest share of FDG-PET utilization. Precision oncology protocols at Keio University and Osaka University hospitals are expanding PET-CT deployment for immunotherapy monitoring, with PMDA reimbursement alignment accelerating adoption curves.
- Cardiology:Myocardial perfusion imaging using technetium-99m sestamibi or tetrofosmin remains the workhorse application for SPECT systems. Diagnostic centers in Osaka's Kansai corridor are consolidating stress-test volumes as hospital outpatient departments face capacity constraints.
- Neurology:Amyloid and tau PET imaging for Alzheimer's disease diagnosis is emerging at specialized memory clinics. PMDA approval timelines for novel radiotracers constrain near-term volume expansion.
- Thyroid:Iodine-131 and technetium-99m pertechnetate imaging for hyperthyroidism and cancer follow-up serves established protocols at general hospitals.
Oncology leads volumes today; neurology is expanding most quickly.
End User:
Procurement authority and capital access separate institutional tiers, with research affiliations determining hybrid imaging adoption rates.
- Hospitals:University-affiliated tertiary centers in Tokyo and Osaka anchor PET-CT and PET-MRI deployment. PMDA's tightened GMP standards are forcing radiopharmaceutical supply chain restructuring at these institutions.
- Research Institutions:Osaka University and Keio University facilities are specifying digital silicon photomultiplier detector architectures for neuro-oncology applications requiring soft-tissue contrast without CT radiation.
- Diagnostic Centers:Independent imaging facilities concentrate SPECT volumes for cardiology and bone scans, facing reimbursement pressure from hospital outpatient departments.
- Clinics:Small-scale thyroid and limited cardiac imaging operations rely on technetium-99m generator supply from regional distributors.
Hospitals lead volumes today; research institutions are climbing the fastest.
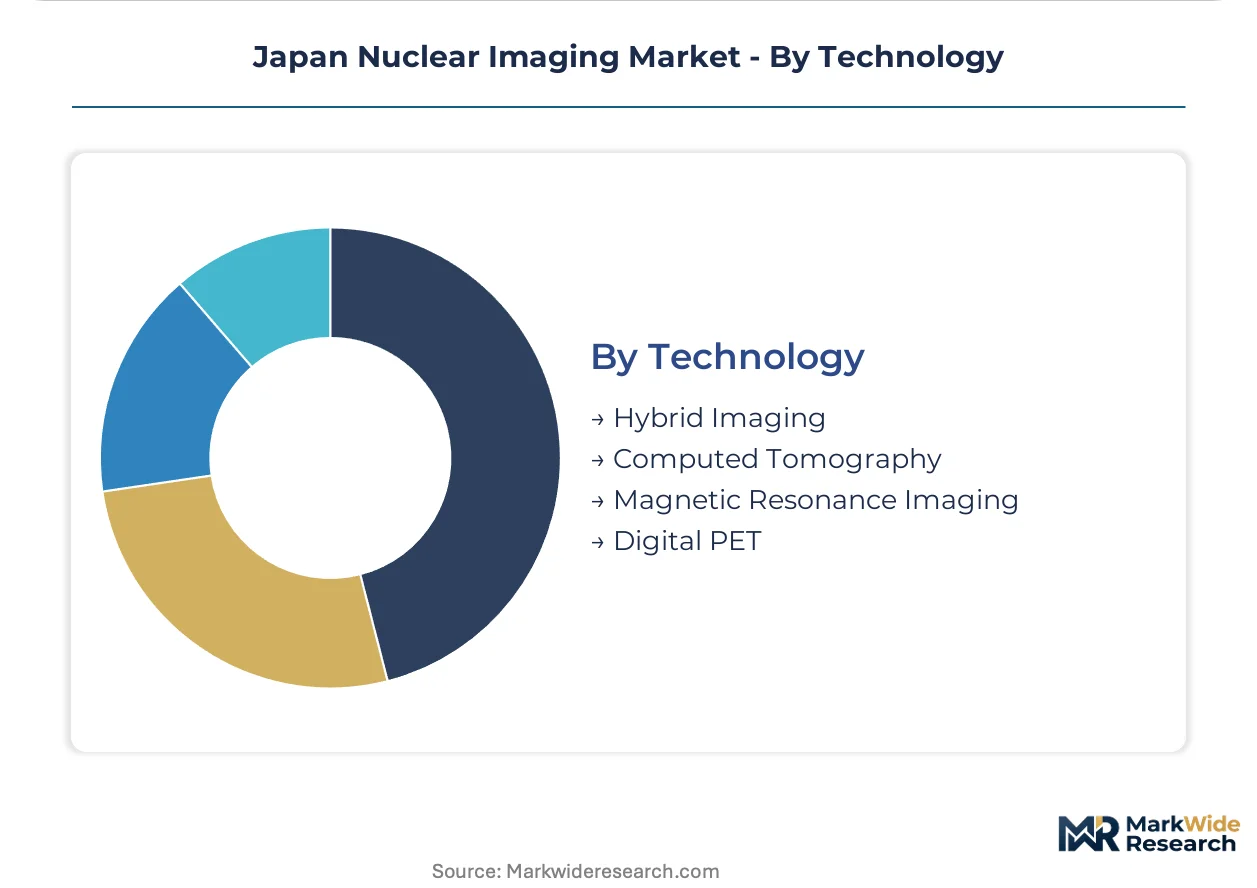
Technology:
Detector architecture transitions and modality integration patterns are rewriting competitive positioning across procurement cycles.
- Hybrid Imaging:PET-CT configurations dominate current installations, while PET-MRI systems are gaining traction at research institutions seeking soft-tissue contrast without ionizing radiation exposure. Osaka University's neuro-oncology program exemplifies this shift.
- Digital PET:Silicon photomultiplier detector arrays are displacing conventional photomultiplier tubes, compressing scanner form factors while expanding quantitative capabilities. Tokyo metropolitan hospitals are specifying this architecture for new procurements.
- Computed Tomography:Diagnostic CT components integrated into hybrid systems provide anatomical localization for functional PET data.
- Magnetic Resonance Imaging:MRI integration into PET-MRI configurations eliminates CT radiation dose for pediatric and repeat-imaging protocols.
Hybrid imaging leads volumes today; digital PET is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's nuclear imaging industry traces its modern foundations to post-war medical technology imports and subsequent domestic manufacturing scale-up during the 1970s-1980s, with cyclotron infrastructure expansion accelerating through METI-coordinated programs in the 2000s.
Kanto/Tokyo
Tokyo's metropolitan medical corridor concentrates the highest PET-CT installation density, driven by university hospital precision oncology protocols and immunotherapy response monitoring. PMDA reimbursement alignment for FDG-PET procedures accelerates capital deployment at Keio University Hospital and adjacent tertiary centers. The Tokyo Bay cyclotron network supplies fluorine-18 within the 110-minute decay window to this cluster.
Kansai/Osaka
Osaka's biocluster anchors contract radiopharmaceutical manufacturing expansion as METI's domestic isotope initiative reduces import dependency. Osaka University neuro-oncology programs specify PET-MRI configurations for soft-tissue contrast applications. Prefectural cancer centers in the corridor face restructuring pressure as PMDA GMP compliance costs exceed standalone distributor capacity.
Chubu/Nagoya
Nagoya's manufacturing heritage supports precision detector component supply chains for digital silicon photomultiplier arrays. Aichi Prefecture hospital networks consolidate SPECT volumes for myocardial perfusion imaging amid budget constraints. The region's cyclotron facilities serve as backup production nodes during metropolitan supply disruptions.
Kyushu
Fukuoka's medical corridor experiences delayed hybrid imaging adoption due to extended capital committee approval timelines at prefectural hospitals. The region relies on technetium-99m generator supply from Osaka-based distributors, creating vulnerability to cold chain integrity risks during metropolitan traffic congestion. Domestic cyclotron deployment remains sparse relative to patient demand.
Hokkaido
Sapporo's university hospitals maintain legacy SPECT systems for thyroid and limited cardiac imaging, constrained by fluorine-18 distribution radius limitations from Honshu production centers. The region's geographic isolation amplifies supply security concerns as METI prioritizes cyclotron network density in western Japan. Seasonal tourism fluctuations complicate radiopharmaceutical demand forecasting.
Japan Nuclear Imaging Market Competitive Landscape
The competitive structure tilts toward integrated system suppliers with cyclotron-equipped radiopharmaceutical capabilities. Three archetypes dominate: multinational imaging equipment manufacturers with domestic cyclotron networks, regional radiopharmaceutical compounders facing consolidation pressure, and university-affiliated research system integrators. Dominant competitive moves include detector technology roadmaps displacing legacy architectures and procurement contract unbundling separating equipment from per-dose supply arrangements.
Among multinational equipment suppliers, GE Healthcare, Siemens Healthineers, and Canon Medical Systems Corporation exemplify the integrated system archetype. GE Healthcare leverages cyclotron network coverage across Honshu. Siemens Healthineers anchors hybrid imaging R&D partnerships with Japanese university hospitals. Canon Medical Systems Corporation occupies a position competing on spatial resolution metrics through integrated detector technology. Nihon Medi-Physics Co., Ltd. represents the domestic radiopharmaceutical specialist tier facing PMDA GMP compliance restructuring.
| Leading Market Players |
|---|
| GE Healthcare |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Koninklijke Philips |
| Fujifilm Healthcare Corporation |
| Nihon Medi-Physics Co., Ltd. |
| Shimadzu Corporation |
| Bracco Imaging |
| ATOX Co., Ltd. |
| Others |
Supply & Pricing Matrix
Tokyo metropolitan university hospitals concentrate procurement authority and enforce contract unbundling that separates capital equipment from per-dose radiopharmaceutical supply. This buyer concentration sustains premium positioning for hybrid imaging systems while compressing margins on commoditized technetium-99m generators.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates the market. Premium tiers attach to PET-MRI configurations with digital silicon photomultiplier detectors at research institutions, while standard PET-CT systems serve prefectural cancer centers and economy SPECT systems address diagnostic centers. Price differentiation rests on detector architecture sophistication and after-sales service bundling. Cost compression in the economy tier is intensifying because hospital capital committees face extended approval timelines. Diagnostic centers exhibit the highest price sensitivity, whereas university hospitals prioritize performance metrics over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements for fluorine-18 precursors mandate qualification of multiple cyclotron facilities within the 110-minute distribution radius. Geographic supply concentration centers on Japan's Honshu island, with backup nodes in South Korea and limited North American import channels for molybdenum-99. Raw material dependencies include enriched molybdenum-99 targets, cyclotron target materials, and specialized detector scintillator crystals. Single-source vulnerability at Canadian reactor facilities for molybdenum-99 creates structural exposure to maintenance cycle disruptions. Distribution runs through temperature-controlled metropolitan corridors with real-time decay monitoring.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where PMDA's 2023 radiopharmaceutical GMP guideline revision is accelerating demand for compliant manufacturing infrastructure and reshaping competitive viability thresholds.
For Market Incumbents: Deepen cyclotron network density across the Kansai biocluster to preempt supply security advantages. Invest in automated batch record systems and real-time environmental monitoring to satisfy PMDA compliance mandates before consolidation pressure eliminates mid-tier compounders. Threat substitution from AI-assisted image reconstruction demands accelerated detector roadmap execution to preserve premium positioning. For New Entrants and Emerging Players: Prefectural cancer centers in Kyushu represent an underserved buyer archetype with delayed hybrid imaging adoption and extended capital committee timelines. Contract radiopharmaceutical manufacturing services offer the most penetrable entry point, particularly for lutetium-177 theranostic agents. A go-to-market angle emphasizing PMDA GMP pre-qualification and cold chain reliability can displace import-reliant distributors. For Investors and Strategic Acquirers: Integrated imaging equipment manufacturers are the most active acquirer in this space, seeking radiopharmaceutical production capabilities to complete vertical service stacks. The five-to-ten year viability window favors targets with established PMDA regulatory track records and cyclotron-equipped infrastructure. The signal to watch is METI funding allocation shifts for domestic isotope production nodes.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Cyclotron Network Expansion | METI infrastructure coordination reduces Honshu supply vulnerability to North American reactor schedules. |
| Digital Detector Architecture Migration | Silicon photomultiplier arrays at Osaka University rewrite spatial resolution benchmarks for neuro-oncology. |
| PMDA GMP Compliance Investment | Automated cleanroom retrofits protect manufacturing viability against 2023 guideline enforcement. |
| Theranostics Service Integration | Lutetium-177 radioligand therapy unification at specialized oncology centers creates captive demand. |
| AI-Assisted Image Reconstruction | Deep learning algorithms at Tokyo metropolitan hospitals compress PET acquisition times without scanner expansion. |
Research Methodology
Bottom-up hospital procurement modeling reconciled against top-down cyclotron capacity tracking forms the analytical core. Primary interviews with cyclotron operations engineers, PMDA regulatory affairs specialists, hospital biomedical equipment procurement committees, and GPO contracts managers combined with secondary validation from METI infrastructure disclosures, PMDA GMP guideline documents, hospital procurement databases, and JIS equipment safety standards. Triangulation between facility-level capital deployment patterns and national isotope production capacity estimates ensures coherence across granular and aggregate perspectives.
Historical trendline analysis of PET-CT installation rates and radiopharmaceutical dose volumes established baseline momentum parameters across the projection horizon. Segmentation dimensions modeled include product type, application area, end-user institution tier, and detector technology architecture. CAGRs were derived from fitted trend extrapolation adjusted for regulatory milestone impacts. Industry-specific forecast inputs incorporate cyclotron facility commissioning timelines and PMDA reimbursement alignment schedules for novel radiotracers.
Underlying measurement precision varies by segment; Tokyo metropolitan hospital procurement data carries tighter precision than Kyushu prefectural estimates. Forecasts reflect assumptions regarding METI funding continuity and PMDA enforcement intensity. Deviation in North American molybdenum-99 reactor maintenance schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
US and Europe Digital Pathology Market
Medical Imaging
Preclinical Imaging (in-VIVO) Market
Medical Imaging
Brazil Nuclear Imaging Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
Digital Radiology Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Spain Mammography Market
Medical Imaging
Asia Pacific Nuclear Imaging Devices Market
Medical Imaging
Canada Mammography Market
Medical Imaging
Carotid Ultrasound Imaging Market
Medical Imaging
Middle East and Africa Digital X-Ray Devices Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Fluoroscopy and Mobile C-Arms Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
US Magnetic Resonance Angiography Market