
 Neuroendocrine Carcinoma Market | 2026-2036
Neuroendocrine Carcinoma Market Size, Share, and Industry Trends Forecast 2026-2036
Neuroendocrine Carcinoma Market Outlook
Aftermarket service revenue from long-acting somatostatin analog delivery is tilting toward integrated patient-monitoring platforms. Novartis AG leverages its radioligand therapy infrastructure to sustain premium positioning in nuclear medicine networks. Pfizer Inc anchors its presence through manufacturing scale in biologic injectables, while Ipsen Pharma specializes in sustained-release formulations for chronic neuroendocrine tumor management.
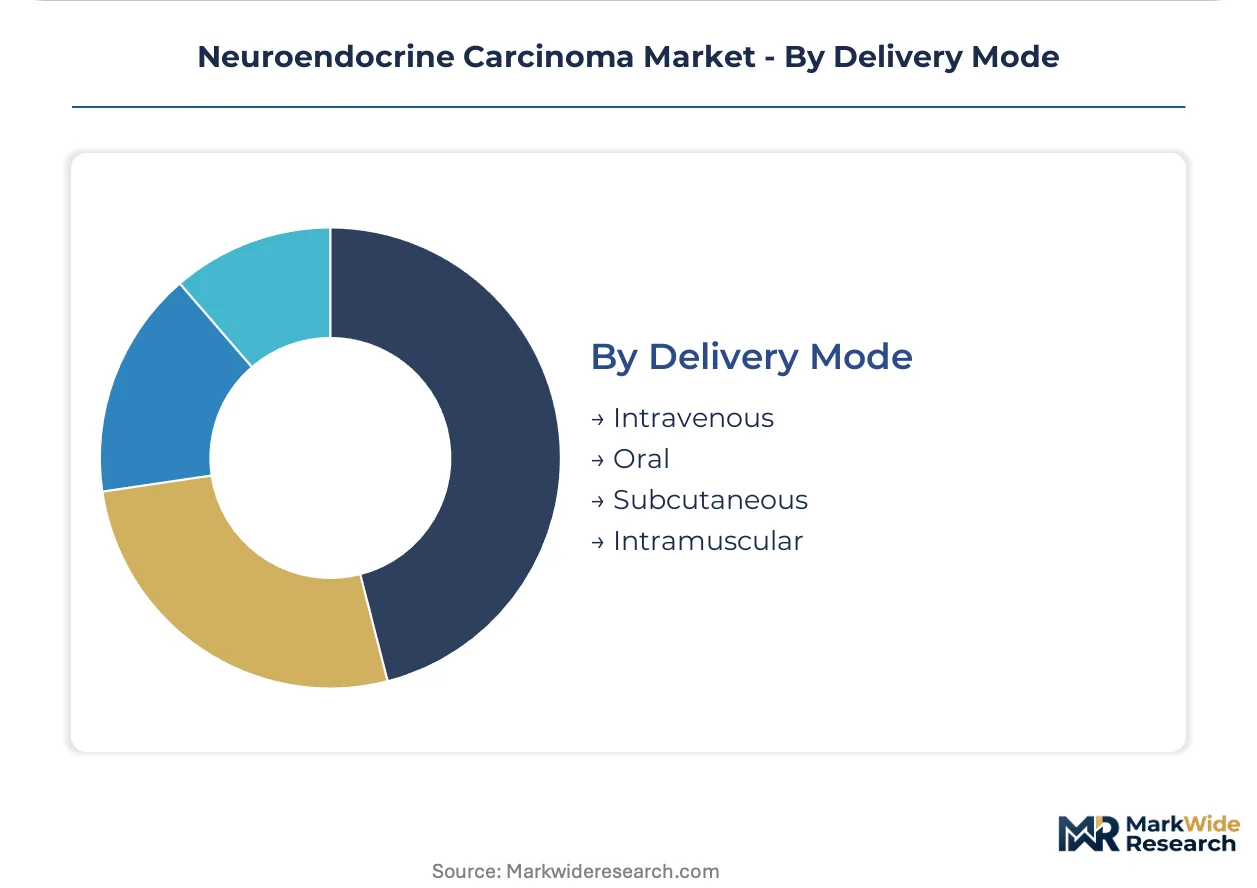
Neuroendocrine carcinoma denotes a heterogeneous group of malignancies arising from neuroendocrine cells distributed across the gastrointestinal tract, lungs, and endocrine organs, characterized by variable differentiation grades and secretory profiles including serotonin and chromogranin A. These tumors demand multimodal intervention spanning cytoreduction, hormone suppression, and targeted radionuclide delivery to manage both tumor burden and paraneoplastic syndromes. Targeted therapy commands the deepest margin pools where radiopharmaceutical supply constraints create scarcity premiums, while immunotherapy represents the fastest-expanding category as checkpoint inhibitors penetrate previously refractory high-grade populations. Delivery mode stratification shows intravenous administration dominating hospital-based revenue, though subcutaneous formulations are capturing outpatient clinic volume through reduced infusion center dependency.
FDA orphan drug designations and EMA rare disease frameworks shape trial design incentives and market exclusivity timelines for novel neuroendocrine agents. The EPA and national nuclear regulators govern radiopharmaceutical manufacturing, distribution, and waste handling standards that constrain site certification and geographic reach. Stakeholders must monitor evolving reimbursement thresholds for radioligand therapy across Medicare, statutory health insurance systems, and supplemental private coverage tiers.
Market Dynamics
Peptide receptor radionuclide therapy infrastructure is concentrating treatment capacity into certified nuclear medicine networks, creating scarcity premiums for site-certified providers while marginalizing community oncology practices lacking radiopharmaceutical handling capabilities.
Growth Catalysts
- EMA Orphan Drug Incentives:Extended market exclusivity timelines and protocol assistance are accelerating clinical trial investment for rare neuroendocrine indications across European reference networks.
- Japan's PMDA Sakigake Pathway:Priority review designation for innovative radioligand therapies is compressing regulatory timelines for novel somatostatin receptor-targeted agents.
- Specialty Cancer Center Expansion:Dedicated neuroendocrine tumor programs in the United States, Germany, and Japan are consolidating referral volumes and standardizing multimodal care pathways.
Market Restraints
- Isotope Supply Concentration:Lutetium-177 and Actinium-225 production depends on aging high-flux research reactors in the Netherlands, Canada, and Russia, creating geographic single points of failure.
- Radiopharmaceutical Manufacturing Complexity:Current Good Manufacturing Practice compliance for positron-emitting compounds requires dedicated cleanroom suites and cyclotron proximity, limiting site certification.
- Reimbursement Threshold Rigidity:Medicare's episode-based payment bundles and Germany's statutory health insurance reference pricing create coverage gaps for sequential radionuclide therapy cycles.
Strategic Opportunities
- India's CDSCO Accelerated Approval:Emerging regulatory pathways for orphan oncology indications offer first-mover positioning in an underpenetrated referral market.
- Subcutaneous Formulation Migration:Outpatient clinic administration of long-acting somatostatin analogs is displacing hospital-based infusion center dependency, capturing ambulatory surgery center volume.
- Theranostic Pair Integration:Gallium-68 DOTATATE imaging combined with Lutetium-177 DOTATATE therapy is creating unified diagnostic-therapeutic platforms for patient selection and response monitoring.
Industry Challenges
- Nuclear Medicine Physician Scarcity:Fellowship-trained radiopharmaceutical therapists remain concentrated in academic medical centers, constraining community site certification expansion.
- Waste Handling Compliance Burden:EPA and national nuclear regulator standards for radioactive waste storage, decay, and disposal extend facility commissioning timelines by 18-24 months.
- Biomarker Assay Standardization:Chromogranin A and neuron-specific enolase testing variability across reference laboratories complicates clinical trial endpoint harmonization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Neuroendocrine Carcinoma Market |
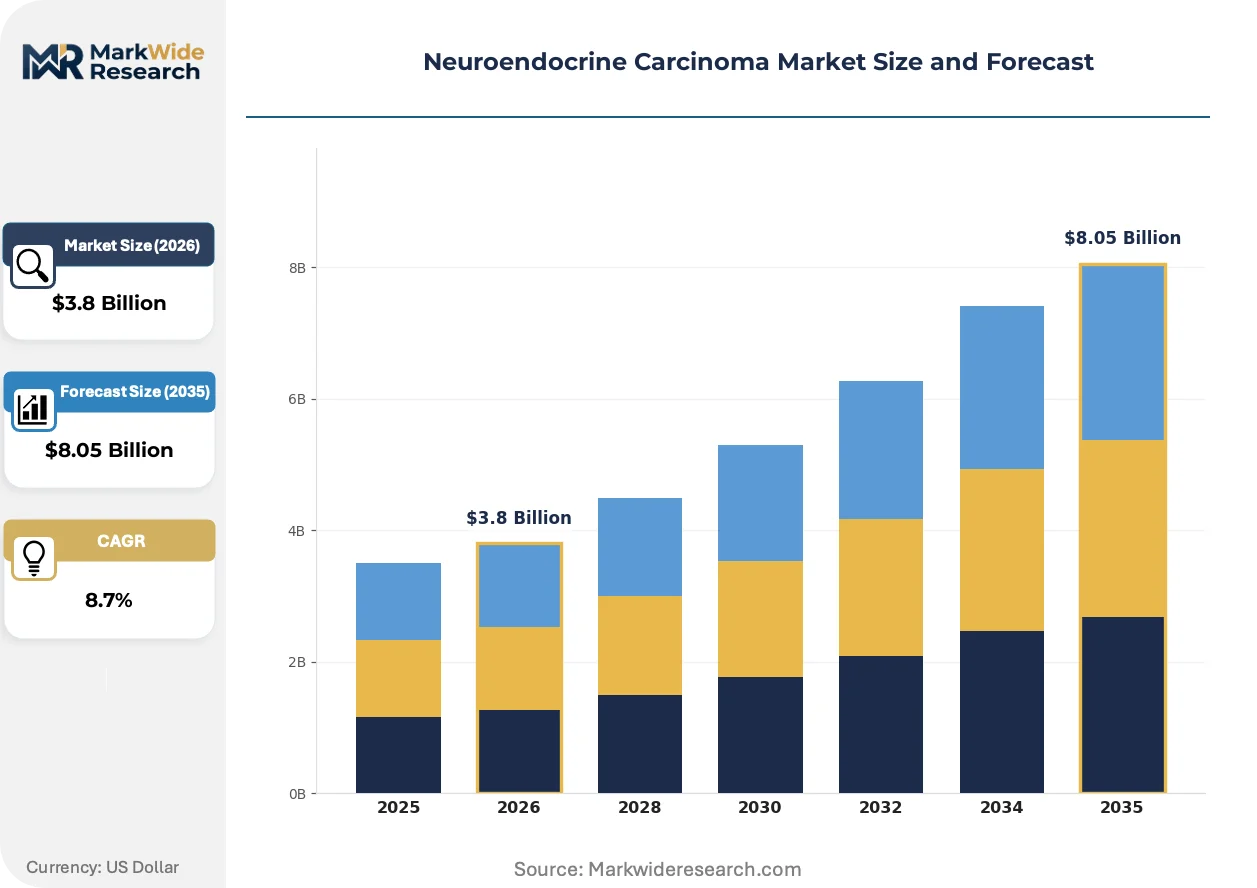
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Targeted Therapy, Immunotherapy End User: Hospitals, Clinics, Cancer Research Institutes, Specialty Centers Therapy Area: Gastrointestinal, Respiratory, Endocrine, Other Malignancies Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | Novartis AG, Pfizer Inc., Ipsen Pharma, Exelixis Inc, Bristol-Myers Squibb, Boehringer Ingelheim, Eli Lilly and Company, Hutchison China MediTech, Advanced Accelerator Applications, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Neuroendocrine Carcinoma Market Strategic Shifts
Radioligand therapy platforms are restructuring competitive boundaries between nuclear medicine specialists and medical oncologists, while regulatory convergence around theranostic pair approvals is reshaping clinical trial design and manufacturing investment priorities.
Alpha-emitting radiopharmaceuticals targeting somatostatin receptor subtype 2 are collapsing the therapeutic index advantage of beta-emitting predecessors in high-grade neuroendocrine neoplasms. Academic medical centers in Germany and the Netherlands are adopting these agents for heavily pretreated small-cell lung cancer variants and pancreatic neuroendocrine carcinoma with liver-dominant metastases. The shift is collapsing traditional chemotherapy sequencing protocols and compressing market windows for platinum-based regimens in refractory populations.
FDA's Project Orbis and EMA's parallel scientific advice programs are synchronizing review timelines for radioligand therapy submissions across the Atlantic. This regulatory convergence reduces redundant clinical trial infrastructure and accelerates patient access in both jurisdictions. High-grade neuroendocrine carcinoma indications with limited treatment options are receiving priority review vouchers, redirecting sponsor investment toward biomarker-selected trial populations.
Integrated patient-monitoring platforms are displacing standalone injection administration as the primary revenue capture mechanism for chronic somatostatin analog therapy. Specialty pharmacies and home infusion providers are consolidating ordering, adverse event reporting, and tumor marker tracking into unified digital interfaces. This consolidation is most visible in United States Medicare Advantage plans and German disease management programs, where risk-adjusted capitation rewards care coordination over product margin.
Neuroendocrine Carcinoma Market Segmentation
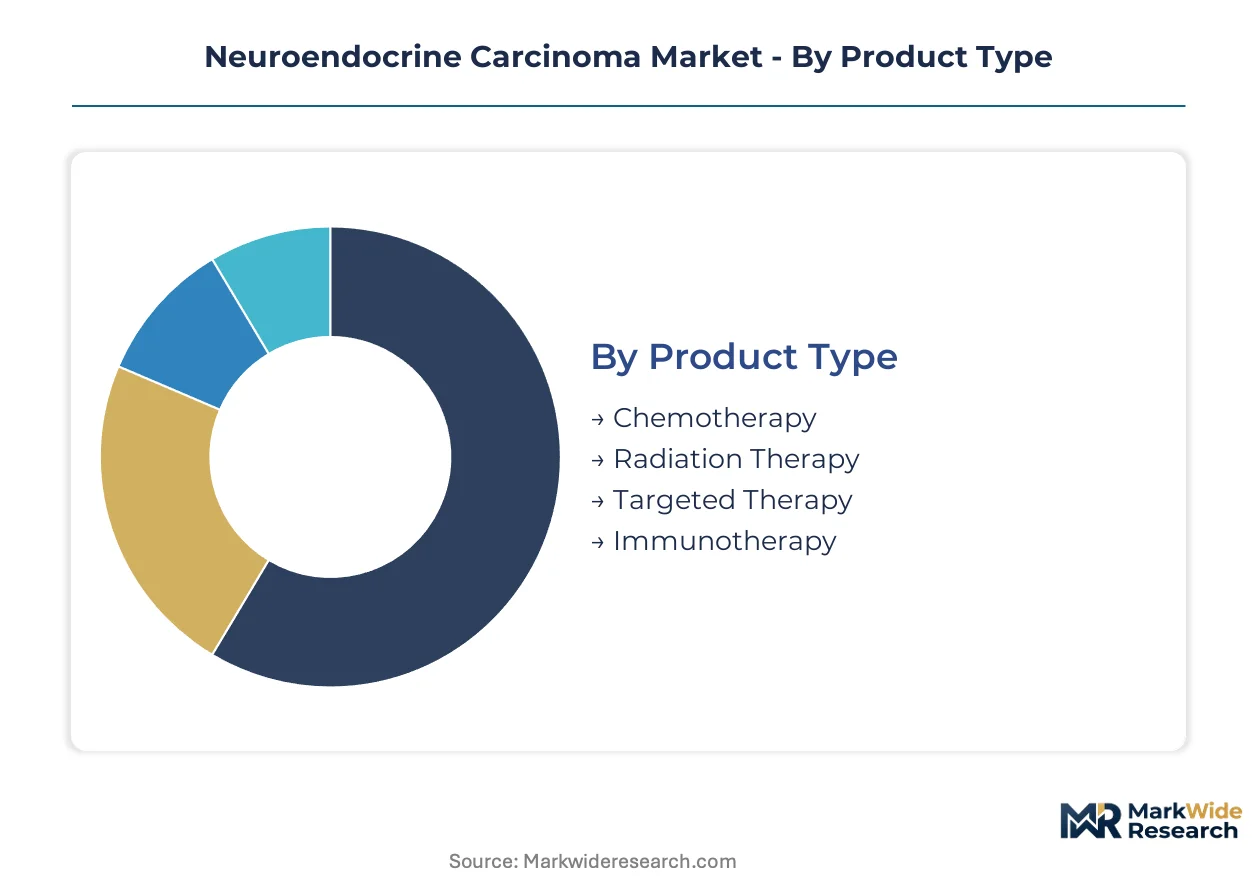
Segmentation in neuroendocrine carcinoma treatment reveals divergent margin profiles across delivery modes and therapy categories. Therapy area stratification exposes distinct referral network dependencies, while end-user concentration shapes capital equipment investment cycles.
Product Type:
Radioligand therapy cycles turn over fastest with quarterly dosing schedules, while immunotherapy protocols stretch longest through extended checkpoint inhibitor courses.
- Chemotherapy:Platinum-based regimens and temozolomide combinations remain foundational for high-grade neuroendocrine neoplasms. Demand concentrates in Germany and Japan where academic medical centers maintain established cytotoxic sequencing protocols for pancreatic and small-cell lung cancer variants.
- Radiation Therapy:External beam modalities and peptide receptor radionuclide therapy address localized and metastatic disease respectively. United States hospital networks are expanding Lutetium-177 DOTATATE capacity as Medicare reimbursement stabilizes for sequential therapy cycles.
- Targeted Therapy:Tyrosine kinase inhibitors and mTOR pathway blockers serve well-differentiated tumors.
- Immunotherapy:Checkpoint inhibitors penetrate refractory high-grade populations with limited alternatives.
Chemotherapy dominates installed base. Immunotherapy is where expansion concentrates.
End User:
Capital intensity separates high-investment nuclear medicine suites from scalable outpatient infusion operations.
- Hospitals:Academic medical centers and tertiary facilities house radiopharmaceutical manufacturing infrastructure, cyclotron proximity, and fellowship-trained nuclear medicine physicians. United States NCI-designated cancer centers and German university hospitals anchor regional referral networks for complex multimodal cases.
- Specialty Centers:Dedicated neuroendocrine tumor programs consolidate expertise across surgery, interventional radiology, and medical oncology. Japan's designated cancer care hospitals and select United States Medicare Advantage network sites are capturing risk-adjusted capitation through integrated care pathways.
- Clinics:Community oncology practices administer somatostatin analogs and oral targeted agents.
- Cancer Research Institutes:Phase I-II trial sites drive pipeline access for novel radioligand and alpha-emitter candidates.
Hospitals dominate installed base. Specialty centers are climbing the fastest.
Therapy Area:
Biomarker assay standardization varies dramatically across organ systems, complicating cross-trial endpoint harmonization.
- Gastrointestinal:Pancreatic, small intestinal, and colorectal neuroendocrine tumors constitute the largest addressable population with established somatostatin receptor imaging protocols. United States referral networks and European reference networks standardize Gallium-68 DOTATATE PET for patient selection.
- Respiratory:Typical and atypical pulmonary carcinoids plus small-cell lung cancer variants present distinct therapeutic challenges. German thoracic oncology centers are piloting alpha-emitting radiopharmaceuticals for liver-dominant metastases from high-grade lung primaries.
- Endocrine:Medullary thyroid carcinoma and pheochromocytoma demand specialized biochemical monitoring.
- Other Malignancies:Merkel cell carcinoma and rare neuroendocrine variants fall outside standardized protocols.
Gastrointestinal dominates installed base. Respiratory is gaining share fastest.
Delivery Mode:
Administration setting determines reimbursement mechanics and site certification requirements.
- Intravenous:Radioligand therapy and cytotoxic infusions require hospital-based administration with nuclear medicine oversight or infusion center staffing. United States hospital outpatient departments and German statutory health insurance contracted facilities capture episode-based bundled payments.
- Subcutaneous:Long-acting somatostatin analogs enable ambulatory surgery center and specialty pharmacy administration. United States Medicare Advantage plans and German disease management programs reward reduced infusion center dependency through risk-adjusted capitation models.
- Oral:Targeted agents permit home administration with remote monitoring.
- Intramuscular:Depot formulations serve specific hormonal suppression protocols.
Intravenous dominates installed base. Subcutaneous shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity for radioligand therapy varies sharply across reimbursement systems. Germany and Japan absorb premium pricing through statutory coverage, while United States patients face prior authorization hurdles that delay treatment initiation.
United States
Medicare Advantage capitation models reward integrated care coordination for chronic somatostatin analog therapy. The FDA's Project Orbis accelerates radioligand therapy approvals through synchronized review with Health Canada and Australia's TGA. NCI-designated cancer centers in Houston and Boston anchor regional referral networks for complex multimodal cases.
Germany
University hospitals in Heidelberg and Munich pilot alpha-emitting radiopharmaceuticals for high-grade neuroendocrine neoplasms. The EMA's orphan drug incentives extend market exclusivity timelines for rare indication submissions. Statutory health insurance reference pricing creates coverage negotiation leverage for sequential radionuclide therapy cycles.
Japan
Designated cancer care hospitals consolidate expertise across surgery and nuclear medicine for liver-dominant metastases. The PMDA's Sakigake pathway compresses regulatory timelines for innovative somatostatin receptor-targeted agents. Tokyo and Osaka metropolitan clusters concentrate fellowship-trained radiopharmaceutical therapists.
India
Private hospital chains in Mumbai and Delhi expand nuclear medicine capacity for gallium-68 DOTATATE imaging. The CDSCO's accelerated approval pathway for orphan oncology indications attracts first-mover investment. Regional reference laboratories standardize chromogranin A testing protocols for clinical trial enrollment.
Netherlands
PET radiopharmaceutical manufacturing concentrates around aging high-flux research reactors supplying lutetium-177. The EMA's centralized procedure streamlines pan-European market access for radioligand therapies. Rotterdam and Amsterdam academic centers lead theranostic pair integration for patient selection and response monitoring.
Neuroendocrine Carcinoma Market Competitive Environment
Radiopharmaceutical specialists and diversified oncology incumbents split the market along therapy modality lines. Consolidation concentrates around nuclear medicine networks with site certification capabilities, while fragmentation persists in oral targeted agents and supportive care. Three archetypes dominate: vertically integrated radioligand manufacturers, biologic injectable scale players, and sustained-release formulation specialists. Capacity expansion into cyclotron-adjacent manufacturing and strategic partnerships for isotope supply security represent the dominant competitive moves.
Within the radiopharmaceutical tier, Novartis AG and Advanced Accelerator Applications occupy positions anchored by nuclear medicine infrastructure investment. Pfizer Inc exemplifies the biologic injectable scale archetype through manufacturing breadth. Ipsen Pharma sits within the sustained-release specialization segment for chronic neuroendocrine tumor management. These three entities represent distinct strategic postures without implying specific market share or revenue claims.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Ipsen Pharma |
| Exelixis Inc |
| Bristol-Myers Squibb |
| Boehringer Ingelheim |
| Eli Lilly and Company |
| Hutchison China MediTech |
| Advanced Accelerator Applications |
| Others |
Value Chain & Pricing Dynamics
Amsterdam-Rotterdam-Antwerp freight corridors carry Lutetium-177 shipments from Dutch research reactors to German university hospitals, with transport cost volatility amplifying scarcity premiums at certified nuclear medicine sites while compressing margins at community oncology practices lacking radiopharmaceutical handling capabilities.
Pricing Analysis
Aftermarket service revenue from patient-monitoring platforms and injection administration now exceeds product margin for chronic somatostatin analog therapy. Three-tier pricing structure across premium radioligand therapy, standard biologic injectables, and economy oral targeted agents reflects site certification requirements and reimbursement bundling. Cost compression in the subcutaneous formulation tier is intensifying because Medicare Advantage capitation rewards ambulatory administration over hospital-based infusion. Community oncology practices show highest price sensitivity; academic medical centers with captive nuclear medicine infrastructure absorb premium positioning.
Supply Chain Analysis
Export-control regimes governing dual-use radiopharmaceutical technology limit Actinium-225 transfer from Russian research reactors to Western manufacturing sites. Supply concentrates in the Netherlands for Lutetium-177 production, Canada for isotope processing infrastructure, and Belgium for positron-emitting compound manufacturing. Raw material dependencies include high-purity Lutetium-177, Gallium-68 generators, and somatostatin receptor-binding peptide precursors. Single-source vulnerability at aging high-flux research reactors creates geographic concentration risk. Distribution runs through certified nuclear medicine networks with cyclotron proximity requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward United States Medicare Advantage plans and German statutory health insurance funds as these consolidated payers consolidate formularies and tighten prior authorization criteria for sequential radionuclide therapy cycles.
For Market Incumbents: Pre-empt commoditization of long-acting somatostatin analogs by deepening backward integration into patient-monitoring platform development and securing captive isotope supply agreements with Dutch and Canadian reactor operators. Novartis AG's radioligand therapy infrastructure exemplifies defensive positioning against emerging alpha-emitter specialists. Priority lever rests on theranostic pair integration to lock in referral network loyalty. For New Entrants and Emerging Players: Establish a beachhead in India's CDSCO accelerated approval pathway for orphan oncology indications, where private hospital chains in Mumbai and Delhi are expanding nuclear medicine capacity without entrenched competitor presence. Target respiratory neuroendocrine neoplasms as the most penetrable segment given German thoracic oncology centers' early adoption of alpha-emitting radiopharmaceuticals. Go-to-market angle centers on biomarker assay standardization partnerships with regional reference laboratories. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified pharmaceutical parents seeking to divest non-core oncology assets with radiopharmaceutical manufacturing capabilities. Long-term viability over the analysis window hinges on site certification scarcity and isotope supply security rather than molecule patent exclusivity. Watch for FDA Project Orbis synchronized approvals as inflection indicator for cross-Atlantic regulatory convergence accelerating market access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Theranostic Pair Integration | Gallium-68 DOTATATE imaging combined with Lutetium-177 DOTATATE therapy unifies diagnostic-therapeutic platforms for patient selection. |
| Isotope Supply Security Partnership | Long-term offtake agreements with Dutch and Canadian reactor operators mitigate geographic single points of failure in Lutetium-177 production. |
| Subcutaneous Formulation Migration | Ambulatory surgery center administration of long-acting somatostatin analogs captures Medicare Advantage capitation rewards. |
| Alpha-Emitter Pipeline Advancement | Actinium-225 somatostatin receptor-targeted agents address high-grade neuroendocrine neoplasms with collapsed therapeutic index. |
| Site Certification Expansion | Cyclotron-adjacent cleanroom manufacturing capacity enables geographic reach into underserved United States and Indian referral markets. |
Study Parameters
A spread of perspectives from nuclear medicine physicians, formulary directors at Medicare Advantage plans, regulatory affairs leads at radiopharmaceutical manufacturers, and hospital procurement managers converged on the working assumptions. Primary interviews combined with secondary validation from FDA orphan drug designation filings, EMA centralized procedure submissions, ClinicalTrials.gov entries for neuroendocrine carcinoma indications, and CMS Medicare reimbursement databases. Bottom-up patient flow modeling and top-down therapy category revenue triangulation anchored market sizing.
Demand-supply balance framing shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include therapy modality, delivery mode, differentiation grade, and regional regulatory cluster. CAGRs derived from therapy-specific adoption curves and reimbursement threshold evolution. Forecast inputs incorporated isotope production capacity at research reactors, site certification timelines for radiopharmaceutical handling, and biomarker assay standardization progress.
Macroeconomic conditions sit as an overlay; deviation in Medicare reimbursement bundling rules or EMA orphan drug incentive structures would shift the trajectory. Forecasts reflect documented assumptions about regulatory approval timelines and isotope supply continuity. Material shifts in Dutch or Canadian reactor operational status would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Australia Neurology Devices Market
Neurology
Neurocutaneous Disorders Market
Neurology
Global Acoustic Neuroma Market
Neurology
Global Neurology Clinical Trials Market
Neurology
United Kingdom Neurology Devices Market
Neurology
North America Neurology Devices Market
Neurology
Global Sciatica Treatment Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Global Diabetic Neuropathy Treatment Market
Neurology
Global Vertigo Treatment Market
Neurology
Arachnoid Cysts Treatment Market
Neurology
Cerebral Aneurysm Management Market
Neurology
Netherlands Neurology Devices Market
Neurology
Labyrinthitis Market
Neurology
Brazil Neurology Devices Market
Neurology
Neurology Devices Market