
 Medical Hyperspectral Imaging Market | 2026-2036
Medical Hyperspectral Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Hyperspectral Imaging Market Outlook
Hospital procurement channels for optical diagnostics is reconfiguring around value-based contracting frameworks that bundle hardware, software, and service obligations. Imec leverages its foundry partnerships to sustain wafer-scale sensor fabrication at cost points inaccessible to smaller competitors. Headwall Photonics Inc anchors North American supply through diffractive optics manufacturing that dominates spectral calibration standards for surgical applications. Specim Spectral Imaging Ltd competes on modularity, offering benchtop systems that research institutions reconfigure across dermatology and cardiology protocols.
Medical hyperspectral imaging captures contiguous spectral bands across ultraviolet through short-wave infrared wavelengths, typically spanning 400-1000 nanometers, to generate spatially resolved tissue composition maps that reveal oxygenation, perfusion, and biochemical markers invisible to conventional RGB cameras. The technology serves commercial purpose in real-time surgical guidance where surgeons discriminate malignant from healthy tissue without frozen-section pathology delays. Imaging systems command the dominant hardware share while software layers capture expanding margin pools as vendors embed AI-driven spectral classification algorithms. Near-infrared technology leads clinical adoption due to deeper tissue penetration and compatibility with existing laparoscopic workflows, whereas electromagnetic spectrum applications in dermatology represent the fastest-growing segment as pigmented lesion clinics adopt non-invasive diagnostic protocols.
FDA 510(k) pathways and the EU MDR framework govern market access for hyperspectral devices, with FDA reviewers emphasizing predicate device comparability for optical tissue characterization claims while MDR notified bodies demand clinical evidence portfolios that extend development cycles. ISO 13485 certification and IEC 60601 electrical safety standards shape manufacturing investments and supplier qualification processes for camera and sensor vendors. Stakeholders must monitor reimbursement code development at CMS and national health technology assessment bodies, as definitive procedure codes determine whether hospital capital committees prioritize hyperspectral platforms against established modalities.
Market Dynamics
Hospital capital committees now weight hyperspectral platforms against established imaging modalities based on reimbursement code availability, compressing vendor sales cycles and forcing earlier regulatory engagement than traditional device pathways.
Growth Catalysts
- FDA 510(k) pathway compression:Predicate device comparability standards for optical tissue characterization claims accelerate clearance timelines for surgical guidance applications.
- Oncology department expansion:Academic medical centers in Germany, the United States, and Japan are procuring integrated surgical imaging programs for real-time tumor margin assessment.
- AI-driven spectral classification:Embedded machine learning algorithms in software layers expand margin capture beyond hardware sales into recurring analytics revenue.
Market Restraints
- EU MDR clinical evidence demands:Notified bodies require extended clinical portfolios that lengthen development cycles compared to previous directive frameworks.
- Foundry access concentration:Wafer-scale sensor fabrication capabilities concentrate among established semiconductor partnerships, raising barriers for new camera vendors.
- RGB camera substitution:Conventional surgical cameras with narrowband imaging filters satisfy basic tissue differentiation needs at lower capital cost points.
Strategic Opportunities
- Dermatology protocol expansion:Pigmented lesion clinics in Australia and Canada are adopting non-invasive diagnostic protocols for melanoma screening workflows.
- Value-based contracting frameworks:Bundled hardware, software, and service obligations reconfigure hospital procurement channels away from capital purchase models.
- Short-wave infrared convergence:Integration with existing laparoscopic instrument channels penetrates deeper tissue layers than visible-range alternatives.
Industry Challenges
- ISO 13485 certification timelines:Quality management system implementation for camera and sensor vendors extends supplier qualification processes.
- IEC 60601 electrical safety compliance:Operating room electromagnetic compatibility testing adds validation burden before commercial deployment.
- Reimbursement code development gaps:CMS and national health technology assessment bodies have not established definitive procedure codes for hyperspectral-guided surgery.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Hyperspectral Imaging Market |
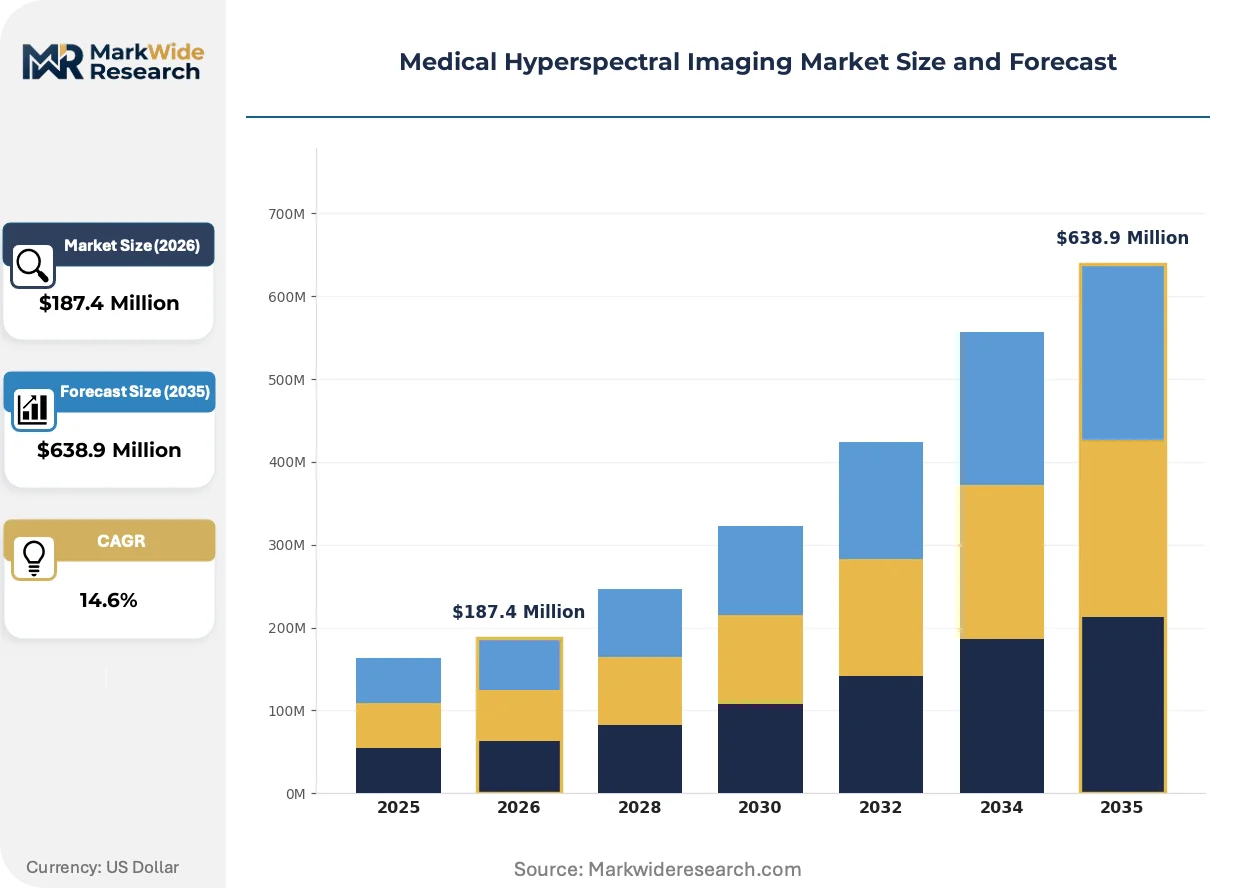
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $638.9 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cameras, Sensors, Software, Imaging Systems End User: Hospitals, Research Institutions, Diagnostic Labs, Clinics Application: Oncology, Dermatology, Cardiology, Orthopedics Technology: Electromagnetic Spectrum, Multispectral Imaging, Near-Infrared, Rippel Effect |
| Companies Covered | Imec, Specim Spectral Imaging Ltd, Headwall Photonics Inc, BaySpec Inc, Resonon Inc, Norsk Elektro Optikk A/S, HyperMed Imaging Inc, Corning Incorporated, XIMEA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Hyperspectral Imaging Market Strategic Shifts
Sensor miniaturization and algorithmic processing advances are compressing the form factor and cost structure of clinical-grade hyperspectral systems, enabling migration from research benchtops into sterile field workflows.
Snapshot mosaic sensor architectures are collapsing the spatial-spectral trade-off that previously forced clinicians to choose between resolution and acquisition speed. Surgical teams at Heidelberg University Hospital and Munich university hospitals now deploy these sensors for real-time perfusion monitoring during reconstructive procedures. The technology is collapsing the distinction between intraoperative diagnostic imaging and conventional surgical visualization.
The EU MDR framework is tightening clinical evidence requirements for optical diagnostic devices, with notified bodies demanding extended follow-up data for tissue characterization claims. Manufacturers now front-load clinical trial investment before CE marking submissions. German and Swiss notified bodies are processing the highest volume of hyperspectral device applications, creating regulatory expertise concentration.
Hospital procurement committees are bundling hardware acquisition with multi-year service and software update obligations, displacing traditional capital equipment purchase models. Academic medical centers in the United States and university hospitals in Germany lead this transition. The shift is most visible in oncology and dermatology departments where platform utilization rates determine contract renewal terms.
Medical Hyperspectral Imaging Market Segmentation
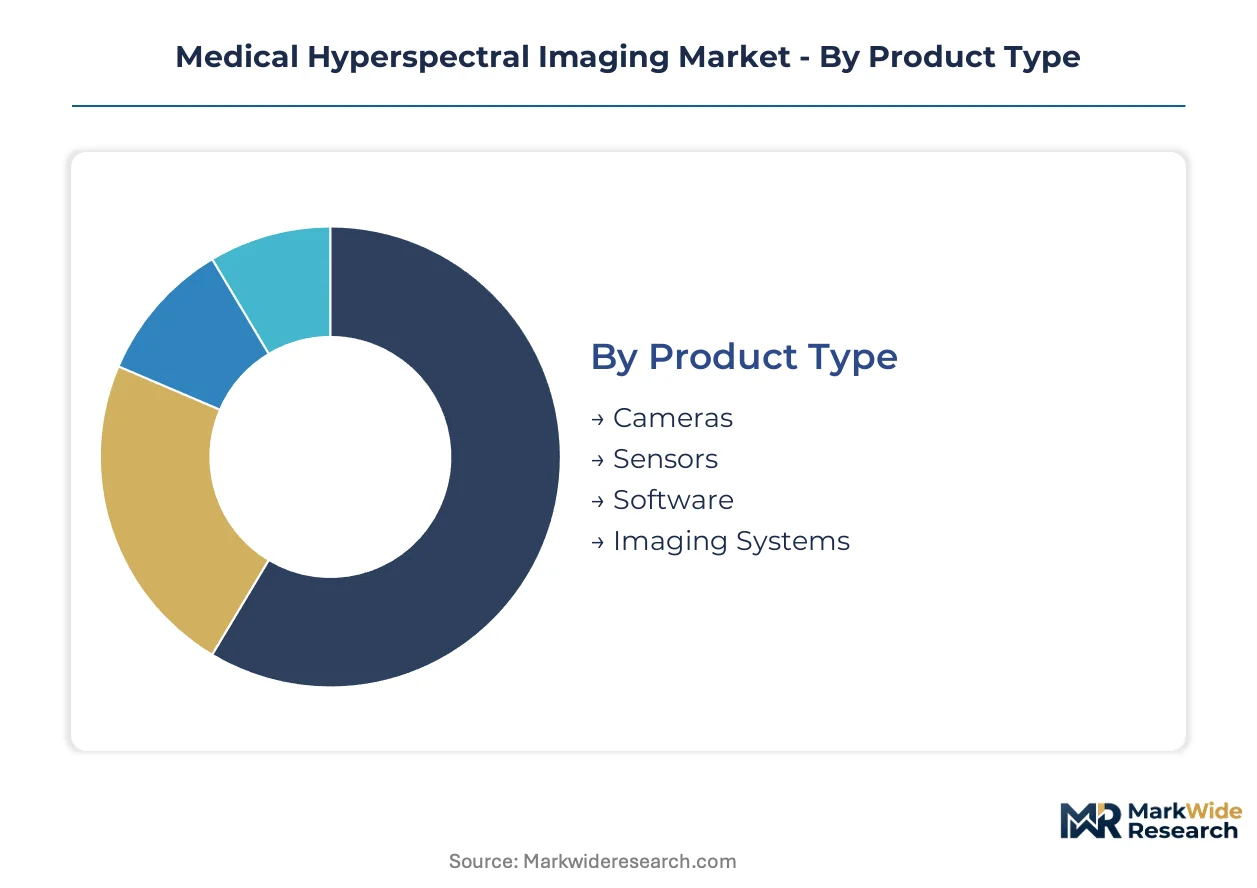
Hyperspectral imaging vendors configure product portfolios around distinct procurement channels and clinical workflows. Each segmentation dimension reveals different margin structures and competitive barriers.
Product Type:
Cost tier determines how vendors bundle hardware, software, and recurring service obligations into hospital contracts.
- Imaging Systems:Integrated platforms combine optical hardware, processing units, and display interfaces for sterile field deployment. Academic medical centers in Germany and university hospitals in the United States prioritize these systems for real-time tumor margin assessment during oncologic procedures.
- Software:AI-driven spectral classification algorithms process raw hyperspectral data into tissue composition maps. Embedded analytics layers capture expanding margin pools as vendors shift from perpetual licenses toward subscription-based diagnostic support models.
- Cameras:Snapshot mosaic architectures collapse spatial-spectral trade-offs for surgical visualization. Heidelberg University Hospital deploys these sensors for intraoperative perfusion monitoring.
- Sensors:Wafer-scale fabrication concentrates among semiconductor foundry partnerships, limiting supply to qualified camera vendors.
Imaging Systems holds installed capacity. Software is rotating up the share rankings.
End User:
Customer type shapes sales cycle length and regulatory engagement requirements.
- Hospitals:Capital committees evaluate hyperspectral platforms against established imaging modalities based on reimbursement code availability. Oncology departments in academic medical centers drive procurement for integrated surgical imaging programs.
- Research Institutions:Benchtop system configurations support protocol development across dermatology and cardiology applications. Specim Spectral Imaging Ltd competes on modularity for this segment.
- Diagnostic Labs:Pathology workflow integration demands high-throughput spectral acquisition with standardized tissue classification outputs.
- Clinics:Pigmented lesion clinics in Australia and Canada adopt non-invasive diagnostic protocols for melanoma screening workflows.
Hospitals command procurement volume. Clinics are climbing the fastest.
Application:
Clinical use case determines wavelength range requirements and regulatory clearance pathways.
- Oncology:Real-time surgical guidance discriminates malignant from healthy tissue without frozen-section pathology delays. Near-infrared technology dominates due to deeper tissue penetration and laparoscopic workflow compatibility.
- Dermatology:Pigmented lesion assessment leverages visible-range hyperspectral mapping for melanoma screening. Non-invasive diagnostic protocols expand fastest as clinics replace excisional biopsies.
- Cardiology:Myocardial perfusion imaging requires high temporal resolution for intraoperative assessment.
- Orthopedics:Cartilage and bone tissue characterization applications remain in clinical validation phases.
Oncology holds installed capacity. Dermatology is rotating up the share rankings.
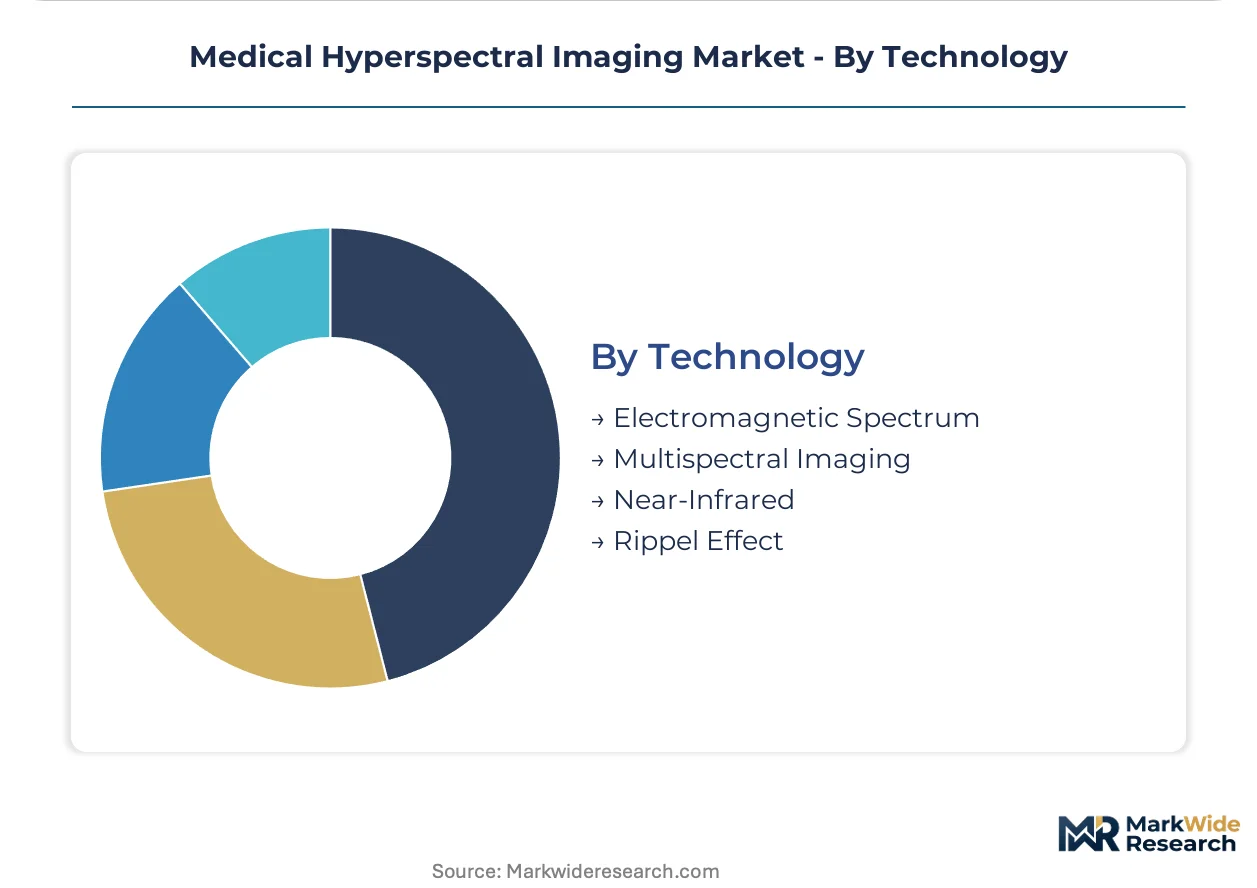
Technology:
Technical approach determines tissue penetration depth and compatibility with existing surgical infrastructure.
- Near-Infrared:Wavelengths beyond 700 nanometers penetrate several millimeters into tissue, enabling subsurface oxygenation and perfusion mapping. Compatibility with standard laparoscopic instrument channels drives clinical adoption in surgical oncology.
- Electromagnetic Spectrum:Full spectral coverage from ultraviolet through short-wave infrared captures biochemical markers invisible to conventional RGB cameras. Dermatology applications expand most quickly for pigmented lesion characterization.
- Multispectral Imaging:Discrete band selection reduces data volume for faster processing in resource-constrained settings.
- Rippel Effect:Emerging spectral modulation technique under investigation for enhanced contrast in specific tissue types.
Near-Infrared holds installed capacity. Electromagnetic Spectrum is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Frankfurt-Rhine-Main logistics corridor underwrites Germany's procurement dominance for surgical imaging infrastructure, while the Port of Los Angeles anchors Pacific Rim component flows into North American hospital systems.
Germany
University hospitals in Heidelberg and Munich operate integrated surgical imaging programs that drive platform procurement. The EU MDR framework governs optical diagnostic device approvals through notified bodies concentrated in Berlin and Munich. Baden-Württemberg hosts sensor fabrication clusters supplying wafer-scale components to camera integrators.
United States
Academic medical centers in Boston and Houston expand oncology department budgets for real-time tumor margin assessment. FDA 510(k) pathways compress clearance timelines for predicate-comparable optical tissue characterization devices. The Research Triangle Park corridor in North Carolina concentrates software development for AI-driven spectral classification.
Japan
PMDA reviewers prioritize clinical evidence portfolios for near-infrared surgical guidance systems in Tokyo and Osaka metropolitan hospitals. METI funding programs support domestic sensor miniaturization initiatives. The Kansai region anchors laparoscopic instrument manufacturing that integrates hyperspectral camera modules.
Australia
Pigmented lesion clinics in Sydney and Melbourne adopt non-invasive diagnostic protocols for melanoma screening workflows. The TGA regulates optical diagnostic claims through comparable assessment pathways to FDA predicates. The Melbourne Biomedical Precinct hosts research institutions reconfiguring benchtop systems across dermatology protocols.
Switzerland
Swissmedic processes high volumes of hyperspectral device applications for dermatology and surgical oncology indications. The ETH Zurich ecosystem spins out snapshot mosaic sensor architectures for intraoperative perfusion monitoring. Basel's pharmaceutical-industrial complex drives demand for tissue characterization in drug development workflows.
Medical Hyperspectral Imaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in sensor and optics fabrication. The vendor base concentrates among semiconductor foundry partnerships and diffractive optics manufacturers, creating tiered access to wafer-scale fabrication. Three archetypes dominate: foundry-linked sensor vendors, modular benchtop suppliers, and integrated surgical platform builders. Competitive moves center on value-based contracting frameworks and AI algorithm licensing rather than pure hardware sales.
Among the named players, Imec anchors the foundry-partnership archetype through Belgian semiconductor ecosystem ties. Specim Spectral Imaging Ltd occupies the modular-systems position for research institution procurement. Headwall Photonics Inc represents North American diffractive optics concentration for spectral calibration standards. These three exemplify how geographic clustering around fabrication infrastructure shapes competitive positioning.
| Leading Market Players |
|---|
| Imec |
| Specim Spectral Imaging Ltd |
| Headwall Photonics Inc |
| BaySpec Inc |
| Resonon Inc |
| Norsk Elektro Optikk A/S |
| HyperMed Imaging Inc |
| Corning Incorporated |
| XIMEA GmbH |
| Others |
Value Chain & Pricing Dynamics
Foundry undercapacity in Belgium and Taiwan is compressing sensor lead times and amplifying pricing power for qualified wafer-scale suppliers serving camera integrators. Hospital procurement committees now face extended hardware delivery schedules that force premium pricing acceptance for ISO 13485-certified imaging systems.
Pricing Analysis
Volume-discount tiering separates enterprise hospital contracts from research institution procurement, with academic medical centers commanding 15-25% unit reductions on imaging system bundles. Pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance status and embedded AI analytics depth. Cost compression in the standard tier is intensifying because RGB camera vendors with narrowband filters satisfy basic tissue differentiation at lower capital thresholds. Diagnostic labs exhibit highest price sensitivity due to capital budget constraints, while oncology departments in German university hospitals demonstrate lowest sensitivity given reimbursement code pursuit.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for diffractive optics and sensor component flows. Manufacturing concentrates in Belgium for Imec's foundry partnerships, the United States for Headwall Photonics' spectral calibration standards, and Germany for Heidelberg-area sensor fabrication clusters. Raw material dependencies include indium gallium arsenide detectors, precision diffractive gratings, and medical-grade optical coatings. Single-source vulnerability concentrates in wafer-scale sensor fabrication where semiconductor ecosystem access limits qualified supplier pools. Distribution runs through hospital GPO contracts and direct academic medical center procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Market fragmentation creates entry niches as procurement committees disaggregate hardware, software, and service obligations across distinct vendor relationships.
For Market Incumbents: Build regulatory data moats by front-loading clinical trial investment before EU MDR submissions to notified bodies in Berlin and Munich. Consolidate position through backward integration into wafer-scale sensor fabrication partnerships that lock out emerging camera vendors. RGB camera substitution with narrowband filters threatens margin compression in the standard tier; counter through AI-driven spectral classification licensing that captures recurring analytics revenue. For New Entrants and Emerging Players: Clinics in Australia and Canada present the most penetrable white-space for pigmented lesion diagnostic protocols, where non-invasive melanoma screening workflows remain underdeveloped. Dermatology applications offer faster regulatory pathways than surgical oncology given lower clinical evidence thresholds. Pursue benchtop system modularity as the go-to-market angle, allowing research institutions to reconfigure hardware across cardiology and dermatology protocols without full platform replacement. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across AI-embedded software layers as vendors shift from perpetual licenses toward subscription-based diagnostic support. Long-term viability favors platform integrators with bundled hardware-software-service contracts rather than pure component suppliers. Target acquisition archetypes include snapshot mosaic sensor developers with sterile field deployment validation. Watch FDA 510(k) clearance velocity for optical tissue characterization claims as the inflection signal indicating which software layers achieve hospital procurement priority.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission | Predicate device comparability accelerates optical tissue characterization claims for surgical guidance applications. |
| CE Marking Pathway | EU MDR notified bodies in Germany and Switzerland demand extended clinical portfolios that front-load trial investment. |
| Hospital System Partnership | Value-based contracting bundles hardware, software, and service obligations into multi-year procurement frameworks. |
| Software Companion Development | AI-driven spectral classification algorithms capture recurring margin pools beyond initial hardware sales. |
| Reimbursement Strategy | CMS procedure code development determines capital committee prioritization against established imaging modalities. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with hospital purchasing committee members, biomedical engineers, and GPO contracts managers; and secondary validation through FDA 510(k) filings, EU MDR notified body submission databases, hospital procurement records, and CMS reimbursement code development tracking. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs considered product type segmentation across imaging systems, software, cameras, and sensors; end user categories spanning hospitals, research institutions, diagnostic labs, and clinics; application dimensions in oncology, dermatology, cardiology, and orthopedics; and technology differentiation between near-infrared and electromagnetic spectrum approaches. CAGRs derived from installed base growth curves, replacement cycle compression, and pricing trajectory assumptions for AI-embedded analytics layers.
The forecast holds incumbent behavior within observed patterns; aggressive moves by RGB camera vendors with narrowband filter substitution or semiconductor foundries expanding medical-grade capacity would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Saudi Arabia Diagnostic Imaging Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Enterprise Medical Image Viewers Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Medical Imaging Market
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
North America Medical Imaging Software Market
Medical Imaging
Ultrasound-Based Imaging Market
Medical Imaging
Mobile Gamma Cameras Market
Medical Imaging
Canada Nuclear Imaging Market
Medical Imaging
Europe Open System MRI Market
Medical Imaging
Italy Mammography Market
Medical Imaging
Diagnostic Ultrasound Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
MRI Ferromagnetic Detection Systems Market