
 Precision Cancer Imaging Market | 2026-2036
Precision Cancer Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Precision Cancer Imaging Market Outlook
Hospital procurement consolidation is repositioning vendor relationships across major health systems. Siemens Healthineers leverages its hybrid imaging portfolio to anchor long-term service contracts with integrated delivery networks. GE Healthcare competes through AI-embedded CT and MRI platforms that reduce scan times for oncology workflows.
Precision cancer imaging encompasses multimodal diagnostic systems that combine anatomical and functional data to characterize tumors with sub-millimeter resolution. PET-MRI systems achieve spatial resolution below 2 millimeters while simultaneously capturing metabolic activity, enabling clinicians to stage cancers and plan radiotherapy with molecular precision. Magnetic Resonance Imaging and Positron Emission Tomography dominate installed base value, though AI Imaging sustains the fastest expansion as algorithms automate lesion detection and treatment response quantification. Hybrid Imaging occupies premium margin pools where vendors bundle hardware with proprietary software analytics and recurring contrast agent revenues.
FDA's breakthrough device designation pathway accelerates AI-enabled imaging approvals, while the EU AI Act imposes conformity requirements on clinical decision-support algorithms entering European markets. ISO 13485 quality management standards govern manufacturing processes for imaging hardware and embedded software across regulated jurisdictions. Stakeholders must monitor evolving reimbursement codes for AI-augmented reads and radiomics-based response assessments as payers recalibrate coverage policies.
Market Dynamics
Hospital procurement consolidation across integrated delivery networks is compressing vendor relationships into long-term, multi-modality service agreements that bundle hardware, software, and consumables into unified contracts.
Growth Catalysts
- FDA Breakthrough Device Designation:The accelerated approval pathway compresses time-to-market for AI-enabled lesion detection algorithms, enabling faster clinical validation and reimbursement coding.
- Academic Medical Center Investment:Leading oncology centers in the United States are driving hybrid imaging adoption as they compete for National Cancer Institute designation and research funding.
- Radiomics Standardization:Quantitative imaging biomarker protocols are maturing through QIBA and other frameworks, creating reproducible endpoints for immunotherapy response monitoring.
Market Restraints
- Isotope Supply Concentration:Molybdenum-99 production concentrates in aging research reactors in Canada, the Netherlands, and South Africa, creating vulnerability in PET radiotracer availability.
- Capital Equipment Intensity:PET-MRI systems require specialized shielding, helium infrastructure, and facility renovations that extend deployment timelines to 18-24 months.
- Reimbursement Lag:CMS and private payers maintain limited coverage for AI-augmented reads and radiomics-based assessments, constraining clinical adoption velocity.
Strategic Opportunities
- Community Hospital Penetration:Mid-sized oncology programs in the United States represent underpenetrated demand for compact PET-CT systems with embedded AI workflow tools.
- Photon-Counting CT Convergence:Spectral imaging technology combined with dual-energy algorithms enables tissue characterization previously requiring multimodal protocols.
- Remote Reading Networks:Teleradiology platforms are creating new distribution channels that extend subspecialty interpretation access to rural and underserved regions.
Industry Challenges
- Computational Pathology Integration:Imaging departments face interoperability friction when merging radiology PACS with digital pathology systems for multidisciplinary tumor boards.
- Helium Supply Volatility:MRI magnet cooling depends on helium availability subject to export restrictions and price spikes, forcing vendors to develop closed-loop recovery systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Precision Cancer Imaging Market |
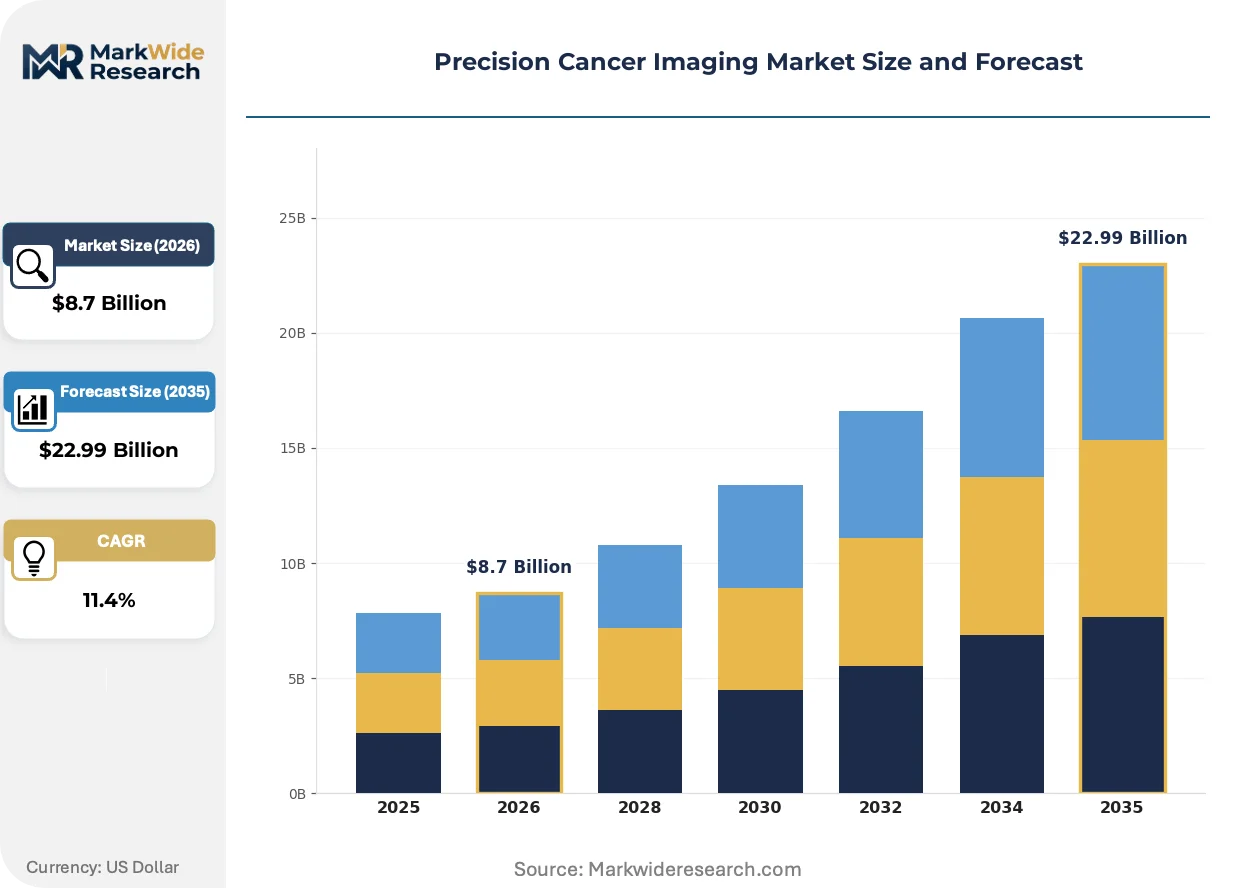
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Magnetic Resonance Imaging, Computed Tomography, Ultrasound, Positron Emission Tomography Technology: Hybrid Imaging, 3D Imaging, Radiomics, AI Imaging End User: Hospitals, Diagnostic Imaging Centers, Research Institutes, Outpatient Facilities Application: Tumor Detection, Treatment Planning, Monitoring Response, Surgical Guidance |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips, Canon Medical Systems, Hologic, Medtronic, Stryker, Olympus, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Precision Cancer Imaging Market Strategic Shifts
Artificial intelligence is restructuring how imaging data flows from acquisition through interpretation, compressing diagnostic timelines while fragmenting traditional hardware-software bundling models.
Deep learning reconstruction algorithms are modularizing CT and MRI acquisition protocols, enabling reduced scan times without compromising signal-to-noise ratios. Academic medical centers in the United States are deploying these tools to increase scanner throughput and reduce patient motion artifacts. The technology is modularizing vendor service offerings, separating algorithm licensing from hardware maintenance contracts and creating new recurring revenue streams for software analytics.
The EU AI Act imposes conformity assessment requirements on clinical decision-support algorithms entering European markets, mandating risk classification and post-market surveillance. Manufacturers must establish quality management systems exceeding ISO 13485 for software-as-medical-device products. High-risk AI imaging applications face notified body scrutiny that extends certification timelines, prompting vendors to prioritize US FDA clearance pathways before European commercialization.
Radiology group purchasing organizations are consolidating procurement authority across multi-hospital systems, unbundling equipment purchases from service agreements. Independent imaging centers and community hospitals are responding by joining regional buying cooperatives to access pricing parity with integrated delivery networks. This concentration is most visible in the United States, where three national GPOs now influence over sixty percent of diagnostic imaging capital expenditure decisions.
Precision Cancer Imaging Market Segmentation
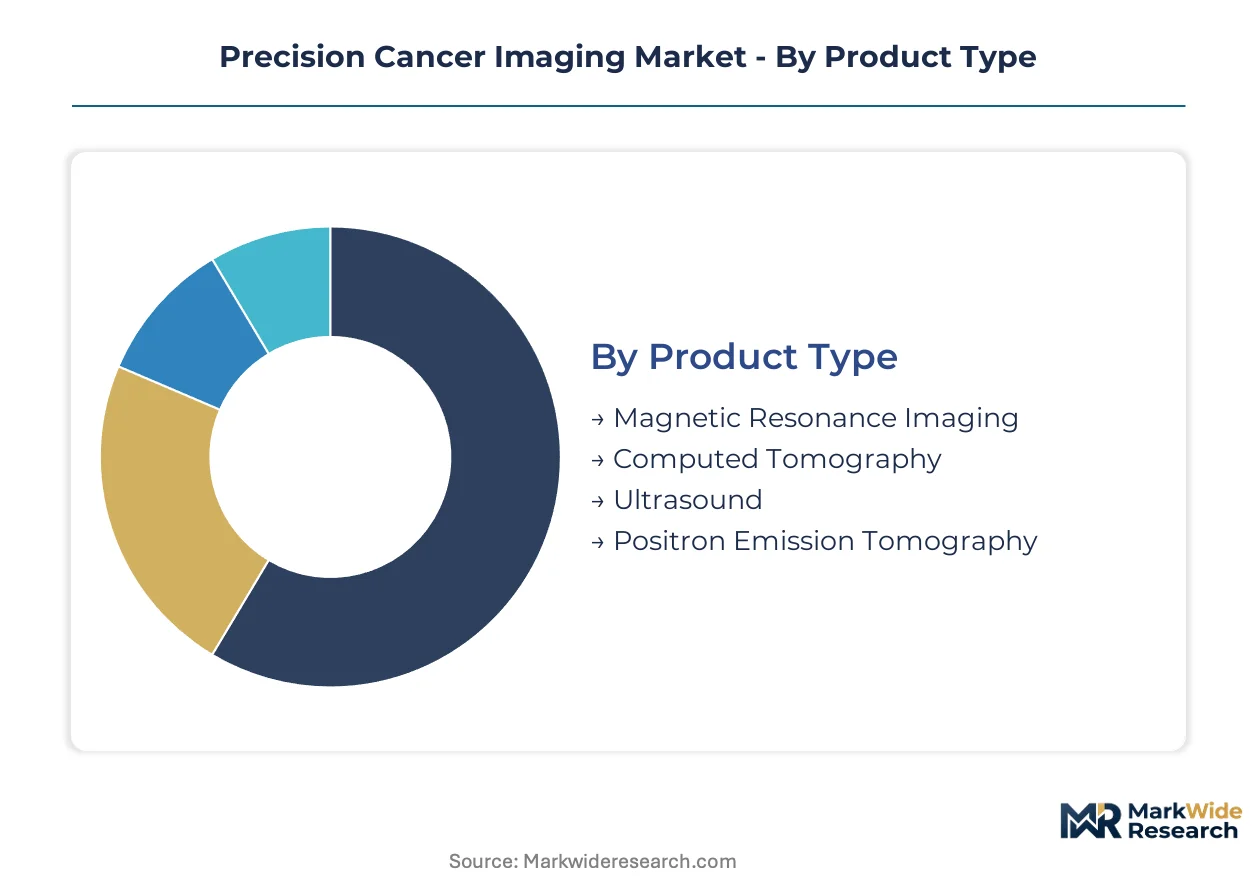
Precision cancer imaging segments reflect divergent capital intensity and reimbursement profiles. Modalities with established CPT codes command predictable revenue streams, while emerging technologies navigate coverage uncertainty. Technology selection varies by tumor type, with metabolic imaging dominating hematologic malignancies and anatomical precision guiding solid tumor staging.
Product Type:
Modality specifications determine spatial resolution, tissue contrast, and throughput capacity in oncology workflows.
- Magnetic Resonance Imaging:Soft tissue contrast resolution reaches sub-millimeter precision without ionizing radiation. Academic medical centers in the United States deploy 3 Tesla systems for multiparametric prostate and breast imaging protocols. Installation constraints include specialized magnet shielding and helium infrastructure.
- Positron Emission Tomography:Radiotracer-based metabolic imaging quantifies glucose uptake through FDG and novel agents targeting PSMA and DOTATATE. Demand concentrates in comprehensive cancer centers where PET-CT staging guides treatment selection for lymphoma and lung malignancies. Isotope supply vulnerability from aging research reactors constrains expansion timelines.
- Computed Tomography:Rapid acquisition enables thoracic and abdominal staging with spectral imaging advancing tissue characterization. Community hospitals prioritize CT for initial diagnosis given lower capital requirements and faster deployment.
- Ultrasound:Portable systems support intraoperative guidance and biopsy targeting with elastography advancing lesion characterization. Outpatient facilities leverage ultrasound for thyroid and breast surveillance given minimal infrastructure needs.
Mature deployment sits with Computed Tomography. Newer deployment is concentrated in Magnetic Resonance Imaging.
Technology:
Technology layers determine analytical depth and workflow automation potential across imaging platforms.
- AI Imaging:Deep learning algorithms automate lesion detection, segmentation, and treatment response quantification. FDA breakthrough device designation accelerates commercialization for lung nodule and mammography applications. Reimbursement codes for AI-augmented reads remain limited, constraining adoption velocity outside capitated payment models.
- Hybrid Imaging:PET-MRI and PET-CT fusion captures anatomical and metabolic data in single sessions. Premium margin pools attract vendor investment in proprietary reconstruction algorithms and contrast agent bundling. Academic medical centers drive adoption for radiotherapy planning and immunotherapy monitoring.
- Radiomics:Quantitative imaging biomarker extraction enables treatment response prediction beyond visual assessment. QIBA standardization efforts are maturing reproducibility protocols for multicenter trials.
- 3D Imaging:Volumetric reconstruction supports surgical planning and interventional navigation. Diagnostic imaging centers deploy 3D mammography and CT colonography to differentiate service offerings.
Capital intensity peaks with Hybrid Imaging. Regulatory momentum favors AI Imaging.
End User:
Procurement authority and patient volume shape technology adoption patterns across care settings.
- Hospitals:Integrated delivery networks consolidate multi-modality purchasing through long-term service agreements bundling hardware, software, and consumables. GPO concentration in the United States compresses vendor margins while extending contract duration.
- Diagnostic Imaging Centers:Independent operators join regional buying cooperatives to access pricing parity with health systems. Teleradiology platforms extend subspecialty interpretation reach to underserved markets.
- Research Institutes:National Cancer Institute designation drives hybrid imaging investment for competitive grant funding and clinical trial enrollment.
- Outpatient Facilities:Ambulatory surgery centers deploy compact ultrasound and CT systems for procedural guidance and post-treatment surveillance.
Volume concentration sits with Hospitals. Margin expansion targets Diagnostic Imaging Centers.
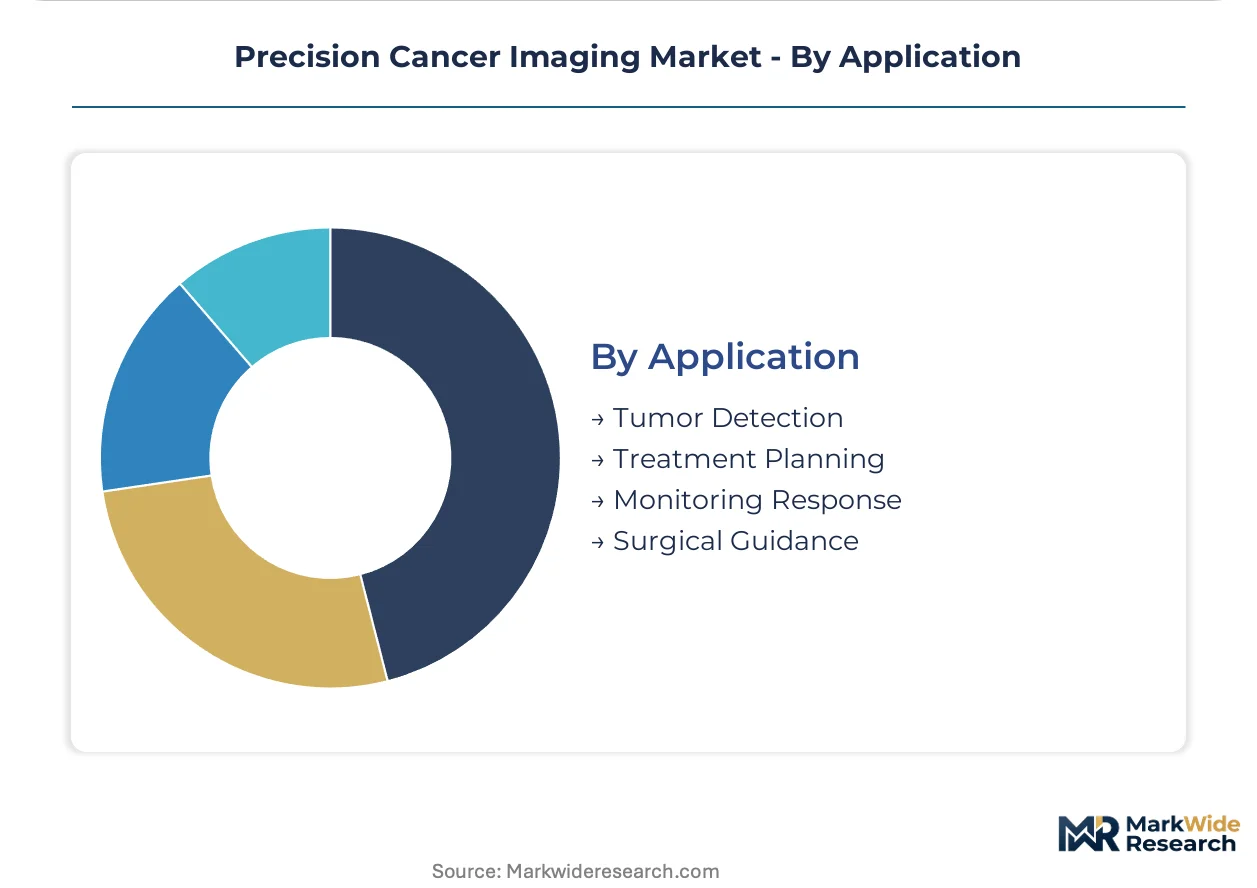
Application:
Clinical use case determines imaging protocol complexity and reimbursement valuation.
- Tumor Detection:Screening and diagnostic workflows prioritize sensitivity with AI-enabled false-positive reduction. Population health initiatives in the United States drive lung cancer CT screening expansion.
- Treatment Planning:Radiotherapy simulation demands sub-millimeter spatial accuracy and motion management. Hybrid imaging guides dose escalation to metabolic hotspots while sparing healthy tissue.
- Monitoring Response:Immunotherapy assessment requires metabolic and anatomical criteria beyond RECIST 1.1. Radiomics protocols are standardizing quantitative endpoints for regulatory submissions.
- Surgical Guidance:Intraoperative imaging integrates with navigation systems for margin assessment and lesion localization. Ultrasound and MRI modalities dominate this segment given real-time capability.
Reimbursement stability sits with Tumor Detection. Technical complexity concentrates in Monitoring Response.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Academic medical centers in the United States concentrate demand for hybrid imaging systems, while procurement consolidation across integrated delivery networks compresses vendor margins. Regulatory pathways diverge sharply between FDA breakthrough designations and EU AI Act conformity requirements. Facility deployment timelines stretch 18-24 months due to specialized infrastructure needs.
United States
National Cancer Institute designation drives competitive investment in PET-MRI systems among leading oncology centers. FDA breakthrough device designation accelerates AI-enabled imaging approvals, compressing commercialization timelines for lesion detection algorithms. The Greater Boston cluster anchors radiomics standardization efforts through QIBA protocol development.
Germany
Comprehensive cancer centers in Bavaria and Baden-Württemberg prioritize spectral CT and photon-counting technology for tissue characterization. EU AI Act conformity assessment extends certification timelines for clinical decision-support algorithms entering European markets. The Munich metropolitan area concentrates vendor service infrastructure for hybrid imaging maintenance contracts.
China
Provincial hospital networks in the Yangtze River Delta expand PET-CT procurement to address rising oncology caseloads. NMPA regulatory harmonization with international standards accelerates import substitution for domestic imaging equipment manufacturers. Shanghai anchors joint ventures between multinational vendors and local production facilities.
Japan
Metropolitan medical centers in Tokyo and Osaka deploy 3 Tesla MRI systems for multiparametric prostate and breast imaging protocols. PMDA streamlined review pathways support rapid adoption of AI-embedded reconstruction algorithms. The Kansai region concentrates proton therapy centers requiring hybrid imaging integration for treatment planning.
United Kingdom
NHS England procurement frameworks consolidate multi-modality purchasing through long-term service agreements bundling hardware and analytics. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines for software-as-medical-device products. The London-Southeast corridor dominates teleradiology platform deployment for subspecialty interpretation networks.
Precision Cancer Imaging Market Competitive Environment
German and Dutch producers anchor one tier; American specialists hold premium positions in AI-embedded platforms. The vendor structure concentrates around conglomerate health technology divisions with integrated imaging portfolios. Three archetypes dominate: full-modality conglomerates, AI-native software vendors, and regional service integrators. Capacity expansion in helium-independent MRI systems and strategic partnerships for isotope supply security represent dominant competitive vectors.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare exemplify the full-modality archetype, anchoring long-term service contracts through hybrid imaging bundling. Philips occupies a position spanning diagnostic hardware and informatics integration. These three entities represent the scale-driven tier where procurement consolidation favors vendors offering unified multi-modality agreements.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips |
| Canon Medical Systems |
| Hologic |
| Medtronic |
| Stryker |
| Olympus |
| Koninklijke Philips N.V. |
| Others |
Value Chain & Pricing Dynamics
Integrated delivery network procurement consolidation across the United States anchors contract-based pricing models that bundle hardware, software, and consumables into multi-year service agreements. This buyer concentration compresses vendor margins while extending contract duration, creating feedback loops that favor vendors with captive helium recovery systems and isotope supply security.
Pricing Analysis
High-volume PET-CT installations at community hospitals generate thinner margins than premium PET-MRI deployments at academic medical centers, creating a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on magnet field strength, AI-embedded software tiers, and FDA breakthrough designation status. Pricing pressure stems from GPO concentration influencing over sixty percent of capital expenditure decisions. Community hospitals exhibit highest price sensitivity, while NCI-designated cancer centers prioritize performance specifications over unit economics.
Supply Chain Analysis
Domestic-content mandates in China's Yangtze River Delta and NMPA regulatory harmonization are reshaping sourcing patterns for multinational vendors operating joint ventures with local producers. Manufacturing concentrates in Germany, the United States, and China, with component sourcing drawing from specialized magnet wire suppliers in Japan and South Korea. Helium supply volatility from export restrictions in Qatar and Algeria creates single-source vulnerability for MRI magnet cooling. Distribution runs through hospital GPOs and regional buying cooperatives serving independent imaging centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hospital procurement consolidation is accelerating vendor attrition as integrated delivery networks demand unified multi-modality contracts that smaller players cannot fulfill. This structural pressure forces weaker competitors toward niche AI software licensing or exit.
For Market Incumbents: Deploy captive helium recovery infrastructure to insulate service contract profitability from supply volatility. Siemens Healthineers and GE Healthcare should anchor long-term hybrid imaging agreements with integrated delivery networks while acquiring AI-native lesion detection firms to counter software-only entrants threatening hardware-software bundling models.
For New Entrants and Emerging Players: Capture teleradiology platform penetration in rural United States markets where subspecialty interpretation shortages persist. Compact PET-CT systems with embedded AI workflow tools represent the most penetrable white-space for mid-sized oncology programs, with go-to-market execution through regional buying cooperatives rather than direct GPO competition.
For Investors and Strategic Acquirers: The window for entry favors AI-native software vendors with FDA breakthrough device designations ahead of EU AI Act conformity bottlenecks. Acquisition targets should demonstrate radiomics protocol standardization through QIBA frameworks. Watch CMS reimbursement coding decisions for AI-augmented reads as the inflection signal determining clinical adoption velocity outside capitated models.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Accelerates commercialization timelines for AI-enabled lesion detection algorithms ahead of EU regulatory bottlenecks. |
| Helium Recovery Infrastructure | Insures MRI service contract margins against Qatar export restrictions and spot price volatility. |
| Hospital System Partnership | Locks multi-modality purchasing through unified hardware-software-consumable bundling with GPO-affiliated networks. |
| Software Companion Development | Separates algorithm licensing from hardware maintenance, creating recurring revenue streams independent of capital cycles. |
| Reimbursement Strategy | Secures CPT code coverage for AI-augmented reads and radiomics-based response assessments with CMS. |
Study Parameters
Multi-period observation of FDA breakthrough designations, GPO contract awards, and isotope supply disruptions anchored the trend analysis, supplemented by interviews with hospital purchasing committee directors, biomedical engineers, GPO contracts managers, and radiology department chairs. Secondary validation drew from FDA 510(k) filings, CMS Medicare reimbursement databases, hospital procurement records, and ISO 13485 certification registries. Bottom-up modality shipment tracking and top-down healthcare capital expenditure analysis were triangulated to constrain forecast variance.
Segment-weighting applied differential growth assumptions across AI Imaging, Hybrid Imaging, Radiomics, and 3D Imaging technology layers, with additional stratification by magnet field strength, deployment setting, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles, reimbursement code expansion trajectories, and academic medical center capital budget allocations. Forecast inputs incorporated helium supply scenario modeling and NMPA import substitution timelines for domestic Chinese equipment manufacturers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to CMS reimbursement decisions, EU AI Act certification delays, and research reactor decommissioning schedules affecting Molybdenum-99 availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Handheld Ultrasound Scanners Market
Medical Imaging
AI in Diagnostic Imaging Market
Medical Imaging
Global Artificial Intelligence in Ultrasound Imaging Market
Medical Imaging
Global Digital Subtraction Angiography Market
Medical Imaging
Interventional X - Ray Systems Market
Medical Imaging
Non-Invasive & Minimally Invasive Medical Imaging and Visualization Systems Market
Medical Imaging
Global Dental Radiology and Dental Imaging Devices Market
Medical Imaging
Vendor Neutral Archive Market
Medical Imaging
Japan Diagnostic Imaging Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Structural Heart Imaging Market
Medical Imaging
Global Elastography Imaging Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Asia-Pacific CT Market