
 North America Vitamin D Market | 2026-2036
North America Vitamin D Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vitamin D Market Intelligence
Revenue from functional food applications is rewriting the margin structure historically dominated by standard supplements. This shift creates new opportunities for ingredient suppliers and finished product manufacturers. Koninklijke DSM N.V. specializes in high-potency formulations, while Nestlé S.A. leverages its extensive food and beverage portfolio to integrate vitamin D. Abbott Laboratories also competes with its line of fortified nutritional products.
Vitamin D is a group of fat-soluble secosteroids, with the most important forms being D2 (ergocalciferol) and D3 (cholecalciferol). Its primary physiological function is to enhance intestinal absorption of calcium, magnesium, and phosphate. The dietary supplements application continues to represent the largest market segment by revenue. However, capsules and liquid product types are gaining share over traditional tablets due to perceived higher bioavailability and ease of consumption.
In the United States, the Food and Drug Administration (FDA) sets the Daily Value and regulates fortification claims. Similarly, Health Canada establishes dietary reference intakes and oversees supplement safety for the Canadian market. Navigating the different regulatory requirements and consumer preferences between the US and Canada is critical for market participants. Success depends on aligning product formats and marketing with specific national health guidelines.
Market Dynamics
The primary force shaping the North America Vitamin D market is the convergence of regulatory updates and consumer demand for functional foods. Fortification guidelines from the U.S. Food and Drug Administration are creating a new baseline for product formulation across the food industry.
Growth Catalysts
- Regulatory Fortification Mandates:Updated U.S. Food and Drug Administration (FDA) guidelines expanding permissible vitamin D fortification in foods and beverages create new avenues for product development and health claims, particularly within the dairy and plant-based alternative sectors.
- Consumer Format Preference:A clear shift in consumer behavior favors capsules and liquid forms over traditional tablets, driven by perceptions of enhanced bioavailability and greater ease of consumption for both children and older adults.
- Functional Food Integration:The expansion of vitamin D application beyond dietary supplements into everyday functional foods and beverages, such as cereals, juices, and yogurts, is broadening the consumer base and increasing daily intake occasions.
Market Restraints
- Input Material Volatility:The market faces price and supply instability for lanolin, the primary raw material sourced from sheep's wool for producing cholecalciferol (D3), impacting production costs for supplement and food ingredient manufacturers.
- Cross-Border Regulatory Divergence:Navigating the distinct labeling regulations, daily value recommendations, and health claim rules between the FDA in the United States and Health Canada creates complexity and increases compliance costs for brands operating in both countries.
- Formulation Stability Issues:Vitamin D's sensitivity to heat, light, and oxidation presents technical challenges for food scientists, limiting its effective incorporation into certain food products and potentially reducing shelf-life potency without specialized encapsulation technologies.
Strategic Opportunities
- Geographic Expansion in Mexico:There is a significant opportunity to target Mexico's growing wellness-focused consumer segment with fortified food products and dietary supplements, an area currently less saturated than the U.S. and Canadian markets.
- Medical and Clinical Nutrition:Developing high-potency, prescription-grade vitamin D formulations for use in medical foods and clinical nutrition settings addresses the specific needs of populations with diagnosed deficiencies or malabsorption disorders.
- Channel Innovation via DTC:The rise of direct-to-consumer (DTC) e-commerce platforms allows for the creation of personalized subscription services, offering tailored vitamin D dosages based on lifestyle questionnaires or at-home testing kits.
Industry Challenges
- Compliance and Reformulation Costs:Manufacturers face significant operational challenges and costs associated with reformulating products and redesigning packaging to comply with updated nutritional labeling requirements mandated by the FDA.
- Supply Chain Adaptation:Shifting from a bulk ingredient model suited for supplement manufacturing to a food-grade, just-in-time logistics model required by large-scale functional food producers introduces complexity and requires new quality control protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vitamin D Market |
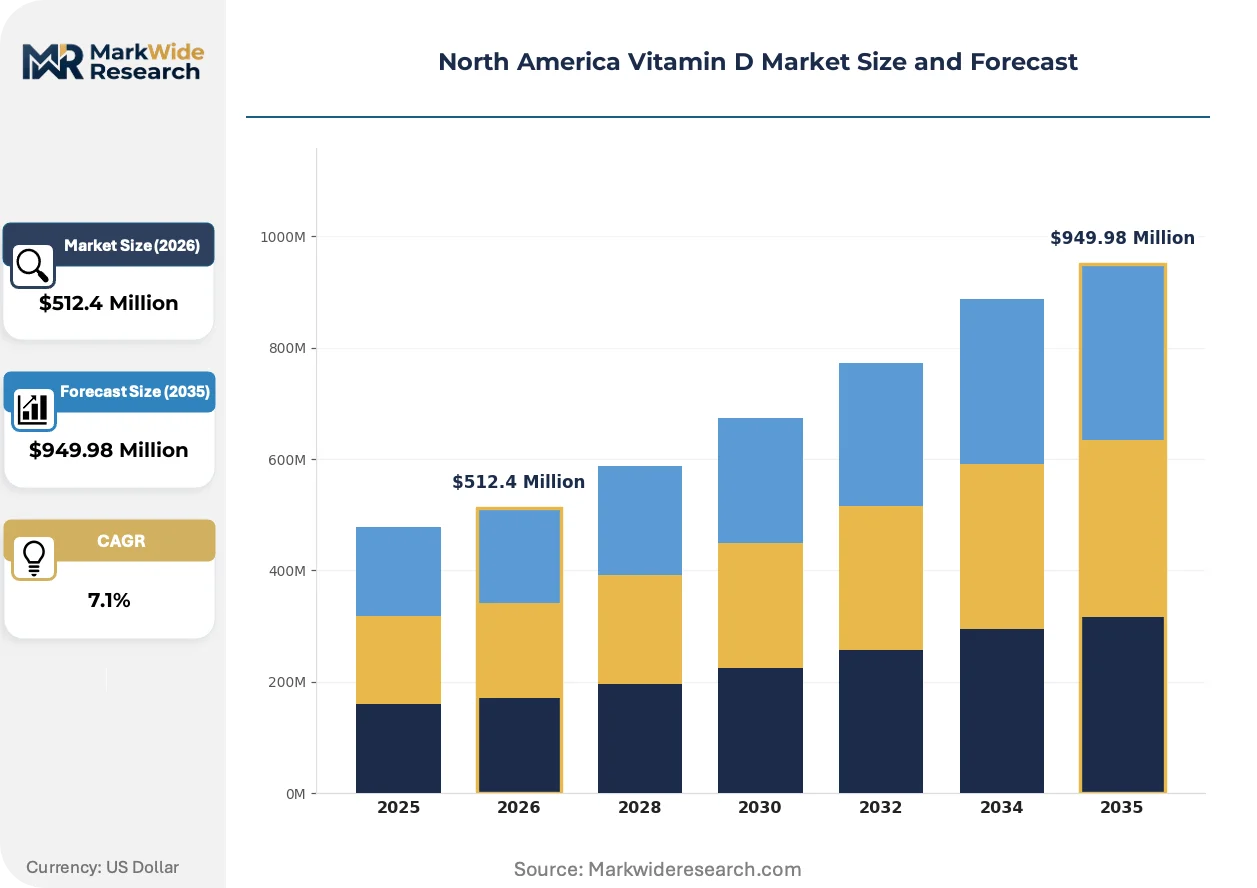
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $949.98 Million |
| CAGR (2026 – 2036) | 7.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tablets, Capsules, Powders, Liquid End User: Retail Stores, Online Retail, Pharmacies, Hospitals Application: Dietary Supplements, Functional Foods, Pharmaceuticals, Cosmetics Distribution Channel: Direct Sales, Wholesalers, E-commerce, Supermarkets |
| Companies Covered | Nestlé S.A., Pfizer Inc., GlaxoSmithKline plc, BASF SE, Abbott Laboratories, Koninklijke DSM N.V., Amway Corporation, Haleon PLC, The Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vitamin D Market Strategic Shifts & Innovations
Digitalization of personal health is creating new demand pathways, moving the market from generalized supplementation toward data-driven, personalized nutrition. This trend influences product development, delivery models, and consumer engagement, emphasizing individual health outcomes over broad recommendations.
At-home blood spot testing provides consumers with personalized data on their vitamin D levels. Health-conscious consumers and users of digital wellness applications are adopting these services to guide their purchasing decisions. This data-driven feedback loop is virtualizing the traditional health consultation process, creating direct demand for specific dosages and product formats.
The U.S. Food and Drug Administration's rule permitting increased vitamin D fortification levels in milk and certain plant-based beverages has significant industrial consequences. This regulatory shift allows food and beverage manufacturers to formulate products with higher, more efficacious doses. The functional foods segment in the United States is most affected, gaining the ability to launch new products with stronger health-benefit messaging.
A notable consumer behavioral change involves moving from bulk, one-time purchases at mass-market retailers to curated subscription box services. This model disrupts the traditional grocery and pharmacy channels by offering vitamin packs tailored to individual health profiles and preferences. This direct-to-consumer trend is most visible in major urban centers across the United States and Canada.
North America Vitamin D Market Segmentation
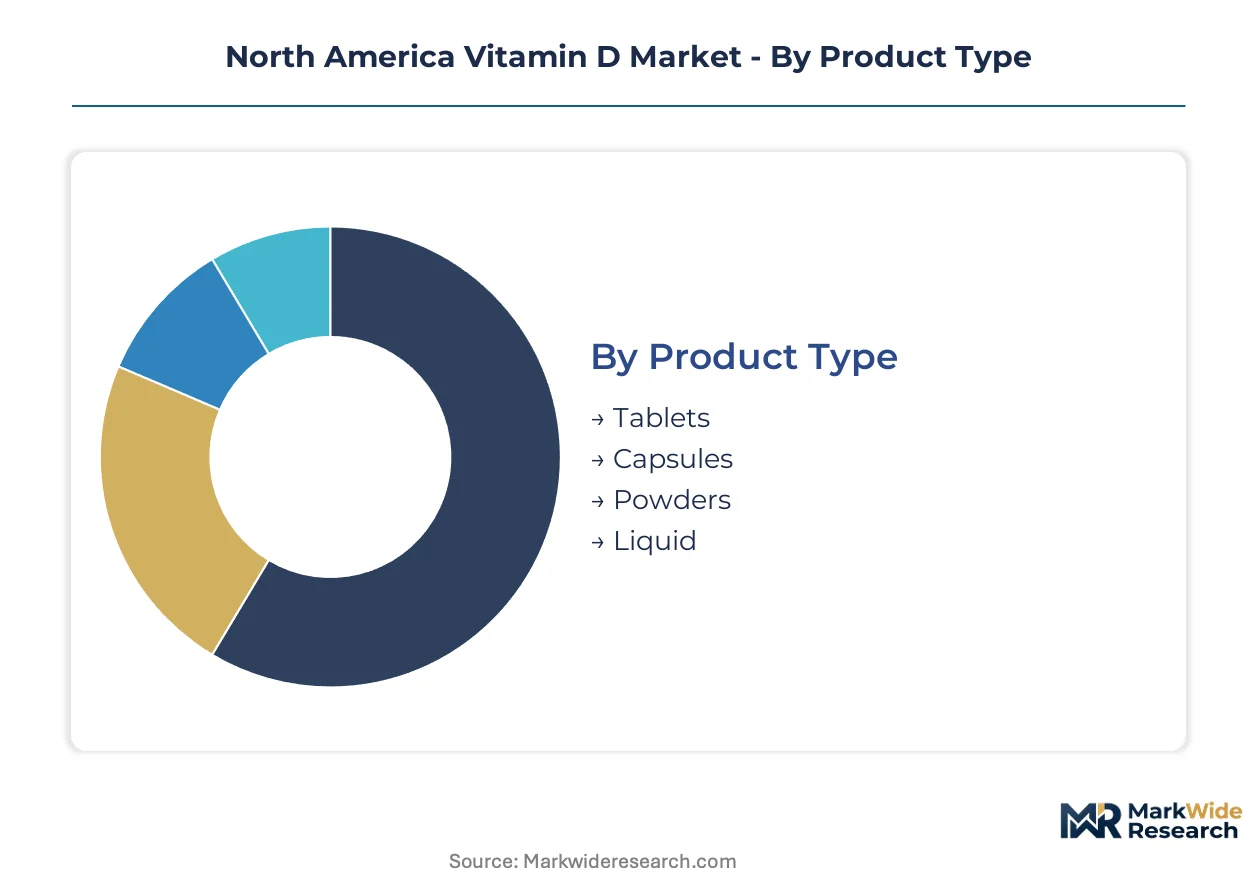
The North America Vitamin D market's segmentation reveals diverse product formats, end-user preferences, and application areas. Understanding these distinctions helps market participants tailor product development and distribution strategies. This granular analysis highlights where demand concentrates and how consumer behavior influences market evolution.
Product Type:
The product type segmentation highlights the diverse forms consumers utilize vitamin D across a broad use-case spectrum.
- Capsules:These oral dosage forms encapsulate vitamin D within a soluble shell, often perceived to offer enhanced bioavailability and quicker absorption. Consumer preference for capsules is increasing due to their ease of consumption, particularly among adults seeking convenient supplementation.
- Liquid:Liquid vitamin D formulations provide precise dosing and are easily mixed with food or beverages, making them ideal for children and older adults. This format gains traction from perceptions of higher bioavailability and greater palatability compared to solid forms.
- Tablets:Traditional tablet forms remain a foundational product type, offering cost-effectiveness and stability for general vitamin D supplementation.
- Powders:Powdered vitamin D allows for flexible dosing and integration into various food products or beverages, catering to specific formulation needs.
The dominant share belongs to Tablets, while Capsules is closing the gap fastest.
End User:
The end-user classification delineates distinct customer types driving demand for vitamin D products across various purchasing environments.
- Online Retail:This channel encompasses e-commerce platforms and direct-to-consumer (DTC) websites, offering personalized subscription services and a wide product selection. Consumers increasingly favor online retail for convenience, competitive pricing, and privacy in health-related purchases.
- Retail Stores:Traditional retail outlets, including supermarkets and health food stores, serve as primary access points for a broad consumer base seeking immediate product availability. These stores cater to impulse purchases and consumers preferring in-person shopping experiences.
- Pharmacies:Pharmacies provide a trusted source for vitamin D products, often accompanied by professional health advice from pharmacists.
- Hospitals:Hospitals procure vitamin D formulations for clinical nutrition and therapeutic applications, addressing deficiencies in inpatient and outpatient settings.
Online Retail exhibits a significant expansion trajectory, complementing the established reach of Retail Stores.
Application:
The application segment highlights the diverse industrial uses and consumer purposes for vitamin D across various product categories.
- Dietary Supplements:This category represents the largest market segment, with vitamin D consumed in various forms to prevent or treat deficiencies. Consumers prioritize dietary supplements for general wellness, bone health, and immune support.
- Functional Foods:Functional foods integrate vitamin D into everyday food and beverage items, such as dairy, cereals, and plant-based alternatives, expanding daily intake occasions. Regulatory updates from the U.S. Food and Drug Administration support increased fortification levels in these products.
- Pharmaceuticals:Pharmaceutical applications involve high-potency or prescription-grade vitamin D formulations for specific medical conditions and severe deficiencies.
- Cosmetics:Cosmetics incorporate vitamin D for its potential skin health benefits, including antioxidant properties and support for skin barrier function.
While Dietary Supplements maintain the largest share, Functional Foods are experiencing the steepest expansion trajectory.
Distribution Channel:
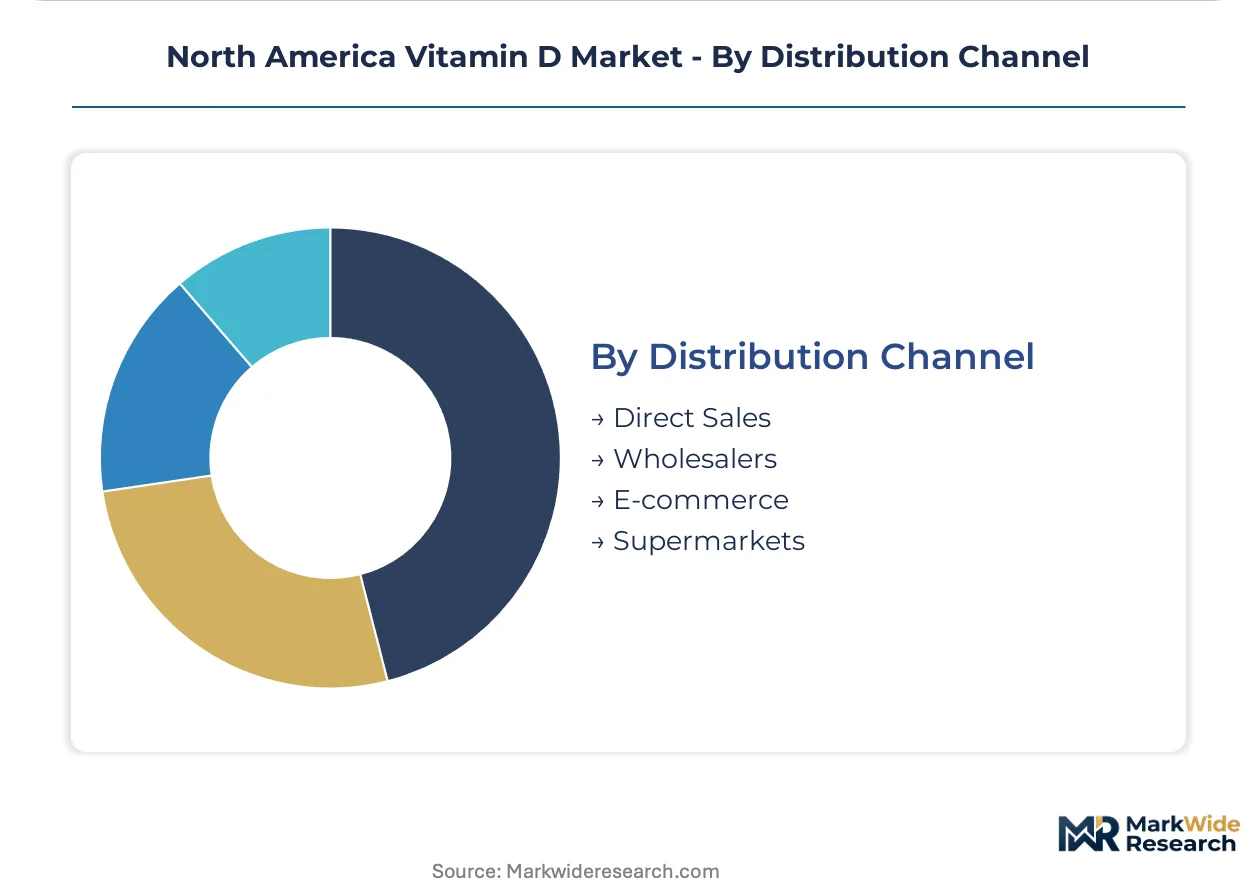
The distribution channel segment illustrates how vitamin D products reach end-users, reflecting varying levels of supply concentration and logistical approaches.
- E-commerce:E-commerce platforms facilitate direct-to-consumer sales and personalized subscription models, bypassing traditional retail intermediaries. This channel supports customized offerings and offers a convenient purchasing experience for health-conscious consumers.
- Wholesalers:Wholesalers serve as crucial intermediaries, distributing bulk vitamin D ingredients and finished products to various retailers, manufacturers, and institutions. They manage large-scale logistics and supply chain efficiency for the broader market.
- Supermarkets:Supermarkets offer widespread availability of vitamin D-fortified foods and dietary supplements, catering to general consumer grocery shopping habits.
- Direct Sales:Direct sales models involve manufacturers selling directly to consumers or specific clients, often for specialized or high-potency formulations.
E-commerce continues to gain share rapidly, challenging traditional models primarily driven by Wholesalers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The consumption mix for vitamin D in North America differs significantly, with the United States showing strong demand for dietary supplements while Canada emphasizes functional food integration. Mexico presents an emerging market with distinct consumer preferences for fortified products. This regional variation influences product development and regulatory compliance strategies for market participants.
United States
United States consumers show strong demand for vitamin D, primarily through dietary supplements and a rapidly expanding functional foods segment. The U.S. Food and Drug Administration's updated fortification guidelines allow for increased vitamin D levels in milk and plant-based beverages, creating new product development avenues. California's health-conscious population and digital wellness applications drive innovation in personalized nutrition and direct-to-consumer product offerings, influencing national trends.
Canada
Canadian consumers increasingly seek vitamin D in functional foods, valuing both convenience and perceived health benefits from fortified products. Health Canada establishes stringent dietary reference intakes and oversees supplement safety, shaping product formulations and marketing claims within the market. Toronto’s diverse food and beverage manufacturing sector actively integrates vitamin D into various new product lines, including plant-based alternatives and specialty dairy items.
Mexico
Mexico presents a significant opportunity for vitamin D market expansion, driven by a growing wellness-focused consumer segment and increasing awareness of nutritional deficiencies. Local health authorities set specific food fortification standards, influencing the composition of staple foods and beverages. Mexico City’s large urban population and expanding middle class represent a substantial market for accessible fortified dairy products, cereals, and dietary supplements.
Northeast United States
The Northeast United States demonstrates elevated demand for vitamin D, driven by an aging population and strong clinical nutrition requirements. State health departments support public health initiatives promoting bone health and deficiency awareness. Boston's prominent biotech and academic medical centers lead in developing high-potency, prescription-grade vitamin D formulations for specialized patient needs.
North America Vitamin D Market Key Industry Players
Capability concentration sits with specialized ingredient suppliers, while scale advantage rests with large consumer goods conglomerates. The North America Vitamin D market exhibits a tiered structure, with established pharmaceutical companies, diversified food and beverage giants, and niche supplement manufacturers forming distinct strategic archetypes. Dominant competitive moves include strategic partnerships for functional food integration and portfolio diversification into personalized nutrition solutions, addressing varied consumer demands across the region.
Diversified food and beverage giants, such as Switzerland-based Nestlé S.A., leverage extensive distribution networks to integrate vitamin D into everyday products, targeting broad consumer segments. Netherlands-based Koninklijke DSM N.V. represents a key ingredient supplier, specializing in high-potency formulations for both supplement and food fortification applications. Abbott Laboratories, a U.S.-based healthcare company, occupies a strong position within the fortified nutritional products and clinical nutrition segments, catering to specific health needs. These players exemplify the varied approaches to market penetration and product delivery within the North American vitamin D landscape.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Pfizer Inc. |
| GlaxoSmithKline plc |
| BASF SE |
| Abbott Laboratories |
| Koninklijke DSM N.V. |
| Amway Corporation |
| Haleon PLC |
| The Procter & Gamble Company |
| Others |
Cost & Logistics Intelligence
Trans-Pacific shipping lanes, vital for global ingredient sourcing, influence the cost dynamics of vitamin D raw materials, impacting both supply concentration and downstream price differentiation across North America.
Pricing Analysis
Long-term contract-based agreements often define pricing for bulk vitamin D ingredients supplied to large food and pharmaceutical manufacturers. Price differentiation emerges from specific formulation potency and FDA or Health Canada regulatory compliance certifications. Pricing softness stems from input material volatility for lanolin, affecting cholecalciferol production costs. Functional food producers typically exhibit higher price sensitivity compared to pharmaceutical companies procuring high-potency formulations.
Supply Chain Analysis
Lanolin, the primary upstream feedstock for cholecalciferol (D3), sources from global sheep wool markets, with processing concentrated in countries like China and Australia. The industry relies heavily on a consistent supply of both lanolin and ergocalciferol (D2) from specialized producers. Supply chain risk centers on commodity price volatility for lanolin, creating cost instability for manufacturers. Downstream distribution runs through a hybrid model encompassing wholesalers for bulk ingredients and direct-to-consumer channels for finished supplements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Vitamin D market presents a substitution defense challenge, as traditional generic supplements face displacement from personalized nutrition solutions and fortified functional foods.
For Market Incumbents: Insulate core market share by strategically integrating vitamin D into extensive functional food and beverage portfolios, leveraging existing distribution networks. Manufacturers must invest in advanced encapsulation technologies to enhance stability and bioavailability, addressing specific consumer format preferences. This approach counters the shift towards personalized solutions and reinforces brand trust through science-backed product development.
For New Entrants and Emerging Players: Pursue white-space opportunities in Mexico's growing wellness segment with targeted fortified products, leveraging less saturated market conditions. Develop specialized high-potency formulations for clinical nutrition settings, addressing specific malabsorption disorders. The most penetrable segment lies within direct-to-consumer personalized subscription services, offering tailored dosages based on at-home testing data.
For Investors and Strategic Acquirers: Specialized ingredient formulators with advanced encapsulation or bioavailability enhancement capabilities present compelling acquisition targets over the next 5-10 years. Digital health platforms offering personalized nutrition assessments and direct-to-consumer delivery models also hold strategic value. The signal to watch is the accelerated uptake of at-home vitamin D testing kits, indicating a broader market shift towards data-driven health.
| Strategic Initiative | Industry Significance |
|---|---|
| Functional Food Portfolio Expansion | Nestlé S.A. expands its vitamin D offerings across dairy and plant-based alternatives, broadening consumer reach. |
| Encapsulation Technology Investment | Koninklijke DSM N.V. enhances vitamin D stability in complex food matrices, improving product shelf-life. |
| DTC Subscription Model Launch | Abbott Laboratories introduces personalized vitamin D dosages via e-commerce, catering to individual health needs. |
| Clinical Nutrition Product Development | Pfizer Inc. targets specific patient populations with prescription-grade vitamin D formulations for severe deficiencies. |
| Regulatory Compliance Specialization | GlaxoSmithKline plc navigates U.S. FDA and Health Canada guidelines for seamless market entry and product claims. |
Research Approach
A standing panel of R&D scientists, regulatory affairs leads, brand managers, and procurement officers provided ongoing calibration for market assumptions. This primary interview data was cross-referenced with extensive secondary research, including U.S. FDA guidelines, Health Canada reports, company financial filings, and academic journals. The analysis employed both bottom-up and top-down triangulation to ensure robust market sizing and forecast validation.
Scenario-bracketing analysis defined the plausible range for market growth across the analysis window, accounting for various influencing factors. The model segmented the market by product type, end user, application, distribution channel, and specific D2/D3 forms. Compound Annual Growth Rates (CAGRs) were derived from historical data trends and projected future market dynamics. Key forecast inputs included updated regulatory fortification levels and evolving consumer health awareness regarding vitamin D deficiency.
Macroeconomic conditions sit as an overlay; deviation in consumer disposable income or global trade policies would shift the trajectory. Forecasts reflect specific assumptions about raw material supply stability and sustained consumer preference for functional health solutions. Cross-checking against external industry benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fortified Juices Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Colecalciferol Market
Vitamin Fortified
Calcium Fortified Juice Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Global Fortified Yogurt Market
Vitamin Fortified
Fortified Baby Food Market
Vitamin Fortified
Liquid Vitamins Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Delta-Tocopherol Market