
 Global Fortified Yogurt Market | 2026-2036
Global Fortified Yogurt Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fortified Yogurt Market Foresight
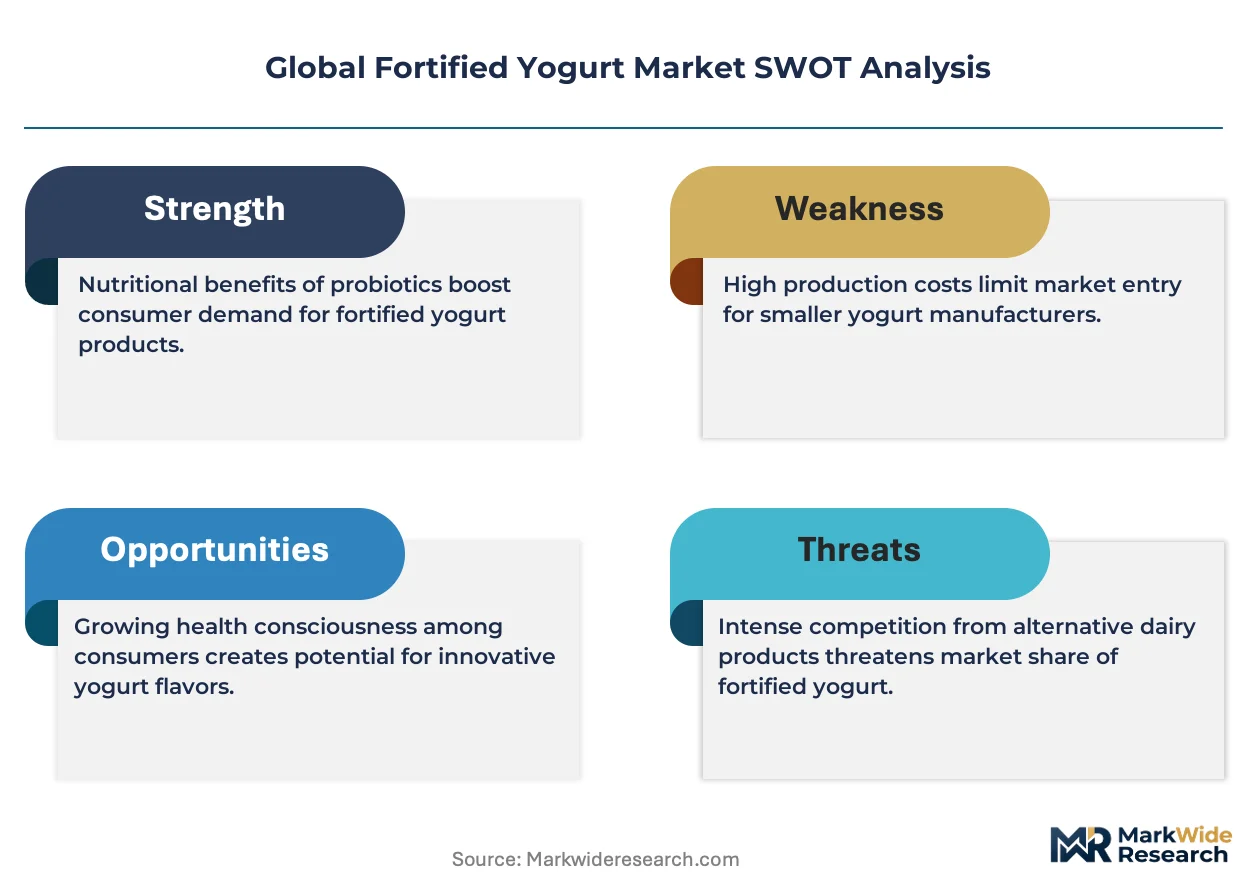
Premium probiotic tier is unwinding new margin pools across refrigerated dairy aisles. Danone leverages its European fermentation expertise to sustain shelf-stable distribution networks. Chobani anchors North American demand through Greek-style protein fortification. Nestlé competes in emerging markets with localized vitamin D and calcium formulations.
Fortified yogurt denotes dairy or plant-based cultured milk products with added micronutrients, typically achieving live culture counts exceeding 10^6 CFU per gram and protein fortification above 10 grams per serving, designed to deliver targeted physiological benefits beyond basic nutrition. Probiotic yogurt and high-protein yogurt command the deepest margin pools, while plant-based yogurt represents the fastest-expanding frontier as oat and coconut bases attract lactose-intolerant consumers. Distribution through online retail channels is accelerating, though supermarkets still capture the bulk of volume throughput in mature markets.
EFSA governs health claim substantiation across Europe, while the FDA regulates nutrient content labeling in the United States, and India's FSSAI mandates fortification standards for dairy products sold through organized retail. These frameworks collectively elevate R&D costs for new entrants but lock in quality premiums for compliant manufacturers. Stakeholders must monitor evolving probiotic strain approval pathways and shifting retail channel economics to capture value migration toward functional dairy segments.
Market Dynamics
EFSA's tightening health claim substantiation rules under the EU Green Deal are forcing reformulation cycles across European dairy cooperatives, while India's FSSAI fortification mandates create compliance arbitrage between organized retail and traditional milk channels.
Growth Catalysts
- Pediatric nutrition programs:Institutional cafeteria contracts in Indian school feeding schemes and Brazilian daycare networks are creating volume anchors for vitamin D and zinc-fortified SKUs. These programs lock in multi-year procurement cycles.
- EFSA probiotic strain approvals:The 2023 updated Qualified Presumption of Safety list is accelerating novel Lactobacillus and Bifidobacterium strain commercialization across EU member states, reducing R&D uncertainty for fermentation specialists.
- Plant-based substrate innovation:Oat protein concentrate and coconut cream fractionation technologies are expanding the addressable base beyond lactose-intolerant consumers into flexitarian households seeking dual-fortification formats.
Market Restraints
- Live culture stability costs:Cold chain maintenance for 10^6 CFU/g retention through last-mile distribution in tropical climates adds 12-18% logistics overhead versus ambient-stable alternatives.
- Fortificant input concentration:Vitamin D3 and calcium carbonate supply clusters in Chinese chemical processing hubs, creating tariff-exposure and single-source dependency for European formulators.
- FDA nutrient content claim friction:The agency's 2023 proposed revisions to "healthy" labeling criteria are delaying new product launches as legal teams reassess protein threshold positioning.
Strategic Opportunities
- Southeast Asian pharmacy channels:Vietnam and Indonesia's expanding drugstore networks represent white space for medicinal-positioned probiotic yogurt with digestive health claims, bypassing crowded supermarket dairy aisles.
- USDA school meal pattern alignment:The 2024 updated nutrition standards create a regulatory tailwind for calcium-fortified yogurt to displace flavored milk in K-12 cafeterias, with preferential bidding status.
- Precision fermentation convergence:Integration of recombinant protein expression with traditional dairy fermentation is enabling hybrid products with enhanced bioactive peptide profiles and reduced land-use intensity.
Industry Challenges
- Microbiome assay standardization:Inconsistent CFU enumeration methods between ISO 7889 and AOAC protocols create batch-release disputes between contract manufacturers and brand owners.
- Legacy ERP integration:Dairy cooperatives migrating from paper-based member-milk tracking to SAP or Oracle systems face 18-24 month implementation timelines, delaying real-time fortification dosing controls.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fortified Yogurt Market |
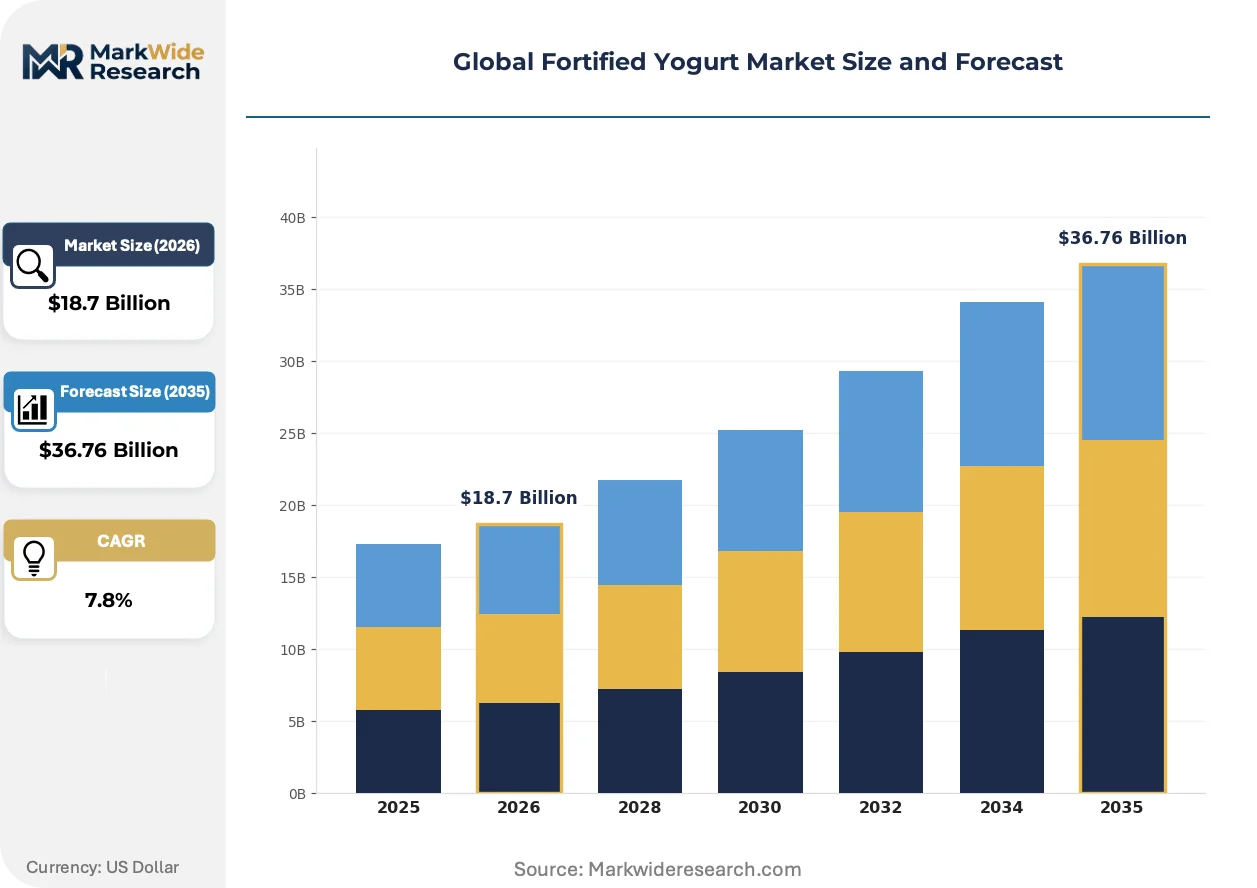
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $36.76 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotic Yogurt, High-Protein Yogurt, Low-Fat Yogurt, Plant-Based Yogurt Fortification Ingredient: Vitamin D, Calcium, Iron, Omega-3 Fatty Acids, Fiber Application: Weight Management, Immune Support, Digestive Health, Bone Strengthening, Energy Boost Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Specialty Health Stores |
| Companies Covered | Nestlé, Ultima Foods, Danone, Arla Foods Ingredients, General Mills, Chobani, Sodiaal, Lactalis, FAGE International S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fortified Yogurt Market Shifts & Advancements
Bioprocessing advances and regulatory recalibration are splitting the competitive landscape between precision-fermented premium tiers and commodity fortification plays, with channel strategy becoming the primary differentiation lever.
Precision fermentation for dairy-identical proteins is bifurcating the ingredient supply base. Perfect Day and Remilk are licensing their whey protein platforms to CPG manufacturers seeking clean-label fortification without lactose or cholesterol. Early adopters in North American specialty retail are commanding shelf price premiums of 40-60% above conventional Greek yogurt, compressing margin pools for legacy protein concentrate suppliers.
REACH's 2024 microplastics monitoring requirements and EFSA's updated food contact material guidelines are forcing packaging migration. Multi-layer plastic cups with mineral oil migration risks face phase-out timelines, accelerating investment in mono-material polyethylene or fiber-based alternatives. German and Dutch retailers are imposing unilateral 2026 deadlines ahead of regulatory mandates, squeezing mid-tier brands with limited R&D bandwidth.
Direct-to-consumer subscription models are disrupting traditional grocery velocity calculations. Chobani and Icelandic Provisions have launched personalized nutrition programs using microbiome test kits to recommend strain-specific SKUs. This channel shift is most visible in US coastal metros, where cohort retention rates exceed 70% versus 25-30% repeat purchase rates in conventional retail, forcing slotting fee economics toward irrelevance for insurgent brands.
Global Fortified Yogurt Market Segmentation
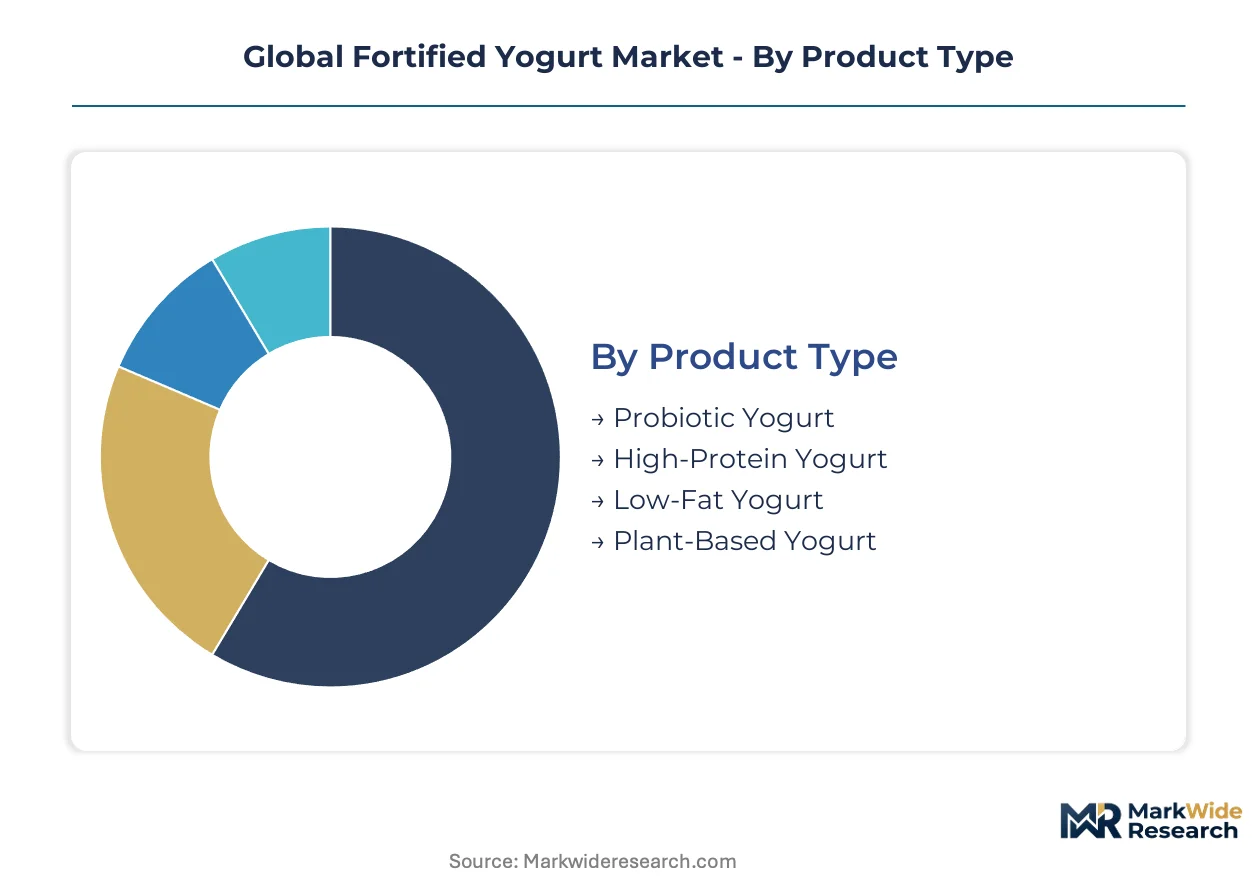
Fortified yogurt segmentation reflects divergent regulatory thresholds across EFSA, FDA, and FSSAI jurisdictions, with each category demanding distinct substantiation protocols and labeling investments. Product developers must align formulation architecture with the specific compliance pathways governing their target markets.
Product Type:
EFSA's Qualified Presumption of Safety list and FDA GRAS determinations create divergent approval timelines for live culture formulations, directly shaping R&D allocation across product tiers.
- Probiotic Yogurt:Live culture counts exceeding 10^6 CFU per gram deliver targeted digestive and immune modulation benefits. Pediatric nutrition programs in Indian school feeding schemes and Brazilian daycare networks are locking in multi-year procurement contracts for strain-specific SKUs, with EFSA's 2023 QPS updates accelerating novel Lactobacillus commercialization across EU member states.
- High-Protein Yogurt:Protein fortification above 10 grams per serving targets athletic and satiety-positioned consumption occasions. Greek-style processing and ultrafiltration methods command premium shelf positioning in North American refrigerated aisles, where Chobani and Icelandic Provisions have established category benchmarks through sustained fermentation expertise.
- Low-Fat Yogurt:Fat reduction below 2% while maintaining texture through modified starch or hydrocolloid systems addresses calorie-conscious demographics in Western European markets with mature dietary guidelines.
- Plant-Based Yogurt:Oat protein concentrate and coconut cream substrates expand the addressable base beyond lactose-intolerant consumers into flexitarian households seeking dual-fortification formats without dairy allergens.
High-protein yogurt handles the majority of throughput; plant-based yogurt is gaining share fastest as substrate innovation unlocks new consumer cohorts.
Fortification Ingredient:
Input sourcing geography determines tariff exposure and single-source dependency risks, with Chinese chemical processing hubs dominating vitamin D3 and calcium carbonate supply clusters.
- Vitamin D:Cholecalciferol (D3) and ergocalciferol (D2) formulations address deficiency prevalence in Northern European and North American populations with limited solar exposure. Nestlé's localized D3 fortification strategies in emerging markets leverage regional dairy cooperative networks to bypass import dependency.
- Calcium:Calcium carbonate and calcium citrate additions target bone health claims, with FSSAI mandates in India creating compliance arbitrage between organized retail and traditional milk channels.
- Iron:Ferrous sulfate and bisglycinate chelate formulations address anemia prevalence in South Asian and Sub-Saharan African markets, though metallic off-notes require flavor masking investments.
- Omega-3 Fatty Acids:Algal DHA and EPA microencapsulation enables vegetarian-positioned cognitive and cardiovascular claims without fish-derived ingredient perception barriers.
- Fiber:Inulin, chicory root, and resistant starch additions support digestive health positioning and glycemic response modulation in diabetes-prevention formulations.
Calcium fortification handles the majority of throughput; omega-3 fatty acids are climbing the fastest as algal sourcing solves vegetarian formulation constraints.
Application:
Health claim substantiation requirements under EFSA's 1924/2006 regulation and FDA's pending "healthy" labeling revisions are forcing reformulation cycles that privilege specific physiological benefit architectures.
- Weight Management:High-protein, low-calorie density formulations leverage satiety signaling research to support portion-controlled meal replacement positioning in US and UK markets with established dietetic counseling channels.
- Immune Support:Vitamin D and zinc combinations with specific probiotic strains target seasonal consumption patterns, though EFSA's strict health claim substantiation limits permitted marketing language in EU markets.
- Digestive Health:Live culture retention through shelf life supports regularity and microbiome modulation claims, with direct-to-consumer subscription models using microbiome test kits to recommend strain-specific SKUs in US coastal metros.
- Bone Strengthening:Calcium and vitamin D co-fortification aligns with USDA school meal pattern updates creating preferential bidding status for K-12 cafeteria displacement of flavored milk.
- Energy Boost:B-vitamin complexes and iron fortification target fatigue-positioned consumption in Southeast Asian pharmacy channels where medicinal positioning bypasses crowded supermarket dairy aisles.
Digestive health handles the majority of throughput; immune support is expanding most quickly as post-pandemic consumer prioritization sustains premium pricing tolerance.
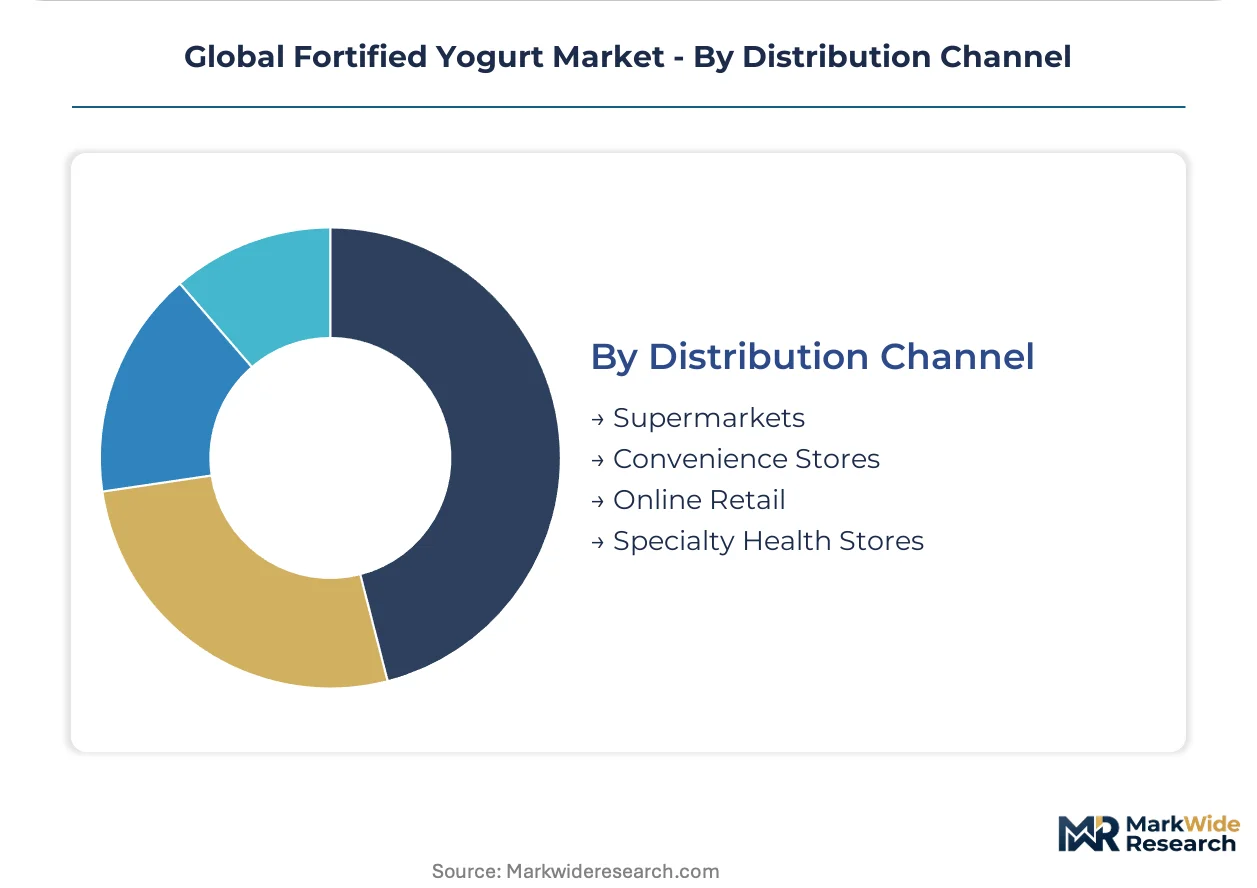
Distribution Channel:
Cold chain economics and live culture stability requirements create 12-18% logistics overhead premiums in tropical climates, reshaping channel viability calculations by geography.
- Supermarkets:Refrigerated dairy aisle placement captures bulk volume throughput in mature North American and Western European markets, with slotting fee economics favoring established brands with velocity history.
- Convenience Stores:Single-serve, ambient-stable UHT yogurt formats address immediate consumption occasions in urban transit corridors across Japanese and South Korean metropolitan networks.
- Online Retail:Direct-to-consumer subscription models with microbiome personalization are achieving 70% cohort retention rates in US coastal metros versus 25-30% conventional retail repeat purchase rates.
- Specialty Health Stores:Pharmacy and drugstore networks in Vietnam and Indonesia represent white space for medicinal-positioned probiotic yogurt with digestive health claims, bypassing competitive supermarket environments.
Supermarkets handle the majority of throughput; online retail is the fastest mover on share as subscription economics erode traditional slotting fee structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply by geography. Indian consumers demonstrate high sensitivity to per-unit costs, driving dairy cooperative dominance. German and US buyers absorb premium pricing for strain-specific probiotic claims. Brazilian institutional procurement locks in volume at regulated price ceilings.
United States
USDA school meal pattern updates create preferential bidding status for calcium-fortified yogurt displacing flavored milk in K-12 cafeterias. FDA nutrient content claim revisions delay new product launches as legal teams reassess protein thresholds. Chobani anchors protein-fortified Greek yogurt positioning through sustained fermentation expertise in upstate New York.
India
FSSAI fortification mandates for organized retail create compliance arbitrage with traditional milk channels. Dairy cooperatives expand probiotic and vitamin-enriched access through urban retail chains. Amul and Mother Dairy leverage Gujarat and Maharashtra procurement networks to lock in multi-year school feeding scheme contracts.
Germany
EFSA's 2023 QPS list updates accelerate novel Lactobacillus strain commercialization across EU member states. REACH microplastics monitoring requirements force mono-material packaging migration ahead of 2026 retailer deadlines. Bavarian and North Rhine-Westphalian dairy processors invest in fiber-based cup alternatives to satisfy unilateral German retail phase-out timelines.
Brazil
ANVISA regulates probiotic health claim substantiation with stricter evidentiary requirements than regional neighbors. Daycare network procurement creates volume anchors for zinc-fortified SKUs with multi-year contract cycles. São Paulo and Minas Gerais dairy clusters concentrate formulation capacity for pediatric nutrition program compliance.
Japan
METI promotes functional food innovation through streamlined novel food ingredient approval pathways. Convenience store networks demand ambient-stable UHT formats for metropolitan transit corridor distribution. Tokyo and Osaka refrigerated dairy aisles prioritize live culture stability claims with 10^6 CFU/g retention guarantees.
Global Fortified Yogurt Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Fermentation specialists with strain libraries command premium positioning, while dairy cooperatives leverage raw milk access for commodity fortification plays. The market consolidates around three strategic archetypes: multinational CPG conglomerates with global distribution, regional dairy cooperatives with captive supply, and insurgent precision-fermentation platforms. Dominant competitive moves include M&A for strain portfolio expansion and backward integration into fortificant ingredient sourcing.
Within the multinational tier, Danone and Nestlé exemplify divergent geographic strategies. Danone leverages European fermentation expertise to sustain shelf-stable distribution networks across tropical climates. Nestlé competes through localized vitamin D and calcium formulations tailored to emerging market cooperative networks. Chobani anchors the insurgent specialist archetype, occupying a position defined by Greek-style protein fortification and direct-to-consumer subscription economics.
| Leading Market Players |
|---|
| Nestlé |
| Ultima Foods |
| Danone |
| Arla Foods Ingredients |
| General Mills |
| Chobani |
| Sodiaal |
| Lactalis |
| FAGE International S.A. |
| Others |
Supply & Pricing Matrix
Oat protein concentrate substitution for dairy solids is simultaneously shifting raw material sourcing toward Nordic and Canadian grain processors while compressing margin structures for traditional whey protein suppliers. This input migration redraws procurement geography and forces pricing recalibration across plant-based and hybrid formulation tiers.
Pricing Analysis
Subscription renewal revenue from microbiome-personalized programs now exceeds initial hardware-equivalent product sales in lifetime value calculations for insurgent brands. Three-tier pricing structure across premium precision-fermented, standard Greek-style protein, and economy commodity fortification levels stratifies the market. Price differentiation hinges on EFSA QPS strain certification status and cold chain delivery guarantees. Cost compression in the economy tier is intensifying as Indian dairy cooperatives expand volume procurement. Institutional buyers in Brazilian daycare networks demonstrate lowest price sensitivity; Indian school feeding schemes face highest per-unit cost pressure.
Supply Chain Analysis
Inventory lead times for vitamin D3 and calcium carbonate have extended as Chinese chemical processing hubs face export documentation scrutiny under REACH-aligned protocols. Raw material sourcing draws from China for fortificant concentrates, India for dairy cooperative milk solids, and Germany for precision fermentation equipment. Single-source vulnerability concentrates in vitamin D3 supply clusters. Distribution runs through refrigerated dairy aisles in mature markets, with direct-to-consumer subscription models bypassing traditional slotting fee structures in US coastal metros.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities dominate value capture in this market, with microbiome testing subscriptions and strain-specific recommendation engines expanding faster than base yogurt product sales.
For Market Incumbents: Fortify strain portfolio depth through backward integration into precision fermentation platforms before Perfect Day and Remilk licensing terms harden. Lock in multi-year procurement contracts with Indian school feeding schemes and Brazilian daycare networks to anchor volume against emerging cooperative competition. EFSA's tightening QPS approval timelines threaten to accelerate R&D cost inflation for laggards. For New Entrants and Emerging Players: Anchor in Southeast Asian pharmacy channels in Vietnam and Indonesia, where medicinal-positioned probiotic yogurt faces minimal incumbent saturation. Target flexitarian households with dual-fortification oat-based formats that bypass crowded dairy aisles. Deploy direct-to-consumer microbiome test kits to establish subscription economics before retail slotting fee barriers solidify. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors precision fermentation platform owners with recombinant protein expression capabilities. Five-to-ten year viability hinges on regulatory approval velocity for novel strains and packaging material transitions. Acquisition target archetype: mid-tier brands with established cold chain distribution but limited R&D bandwidth for EFSA compliance. Monitor EFSA QPS list update frequency as inflection signal for R&D cost trajectories.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Platform Licensing | Enables clean-label fortification without lactose or cholesterol for premium tier positioning. |
| EFSA QPS Strain Portfolio Expansion | Accelerates novel Lactobacillus commercialization across EU member states with reduced approval uncertainty. |
| Direct-to-Consumer Subscription Launch | Achieves 70% cohort retention rates versus 25-30% conventional retail repeat purchase economics. |
| Mono-Material Packaging Migration | Satisfies German and Dutch retailer 2026 deadlines ahead of REACH microplastics mandates. |
| Institutional Cafeteria Contract Lock-In | Captures multi-year procurement cycles in Indian school feeding and Brazilian daycare networks. |
Research Methodology
Operator-level perspectives from fermentation specialists, dairy cooperative procurement managers, retail category buyers, and regulatory affairs directors anchored the qualitative base. Primary interviews combined with secondary validation from FSSAI fortification circulars, EFSA QPS list updates, FDA nutrient content claim dockets, and customs trade data for fortificant imports. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Sensitivity analysis tested input assumptions across the projection horizon. Segmentation dimensions modeled include product type architecture, fortification ingredient sourcing geography, application benefit positioning, and distribution channel economics. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment. Forecast inputs incorporated live culture stability cost curves and precision fermentation scale-up timelines.
Material uncertainties — EFSA probiotic strain approval delays, REACH packaging mandate acceleration, and Indian cooperative capacity expansion — sit outside the modeled envelope. Forecasts reflect documented assumptions subject to revision from these factors. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Global Quercetin Market
Vitamin Fortified
Calcium-Fortified Food Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Global Mineral Fortification Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Calcium-Fortified Cereals Market