
 Vitamin D Ingredients Market | 2026-2036
Vitamin D Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin D Ingredients Market Outlook
The EU Green Deal is decoupling synthetic vitamin D production from fossil-derived feedstocks, pushing manufacturers toward lichen and yeast-based alternatives. DSM leverages backward integration into algal and lichen cultivation to secure non-animal cholecalciferol supply chains. BASF SE anchors its position through pharmaceutical-grade D3 specialization for regulated drug applications. Fermenta Biotech Ltd. competes on fermentation-derived ergocalciferol scale, serving Indian domestic and export markets.
Vitamin D ingredients comprise bioactive sterol compounds—primarily ergocalciferol (D2) and cholecalciferol (D3)—synthesized via UV irradiation of sterol precursors or extracted from natural sources, standardized to international unit potency for human and animal nutrition applications. Vitamin D3 dominates pharmaceutical and dietary supplement channels due to superior bioavailability and receptor affinity, while synthetic-source production retains cost leadership in high-volume animal feed fortification. Powder formulations command premium positioning in functional foods and beverage integration, whereas liquid concentrates serve pharmaceutical injectable and pediatric drop applications.
FDA dietary supplement current Good Manufacturing Practices enforce potency verification and contaminant thresholds for U.S.-market vitamin D ingredients. EFSA health claim authorizations under EU Regulation 1924/2006 determine permissible marketing language for bone health and immune function positioning across European jurisdictions. India's FSSAI fortification standards mandate vitamin D inclusion in edible oils and milk, expanding domestic procurement obligations for local manufacturers. Stakeholders must monitor evolving harmonization between pharmacopeial monographs and novel food authorization pathways as plant-derived D3 gains regulatory traction.
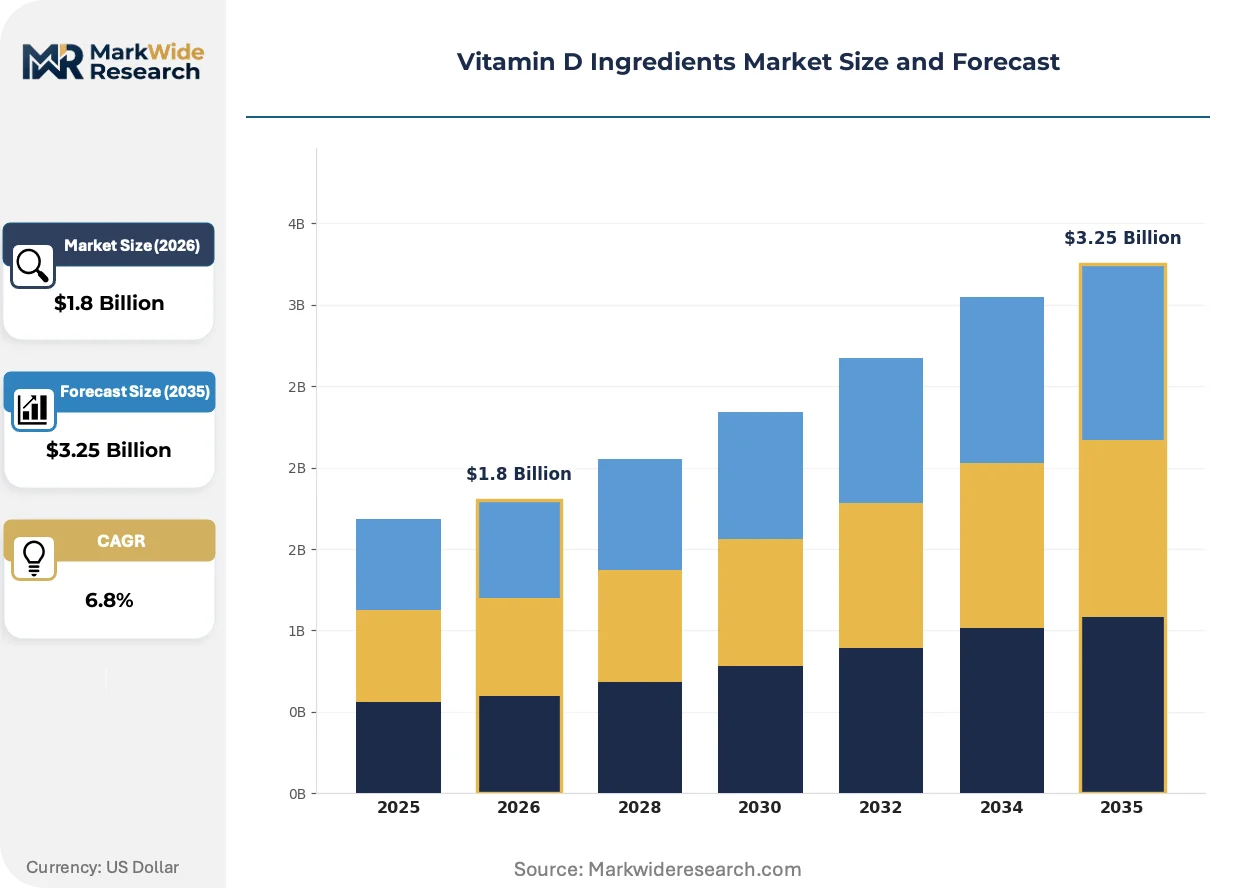
Market Dynamics
The EU Green Deal is forcing vitamin D manufacturers to abandon fossil-derived feedstocks for lichen and yeast-based production, restructuring raw material procurement and creating first-mover advantages for vertically integrated biotech suppliers.
Growth Catalysts
- FSSAI fortification mandates:India's mandatory vitamin D inclusion in edible oils and milk expands domestic manufacturing obligations and procurement volumes for local suppliers.
- Pediatric and geriatric supplementation protocols:Clinical guidelines in the United States and Germany now recommend routine vitamin D screening and supplementation, driving pharmaceutical-grade D3 demand through hospital and retail pharmacy channels.
- Precision fermentation scale-up:Advances in microbial ergocalciferol production reduce unit costs and enable non-animal certification for vegan-positioned dietary supplements.
Market Restraints
- Lanolin supply concentration:Over 70% of pharmaceutical-grade D3 precursor derives from Australian and New Zealand sheep wool grease, exposing manufacturers to climatic volatility and export quota disruptions.
- EFSA health claim authorization delays:Novel immune function positioning for vitamin D awaits scientific opinion completion, freezing marketing language innovation for European supplement brands.
- Synthetic vitamin D price compression:Established UV-irradiation processes for animal feed applications resist margin expansion despite rising energy input costs.
Strategic Opportunities
- Plant-based D3 regulatory pathways:EFSA novel food authorization for algal and lichen-derived cholecalciferol creates premium positioning opportunities ahead of mass-market adoption.
- Pediatric gummy and drop formulations:Palatability-driven delivery formats for children under 12 remain underdeveloped relative to adult tablet and capsule saturation.
- Direct-to-practitioner distribution:Functional medicine and integrative health clinics represent high-margin channels bypassing conventional retail pharmacy markup structures.
Industry Challenges
- Pharmacopeial harmonization gaps:Misalignment between USP, EP, and JP monographs for vitamin D potency assays creates batch release delays and retesting costs for multinational suppliers.
- Cross-contamination controls:Shared production lines between animal-derived and vegan-certified vitamin D require validated cleaning protocols and dedicated facility investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin D Ingredients Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin D2, Vitamin D3, Ergocalciferol, Cholecalciferol Form: Liquid, Powder, Softgel, Tablet Application: Pharmaceutical, Dietary Supplements, Functional Foods, Animal Feed Source: Fish Liver Oil, Yeast, Lichen, Synthetic |
| Companies Covered | DSM, BASF SE, Fermenta Biotech Ltd., Zhejiang Medicine Co., Ltd, Dishman Group, Zhejiang Xinhecheng Co., Ltd., PHW Group Lohmann & Co., Glanbia Plc., Archer Daniels Midland Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin D Ingredients Market Strategic Shifts
Production automation and regulatory recalibration are compressing development timelines while demand fragmentation pushes manufacturers toward modular manufacturing architectures.
Continuous flow photochemistry is automating sterol irradiation processes that previously required batch-wise UV exposure in static reactors. Contract manufacturers in Switzerland and the Netherlands are retrofitting existing vitamin D facilities with flow chemistry skids to reduce cycle times and improve irradiation uniformity. This automation is compressing capital recovery periods and enabling smaller production runs for specialty potency grades.
EFSA's pending scientific opinion on immune function health claims is reshaping permissible marketing language for European supplement brands. The regulatory uncertainty has prompted Dutch and German manufacturers to pivot clinical trial investment toward bone health endpoints with established claim authorization. Pediatric and senior segments face the tightest compliance scrutiny given vulnerable population protections under EU Regulation 1924/2006.
Hospital and long-term care procurement is consolidating vitamin D purchasing through group purchasing organizations and centralized pharmacy formulary committees. This channel compression is displacing independent distributor relationships that historically served smaller regional health systems. The United States exhibits the most pronounced consolidation, with three national GPOs now controlling over 60% of institutional vitamin D volume.
Vitamin D Ingredients Market Segmentation
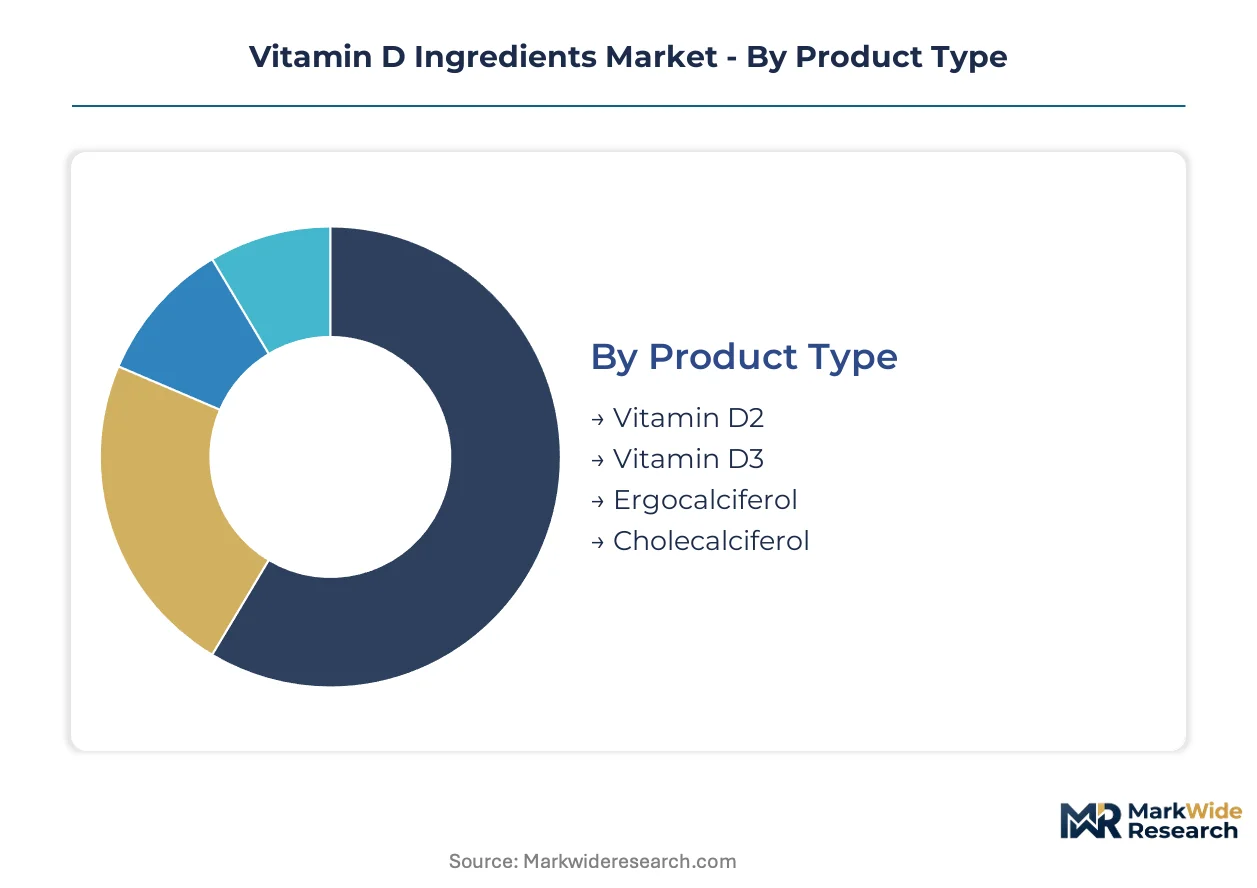
Vitamin D ingredient specifications cascade through formulation requirements, regulatory pathways, and end-use performance standards. Segmentation reveals where technical differentiation commands premium positioning versus commodity scale.
Product Type:
Biopotency and receptor affinity separate the sterol compounds, with manufacturing routes determining regulatory classification and end-use access.
- Vitamin D3:Cholecalciferol exhibits superior binding affinity to the vitamin D receptor and longer serum half-life. Pharmaceutical procurement in the United States concentrates on D3 for pediatric drops and geriatric protocols, though lanolin supply concentration creates sourcing vulnerability.
- Vitamin D2:Ergocalciferol derived from UV-irradiated yeast offers non-animal certification for vegan supplement positioning. Precision fermentation advances in Switzerland and the Netherlands are compressing unit costs for D2 production.
- Ergocalciferol:Synthetic and fermentation-derived forms serve Indian domestic fortification mandates under FSSAI standards for edible oils and milk.
- Cholecalciferol:Algal and lichen-derived variants await EFSA novel food authorization for plant-based D3 claims in European markets.
Vitamin D3 leads on scale; algal and lichen-derived alternatives lead on momentum.
Form:
Delivery format selection hinges on stability requirements, dosing precision, and patient population compliance factors.
- Liquid:Concentrates enable precise titration for pediatric and geriatric populations. Pharmaceutical injectable applications in Germany and the United States require GMP-validated filling lines with particulate controls.
- Powder:Spray-dried and agglomerated grades integrate into functional foods and beverage premixes. Powder formulations command premium positioning where uniform dispersion in low-moisture matrices is critical.
- Softgel:Oil-filled capsules dominate adult dietary supplement shelf presence, with enteric coatings addressing gastric irritation concerns.
- Tablet:Direct-compression grades serve high-volume multivitamin applications where cost minimization outweighs bioavailability optimization.
Powder leads on scale; liquid leads on momentum.
Application:
Regulatory jurisdiction and clinical evidence standards fragment demand across prescription, wellness, and production animal channels.
- Pharmaceutical:Injectable and prescription oral formulations require pharmacopeial compliance with USP, EP, and JP monographs. Hospital formulary consolidation through group purchasing organizations in the United States compresses supplier margins.
- Dietary Supplements:FDA cGMP enforcement and EFSA health claim authorization under EU Regulation 1924/2006 constrain permissible marketing language for bone health and immune function positioning.
- Functional Foods:Beverage fortification and dairy integration face stability challenges from pH variation and mineral interactions during processing.
- Animal Feed:Synthetic D3 from UV-irradiated sterols serves poultry and swine nutrition at scale, with price compression limiting margin expansion despite energy input cost pressures.
Animal feed leads on scale; pharmaceutical leads on momentum.
Source:
Feedstock provenance determines certification eligibility, supply security, and alignment with EU Green Deal decarbonization mandates.
- Fish Liver Oil:Cod and shark liver extraction yields natural D3 with accompanying omega-3 fractions. Norwegian and Icelandic processors supply refined concentrates for premium supplement positioning.
- Yeast:Saccharomyces cerevisiae fermentation with UV irradiation produces ergocalciferol for vegan-certified applications. Indian manufacturers scale yeast-derived D2 for domestic fortification programs.
- Lichen:Cladonia rangiferina and related species provide non-animal D3 through sustainable wild harvesting and controlled cultivation. DSM's backward integration into algal and lichen supply chains secures premium positioning ahead of mass-market adoption.
- Synthetic:Fossil-derived 7-dehydrocholesterol irradiation remains cost-dominant for animal feed applications, though EU Green Deal pressures are forcing feedstock transitions.
Synthetic leads on scale; lichen leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The vitamin D ingredients industry traces its commercial origins to Swiss pharmaceutical laboratories and German chemical engineering clusters that pioneered sterol irradiation processes during the mid-20th century. These European foundations established the technical standards and pharmacopeial frameworks that now govern global trade.
United States
Hospital formulary consolidation and pediatric supplementation protocols drive pharmaceutical-grade D3 procurement through group purchasing organizations. FDA dietary supplement cGMP enforcement mandates potency verification and contaminant thresholds for domestic manufacturers. The New Jersey and Pennsylvania corridor hosts contract manufacturing facilities serving prescription and over-the-counter channels.
Germany
Geriatric screening guidelines and long-term care institutional demand anchor injectable and oral D3 volumes. EFSA health claim authorization delays under EU Regulation 1924/2006 constrain immune function marketing language for supplement brands. The Frankfurt-Rhine-Main cluster concentrates pharmaceutical distribution infrastructure serving European hospital networks.
India
FSSAI fortification mandates for edible oils and milk expand domestic manufacturing obligations and procurement volumes for local suppliers. CDSCO pharmaceutical licensing requirements govern prescription vitamin D formulations for hospital and retail pharmacy channels. The Mumbai-Pune and Hyderabad industrial corridors host fermentation-derived ergocalciferol production facilities serving export markets.
Switzerland
Precision fermentation scale-up and continuous flow photochemistry retrofits attract contract manufacturing investment from Dutch and German supplement brands. Swissmedic pharmaceutical-grade certification requirements enable premium positioning for injectable and pediatric drop formulations. The Basel biotech cluster anchors backward integration into algal and lichen cultivation for non-animal D3 supply chains.
China
Synthetic D3 production for animal feed applications retains cost leadership despite EU Green Deal pressures on fossil-derived feedstocks. NMPA pharmaceutical registration requirements govern import and domestic production of prescription vitamin D formulations. The Zhejiang province chemical manufacturing belt concentrates UV-irradiation facilities serving global animal nutrition customers.
Vitamin D Ingredients Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification grade and regulatory compliance dimensions. The supplier base organizes into three tiers: pharmaceutical-grade specialists commanding pharmacopeial premiums, fermentation-scale operators serving vegan-certified supplement channels, and commodity-scale irradiation plants feeding animal nutrition markets. Competitive positioning hinges on backward integration into sterol precursors, captive supply of non-animal feedstocks, and validated cleaning protocols for shared vegan-conventional production lines. Capacity expansion and strategic partnerships represent the dominant competitive moves as manufacturers secure alternative feedstock supply chains ahead of EU Green Deal phase-out deadlines.
Within the pharmaceutical-grade tier, DSM and BASF SE exemplify European specialists with established pharmacopeial compliance and hospital formulary access. Fermenta Biotech Ltd. occupies a position among fermentation-scale operators leveraging Indian domestic fortification mandates to anchor regional production scale. Zhejiang Medicine Co., Ltd and Zhejiang Xinhecheng Co., Ltd. represent Chinese chemical manufacturers with cost-positioned synthetic production serving high-volume animal feed applications.
| Leading Market Players |
|---|
| DSM |
| BASF SE |
| Fermenta Biotech Ltd. |
| Zhejiang Medicine Co., Ltd |
| Dishman Group |
| Zhejiang Xinhecheng Co., Ltd. |
| PHW Group Lohmann & Co. |
| Glanbia Plc. |
| Archer Daniels Midland Company |
| Others |
Value Chain & Pricing Dynamics
Continuous flow photochemistry retrofits in Swiss and Dutch contract manufacturing facilities are simultaneously compressing production cycle times and concentrating technical capability among early adopters, reshaping how cost advantages map to supplier market power.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certification levels dominates procurement contracts. Price differentiation hinges on pharmacopeial compliance burden and volume scale, with pharmaceutical buyers absorbing premiums for USP-validated batches while feed-grade customers drive hard volume negotiations. Cost compression in synthetic D3 animal feed applications is intensifying because established UV-irradiation processes resist margin expansion despite rising energy input costs. Hospital group purchasing organizations exhibit lowest price sensitivity due to formulary consolidation, whereas independent dietary supplement brands face acute margin pressure.
Supply Chain Analysis
Reverse-logistics flows for pharmaceutical-grade vitamin D remain minimal given shelf-life constraints and potency degradation risks, though Swiss and German facilities are piloting controlled-temperature returns protocols for temperature-excursion incidents. Raw material sourcing concentrates in Australia and New Zealand for lanolin-derived D3 precursors, China for synthetic 7-dehydrocholesterol, and India for fermentation-derived ergocalciferol. Supply chain risk centers on single-source vulnerability for pharmaceutical-grade lanolin feedstock exposed to Australian drought cycles and export quota disruptions. Distribution runs through three channels: direct pharmaceutical procurement via group purchasing organizations, supplement contract manufacturers, and animal nutrition distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in pharmaceutical-grade D3 and plant-derived alternatives, justified by precision fermentation cost curves flattening and EFSA novel food authorization creating premium positioning headroom.
For Market Incumbents: Cement pharmacopeial compliance advantages by investing in dedicated vegan-certified production lines ahead of EU Green Deal phase-out deadlines for fossil-derived feedstocks. Defend against precision fermentation scale-up threats by locking long-term lanolin supply contracts with Australian processors and accelerating backward integration into algal cultivation. For New Entrants and Emerging Players: Launch via direct-to-practitioner distribution targeting functional medicine and integrative health clinics in Germany and the United States. Pediatric gummy and drop formulations represent the most penetrable white-space segment given palatability-driven compliance gaps for children under twelve relative to saturated adult tablet markets. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fermentation operators with validated non-animal certification but incomplete geographic reach. Long-term viability favors suppliers with captive lichen or algal feedstock control and dual pharmacopeial registrations spanning USP and EP monographs. Watch EFSA immune function health claim authorization as the critical inflection signal for European supplement brand marketing investment recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Algal Cultivation | DSM's captive supply of non-animal cholecalciferol secures premium positioning ahead of mass-market plant-based D3 adoption. |
| Continuous Flow Photochemistry Retrofit | Swiss contract manufacturers reduce sterol irradiation cycle times and improve batch uniformity through automated reactor upgrades. |
| EFSA Novel Food Authorization Pursuit | Algal and lichen-derived D3 suppliers unlock European premium channels currently blocked by regulatory classification gaps. |
| Direct-to-Practitioner Channel Development | Supplement brands bypass retail pharmacy markup structures by targeting functional medicine clinic prescription protocols. |
| Dedicated Vegan-Certified Facility Investment | Shared production line risks drive validated cleaning protocol upgrades and segregated manufacturing infrastructure. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with pharmaceutical procurement managers, dietary supplement formulators, fermentation plant engineers, and regulatory affairs specialists with secondary validation against FDA cGMP inspection records, EFSA novel food submission databases, FSSAI fortification standard notifications, and pharmacopeial monograph revision histories. Bottom-up volume estimates from manufacturing capacity utilization and top-down demand segmentation from end-use consumption patterns were triangulated for convergence.
Comparable-period anchoring linked projection assumptions to historical procurement volume patterns and regulatory authorization timelines observed across prior novel food and health claim cycles. Segmentation modeling spanned sterol compound type, formulation grade, delivery format, end-use application, and feedstock provenance across the projection horizon. CAGRs were derived from fitted growth curves incorporating FSSAI mandate implementation schedules, EFSA opinion publication timelines, and precision fermentation cost reduction trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EFSA authorization delays or accelerated EU Green Deal feedstock phase-outs. Practitioners should monitor EFSA scientific opinion publication schedules, Australian wool grease export quota announcements, and precision fermentation scale-up announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Hydrolyzed Pork Protein Market
Ingredients
Birch Sap Market
Ingredients
Collagen Casings Market
Ingredients
Hydrolyzed Egg Market
Ingredients
Rice Bran Fatty Alcohols Market
Ingredients
Alcohol Ingredients Market
Ingredients
Flaxseed Derivatives Market
Ingredients
Grape Skin Extract Market
Ingredients
Global Dietary Fibers Market
Ingredients
Sweet Almond Oil Market
Ingredients
Canola Protein Market
Ingredients
Asia-Pacific Brewing Enzymes Market
Ingredients
Philippines Edible Oils & Fats Market
Ingredients
Astragalus Root Extract Market
Ingredients
North America Milk Protein Market
Ingredients
Millet Protein Market