
 Vitamin E Market | 2026-2036
Vitamin E Market Size, Share, and Industry Trends Forecast 2026-2036
Vitamin E Market Analysis
Phytochemical extraction expertise is collapsing across traditional supply regions, forcing manufacturers to rebuild technical capabilities from seed oil processing through molecular distillation. DSM-Firmenich NV leverages its integrated biotechnology platform to sustain tocopherol yields from renewable feedstocks. BASF SE anchors its position through synthetic vitamin E production at industrial scale. Kemin Industries Inc. differentiates via specialized plant-derived tocotrienol formulations for premium nutraceutical channels.
Vitamin E denotes a family of fat-soluble antioxidants comprising four tocopherols and four tocotrienols, with alpha-tocopherol exhibiting the highest biological activity and serving primarily as a dietary supplement and food preservative against lipid peroxidation. Natural tocopherol extracts command premium positioning in cosmetics and clean-label food applications where synthetic alternatives face formulation restrictions. The dietary supplements end user segment leads absolute volume consumption, while tocotrienol isolates within the product type category represent the fastest-growing margin pool due to emerging research in cellular health applications.
The FDA governs dietary supplement labeling and Good Manufacturing Practice compliance for vitamin E products distributed in the United States, while the EMA and EFSA regulate health claim substantiation and novel food approvals across European jurisdictions. China's NMPA and national food safety standards additionally shape import requirements and domestic production licensing for tocopherol concentrates. Stakeholders must monitor evolving tocotrienol extraction patents and regulatory reclassifications of antioxidant health claims to anticipate where value capture will shift in bioactive ingredient supply chains.
Market Dynamics
The collapse of phytochemical extraction expertise across traditional supply regions is forcing manufacturers to rebuild technical capabilities from seed oil processing through molecular distillation, fundamentally restructuring competitive advantage in tocopherol and tocotrienol production.
Growth Catalysts
- Immune-support portfolio expansion:Dietary supplement manufacturers are accelerating vitamin E inclusion in immune health formulations, driven by post-pandemic consumer prioritization of preventive wellness.
- FDA labeling modernization:Updated dietary supplement labeling requirements are compelling reformulation investments that upgrade product quality tiers and open premium positioning opportunities.
- China's nutraceutical manufacturing corridor:Demand concentration in China's processing hubs is creating economies of scale that lower unit costs for global distribution.
Market Restraints
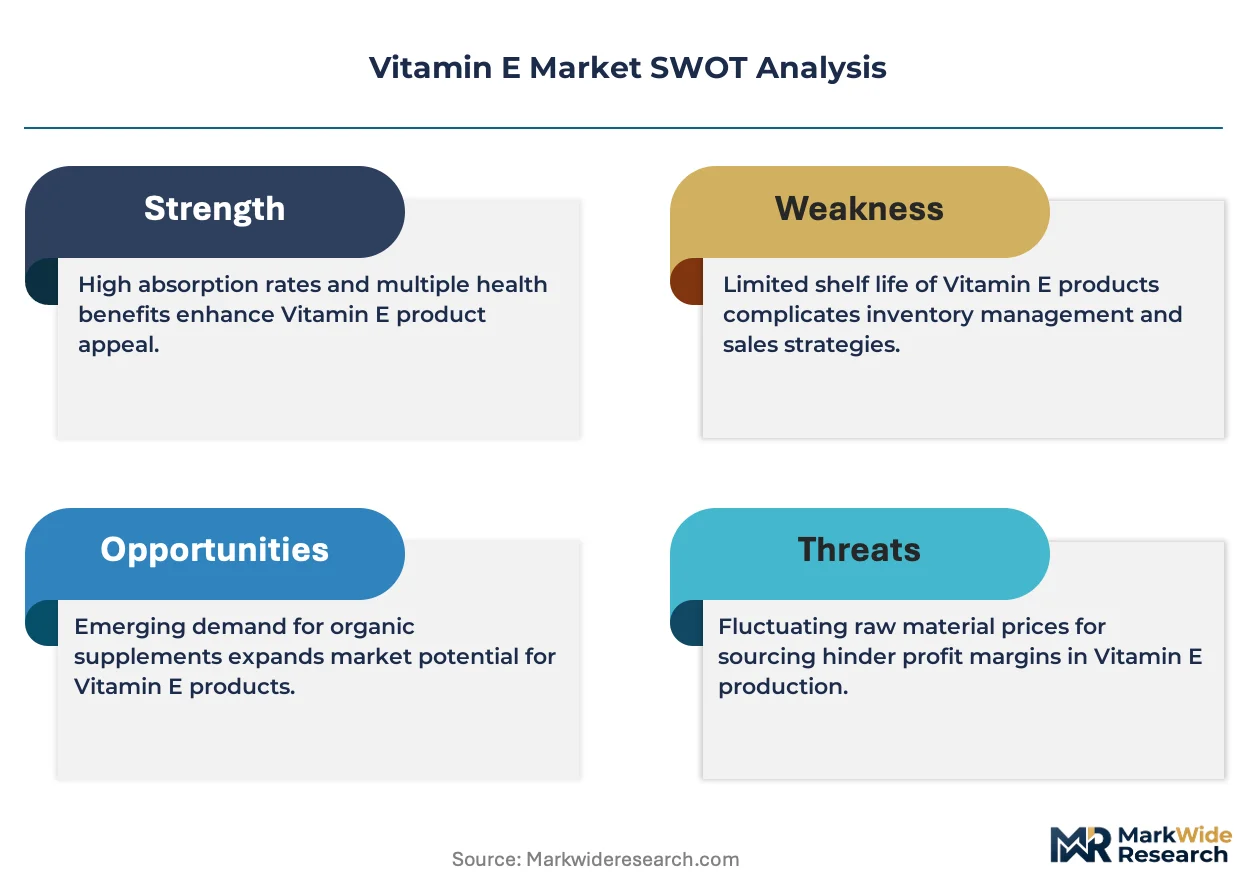
- Feedstock cost volatility:Vegetable oil price swings directly compress tocopherol extraction margins, with soybean and sunflower oil markets exhibiting cyclical instability.
- Technical capability scarcity:Molecular distillation expertise concentrates among a shrinking pool of specialists, creating bottleneck risks in high-purity natural vitamin E production.
- Synthetic-natural substitution pressure:Synthetic vitamin E from petrochemical routes maintains cost advantages that constrain natural extract penetration in price-sensitive food applications.
Strategic Opportunities
- Tocotrienol cellular health applications:Emerging research in neuroprotection and cholesterol management is opening pharmaceutical-adjacent positioning for palm and rice-derived tocotrienol isolates.
- Clean-label cosmetic formulation:EU and North American cosmetic brands are eliminating synthetic antioxidants, creating pull for natural tocopherol in premium skincare.
- Biotechnology platform integration:Renewable feedstock fermentation and enzymatic conversion technologies are enabling novel production pathways independent of agricultural commodity cycles.
Industry Challenges
- Patent landscape navigation:Evolving tocotrienol extraction patents and process IP from Malaysian and Japanese research institutions create licensing complexity for new market entrants.
- Multi-jurisdiction compliance synchronization:Reconciling FDA Good Manufacturing Practice requirements with EFSA health claim substantiation protocols and China's NMPA licensing demands stretches regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vitamin E Market |
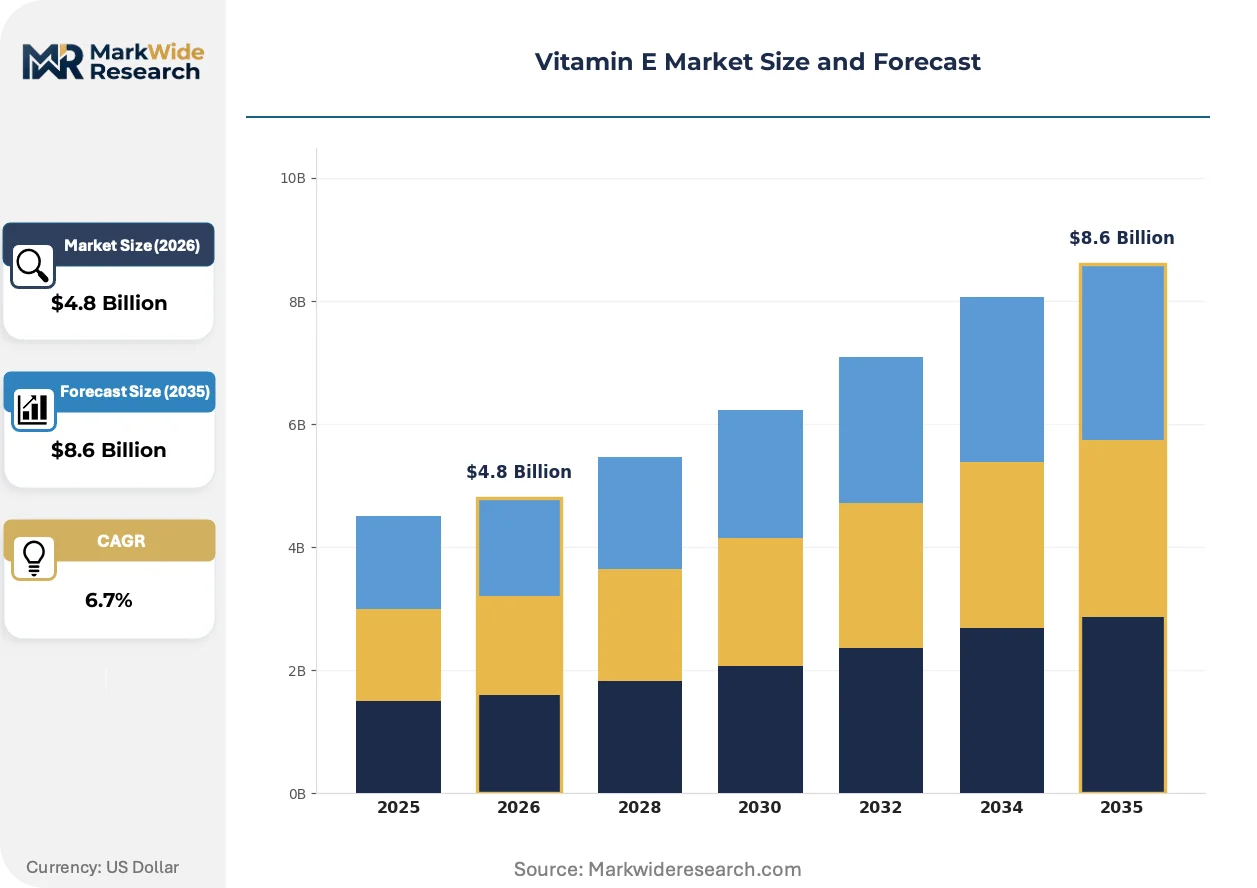
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Synthetic, Mixed, Tocopherols Formulation: Softgels, Capsules, Oil, Powder End User: Dietary Supplements, Cosmetics, Pharmaceuticals, Food & Beverage Distribution Channel: Online Retail, Supermarkets, Health Stores, Pharmacies |
| Companies Covered | Archer Daniels Midland Company, BASF SE, DSM-Firmenich NV, Cargill Incorporated, Wilmar International Limited, Davos Life Science Pte Ltd, Merck KGaA, Kemin Industries Inc., BTSA Biotecnologías Aplicadas S.L., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vitamin E Market Emerging Trajectories
Supercritical CO2 extraction and membrane separation technologies are displacing conventional solvent-based methods, while regulatory divergence between jurisdictions is fragmenting formulation standards and procurement patterns are compressing supplier qualification cycles.
Supercritical CO2 extraction systems are displacing hexane-based solvent extraction in high-purity natural tocopherol production. European nutraceutical contract manufacturers are adopting these systems fastest, with German and Swiss processors leading capital deployment. This displacement is compressing the viable supplier base to equipment-capitalized specialists while raising purity benchmarks that marginalize legacy processors.
EFSA's evolving stance on antioxidant health claim substantiation is tightening evidentiary requirements for tocopherol and tocotrienol marketing. The regulation now demands human intervention studies for cardiovascular and cellular protection claims, forcing reformulation of legacy product positioning. Premium supplement brands targeting EU distribution are responding by funding clinical trials and shifting messaging toward generic wellness framing.
Direct procurement relationships between finished goods manufacturers and extraction specialists are shortening traditional multi-tier distribution channels. Large dietary supplement brands in the United States and Germany are bypassing ingredient traders to secure volume commitments with Malaysian palm tocotrienol processors. This channel compression is most visible in North America, where vertical integration between brand houses and extraction assets is accelerating.
Vitamin E Market Segmentation
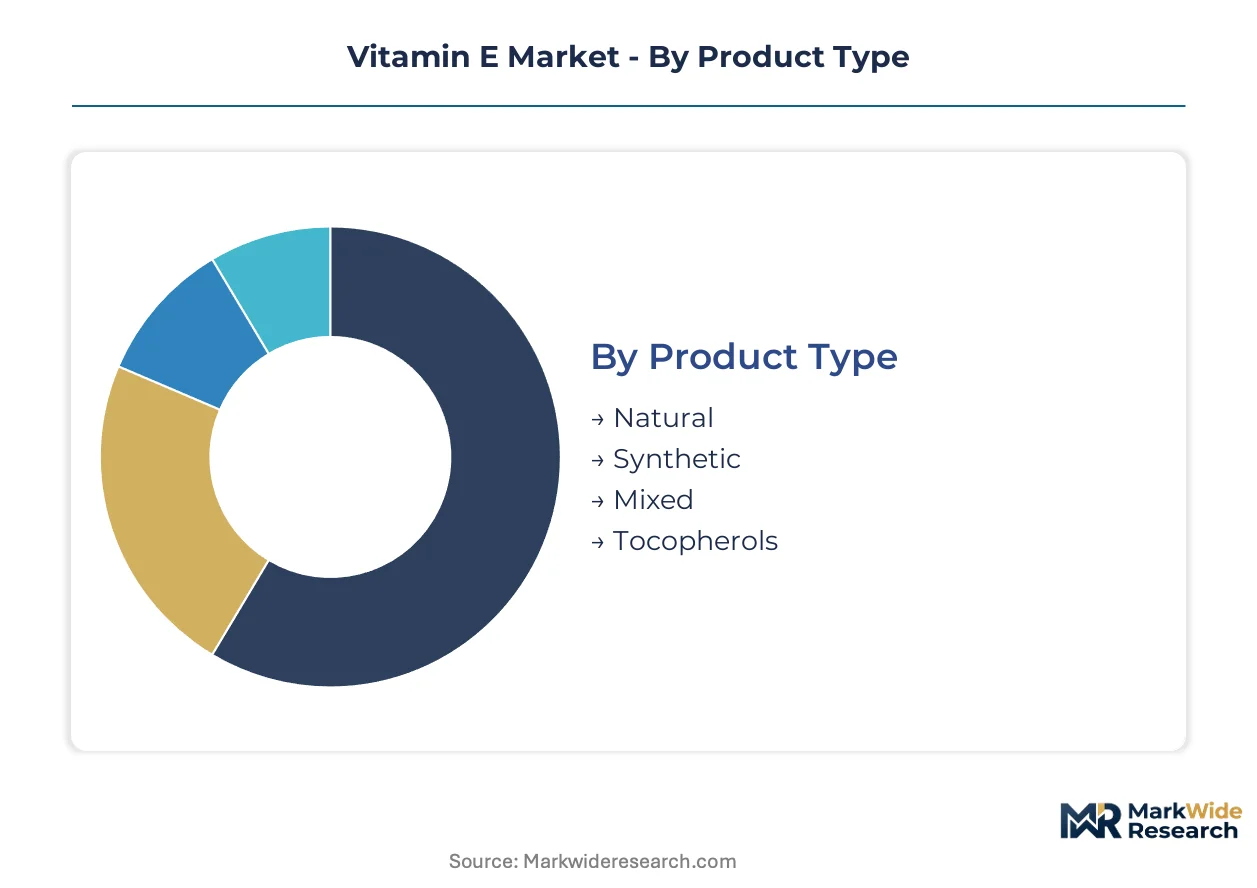
Vitamin E market segmentation reveals how regulatory frameworks, formulation requirements, and channel economics fragment commercial opportunity across distinct technical and customer profiles. Understanding these divides exposes where margin pools concentrate and where supply constraints create competitive bottlenecks.
Product Type:
Regulatory differentiation between natural and synthetic tocopherols creates tiered compliance burdens that reshape competitive positioning across jurisdictions.
- Natural:Alpha-tocopherol extracted from vegetable oils via molecular distillation carries premium positioning in EU cosmetic and clean-label food applications where EFSA restrictions on synthetic antioxidants apply. Chinese nutraceutical manufacturers concentrate demand here for immune-support portfolios targeting export markets.
- Synthetic:Petrochemical-derived all-rac-alpha-tocopherol dominates price-sensitive food preservation applications in the United States where FDA labeling permits equivalence claims. Cost advantages sustain volume leadership despite lower bioavailability versus natural forms.
- Mixed:Blended tocopherol concentrates balance cost and performance for industrial food applications requiring standardized antioxidant activity.
- Tocopherols:Isolated alpha-, beta-, gamma-, and delta-forms serve specialized pharmaceutical and research applications demanding precise stereochemistry.
Established volume favors Synthetic; emerging adoption favors Natural.
Formulation:
Cost tier differentiation separates capital-intensive softgel manufacturing from commodity powder processing, concentrating margin capture among equipment-specialized contract manufacturers.
- Softgels:Gelatin or plant-based encapsulation of tocopherol oils commands premium pricing in dietary supplement channels where bioavailability marketing drives consumer preference. German and Swiss contract manufacturers lead capacity deployment for EU distribution.
- Capsules:Hard-shell delivery systems accommodate higher-potency vitamin E dosing for clinical nutrition and pharmaceutical applications requiring precise unitization.
- Oil:Bulk tocopherol concentrates serve food industry fortification and cosmetic formulation where processors integrate antioxidants directly into lipid matrices.
- Powder:Spray-dried or microencapsulated forms enable dry-blend dietary supplements and functional food applications requiring extended shelf stability.
Softgels anchor premium positioning; Powder scales through commodity food fortification.
End User:
Application-specific purity standards and health claim substantiation requirements fragment demand across customer types with divergent regulatory exposure.
- Dietary Supplements:Post-pandemic immune health prioritization concentrates absolute volume consumption here, with brands reformulating portfolios to meet FDA's updated labeling requirements and EFSA's tightened antioxidant claim protocols.
- Cosmetics:EU clean-label momentum and elimination of synthetic antioxidants in premium skincare creates pull for natural tocopherol in North American and European beauty formulations.
- Pharmaceuticals:Tocotrienol isolates for emerging neuroprotection and cholesterol management research open pharmaceutical-adjacent positioning requiring clinical trial investment.
- Food & Beverage:Synthetic vitamin E preserves lipid-containing products where cost constraints override clean-label preferences, particularly in price-sensitive retail channels.
Dietary Supplements dominate volume; Pharmaceuticals present the steepest expansion trajectory.
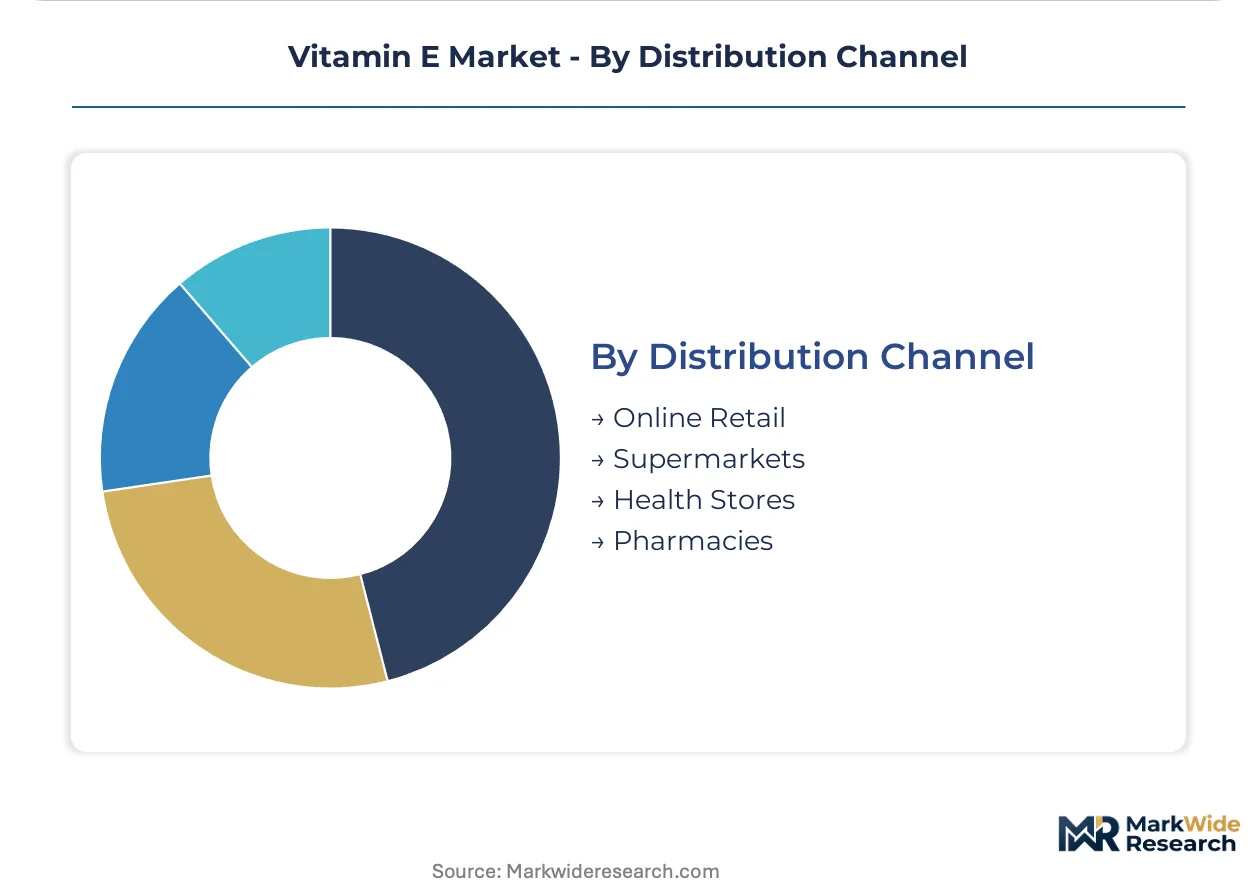
Distribution Channel:
Customer type and procurement scale determine channel economics, with direct manufacturer relationships compressing traditional trader margins in high-volume segments.
- Online Retail:Direct-to-consumer supplement brands leverage e-commerce for immune health product launches, bypassing brick-and-mortar slotting fees and capturing subscription recurring revenue.
- Supermarkets:Mass-market food fortification and private-label supplement placement depend on price-competitive synthetic vitamin E sourcing at industrial scale.
- Health Stores:Premium natural tocopherol and tocotrienol formulations target educated consumers seeking clean-label credentials and specialized antioxidant profiles.
- Pharmacies:Clinical-grade supplements and pharmacist-recommended brands require GMP certification and documentation supporting FDA compliance for professional channel distribution.
Pharmacies and Health Stores concentrate premium margin; Online Retail scales fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FDA's updated dietary supplement labeling requirements are reshaping manufacturing standards across the United States, while China's NMPA and national food safety standards drive production licensing in the dominant processing corridor. These regulatory anchors define where value concentrates and how supply chains reconfigure.
United States
Dietary supplement manufacturers in the United States are accelerating vitamin E inclusion in immune-support portfolios, responding to post-pandemic consumer prioritization of preventive wellness. The FDA's Good Manufacturing Practice compliance and updated labeling mandates compel reformulation investments that upgrade product quality tiers. Greater Boston and the New York Metro corridor host contract manufacturers deploying supercritical CO2 extraction systems for high-purity natural tocopherol production.
China
China's nutraceutical manufacturing corridor concentrates absolute volume demand as domestic processors scale for global distribution. The NMPA's production licensing requirements and national food safety standards shape import requirements for tocopherol concentrates. The Yangtze River Delta and Pearl River Delta industrial clusters anchor synthetic vitamin E production at industrial scale, with Zhejiang and Jiangsu provinces leading molecular distillation capacity deployment.
Germany
German nutraceutical contract manufacturers are adopting supercritical CO2 extraction systems fastest among European processors, capitalizing on EFSA's tightening evidentiary requirements for antioxidant health claims. The EMA and EFSA regulate health claim substantiation across European jurisdictions, demanding human intervention studies for cardiovascular positioning. The Baden-Württemberg and Bavaria regions concentrate softgel manufacturing capacity for premium EU distribution.
Malaysia
Malaysian palm tocotrienol processors are securing direct procurement relationships with large dietary supplement brands, bypassing traditional ingredient traders. The country's national food safety regulator and evolving extraction patents from domestic research institutions create licensing complexity for new entrants. The Klang Valley and Penang industrial zones specialize in palm-derived tocotrienol isolates for pharmaceutical-adjacent cellular health applications.
Switzerland
Swiss processors lead European capital deployment in membrane separation technologies for high-purity natural tocopherol extraction. Swissmedic regulates pharmaceutical-grade supplement distribution, while EFSA protocols govern antioxidant marketing claims. The Basel region and Zurich economic area anchor premium softgel contract manufacturing for clean-label cosmetic and nutraceutical channels targeting EU and North American markets.
Vitamin E Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the vitamin E market, with biotechnology platforms and petrochemical routes defining the upper stratum. The competitive structure rewards scale in synthetic production and extraction expertise in natural tocopherol isolation. Three archetypes dominate: integrated life-science conglomerates with fermentation capabilities, agribusiness processors controlling seed oil feedstocks, and specialized tocotrienol extractors serving premium nutraceutical channels. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as players secure renewable feedstock commitments and extraction technology licenses.
Within the integrated biotechnology tier, DSM-Firmenich NV exemplifies platform-based tocopherol production from renewable feedstocks, while BASF SE anchors synthetic manufacturing at industrial scale. Kemin Industries Inc. occupies a specialist position in plant-derived tocotrienol formulations for premium channels. These three entities represent how competitive advantage fragments across feedstock control, synthetic chemistry scale, and extraction specialization in a market where technical capability scarcity concentrates value capture among equipment-capitalized processors.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| BASF SE |
| DSM-Firmenich NV |
| Cargill Incorporated |
| Wilmar International Limited |
| Davos Life Science Pte Ltd |
| Merck KGaA |
| Kemin Industries Inc. |
| BTSA Biotecnologías Aplicadas S.L. |
| Others |
Supply Flow & Price Mechanics
Synthetic tocopherol displacement of natural extracts in price-sensitive food applications simultaneously shifts production gravity toward China's petrochemical corridors and compresses margin capture for vegetable oil-dependent processors in Europe and North America. This substitution dynamic concentrates pricing power among integrated synthetic manufacturers while fragmenting natural extract premiums across specialized cosmetic and pharmaceutical channels.
Pricing Analysis
Geographic price spreads between Chinese synthetic production and European natural extraction facilities exceed three-to-one multiples, with alpha-tocopherol from Zhejiang province commanding commodity-scale discounts against Swiss molecular distillation output. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certifications anchors differentiation, with FDA and EFSA compliance tiers adding substantial premiums. Cost compression in synthetic tocopherol is intensifying because BASF and DSM-Firmenich sustain industrial-scale fermentation and petrochemical routes. Mass-market food manufacturers exhibit highest price sensitivity, while pharmaceutical-adjacent tocotrienol buyers demonstrate lowest elasticity due to neuroprotection research funding.
Supply Chain Analysis
China and Malaysia anchor global tocopherol and tocotrienol production, with Zhejiang and Jiangsu provinces hosting synthetic manufacturing clusters and the Klang Valley specializing in palm-derived tocotrienol isolates. Feedstock dependencies center on soybean oil, sunflower oil, and crude palm oil for natural extraction, while synthetic routes draw from petrochemical intermediates and renewable fermentation sugars. Single-source vulnerability concentrates in Malaysian palm tocotrienol processors, where direct procurement relationships between brands and extractors bypass traditional trader networks. Distribution runs through vertically integrated nutraceutical contract manufacturers in Germany and Switzerland for premium EU channels, with bulk commodity flows serving US food fortification via direct importer relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The vitamin E market sits at an early-cycle expansion phase driven by tocotrienol cellular health research penetrating pharmaceutical-adjacent applications. Post-pandemic immune-support portfolio expansion sustains foundational demand while clean-label cosmetic reformulation accelerates premium natural extract adoption.
For Market Incumbents: Secure captive supply of vegetable oil feedstocks through backward integration into seed crushing and molecular distillation capacity in China's Yangtze River Delta. Defend against synthetic-natural substitution pressure by certifying natural tocopherol for EU cosmetic applications where EFSA synthetic restrictions apply. Prioritize supercritical CO2 extraction equipment deployment to marginalize legacy hexane-based processors in high-purity segments. For New Entrants and Emerging Players: Differentiate on tocotrienol extraction specialization targeting neuroprotection and cholesterol management research channels with pharmaceutical-grade purity credentials. White-space opportunities concentrate in rice-derived tocotrienol isolates from Indian feedstocks, where Malaysian palm IP concentration creates licensing barriers. Penetrate through direct procurement relationships with US dietary supplement brands seeking immune-support portfolio diversification beyond commodity alpha-tocopherol. For Investors and Strategic Acquirers: The market sits at a capability-scarcity phase that favors equipment-capitalized extraction specialists with patented tocotrienol isolation technologies. Long-term viability across the projection horizon rests on biotechnology platform integration enabling renewable feedstock independence from agricultural commodity cycles. Acquisition target archetype: Malaysian or Japanese research spinouts with clinical trial partnerships in cellular health applications. The signal to watch is EFSA antioxidant health claim substantiation rulings, which would recategorize tocotrienol marketing from generic wellness toward disease-prevention positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Seed Oil Processing | Captive tocopherol feedstock supply secures margin control against vegetable oil price volatility. |
| Supercritical CO2 Extraction Deployment | German and Swiss processors leverage capital intensity to displace hexane-based competitors in EU markets. |
| Tocotrienol Clinical Trial Investment | Human intervention studies satisfy EFSA evidentiary requirements for cardiovascular health claim positioning. |
| Direct Procurement Relationship Formation | US supplement brands bypass traders to secure volume commitments with Malaysian palm processors. |
| Biotechnology Platform Licensing | DSM-Firmenich's renewable feedstock fermentation enables production pathways independent of soybean cycles. |
Methodological Framework
Cross-validation between regulatory filing analysis and extraction technology patent mapping anchors the qualitative findings in documented compliance and intellectual property trajectories. Primary interviews with molecular distillation plant managers, nutraceutical procurement leads at German contract manufacturers, palm tocotrienol extraction specialists in Malaysia, and FDA regulatory affairs consultants combined with secondary validation from NMPA production licensing records, EFSA health claim substantiation databases, USITC trade flow data, and SEC 10-K disclosures from listed ingredient suppliers. Bottom-up capacity modeling and top-down demand segmentation from end-use applications triangulate volume estimates.
Sensitivity analysis around vegetable oil price volatility and regulatory reclassification scenarios tests forecast robustness across the projection horizon. The analytical framework segments by product type (natural, synthetic, tocotrienol isolates), formulation (softgels, powders, bulk oils), and end-use application (dietary supplements, cosmetics, pharmaceuticals, food fortification), with geographic regulatory clusters as an additional modeling dimension. CAGRs derive from trend extrapolation of immune-support portfolio expansion rates, clean-label cosmetic reformulation adoption curves, and tocotrienol research funding trajectories.
The analysis sits within stated boundaries; outcomes outside sustained post-pandemic preventive wellness prioritization or EFSA antioxidant claim liberalization would require recalibration. Forecasts reflect assumptions regarding phytochemical extraction expertise reconstruction timelines and synthetic-natural substitution elasticity in food applications. Recalibration cycles align with material shifts in FDA labeling enforcement, EFSA evidentiary requirement evolution, and NMPA production licensing policy changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Fortified Juices Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Fortified Yeast Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Global Vitamins Market