
 Food-Grade Mixing Tank Market | 2026-2036
Food-Grade Mixing Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Food-Grade Mixing Tank Market Foresight
The gap between premium sanitary designs and commodity-grade vessels is realigning procurement patterns across the food processing sector. Alfa Laval dominates high-purity stainless steel fabrication for dairy and pharmaceutical-adjacent food lines. SPX FLOW leverages its global service network to sustain long-term contracts with multinational beverage manufacturers. INOXPA specializes in compact modular tanks that anchor regional bakery and condiment operations in Southern Europe and Latin America.
Food-grade mixing tanks are pressure-rated vessels constructed from 304 or 316L stainless steel with surface finishes below 0.8 micrometers Ra, designed to blend, emulsify, or suspend ingredients while maintaining aseptic conditions through integrated clean-in-place spray balls and jacketed temperature control. Stainless steel constructions occupy the majority of value share due to corrosion resistance and weldability for hygienic seams, while plastic and glass-lined alternatives compete in acidic sauce applications and specialized confectionery batches where metallic ion leaching poses flavor risks. Above 5000 liter capacities lead in beverage production and dairy processing where continuous flow operations demand single-vessel throughput, though 500-1000 liter units represent the fastest-growing segment among craft distilleries and artisanal condiment startups seeking flexible batch sizes.
FDA sanitary standards, EU Machinery Directive 2006/42/EC with CE marking requirements, and 3-A SSI hygienic equipment design principles collectively shape tank specifications, welding protocols, and surface certification demands that determine market access for manufacturers and upgrade cycles for end users. The USDA National Organic Program further constrains material compatibility and cleaning agent residues for certified organic processing lines. Buyers must evaluate total cost of ownership across energy-efficient agitation systems and predictive maintenance integration rather than prioritizing capital expenditure alone.
Market Dynamics
The transition from batch to continuous processing architectures is compressing replacement cycles across dairy, beverage, and prepared food facilities. This shift demands vessels with integrated clean-in-place systems and real-time monitoring capabilities that legacy equipment cannot accommodate.
Growth Catalysts
- FDA Food Safety Modernization Act compliance deadlines:Processors in the United States face mandated hazard analysis requirements that accelerate retirement of open-top mixing equipment in favor of closed-loop sanitary designs.
- Electropolished 316L stainless steel adoption:Surface finish specifications below 0.5 micrometers Ra enable extended production runs between cleaning cycles in high-purity dairy applications.
- Modular skid-mounted tank systems:Regional condiment and sauce producers in Southern Europe deploy compact configurations that reduce installation timelines and facility footprint requirements.
Market Restraints
- 316L stainless steel price volatility:Molybdenum content fluctuations in specialty alloys create margin pressure for fabricators committed to fixed-price contracts.
- Skilled orbital welder scarcity:Certification requirements for sanitary seam welding constrain production throughput at independent tank shops across industrial clusters.
- Glass-lined vessel substitution:Acidic sauce and fruit preserve processors in select applications migrate toward ceramic-coated alternatives to eliminate metallic ion contamination risks.
Strategic Opportunities
- EU Green Deal industrial decarbonization incentives:Energy-efficient jacketed heating systems and heat recovery integration qualify for facility upgrade subsidies in Germany and France.
- Precision fermentation expansion:Alternative protein startups require aseptic mixing vessels with sterile boundary maintenance that existing biopharma suppliers cannot scale cost-effectively.
- Direct-to-processor digital sales channels:Configurator platforms enable craft distillery and artisanal food operators to specify custom agitation profiles without distributor markup.
Industry Challenges
- 3-A SSI certification timeline compression:Third-party hygienic design verification creates bottlenecks for manufacturers launching new vessel geometries.
- Legacy SCADA integration complexity:Brownfield facilities struggle to retrofit predictive maintenance sensors onto existing tank fleets without control system overhaul.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food-Grade Mixing Tank Market |
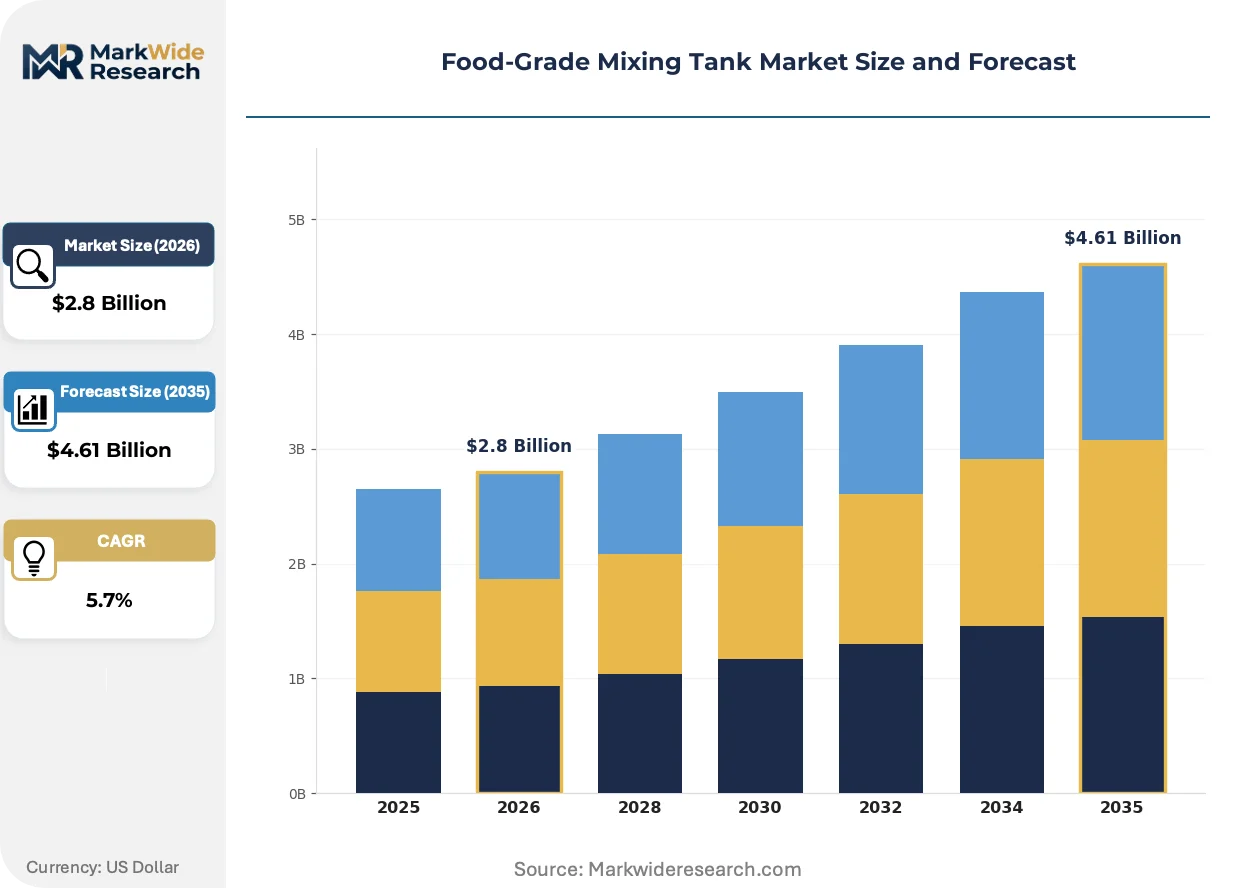
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Stainless Steel, Aluminum, Carbon Steel, Plastic, Glass-Lined Capacity: Below 500 Liters, 500-1000 Liters, 1000-5000 Liters, Above 5000 Liters Application: Dairy Processing, Beverage Production, Confectionery, Bakery Ingredients, Sauces & Dressings End User Industry: Food Processing Plants, Beverage Manufacturers, Bakeries, Condiment Producers |
| Companies Covered | SPX FLOW, Sulzer, Alfa Laval, Xylem, GEA Group, EKATO, Silverson Machines, INOXPA, Cedarstone Industry, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food-Grade Mixing Tank Market Shifts & Advancements
Digital twin simulation and advanced surface engineering are converging to redefine how processors validate mixing performance and sanitary compliance before physical installation.
Magnetically coupled agitation systems eliminate mechanical shaft seals that harbor bacterial contamination in aseptic dairy and beverage applications. Major processors in Germany and Japan specify these drives for extended run times between clean-in-place cycles. This technology is rewriting the trade-off between mixing intensity and seal integrity that has constrained vessel design for decades.
EU Machinery Directive 2006/42/EC with integrated CE marking requirements now mandates traceable documentation for all pressure-bearing welds in food-contact equipment. Fabricators must maintain digital weld logs with radiographic inspection records for market access. Small and mid-sized tank shops in Italy and Spain invest in automated welding cells to meet documentation burdens that manual processes cannot sustain.
Specification authority is migrating from procurement departments to plant engineering and quality assurance functions with direct accountability for FDA and EFSA compliance outcomes. Engineering-led buying committees in United States dairy cooperatives now disqualify vendors lacking validated clean-in-place spray ball coverage documentation. This shift concentrates contract awards among fabrication specialists with in-house validation capabilities rather than commodity distributors.
Food-Grade Mixing Tank Market Segmentation
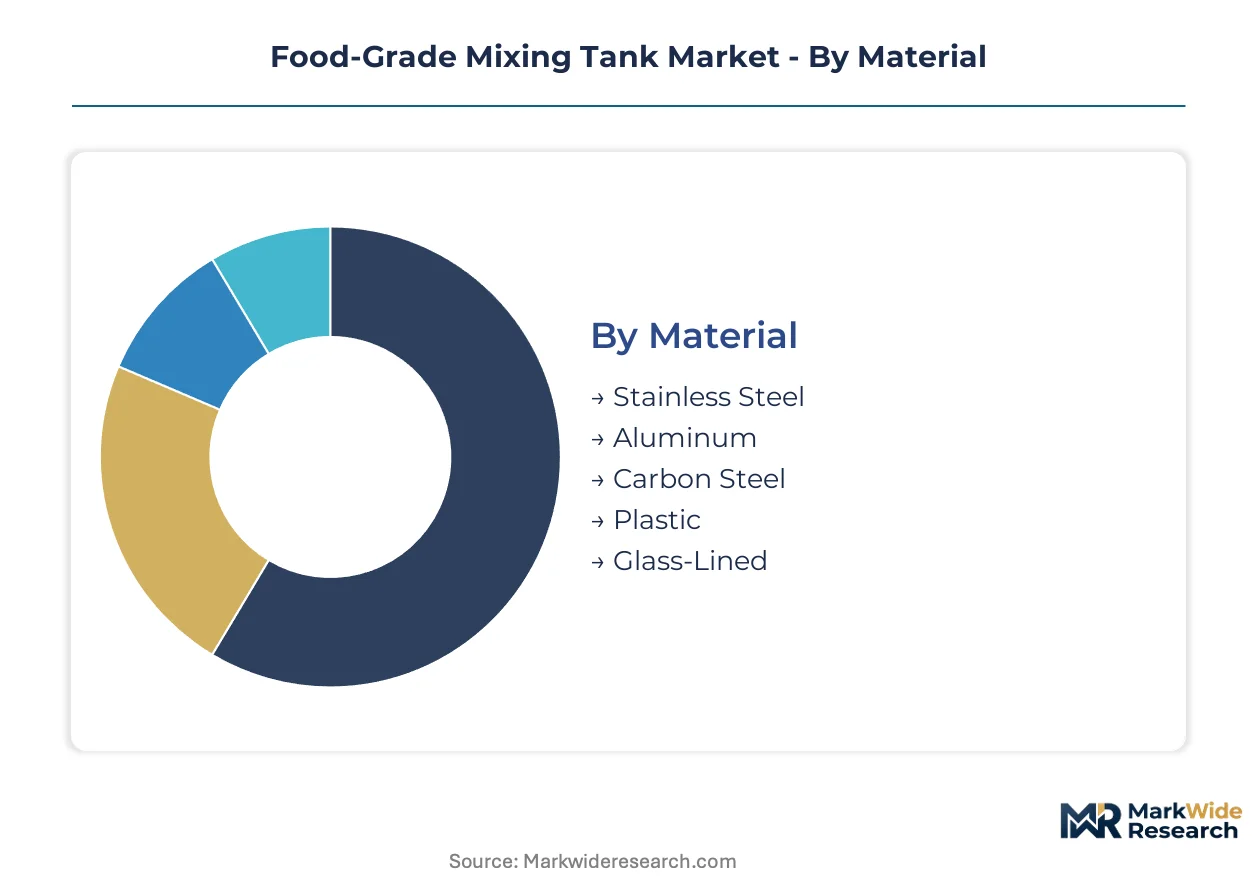
Material selection determines regulatory compliance pathways and total cost of ownership across food-grade mixing tank procurement. Capacity specifications align with batch versus continuous processing architectures. Application and end-user segmentation reveals divergent technical requirements between commodity-scale processors and specialty food manufacturers.
Material:
Surface finish specifications and corrosion resistance define material selection criteria for FDA and EU hygiene compliance.
- Stainless Steel:304 and 316L grades with surface finishes below 0.8 micrometers Ra dominate dairy and beverage applications. Dairy processing facilities across Germany, Japan, and the United States specify electropolished 316L for extended production runs between clean-in-place cycles under FDA Food Safety Modernization Act mandates.
- Glass-Lined:Ceramic-coated vessels eliminate metallic ion leaching risks in acidic sauce and fruit preserve processing. Condiment producers in Southern Europe migrate toward these alternatives to address flavor contamination concerns that stainless steel cannot resolve.
- Plastic:Polymer constructions compete in specialized confectionery batches and low-temperature applications where thermal conductivity requirements are minimal.
- Aluminum:Lightweight alloys serve mobile and temporary processing installations where vessel portability outweighs surface finish precision.
- Carbon Steel:Epoxy-coated variants occupy non-contact structural and utility tank applications with limited food-grade exposure.
Stainless steel leads on scale; glass-lined leads on momentum.
Capacity:
Volume thresholds separate continuous flow operations from flexible batch production economics.
- Above 5000 Liters:Single-vessel throughput configurations anchor beverage production and dairy processing facilities running continuous operations. Major processors deploy these capacities to minimize tank farm footprints and reduce cleaning cycle frequency.
- 500-1000 Liters:Mid-scale units enable craft distilleries and artisanal condiment startups to adjust batch sizes without capital-intensive retooling. This bracket gains share fastest among regional specialty producers seeking operational flexibility.
- Below 500 Liters:Compact vessels support pilot-scale product development and small-batch organic certification lines.
- 1000-5000 Liters:Intermediate capacities bridge commercial-scale throughput with modular facility expansion pathways.
Above 5000 liter units dominate capital deployment; 500-1000 liter configurations expand most quickly.
Application:
Process viscosity and aseptic requirements drive specification divergence across food categories.
- Dairy Processing:Aseptic mixing with integrated clean-in-place systems and jacketed temperature control dominates procurement specifications. EU hygiene regulations and FDA Food Safety Modernization Act compliance deadlines accelerate replacement of open-top legacy equipment.
- Beverage Production:Carbonated and still beverage lines demand pressure-rated vessels with precise agitation control to maintain dissolved gas stability and suspension uniformity.
- Sauces & Dressings:Acidic and high-viscosity formulations require specialized surface finishes and scraping agitation systems to prevent burn-on and ensure emulsion stability.
- Confectionery:Temperature-sensitive batches with crystallization control needs specify narrow-band jacketed heating systems.
- Bakery Ingredients:Yeast and starter culture propagation demands sanitary designs with minimal deadleg configurations.
Dairy processing commands the largest installed base; sauces and dressings show the steepest specification upgrade trajectory.
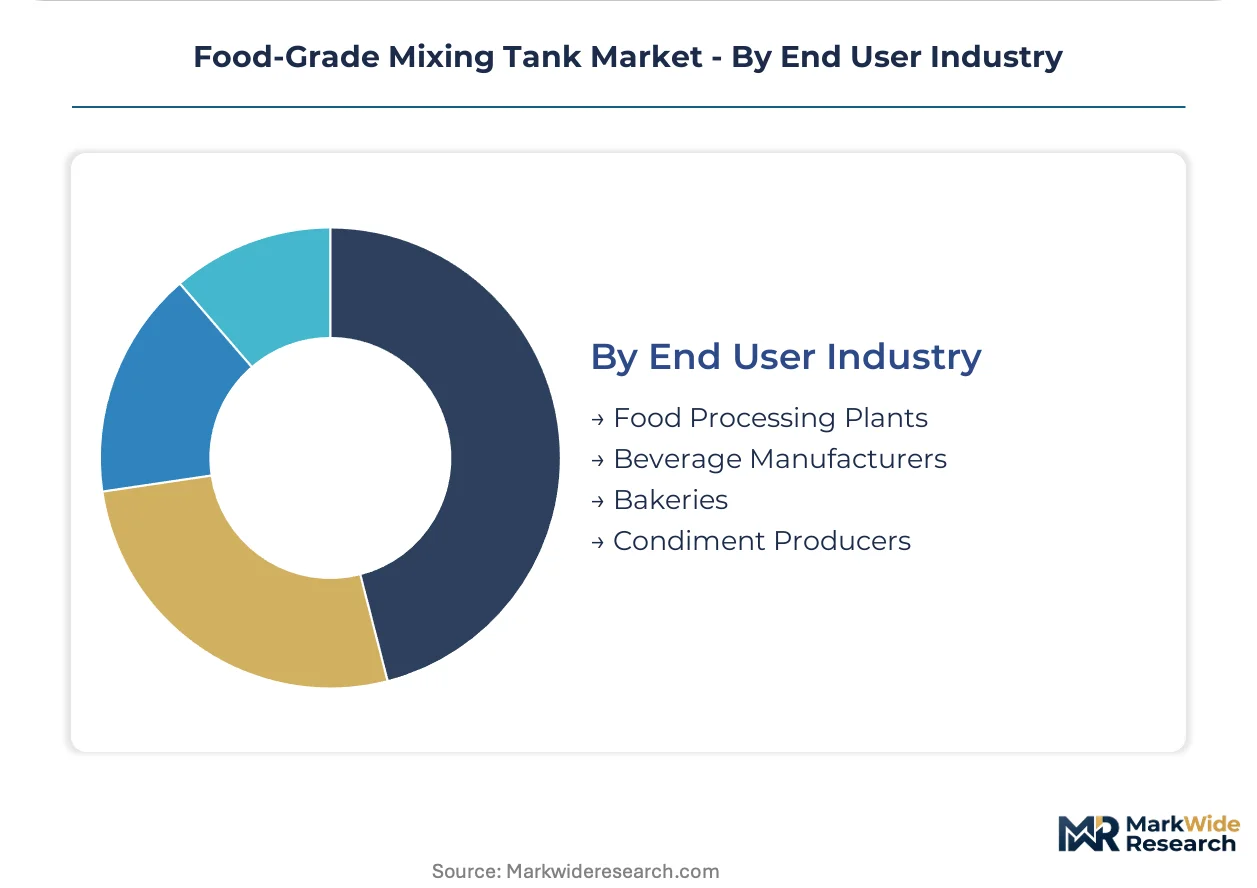
End User Industry:
Facility scale and certification requirements segment buyer behavior across the food production value chain.
- Food Processing Plants:Integrated multi-line operations specify standardized vessel platforms to reduce spare parts inventory and maintenance training burdens.
- Beverage Manufacturers:Carbonated and functional drink producers prioritize pressure vessel certification and automated clean-in-place integration for line efficiency.
- Condiment Producers:Regional sauce and specialty dressing manufacturers favor modular skid-mounted systems to compress installation timelines.
- Bakeries:Ingredient preparation and starter culture operations concentrate demand in compact 500-1000 liter configurations.
Food processing plants lead on procurement volume; condiment producers lead on adoption velocity for modular configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and the United States diverge in their upgrade urgency, with German dairy cooperatives accelerating fleet replacement under EU Machinery Directive timelines while U.S. processors face staggered FDA Food Safety Modernization Act compliance deadlines through 2026.
United States
Dairy cooperatives in Wisconsin and California are retiring open-top batch equipment ahead of FDA Food Safety Modernization Act hazard analysis mandates. The USDA National Organic Program constrains material compatibility for certified processors in the Pacific Northwest. Electropolished 316L stainless steel installations concentrate in the Upper Midwest dairy belt.
Germany
Bavarian and North Rhine-Westphalia processing facilities lead EU adoption of magnetically coupled agitation systems for extended clean-in-place intervals. EU Green Deal industrial decarbonization subsidies accelerate heat recovery integration in jacketed heating retrofits. The Stuttgart industrial cluster hosts automated welding cell investments for CE marking documentation compliance.
Japan
Kanto region beverage manufacturers specify pressure-rated vessels with real-time monitoring capabilities for continuous flow operations. METI energy efficiency standards drive procurement of advanced temperature control systems. Yokohama-based fabricators dominate domestic supply for aseptic dairy applications.
Italy
Emilia-Romagna condiment producers deploy modular skid-mounted tanks to compress installation timelines for regional sauce lines. CE marking requirements under EU Machinery Directive 2006/42/EC mandate traceable weld documentation that manual processes cannot sustain. Bologna-area tank shops invest in automated orbital welding for sanitary seam certification.
Brazil
São Paulo state dairy processors import European-designed closed-loop architectures to replace legacy batch infrastructure. ANVISA sanitary regulations align with international 3-A SSI principles for equipment design verification. The Campinas industrial corridor concentrates demand for above-5000-liter continuous throughput configurations.
Food-Grade Mixing Tank Market Competitive Landscape
Top-tier vendors anchor premium sanitary fabrication, while regional specialists and commodity fabricators occupy mid-market and project-specific tiers. The market exhibits moderate concentration with three to five dominant players controlling high-purity stainless steel segments, while independent tank shops fragment across geography-bound condiment and bakery applications. Strategic archetypes include integrated process technology conglomerates, specialized hygienic equipment fabricators, and modular skid-system assemblers. Competitive moves concentrate on automated welding cell deployment for certification throughput and direct-to-processor digital configurator platforms that bypass distributor networks.
Within the integrated technology tier, Alfa Laval and SPX FLOW represent contrasting geographic and service-model archetypes, with the former exemplifying Scandinavian precision fabrication and the latter demonstrating sustained contract maintenance networks. EKATO anchors the agitation-system specialist position, occupying a role where mechanical design expertise determines vessel performance specifications. Sulzer sits within the industrial pump-and-mix technology convergence space, exemplifying how process equipment diversification creates cross-selling pathways into food-grade tank procurement.
| Leading Market Players |
|---|
| SPX FLOW |
| Sulzer |
| Alfa Laval |
| Xylem |
| GEA Group |
| EKATO |
| Silverson Machines |
| INOXPA |
| Cedarstone Industry |
| Others |
Supply & Pricing Matrix
Dairy cooperative procurement concentration in the Upper Midwest and Bavaria anchors contract-based long-term offtake agreements for electropolished 316L vessels. These buyers leverage multi-unit fleet purchases to compress per-unit pricing across extended service intervals.
Pricing Analysis
Equipment-plus-service bundling versus unbundled vessel-only transactions splits procurement economics across buyer tiers. Three-tier pricing structure across premium, standard, and economy levels reflects 3-A SSI certification grade and surface finish precision. Cost compression in commodity-grade stainless steel segments is intensifying because of molybdenum alloy price volatility. Regional condiment producers exhibit highest price sensitivity due to limited capital reserves, while pharmaceutical-adjacent food processors prioritize certification over unit cost.
Supply Chain Analysis
CE marking documentation and 3-A SSI hygienic design verification gate market access for fabricators lacking certification capabilities. Manufacturing concentrates in Germany, Italy, and Japan, with specialized welding cells clustered around Stuttgart and Bologna industrial corridors. Supply draws from 316L stainless steel feedstock, precision agitation drives, and automated orbital welding equipment. Single-source vulnerability in skilled orbital welder certification constrains production throughput. Distribution runs through direct-to-processor digital configurators and established distributor networks serving legacy accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FDA Food Safety Modernization Act compliance deadlines and EU Machinery Directive timelines create non-negotiable replacement demand. Processors face mandated equipment upgrades that override discretionary capital deferrals.
For Market Incumbents: Hedge against glass-lined vessel substitution in acidic sauce applications by securing ceramic-coating partnerships or acquiring specialized surface engineering capabilities. Expand automated welding cell capacity in Germany and Italy to compress 3-A SSI certification timelines for new vessel geometries. Backward integration into electropolishing services captures margin currently flowing to third-party finishers. For New Entrants and Emerging Players: Capture precision fermentation equipment demand from alternative protein startups requiring aseptic mixing vessels with sterile boundary maintenance that biopharma suppliers cannot scale cost-effectively. Target modular skid-mounted configurations for Southern European condiment producers seeking compressed installation timelines. Deploy direct-to-processor digital configurator platforms to bypass established distributor markups. For Investors and Strategic Acquirers: Process technology conglomerates with existing food-grade fabrication divisions are the most active acquirers in this space, seeking to fill portfolio gaps in aseptic dairy vessel capabilities. Five-to-ten-year viability hinges on regulatory compliance infrastructure rather than commodity manufacturing scale. Acquisition target archetype: mid-sized Italian or Spanish tank shops with automated welding investments but limited validation documentation capabilities. Watch for FDA enforcement action intensity as inflection indicator for U.S. replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Welding Cell Deployment | CE marking documentation requirements under EU Machinery Directive 2006/42/EC mandate traceable weld logs that manual processes cannot sustain. |
| Direct-to-Processor Digital Configurator Launch | Craft distillery and artisanal food operators specify custom agitation profiles without distributor markup, compressing sales cycles. |
| Precision Fermentation Vessel Development | Alternative protein startups require aseptic mixing with sterile boundary maintenance that existing biopharma suppliers cannot scale cost-effectively. |
| Heat Recovery Integration Retrofit | EU Green Deal industrial decarbonization subsidies in Germany and France qualify energy-efficient jacketed heating systems for facility upgrade grants. |
| Glass-Lined Surface Engineering Partnership | Acidic sauce and fruit preserve processors migrate toward ceramic-coated alternatives to eliminate metallic ion contamination risks. |
Research Methodology
Multiple input streams — primary interviews with plant engineers and quality assurance directors, regulatory filings with FDA and EU notified bodies, and trade data on stainless steel vessel imports — were reconciled through bottom-up and top-down triangulation. Secondary validation drew from 3-A SSI equipment certification databases, EU Machinery Directive conformity assessments, and SEC filings of publicly traded process technology conglomerates. Dairy cooperative procurement managers, aftermarket service heads at major fabricators, and condiment producer facility directors provided operational perspective on replacement cycle timing.
Data-stream reconciliation across material grade, capacity tier, application vertical, and regional regulatory cluster enabled segmentation-specific modeling. Volume and value outputs were cross-checked against installation records for clean-in-place system integrations and jacketed heating retrofits. CAGRs were derived from replacement cycle compression analysis and regulatory deadline mapping. Forecast inputs included FDA compliance timeline enforcement patterns and EU Green Deal subsidy allocation trajectories.
Molybdenum alloy price volatility, orbital welder certification bottlenecks, and glass-lined substitution acceleration are the dominant revision risks to installed base projections. Forecasts reflect documented assumptions on regulatory enforcement intensity and subsidy program continuity. A model refresh is warranted upon material change in FDA inspection priority elevation or EU Machinery Directive amendment timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Deep Fryer Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Food Automation Market
Food Processing Equipment
High-Pressure Processing Equipment Market
Food Processing Equipment
Automatic Canning Machine Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Walk-In Refrigerators & Freezers Market
Food Processing Equipment
Commercial Beverage Blender Market
Food Processing Equipment
Ice Flaking Machine Market
Food Processing Equipment
Pasty Products Filling Machine Market
Food Processing Equipment
Oceania Commercial Ice Machine Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Optical Sorter Market