
 South America Food Fortifying Agents Market | 2026-2036
South America Food Fortifying Agents Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Fortifying Agents Market Analytics
Infant nutrition formulation is decoupling from general food processing as Brazilian and Argentine manufacturers demand higher-grade vitamin premixes. BASF SE anchors the vitamin K2 and D3 supply position through its regional compounding facilities. Cargill Inc. leverages its grain processing footprint to integrate mineral fortification into milled wheat streams. Chr. Hansen Holding A/S specializes in probiotic strains tailored to ambient-stability dairy applications across the Mercosur trade zone.
Food fortifying agents are concentrated bioactive compounds—vitamins, minerals, amino acids, and live microbial cultures—typically dosed at parts-per-million to parts-per-thousand levels to restore processing losses or elevate nutritional claims in finished goods. Production relies on fermentation-derived, chemically synthesized, or naturally extracted inputs, followed by spray-drying, microencapsulation, or standardization to achieve batch-to-batch potency uniformity. The vitamins segment dominates value contribution due to heat-labile stability challenges and complex supply chains for riboflavin and ascorbic acid derivatives. Probiotics represents the fastest-expanding category as Argentine yogurt processors and Brazilian fermented beverage startups adopt strain-specific health positioning. Margin pools concentrate in customized premix services where Koninklijke DSM NV and Corbion NV compete on formulation precision and regulatory dossier support.
ANVISA governs food additive approvals and maximum permitted levels for fortificants in Brazil, while Argentina's national food code enforces mandatory wheat flour iron and folic acid standards through its federal health secretariat. Compliance complexity rises as Mercosur member states pursue partial regulatory harmonization without unified maximum limits. Stakeholders must monitor pending technical regulations for biofortification claims and novel probiotic strain authorizations across national health agencies.
Market Dynamics
ANVISA's updated fortification mandates for wheat flour and vegetable oils are compressing compliance timelines while forcing premix suppliers to revalidate dossiers, tightening the link between regulatory precision and commercial viability across Brazilian food manufacturing corridors.
Growth Catalysts
- Mandatory wheat flour fortification:Brazil's federal requirements for iron and folic acid addition create baseline demand stability for mineral premixes regardless of economic cycles.
- Infant formula micronutrient escalation:Argentine and Brazilian manufacturers are sourcing higher-grade vitamin K2 and D3 premixes to meet export-grade nutritional density specifications.
- Probiotic strain authorization pipeline:Pending ANVISA technical regulations for novel live culture claims are positioning fermented dairy processors to expand functional positioning.
Market Restraints
- Riboflavin supply concentration:Fermentation-derived vitamin B2 production clusters in Chinese bioreactor facilities, exposing South American formulators to shipping cost volatility and customs clearance delays.
- Mercosur regulatory fragmentation:Partial harmonization efforts between Brazil, Argentina, Paraguay, and Uruguay maintain divergent maximum permitted levels for identical fortificants, forcing duplicate dossier submissions.
- Heat-labile vitamin degradation:Ascorbic acid and thiamine losses during spray-drying of infant formula impose overage requirements that compress premix margins.
Strategic Opportunities
- Biofortification claim authorization:Pending ANVISA frameworks for intrinsic nutrient enhancement in staple crops could open premix partnerships with seed and grain biotechnology providers.
- Amazon basin dairy expansion:Fermented beverage startups in Pará and Amazonas states lack access to strain-specific probiotic suppliers, creating white space for ambient-stability culture providers.
- Direct-to-processor premix distribution:Bypassing traditional ingredient distributors through regional compounding facilities in Minas Gerais reduces lead times for mid-size wheat millers.
Industry Challenges
- Microencapsulation technician scarcity:Brazilian universities produce insufficient formulation chemists trained in lipid-shell encapsulation for heat-sensitive vitamins, forcing reliance on imported technical services.
- Batch-to-batch potency verification:HPLC and microbiological assay capacity at third-party laboratories in São Paulo and Buenos Aires creates bottlenecks for premix release timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Fortifying Agents Market |
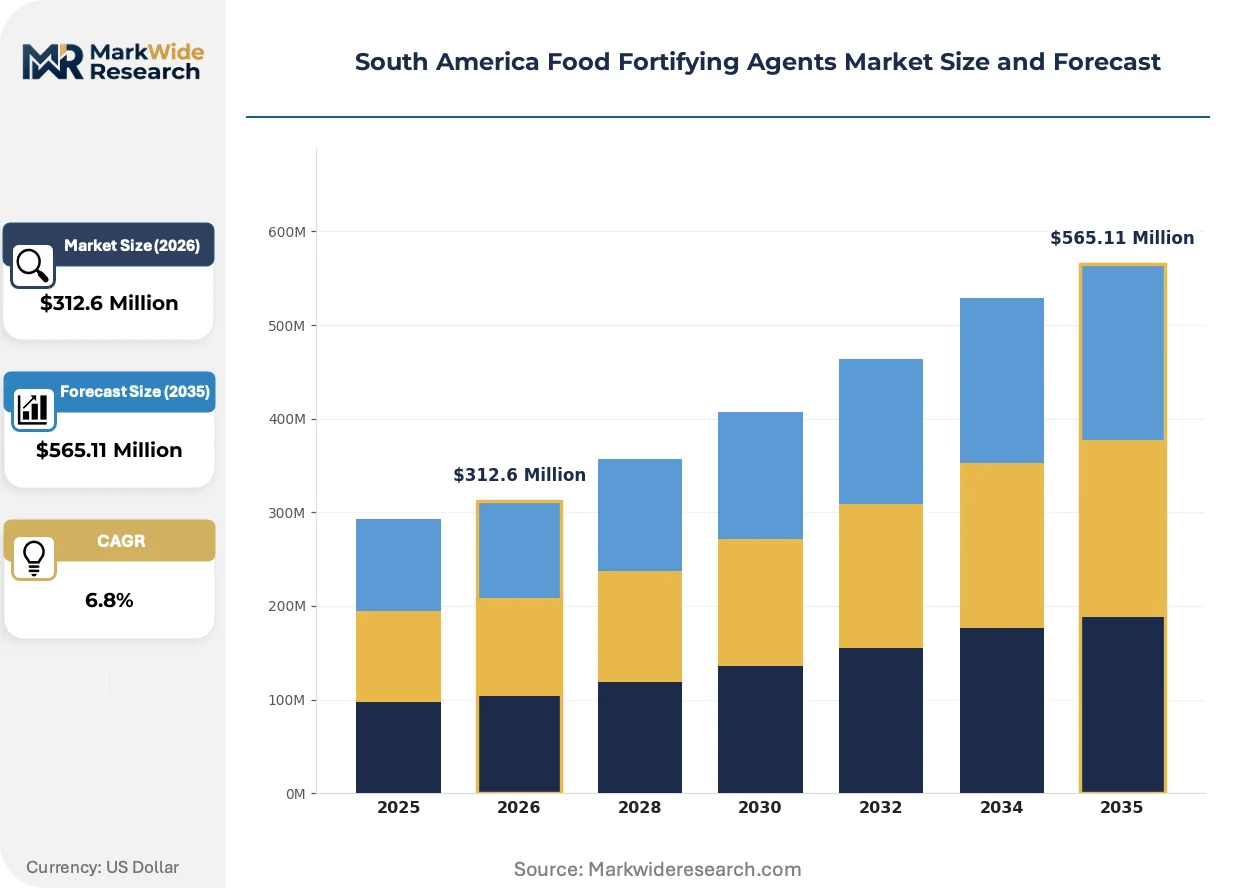
| Market Size in 2026 | $312.6 Million |
| Market Size in 2035 | $565.11 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Amino Acids, Probiotics Application: Beverages, Dairy Products, Bakery, Snacks End User: Food Manufacturers, Restaurants, Households, Nutritional Companies Distribution Channel: Online Stores, Supermarkets, Specialty Shops, Direct Sales |
| Companies Covered | BASF SE, Cargill Inc., DuPont de Nemours Inc., Archer Daniels Midland Company, Ingredion Inc., AOM SA, Corbion NV, Koninklijke DSM NV, Chr. Hansen Holding A/S, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Fortifying Agents Market Evolving Landscape
Formulation science and regulatory dossier architecture are converging to reshape competitive positioning in South American food fortification, with stability engineering and compliance automation emerging as distinct capability axes.
Microencapsulation technology using lipid-shell matrices is absorbing thermal stress during high-temperature extrusion and spray-drying processes. Brazilian infant formula processors in São Paulo state are adopting these systems at accelerated procurement cycles. The technology is absorbing margin pressure from vitamin overage requirements by reducing degradation losses from fifteen percent to under five percent.
ANVISA's pending technical regulation for novel probiotic strain authorizations is compressing approval timelines from thirty-six to eighteen months for dossiers with complete genomic characterization. Argentine yogurt manufacturers are pre-submitting strain-specific safety packages to capture first-mover positioning. Fermented dairy applications across the Mercosur trade zone face the steepest compliance investment requirements.
Ingredient procurement from regional compounding facilities is displacing traditional distributor relationships among mid-size wheat millers. São Paulo and Minas Gerais industrial corridors are consolidating purchasing through direct premix service contracts. Argentine pasta manufacturers in Córdoba province are replicating this model to secure folic acid premix consistency.
South America Food Fortifying Agents Market Segmentation
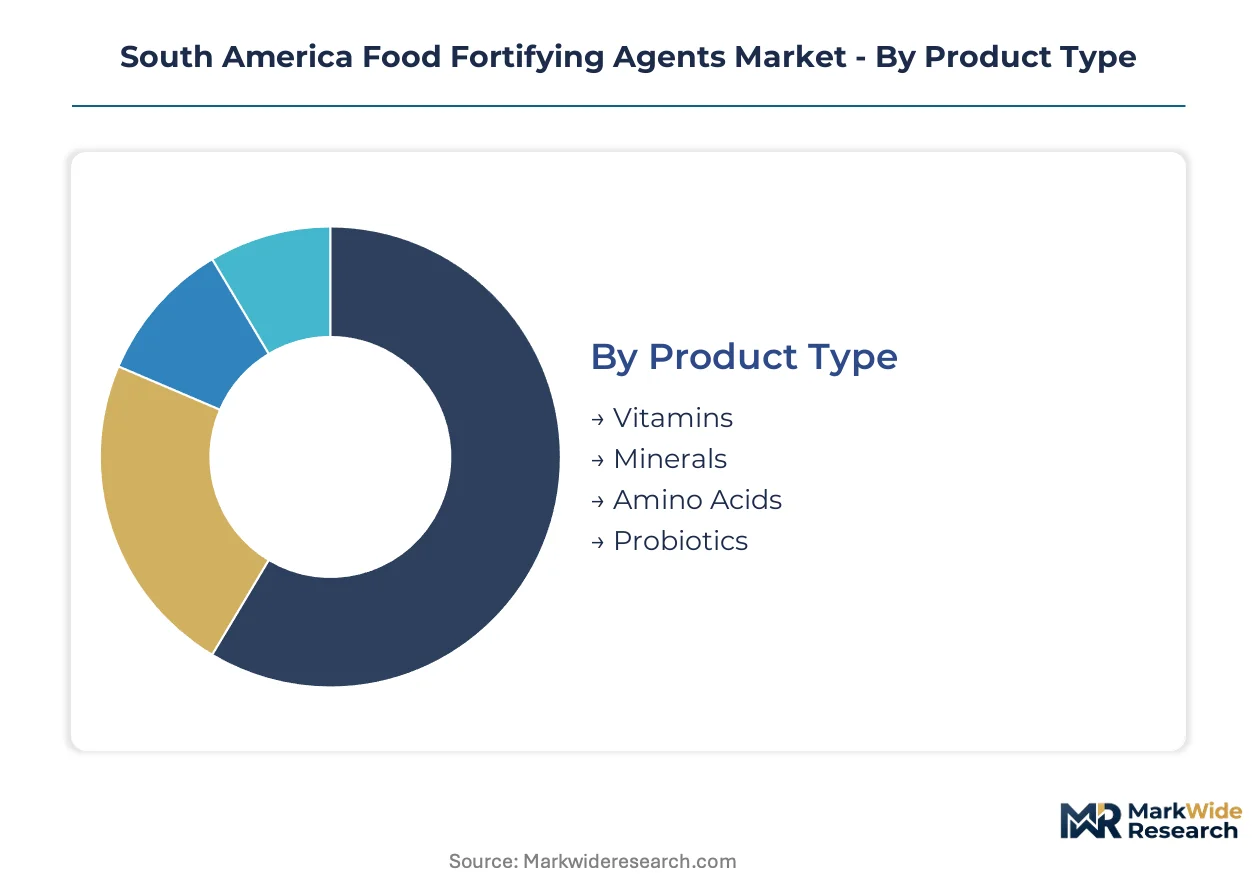
Fortifying agent procurement patterns diverge sharply across product categories and customer tiers in South America. Capital allocation, regulatory exposure, and technical service requirements vary by segment in ways that reshape supplier priorities.
Product Type:
Vitamins and probiotics demand the heaviest upfront investment in fermentation infrastructure, stability testing, and regulatory dossier preparation.
- Vitamins:Heat-labile compounds including riboflavin and ascorbic acid derivatives require spray-drying and microencapsulation to survive processing losses. Brazilian infant formula manufacturers in São Paulo state absorb premium pricing for validated potency uniformity.
- Probiotics:Live microbial cultures demand cold-chain integrity and strain-specific genomic characterization for ANVISA authorization. Argentine yogurt processors are pre-submitting safety packages to capture shortened approval timelines.
- Minerals:Iron and folic acid premixes anchor mandatory wheat flour fortification programs across Brazil and Argentina.
- Amino Acids:Lysine and methionine supplementation serves processed protein applications with lower regulatory complexity than live cultures.
Most installed capacity flows through Vitamins. Expansion is steepest in Probiotics.
Application:
Beverage and dairy applications concentrate technical service resources due to pH stability challenges and live culture viability requirements.
- Dairy Products:Fermented milk and yogurt applications in the Mercosur trade zone strain probiotic suppliers for ambient-stability strain development. Brazilian processors in Minas Gerais prioritize direct premix contracts over distributor relationships.
- Beverages:Fortified juices and fermented drinks in Brazil's Amazon basin states lack local probiotic suppliers, forcing reliance on São Paulo-based technical service teams.
- Bakery:Wheat flour iron and folic acid mandates create baseline demand stability regardless of economic cycles.
- Snacks:Extruded and baked applications impose thermal stress that microencapsulation technology must absorb.
Revenue concentration sits with Dairy Products. Volume growth is climbing the fastest in Beverages.
End User:
Food manufacturers command supplier attention through volume scale and formulation complexity, while nutritional companies drive premium specification development.
- Food Manufacturers:Mid-size wheat millers in São Paulo and Córdoba provinces are consolidating procurement through direct premix service contracts. These buyers validate batch-to-batch potency through third-party HPLC capacity.
- Nutritional Companies:Infant formula producers in Brazil and Argentina demand export-grade vitamin K2 and D3 premixes with documented stability profiles.
- Restaurants:Foodservice fortification remains limited to iodized salt and standardized oil blends.
- Households:Direct consumer purchases concentrate in single-nutrient supplements rather than food-grade premixes.
Margin pools concentrate with Nutritional Companies. Procurement volume concentrates with Food Manufacturers.
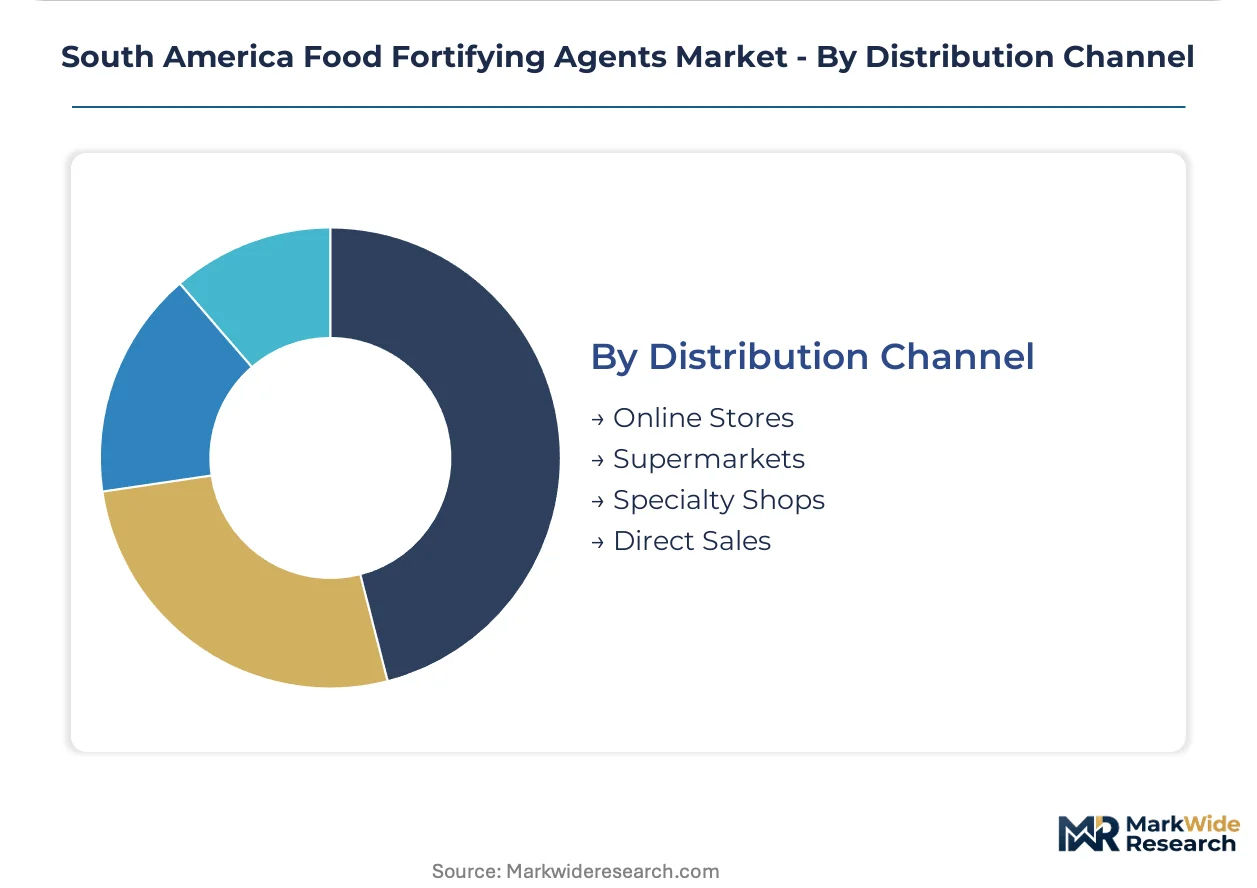
Distribution Channel:
Direct sales and online platforms are displacing traditional ingredient distributors among technically sophisticated buyers.
- Direct Sales:Regional compounding facilities in Minas Gerais bypass distributors to serve mid-size wheat millers with compressed lead times. Argentine pasta manufacturers replicate this model for folic acid consistency.
- Online Stores:Digital procurement platforms gain traction among smaller processors seeking transparent pricing on standardized vitamin premixes.
- Supermarkets:Retail channels dominate finished fortified foods rather than ingredient-grade fortificants.
- Specialty Shops:Niche suppliers serve artisanal bakeries and fermented beverage startups with small-batch probiotic cultures.
Relationship value concentrates in Direct Sales. Digital adoption is gaining share fastest in Online Stores.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing premix procurement across South American manufacturing corridors as compliance cost differentials widen between Mercosur members. Brazilian ANVISA mandates compress approval timelines while Argentine federal standards maintain divergent maximum limits, creating procurement migration patterns toward jurisdictions with faster dossier validation.
Brazil
ANVISA's updated fortification mandates for wheat flour and vegetable oils are forcing premix suppliers to revalidate technical dossiers on compressed timelines. The Southeast industrial corridor spanning São Paulo and Minas Gerais states concentrates infant formula manufacturing and direct-to-processor premix distribution. São Paulo-based processors absorb premium pricing for validated vitamin K2 and D3 potency uniformity.
Argentina
The national food code enforces mandatory wheat flour iron and folic acid standards through the federal health secretariat, creating baseline demand stability for mineral premixes. Argentine yogurt manufacturers are pre-submitting strain-specific probiotic safety packages to capture shortened ANVISA-aligned approval timelines. Córdoba province pasta manufacturers replicate Brazilian direct premix contracting models to secure folic acid consistency.
Chile
Processed food export requirements to Mercosur and Pacific Alliance markets drive demand for dual-compliant vitamin premixes with documented stability profiles. The country's national health regulator maintains voluntary fortification frameworks that contrast with Brazilian mandatory standards, attracting formulation R&D investment. Santiago metropolitan area food manufacturers serve as testing grounds for novel microencapsulation technologies prior to Brazilian scale-up.
Colombia
Bogotá-based nutritional companies source export-grade vitamin premixes through Brazilian compounding facility partnerships to bypass distributor markups. The national food and drug surveillance institute monitors maximum permitted levels that partially reference ANVISA technical standards. Antioquia department dairy processors are evaluating ambient-stability probiotic strains for fermented beverage applications.
Peru
Lima industrial corridor wheat millers face compliance gaps between national fortification guidelines and Brazilian technical regulations for cross-border premix procurement. The country's general health directorate maintains evolving additive approval frameworks that lag ANVISA authorization pipelines. Coastal dairy processors rely on Santiago and São Paulo technical service teams for probiotic strain viability verification.
South America Food Fortifying Agents Market Competitive Landscape
Capacity expansion dominates the current landscape as regional compounding facilities displace traditional distributor relationships across Brazilian and Argentine manufacturing corridors. Market structure consolidates around three strategic tiers: multinational chemical conglomerates with integrated vitamin fermentation assets, specialized premix service providers competing on formulation precision, and regional distributors losing share to direct sales models. Strategic archetypes include stability-engineering specialists, regulatory dossier architects, and supply-chain integrators. M&A activity and geographic expansion through regional compounding facilities represent the dominant competitive moves.
Among European-based chemical conglomerates, BASF SE and Koninklijke DSM NV occupy anchor positions exemplifying integrated vitamin production and customized premix service capabilities respectively. Chr. Hansen Holding A/S represents the specialized live culture tier with strain-specific genomic characterization expertise. These three companies illustrate the competitive spectrum from fermentation-derived bulk vitamin supply through probiotic authorization dossier support.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Inc. |
| DuPont de Nemours Inc. |
| Archer Daniels Midland Company |
| Ingredion Inc. |
| AOM SA |
| Corbion NV |
| Koninklijke DSM NV |
| Chr. Hansen Holding A/S |
| Others |
Value Network & Pricing Analysis
Microencapsulation technology adoption across São Paulo infant formula processors is compressing cost structures while concentrating supply relationships among premix providers with validated lipid-shell formulation capabilities. Brazilian wheat millers in Minas Gerais now demand direct-to-processor contracts that eliminate distributor markups, reshaping margin allocation across the value chain.
Pricing Analysis
Distributor margin compression is accelerating as regional compounding facilities in Brazil's Southeast industrial corridor bypass traditional ingredient channels. Pricing stratifies across export-grade vitamin K2 and D3 premixes, standard mineral fortification blends, and economy-tier amino acid supplements, with differentiation driven by ANVISA dossier completeness and batch-to-batch potency verification. Cost compression in standard mineral premixes is intensifying because Argentine pasta manufacturers replicate Brazilian direct-contracting models. Mid-size wheat millers exhibit highest price sensitivity, while infant formula manufacturers absorb premium pricing for genomic-characterized probiotic strains.
Supply Chain Analysis
Dual-sourcing mandates from Brazilian infant formula manufacturers are forcing premix suppliers to qualify secondary fermentation-derived vitamin providers beyond their primary Chinese bioreactor relationships. Supply concentration centers on China for riboflavin fermentation, Brazil for regional compounding and microencapsulation services, and Argentina for strain-specific probiotic culture development. Raw material dependencies include fermentation feedstocks for B-vitamin production, lipid matrices for heat-sensitive encapsulation, and live culture cryoprotectants. Single-source vulnerability in Chinese vitamin B2 production exposes South American formulators to shipping cost volatility. Distribution runs through direct premix service contracts displacing traditional ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a late-cycle quality story as Argentine and Brazilian infant formula manufacturers escalate procurement toward export-grade micronutrient density specifications with documented stability profiles.
For Market Incumbents: Acquire regional compounding facility assets in Minas Gerais and Córdoba provinces to defend against direct-to-processor distribution models eroding distributor relationships. Backward integration into microencapsulation technician training programs addresses capability scarcity threatening batch release timelines. Capacity addition in Amazon basin states captures fermented beverage startup demand lacking local probiotic suppliers. For New Entrants and Emerging Players: Enter via ambient-stability probiotic strain development for Pará and Amazonas dairy processors underserved by São Paulo-based technical service teams. White space concentrates in biofortification claim partnerships with seed biotechnology providers pending ANVISA framework authorization. Target mid-size wheat millers seeking transparent digital procurement platforms for standardized mineral premixes. For Investors and Strategic Acquirers: Valuations sit cheapest among specialized premix service providers competing on formulation precision and regulatory dossier support rather than integrated fermentation assets. Long-term viability favors companies with ANVISA pre-submission capabilities and genomic characterization infrastructure. Acquisition target archetype includes regional distributors with captive relationships to Southeast Brazilian industrial corridors. The signal to watch is ANVISA's final technical regulation for novel probiotic strain authorizations compressing approval timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Compounding Facility Expansion | Direct premix contracts with Minas Gerais wheat millers eliminate distributor margin layers and compress lead times. |
| Microencapsulation Technology Licensing | Lipid-shell matrix systems reduce vitamin overage requirements from fifteen percent to under five percent for São Paulo processors. |
| Probiotic Strain Pre-Submission Program | Complete genomic characterization packages position Argentine yogurt manufacturers for shortened ANVISA approval timelines. |
| Backward Integration into Fermentation | In-house riboflavin production mitigates Chinese supply concentration and customs clearance delay exposure. |
| Digital Procurement Platform Launch | Transparent pricing interfaces attract smaller Brazilian processors seeking standardized vitamin premix sourcing efficiency. |
Research Methodology
Bottom-up infant formula and wheat milling demand modeling reconciled against top-down vitamin and probiotic supply tracking forms the analytical core of this study. Primary interviews with premix formulation chemists, ANVISA regulatory consultants, procurement directors at Brazilian food manufacturers, Argentine yogurt processing executives, and third-party laboratory assay technicians combined with secondary validation from ANVISA technical regulations, Argentine national food code filings, Mercosur harmonization documents, customs trade data, and SEC filings of listed ingredient suppliers. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production capacity.
Historical trendline analysis of premix procurement volumes across dairy, bakery, and infant nutrition applications informed projection frameworks over the analysis window. Segmentation dimensions modeled include product type, application category, end-user tier, and distribution channel structure, with additional granularity on regulatory compliance tier. CAGRs derive from curve-fitting approaches applied to validated consumption data, incorporating ANVISA mandate implementation schedules and probiotic strain authorization pipeline status as industry-specific forecast inputs.
Inputs from ANVISA pre-submission filings and Argentine federal health secretariat consultations were available through the study window; gaps in pending biofortification claim frameworks introduce uncertainty bands around long-term premix partnership revenue potential. Deviation in ANVISA's final technical regulation timeline would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Vitamin B12 Drops Market
Vitamin Fortified
Natural Vitamins Market