
 United States Digestive Supplement Market | 2026-2036
United States Digestive Supplement Market Size, Share, and Industry Trends Forecast 2026-2036
United States Digestive Supplement Market Analytics
Single-serve stick packs and subscription bundles is restructuring how consumers purchase digestive supplements, shifting volume from bulk bottles to portable formats. Abbott Laboratories anchors its position through pharmacy and healthcare channel control, while NOW Foods Inc. competes via specialized manufacturing scale in probiotic strains. Pfizer Inc. leverages its pharmaceutical distribution infrastructure to extend reach into clinician-recommended supplement protocols.
Digestive supplements encompass orally administered products containing live microbial cultures, non-digestible fibers, or enzymatic proteins formulated to support gastrointestinal function, nutrient absorption, and microbiome balance. Manufacturing requires controlled-temperature encapsulation and moisture-barrier packaging to maintain colony-forming unit viability through shelf life. Probiotics and prebiotics together command the dominant value share, with digestive enzymes representing the fastest-expanding margin pool as consumers seek targeted solutions for lactose intolerance and protein malabsorption. Capsule and tablet formats still occupy the largest volume position, though powder formats are gaining traction among athlete and senior segments seeking dose flexibility.
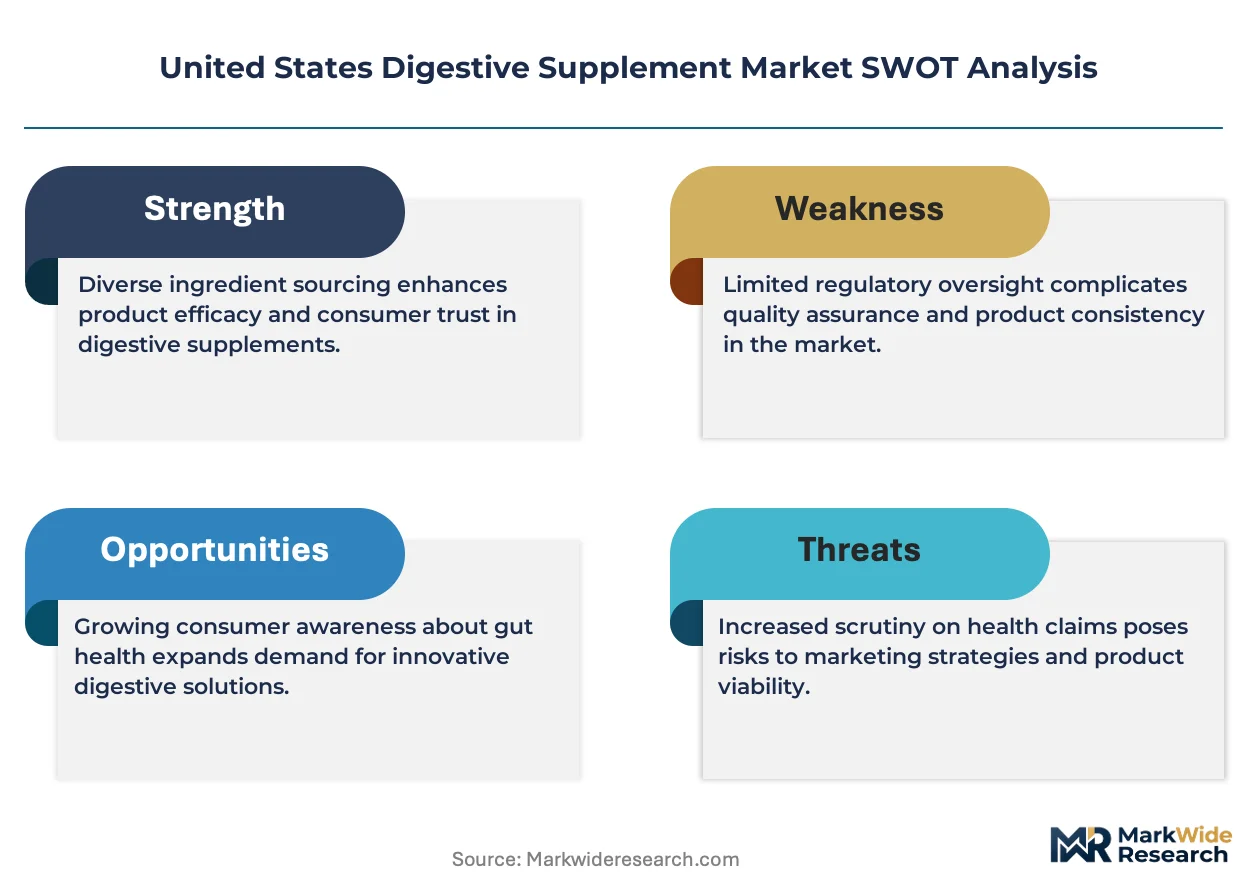
FDA NDI notifications, FTC advertising substantiation rules, and USP verification standards collectively govern product claims, ingredient safety documentation, and quality certification pathways in this market. The FDA's evolving enforcement posture on structure-function claims directly shapes marketing expenditures and reformulation cycles for manufacturers. Stakeholders must monitor whether Congress advances mandatory product listing legislation that would fundamentally alter market access requirements for new entrants.
Market Dynamics
Collegiate sports nutrition programs are expanding their procurement of digestive supplements, creating a concentrated buyer segment that reshapes volume allocation and contract structures across manufacturing networks.
Growth Catalysts
- FDA New Dietary Ingredient notifications:The notification pathway accelerates safety documentation standards, pushing established manufacturers toward premium positioning and filtering out undercapitalized entrants.
- Functional food clusters:California's Los Angeles and San Francisco metro areas concentrate R&D talent, contract manufacturing capacity, and direct-to-consumer brand headquarters in tight geographic proximity.
- Microbiome sequencing:Advances in gut flora analysis enable personalized probiotic formulations, opening subscription-based revenue models with higher lifetime value metrics.
Market Restraints
- Colony-forming unit degradation:Controlled-temperature encapsulation and moisture-barrier packaging add 15-25% to unit production costs versus standard supplement manufacturing.
- Supply concentration:Domestic production of specialized probiotic strains relies on a limited base of fermentation facilities, creating bottlenecks during demand surges.
- FTC advertising substantiation:Structure-function claim enforcement requires extensive clinical documentation, extending marketing compliance timelines and legal expenditure.
Strategic Opportunities
- Senior dose flexibility:Powder formats remain underdeveloped for the 65-plus demographic seeking customizable enzyme and fiber dosing outside capsule constraints.
- Clinician-recommended protocols:Pharmacy and healthcare channel penetration offers margin expansion through professional endorsement models distinct from mass retail.
- Subscription bundle architecture:Recurring revenue platforms reduce customer acquisition cost amortization while capturing predictable volume commitments from athletic programs.
Industry Challenges
- Reformulation cycle compression:Evolving FDA enforcement on structure-function claims forces quarterly label revisions and inventory write-downs for non-compliant stock.
- Moisture-barrier packaging scale-up:Transitioning from bulk bottles to single-serve stick packs requires capital-intensive line conversion at contract manufacturing partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Digestive Supplement Market |
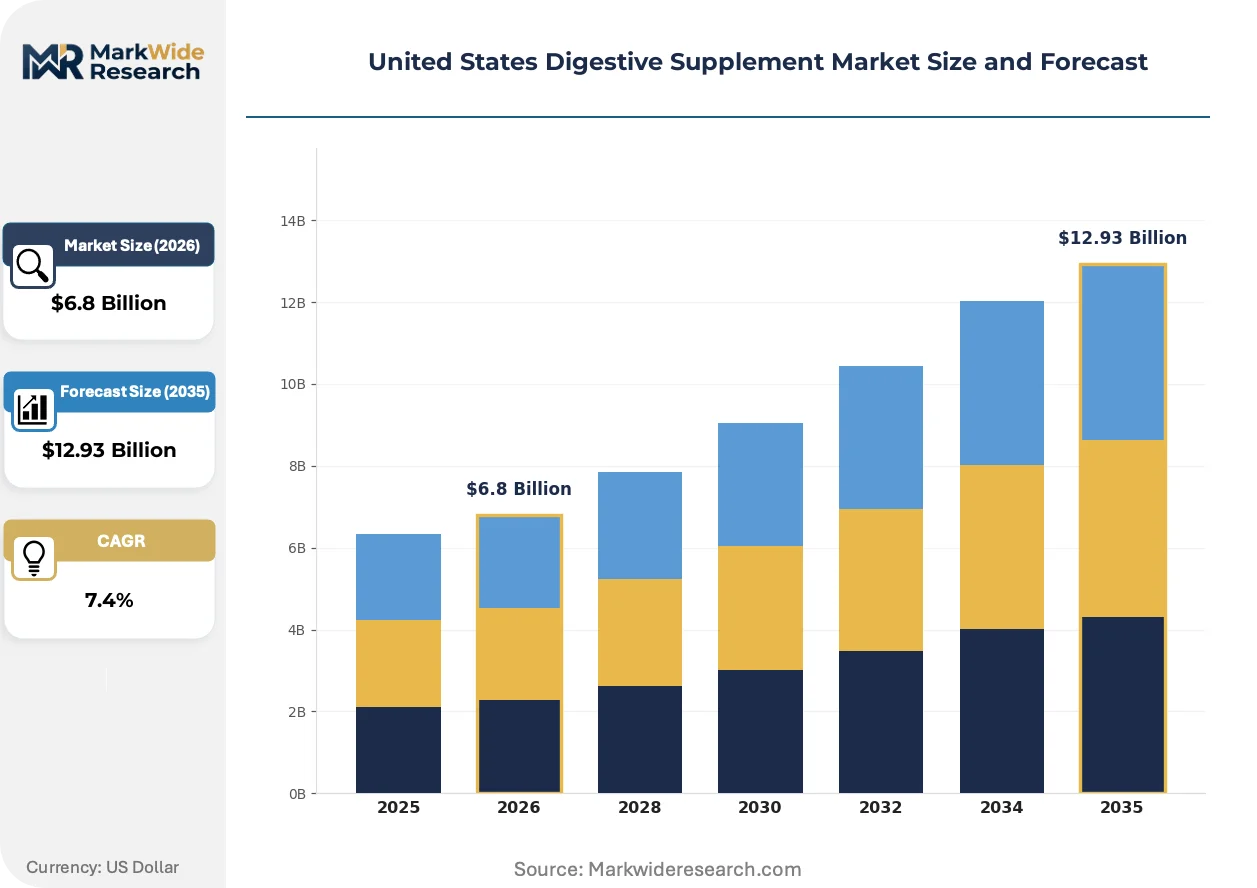
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $12.93 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Probiotics, Prebiotics, Digestive Enzymes, Fiber Supplements Form: Capsules, Tablets, Powders, Liquids Customer Type: Adults, Seniors, Children, Athletes Distribution Channel: Online Retail, Pharmacies, Supermarkets, Specialty Stores |
| Companies Covered | Pfizer Inc., Nestlé SA, NOW Foods Inc., Herbalife Nutrition Ltd., Bayer AG, Amway Corporation, Haleon PLC, Abbott Laboratories, Procter & Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Digestive Supplement Market Evolving Landscape
Format innovation and regulatory documentation requirements are compressing traditional supply chain relationships while opening new channel architectures for digestive supplement distribution.
Controlled-atmosphere encapsulation technology is consolidating manufacturing capabilities among suppliers capable of maintaining colony-forming unit viability across extended shelf life. Collegiate athletic programs and senior living operators are adopting these stabilized formats at accelerating rates. This technical barrier is consolidating contract manufacturing relationships around partners with validated cold-chain and humidity-controlled production environments.
FDA's evolving enforcement posture on structure-function claims is extending compliance timelines for new product introductions. Manufacturers must now front-load clinical substantiation budgets before market entry, compressing available capital for brand marketing. The probiotic and prebiotic category faces the steepest documentation requirements, with several mid-tier brands retreating to generic fiber positioning.
Athletic department procurement officers are consolidating vendor relationships around suppliers offering bundled sports nutrition and digestive health protocols. This buyer concentration is displacing single-category specialists who lack cross-portfolio contract negotiation leverage. The shift is most visible across NCAA Division I programs in the Southeast and Midwest, where consolidated purchasing agreements now cover 60-80% of supplement spend.
United States Digestive Supplement Market Segmentation
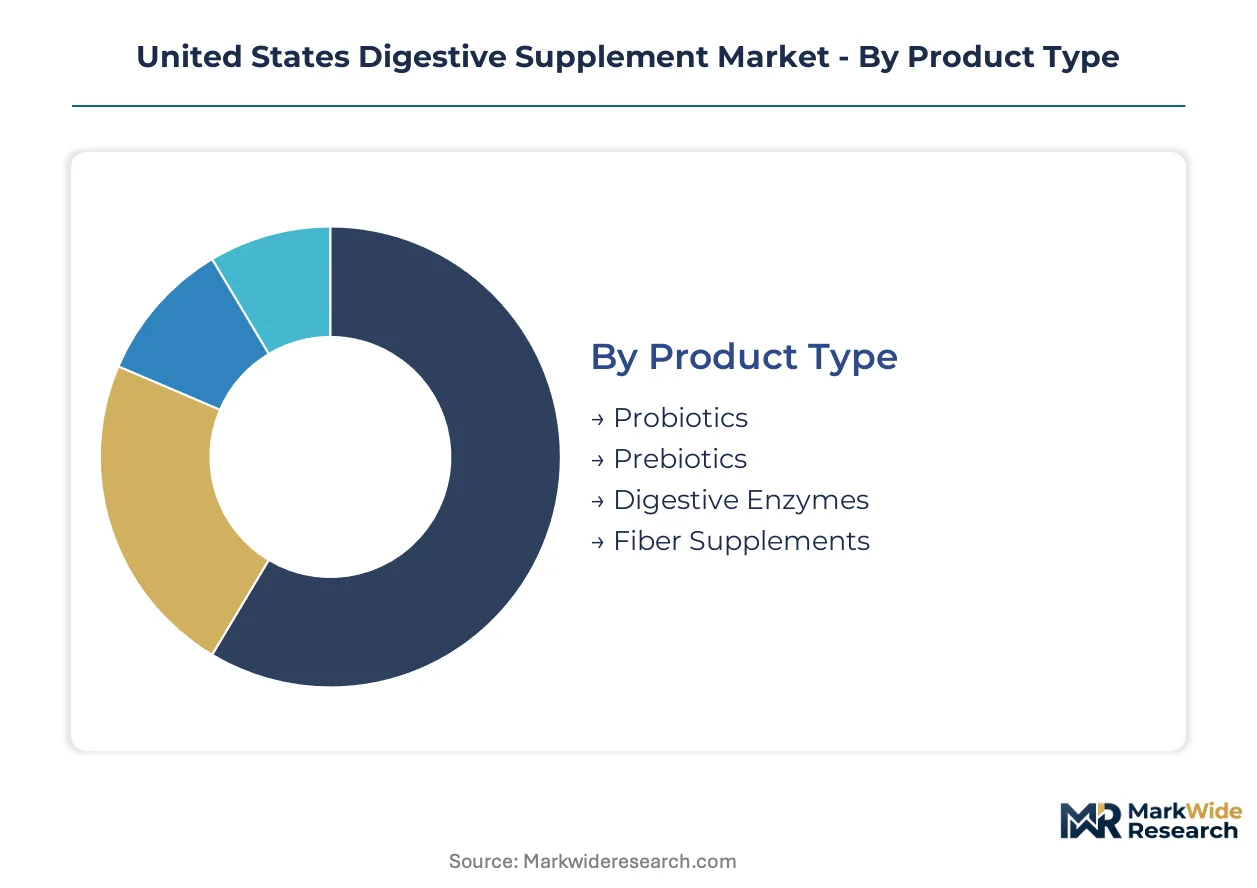
Segmentation in the United States digestive supplement market reveals how formulation complexity, delivery format, and buyer concentration reshape procurement patterns across manufacturing networks. Each dimension exposes distinct margin pools and regulatory exposure profiles that determine competitive positioning.
Product Type:
Customization versus standardization splits sharply across this category, with live microbial cultures demanding validated cold-chain infrastructure while fiber supplements operate on commodity manufacturing economics.
- Probiotics:Live bacterial and yeast cultures requiring controlled-temperature encapsulation and moisture-barrier packaging to maintain colony-forming unit viability. Demand concentrates in California's Los Angeles and San Francisco metro functional food clusters, where R&D talent and contract manufacturing capacity enable rapid formulation iteration under FDA New Dietary Ingredient notification pathways.
- Prebiotics:Non-digestible fibers that selectively feed beneficial gut microbiota, typically oligosaccharides or inulin derivatives. Collegiate sports nutrition programs in the Southeast and Midwest are expanding procurement of these substrates as bundled protocols with protein supplements, creating volume concentration that reshapes contract structures.
- Digestive Enzymes:Proteolytic and lipolytic proteins targeting lactose intolerance and protein malabsorption conditions.
- Fiber Supplements:Psyllium husk, methylcellulose, and synthetic soluble fiber formulations for bowel regularity.
Leading the category by volume: Probiotics. Growing fastest: Digestive Enzymes.
Form:
Unit economics and shelf-stability requirements create divergent capital intensity across production formats, with powder manufacturing requiring lower barrier packaging investment than live culture encapsulation.
- Capsules:Gelatin or vegetable-based shells containing probiotic powders or enzyme blends, dominating pharmacy and clinician-recommended distribution channels. Senior demographics and standardized dosing protocols drive volume concentration here, though moisture sensitivity limits ambient storage duration.
- Tablets:Compressed formulations with binding agents and disintegrants, occupying the largest volume position across mass retail. California's contract manufacturing base specializes in high-speed tablet production for national supermarket and pharmacy chains.
- Powders:Loose granules or micronized formulations enabling dose customization. Athletes and seniors seeking flexibility outside capsule constraints are accelerating adoption, particularly through subscription bundle architectures and single-serve stick pack formats.
- Liquids:Suspension or solution-based delivery for pediatric applications and dysphagia patients.
Capsules generate the highest absolute volume. Powders are climbing the fastest as format innovation restructures purchase patterns.
Customer Type:
Age-related physiological variation and performance demands fragment this category into distinct dosing regimens and channel preferences.
- Adults:General wellness seekers purchasing through supermarkets and online retail, representing the baseline volume pool for standardized probiotic and fiber formulations.
- Seniors:Consumers over 65 requiring customizable enzyme and fiber dosing for age-related digestive decline. Powder formats remain underdeveloped for this demographic, presenting strategic whitespace for dose-flexible product development.
- Children:Pediatric formulations with flavor masking and reduced colony-forming unit counts, distributed primarily through pediatrician recommendations and specialty stores.
- Athletes:Collegiate and professional sports programs procuring through consolidated vendor relationships. NCAA Division I programs in the Southeast and Midwest now cover 60-80% of supplement spend through bundled sports nutrition and digestive health protocols.
Athletes command the steepest expansion trajectory. Seniors present the largest untapped volume opportunity.
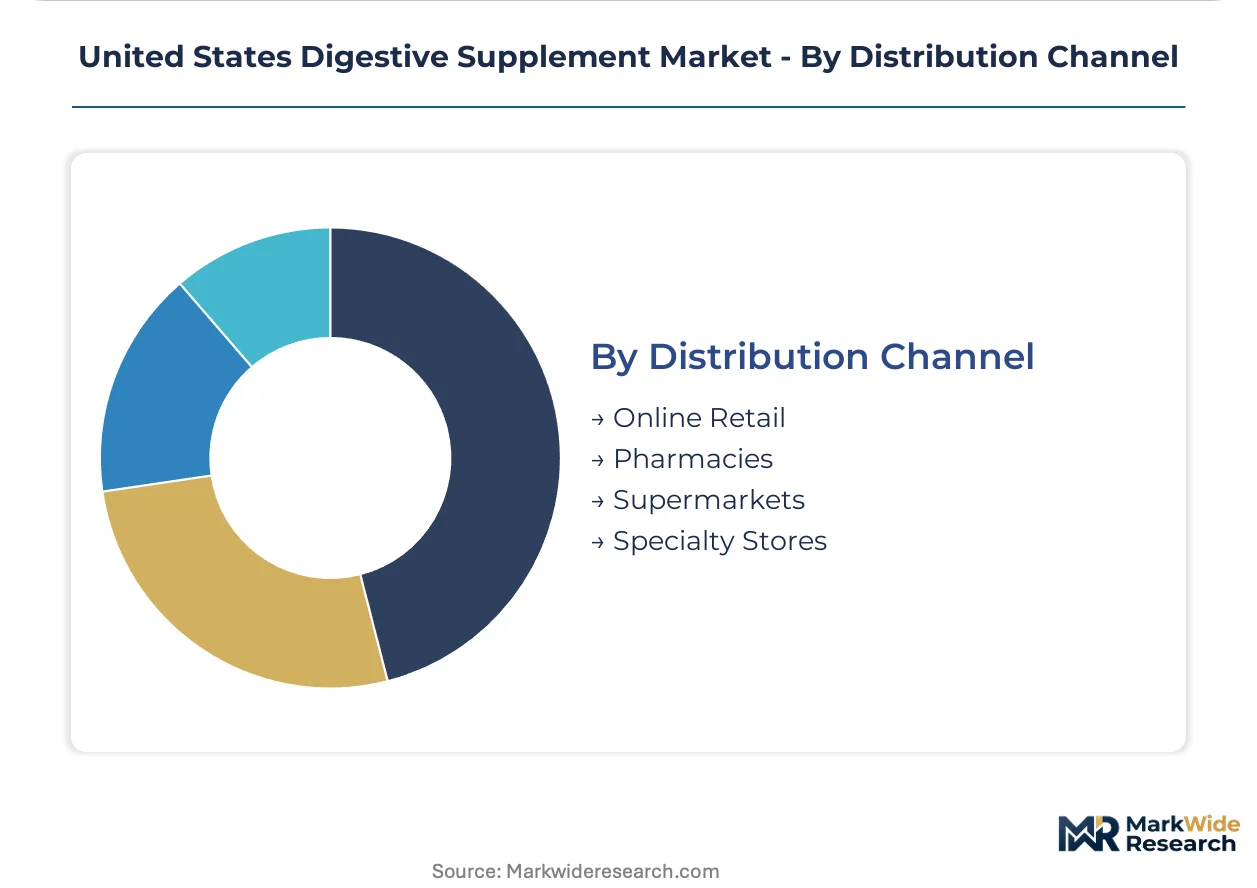
Distribution Channel:
Channel control determines margin capture, with professional endorsement models commanding premium positioning over mass retail price competition.
- Online Retail:Direct-to-consumer platforms and subscription services enabling recurring revenue models. California's brand headquarters cluster leverages this channel for microbiome sequencing-based personalized formulations with higher lifetime value metrics.
- Pharmacies:Clinician-recommended supplement protocols distributed through pharmacy networks. Abbott Laboratories and Pfizer Inc. anchor positions here through healthcare channel control and pharmaceutical distribution infrastructure.
- Supermarkets:Mass retail placement for standardized fiber and probiotic formulations, competing primarily on shelf price and brand recognition.
- Specialty Stores:Health food retailers and vitamin shops catering to enthusiast consumers seeking strain-specific probiotic products.
Pharmacies deliver the highest margin per unit. Online retail is gaining share fastest through subscription architecture adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California's functional food cluster spanning Los Angeles and San Francisco metro areas concentrates R&D talent, contract manufacturing capacity, and direct-to-consumer brand headquarters in tight geographic proximity, creating the nation's densest digestive supplement production zone.
California
Los Angeles and San Francisco metro areas anchor formulation innovation and cold-chain encapsulation infrastructure for live microbial cultures. FDA New Dietary Ingredient notification pathways accelerate here due to proximity to regulatory consultants and clinical research organizations. The state's functional food cluster enables rapid iteration from microbiome sequencing insights to commercial probiotic products.
Texas
Greater Houston and Dallas-Fort Worth metro areas concentrate sports nutrition manufacturing serving collegiate athletic programs across the Southeast and Midwest. The state's central logistics position supports distribution to NCAA Division I procurement officers consolidating vendor relationships. Contract manufacturers here specialize in powder format production for athlete-customizable dosing protocols.
New York Metro
Pharmacy and healthcare channel control centers on Manhattan and northern New Jersey distribution infrastructure. Abbott Laboratories and Pfizer Inc. leverage this corridor for clinician-recommended supplement protocol penetration. The region's dense healthcare provider networks enable professional endorsement models distinct from mass retail price competition.
Midwest
Illinois, Michigan, and Ohio host high-speed tablet and capsule production for national supermarket and pharmacy chains. Manufacturing economics here favor standardized fiber and probiotic formulations at scale. The region's fermentation facilities supply specialized probiotic strains, though capacity constraints emerge during demand surges.
Southeast
Florida and Georgia senior living operators drive powder format adoption for customizable enzyme and fiber dosing outside capsule constraints. The demographic concentration here presents strategic whitespace for dose-flexible product development targeting age-related digestive decline. Regional distribution networks support subscription bundle architectures for recurring revenue capture.
United States Digestive Supplement Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. Pharmaceutical-backed entities leverage healthcare channel infrastructure while specialized manufacturers concentrate on strain-specific probiotic cultivation and controlled-atmosphere encapsulation technology. Three archetypes dominate: conglomerates with pharmacy distribution networks, mid-cap specialists with validated cold-chain partnerships, and direct-to-consumer brands with microbiome personalization platforms. Competitive moves center on subscription bundle architecture deployment and moisture-barrier packaging line conversion at contract manufacturing partners.
Among pharmaceutical conglomerates, Pfizer Inc. and Abbott Laboratories anchor positions through healthcare channel control and clinician-recommended protocol distribution. NOW Foods Inc. exemplifies the specialized manufacturing archetype with scale in probiotic strain production and encapsulation infrastructure. Nestlé SA and Haleon PLC represent diversified nutrition and consumer health portfolios competing via mass retail placement and brand recognition. These entities collectively illustrate how regulatory compliance capabilities and channel access determine competitive positioning under evolving FDA enforcement postures.
| Leading Market Players |
|---|
| Pfizer Inc. |
| Nestlé SA |
| NOW Foods Inc. |
| Herbalife Nutrition Ltd. |
| Bayer AG |
| Amway Corporation |
| Haleon PLC |
| Abbott Laboratories |
| Procter & Gamble Company |
| Others |
Value Network & Pricing Analysis
Controlled-temperature encapsulation costs flow from specialized fermentation facilities through three-tier pricing structures across premium, standard, and economy levels, with moisture-barrier packaging investments separating pharmacy-grade probiotics from mass-market fiber supplements. This cost cascade concentrates margin capture among manufacturers with validated cold-chain partnerships while squeezing commodity tablet producers.
Pricing Analysis
Margin tightening in economy-tier fiber supplements reflects California contract manufacturers' scale advantages in high-speed tablet production. Three-tier pricing structure across premium, standard, and economy levels separates USP-verified pharmacy protocols from supermarket shelf products, with strain-specific probiotics commanding brand premiums. Cost-down pressure on standard-tier capsules accelerates because collegiate athletic programs consolidate procurement around bundled vendor relationships. Senior demographics show lowest price sensitivity for dose-flexible powders, while mass retail adults drive hardest bargain on bulk bottled probiotics.
Supply Chain Analysis
Return flows of temperature-compromised probiotic inventory create reverse-logistics burdens that specialized fermentation facilities in Illinois, Michigan, and Ohio absorb through batch reprocessing agreements. Domestic production draws from limited Midwest fermentation capacity for specialized strains, with psyllium husk and inulin derivatives sourcing from India and Mexico. Single-source vulnerability concentrates in validated cold-chain encapsulation partners serving California's functional food cluster. Distribution runs through pharmacy networks for clinician-recommended protocols and direct-to-consumer platforms for subscription bundles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States digestive supplement market is consolidating around FDA New Dietary Ingredient notification capabilities, with undercapitalized entrants unable to front-load clinical substantiation budgets retreating to generic positioning.
For Market Incumbents: Deepen vertical integration into controlled-atmosphere encapsulation technology to defend against mid-tier brands retreating to commodity fiber positioning. Secure exclusive fermentation capacity agreements in Midwest facilities before demand surges trigger allocation bottlenecks. Lock in multi-year contracts with NCAA Division I procurement officers consolidating vendor relationships across Southeast and Midwest programs. For New Entrants and Emerging Players: Direct-to-consumer microbiome sequencing platforms offer the most penetrable entry vector for personalized probiotic subscription models with higher lifetime value metrics. Target senior living operators in Florida and Georgia seeking dose-flexible powder formats outside capsule constraints. Launch through California's functional food cluster to leverage proximity to regulatory consultants and rapid formulation iteration. For Investors and Strategic Acquirers: Mandatory product listing legislation advancing through Congress is the leading indicator that regulatory compliance capabilities will determine acquisition premiums. Focus on mid-cap specialists with validated cold-chain partnerships and existing FDA NDI notification track records. Monitor FTC structure-function claim enforcement actions for signals of which brands face inventory write-down risk.| Strategic Initiative | Industry Significance |
|---|---|
| Moisture-Barrier Packaging Line Conversion | Enables single-serve stick pack formats that capture portable consumption occasions from bulk bottles. |
| Subscription Bundle Architecture Deployment | Reduces customer acquisition cost amortization while locking predictable volume from athletic programs. |
| FDA New Dietary Ingredient Notification Investment | Accelerates market access timelines and filters out undercapitalized competitors lacking documentation resources. |
| Collegiate Sports Nutrition Partnership Expansion | Captures procurement consolidation trend across NCAA Division I programs in Southeast and Midwest regions. |
| Microbiome Sequencing Platform Integration | Opens personalized formulation revenue models with recurring subscription economics and higher retention rates. |
Research Methodology
Document review covered FDA New Dietary Ingredient notification filings, FTC advertising substantiation case records, and USP verification standards, complemented by interviews with contract manufacturing executives, sports nutrition procurement officers at collegiate athletic programs, pharmacy chain supplement buyers, and regulatory affairs consultants. Secondary validation drew from SEC filings of publicly traded nutrition companies, clinical trial registrations for probiotic strains, and trade customs data on fermentation equipment imports. Bottom-up volume modeling triangulated against top-down category spending estimates across the analysis window.
Segment-level outputs trace formulation type, delivery format, customer demographic, and distribution channel across the projection horizon, with CAGRs derived from elasticity modeling against healthcare expenditure trends and consumer wellness spending patterns. Inputs incorporated FDA enforcement posture shifts on structure-function claims, collegiate athletic program procurement consolidation rates, and senior demographic powder format adoption curves.
The model holds under stable FDA notification pathways and continued FTC advertising substantiation enforcement; deviation in mandatory product listing legislation timing or moisture-barrier packaging material cost spikes would shift volume allocation forecasts. Practitioners should monitor congressional legislative calendars and fermentation facility capacity utilization reports for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Probiotic Supplements
Global Saccharomyces Boulardii Market
Probiotic Supplements
Global Liquid Feed Supplements Market
Probiotic Supplements
Digestion Aids Market
Probiotic Supplements
Europe Probiotics Market
Probiotic Supplements
Lactobacillus Acidophilus Market
Probiotic Supplements
Global Enteric Softgel Capsules Market
Probiotic Supplements
Mediterranean Probiotic-Polyphenol Synbiotic Concepts Market
Probiotic Supplements
Probiotics Gummies Market
Probiotic Supplements
Probiotics for Kids Market
Probiotic Supplements
South America Digestive Health Supplements Market
Probiotic Supplements
Europe Probiotic Supplements Market
Probiotic Supplements
South America Microbial Food Culture Market
Probiotic Supplements
Probiotics Market
Probiotic Supplements
Bifidobacterium Probiotics Market
Probiotic Supplements
Synbiotic Product Market
Probiotic Supplements
Women Probiotic Market