
 Multivitamin Gummies Market | 2026-2036
Multivitamin Gummies Market Size, Share, and Industry Trends Forecast 2026-2036
Multivitamin Gummies Market Analytics
The adult wellness segment is pivoting away from traditional tablets toward palatable gummy formats that improve compliance. Bayer AG leverages its pharmaceutical heritage to sustain credibility in clinical-grade formulations. SmartyPants Vitamins anchors its position through third-party testing transparency. OLLY Public Benefit Corporation differentiates via lifestyle branding and retail shelf presence.
Multivitamin gummies are chewable dietary supplements containing encapsulated vitamins, minerals, and functional additives within a gelatin or pectin matrix, manufactured through starch molding or depositing processes at controlled temperatures to preserve heat-sensitive nutrients like vitamin C and biotin. The organic and sugar-free product types command premium shelf positioning as consumers scrutinize excipient lists. Senior-targeted formulations within the target audience dimension represent an underserved margin pool given aging demographics. Immune support formulations lead the formulation type split, though digestive health variants show the steepest growth trajectory.
FDA Good Manufacturing Practices and EFSA health claims regulations constrain permissible ingredient dosages and marketing language, forcing reformulation cycles that extend product development timelines. The USDA organic seal and EU organic certification create bifurcated sourcing requirements for multinational portfolios. Stakeholders must monitor evolving pediatric dosing guidelines from regulators as child-targeted SKUs face heightened scrutiny.
Market Dynamics
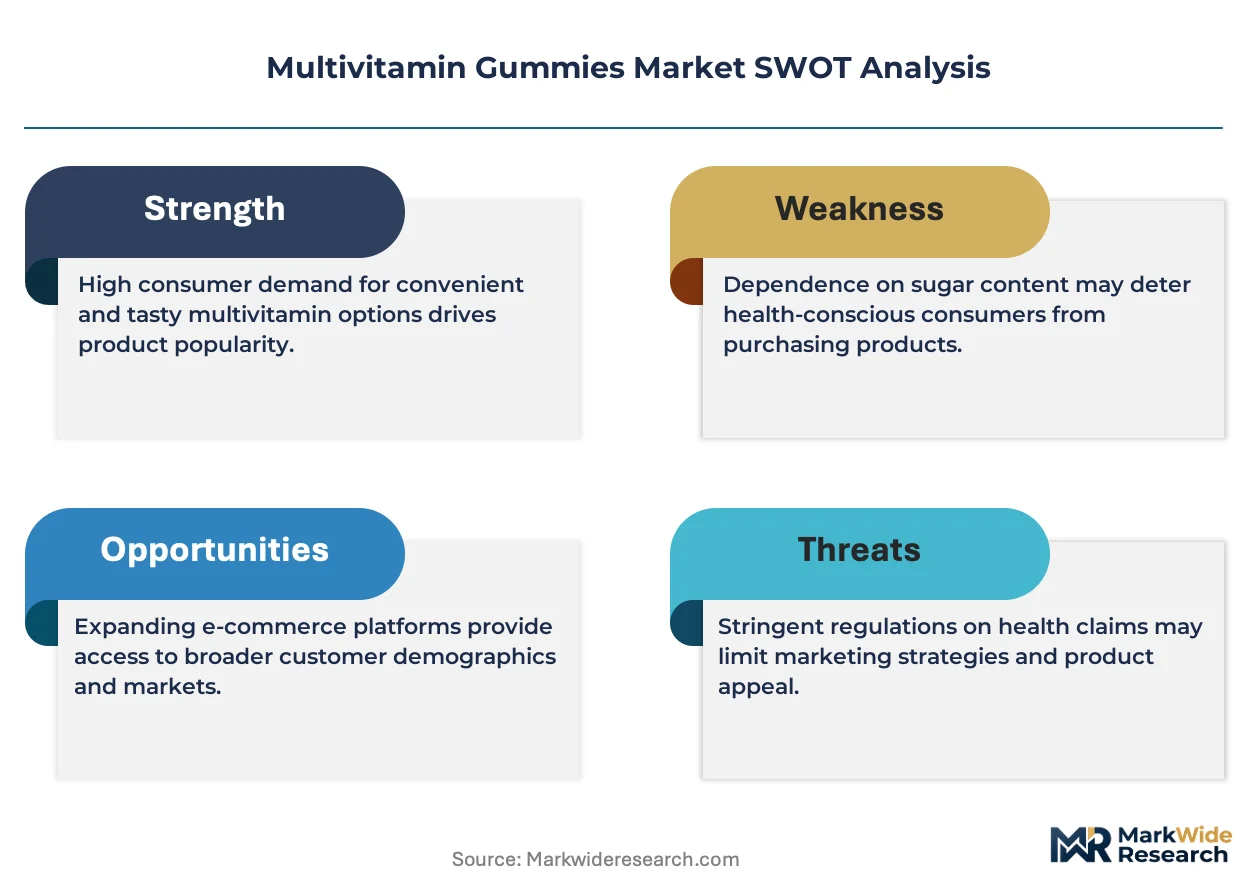
Adult pill fatigue is restructuring the multivitamin gummies competitive landscape as compliance-driven consumers abandon tablet formats for palatable alternatives, forcing incumbent pharmaceutical manufacturers to reconfigure production lines toward confectionery-grade facilities.
Growth Catalysts
- FDA Good Manufacturing Practices:Stringent quality mandates elevate barrier to entry for low-cost competitors, protecting margin pools for compliant domestic manufacturers.
- Pectin-based gelling systems:Plant-derived alternatives to gelatin capture vegan and religious dietary segments previously excluded from animal-source products.
- Germany:Europe's largest functional food market anchors regional demand as EFSA health claim authorizations validate immune-support positioning.
Market Restraints
- Gelatin supply concentration:Bovine and porcine-derived gelatin production clusters in Brazil and Argentina, exposing formulators to livestock disease quarantine risks.
- Heat-sensitive nutrient degradation:Vitamin C and biotin potency losses during starch molding above 80°C necessitate costly microencapsulation or overage compensation.
- EFSA nutrient reference value ceilings:Maximum permitted dosages in food supplements constrain clinical-grade positioning versus pharmaceutical alternatives.
Strategic Opportunities
- China's aging population:Senior-targeted formulations addressing bone health and cognitive function remain underdeveloped relative to pediatric and adult mass-market SKUs.
- Direct-to-subscription channels:Personalized vitamin platforms bypass retail slotting fees while capturing recurring revenue and compliance data.
- USDA Organic certification:Premium positioning through certified organic excipients commands shelf space in natural channel retailers.
Industry Challenges
- Confectionery-scale manufacturing expertise:Pharmaceutical heritage companies lack starch molding and depositing process engineering talent, requiring acquisition or partnership.
- Dual certification complexity:Simultaneous USDA Organic and EU organic compliance demands bifurcated ingredient sourcing and documentation systems.
- Pediatric dosing guideline evolution:FDA and EFSA scrutiny of child-targeted vitamin concentrations forces SKU-specific stability testing extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multivitamin Gummies Market |
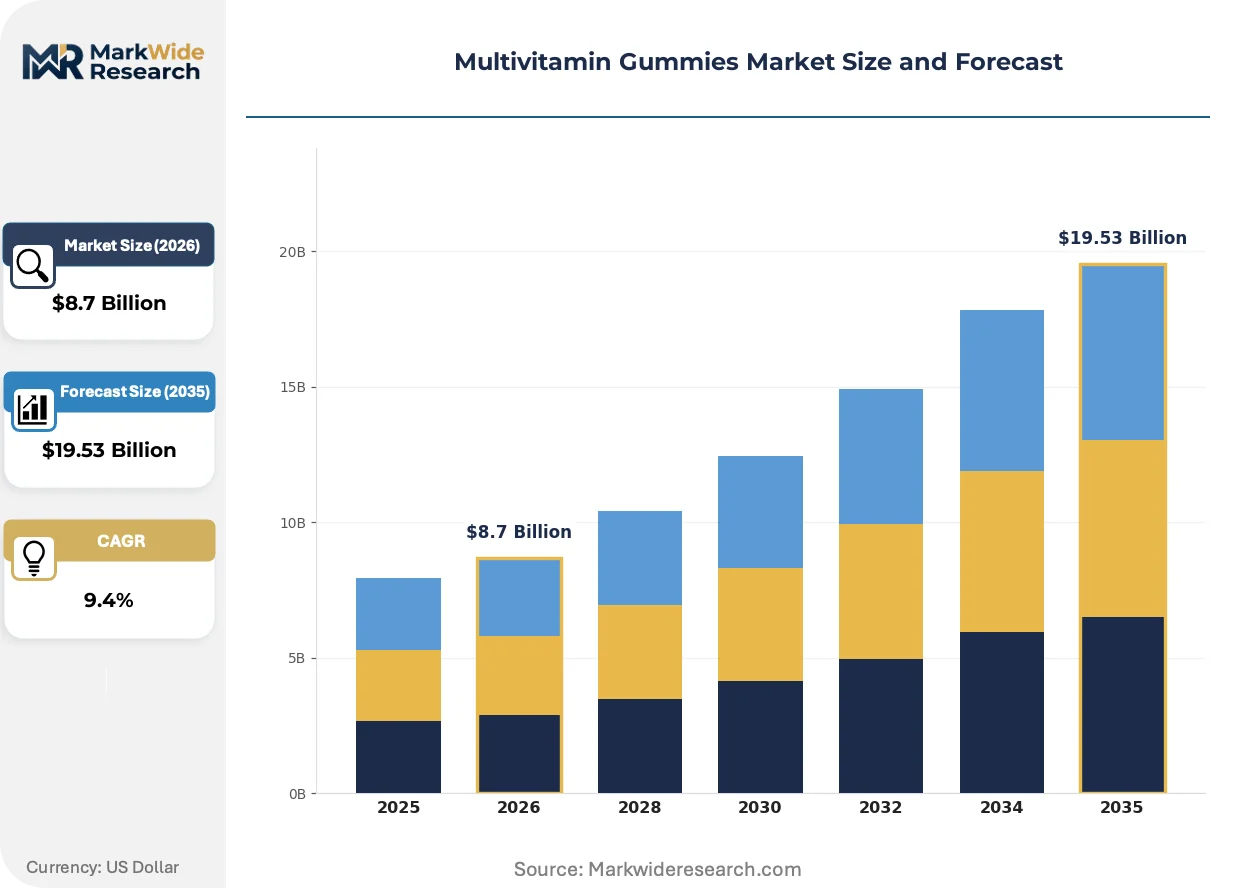
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Sugar-Free, Vegan, Regular Target Audience: Children, Adults, Seniors, Athletes Distribution Channel: Online, Supermarkets, Health Stores, Pharmacies Formulation Type: Immune Support, Digestive Health, Overall Wellness, Energy Boost |
| Companies Covered | Church & Dwight Co., Inc., Bayer AG, SmartyPants Vitamins, Pharmavite LLC, Garden of Life, OLLY Public Benefit Corporation, Nestlé, Otsuka Pharmaceutical Co., Ltd., Goli Nutrition Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multivitamin Gummies Market Evolving Landscape
Manufacturing technology convergence and regulatory claim tightening are compressing product development cycles while expanding addressable consumer segments through format innovation and clean-label positioning.
Microencapsulation technology using lipid or polysaccharide shells is modularizing nutrient protection strategies, enabling heat-sensitive vitamin incorporation into conventional starch molding without potency sacrifice. Adult wellness brands are adopting these systems fastest as they scale clinical-grade formulations. The technology is modularizing competitive differentiation around bioavailability claims rather than basic compliance.
EFSA's 2022 guidance on immune function health claims has narrowed permissible marketing language for vitamin C, zinc, and D formulations, forcing European marketers toward structure-function disclaimers. Manufacturers now invest in clinical trial infrastructure to support Article 13.5 proprietary claims. The adult segment bears primary adaptation costs as immune positioning dominates their value proposition.
Subscription-based replenishment models are displacing traditional retail impulse purchasing among millennial and Gen Z wellness consumers. Direct channels capture compliance data that informs personalized formulation adjustments. The United States exhibits the steepest channel migration as DTC-native brands capture urban coastal demographics.
Multivitamin Gummies Market Segmentation
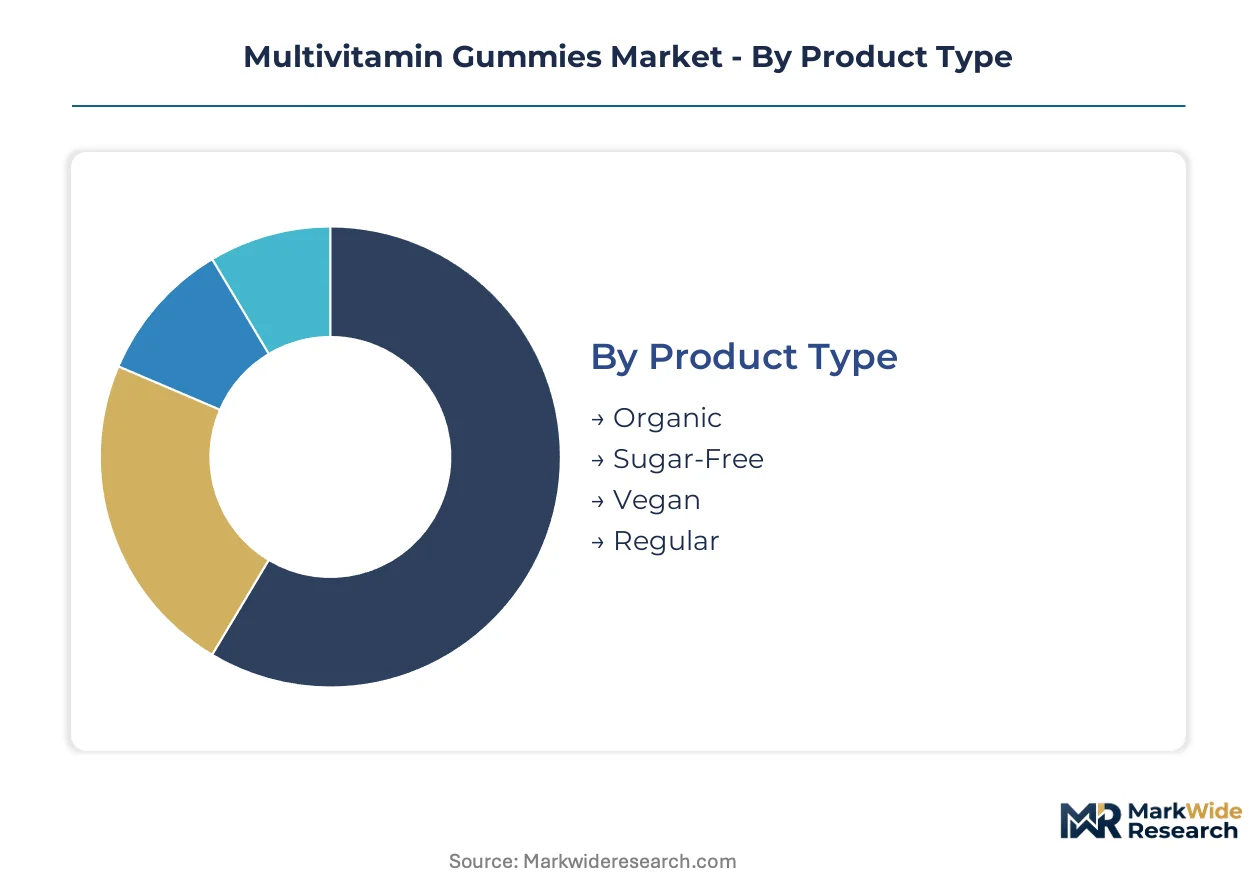
Format preferences and regulatory positioning create distinct competitive arenas within multivitamin gummies. Each segmentation axis reveals divergent margin structures and compliance burdens that reshape manufacturer resource allocation.
Product Type:
Pectin versus gelatin gelling systems define the technical specification frontier, with plant-derived alternatives commanding premium positioning.
- Organic:USDA-certified organic excipients and non-GMO vitamin sourcing satisfy natural channel requirements. Demand clusters in United States coastal metros and German organic retailers where EFSA health claim authorizations validate premium positioning.
- Sugar-Free:Polyol-based sweetening systems replace sucrose for diabetic and dental-conscious consumers. Adoption concentrates in Germany and United States pharmacy channels where clinical credibility drives repeat purchase.
- Vegan:Pectin matrices eliminate animal-derived gelatin entirely, capturing religious dietary exclusions and ethical positioning. This segment expands most quickly as EMA-adjacent clean-label mandates tighten across European markets.
- Regular:Gelatin-based formulations with standard excipient profiles maintain mass-market price accessibility.
Mature deployment sits with Regular. Newer deployment is concentrated in Vegan.
Target Audience:
Demographic-specific dosing regimens and marketing claims create divergent regulatory exposure profiles across consumer life stages.
- Adults:Pill fatigue drives the steepest format migration as wellness-oriented millennials abandon tablets for palatable alternatives. United States urban professionals represent the densest concentration of direct-to-subscription adoption.
- Seniors:Bone health and cognitive function formulations remain underdeveloped relative to population aging in China and Germany. This segment offers the highest untapped margin potential given clinical-grade positioning opportunities.
- Children:Pediatric dosing guidelines from FDA and EFSA impose SKU-specific stability testing extensions. Heightened regulatory scrutiny constrains permissible vitamin concentrations.
- Athletes:NSF Certified for Sport and Informed Sport verification requirements add third-party testing costs. Demand localizes to United States collegiate and professional sports nutrition channels.
Volume leadership sits with Adults. Margin expansion concentrates in Seniors.
Distribution Channel:
Channel selection determines slotting fee exposure, compliance data capture capabilities, and subscription revenue potential.
- Online:Direct-to-consumer platforms bypass retail intermediaries while capturing recurring revenue and personalization data. United States millennial and Gen Z demographics drive the steepest channel migration.
- Supermarkets:Mass-market placement requires trade spend investment but delivers impulse purchase volume. Shelf space competition intensifies as confectionery and pharmaceutical suppliers converge.
- Health Stores:Natural channel positioning demands USDA Organic or equivalent certification. Staff recommendation dependency creates education burden for emerging brands.
- Pharmacies:Clinical credibility endorsement supports premium pricing but requires pharmacist detailing investment. Germany's pharmacy-dominant supplement culture anchors European demand.
Established presence sits with Supermarkets. Fastest channel share gains concentrate in Online.
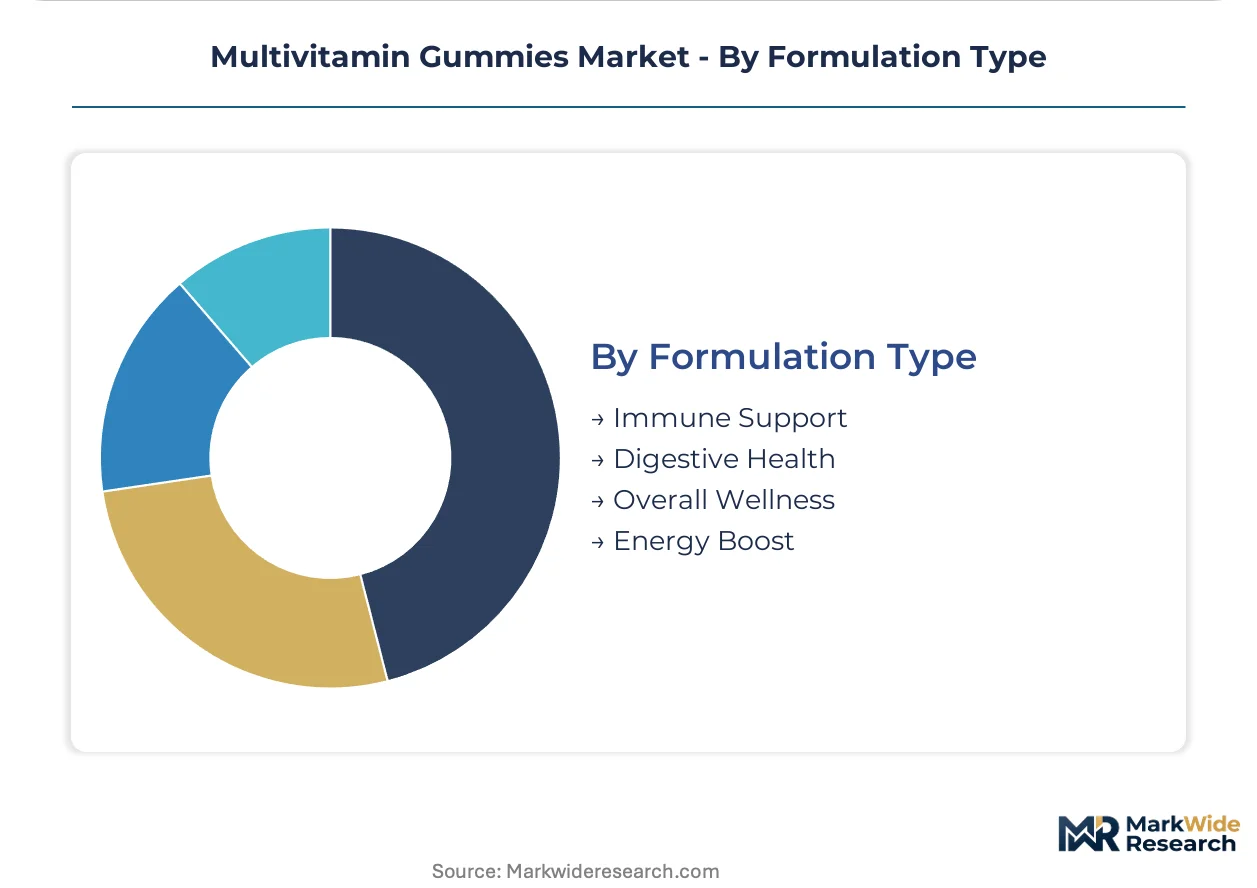
Formulation Type:
Functional claim specificity shapes regulatory risk exposure and clinical trial investment requirements.
- Immune Support:Vitamin C, zinc, and D combinations dominate SKU counts. EFSA's narrowed health claim guidance forces European marketers toward structure-function disclaimers.
- Digestive Health:Probiotic and prebiotic inclusions require live culture stability validation. This segment climbs the fastest as gut microbiome research validates consumer interest.
- Overall Wellness:Broad-spectrum multivitamin positioning minimizes claim risk but commoditizes differentiation. Price competition intensifies in mass-market channels.
- Energy Boost:B-vitamin complexes and adaptogenic additives target fatigue positioning. Caffeine content triggers additional labeling requirements in select jurisdictions.
SKU density sits with Immune Support. Steepest expansion trajectory concentrates in Digestive Health.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in China's coastal provinces and India's Special Economic Zones for nutraceuticals concentrate contract manufacturing capacity. These zones attract multinationals seeking tariff-efficient export bases for gummy vitamin production. Regulatory harmonization pressures across the United States, Germany, and China reshape regional investment patterns.
United States
Direct-to-consumer subscription models capture millennial and Gen Z wellness consumers in coastal metros. FDA Good Manufacturing Practices enforcement elevates compliance costs for imported finished goods. New Jersey and California host the densest clusters of contract manufacturers serving both domestic retail and cross-border e-commerce channels.
Germany
Pharmacy-dominant supplement culture anchors European demand for clinical-grade positioning. EFSA health claim authorizations validate immune-support formulations while constraining permissible marketing language. Bavaria and North Rhine-Westphalia concentrate production facilities serving EU-wide distribution networks.
China
Aging demographics drive underdeveloped demand for senior-targeted bone health and cognitive function formulations. NMPA registration requirements for imported health foods extend product launch timelines. Yangtze River Delta free trade zones host multinational contract manufacturing for Asia-Pacific export markets.
India
Domestic nutraceutical demand expands through pharmacy and modern trade channels as preventive health awareness rises. FSSAI labeling mandates and health claim restrictions parallel EFSA frameworks. Maharashtra and Gujarat Special Economic Zones attract gummy vitamin contract manufacturers serving Middle East and African export markets.
Brazil
Bovine gelatin supply concentration exposes formulators to livestock disease quarantine risks from southern ranching regions. ANVISA health supplement regulations require pre-market notification for novel formulations. São Paulo state anchors both domestic consumption and Mercosur export logistics.
Multivitamin Gummies Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with pharmaceutical heritage companies competing against DTC-native wellness brands. The vendor base organizes into three tiers: multinational CPG conglomerates with shelf-space leverage, mid-cap branded specialists with third-party certification credibility, and private-label contract manufacturers serving retailer-owned brands. Strategic archetypes include clinical-credibility players leveraging pharmaceutical heritage, lifestyle-positioned brands emphasizing clean-label transparency, and scale-driven commodity suppliers. M&A activity concentrates on confectionery-process engineering capabilities, while strategic partnerships bridge pharmaceutical formulation expertise with starch molding production technology.
Among pharmaceutical-heritage conglomerates, Bayer AG and Nestlé occupy positions emphasizing clinical-grade credibility and CPG scale respectively. Within the branded specialist tier, SmartyPants Vitamins exemplifies third-party testing transparency as a competitive anchor, while OLLY Public Benefit Corporation represents lifestyle-brand positioning through retail shelf presence and benefit-corporation structure. Church & Dwight Co., Inc. sits within the diversified consumer health archetype, leveraging cross-category brand equity into gummy vitamin adjacencies. These named entities illustrate strategic positioning patterns rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Church & Dwight Co., Inc. |
| Bayer AG |
| SmartyPants Vitamins |
| Pharmavite LLC |
| Garden of Life |
| OLLY Public Benefit Corporation |
| Nestlé |
| Otsuka Pharmaceutical Co., Ltd. |
| Goli Nutrition Inc. |
| Others |
Value Network & Pricing Analysis
Gelatin commodity indices and pectin feedstock costs cascade through multivitamin gummy supply chains, compressing margin structures for manufacturers locked into animal-derived gelling systems while rewarding plant-based formulators with pricing power in premium channels. FDA Good Manufacturing Practices compliance costs and EFSA health claim authorization expenses further stratify final shelf prices across organic, sugar-free, and clinical-grade positioning tiers.
Pricing Analysis
Short lead-time premiums command shelf space in pharmacy and direct-to-subscription channels where inventory freshness drives repeat purchase loyalty, while spot inventory discounts concentrate in mass-market retail overstocks nearing expiration windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—USDA Organic and third-party tested SKUs anchor the top tier, conventional gelatin-based formulations occupy the middle, and private-label contract production fills economy positioning. Pricing pressure stems from gelatin supply volatility in Brazil and Argentina as livestock disease quarantines disrupt input costs. Pharmacy channel buyers exhibit lowest price sensitivity given clinical credibility requirements, while supermarket impulse purchasers show highest elasticity to promotional discounting.
Supply Chain Analysis
Return flows and temperature excursion claims reshape reverse logistics burdens as heat-sensitive vitamin degradation triggers product recalls and retailer chargebacks across distribution networks. Gelatin production concentrates in Brazil and Argentina, pectin sourcing clusters in citrus-growing regions of Mexico and Spain, and finished goods manufacturing localizes in United States contract facilities and China's Yangtze River Delta free trade zones. Raw material dependencies span bovine-derived gelatin, citrus peel pectin, and microencapsulated vitamin premixes from specialized chemical suppliers. Single-source vulnerability in South American gelatin exposes formulators to foot-and-mouth disease quarantine protocols. Distribution runs through pharmacy wholesale networks in Germany, direct-to-consumer platforms in United States coastal metros, and modern trade retail in China's tier-one cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multivitamin gummy manufacturing is consolidating around confectionery-process engineering capabilities as pharmaceutical heritage companies acquire starch molding expertise to defend against DTC-native brands, forcing sub-scale private-label operators toward distressed exit or contract manufacturing absorption.
For Market Incumbents: Anchor market position through backward integration into pectin supply chains and captive microencapsulation technology production, neutralizing gelatin price volatility threats while securing bioavailability claim differentiation. Invest in dual USDA Organic and EU organic certification infrastructure to capture natural channel shelf space before EMA-adjacent clean-label mandates tighten. Prioritize acquisition targets with starch molding process engineering talent over brand equity plays. For New Entrants and Emerging Players: Enter via senior-targeted bone health and cognitive function formulations in China and Germany, the most penetrable white space given aging demographics and underdeveloped SKU counts relative to pediatric and adult mass-market saturation. Leverage direct-to-subscription channels to bypass retail slotting fee barriers and capture compliance data for personalized formulation adjustments. Position through third-party testing transparency as SmartyPants Vitamins exemplifies. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap branded specialists with USDA Organic certification and established pharmacy channel relationships in Germany and United States coastal markets, as FDA enforcement elevates compliance costs for imported finished goods. Long-term viability across the projection horizon hinges on confectionery-scale manufacturing expertise convergence with pharmaceutical formulation credibility. Monitor EFSA pediatric dosing guideline evolution and NMPA registration timeline extensions as inflection indicators for child-targeted SKU profitability.| Strategic Initiative | Industry Significance |
|---|---|
| Pectin Supply Integration | Backward integration into citrus peel sourcing secures vegan positioning against gelatin volatility. |
| Dual Organic Certification | Simultaneous USDA and EU organic compliance captures natural channel shelf space in Germany. |
| Senior Formulation Development | Bone health and cognitive SKUs address underpenetrated aging demographics in China. |
| Direct-to-Subscription Launch | DTC platforms bypass retail slotting fees while capturing recurring revenue and personalization data. |
| Microencapsulation Scale-Up | Lipid shell technology enables heat-sensitive vitamin incorporation without potency sacrifice. |
Research Methodology
Trade publications, FDA enforcement action databases, and EFSA health claim authorization records formed the secondary backbone, supplemented by customs data on gelatin and pectin import flows. Primary interviews with contract manufacturing executives, pharmacy category buyers, regulatory affairs directors at multinational CPG firms, and R&D leads at pectin suppliers validated secondary findings. Bottom-up SKU-level volume estimates triangulated against top-down category expenditure data from retail audit services.
Historical trendline analysis of adult wellness format migration and pill fatigue adoption curves informed projection assumptions across the modeling period. Segmentation dimensions modeled include gelling system type, target audience life stage, distribution channel structure, and functional claim specificity. CAGRs derived from logistic diffusion curves fitted to observed adoption patterns in United States, Germany, and China. Forecast inputs incorporated EFSA nutrient reference value ceiling revisions and NMPA registration timeline assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under livestock disease quarantine scenarios in Brazil and Argentina or abrupt EFSA pediatric dosing guideline restrictions. Practitioners should monitor gelatin commodity price indices, EMA clean-label mandate evolution, and direct-to-subscription churn rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
North America Feed Vitamins Market
Vitamin Fortified
Vitamin Premix Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
Vitamin B Complex Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Asia-Pacific Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Europe Feed Vitamins Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Vitamin a in Feed Additives Market
Vitamin Fortified
Natural Beta Carotene Market
Vitamin Fortified
Vitamin K Market