
 Calcium-Fortified Bread Market | 2026-2036
Calcium-Fortified Bread Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium-Fortified Bread Market Analytics
Premium calcium density specifications is rotating toward the center of competitive strategy as consumers prioritize measurable nutritional claims over generic wellness branding. Grupo Bimbo leverages its North American manufacturing scale to anchor shelf-stable fortified lines in mass retail. Associated British Foods PLC competes through channel control across European supermarkets and health food stores. Britannia Industries Ltd. specializes in price-accessible fortified white bread for family segments in South Asian markets.
Calcium-fortified bread denotes wheat-based or alternative-grain loaves enriched with bioavailable calcium salts, typically calcium carbonate or calcium lactate, to deliver 10-30% of daily recommended intake per serving through standard baking processes. The primary commercial purpose centers on converting commodity bread into differentiated functional food with validated bone-health claims. Whole grain and multigrain product types command the deepest margin pools due to ingredient premiums and dual health positioning. Supermarkets dominate volume throughput, while health food stores and online retail represent the fastest-growing distribution channels as direct-to-consumer subscription models expand.
The FDA governs nutrient content claims and fortification ceilings for bread sold in the United States, while the EFSA evaluates health claim substantiation across European markets, and India's FSSAI mandates additive safety thresholds for calcium compounds in baked goods. These frameworks collectively elevate compliance costs for cross-border suppliers while creating barriers against unsubstantiated fortification marketing. Stakeholders must monitor evolving bioavailability testing standards and front-of-pack labeling mandates to preserve market access and consumer trust.
Market Dynamics
The FDA's updated fortification guidelines for grain products are compressing formulation flexibility while elevating compliance thresholds, forcing manufacturers to revalidate calcium salt bioavailability claims under stricter substantiation protocols.
Growth Catalysts
- School nutrition programs:North American institutional procurement mandates are expanding calcium-fortified bread volumes through federally subsidized meal contracts that prioritize measurable nutrient density.
- EFSA health claim substantiation:Validated bone-health positioning enables premium pricing across European supermarket channels where regulatory credibility differentiates functional from commodity bread.
- Aging demographics:United States preventive health priorities are concentrating demand among consumers over 55 seeking dietary calcium alternatives to supplements.
Market Restraints
- Calcium carbonate input volatility:Industrial mineral supply concentration in China creates price instability for primary fortification salts used in standard baking processes.
- FSSAI additive safety thresholds:India's maximum permitted levels for calcium lactate in baked goods restrict formulation latitude compared to North American ceilings.
- Plant-based milk substitution:Oat and almond beverage fortification programs are diverting consumer calcium intake away from bread-based sources in urban markets.
Strategic Opportunities
- Direct-to-consumer subscription models:Online retail channels enable recurring revenue capture through personalized nutrition bundles combining fortified bread with biomarker testing services.
- PLI scheme alignment:India's production-linked incentive framework for food processing offers capital subsidy pathways for automated fortification lines serving price-accessible segments.
- Dual-carbon bakery integration:Renewable energy-powered production facilities can pair calcium fortification with carbon-neutral positioning in European sustainability-indexed retail.
Industry Challenges
- Bioavailability validation expertise:Clinical trial design for calcium absorption studies requires specialized nutrition science talent scarce among mid-scale bakery operations.
- Front-of-pack labeling compliance:Evolving EU Nutri-Score algorithm updates demand continuous reformulation to maintain favorable color-coded ratings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium-Fortified Bread Market |
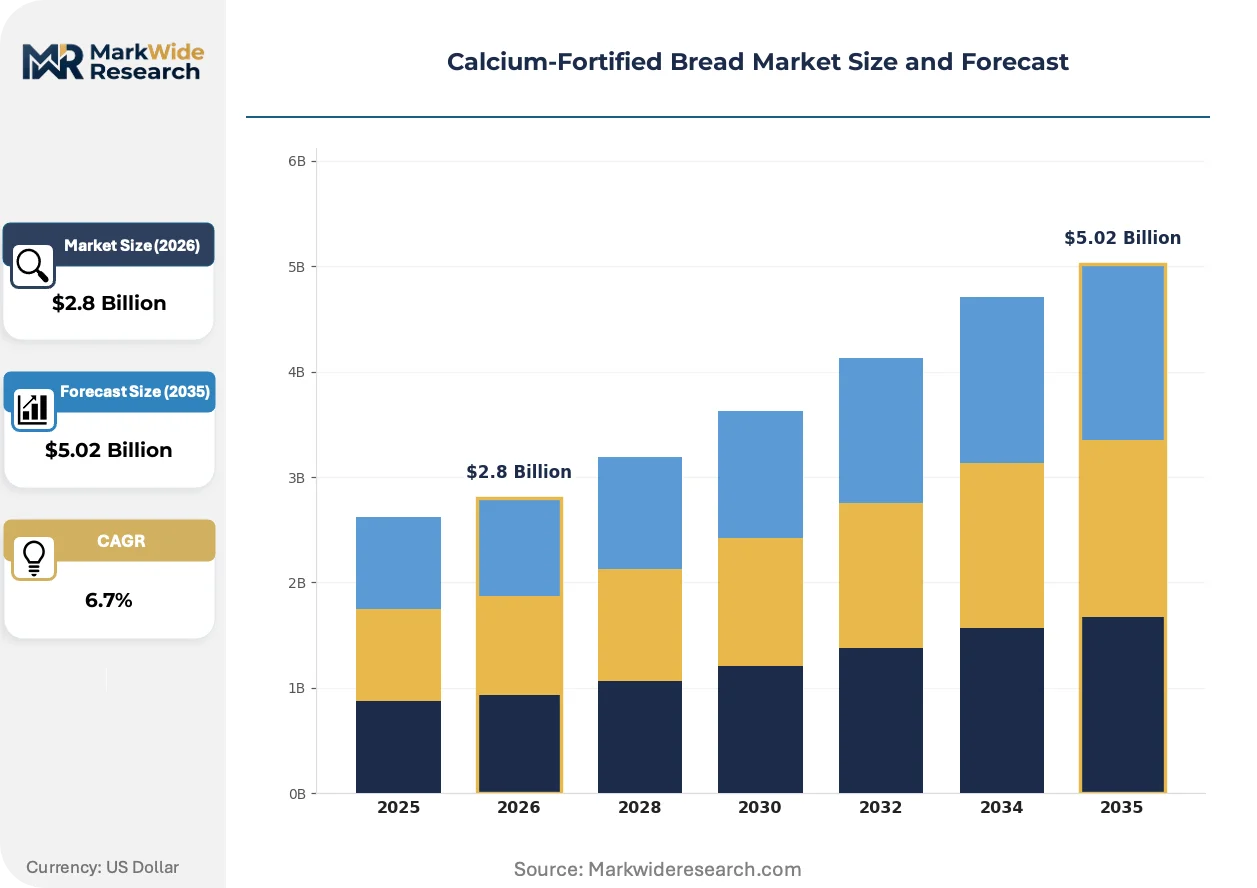
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Grain, White Bread, Sourdough, Multigrain Distribution Channel: Supermarkets, Health Food Stores, Online Retail, Local Bakeries End User: Health-conscious Consumers, Families, Athletes, Elderly Packaging Type: Loaves, Rolls, Bun Packs, Slices |
| Companies Covered | Grupo Bimbo, Associated British Foods PLC, General Mills Inc., Britannia Industries Ltd., Barilla G. e R. Fratelli S.p.A., Dawn Food Products, Inc., Yamazaki Baking Co. Ltd, Finsbury Food Group Plc, Modern Food Enterprises Private Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium-Fortified Bread Market Evolving Landscape
Microencapsulation technologies are compressing calcium salt particle sizes to preserve bread texture while maintaining label claim stability through shelf life. Regulatory front-of-pack mandates and procurement model fragmentation are simultaneously reshaping competitive positioning.
Nano-encapsulated calcium carbonate is miniaturizing fortification particle dimensions below 100 nanometers to eliminate grittiness in artisanal sourdough applications. Premium bakery chains in Germany and Switzerland are adopting these systems to maintain mouthfeel parity with unfortified equivalents. The technology is miniaturizing the trade-off between functional claims and sensory quality that previously limited calcium density ceilings.
EFSA's 2023 updated guidance on bone-health claim substantiation requires human intervention studies with validated biomarkers for all new fortified product registrations. This elevates clinical evidence costs for market entrants while grandfathering existing claims for established suppliers. Whole grain and multigrain categories face the steepest compliance burden due to dual positioning requirements.
Health food store buyers are consolidating supplier relationships around single-source accountability for fortification integrity and traceability. Independent retailers in California and New York are displacing multi-brand bread sections with exclusive house-label fortified lines. This concentration is most visible in coastal metropolitan markets where consumer litigation risk around unsubstantiated health claims remains elevated.
Calcium-Fortified Bread Market Segmentation
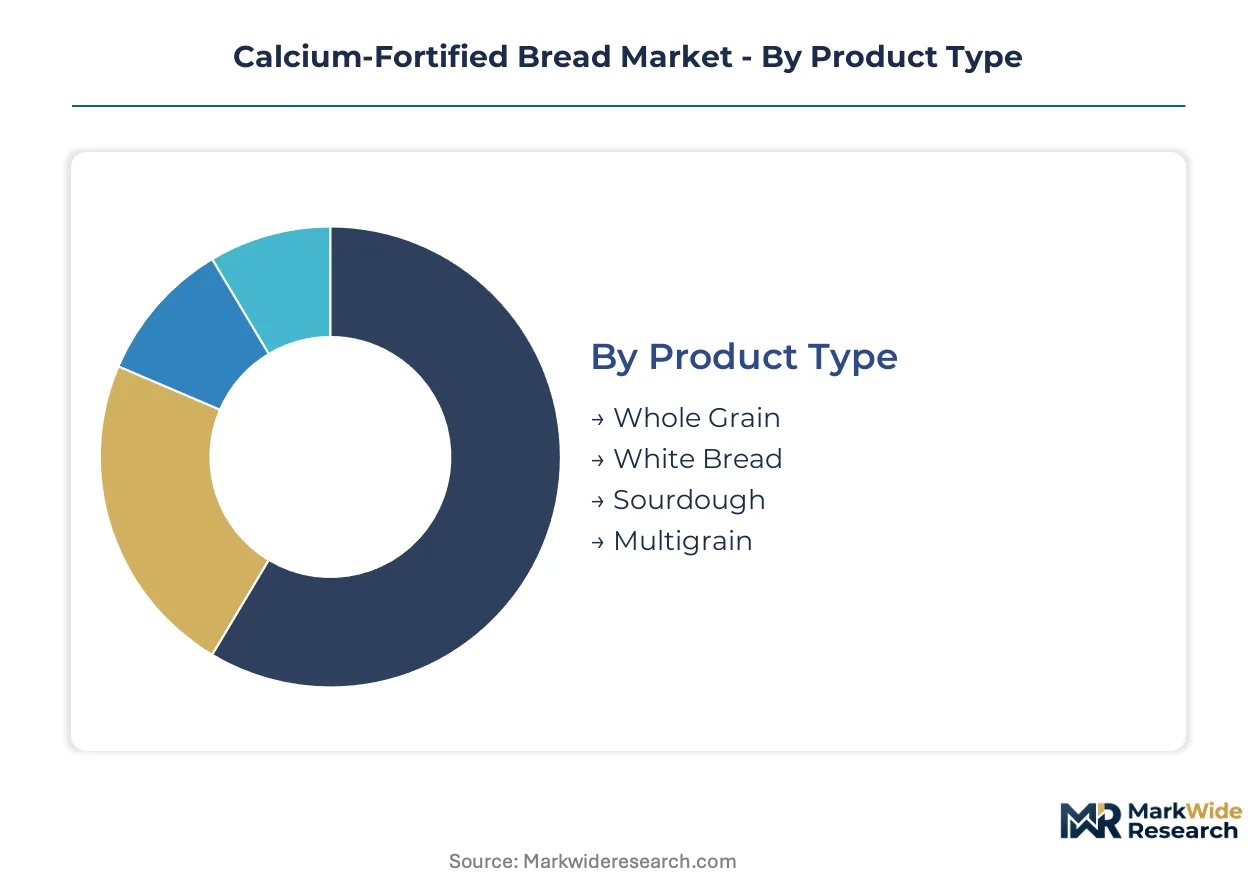
Segmentation in calcium-fortified bread reveals divergent margin architectures across product formats and procurement channels. Manufacturers calibrate calcium density, grain composition, and packaging formats to match distinct consumption occasions and retail environments.
Product Type:
Supermarkets move the highest volumes of standard white and whole grain fortified lines, while health food stores and direct channels concentrate premium multigrain and sourdough variants with elevated calcium specifications.
- Whole Grain:Dual-fortification formulations combine calcium carbonate with intrinsic mineral content from bran and germ fractions. Demand clusters in United States coastal metropolitan markets where Nutri-Score-aligned front-of-pack labeling drives procurement decisions among institutional buyers.
- White Bread:Refined flour bases enable precise calcium salt dispersion and uniform crumb structure. Price-accessible positioning captures family segment volume in Indian urban centers where FSSAI-mandated fortification thresholds apply to subsidized distribution programs.
- Sourdough:Acidic fermentation environments demand microencapsulated calcium systems to prevent salt degradation and preserve leavening integrity. German and Swiss artisanal bakeries pilot nano-encapsulated formats for mouthfeel parity.
- Multigrain:Composite flour matrices with seeds and ancient grains create heterogeneous calcium distribution challenges. EFSA bone-health claim substantiation requirements impose elevated clinical evidence burdens on new entrants.
By volume, White Bread leads. By growth pace, Whole Grain is ahead.
Distribution Channel:
Margin structures stratify sharply between high-throughput mass retail and relationship-driven specialty channels with divergent service requirements.
- Supermarkets:Centralized distribution networks and slotting fee structures favor national suppliers with automated fortification lines and validated shelf-life stability data. United States federal school nutrition contracts flow predominantly through this channel.
- Health Food Stores:Curated assortments emphasize traceability documentation and exclusive house-label relationships. California and New York independent retailers consolidate around single-source accountability for fortification integrity.
- Online Retail:Direct-to-consumer subscription models enable recurring revenue capture through personalized nutrition bundles. Biomarker testing service pairings represent an emerging value-add configuration.
- Local Bakeries:Small-batch production limits calcium salt inventory economies but permits rapid formulation iteration for neighborhood preferences. Fresh-daily positioning commands localized price premiums.
Supermarkets dominate absolute throughput. Online Retail shows the steepest expansion trajectory.
End User:
Demographic targeting determines calcium density specifications, portion sizing, and companion nutrient fortification strategies.
- Health-conscious Consumers:Nutritional transparency demands drive preference for validated bioavailability claims and clean-label calcium sources. EFSA-substantiated bone-health positioning supports premium pricing tolerance.
- Families:Bulk-format purchasing and child-friendly portion sizing prioritize cost efficiency over specification density. Indian price-accessible segments concentrate here.
- Athletes:Recovery-oriented positioning combines calcium fortification with protein enrichment and electrolyte balance. Sports nutrition retail channels and performance-oriented subscription services serve this niche.
- Elderly:Osteoporosis prevention claims and easy-chew texture modifications address swallowing difficulty and medication interaction concerns. United States consumers over 55 represent the core demographic.
Families generate the largest addressable base. The Elderly segment commands the highest per-unit margins.
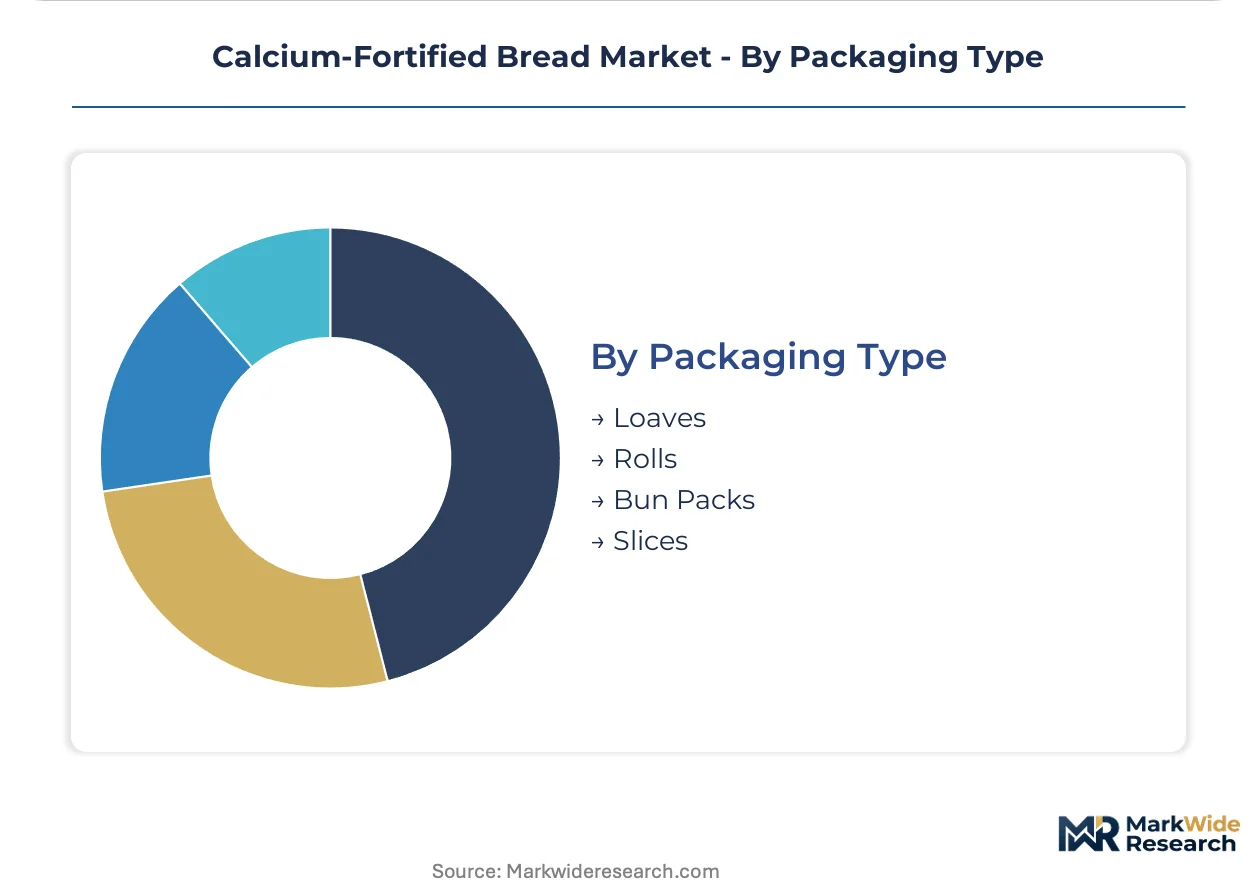
Packaging Type:
Format selection governs calcium stability through distribution, portion control compliance, and consumption occasion matching.
- Loaves:Standard 400-800g formats with modified atmosphere packaging preserve calcium carbonate integrity across 7-14 day shelf life. Mass retail bread aisles allocate primary shelf positioning.
- Rolls:Individual portion sizing aligns with institutional meal tray specifications and school nutrition program procurement standards. Freezer-to-oven compatibility extends service flexibility.
- Bun Packs:Multi-count configurations target family purchasing with per-unit cost efficiency. Hamburger and sandwich bun applications compete with unfortified commodity alternatives.
- Slices:Pre-sliced formats with interleaved packaging reduce handling contamination and enable precise serving-size nutritional declarations. Convenience positioning supports premium pricing in grab-and-go retail.
Loaves anchor volume production. Slices are gaining share fastest in convenience-oriented channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German artisanal bakeries export nano-encapsulated sourdough formulations to Swiss retail chains, establishing a cross-border premium corridor that channels technical innovation into adjacent markets.
United States
School nutrition contracts and aging consumer demand over 55 drive institutional and retail volume. FDA fortification guidelines for grain products enforce bioavailability validation standards. California and New York metropolitan markets concentrate health food store consolidation around single-source fortification accountability.
Germany
Artisanal sourdough premiumization and sustainability-indexed retail procurement shape demand patterns. EFSA bone-health claim substantiation requirements filter market entrants through clinical evidence burdens. Bavaria and Baden-Württemberg host pilot programs for nano-encapsulated calcium systems in traditional bakery applications.
India
Price-accessible family segments and subsidized urban distribution programs anchor volume expansion. FSSAI additive safety thresholds for calcium lactate restrict formulation latitude relative to export markets. Maharashtra and Gujarat industrial corridors attract PLI scheme capital subsidies for automated fortification line deployment.
Switzerland
Coastal metropolitan health-conscious consumers and premium bakery chain expansion sustain per-unit margins. Swissmedic-aligned bioavailability testing standards exceed baseline EFSA requirements. Zurich and Geneva retail clusters pilot carbon-neutral bakery integration paired with calcium fortification positioning.
United Kingdom
Supermarket channel control and Nutri-Score-aligned procurement decisions concentrate volume throughput. EFSA-equivalent health claim frameworks govern bone-health marketing integrity. London and Southeast England health food store networks consolidate exclusive house-label fortified bread relationships.
Calcium-Fortified Bread Market Competitive Landscape
Listed leaders compete with private specialists across manufacturing scale and channel access dimensions, producing a tiered structure where multinational baked goods conglomerates anchor mass retail throughput while regional private operators capture premium artisanal niches. Three archetypes dominate: North American scale players with automated fortification infrastructure, European channel controllers leveraging supermarket exclusivity, and South Asian price-accessible specialists serving subsidized distribution programs. Capacity expansion and strategic portfolio diversification toward dual-health-positioned whole grain lines represent the dominant competitive vectors.
Within the scale-driven tier, Grupo Bimbo and General Mills Inc. exemplify North American manufacturing concentration, while Associated British Foods PLC occupies a position as a European channel anchor. Britannia Industries Ltd. represents the price-accessible specialist archetype serving South Asian family segments through compliant FSSAI formulation thresholds.
| Leading Market Players |
|---|
| Grupo Bimbo |
| Associated British Foods PLC |
| General Mills Inc. |
| Britannia Industries Ltd. |
| Barilla G. e R. Fratelli S.p.A. |
| Dawn Food Products, Inc. |
| Yamazaki Baking Co. Ltd |
| Finsbury Food Group Plc |
| Modern Food Enterprises Private Limited |
| Others |
Value Network & Pricing Analysis
Microencapsulated calcium carbonate displacement of standard fortification salts is simultaneously relocating supply geography toward German and Swiss specialty chemical producers and compressing margin structures for commodity-grade bakers. This substitution dynamic elevates input costs for nano-encapsulated formulations while creating pricing power for technology-licensing suppliers.
Pricing Analysis
Three-tier pricing structure across premium nano-encapsulated, standard microencapsulated, and economy conventional calcium carbonate tiers dominates the market. Price differentiation rests on bioavailability certification grade and sensory quality parity with unfortified equivalents. Cost compression in the economy tier is intensifying because Indian price-accessible segments prioritize FSSAI-compliant thresholds over absorption validation. Families represent the most price-sensitive buyer archetype, while elderly consumers in United States coastal markets demonstrate the least sensitivity.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors constrain just-in-time calcium salt inventory management for European artisanal bakeries. Supply concentration in China for industrial-grade calcium carbonate, Germany for microencapsulation systems, and Switzerland for nano-particle technology creates layered dependency structures. Single-source vulnerability around Chinese mineral processing exposes standard-fortification bakers to input volatility. Distribution runs through centralized supermarket procurement networks in North America, health food store consolidators in California and New York, and subsidized institutional channels in Indian urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The calcium-fortified bread market sits in a post-regulatory-tightening recovery cycle where EFSA and FDA substantiation requirements have cleared marginal competitors, favoring capitalized incumbents with clinical trial capabilities.
For Market Incumbents: Secure exclusive bioavailability certification partnerships with Swissmedic-aligned testing laboratories to preempt competitor claim substantiation. Lock in multi-year calcium carbonate offtake agreements with German chemical suppliers before microencapsulation technology premiums escalate further. Channel control through health food store house-label consolidation in California and New York insulates against private-label erosion. For New Entrants and Emerging Players: Direct-to-consumer subscription bundling with biomarker testing services represents an under-served service layer where Grupo Bimbo and Associated British Foods PLC maintain minimal presence. Target Indian price-accessible segments through PLI scheme-aligned automated fortification lines in Maharashtra and Gujarat industrial corridors. Lead with traceability documentation and single-source accountability narratives that resonate with health food store procurement committees. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors mid-scale regional bakers with validated EFSA claims and automated production infrastructure. Long-term viability hinges on dual-health-positioning capabilities spanning calcium fortification and whole grain credentials. Watch for EFSA algorithm updates on front-of-pack Nutri-Score ratings as the inflection signal requiring portfolio reformulation investments.| Strategic Initiative | Industry Significance |
|---|---|
| Nano-Encapsulation Technology Licensing | Swiss and German bakery chains gain sensory parity premiums in artisanal sourdough segments. |
| EFSA Bone-Health Claim Substantiation | Validated clinical evidence creates defensible pricing power in European supermarket channels. |
| Direct-to-Consumer Subscription Launch | Biomarker testing bundles capture recurring revenue from United States elderly consumers. |
| PLI Scheme Manufacturing Scale-Up | Indian automated fortification lines serve price-accessible family segments through subsidized distribution. |
| Health Food Store Channel Consolidation | Exclusive house-label relationships reduce litigation risk in California and New York metropolitan markets. |
Research Methodology
Desk research of FDA fortification guidelines, EFSA health claim databases, and FSSAI additive safety thresholds preceded structured interviews with bakery R&D directors, supermarket category buyers, health food store procurement managers, and clinical nutrition researchers. Primary fieldwork with German artisanal bakers and Indian industrial bakery operators combined with secondary validation through trade customs data and food processing industry reports. Bottom-up volume modeling across product types and distribution channels triangulated against top-down market sizing from regulatory filings.
Variance decomposition across calcium density specifications, grain composition tiers, and regional regulatory clusters shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include product format, distribution channel structure, end-user demographic targeting, and packaging type. CAGRs derived from growth driver elasticity analysis calibrated against historical school nutrition program procurement volumes and aging demographic intake patterns. Forecast inputs incorporated bioavailability testing standard evolution and front-of-pack labeling mandate implementation timelines.
Forecasts assume regulatory continuity in FDA, EFSA, and FSSAI regimes; material policy shifts would require re-modeling around revised fortification ceilings or substantiation protocols. Calcium carbonate supply disruptions from Chinese industrial mineral markets or nano-encapsulation patent litigation in European jurisdictions represent specific risk factors that could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Delta-Tocopherol Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Calcium-Fortified Cereals Market
Vitamin Fortified
Vitamins Drink Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Food Grade Retinol (Retinene) Market
Vitamin Fortified
Encapsulated Vitamin C Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Ready-To-Use Therapeutic Food and Supplementary Food (RUTF and RUSF) Market
Vitamin Fortified
Feed Grade Vitamin D Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Vitamin K Market