
 Calcium Fortified Juice Market | 2026-2036
Calcium Fortified Juice Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Fortified Juice Market Analytics
The calcium fortified juice category is restructuring around a sharp split between premium cold-pressed offerings with chelated calcium formats and commodity heat-pasteurized lines using standard calcium carbonate. Minute Maid dominates shelf-stable distribution through The Coca-Cola Company's refrigerated logistics network. PepsiCo leverages its Gatorade sports science infrastructure to position fortified juices in athletic recovery. Hain Celestial Group specializes in organic-certified variants that command placement in natural retail channels.
Calcium fortified juice denotes fruit-derived beverages with supplemental calcium compounds, typically tricalcium phosphate or calcium lactate at 100-450 mg per serving, processed through either high-pressure processing or tunnel pasteurization to preserve nutrient stability and sensory profile. The primary commercial purpose is delivering dairy-alternative mineral nutrition to lactose-intolerant consumers, aging populations, and pediatric segments with elevated skeletal development requirements. Orange juice still anchors volume due to established consumer association with breakfast occasion and inherent acidity that masks mineral off-notes. Online Retail represents the fastest-expanding distribution channel, though Supermarkets retain the deepest margin pools through slotting fee structures and promotional calendar control.
The FDA governs nutrient content claims and fortification ceilings under 21 CFR 101, while the USDA National School Lunch Program shapes institutional procurement specifications for child-targeted fortified beverages. China's SAMR enforces GB standards for calcium additive labeling and maximum usage levels in fruit-based drinks. Stakeholders must monitor evolving bioavailability disclosure requirements across multiple jurisdictions and calibrate formulation investments accordingly.
Market Dynamics
The calcium fortified juice market is restructuring around bioavailability disclosure mandates that force manufacturers to abandon standard calcium carbonate in favor of chelated formats with proven absorption rates. This regulatory pressure cascades through formulation pipelines, procurement specifications, and shelf positioning strategies simultaneously.
Growth Catalysts
- Pediatric nutrition mandates:USDA National School Lunch Program procurement specifications now require calcium fortification in reimbursable beverages, institutionalizing volume commitments across district-level contracts.
- Lactose intolerance prevalence:Diagnostic thresholds in East Asian populations are driving dairy-alternative mineral sourcing, with calcium-fortified orange juice capturing breakfast occasion substitution.
- Cold-press technology maturation:High-pressure processing equipment costs have declined sufficiently to enable regional co-packing networks, expanding premium shelf space without capital-intensive plant builds.
Market Restraints
- Citrus input volatility:Florida orange crop yields fluctuate with hurricane frequency and citrus greening disease pressure, compressing margin predictability for concentrate-dependent producers.
- Calcium salt supply concentration:Food-grade tricalcium phosphate production clusters in Chinese phosphate mining regions, exposing formulation costs to export licensing shifts under SAMR industrial policy.
- Mineral precipitation limits:Calcium fortification ceilings in acidic matrices create formulation trade-offs between nutrient density and shelf-stable suspension stability.
Strategic Opportunities
- Sports recovery positioning:Athletic channel penetration remains underdeveloped relative to protein beverages, creating white space for mineral-electrolyte hybrid formulations targeting post-exercise consumption.
- Geriatric nutrition programs:Japan's METI silver economy initiatives subsidize functional food development for osteoporosis prevention, opening reimbursement pathways for clinically positioned fortified juices.
- Direct-to-subscription models:Cold-chain logistics improvements enable recurring delivery of fresh-pressed fortified variants, bypassing slotting fee barriers in conventional retail.
Industry Challenges
- Bioavailability validation capacity:Clinical substantiation of calcium absorption claims requires isotope tracer studies that few manufacturers maintain in-house, creating bottlenecks for regulatory submissions.
- Refrigerated distribution fragmentation:Last-mile cold-chain integrity varies dramatically between urban consolidation centers and rural independent grocers, constraining premium product reach.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Fortified Juice Market |
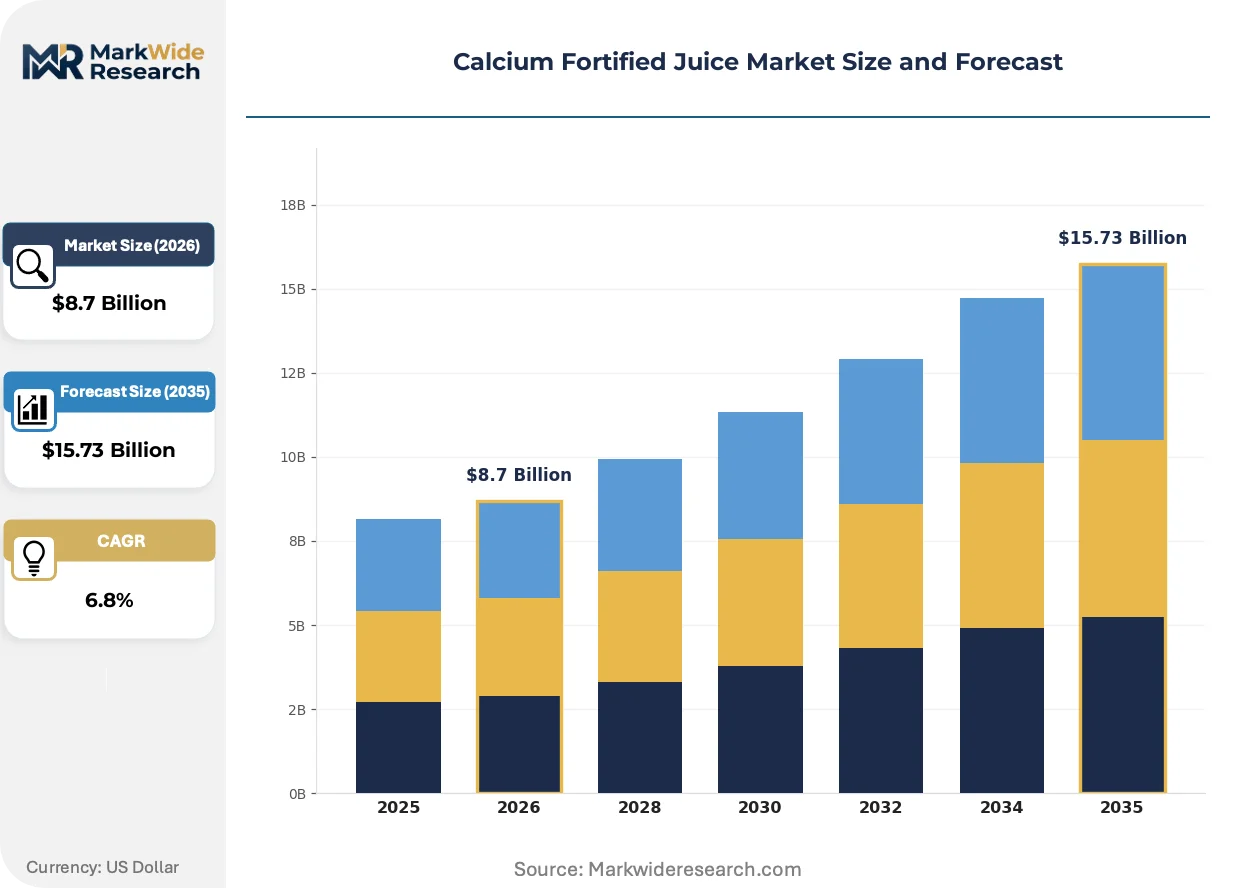
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Orange, Apple, Mango, Mixed Fruit Distribution Channel: Supermarkets, Convenience Stores, Health Food Stores, Online Retail Packaging Type: Bottles, Tetra Packs, Cans, Pouches Consumer Age Group: Children, Teens, Adults, Seniors |
| Companies Covered | Minute Maid, Ceres Fruit Juices, The Coca-Cola Company, Cutrale Group, Eckes-Granini Group, PepsiCo, Hain Celestial Group, Archer Daniels Midland Company, Tropicana Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Fortified Juice Market Evolving Landscape
Reformulation science is displacing commodity fortification approaches across the calcium fortified juice category. Manufacturers now compete on absorption metrics rather than milligram declarations, reshaping R&D priorities and supplier selection criteria.
Chelated calcium formats utilizing calcium bisglycinate and calcium citrate malate are rewriting competitive positioning in the premium segment. Sports nutrition buyers and geriatric health programs are adopting these formats at accelerating rates despite 40-60% ingredient cost premiums. The technology is compressing market share for legacy carbonate-fortified lines that cannot substantiate absorption equivalence.
China's SAMR enforcement of GB standards for calcium additive labeling is tightening disclosure requirements for bioavailability claims. Manufacturers must now substantiate mineral absorption rates through clinical data or forfeit functional positioning. The regulation most affects imported brands targeting China's urban middle-class, forcing reformulation partnerships with domestic clinical research organizations.
Subscription-based replenishment models are capturing household pantry share from intermittent supermarket purchasing. Direct-to-consumer channels now coordinate delivery cadence with consumption velocity data, replacing promotional calendar dependence with predictable revenue streams. This behavioral shift concentrates in coastal Chinese cities and North American metropolitan corridors with mature cold-chain infrastructure.
Calcium Fortified Juice Market Segmentation
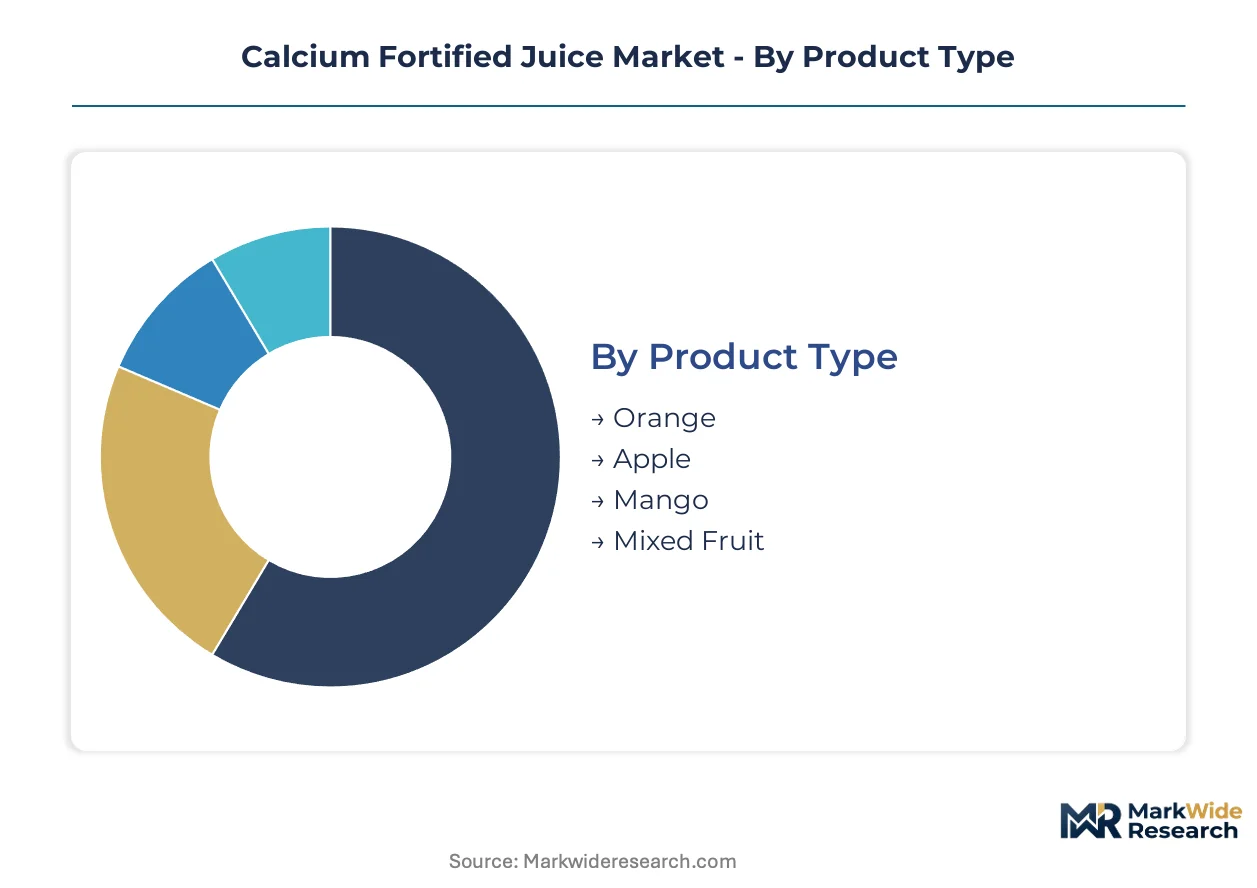
Calcium fortified juice manufacturers calibrate formulation, packaging, and channel strategies against sharply divergent consumer physiology and purchasing contexts. Segmentation discipline separates commodity volume plays from premium absorption-optimized offerings in this restructuring market.
Product Type:
Supply concentration in Florida citrus groves and Brazilian orange concentrate processing tilts competitive advantage toward established orange juice incumbents with backward-integrated sourcing.
- Orange:Natural acidity masks calcium carbonate off-notes without expensive chelation, preserving margin structure for heat-pasteurized shelf-stable lines. USDA National School Lunch Program procurement specifications anchor institutional volume in U.S. district cafeterias, where breakfast occasion habituation drives pediatric consumption.
- Apple:Milder pH demands citrate-malate or bisglycinate chelation to prevent precipitation and metallic aftertaste, elevating ingredient costs 40-60% above carbonate formulations. China's urban middle-class households in Shanghai and Beijing are shifting from traditional soy milk to packaged fortified apple juice as dairy-alternative breakfast options.
- Mango:Pulp viscosity complicates suspension stability for calcium salts, requiring hydrocolloid stabilization systems that extend label declarations. Indian and Southeast Asian export processing zones concentrate aseptic mango puree supply.
- Mixed Fruit:Flavor complexity permits masking of lower-bioavailability carbonate forms, enabling cost-tier stratification across retail channels.
Today's leader: Orange. Tomorrow's challenger: Apple.
Distribution Channel:
Margin capture varies dramatically between slotting-fee-dependent conventional retail and emerging direct-to-consumer models with recurring revenue predictability.
- Supermarkets:Refrigerated case placement commands 15-25% slotting fees as percentage of wholesale value, concentrating volume for Coca-Cola and PepsiCo with captive logistics infrastructure. Promotional calendar control by retail buyers compresses manufacturer pricing power during key consumption periods.
- Online Retail:Subscription replenishment models coordinate delivery cadence with household consumption velocity data, bypassing slotting barriers. Cold-chain logistics maturation in North American metropolitan corridors and coastal Chinese cities enables fresh-pressed fortified variant penetration.
- Convenience Stores:Impulse purchase occasions favor single-serve shelf-stable formats with extended ambient temperature tolerance.
- Health Food Stores:Organic-certified and cold-pressed positioning commands 30-50% price premiums through educated consumer self-selection.
Online Retail gains share fastest. Supermarkets retain deepest margin pools.
Packaging Type:
Barrier properties and cold-chain compatibility requirements segment manufacturing investment between ambient distribution and refrigerated freshness positioning.
- Bottles:PET and HDPE formats dominate refrigerated case presentation, with light-blocking additives preserving vitamin stability in fluorescent retail environments. High-pressure processing compatibility enables premium cold-pressed positioning.
- Tetra Packs:Aseptic carton technology enables ambient distribution with 12-month shelf life, concentrating supply among Swedish and Swiss packaging equipment licensors with regional filling plant networks.
- Cans:Aluminum supply volatility and internal lacquer requirements for acidified beverages elevate minimum efficient scale thresholds.
- Pouches:Flexible format reduces shipping cube and material cost for institutional foodservice bulk dispensing.
Tetra Packs anchor volume economics. Bottles carry premium positioning.
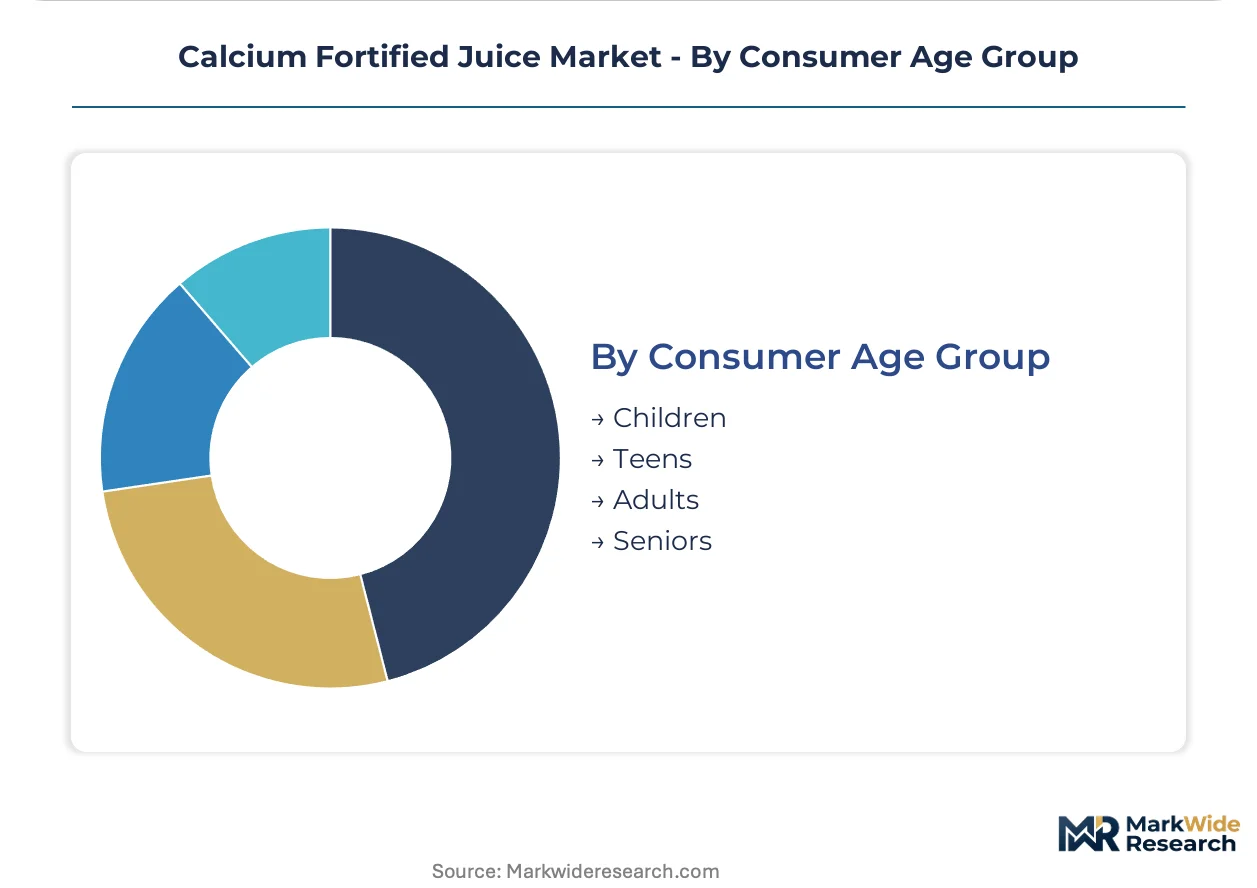
Consumer Age Group:
Physiological calcium requirements and purchasing decision autonomy create divergent formulation and marketing investment priorities across life stages.
- Children:Skeletal development requirements drive 1000-1300 mg daily intake recommendations, with palatability engineering masking mineral presence through flavor systems. USDA school nutrition mandates institutionalize volume through district-level procurement.
- Seniors:Osteoporosis prevention positioning requires clinical bioavailability substantiation that few manufacturers maintain in-house, creating competitive moats for brands with isotope tracer study capabilities. Japan's METI silver economy subsidies open reimbursement pathways for clinically validated formulations.
- Adults:Lactose intolerance prevalence in East Asian populations drives breakfast occasion substitution behavior.
- Teens:Peak bone mass accumulation period combines with limited independent purchasing power, creating household gatekeeper influence dynamics.
Children segment commands institutional volume. Seniors segment unlocks reimbursement premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's urban middle-class households are shifting from traditional soy milk to packaged fortified juices at a faster clip than U.S. school nutrition programs are institutionalizing volume. This divergence in demand drivers is reshaping where manufacturers allocate formulation investments and cold-chain infrastructure.
United States
The USDA National School Lunch Program procurement specifications anchor institutional volume through district-level contracts covering breakfast occasion habituation. FDA's updated Nutrition Facts label requirements under 21 CFR 101 are prompting reformulation with bioavailable calcium salts. Florida citrus groves concentrate concentrate-dependent supply, though hurricane frequency and citrus greening disease pressure compress margin predictability.
China
Urban middle-class households in Shanghai and Beijing are shifting from traditional soy milk to packaged fortified apple juice as dairy-alternative breakfast options. SAMR enforcement of GB standards for calcium additive labeling is tightening disclosure requirements for bioavailability claims. Yangtze River Delta processing clusters are expanding high-pressure processing co-packing networks to serve premium cold-pressed demand.
Japan
METI silver economy initiatives subsidize functional food development for osteoporosis prevention, opening reimbursement pathways for clinically positioned fortified juices targeting seniors. The country's aging population drives physiological calcium requirements that exceed typical dietary intake. Kanto region metropolitan corridors concentrate direct-to-subscription model adoption with mature cold-chain infrastructure.
Germany
EFSA nutrient content claim regulations shape fortification ceilings and bioavailability disclosure standards for products distributed across EU member states. Organic-certified variant demand concentrates in natural retail channels with educated consumer self-selection. Bavaria and North Rhine-Westphalia anchor aseptic carton filling plant networks licensed from Swedish and Swiss packaging equipment providers.
Brazil
Lactose intolerance prevalence in urban populations drives dairy-alternative mineral sourcing through breakfast occasion substitution behavior. ANVISA governs nutrient content claims and maximum usage levels for calcium additives in fruit-based drinks. São Paulo state processing zones concentrate aseptic mango puree supply for pulp-viscosity fortified formulations.
Calcium Fortified Juice Market Competitive Landscape
Top-tier vendors anchor shelf-stable distribution through captive refrigerated logistics networks, while mid-tier specialists occupy premium cold-pressed positioning through regional co-packing arrangements. The vendor base stratifies across three archetypes: beverage conglomerates with backward-integrated citrus sourcing, organic-certified specialists commanding natural channel placement, and sports nutrition crossovers leveraging electrolyte science infrastructure. Dominant competitive moves include portfolio diversification into chelated calcium formats and strategic partnerships with clinical research organizations for bioavailability substantiation.
Among U.S.-based beverage conglomerates, The Coca-Cola Company and PepsiCo exemplify scale-driven archetypes with logistics infrastructure that constrains premium product reach for smaller competitors. Hain Celestial Group occupies a position within the organic-certified specialist tier, representing the natural retail channel positioning that commands price premiums through educated consumer self-selection. These three entities illustrate how competitive advantage in this market flows from either captive distribution scale or certification-driven channel access rather than formulation technology alone.
| Leading Market Players |
|---|
| Minute Maid |
| Ceres Fruit Juices |
| The Coca-Cola Company |
| Cutrale Group |
| Eckes-Granini Group |
| PepsiCo |
| Hain Celestial Group |
| Archer Daniels Midland Company |
| Tropicana Products |
| Others |
Value Network & Pricing Analysis
USDA National School Lunch Program procurement specifications for calcium fortification are compressing supplier margins while forcing manufacturers to absorb higher chelated calcium salt costs, creating divergence between institutional contract pricing and premium retail tiers.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for high-pressure processed fortified juices. Three-tier pricing structure across premium, standard, and economy levels separates cold-pressed chelated formats from heat-pasteurized carbonate lines and private-label commodity offerings. Price differentiation hinges on bioavailability certification status and refrigerated distribution reach. Cost compression in shelf-stable carbonate tiers is intensifying because Florida citrus input volatility and Chinese phosphate export licensing shifts feed raw material uncertainty. Institutional buyers in U.S. school districts exhibit highest price sensitivity, while Japan's METI-subsidized geriatric nutrition programs show lowest sensitivity due to reimbursement coverage.
Supply Chain Analysis
Food-grade tricalcium phosphate supply rests on Chinese phosphate mining regions, Brazilian orange concentrate processing clusters, and Florida citrus grove networks. Raw material dependencies span calcium salt precursors, aseptic mango puree from Indian export zones, and hydrocolloid stabilization systems. Single-source vulnerability concentrates in SAMR-regulated calcium additive licensing, where export permission shifts disrupt formulation costs abruptly. Distribution runs through Coca-Cola and PepsiCo captive refrigerated logistics networks for conventional retail, with emerging direct-to-subscription cold-chain models bypassing slotting fee structures in coastal Chinese and North American metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's tightening GB standards for calcium additive labeling create a geographic-arbitrage opportunity: manufacturers with clinical bioavailability substantiation capabilities capture premium positioning unavailable to carbonate-dependent competitors facing reformulation mandates.
For Market Incumbents: Acquire cold-press high-pressure processing capacity in regional co-packing networks to defend against sports nutrition crossovers leveraging electrolyte science infrastructure. Secure backward integration into chelated calcium salt supply through partnerships with Chinese clinical research organizations, insulating formulation costs from SAMR export licensing volatility while building absorption claim substantiation moats. For New Entrants and Emerging Players: Direct-to-subscription replenishment models offer the most penetrable route for fresh-pressed fortified variants, targeting lactose-intolerant East Asian households in Shanghai and Beijing breakfast occasions. Bypass slotting fee barriers through cold-chain logistics partnerships with mature metropolitan infrastructure providers, positioning chelated apple juice as soy milk replacement with household consumption velocity data driving delivery cadence. For Investors and Strategic Acquirers: Asymmetric upside sits with organic-certified specialists commanding natural retail channel placement and clinical research organization partnerships for bioavailability validation. Long-term viability over a multi-year window favors targets with isotope tracer study capabilities and METI silver economy reimbursement pathway access. Watch for FDA enforcement shifts on 21 CFR 101 nutrient content claims as inflection indicator for reformulation investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Chelated Calcium Format Transition | Repositions manufacturers for SAMR bioavailability disclosure mandates and premium segment capture. |
| Direct-to-Subscription Launch | Bypasses supermarket slotting fees through cold-chain logistics coordination in metropolitan corridors. |
| Clinical Research Organization Partnership | Enables isotope tracer study capabilities required for Japan METI geriatric nutrition reimbursement. |
| Regional Co-Packing Network Expansion | Extends high-pressure processing reach without capital-intensive plant builds in Yangtze River Delta. |
| USDA School Nutrition Contract Pursuit | Institutionalizes volume through district-level procurement specifications for pediatric breakfast occasions. |
Research Methodology
Multiple input streams — regulatory filing analysis, trade customs data, and channel inventory audits — were reconciled across primary interviews with beverage formulation scientists, refrigerated logistics operators, and school district procurement officers, combined with secondary validation from FDA 21 CFR 101 guidance documents, SAMR GB standard publications, and USDA National School Lunch Program procurement databases. Bottom-up demand modeling triangulated against top-down market sizing from Nielsen retail audit data and cold-chain logistics capacity disclosures.
Data-stream reconciliation anchored volume and value projections across the analysis window through segmentation by product type, distribution channel, packaging format, and consumer age group. CAGRs derived from fitted growth curves incorporating pediatric nutrition mandate expansion rates, lactose intolerance diagnostic thresholds in East Asian populations, and high-pressure processing equipment cost decline trajectories. Industry-specific inputs included Florida citrus crop yield volatility indices and Chinese phosphate export licensing frequency.
The model assumes a particular technology adoption path; alternative pathways for cold-press high-pressure processing versus tunnel pasteurization would alter the outlook for premium shelf space allocation and bioavailability claim substantiation requirements. Forecasts reflect assumptions on SAMR enforcement consistency, METI subsidy continuity, and Florida hurricane frequency patterns. A small set of named triggers — citrus greening disease severity, Chinese industrial policy shifts, and FDA label rule finalization — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Natural Vitamins Market
Vitamin Fortified
Sodium Ascorbate Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Natural Source Vitamin E Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Tocopherols Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Vitamin D3 Oil Market
Vitamin Fortified
Fortified Yeast Market