
 Weight Loss Supplements Market | 2026-2036
Weight Loss Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Weight Loss Supplements Market Intelligence
Personalized nutrition algorithms is fragmenting how weight loss supplements are formulated and distributed, shifting from mass-market SKUs to microbiome-matched and DNA-informed products. Herbalife Nutrition Ltd. leverages its direct-selling infrastructure across emerging markets to sustain recurring revenue streams. Glanbia PLC anchors its position through backward integration into whey protein and peptide supply chains. Abbott competes in the clinical nutrition crossover segment, where medical credibility commands premium positioning.
Weight loss supplements comprise orally administered formulations containing active compounds such as caffeine, green tea extract, conjugated linoleic acid, or glucomannan, designed to elevate energy expenditure, reduce caloric intake, or alter macronutrient absorption. Fat burners and thermogenics dominate current volume, though meal replacements capture disproportionate margin through subscription-based replenishment models. Natural and herbal ingredient sourcing is accelerating fastest among synthetic alternatives as clean-label scrutiny intensifies across retail and e-commerce channels. Gummies and liquid formats are displacing traditional pills among younger demographics seeking convenience and palatability.
The FDA's New Dietary Ingredient notification framework and cGMP enforcement actions constrain market entry for unvalidated formulations, while the FTC actively prosecutes unsubstantiated weight-loss claims in digital advertising. EFSA's health claim authorization process in Europe creates parallel compliance thresholds for brands seeking cross-border expansion. Stakeholders must monitor how AI-driven personalization intersects with evolving substantiation requirements for structure-function claims.
Market Dynamics
Personalized microbiome testing and DNA-informed formulation are fragmenting mass-market weight loss supplement production, forcing manufacturers to retool from batch-scale to individualized fulfillment infrastructure.
Growth Catalysts
- Fitness app integration:Wearable data streams from Strava, MyFitnessPal, and Apple Health create real-time dosage adjustment protocols. Subscription algorithms now auto-replenish based on user biometrics rather than fixed schedules.
- FDA cGMP enforcement tightening:Enhanced facility inspections and certificate revocations are culling marginal producers. Compliant manufacturers capture shelf space vacated by delisted competitors in mass retail and pharmacy channels.
- Gym ecosystem embedding:Equinox, Life Time, and boutique studios now white-label co-branded supplement lines. Point-of-sale placement at fitness facility exits converts workout endorphins into immediate purchase behavior.
Market Restraints
- Raw material concentration:China dominates green tea extract and glucomannan supply chains. Geopolitical friction or export licensing shifts disrupt formulation continuity for US and European brands.
- Clinical substantiation costs:Structure-function claims require human trials for FTC defensibility. Small and mid-tier manufacturers lack capital to fund placebo-controlled studies on novel botanical compounds.
- Physician skepticism:Medical professionals counsel patients against unregulated thermogenics. This professional resistance constrains pharmacy channel penetration and insurance-adjacent wellness program inclusion.
Strategic Opportunities
- India regulatory opening:FSSAI's streamlined health supplement notification pathway reduces time-to-market versus legacy drug-style approvals. Domestic contract manufacturers now offer turnkey regulatory submission services.
- GLP-1 adjacency positioning:Semaglutide and tirzepatide users seek complementary metabolic support. Brands formulating for appetite management during drug tapering capture a patient population exiting prescription protocols.
- Biometric-locked dispensing:Smart pill bottles paired with continuous glucose monitors enable outcome-verified replenishment. This hardware-software convergence creates switching costs and subscription stickiness.
Industry Challenges
- Clean-label verification gaps:Third-party testing for heavy metals, adulterants, and label claim accuracy requires 6-12 week laboratory turnaround. Batch release delays compress effective shelf life and working capital cycles.
- Talent scarcity in computational biology:Microbiome-matched formulation demands rare cross-training in nutraceutical chemistry and bioinformatics. Compensation premiums for these hybrid scientists strain R&D operating budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Weight Loss Supplements Market |
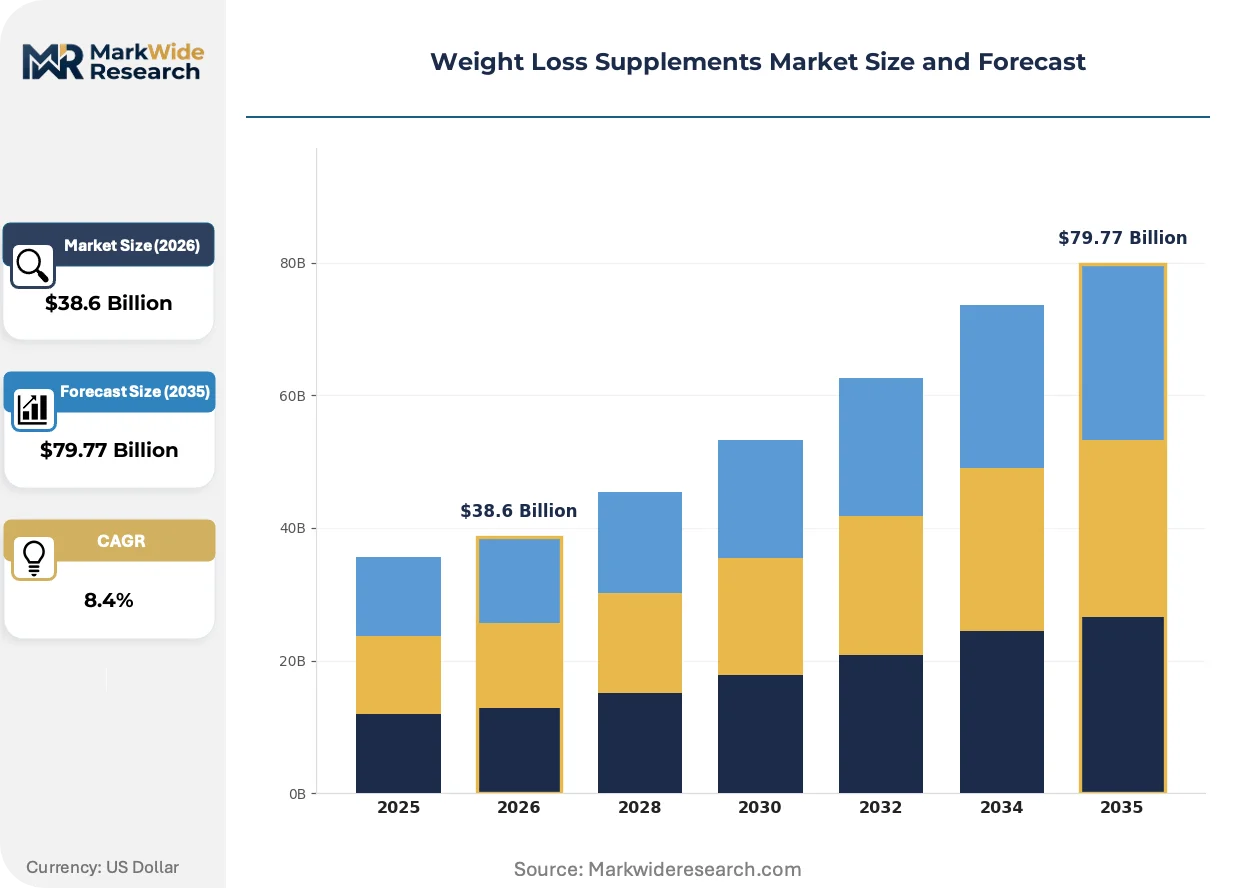
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fat Burners, Appetite Suppressants, Thermogenics, Meal Replacements Ingredient Source: Natural, Synthetic, Herbal, Amino Acids Form: Pills, Powders, Liquids, Gummies Target Demographic: Adults, Athletes, Seniors, Women |
| Companies Covered | Herbalife Nutrition Ltd., Glanbia PLC, GNC Holdings, LLC, Nestle, Amway Corp., GlaxoSmithKline PLC, Abbott, Ajinomoto Co. Inc., NutriSport Pharmacal, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Weight Loss Supplements Market Strategic Shifts & Innovations
Artificial intelligence and connected health hardware are collapsing the latency between biometric signal and personalized nutrient delivery, restructuring how weight management products reach consumers.
Metabolomics-based recommendation engines analyze continuous glucose monitor and microbiome sequencing data to generate individualized ingredient stacks. Wellness platforms including Zoe and Viome license these algorithms to supplement brands for white-label deployment. This data layer is digitizing the transition from static SKUs to dynamic, subscriber-locked formulations that adjust monthly based on metabolic feedback.
EFSA's 2024 guidance on botanical health claims tightens evidentiary standards for European market access. Brands must now submit human intervention studies rather than mechanistic plausibility arguments. German and French regulators are cross-referencing these submissions, creating a centralized compliance bottleneck that favors well-capitalized players with existing clinical trial infrastructure.
Direct-to-consumer brands now bypass retail slotting fees entirely through TikTok Shop and Instagram Checkout integration. Influencer-led live commerce converts engagement into immediate purchase without warehouse intermediation. This channel compression is most advanced in the United States, where creator economy infrastructure and same-day fulfillment networks enable impulse replenishment at scale.
Weight Loss Supplements Market Segmentation
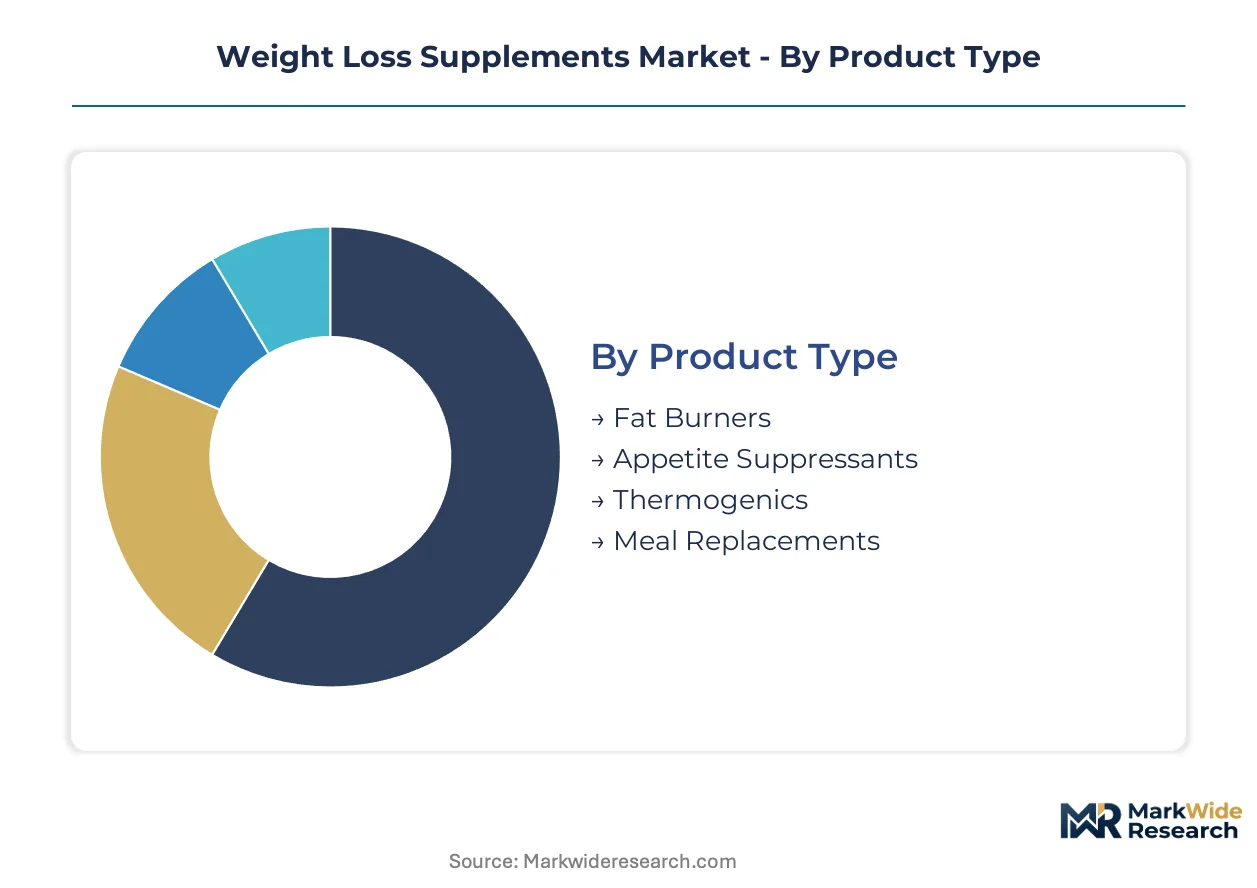
Segmentation in weight loss supplements determines formulation complexity, regulatory pathway, and channel strategy. Product type dictates manufacturing infrastructure requirements. Ingredient sourcing shapes clean-label positioning and supply chain geography. Form factor influences packaging automation and shelf-life engineering. Demographic targeting drives marketing spend allocation and influencer partnership selection.
Product Type:
After-sales engagement intensity varies sharply across product categories, with subscription-dependent formats demanding proactive replenishment management and biometric feedback loops.
- Fat Burners:Caffeine-based and thermogenic compound formulations elevate basal metabolic rate through sympathetic nervous system activation. Demand concentrates in United States gym ecosystems and CrossFit affiliate networks, where pre-workout stacking rituals normalize multi-supplement regimens. Regulatory scrutiny from FDA on synephrine and yohimbine concentrations constrains formulation flexibility.
- Meal Replacements:Macronutrient-complete powders and ready-to-drink shakes deliver caloric deficit through portion-controlled nutrition. Subscription auto-replenishment dominates United States direct-to-consumer channels, with algorithms adjusting flavor variety and serving frequency based on weight trajectory data. Margin profiles exceed standard supplements due to recurring revenue predictability and lower customer acquisition costs.
- Appetite Suppressants:Glucomannan and 5-HTP formulations modulate satiety signaling through gastric distension and serotonergic pathways.
- Thermogenics:Capsaicin and green tea catechin blends increase energy expenditure through brown adipose tissue activation and mitochondrial uncoupling.
Fat burners hold the largest share; momentum sits with meal replacements.
Ingredient Source:
Raw material provenance determines regulatory classification, label claim substantiation burden, and EFSA health claim eligibility across European markets.
- Natural:Plant-derived extracts from green coffee, Garcinia cambogia, and forskolin root command clean-label premiums in United States natural retail channels. Supply chain traceability requirements from Whole Foods Market and Sprouts Farmers Market mandate third-party organic certification and heavy metals testing.
- Herbal:Traditional botanical preparations including hoodia gordonii and bitter orange extract leverage ethnobotanical credibility in Asian markets. India's FSSAI notification pathway for Ayurvedic-derived supplements accelerates time-to-market versus novel synthetic compounds.
- Synthetic:Laboratory-synthesized molecules including conjugated linoleic acid isomers and chromium picolinate enable precise dosing standardization.
- Amino Acids:L-carnitine and L-tyrosine formulations support fat oxidation and thyroid hormone synthesis in athletic populations.
Natural sourcing commands premium positioning; herbal ingredients are climbing the fastest in emerging market penetration.
Form:
Manufacturing capital allocation diverges across delivery technologies, with gummy production requiring starch molding infrastructure distinct from tablet compression lines.
- Gummies:Gelatin and pectin-based chewable matrices mask bitter actives through flavor engineering and sugar alcohol sweetening. United States millennial and Gen Z consumers in TikTok-driven discovery channels demonstrate highest willingness-to-pay for palatability-convenience tradeoffs.
- Pills:Two-piece hard capsules and film-coated tablets dominate pharmacy channel distribution and clinical trial placebo matching. German and French retail pharmacies maintain strict documentation requirements for solid dosage form stability data.
- Powders:Bulk scoop-and-mix formats enable flexible dosing titration and flavor customization in shaker bottle consumption rituals.
- Liquids:Ready-to-drink shots and concentrates deliver rapid absorption claims for pre-workout timing protocols.
Pills retain institutional channel dominance; gummies show steepest expansion trajectory in direct-to-consumer acquisition.
Target Demographic:
Customer lifetime value calculations vary by cohort, with athlete segments showing highest purchase frequency and seniors demonstrating superior subscription retention.
- Athletes:Competition-tested formulations prioritize NSF Certified for Sport and Informed Sport third-party verification to avoid WADA-prohibited substance contamination. United States collegiate and professional sports programs mandate these certifications for locker room access.
- Women:Iron-fortified and hormone-aware formulations address menstrual cycle metabolic variation and postpartum weight management. Influencer marketing through Instagram and Pinterest drives discovery in United States suburban demographics.
- Adults:General population targeting emphasizes BMI reduction and metabolic syndrome prevention in employer wellness programs.
- Seniors:Sarcopenia-conscious protein integration and medication interaction screening address polypharmacy safety concerns.
Adults represent the broadest addressable base; athletes deliver highest per-capita expenditure and brand advocacy velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports green tea extract and glucomannan to United States and European formulation facilities, creating supply chain dependencies that shape regional market dynamics. Regulatory divergence between FDA notification requirements and EFSA health claim standards fragments product development timelines across destination markets.
United States
Direct-to-consumer subscription models and influencer marketing on TikTok Shop drive channel innovation. FDA cGMP enforcement actions and FTC prosecution of unsubstantiated claims constrain marginal producers. California and New York metro areas concentrate wellness startup headquarters and third-party testing laboratories.
Germany
Pharmacy channel dominance and consumer preference for clinical substantiation elevate quality thresholds. EFSA health claim authorization and BfR safety assessments create compliance bottlenecks for botanical entrants. Bavaria hosts contract manufacturing clusters serving cross-border European distribution.
China
Domestic demand for herbal-derived supplements accelerates through Tmall and JD Health platforms. SAMR registration requirements for imported health foods extend time-to-market versus domestic Ayurvedic-style approvals. Zhejiang and Fujian provinces anchor green tea extract processing infrastructure.
India
FSSAI's streamlined health supplement notification pathway attracts contract manufacturing investment from Western brands. Ayurvedic ingredient credibility supports export positioning to Southeast Asian diaspora markets. Maharashtra and Gujarat house turnkey regulatory submission services and formulation facilities.
United Kingdom
Post-Brexit divergence from EU health claim frameworks creates parallel compliance tracks for brands. MHRA borderline determinations between food supplements and medicines generate regulatory uncertainty. London concentrates direct-to-consumer brand headquarters and influencer marketing agencies.
Weight Loss Supplements Market Key Industry Players
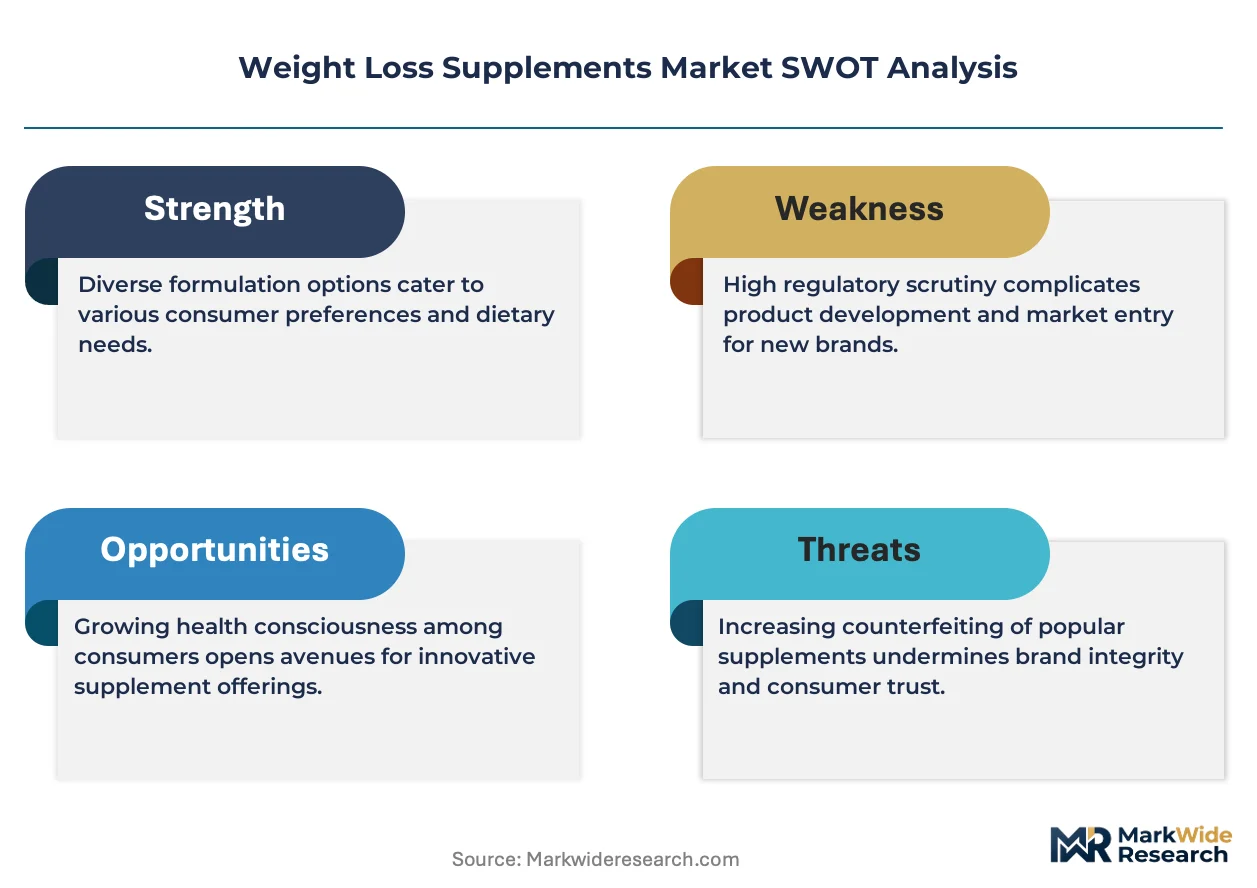
Channel-controlling players compete with product-specialist players across divergent margin structures. The market exhibits tiered consolidation with multinational nutrition conglomerates commanding pharmacy and mass retail shelf space while direct-selling networks sustain recurring revenue in emerging markets. Strategic archetypes include vertically integrated ingredient suppliers, direct-selling infrastructure operators, and clinical nutrition crossovers. Competitive moves center on backward integration into raw material supply chains and biometric-locked subscription technology partnerships.
Among direct-selling infrastructure operators, Herbalife Nutrition Ltd. and Amway Corp. exemplify network-based distribution models that bypass traditional retail slotting fees. Glanbia PLC represents vertically integrated ingredient suppliers with captive whey protein and peptide production. Abbott occupies the clinical nutrition crossover position where medical credibility commands premium pricing in pharmacy-adjacent channels.
| Leading Market Players |
|---|
| Herbalife Nutrition Ltd. |
| Glanbia PLC |
| GNC Holdings, LLC |
| Nestle |
| Amway Corp. |
| GlaxoSmithKline PLC |
| Abbott |
| Ajinomoto Co. Inc. |
| NutriSport Pharmacal, Inc. |
| Others |
Cost & Logistics Intelligence
Overcapacity in Chinese green tea extract processing facilities is compressing raw material quotations and forcing US and European brands to renegotiate annual supply agreements on cost-plus terms indexed to agricultural commodity benchmarks.
Pricing Analysis
Cost-plus contracts with green tea extract indexation dominate procurement between Chinese processors and Western formulation houses. Pricing stratifies across premium, standard, and economy tiers based on third-party certification grade and subscription bundling intensity. Pricing pressure stems from FDA cGMP compliance costs that marginal producers cannot absorb. Direct-to-consumer subscribers show lowest price sensitivity; mass retail private-label buyers demonstrate highest.
Supply Chain Analysis
Upstream feedstock cultivation centers on China for green tea catechins and glucomannan, India for Ayurvedic botanicals, and New Zealand for whey protein isolates. Formulation depends on extraction and drying infrastructure concentrated in Zhejiang province, Maharashtra state, and Bavaria. Single-source vulnerability in Chinese polyphenol supply creates disruption exposure from export licensing shifts. Distribution runs through direct-to-consumer subscription platforms and pharmacy wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GLP-1 drug adjacency and AI-driven personalization are disrupting traditional mass-market formulation, creating openings for biometric-locked subscription models that incumbent infrastructure cannot easily replicate.
For Market Incumbents: Pre-empt direct-to-consumer challengers by acquiring microbiome-testing platforms and embedding continuous glucose monitor data into replenishment algorithms. Defend pharmacy channel positioning through NSF Certified for Sport and Informed Sport investments that emerging players cannot immediately fund.
For New Entrants and Emerging Players: GLP-1 tapering populations in the United States represent the most penetrable entry point for appetite management formulations. India's FSSAI notification pathway offers regulatory arbitrage for Ayurvedic-derived entrants. Launch through TikTok Shop live commerce to bypass slotting fee barriers.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer brands with biometric-locked dispensing hardware. Long-term viability hinges on clinical substantiation infrastructure for FTC-defensible structure-function claims. Monitor FDA cGMP certificate revocation announcements as consolidation inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Peptide Supply | Glanbia's captive whey protein production insulates margin from dairy commodity volatility. |
| Biometric-Locked Subscription Platform | Smart pill bottle integration with Apple Health creates switching costs and retention premiums. |
| Regulatory Submission Service Expansion | Turnkey FSSAI and FDA notification offerings attract Western brands seeking India manufacturing. |
| Influencer-Led Live Commerce Launch | TikTok Shop integration converts engagement into immediate purchase without retail intermediation. |
| Clinical Trial Infrastructure Investment | Human intervention studies satisfy EFSA botanical health claim requirements for European access. |
Research Approach
A spread of perspectives from formulation chemists, regulatory affairs directors at FDA-registered facilities, direct-to-consumer brand operators, and pharmacy category buyers converged on the working assumptions. Secondary validation drew from FDA warning letters, EFSA health claim submissions, FSSAI notification databases, and customs trade records. Bottom-up demand modeling and top-down market sizing triangulated on segment-level outputs.
Demand-supply-balance framing anchored the analytical framework across the analysis window. Segmentation dimensions included product type, ingredient source, form factor, and target demographic. CAGRs derived from trend extrapolation adjusted for regulatory inflection points. Forecast inputs incorporated GLP-1 prescription volume trajectories and fitness app subscriber penetration curves.
Practitioners should monitor FDA cGMP enforcement intensity and Chinese export licensing shifts for early signals. Forecasts reflect assumptions about subscription retention rates and influencer marketing cost inflation. Cross-checking against Nielsen retail audit data and Strava user growth metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Sleep Gummies Market
Nutritional Supplements
Grass Fed Protein Market
Nutritional Supplements
Asia-Pacific Omega-3 Products Market
Nutritional Supplements
Functional Carbohydrates Market
Nutritional Supplements
North America Memory Supplements Market
Nutritional Supplements
North America Whey Protein Market
Nutritional Supplements
Middle East and Africa Feed Antioxidants Market
Nutritional Supplements
Middle East and Africa Amino Acid in Dietary Supplements Market
Nutritional Supplements
Vegan Protein Supplements Market
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
North America Immune Health Supplements Market
Nutritional Supplements
Cognition Supplements Market
Nutritional Supplements
Europe Nutraceutical Market
Nutritional Supplements
Natural Vitamin E Product Market
Nutritional Supplements
Choline Bitartrate Market
Nutritional Supplements
Dietary Supplements Market