
 Western Europe Food Phosphate Market | 2026-2036
Western Europe Food Phosphate Market Size, Share, and Industry Trends Forecast 2026-2036
Western Europe Food Phosphate Market Analysis
Spanish phosphate production capacity is consolidating around fewer integrated suppliers serving Western European food manufacturers. EuroChem Group leverages its upstream mining assets to secure feedstock reliability for downstream food-grade output. ICL Group sustains competitive positioning through specialized phosphate blends tailored to meat processing applications. Fosfitalia Group anchors its presence in Mediterranean markets with granular and powder formulations for bakery and dairy clients.
Food phosphates comprise mineral salts derived from phosphoric acid, functioning as leavening agents, emulsifiers, moisture retainers, and pH stabilizers in processed foods, with specifications typically requiring food-grade purity above 99% and controlled heavy metal thresholds below 10 ppm. Sodium phosphate variants dominate functional applications in meat processing due to superior water-binding capacity, while dicalcium phosphate leads nutritional supplements where calcium fortification commands premium positioning. Tricalcium phosphate and monoammonium phosphate occupy narrower but defensible niches in bakery leavening and specialized dairy buffering respectively.
ECHA enforces REACH registration and restricted substance protocols that elevate compliance costs for non-EU phosphate importers seeking Western European market access. EFSA purity standards and the EU Green Deal carbon-border adjustments shape product specifications and sourcing decisions across the supply base. The F-Gas Regulation indirectly affects phosphate processing energy inputs in certain production clusters. Stakeholders must monitor evolving ECHA substance evaluation timelines and carbon-border implementation phases to anticipate cost structure shifts and qualification requirements.
Market Dynamics
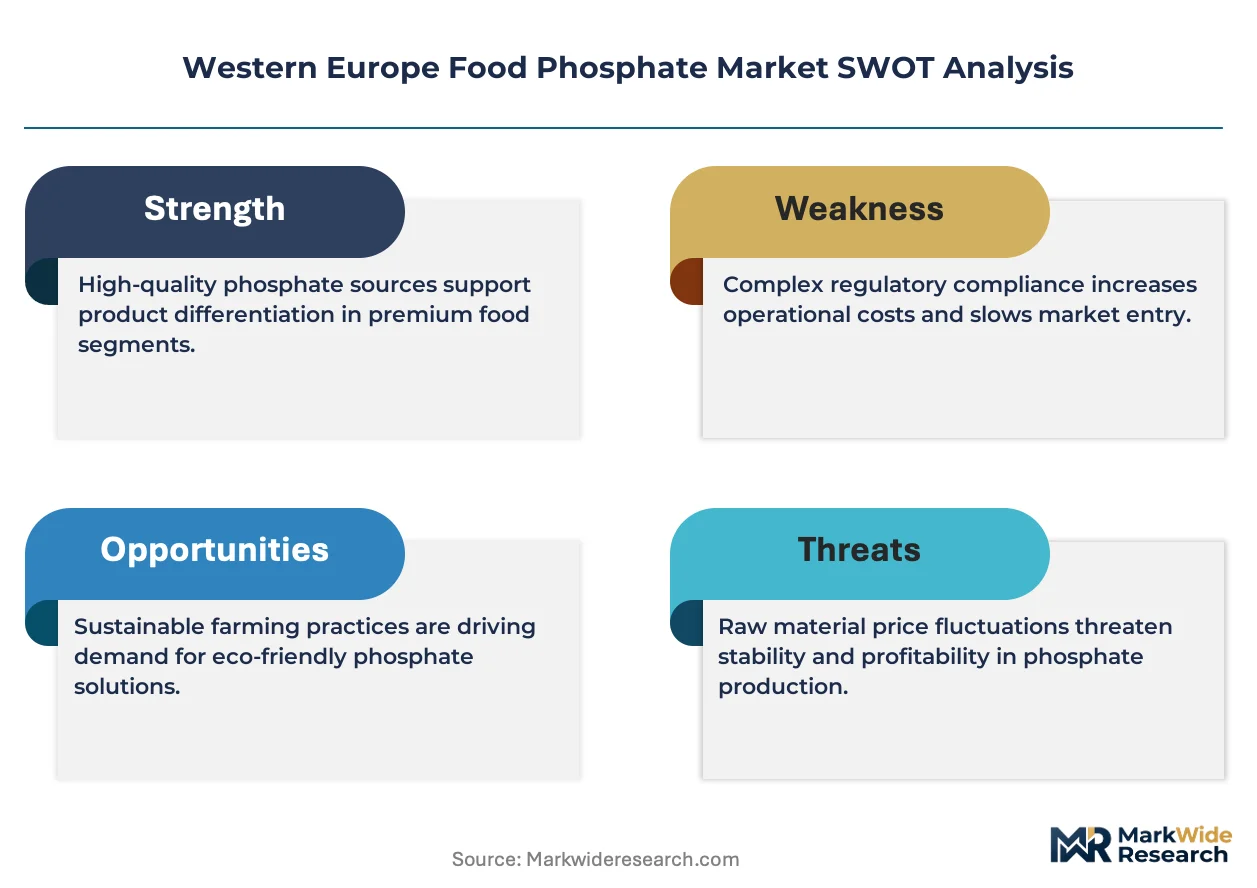
REACH compliance and the EU Green Deal are forcing Western European food phosphate suppliers to requalify feedstocks and document carbon intensity across every production stage, compressing margins for non-integrated processors while advantaging upstream-anchored producers.
Growth Catalysts
- Processed meat applications:Manufacturers across Germany and Spain deploy sodium phosphate blends to lock moisture and extend shelf life in cured products, driving volume procurement.
- EFSA purity mandates:Tighter heavy metal thresholds below 10 ppm are filtering out marginal suppliers and concentrating demand among certified food-grade producers.
- Dairy fortification:Dicalcium phosphate for calcium enrichment commands premium positioning in nutritional supplements across France and the Netherlands.
Market Restraints
- Phosphate rock import dependency:Western European processors rely on Moroccan and Russian feedstock, exposing cost structures to geopolitical supply interruptions.
- REACH registration burden:Non-EU importers face elevated compliance costs and extended substance evaluation timelines that delay market entry.
- Plant-based substitution:Clean-label meat alternatives in German retail are displacing traditional phosphate-dependent processed proteins in certain SKUs.
Strategic Opportunities
- Carbon-border positioning:The EU Green Deal's CBAM phases create first-mover advantage for producers with verified low-carbon phosphate processing in Iberia.
- Specialized bakery blends:Tricalcium phosphate for clean-label leavening addresses artisan bakeries in Italy seeking mineral-based alternatives to aluminum compounds.
- Direct distribution channels:Large meat processors in Bavaria and Baden-Württemberg are consolidating supplier relationships through long-term offtake agreements, bypassing traditional distributors.
Industry Challenges
- Food-grade chemist scarcity:Qualified technical staff capable of navigating ECHA substance dossiers and EFSA purity protocols are concentrated among incumbent players.
- Legacy equipment retrofit costs:Carbon capture and energy efficiency upgrades required by F-Gas Regulation amendments demand capital deployment that mid-tier processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Western Europe Food Phosphate Market |
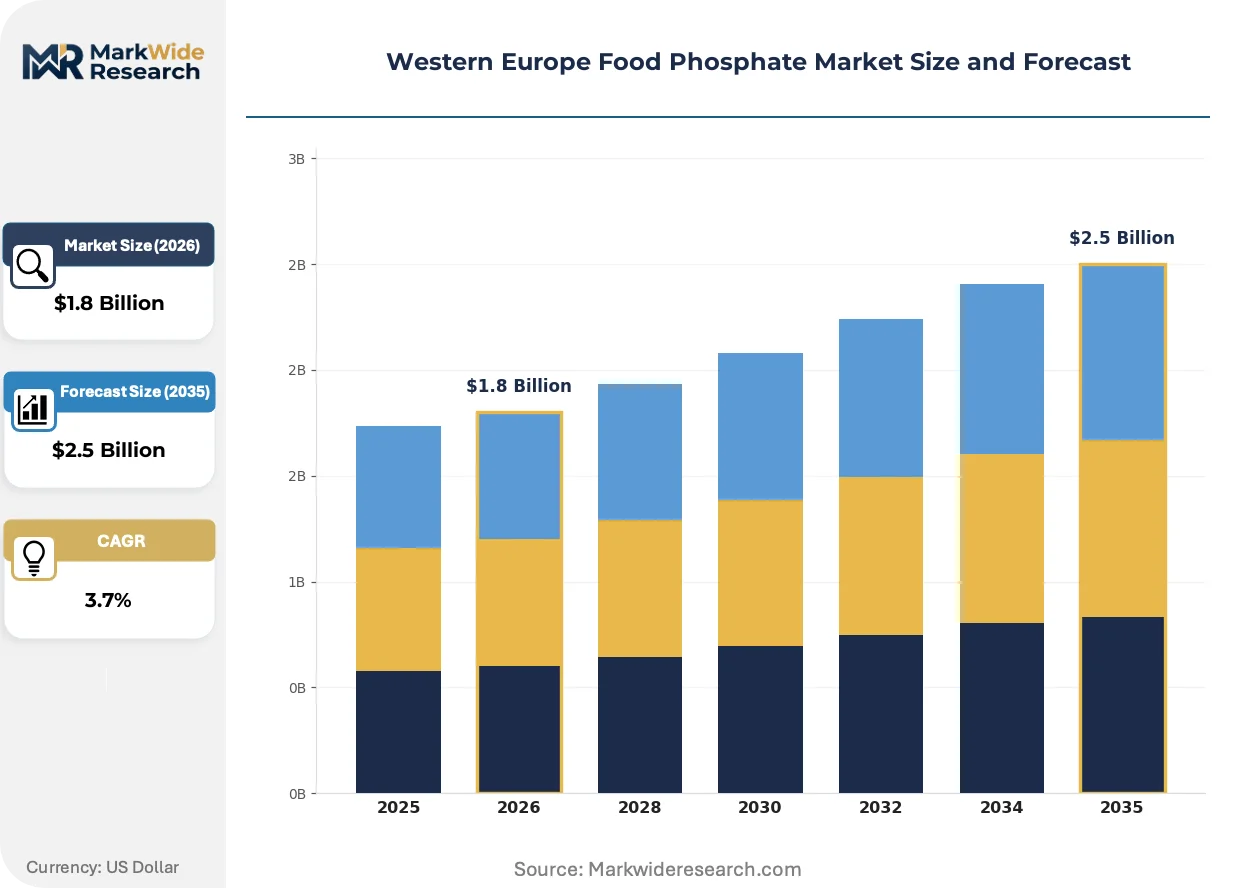
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dicalcium Phosphate, Monoammonium Phosphate, Tricalcium Phosphate, Sodium Phosphate End User: Bakery, Dairy Products, Meat Processing, Nutritional Supplements Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales Form: Granular, Powder, Liquid, Tablets |
| Companies Covered | EuroChem Group, Fosfitalia Group, Yara International ASA, Innophos Holdings, ICL Group, Nutrien Ltd, The Mosaic Company, OCP Group, PhosAgro, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Western Europe Food Phosphate Market Emerging Trajectories
Clean-label formulation pressures and carbon accounting requirements are rewriting how Western European food phosphate suppliers design product portfolios and qualify customer relationships.
Encapsulated phosphate systems is rewriting moisture retention performance in low-sodium meat applications. German processed meat manufacturers are piloting these systems at commercial scale. The technology is rewriting competitive advantage toward suppliers with in-house microencapsulation capabilities.
REACH restriction proposals on certain phosphate salts are tightening substance evaluation timelines for food-grade categories. ECHA's accelerated assessment protocols are compressing reformulation windows for processors. Meat processing applications face the steepest requalification burden as downstream customers demand uninterrupted supply security.
Consolidated procurement by large meat cooperatives is displacing fragmented spot purchasing across the Benelux and northern France. Direct supplier relationships with technical service attachments are replacing distributor-mediated transactions. This pattern is most visible in German pork processing clusters where volume concentration favors integrated phosphate suppliers with dedicated technical support teams.
Western Europe Food Phosphate Market Segmentation
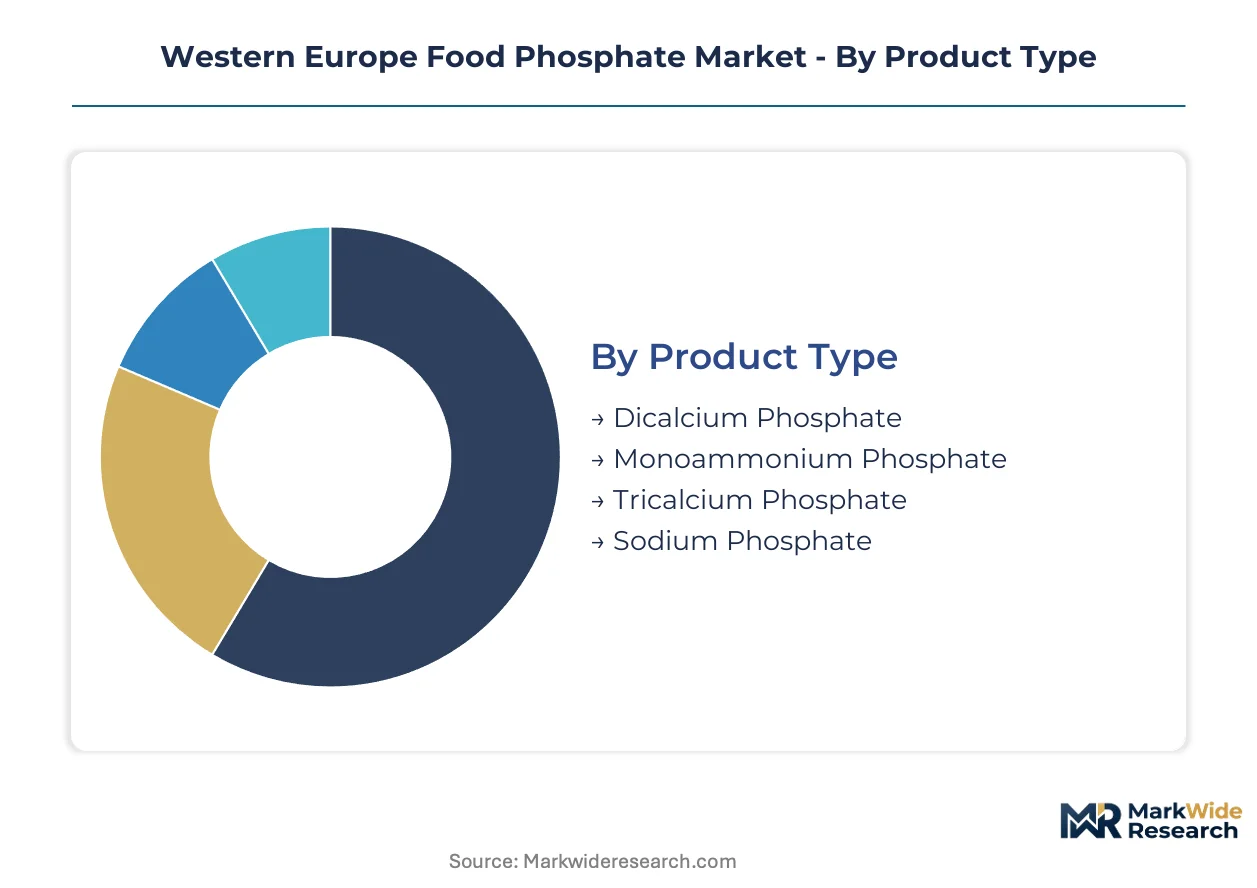
Segmentation in Western Europe food phosphates reveals how capital deployment and regulatory compliance costs concentrate competitive advantage among integrated suppliers. Understanding these divides explains why certain product categories and distribution modes dominate procurement volumes across German meat clusters and Mediterranean dairy operations.
Product Type:
Capital intensity varies sharply across phosphate chemistries, with sodium variants demanding integrated upstream mining assets while nutritional-grade dicalcium permits toll-processing models.
- Sodium Phosphate:Mineral salts engineered for superior water-binding capacity in processed proteins, typically requiring food-grade purity above 99% with heavy metal thresholds below 10 ppm. German cured meat manufacturers in Bavaria deploy these blends at commercial scale to lock moisture and extend shelf life, driving the category's procurement dominance despite REACH registration burdens on non-EU feedstock sources.
- Dicalcium Phosphate:Calcium-fortified mineral compound commanding premium positioning in nutritional supplements where bioavailability specifications elevate processing standards. French and Dutch dairy fortification operations anchor demand, with EFSA purity mandates filtering out marginal toll-processors lacking captive purification capacity.
- Tricalcium Phosphate:Leavening agent gaining traction among Italian artisan bakeries seeking aluminum-free mineral alternatives.
- Monoammonium Phosphate:Specialized dairy buffering agent occupying narrower formulation niches in pH-stabilized cheese production.
Most installed capacity flows through Sodium Phosphate. Expansion is steepest in Dicalcium Phosphate.
End User:
Application-driven margin structures separate commodity meat processing from premium nutritional positioning, with each end-use imposing distinct technical service requirements.
- Meat Processing:Dominant consumption cluster spanning German pork cooperatives and Spanish cured product manufacturers, where sodium phosphate blends enable moisture retention in low-sodium formulations. Direct supplier relationships with embedded technical support teams are displacing distributor channels across Baden-Württemberg processing clusters.
- Dairy Products:Buffering and fortification applications concentrated in Netherlands cheese operations and French yogurt manufacturing, where pH stabilization demands precise phosphate dosing systems.
- Bakery:Clean-label leavening demand rising in Italian artisan segments seeking mineral-based alternatives.
- Nutritional Supplements:Calcium and phosphorus fortification in tablet and capsule formats, with dicalcium variants commanding formulation premiums.
Volume concentrates in Meat Processing. Margin expansion runs strongest in Nutritional Supplements.
Distribution Channel:
Channel economics reflect customer scale concentration, with large processors extracting pricing leverage through consolidated procurement while smaller operators absorb distributor markups.
- Direct Sales:Long-term offtake agreements between integrated phosphate suppliers and large meat cooperatives in Germany, bypassing traditional distribution layers through dedicated technical service attachments.
- Supermarkets:Indirect channel serving small-to-mid dairy and bakery manufacturers via packaged phosphate blends for retail formulation.
- Specialty Stores:Niche supply route for artisan producers requiring customized granular specifications.
- Online Retail:Emerging procurement mode for nutritional supplement manufacturers seeking spot quantities of tablet-grade phosphates.
Procurement volume flows predominantly through Direct Sales. Channel shift momentum favors this route as meat cooperatives consolidate.
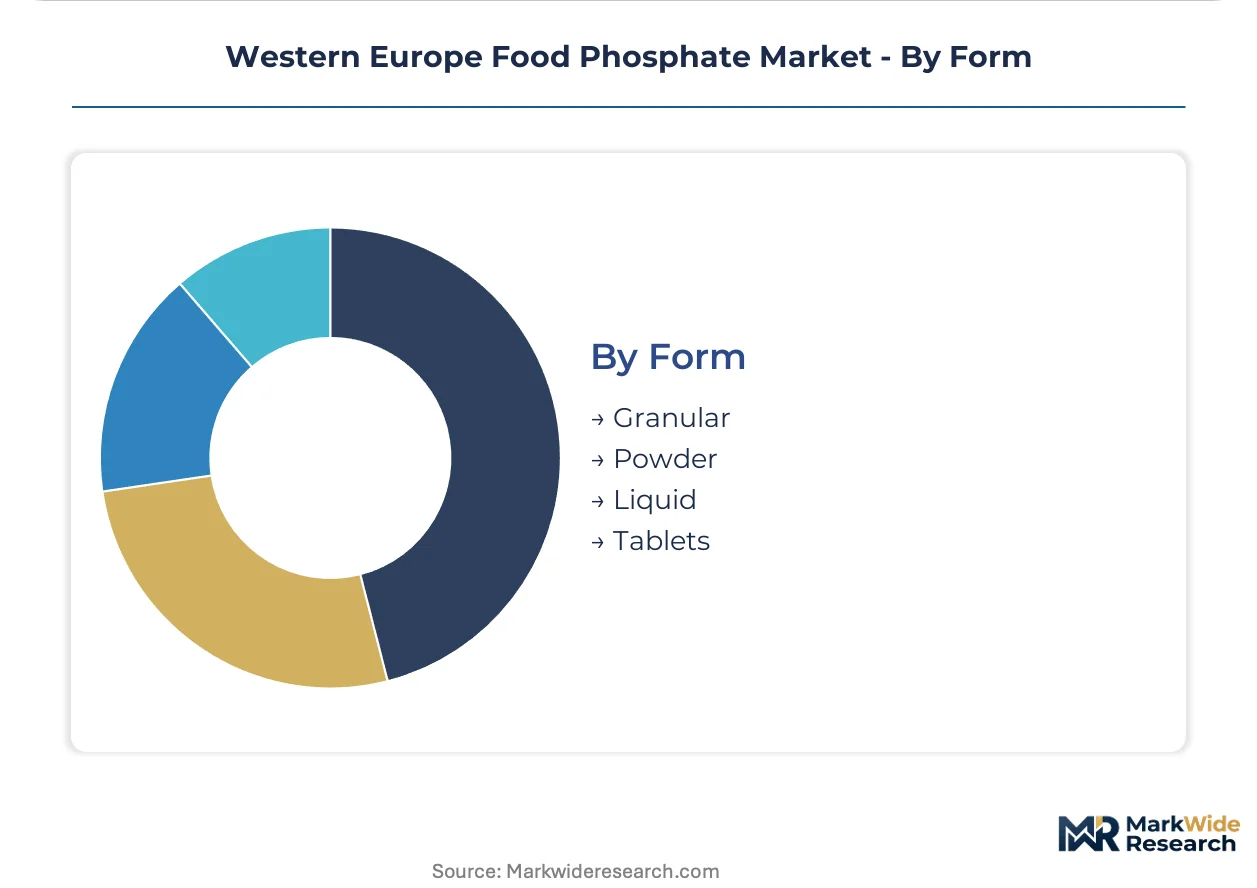
Form:
Physical format selection ties to application equipment compatibility and dissolution kinetics, with powder and granular variants dominating industrial-scale deployment.
- Powder:Standard industrial format for meat processing and dairy buffering applications, offering rapid dissolution and precise dosing integration.
- Granular:Preferred by Mediterranean bakery and dairy clients for dust-free handling and controlled release characteristics.
- Liquid:Pre-dispersed systems for automated injection lines in high-volume cured meat operations.
- Tablets:Compressed format serving nutritional supplement manufacturers with direct-compression tableting equipment.
Processing throughput runs highest through Powder. Technical upgrade investment is concentrating in Liquid systems for injection applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands larger procurement volumes than France, yet Spanish suppliers are consolidating faster around integrated production assets serving cross-border demand.
Germany
Bavarian pork cooperatives and Baden-Württemberg cured meat manufacturers drive sodium phosphate consumption for moisture retention in low-sodium formulations. EFSA purity mandates below 10 ppm heavy metal thresholds filter out marginal suppliers. The Stuttgart processing cluster is consolidating procurement through direct supplier relationships with embedded technical support teams.
France
Dairy fortification operations in Normandy and yogurt manufacturing in the Rhône-Alpes region anchor dicalcium phosphate demand for calcium enrichment. EU Green Deal carbon-border adjustments shape sourcing decisions among nutritional supplement formulators. The Lille metropolitan area hosts toll-processors upgrading purification capacity to meet EFSA bioavailability specifications.
Spain
Cured product manufacturers in Catalonia and Valencia deploy phosphate blends for shelf-life extension in export-oriented ham and sausage operations. REACH registration protocols elevate compliance costs for non-EU feedstock importers. The Tarragona chemical corridor is consolidating around fewer integrated suppliers with captive upstream mining linkages.
Netherlands
Cheese operations in Friesland and Groningen require precise phosphate dosing systems for pH stabilization in aged and fresh varieties. F-Gas Regulation amendments drive energy efficiency retrofits in processing facilities. The Eindhoven-Wageningen corridor concentrates technical service providers supporting dairy phosphate applications.
Italy
Artisan bakeries in Emilia-Romagna and Lombardy are adopting tricalcium phosphate as aluminum-free leavening alternatives. ECHA substance evaluation timelines compress reformulation windows for clean-label ingredient suppliers. The Parma food valley anchors demand for granular phosphate formulations with dust-free handling characteristics.
Western Europe Food Phosphate Market Vendor Landscape
Iberian producers anchor one tier; Central European specialists hold formulation expertise in dairy and meat applications. The vendor base separates into upstream-integrated miners with captive phosphate rock assets and downstream blenders dependent on toll-processing arrangements. Three archetypes dominate: mining-anchored integrated suppliers, application-focused compounders, and regional toll-processors. Capacity expansion and direct technical service attachments represent the dominant competitive moves as large cooperatives consolidate procurement relationships.
Within the integrated tier, EuroChem Group and PhosAgro exemplify upstream-anchored producers securing feedstock reliability through captive mining assets. ICL Group occupies a position among application specialists tailoring phosphate blends to meat processing requirements. These three entities represent the competitive spectrum from raw material control through formulation expertise.
| Leading Market Players |
|---|
| EuroChem Group |
| Fosfitalia Group |
| Yara International ASA |
| Innophos Holdings |
| ICL Group |
| Nutrien Ltd |
| The Mosaic Company |
| OCP Group |
| PhosAgro |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Moroccan mining conglomerates and private-equity-consolidated Iberian processors anchor Western European phosphate supply, translating captive rock access into pricing discipline that toll-dependent blenders cannot match. This ownership structure concentrates margin capture upstream while forcing downstream competitors into cost-pass-through arrangements during feedstock volatility.
Pricing Analysis
Capacity additions in Morocco and Russia are reshaping price floors for food-grade phosphate imports into Western Europe. Three-tier pricing structure across REACH-certified premium, standard food-grade, and technical-economy levels separates integrated suppliers from toll-processors. Price differentiation rests on EFSA purity certification and carbon-border documentation depth. Pricing pressure stems from EU Green Deal compliance costs that non-integrated processors struggle to absorb. Large German meat cooperatives exhibit lowest price sensitivity due to volume leverage, while Italian artisan bakeries face acute cost compression.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Hamburg anchor hub-and-spoke patterns for phosphate distribution across Benelux and German processing clusters. Supply concentrates in Morocco, Russia, and Spain for phosphate rock and upstream derivatives. Western European processors draw from Moroccan OCP Group feedstock, Russian PhosAgro exports, and captive Iberian mining assets. Single-source vulnerability to Moroccan supply interruptions poses structural risk given EU dependency on OCP Group for premium rock grades. Distribution runs through direct supplier relationships with large meat cooperatives, displacing traditional distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Western Europe food phosphates constitute a late-cycle quality story as EFSA purity mandates below 10 ppm heavy metal thresholds filter volume toward certified producers capable of documentation-intensive customer relationships.
For Market Incumbents: Deepen captive mining linkages or long-term offtake agreements with Moroccan and Russian feedstock suppliers to defend against supply interruption risks. Secure ECHA-compliant technical staff through dedicated food-grade chemistry recruitment pipelines, as qualified personnel scarcity constrains competitor expansion. Invest in carbon-border documentation systems ahead of EU Green Deal implementation phases to capture premium positioning.
For New Entrants and Emerging Players: Italian artisan bakeries seeking aluminum-free leavening alternatives represent an underserved buyer archetype with lower certification barriers than German meat processing. Target tricalcium phosphate formulations for clean-label bakery applications where incumbent technical service coverage remains thin. Pursue toll-processing partnerships with Iberian miners lacking downstream food-grade purification capacity as the lowest-capital entry path.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier toll-processors facing REACH registration cost escalation without captive upstream assets. Five-to-ten-year viability favors integrated suppliers with mining linkages and carbon-border readiness. Acquisition target archetype: Iberian processors with latent food-grade capacity and existing Moroccan feedstock relationships. Signal to watch: ECHA substance evaluation timeline acceleration that compresses reformulation windows and favors incumbent technical staff depth.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phosphate Rock Mining | Captive Moroccan or Russian feedstock access insulates margin structures from geopolitical supply shocks. |
| Carbon-Border Documentation Systems Investment | EU Green Deal CBAM compliance creates first-mover premium positioning in German meat cooperative procurement. |
| Specialized Technical Service Team Deployment | Embedded EFSA purity protocol expertise locks in direct supplier relationships with Bavarian processing clusters. |
| Encapsulated Phosphate R&D Partnership | Microencapsulation capabilities for low-sodium meat applications differentiate against commodity blend suppliers. |
| Long-Term Offtake Agreement with Dairy Cooperatives | Volume commitments from Friesland cheese operations secure capacity utilization through cyclical feedstock volatility. |
Methodological Framework
Bottom-up meat processing and dairy fortification modeling reconciled against top-down phosphate rock import tracking forms the analytical core of this study. Primary interviews with plant managers at German cured meat cooperatives, procurement leads at Dutch cheese operations, technical R&D directors at Iberian chemical processors, and distribution channel partners across Benelux provided demand-side validation. Secondary sources include ECHA REACH registration databases, EFSA purity standard filings, Eurostat trade flow records, Cefic chemical industry reports, and SEC 10-K disclosures from listed phosphate producers. Triangulation between consumption estimates and supply-side capacity data ensures cross-verified output integrity.
Historical trendline analysis of sodium phosphate consumption in German pork processing clusters and dicalcium phosphate uptake in French nutritional supplements established baseline growth patterns across the projection horizon. Segmentation modeling spans product chemistry variants, end-use applications spanning meat processing through nutritional supplements, distribution channel structures, and physical formulation formats. CAGRs derive from regression analysis against protein processing output trends and dairy fortification regulatory mandates. Forecast inputs include ECHA substance evaluation timeline acceleration and EU Green Deal carbon-border implementation phases.
Underlying measurement precision varies by segment; sodium phosphate for industrial meat processing carries tighter precision than specialized monoammonium phosphate for artisan cheese applications due to concentration of publicly available production data. Forecasts reflect documented assumptions regarding REACH compliance cost trajectories and feedstock supply continuity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Blueberry Ingredient Market
Food Additives and Ingredients
North America Feed Additives Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Europe Food Micronized Salt Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Italy Food Emulsifier Market
Food Additives and Ingredients
South Africa Food Emulsifiers Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Organic Food Additives Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
Europe Food Emulsifiers Market
Food Additives and Ingredients
France Food Acidulants Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Low Methoxyl Pectin Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Spain Food Colorants Market