
 Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market | 2026-2036
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market Outlook
Project finance for cold-chain distribution networks is rewriting competitive access across rural Africa. Tiger Brands leverages its refrigerated logistics backbone to dominate South African dairy fortification. Promasidor Holdings anchors West African demand through powdered beverage formulations designed for ambient storage. Nestle SA extends its manufacturing footprint with regionally adapted micronutrient premix facilities.
Africa vitamin fortified and mineral enriched food and beverage encompasses products with added vitamins A, D, iron, zinc, or folic acid at levels exceeding baseline nutritional content, produced through spray-drying, extrusion, or liquid injection processes to address documented deficiency burdens. The primary commercial purpose centers on reducing anemia, stunting, and micronutrient gaps among populations with limited dietary diversity. Ready-to-drink beverages command the deepest margin pools where urbanization concentrates purchasing power, while fortified cereals sustain the widest volume base through institutional procurement channels. Pouch packaging for dairy products competes aggressively against bottles on unit economics in price-sensitive East African markets.
South Africa's Department of Health enforces mandatory fortification standards for maize meal and wheat flour under national food control regulations, directly shaping product formulation requirements for domestic manufacturers. The Codex Alimentarius guidelines, referenced by multiple African national food safety agencies, establish baseline micronutrient thresholds that influence import acceptance and local production specifications. Nigeria's National Agency for Food and Drug Administration and Control monitors premix quality and label claims at port of entry. Stakeholders must track evolving national fortification mandates and premix sourcing certification requirements as regulatory fragmentation intensifies across the continent's fragmented customs territories.
Market Dynamics
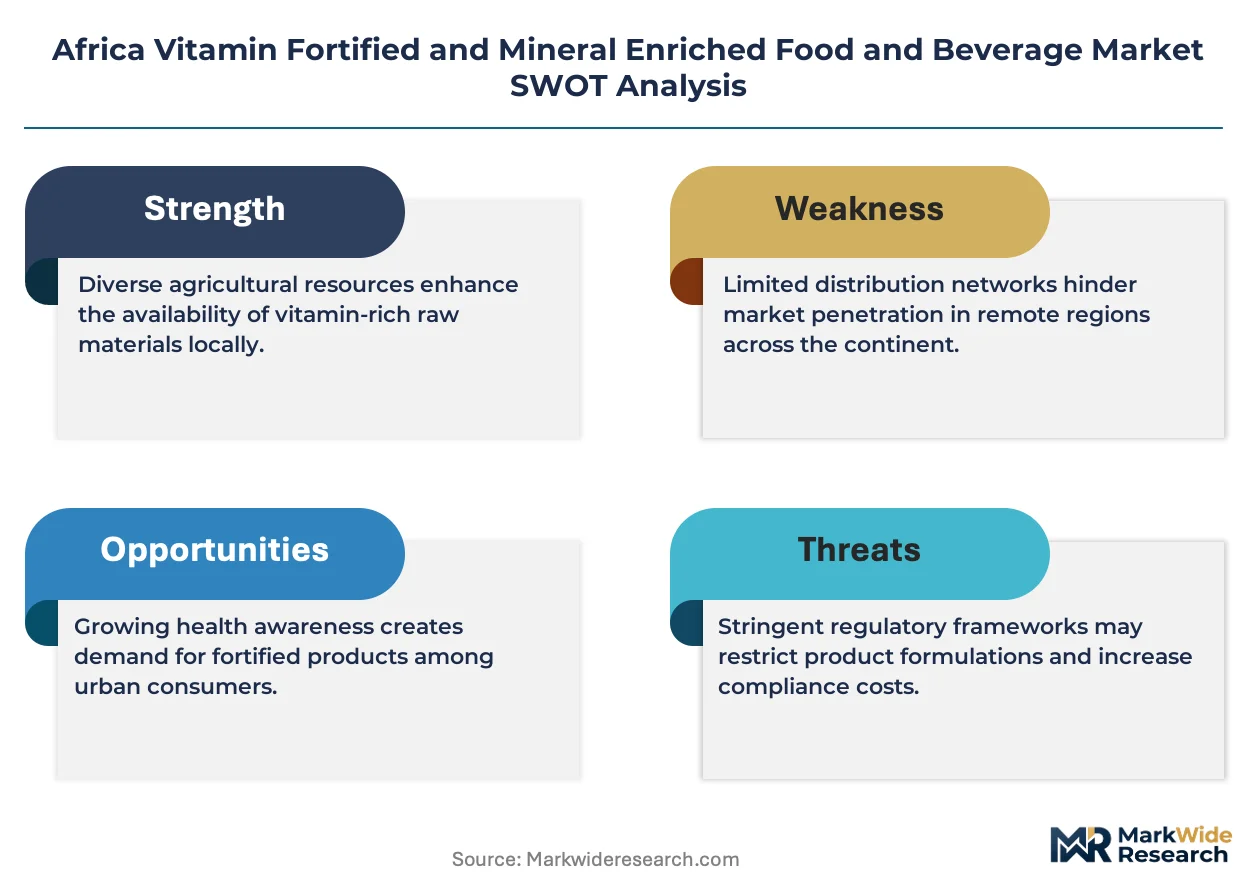
South Africa's mandatory maize meal and wheat flour fortification regulations are forcing reformulation across domestic milling operations while creating compliance arbitrage opportunities for premix suppliers with certified laboratory networks.
Growth Catalysts
- School feeding procurement:East African government tenders for fortified cereals absorb production capacity from Nairobi to Kampala, creating predictable offtake volumes for regional millers.
- National fortification mandates:Nigeria's NAFDAC enforcement of premix quality standards at port of entry is professionalizing import channels and filtering out uncertified suppliers.
- Spray-drying infrastructure:Industrial-scale drying capacity expansion in Dakar and Lagos is reducing unit costs for powdered beverage formulations targeting ambient distribution.
Market Restraints
- Vitamin A premix cost volatility:Synthetic retinol prices fluctuate with palm oil feedstock markets, compressing margins on staple fortification programs with fixed government pricing.
- Single-source cold-chain dependency:Refrigerated logistics in Southern Africa concentrate among three operators, creating distribution bottlenecks for dairy fortification outside urban corridors.
- Iron bioavailability limitations:Ferrous sulfate oxidation in humid storage conditions reduces efficacy in maize meal distributed through informal retail channels.
Strategic Opportunities
- Ethiopian market penetration:Africa's second-largest population lacks mandatory flour fortification legislation, creating first-mover positioning for premix suppliers ahead of regulatory harmonization.
- Digital traceability integration:Blockchain-verified supply chain documentation aligns with EU import requirements and unlocks premium pricing for East African sesame and moringa fortification ingredients.
- Pouch packaging format expansion:Flexible laminate pouches for ready-to-drink dairy reduce logistics costs by 40% versus bottles, enabling rural distribution economics in Tanzania and Uganda.
Industry Challenges
- Premix laboratory certification backlog:ISO 17025 accreditation queues at South African testing facilities delay product launch timelines by 8-14 months for new market entrants.
- Legacy milling equipment retrofitting:Mid-scale Nigerian flour mills require extruder modifications to achieve uniform micronutrient dispersion, demanding capital deployment without guaranteed offtake contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market |
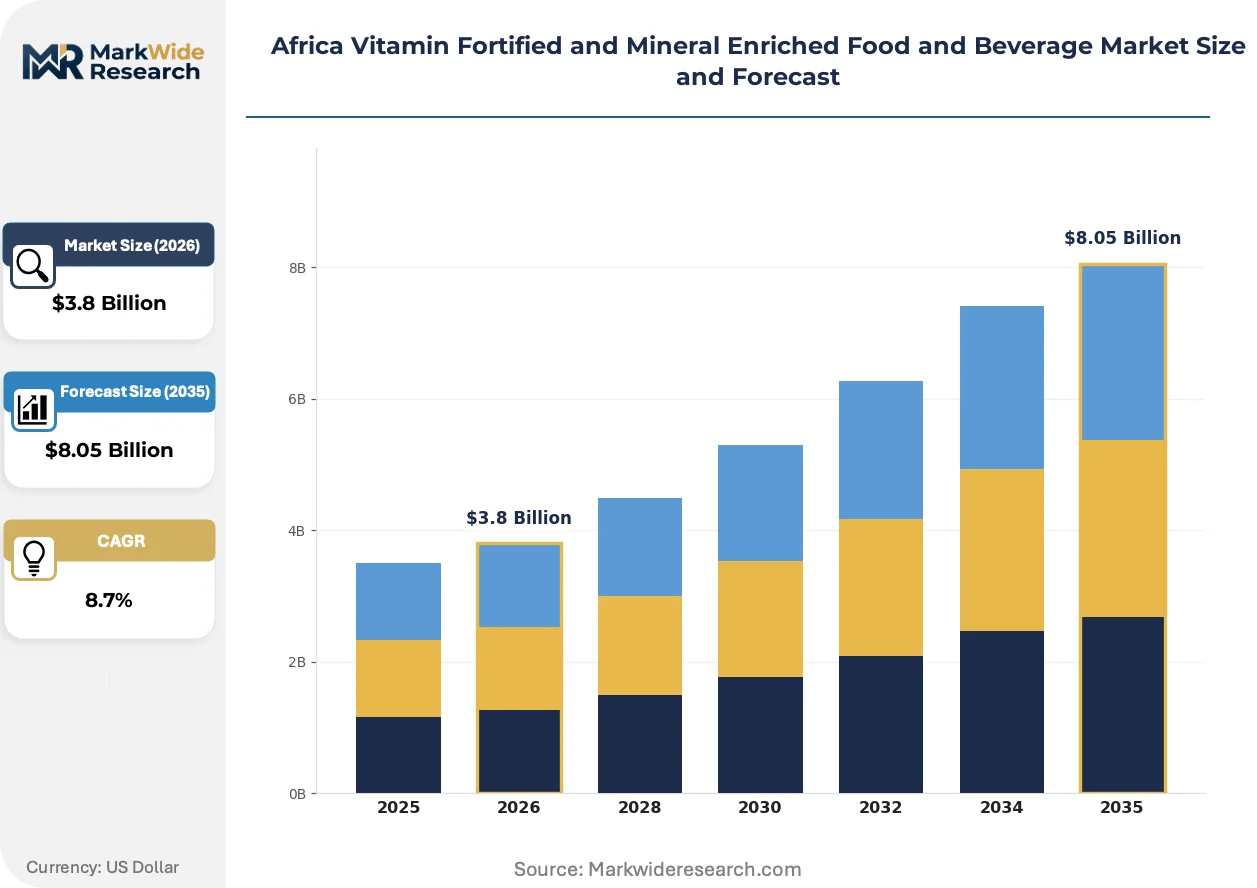
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ready-to-Drink Beverages, Snack Bars, Dairy Products, Fortified Cereals End User: Children, Adults, Elderly, Pregnant Women Distribution Channel: Supermarkets, E-commerce, Specialty Stores, Health Food Shops Packaging Type: Bottles, Pouches, Cans, Tetra Packs |
| Companies Covered | Nestle SA, Abbott, PepsiCo, Inc., Kellogg Company, Amway Corporation, The Coca-Cola Company, Tiger Brands, Promasidor Holdings, Nutriset, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market Strategic Shifts
Digital integration across fortification supply chains is compressing quality assurance cycles while enabling real-time compliance documentation for export-bound production batches.
Microencapsulation technology using lipid-based shell matrices is virtualizing vitamin stability in high-humidity environments. Kenyan dairy processors are adopting these formulations for UHT milk fortification ahead of dry-season distribution peaks. The technology is virtualizing traditional cold-chain requirements for probiotic and fat-soluble vitamin delivery across East African markets.
South Africa's Department of Health is tightening premix supplier registration requirements under amended food control regulations. Domestic millers must now source exclusively from accredited facilities with batch-level testing documentation. Medium-scale wheat flour producers in the Western Cape are consolidating supplier relationships to three certified premix houses to manage compliance audit burdens.
Institutional procurement consolidation is reshaping competitive access across East African school feeding programs. Government tender specifications now prioritize single-source accountability for micronutrient premix supply over lowest-unit-cost bidding. Ethiopian and Kenyan education ministries are piloting multi-year framework agreements with integrated nutrition service providers, displacing fragmented spot purchasing from commodity traders.
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market Segmentation
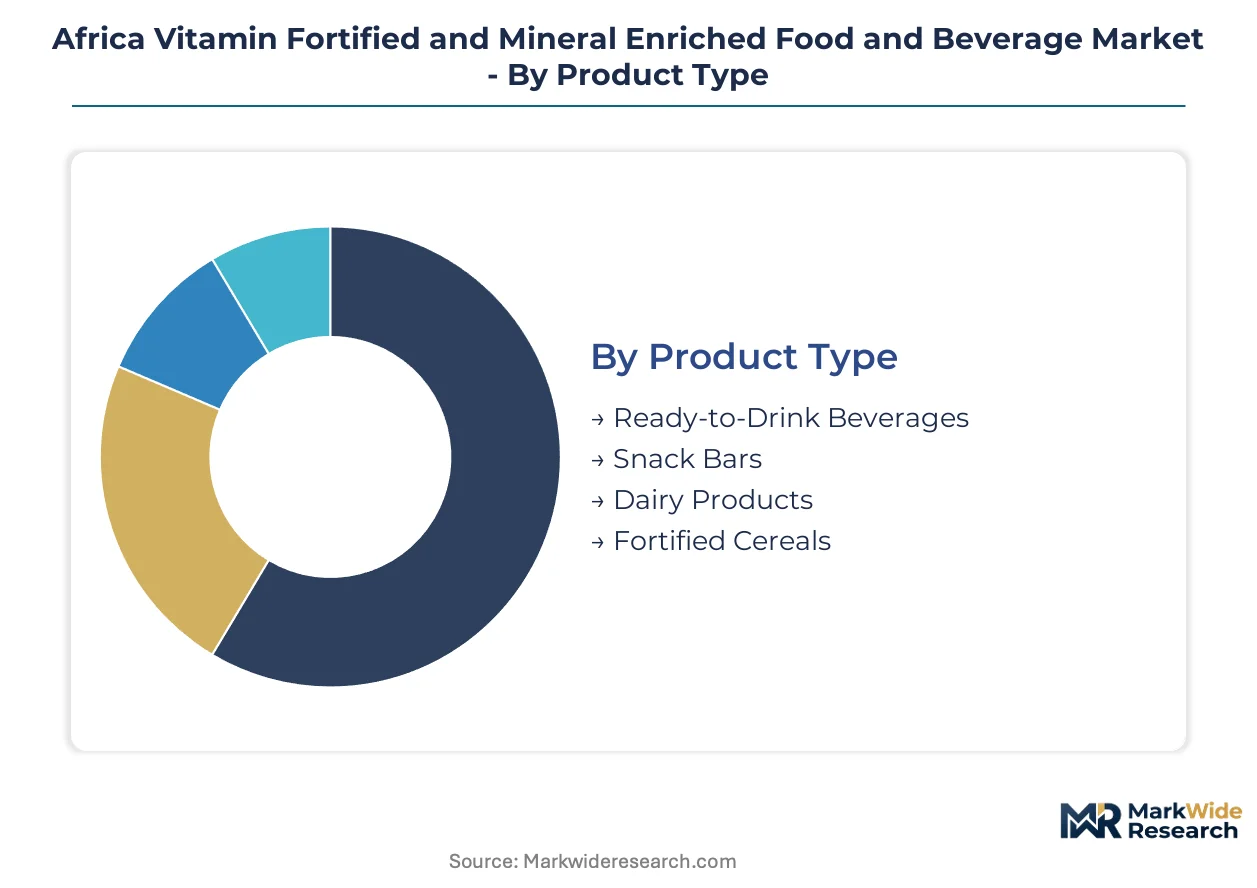
Segmentation in African fortification markets reveals divergent margin structures between institutional procurement channels and retail-driven formats. Understanding turnover velocity across product categories enables manufacturers to align production planning with cash conversion cycles.
Product Type:
Cycle times vary dramatically across this category, with ambient-stable formats turning inventory weekly while refrigerated products face seasonal demand compression.
- Ready-to-Drink Beverages:Liquid formulations with suspended micronutrients requiring homogenization stability. Nigerian urban corridors concentrate demand where ambient distribution reaches informal retail density. Margin pools deepen where cold-chain infrastructure enables probiotic fortification.
- Fortified Cereals:Extruded or flaked grain bases with surface-applied vitamin premixes. East African school feeding tenders in Kenya and Uganda absorb predictable volume blocks. Government pricing caps compress margins despite guaranteed offtake.
- Dairy Products:UHT milk and fermented drinks with fat-soluble vitamin enrichment dominate South African retail shelves.
- Snack Bars:Compressed nutrient-dense formats targeting urban convenience consumption.
Fortified cereals anchors the volume base while ready-to-drink beverages gains share at the steepest rate.
End User:
Cost tier stratification separates subsidized institutional programs from premium self-pay segments, with procurement authority residing in distinct decision-making nodes.
- Children:School-based delivery platforms with government-funded micronutrient targets. Anemia reduction mandates in Ethiopian and Tanzanian education ministries drive formulation specifications. Tender consolidation favors suppliers with integrated premix-to-product capabilities.
- Pregnant Women:Iron and folic acid concentrates with bioavailability optimization. Maternal health programs in Nigeria and Ghana concentrate demand through clinic distribution networks. Compliance tracking requirements favor packaged formats over bulk.
- Adults:Workplace wellness programs and retail self-selection in South African metropolitan areas.
- Elderly:Specialized calcium and vitamin D formulations with swallowability engineering.
Children anchors the volume base while pregnant women climbs the fastest as national maternal health budgets expand.
Distribution Channel:
Geographic reach constraints separate urban-consolidated modern trade from rural-penetrating informal networks, with channel selection determining margin capture versus volume scale.
- Supermarkets:Formal retail with barcode traceability and temperature-controlled display. South African chains in Johannesburg and Cape Town concentrate premium fortified dairy. Shelf-space fees favor suppliers with national brand recognition.
- E-commerce:Direct-to-consumer platforms with subscription bundling for repeat micronutrient purchases. Lagos and Nairobi urban corridors show highest digital payment penetration. Last-mile costs challenge low-unit-value staple fortification.
- Specialty Stores:Health-focused retail with pharmacist consultation in Moroccan and Tunisian urban centers.
- Health Food Shops:Premium positioning with imported organic fortification ingredients.
Supermarkets anchors the volume base while e-commerce shows steepest expansion trajectory as mobile money penetration deepens.
Packaging Type:
Supply concentration in converting capacity creates regional bottlenecks, with format selection driven by logistics cost structure rather than consumer preference alone.
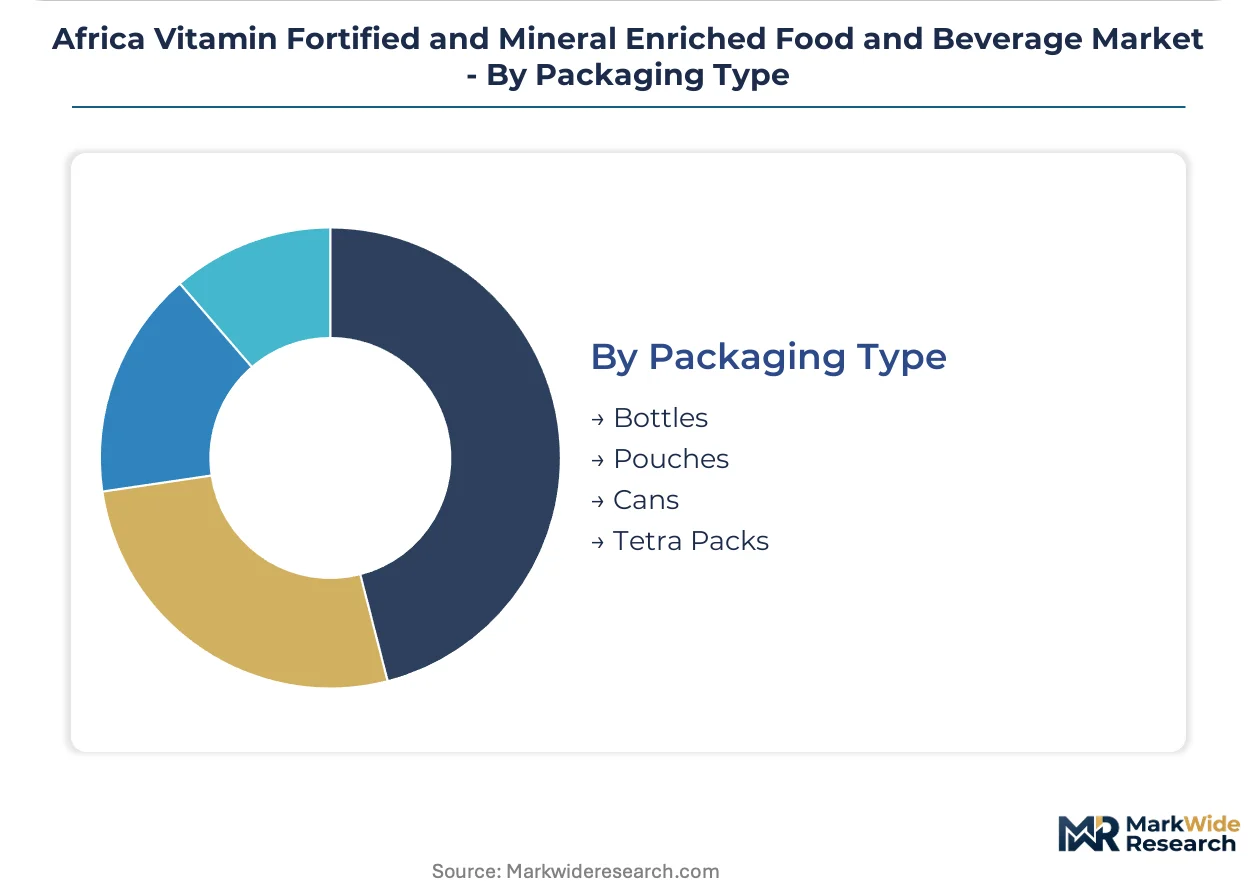
- Pouches:Flexible laminate structures with aseptic fill capability for ambient distribution. Tanzanian and Ugandan dairy processors adopt pouch formats to reduce logistics costs by forty percent versus rigid alternatives. Unit economics enable rural penetration where bottle return logistics fail.
- Tetra Packs:Aseptic carton systems with six-layer barrier protection for UHT liquid fortification. Dakar and Lagos converting plants supply West African markets. Capital intensity limits new entrant participation.
- Bottles:PET and HDPE rigid containers with resealability for household consumption.
- Cans:Metal packaging for carbonated fortification beverages with extended shelf stability.
Pouches anchors the volume base while Tetra Packs gains share fastest as aseptic converting capacity expands in coastal manufacturing zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South African institutional buyers dominate procurement volumes through mandatory fortification compliance, while East African school feeding programs and West African beverage distribution networks create distinct demand archetypes across the continent.
South Africa
The Department of Health enforces mandatory maize meal and wheat flour fortification under national food control regulations, driving consistent premix demand from domestic millers. Tiger Brands leverages refrigerated logistics infrastructure to dominate dairy fortification distribution. Cape Town and Johannesburg manufacturing clusters concentrate spray-drying and extrusion capacity for regional export.
Nigeria
NAFDAC monitors premix quality and label claims at port of entry, professionalizing import channels for ready-to-drink fortified beverages. Lagos absorbs the largest volume of ambient-stable beverage formulations on the continent. Industrial-scale drying capacity expansion in Lagos is reducing unit costs for powdered beverage production.
Kenya
Government tenders for fortified cereals absorb production capacity from Nairobi to Kampala, creating predictable offtake volumes for regional millers. School feeding programs drive adoption of extruded grain formats with surface-applied vitamin premixes. Nairobi's manufacturing corridor anchors East African supply for institutional procurement.
Ethiopia
Africa's second-largest population lacks mandatory flour fortification legislation, creating positioning opportunities for premix suppliers ahead of regulatory harmonization. Anemia reduction mandates in the education ministry drive formulation specifications for school-based delivery. Addis Ababa's emerging industrial zones attract early-mover premix warehousing investments.
Tanzania
Pouch packaging formats for dairy products reduce logistics costs versus bottles, enabling rural distribution economics in price-sensitive markets. Flexible laminate structures with aseptic fill capability support ambient distribution networks. Dar es Salaam's converting plants supply laminate materials for regional dairy processors.
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market Competitive Environment
Channel-controlling players compete with product-specialist players across distinct margin pools. The vendor base organizes around three archetypes: multinational nutrition conglomerates with integrated premix-to-product capabilities, regional dairy and milling operators with captive distribution networks, and specialized premix suppliers with certified laboratory infrastructure. Competitive moves concentrate on backward integration into premix manufacturing and geographic expansion through multi-year framework agreements with institutional buyers.
Among multinational conglomerates, Nestle SA exemplifies the integrated premix-to-product archetype through regionally adapted micronutrient premix facilities. Tiger Brands represents the regional operator model with refrigerated logistics backbone dominance. Promasidor Holdings occupies a position within ambient-stable formulation specialists, anchoring West African demand through powdered beverage formats designed for tropical storage conditions.
| Leading Market Players |
|---|
| Nestle SA |
| Abbott |
| PepsiCo, Inc. |
| Kellogg Company |
| Amway Corporation |
| The Coca-Cola Company |
| Tiger Brands |
| Promasidor Holdings |
| Nutriset |
| Others |
Value Chain & Pricing Dynamics
Spray-drying capacity underutilization in Dakar and Lagos is forcing premix suppliers into aggressive volume pricing while compressing margins for ambient-stable beverage formulations across West African distribution networks.
Pricing Analysis
Certification level (ISO 17025-accredited laboratory networks) creates the primary spread between premium premix suppliers and commodity traders in African fortification markets. Contract-based long-term offtake agreements dominate institutional procurement, with price differentiation driven by batch-level testing documentation and geographic delivery cost to inland milling clusters. Pricing pressure stems from synthetic retinol feedstock volatility linked to palm oil markets, squeezing fixed-price government contracts. School feeding programs exhibit highest price sensitivity due to budget caps, while premium dairy fortification in South African supermarkets shows lowest elasticity.
Supply Chain Analysis
Upstream vitamin A and iron premix feedstock draws from concentrated European and Asian chemical synthesis hubs, with South African laboratory accreditation creating a secondary processing tier. Raw material dependencies center on synthetic retinol, ferrous sulfate compounds, and lipid-based microencapsulation matrices. Single-source cold-chain vulnerability in Southern Africa concentrates refrigerated logistics among three operators, creating distribution bottlenecks for dairy fortification. Distribution runs through institutional procurement frameworks in East Africa and ambient-stable informal retail networks in West Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across African customs territories is fragmenting procurement authority and creating niche positioning opportunities for premix suppliers with certified laboratory infrastructure.
For Market Incumbents: Entrench position through backward integration into ISO 17025-accredited testing facilities and multi-year framework agreements with Ethiopian and Kenyan education ministries. Emerging digital traceability requirements threaten uncertified competitors. Certification investment in blockchain-verified supply chain documentation unlocks premium pricing for export-bound production batches. For New Entrants and Emerging Players: Pursue first-mover positioning in Ethiopia's unregulated flour milling sector ahead of anticipated mandatory fortification legislation. The most penetrable white space sits in pouch-packaged dairy fortification for Tanzanian and Ugandan rural distribution. Target institutional procurement consolidation through integrated premix-to-product capabilities rather than commodity spot bidding. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among premix suppliers with captive laboratory certification and long-term government offtake contracts. Over the medium-term horizon, acquisition targets should cluster around mid-scale Nigerian flour mills requiring extruder retrofitting capital. Watch for Ethiopian regulatory harmonization signals as the primary demand inflection trigger.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Manufacturing | Captive ISO 17025 laboratory networks reduce compliance audit burdens for South African millers. |
| Pouch Packaging Format Expansion | Flexible laminate structures cut logistics costs by forty percent versus bottles in East African dairy. |
| Digital Traceability Integration | Blockchain-verified documentation aligns with EU import requirements for premium ingredient sourcing. |
| Multi-Year Framework Agreements | Single-source accountability clauses displace fragmented spot purchasing in Kenyan school feeding tenders. |
| Microencapsulation Technology Adoption | Lipid-based shell matrices virtualize cold-chain requirements for probiotic fortification in humid climates. |
Study Parameters
The analysis maps ready-to-drink beverages, fortified cereals, dairy products, and snack bars, each validated through premix procurement managers, milling operations directors, and regulatory affairs specialists at national food safety agencies. Primary interviews with institutional feeding program coordinators and cold-chain logistics operators combined with secondary validation against Codex Alimentarius guidelines, NAFDAC import records, and South African Department of Health fortification compliance databases. Bottom-up production capacity assessments and top-down consumption modeling triangulate volume estimates.
Assumptions held fixed include current national fortification mandate coverage and existing cold-chain infrastructure density, while regulatory expansion timelines and premix laboratory accreditation queues varied across scenarios. Segmentation dimensions modeled encompass product format stability requirements, end-user anemia reduction targets, procurement channel authority concentration, and regional customs territory fragmentation. CAGRs derived from production capacity expansion schedules and institutional tender award patterns, with spray-drying utilization rates and school feeding budget allocations as key forecast inputs.
Sensitivities concentrate around Ethiopian regulatory harmonization timing and synthetic retinol feedstock price volatility. Forecasts reflect documented assumptions regarding national mandate enforcement intensity and laboratory certification backlog resolution. Cross-checking against UN World Food Programme procurement data and national health ministry budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Gamma-Tocopherol Market
Vitamin Fortified
Beta Carotene Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Fortified Milk and Milk Products Market
Vitamin Fortified
Esterified Vitamins Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Multivitamin Gummies Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Enriched Flour Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Fortified Cereal Market
Vitamin Fortified
Global Fortified Edible Oils Market
Vitamin Fortified
Global Vitamin Tonics Market