
 North America Vitamin a Market | 2026-2036
North America Vitamin a Market Size, Share, and Industry Trends Forecast 2026-2036
North America Vitamin a Market Analytics
Multi-source procurement of retinol and beta-carotene feedstocks is realigning supply security strategies across North American vitamin A value chains. DSM leverages backward integration into fermentation-derived beta-carotene to sustain raw material cost discipline. BASF SE anchors its position through synthetic retinol production scale at European-North American bridge facilities. Pharmavite competes via direct-to-consumer channel control under its Nature Made brand umbrella.
Vitamin A denotes a group of fat-soluble retinoids—principally retinol, retinal, and retinyl esters—essential for vision, immune function, and cellular differentiation, typically formulated at 2,500–10,000 IU per unit dose for human consumption. The softgels segment dominates volume due to oil-solubility compatibility and consumer familiarity, while powders gain traction in functional food fortification where manufacturing flexibility matters. Natural formulation claims command premium positioning in cosmetics and clean-label supplements, though synthetic retinol retains cost advantages in animal feed and mass-market healthcare applications.
FDA dietary supplement GMPs and NDI notification requirements shape product development timelines and entry barriers for novel delivery formats. Health Canada's Natural and Non-prescription Health Products Directorate imposes parallel efficacy and safety documentation standards on cross-border suppliers. Stakeholders must monitor evolving GRAS affirmation pathways for novel vitamin A precursors and biofortification technologies that could redraw competitive boundaries in ingredient sourcing.
Market Dynamics
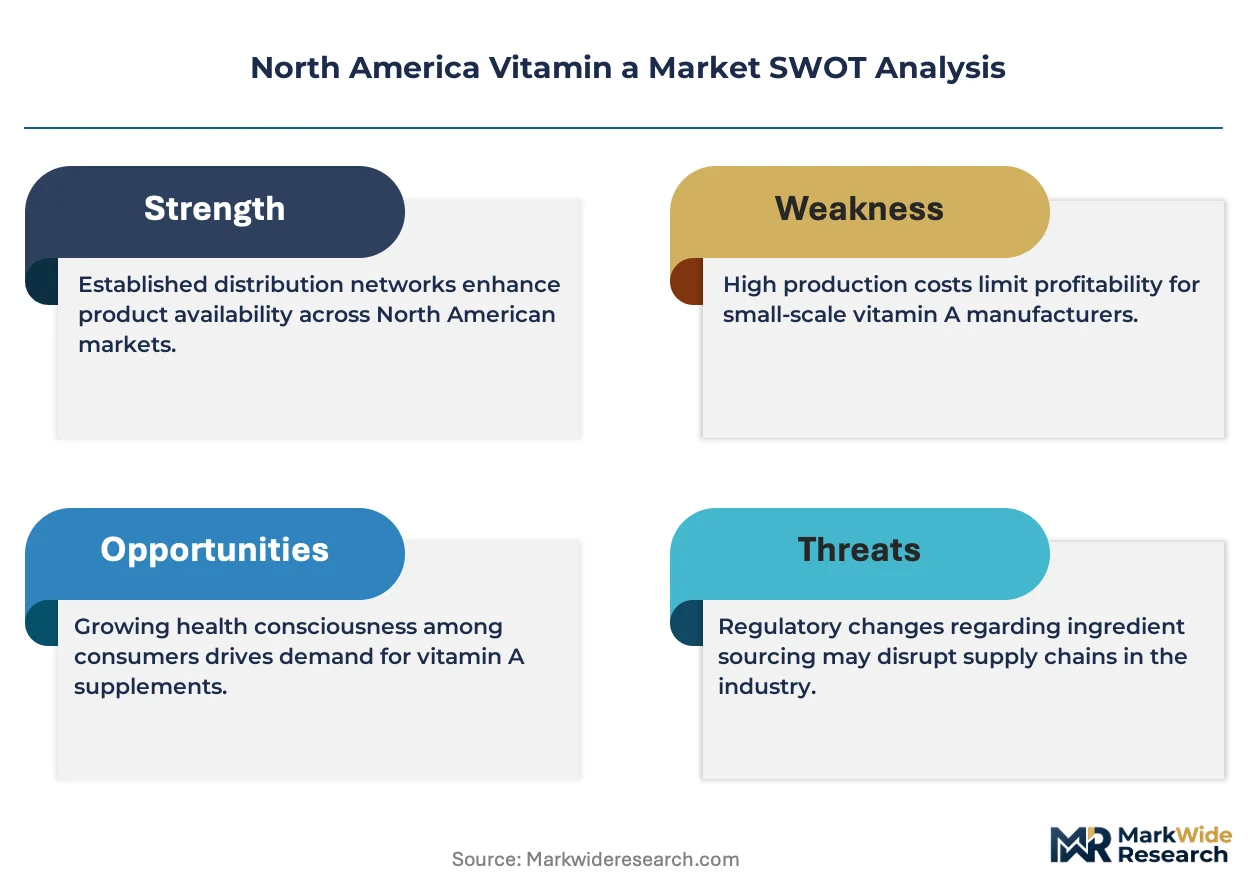
FDA's updated dietary supplement labeling requirements and New Dietary Ingredient notification pathways are tightening quality benchmarks across North American vitamin A value chains, forcing manufacturers to revalidate formulations and extend product development timelines.
Growth Catalysts
- FDA GMP Enforcement:The agency's amplified inspection frequency for dietary supplement manufacturers is accelerating facility upgrades and driving demand for compliant vitamin A premixes and finished formulations.
- Fermentation-Derived Beta-Carotene:Advances in microbial strain engineering are expanding bio-based retinoid production capacity, reducing feedstock price volatility for North American formulators.
- Fortified Food Mandates:School nutrition programs and federal food assistance initiatives in the United States are sustaining baseline demand for vitamin A-fortified dairy and grain products.
Market Restraints
- Synthetic Retinol Feedstock Concentration:European-North American bridge facilities controlled by BASF SE and DSM create supply vulnerability for non-integrated North American formulators during logistics disruptions.
- NDI Notification Burden:FDA's 75-day pre-market notification requirement for novel vitamin A delivery formats imposes documentation costs that deter mid-tier entrants from launching innovative softgel or nanoemulsion products.
- Plant-Based Retinol Substitutes:Bakuchiol and algae-derived carotenoids are capturing clean-label cosmetic applications, compressing addressable market for traditional retinol in premium skincare.
Strategic Opportunities
- Direct-to-Consumer Subscription Models:Personalized nutrition platforms in the United States are creating dedicated vitamin A SKU demand through algorithm-driven supplement regimens.
- Health Canada Cross-Border Harmonization:Alignment between FDA and Natural and Non-prescription Health Products Directorate standards is reducing dual-certification costs for US manufacturers exporting to Canadian markets.
- Biofortification Technology Convergence:CRISPR-edited staple crops and precision fermentation are converging to enable novel vitamin A precursor sourcing outside traditional petrochemical or agricultural supply chains.
Industry Challenges
- Analytical Methodology Talent Scarcity:Validated HPLC and mass spectrometry expertise for retinoid potency testing is concentrated among contract laboratories, creating bottlenecks for in-house quality control expansion.
- GRAS Affirmation Timeline Uncertainty:Novel vitamin A precursors and nano-delivery systems face indeterminate FDA Generally Recognized as Safe evaluation periods that freeze commercialization planning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Vitamin a Market |
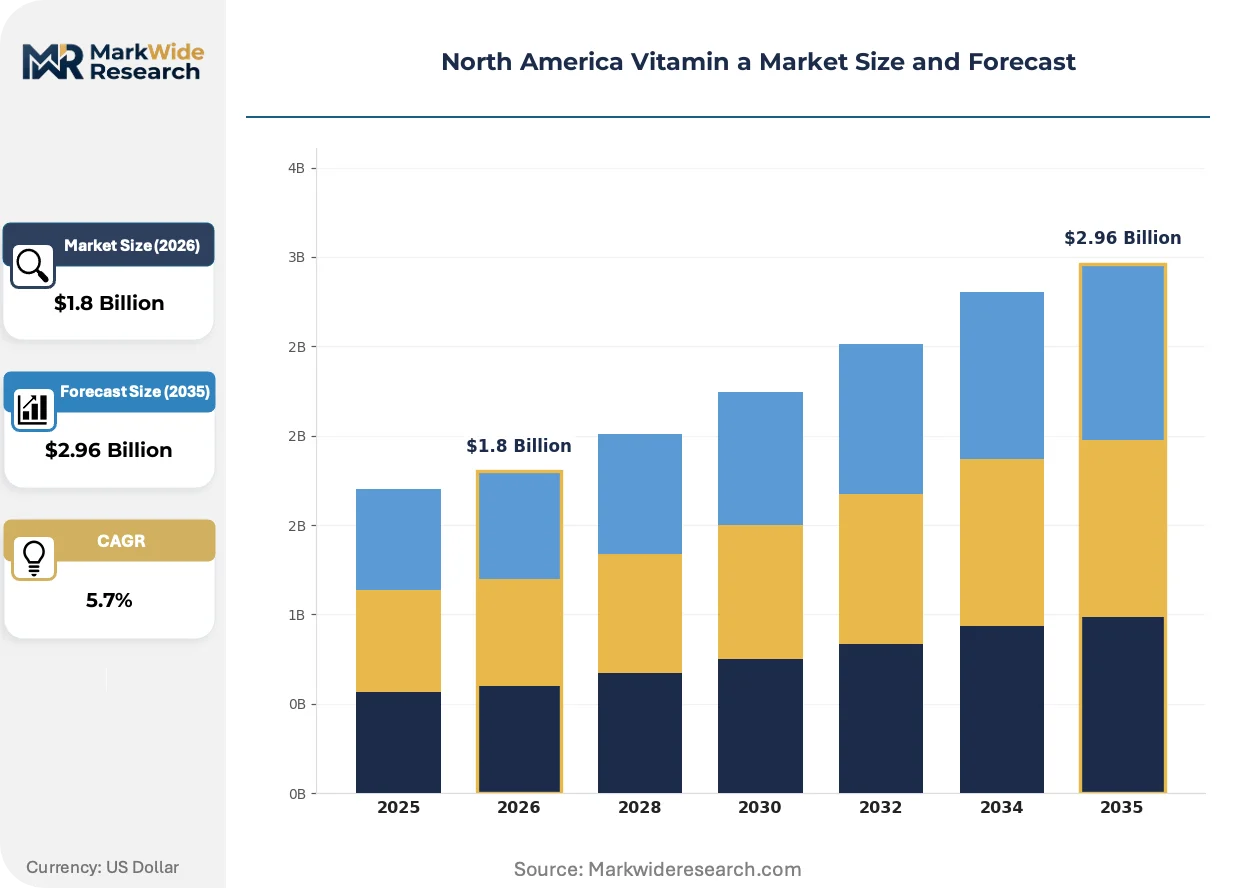
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Softgels, Tablets, Powders, Liquid Formulation: Natural, Synthetic, Fortified, Blends End User: Healthcare, Cosmetics, Food & Beverage, Animal Feed Distribution Channel: Online, Retail, Wholesale, Direct Sales |
| Companies Covered | DSM, BASF SE, Archer Daniels Midland Company, Lonza, BioThrive Sciences, Prinova Group LLC, Farbest Brands, Bactolac Pharmaceutical, Inc., Pharmavite, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Vitamin a Market Evolving Landscape
Formulation science and regulatory compliance automation are converging to reshape competitive capabilities across North American vitamin A manufacturing, with technology investments separating scalable producers from legacy operations.
Continuous manufacturing systems equipped with in-line near-infrared spectroscopy are automating real-time potency verification for vitamin A softgel production. Large-scale dietary supplement contract manufacturers in the United States are adopting these platforms to compress batch release timelines from weeks to days. The technology is automating quality control labor displacement while tightening specification compliance for FDA GMP audits.
Health Canada's Natural and Non-prescription Health Products Directorate is implementing enhanced post-market surveillance requirements for vitamin A products exceeding 10,000 IU per dose. The policy shift is forcing label reformulation and warning statement integration across cross-border product lines. Canadian natural health product license holders are responding by segregating SKU portfolios to isolate high-potency formulations from standard-distribution channels.
Buyer concentration among e-commerce-native wellness brands is compressing supplier negotiation cycles and unbundling traditional distributor markups. Direct-to-consumer supplement companies are bypassing wholesale intermediaries to contract directly with vitamin A premix suppliers for proprietary formulations. This channel disintermediation is most visible in California and New York, where vertically integrated wellness startups command sufficient volume to justify dedicated production runs.
North America Vitamin a Market Segmentation
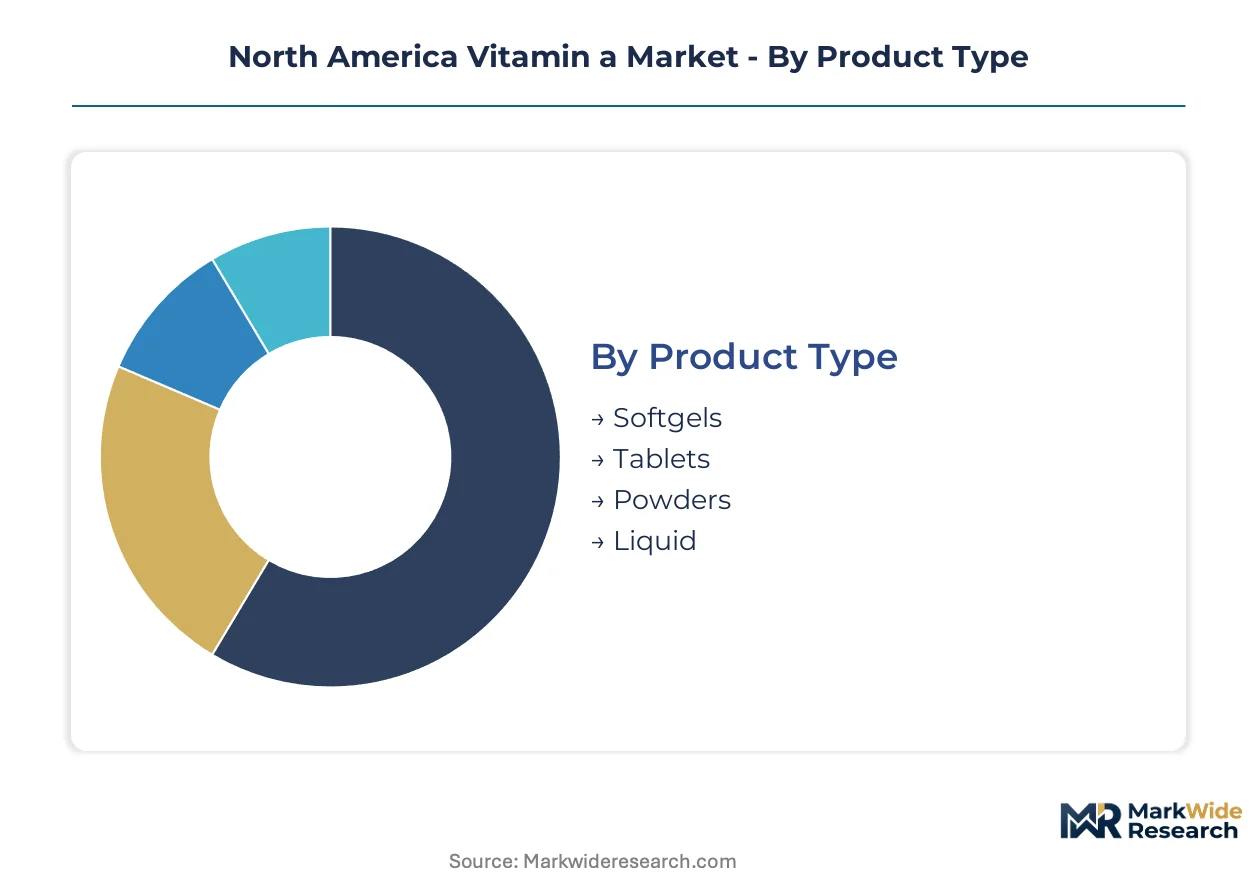
Vitamin A market segmentation reflects divergent technical requirements across human nutrition, animal health, and cosmetic applications. Product form and sourcing strategy directly determine regulatory pathway complexity and margin capture potential for North American formulators.
Product Type:
Standardized unit-dose formats dominate mass-market channels, while flexible bulk forms serve industrial fortification needs across the customization-to-standardization spectrum.
- Softgels:Gelatin or vegetable-based capsules containing oil-suspended retinol or beta-carotene at 2,500–10,000 IU per unit. United States dietary supplement manufacturers favor softgels for direct-to-consumer portfolios due to oil-solubility compatibility and established consumer familiarity with swallowable delivery.
- Powders:Microencapsulated retinoid concentrates or spray-dried beta-carotene beadlets engineered for thermal stability in extrusion and baking processes. Demand concentrates in Midwestern food manufacturing corridors where vitamin A fortification of flour, dairy, and breakfast cereals requires manufacturing flexibility.
- Tablets:Compressed retinyl palmitate or acetate formulations with disintegrant systems for rapid dissolution. Compact storage and dose precision serve institutional healthcare and pharmacy channels.
- Liquid:Oil-based or emulsified retinoid solutions dosed via dropper or pump for pediatric and geriatric populations with swallowing difficulties. Pediatric nutrition programs in Texas and California sustain regional demand.
Leading the category by volume: Softgels. Growing fastest: Powders.
Formulation:
Cost tier stratification separates premium-positioned natural claims from commodity synthetic sourcing, with fortified intermediates occupying the mid-market.
- Synthetic:Petrochemical-derived retinol and retinyl esters produced via BASF SE and DSM bridge facilities. Cost advantages sustain dominance in animal feed premixes and mass-market healthcare applications where label claims do not command price premiums.
- Natural:Fermentation-derived beta-carotene from microbial strains or plant-extracted carotenoids. Clean-label positioning captures premium pricing in cosmetic serums and organic-certified supplements sold through California wellness retailers.
- Fortified:Vitamin A premixes standardized for specific food matrix incorporation with enhanced oxidative stability. Dairy processors in Wisconsin and grain millers in Kansas specify fortified intermediates to meet federal school nutrition mandates.
- Blends:Multi-vitamin complexes combining retinoids with vitamin D, E, or K for synergistic absorption claims. Direct-to-consumer subscription brands formulate proprietary blends for algorithm-driven personalized nutrition regimens.
Volume leader: Synthetic. Steepest expansion trajectory: Natural.
End User:
Application maturity varies sharply, with established pharmaceutical-grade demand contrasting against emerging cosmetic bioactive positioning.
- Healthcare:Prescription and over-the-counter formulations for vision support, immune modulation, and dermatological therapy. FDA GMP compliance requirements concentrate manufacturing among validated dietary supplement contract manufacturers in Utah and North Carolina.
- Cosmetics:Topical retinol, retinal, and retinyl palmitate in anti-aging serums and moisturizers. Bakuchiol substitution pressure is compressing addressable market for traditional retinol in premium skincare lines marketed through New York and Los Angeles beauty retailers.
- Food & Beverage:Mandatory and discretionary fortification of dairy, edible oils, and grain products. Federal food assistance program specifications sustain baseline demand for vitamin A-fortified staples distributed through USDA channels.
- Animal Feed:Retinyl acetate and palmitate premixes for poultry, swine, and aquaculture nutrition. Integrated livestock operations in Iowa and North Carolina specify synthetic retinoid premixes for feed conversion efficiency.
Healthcare commands volume leadership. Cosmetics gains share fastest.
Distribution Channel:
Customer-type concentration drives channel bifurcation between high-velocity retail and disintermediated direct procurement.
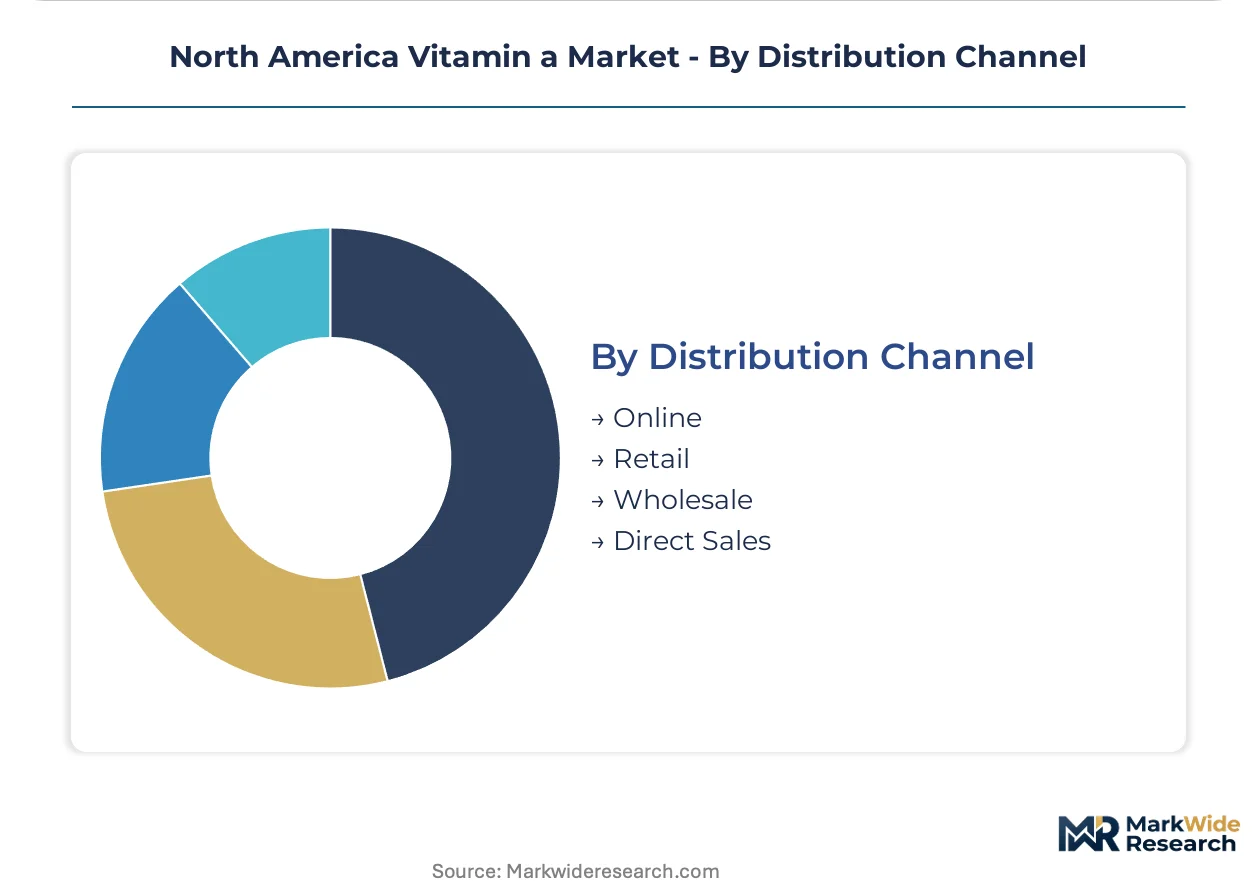
- Retail:Pharmacy, mass merchandiser, and specialty health store placement of branded vitamin A supplements. Shelf-space competition in CVS, Walgreens, and Target locations drives promotional spending and slotting fee structures.
- Online:E-commerce-native wellness brands and Amazon marketplace sellers capturing algorithm-driven search visibility. California and New York vertically integrated startups bypass wholesale markups through direct-to-consumer subscription models.
- Wholesale:Distributor intermediaries supplying independent pharmacies, natural product retailers, and regional grocery chains. Consolidation among national distributors is compressing supplier negotiation cycles.
- Direct Sales:Bulk vitamin A premix and active pharmaceutical ingredient procurement by food manufacturers, contract formulators, and animal nutrition companies. Dedicated production runs serve volume purchasers with proprietary specification requirements.
Retail maintains volume dominance. Online expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Synthetic retinol production clusters in New Jersey and Louisiana anchor North American vitamin A supply security. Fermentation-derived beta-carotene facilities concentrate in Midwestern agricultural corridors. These feedstock localities determine regional manufacturing economics and regulatory compliance burdens.
United States
Dietary supplement manufacturers in Utah and North Carolina drive demand for FDA-compliant vitamin A premixes. The FDA's amplified GMP inspection frequency accelerates facility upgrades among contract manufacturers. Salt Lake City hosts validated softgel production lines serving direct-to-consumer wellness brands.
Canada
Health Canada's Natural and Non-prescription Health Products Directorate imposes parallel documentation standards on cross-border suppliers. Enhanced post-market surveillance requirements for high-potency vitamin A products force label reformulation. Toronto-area natural health product license holders segregate SKU portfolios to isolate formulations exceeding 10,000 IU per dose.
Mexico
Federal food assistance program specifications sustain import demand for vitamin A-fortified dairy and grain premixes. COFEPRIS alignment with FDA quality benchmarks streamlines cross-border ingredient shipments. Guadalajara's food processing corridor concentrates contract manufacturing for North American fortified staple distribution.
North America Vitamin a Market Competitive Landscape
Backward integration into fermentation-derived feedstocks dominates the current competitive landscape. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive retinoid synthesis, mid-scale premix specialists serving regional formulators, and contract manufacturers competing on FDA compliance automation. Strategic archetypes separate around synthetic versus natural sourcing claims and direct-to-consumer channel control versus wholesale distribution. Capacity expansion in microbial strain engineering and M&A targeting personalized nutrition platforms represent the dominant competitive moves.
Among Dutch and German chemical conglomerates, DSM and BASF SE exemplify the upstream-integrated archetype through controlled beta-carotene fermentation and synthetic retinol bridge facilities. Pharmavite occupies a position within the direct-to-consumer channel control tier, anchoring mass-market supplement visibility through retail pharmacy placement. These three companies represent distinct strategic vectors: feedstock security through backward integration, production scale at transatlantic facilities, and brand equity capture in consumer-facing formulations.
| Leading Market Players |
|---|
| DSM |
| BASF SE |
| Archer Daniels Midland Company |
| Lonza |
| BioThrive Sciences |
| Prinova Group LLC |
| Farbest Brands |
| Bactolac Pharmaceutical, Inc. |
| Pharmavite |
| Others |
Value Network & Pricing Analysis
Analytical chemistry talent concentration in Utah and North Carolina contract laboratories creates labor-cost differentials that widen pricing-tier spreads between mass-market softgels and premium natural-formulation SKUs. FDA GMP compliance automation investments at these facilities compress per-unit testing costs for high-volume synthetic retinol production while specialized HPLC expertise premiums sustain elevated pricing for fermentation-derived beta-carotene formulations targeting California wellness retailers.
Pricing Analysis
Warranty-like service bundling separates contract manufacturing tiers, with validated softgel producers including batch-release documentation and audit support within base pricing while commodity premix suppliers unbundle these compliance services. Three-tier pricing structure across premium natural, standard synthetic, and economy animal-feed levels reflects certification-grade differentiation and volume-scale thresholds. Price differentiation stems from Health Canada cross-border documentation requirements and organic certification premiums. Pricing pressure intensifies in synthetic retinol tiers as BASF SE and DSM bridge facility expansions compress feedstock costs. Animal feed premix buyers exhibit highest price sensitivity; cosmetic clean-label purchasers show lowest.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume food fortification demand from Midwestern dairy processors and grain millers, while distributor intermediaries serve fragmented retail pharmacy and independent natural products accounts. Synthetic retinol production concentrates in New Jersey and Louisiana petrochemical corridors; fermentation-derived beta-carotene facilities cluster in Midwestern agricultural regions near glucose feedstock sources. Raw material dependencies include petrochemical intermediates for retinol synthesis, corn-derived glucose for microbial fermentation, and gelatin or vegetable cellulose for capsule shells. Supply chain risk centers on European-North American bridge facility concentration creating single-source vulnerability during transatlantic logistics disruptions. Distribution runs through validated contract manufacturers for healthcare-grade formulations and bulk premix suppliers for industrial fortification applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North American vitamin A supply is structurally constrained by analytical methodology talent scarcity, with validated HPLC and mass spectrometry expertise concentrated among contract laboratories propping pricing power for compliant manufacturers.
For Market Incumbents: Deepen backward integration into fermentation-derived beta-carotene to secure feedstock cost discipline against synthetic retinol price volatility. Expand Utah and North Carolina softgel capacity to capture direct-to-consumer subscription brand demand. FDA's amplified GMP inspection frequency threatens non-automated competitors; continuous manufacturing platforms with in-line spectroscopy defend quality control labor displacement advantages. For New Entrants and Emerging Players: Health Canada's Natural and Non-prescription Health Products Directorate enhanced post-market surveillance requirements open a window for compliant mid-tier formulators targeting segregated high-potency SKU portfolios. Bakuchiol substitution in premium skincare creates white-space for algae-derived carotenoid positioning. Personalized nutrition algorithm partnerships in California and New York offer the most penetrable go-to-market angle through vertically integrated wellness startup procurement. For Investors and Strategic Acquirers: Re-rating potential sits with FDA-validated contract manufacturers given continuous manufacturing technology convergence compressing batch release timelines. Long-term viability favors facilities with captive analytical chemistry expertise and Health Canada dual-certification capabilities. Watch CRISPR-edited staple crop biofortification commercialization as inflection indicator threatening traditional premix demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstocks | DSM's microbial strain engineering investments reduce beta-carotene price volatility exposure for North American formulators. |
| Continuous Manufacturing Platform Deployment | In-line near-infrared spectroscopy adoption at Utah facilities compresses FDA GMP audit preparation timelines from weeks to days. |
| Health Canada Dual-Certification Investment | Alignment between FDA and NNHPD standards reduces cross-border SKU segregation costs for US manufacturers. |
| Direct-to-Consumer Channel Control | Pharmavite's Nature Made retail pharmacy placement captures algorithm-driven subscription brand bypass threats. |
| CRISPR Biofortification Technology Development | Precision fermentation convergence enables novel vitamin A precursor sourcing outside petrochemical supply chains. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this North American vitamin A market assessment. Primary interviews with dietary supplement contract manufacturing executives, FDA regulatory affairs consultants, Health Canada natural health product license holders, and Midwestern food fortification procurement managers combined with FDA GMP inspection databases, USDA school nutrition program specifications, and Health Canada NNHPD submission records. Bottom-up softgel and powder volume estimates triangulated against top-down premix supplier revenue analysis.
Segment-level modeling captured product form granularity across softgels, powders, tablets, and liquids; formulation differentiation between synthetic, natural, fortified, and blended variants; end-use splits across healthcare, cosmetics, food and beverage, and animal feed; and distribution channel dynamics spanning retail, online, wholesale, and direct sales. CAGRs derived from trend extrapolation of FDA dietary supplement shipment data and Health Canada natural health product license issuance patterns across the projection horizon. Fermentation capacity expansion timelines and GRAS affirmation pathway probabilities informed bio-based retinoid adoption curves.
The model assumes a particular technology adoption path; alternative pathways for CRISPR-edited staple crop commercialization would alter the outlook for traditional premix demand. Forecasts incorporate assumptions regarding FDA GMP enforcement intensity and Health Canada-NNHPD harmonization progress that regulatory shifts could revise. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Fat Soluble Vitamins Market
Vitamin Fortified
Global Antioxidant Vitamins Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
North America Vitamin Fortified and Mineral Enriched Food and Beverages Market
Vitamin Fortified
Synthetic Vitamin E Market
Vitamin Fortified
Vitamin Yeast Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
North America Vitamin D Market
Vitamin Fortified
Vitamin D3 Market
Vitamin Fortified
Vitamin B Market
Vitamin Fortified
Pantothenic Acid Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Retinyl Linoleate Market
Vitamin Fortified
Europe Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Fortified Baby Food Market