
 Fortified Juices Market | 2026-2036
Fortified Juices Market Size, Share, and Industry Trends Forecast 2026-2036
Fortified Juices Market Analysis
Capital-intensity divergence between in-house extraction and toll-processing operators is bifurcating competitive returns across the fortified juices landscape. PepsiCo Inc. leverages captive citrus sourcing networks to control input quality for its Tropicana fortification lines. Nestlé S.A. anchors its position through dairy-juice hybrid R&D facilities in Switzerland and Mexico. The Coca-Cola Company competes via Minute Maid's global distribution infrastructure, extending fortified variants into emerging channels.
Fortified juices are beverages enhanced with micronutrients, bioactive compounds, or functional ingredients beyond natural fruit composition, typically processed through cold-aseptic filling or high-pressure processing to preserve nutrient stability. These products serve commercial purposes spanning pediatric nutrition support, adult dietary supplementation, and clinical hydration protocols. Vitamin-enriched ready-to-drink formats occupy the dominant margin pool due to premium positioning and pharmacy channel penetration, while mineral-infused concentrates are gaining fastest in foodservice bulk applications. Fiber-fortified variants sustain niche premiums through digestive health claims targeted at senior citizens and health enthusiasts.
The FDA governs nutrient content claims and fortification ceilings under 21 CFR 101, while EFSA establishes maximum permitted levels for vitamins and minerals in EU-sold juices under the Fortification Regulation. India's FSSAI mandates standardized fortification protocols for packaged fruit beverages sold through retail and institutional channels. Stakeholders must monitor evolving micronutrient ceilings and front-of-pack labeling mandates as regulatory divergence between major jurisdictions reshapes formulation strategies and cross-border product registration requirements.
Market Dynamics
Pediatric nutrition programs and institutional procurement mandates are restructuring demand toward vitamin-enriched formulations, while regulatory divergence between FDA nutrient ceilings and ANVISA functional food standards forces parallel formulation tracks.
Growth Catalysts
- High-pressure processing (HPP):Cold-aseptic filling technologies preserve heat-sensitive micronutrient stability in vitamin-enriched SKUs. Brazil's tropical fruit processing infrastructure supports local HPP capacity expansion.
- FSSAI fortification mandates:India's standardized protocols for packaged fruit beverages accelerate institutional channel penetration. Retail and foodservice operators reformulate to meet micronutrient floor requirements.
- Pharmacy channel expansion:Clinical hydration protocols and adult dietary supplementation drive ready-to-drink placement. Vitamin-enriched formats command shelf space adjacent to pediatric nutrition products.
Market Restraints
- Citrus concentrate volatility:Weather-driven input cost swings compress margins for toll-processing operators lacking captive sourcing.
- EFSA maximum permitted levels:Fortification ceilings under EU Fortification Regulation cap vitamin D and iron concentrations, forcing reformulation for cross-border SKUs.
- Mineral-fortified concentrates:Bulk foodservice applications face substitution pressure from private-label mineral water and functional beverage alternatives.
Strategic Opportunities
- Fiber-fortified digestive health:Senior citizen and health enthusiast segments sustain premium positioning through soluble fiber claims. Pharmacy and direct-to-consumer channels support margin capture.
- Dairy-juice hybrid R&D:Convergence of probiotic delivery systems with fruit matrices opens clinical nutrition applications. Switzerland and Mexico host pilot facilities for stability testing.
- Front-of-pack labeling mandates:Nutri-Score and equivalent systems in EU member states create first-mover advantage for clean-label fortification architectures.
Industry Challenges
- Cross-border registration complexity:Divergent micronutrient ceilings between FDA 21 CFR 101 and EFSA frameworks require jurisdiction-specific dossiers, extending time-to-market.
- Cold-chain capex intensity:HPP and aseptic filling equipment demands specialized infrastructure, favoring capitalized operators over mid-scale toll processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fortified Juices Market |
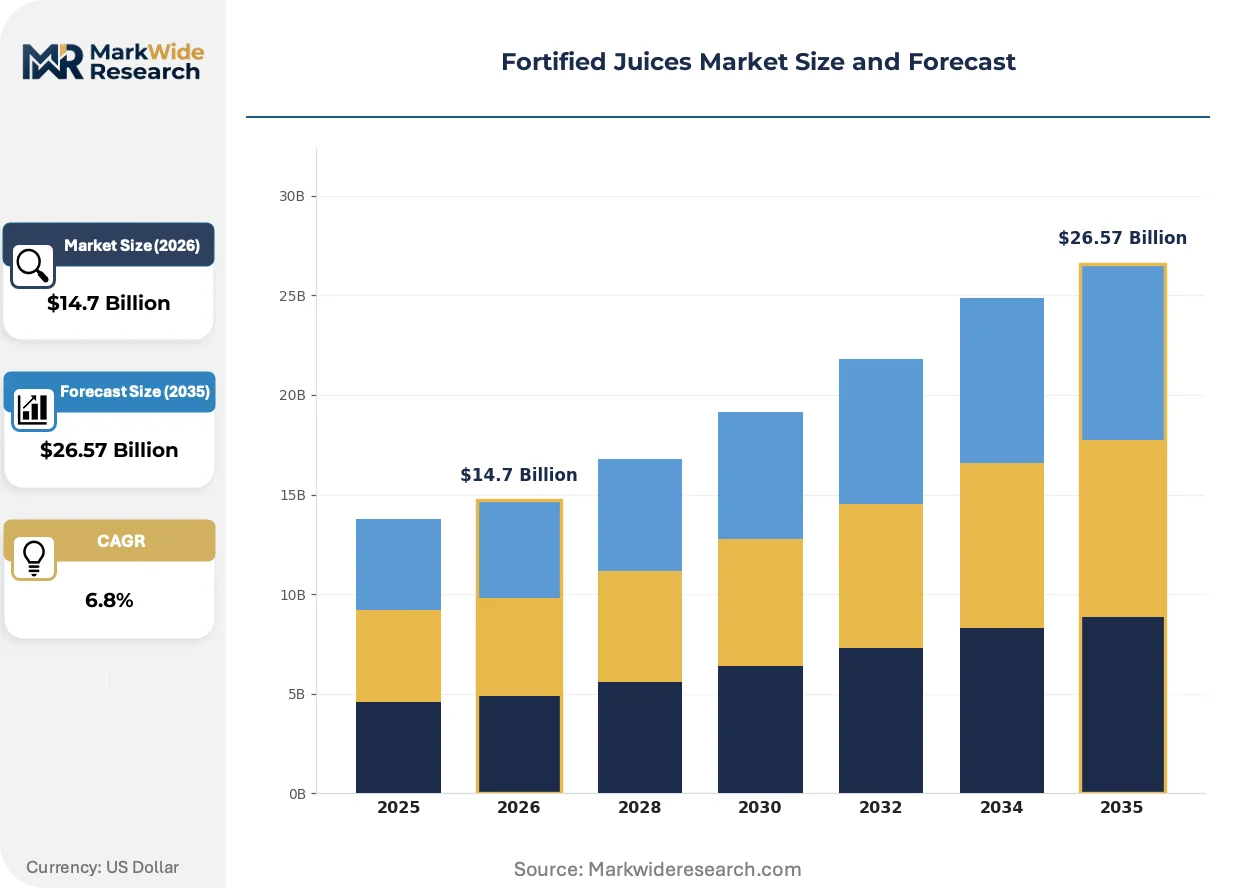
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamin-Enriched, Mineral-Infused, Herbal-Enhanced, Fiber-Fortified End User: Retail Consumers, Health Enthusiasts, Children, Senior Citizens Distribution Channel: Supermarkets, Online Retailers, Convenience Stores, Health Food Shops Formulation: Ready-to-Drink, Concentrates, Powdered, Organic |
| Companies Covered | Hain Celestial, Sudzucker AG, PepsiCo Inc., Nestlé S.A., Doehler Group, The Coca-Cola Company, Evolution Fresh, Keurig Dr Pepper Inc., SunOpta Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fortified Juices Market Emerging Trajectories
Cold-aseptic technologies and micronutrient stabilization chemistry are compressing traditional thermal processing economics, while front-of-pack labeling systems reward transparency in fortification sourcing.
High-pressure processing (HPP) applies isostatic pressure to inactivate pathogens without thermal degradation of vitamin C and folate. Pediatric nutrition manufacturers and premium juice operators adopt HPP at accelerating rates for refrigerated distribution. Thermal pasteurization is supplanting legacy hot-fill methods in vitamin-enriched segments where nutrient retention determines shelf positioning.
The FDA's updated nutrient content claim requirements under 21 CFR 101 redefine fortification thresholds and label architecture for North American supply chains. Manufacturers must recalculate serving-size declarations and health claim eligibility, compressing reformulation timelines. Vitamin-enriched ready-to-drink formats face the steepest compliance burden as pharmacy channel penetration depends on precise claim substantiation.
Institutional procurement consolidation in healthcare and education channels concentrates buyer power around certified fortification protocols. Bulk concentrate contracts now specify micronutrient testing cadences and third-party verification, displacing spot-market purchasing. Brazil's ANVISA-registered facilities capture disproportionate tender volume as pediatric nutrition programs expand through federal procurement frameworks.
Fortified Juices Market Segmentation
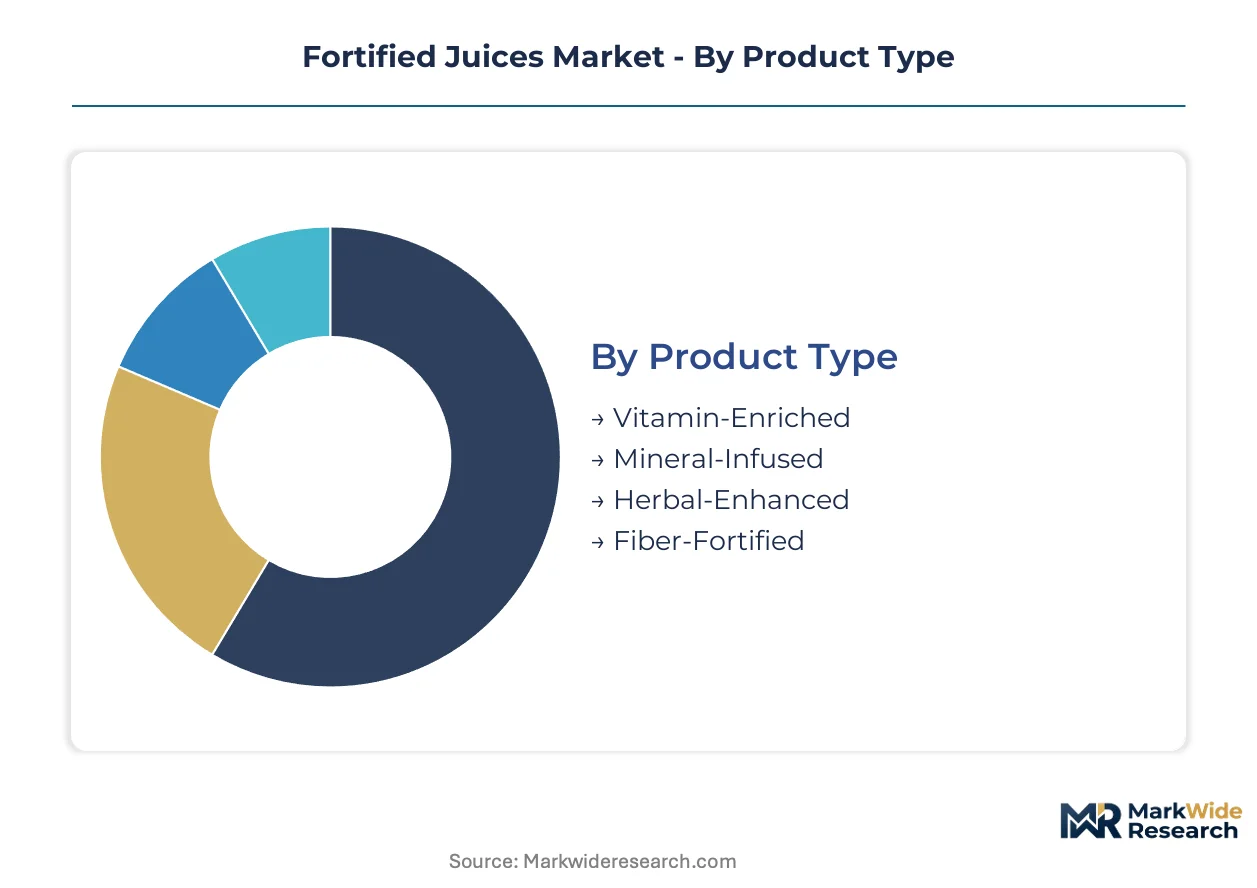
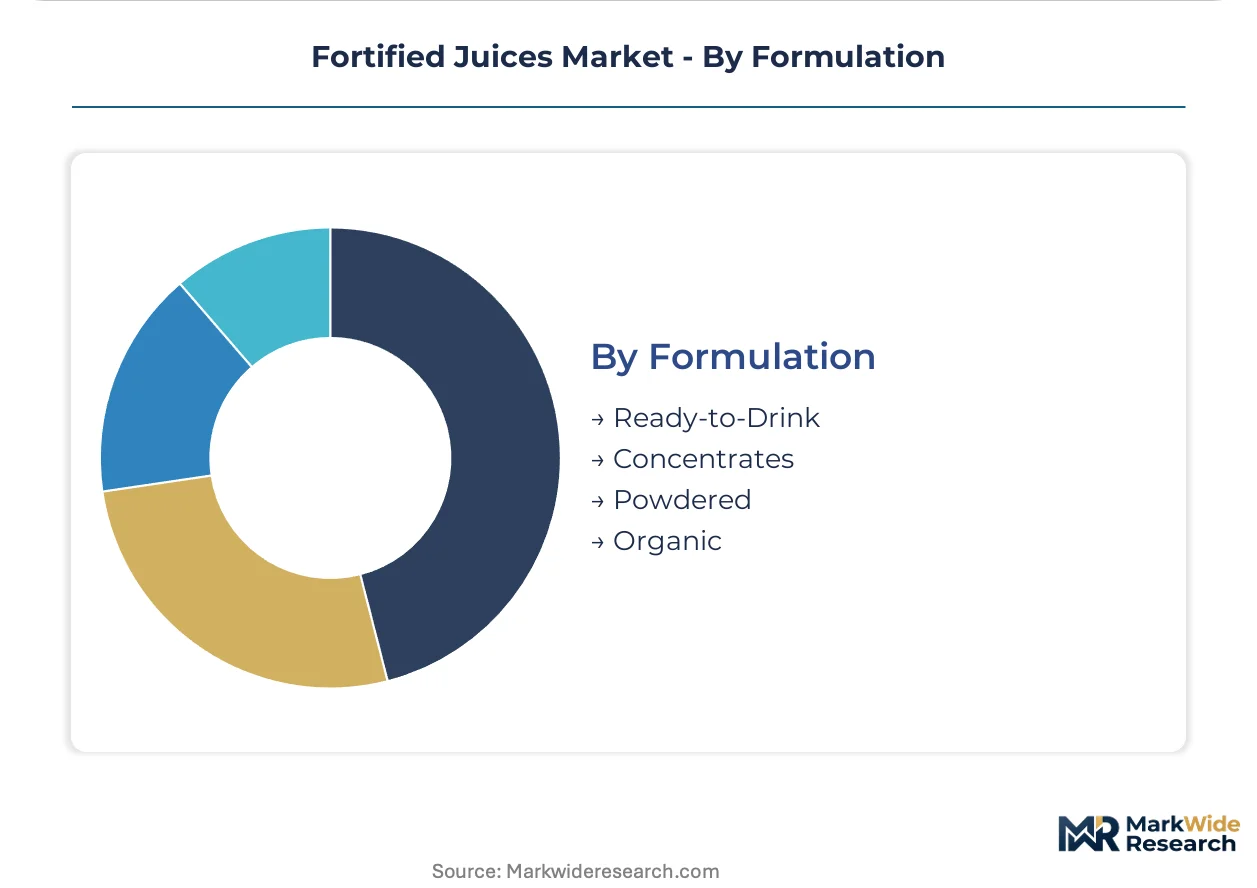
Segmentation in fortified juices reveals how micronutrient positioning, channel access, and formulation technology split margin pools across distinct buyer groups. Manufacturers must align R&D investment with the specific stability requirements and claim substantiation demands of each segment cluster.
Product Type:
Premium margin capture concentrates in clinically positioned formats where pharmacy channel placement and pediatric nutrition tenders command price premiums over commodity juice alternatives.
- Vitamin-Enriched:Formulations enhanced with heat-stable and cold-processed vitamins including C, D, and B-complex variants. Demand concentrates in pediatric nutrition programs across Brazil and India where ANVISA and FSSAI fortification mandates create institutional procurement volume. Cold-aseptic filling investments by PepsiCo and Nestlé anchor supply security for pharmacy channel placement.
- Mineral-Infused:Electrolyte and trace mineral fortification targeting hydration protocols and adult dietary supplementation. Foodservice bulk applications in healthcare and education channels drive volume, though substitution pressure from functional mineral waters compresses pricing power in unbranded concentrate segments.
- Herbal-Enhanced:Botanical extracts combined with fruit matrices for functional positioning around immunity or energy claims.
- Fiber-Fortified:Soluble fiber integration supporting digestive health claims for senior citizens and health enthusiasts.
The dominant share belongs to Vitamin-Enriched, while Fiber-Fortified is closing the gap fastest through pharmacy and direct-to-consumer channel expansion.
End User:
Buyer sophistication and claim verification requirements separate institutional procurement from discretionary retail purchasing.
- Retail Consumers:Mass-market purchasers selecting fortified juices based on front-of-pack labeling and price-positioning. Supermarket and convenience store distribution dominates, with Nutri-Score and equivalent systems in EU member states reshaping purchase decisions toward clean-label architectures.
- Health Enthusiasts:Performance-oriented buyers prioritizing bioavailability claims and third-party verification. Online retailers and health food shops capture this segment through subscription models and direct-to-consumer stability data disclosure.
- Children:Pediatric nutrition programs in institutional channels specify micronutrient testing cadences and certified fortification protocols. Federal procurement frameworks in Brazil concentrate tender volume toward ANVISA-registered facilities.
- Senior Citizens:Digestive health and clinical hydration protocols drive pharmacy channel placement for fiber-fortified and mineral-infused variants.
Children and Health Enthusiasts together command the steepest premium tiers, with Senior Citizens expanding most quickly as aging demographics shift pharmacy shelf allocation.
Distribution Channel:
Cold-chain infrastructure requirements and buyer concentration determine which channels reward branded investment versus private-label substitution.
- Supermarkets:High-volume retail placement requiring front-of-pack compliance with evolving labeling mandates. EFSA nutrient ceilings and FDA 21 CFR 101 thresholds force jurisdiction-specific SKU management.
- Online Retailers:Direct-to-consumer fulfillment enabling stability data transparency and subscription-based replenishment for health enthusiasts.
- Convenience Stores:Impulse-driven purchasing of ready-to-drink formats with shorter shelf-life requirements and ambient distribution economics.
- Health Food Shops:Curated assortment of organic and herbal-enhanced variants with premium positioning through staff recommendation and sampling protocols.
Supermarkets retain volume leadership, though Online Retailers are gaining share fastest through subscription model penetration and cold-chain logistics maturation.
Formulation:
Processing technology selection and nutrient stability chemistry separate refrigerated premium positioning from ambient commodity economics.
- Ready-to-Drink:Single-serve formats processed through HPP or thermal pasteurization for vitamin retention. Pharmacy channel placement and pediatric nutrition tenders demand precise claim substantiation under FDA and EFSA frameworks.
- Concentrates:Bulk formulations for foodservice and institutional procurement with mineral fortification for hydration protocols. Weather-driven citrus input volatility compresses margins for operators lacking captive sourcing networks.
- Powdered:Dehydrated formats with extended shelf stability for emergency nutrition programs and military procurement.
- Organic:Certified fruit sourcing with restricted fortification ingredient lists under USDA Organic and EU Organic regulations.
Ready-to-Drink formulations dominate value capture, while Concentrates maintain volume leadership in institutional bulk contracting.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in fortified juices reveal Brazil as a net supplier of tropical fruit concentrates while the United States and Germany remain import-dependent for vitamin-stable formulations. Trade flows concentrate around ANVISA-registered Brazilian facilities serving pediatric nutrition tenders and FDA-compliant North American pharmacy channels.
United States
Pediatric nutrition programs and clinical hydration protocols drive pharmacy channel placement for vitamin-enriched ready-to-drink formats. The FDA's updated nutrient content claim requirements under 21 CFR 101 are reshaping label architecture and fortification thresholds. Cold-aseptic filling investments concentrate in Florida and California processing corridors serving Minute Maid and Tropicana fortification lines.
Brazil
Tropical fruit processing infrastructure and expanding federal procurement frameworks for institutional nutrition are accelerating local HPP capacity expansion. ANVISA's functional food regulations create favorable registration pathways for both domestic operators and multinational joint ventures. São Paulo state hosts the densest concentration of ANVISA-registered facilities capturing disproportionate tender volume from pediatric nutrition programs.
Germany
Foodservice bulk applications and adult dietary supplementation drive mineral-infused concentrate demand through healthcare and education channels. EFSA maximum permitted levels under the EU Fortification Regulation cap vitamin D and iron concentrations, forcing reformulation for cross-border SKUs. The North Rhine-Westphalia logistics cluster anchors distribution infrastructure for EU-wide fortified juice distribution.
India
Institutional channel penetration accelerates as FSSAI mandates standardized fortification protocols for packaged fruit beverages sold through retail and foodservice. Retail consumers and health enthusiasts represent divergent buyer segments with distinct stability verification requirements. Maharashtra and Gujarat processing hubs are expanding micronutrient testing cadences to meet federal procurement specifications.
Switzerland
Dairy-juice hybrid R&D facilities serve as pilot centers for probiotic delivery system integration with fruit matrices. Clinical nutrition applications and premium positioning through pharmacy channels sustain margin capture above commodity juice alternatives. The Basel-Zurich corridor concentrates stability testing infrastructure for Nestlé's European fortification operations.
Fortified Juices Market Vendor Landscape
Concentration sits with multinational beverage conglomerates possessing captive citrus sourcing networks and global cold-chain distribution infrastructure. The competitive structure bifurcates between capitalized in-house extraction operators and margin-compressed toll-processing specialists. Three archetypes dominate: integrated fruit processors with backward sourcing control, dairy-juice hybrid innovators leveraging probiotic convergence, and pharmacy-channel specialists commanding premium positioning through clinical claim substantiation. Dominant competitive moves include strategic partnerships with tropical fruit cooperatives and portfolio diversification into fiber-fortified digestive health segments.
Within the integrated beverage conglomerate tier, PepsiCo Inc., Nestlé S.A., and The Coca-Cola Company occupy positions defined by distribution scale and fortification R&D infrastructure. PepsiCo exemplifies the captive sourcing archetype through controlled citrus input quality for Tropicana lines. Nestlé anchors the dairy-juice hybrid innovation vector with stability testing facilities in Switzerland and Mexico. The Coca-Cola Company represents global channel extension capability through Minute Maid's pharmacy and foodservice penetration. These three entities collectively illustrate how capital intensity and regulatory compliance infrastructure create defensive positioning against toll-processing competitors.
| Leading Market Players |
|---|
| Hain Celestial |
| Sudzucker AG |
| PepsiCo Inc. |
| Nestlé S.A. |
| Doehler Group |
| The Coca-Cola Company |
| Evolution Fresh |
| Keurig Dr Pepper Inc. |
| SunOpta Inc. |
| Others |
Supply Flow & Price Mechanics
ANVISA functional food registration in Brazil gates both supplier qualification and price differentiation simultaneously, concentrating premium capture among ANVISA-registered facilities while relegating non-certified operators to commodity concentrate tiers.
Pricing Analysis
Configured-to-order pricing for pediatric nutrition tenders commands substantial premiums over standard retail SKUs. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-channel vitamin-enriched formats from foodservice mineral concentrates and private-label ambient juices. Price differentiation rests on certification grade and captive sourcing control. Cost compression in toll-processing tiers is intensifying because citrus concentrate volatility erodes margins for operators lacking backward integration. Retail consumers exhibit highest price sensitivity, while institutional procurement committees prioritize micronutrient verification over unit cost.
Supply Chain Analysis
Port congestion along Santos-São Paulo corridors and container availability constraints on Asia-Brazil trade lanes elevate inbound logistics costs for vitamin premix imports. Supply concentrates in Brazil, India, and Switzerland, with São Paulo state hosting the densest ANVISA-registered processing cluster. Raw material dependencies center on tropical fruit concentrates, vitamin premixes, and aseptic packaging films. Single-source vulnerability in citrus concentrate supply creates structural exposure to weather-driven crop failures. Distribution runs through cold-chain logistics networks serving pharmacy and institutional channels, with ambient distribution reserved for commodity retail tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of HPP-capable processing infrastructure and ANVISA-certified stability testing capacity constrains supply expansion, rewarding early movers who locked in equipment and regulatory dossiers ahead of tender volume concentration.
For Market Incumbents: Secure captive citrus sourcing networks in Brazil and Florida to defend input quality control against toll-processing competitors. Expand ANVISA-registered capacity in São Paulo state ahead of federal pediatric nutrition procurement consolidation. Cold-chain capex intensity threatens mid-scale operators; incumbents should preempt capacity constraints through equipment pre-commitment. For New Entrants and Emerging Players: Anchor in fiber-fortified digestive health segments where pharmacy channel penetration remains underdeveloped relative to vitamin-enriched saturation. Target senior citizen demographics through direct-to-consumer subscription models with stability data transparency. Partner with existing HPP operators to bypass capital barriers while building brand equity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across refrigerated ready-to-drink fortification, favoring asset-heavy integrated processors over toll-dependent specialists. Long-term viability tilts toward operators with backward integration into tropical fruit sourcing and forward integration into pharmacy distribution. Acquisition targets should display ANVISA or FDA dual-registration capability. Monitor ANVISA tender award velocity as inflection signal for institutional demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| HPP Capacity Expansion | Brazil's tropical fruit infrastructure supports local micronutrient stability processing for pharmacy channels. |
| ANVISA Dual-Registration | FDA-ANVISA parallel dossiers reduce cross-border registration complexity for multinational juice portfolios. |
| Captive Citrus Sourcing | Controlled input quality insulates Tropicana and Minute Maid lines from concentrate volatility. |
| Fiber-Fortified Line Extension | Soluble fiber claims capture senior citizen pharmacy shelf allocation ahead of mineral-water substitution. |
| Dairy-Juice Hybrid R&D | Swiss and Mexican pilot facilities test probiotic-fruit matrix stability for clinical nutrition applications. |
Methodological Framework
Desk research of customs trade databases, FSSAI fortification guidelines, and ANVISA registration filings preceded structured interviews with pediatric nutrition procurement officers, HPP equipment vendors, tropical fruit cooperative managers, and pharmacy category buyers. Primary fieldwork combined with secondary validation across FDA 21 CFR 101 documentation, EFSA maximum permitted level determinations, and Brazilian federal tender records. Bottom-up volume modeling triangulated against top-down value estimates from Nielsen retail audit data and institutional procurement disclosures.
Variance decomposition across product type, end user, distribution channel, and formulation technology dimensions shaped analytical framework construction over the projection horizon. CAGRs derived from segment-level growth rate reconciliation against macroeconomic drivers and regulatory inflection points. Modeled inputs included HPP adoption curves, ANVISA registration timelines, and pharmacy channel penetration rates by micronutrient category.
Decision-makers should treat outputs as directional under assumptions of stable ANVISA-FDA regulatory divergence and continued pediatric nutrition program expansion; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for abrupt tariff regime shifts or citrus crop failures. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Vitamin C Market
Vitamin Fortified
Prenatal Vitamin Preparation Market
Vitamin Fortified
Asia-Pacific Feed Vitamins Market
Vitamin Fortified
Vitamin K Market
Vitamin Fortified
Vitamin D Market
Vitamin Fortified
Vitamin AD Drops Market
Vitamin Fortified
Vitamin Fortified and Mineral Enriched Food & Beverage Market
Vitamin Fortified
Calcium-Fortified Bread Market
Vitamin Fortified
Middle East and Africa Vitamin a Market
Vitamin Fortified
Food Grade Vitamin C Market
Vitamin Fortified
Middle East and Africa Food Fortifying Agents Market
Vitamin Fortified
Asia-Pacific Vitamin a Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Riboflavin Market
Vitamin Fortified
Beta Carotene Market