
 Colecalciferol Market | 2026-2036
Colecalciferol Market Size, Share, and Industry Trends Forecast 2026-2036
Colecalciferol Market Insights
Pharmaceutical-grade contract manufacturing revenue is rewriting margin distribution across the Colecalciferol value chain. DSM-Firmenich leverages backward integration into 7-dehydrocholesterol fermentation to secure feedstock consistency. Zhejiang Garden Biochemical High-Tech dominates crystallization capacity and anchors supply for European generics producers. Kingdomway specializes softgel encapsulation and competes on dosage-form flexibility for North American supplement brands.
Colecalciferol, chemically designated cholecalciferol or vitamin D3, functions as a secosteroid prohormone synthesized industrially via ultraviolet-B irradiation of 7-dehydrocholesterol derived from lanolin or fish liver oil, with purity grades spanning feed-grade to EP/BP/USP pharmacopeial standards for calcium homeostasis and bone metabolism modulation. Tablet formulations remain the volume backbone for pharmaceutical prescriptions, while liquid drops command premium positioning in pediatric and geriatric segments where swallowing compliance drives preference. Powder grades for animal feed premixes represent a mature margin pool with limited growth upside compared to pharmaceutical and dietary supplement channels.
The FDA's Current Good Manufacturing Practice framework for dietary supplements and the European Medicines Agency's active substance master file requirements shape quality thresholds and market access conditions for Colecalciferol producers. India's CDSCO Schedule H constraints on vitamin D prescription strength create channel bifurcation between over-the-counter supplements and regulated pharmaceutical dosages. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and ChP standards, as divergence in assay and impurity specifications threatens to fragment quality tiers and complicate multi-territory registration strategies.
Market Dynamics
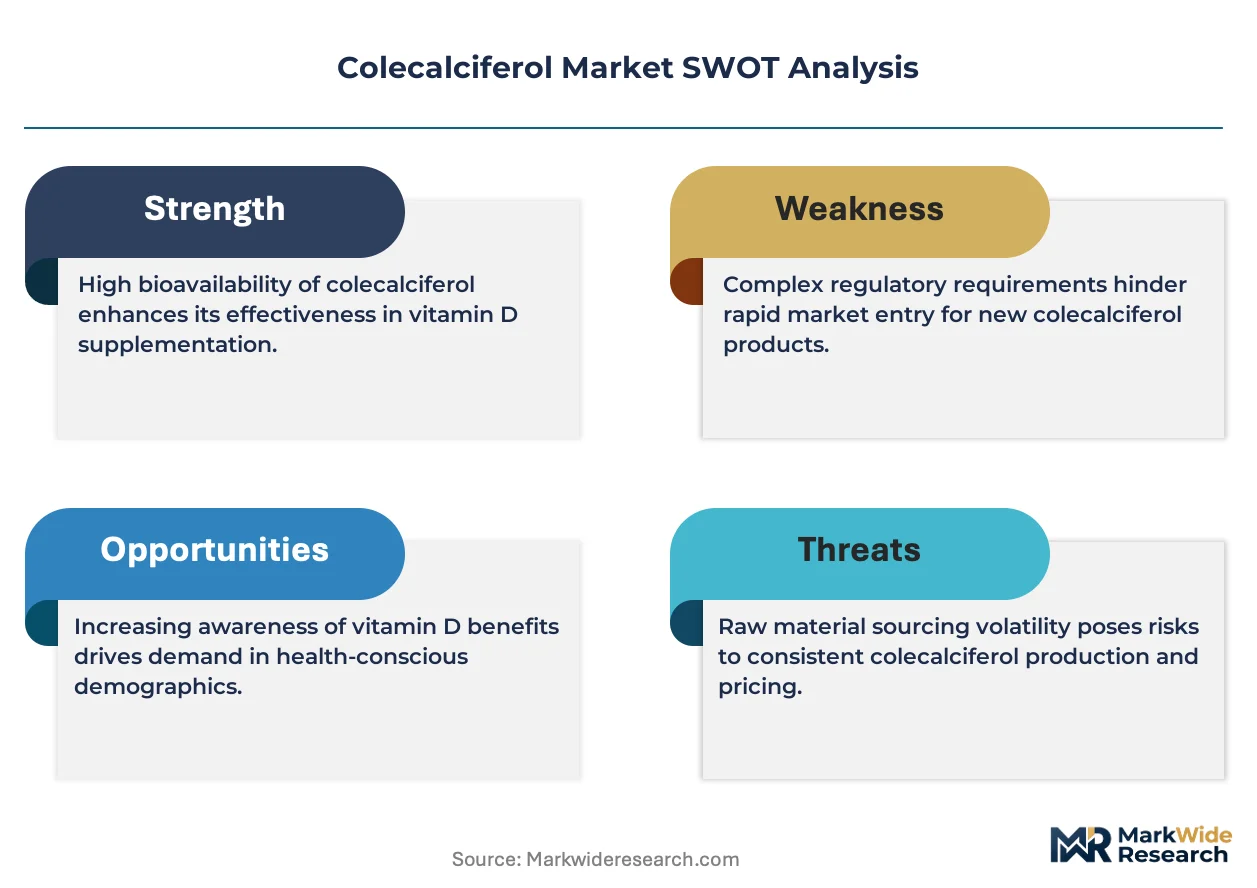
Pharmaceutical-grade crystallization capacity concentrates among a handful of specialized chemical manufacturers, creating asymmetric bargaining power that cascades through contract manufacturing networks serving both osteoporosis therapeutics and precision nutrition formulations.
Growth Catalysts
- EMA Active Substance Master File harmonization:Streamlined multi-territory registration pathways reduce time-to-market for European generics producers seeking pharmacopeial-grade supply.
- Osteoporosis management protocols:Healthcare institutions in Germany's precision nutrition cluster are expanding prophylactic vitamin D3 protocols for aging populations with elevated fracture risk profiles.
- Lanolin-derived 7-dehydrocholesterol fermentation:Biotechnology advances in feedstock biosynthesis are stabilizing precursor availability for ultraviolet-B irradiation processes.
Market Restraints
- Wool grease supply volatility:Lanolin extraction depends on Australian and New Zealand sheep husbandry cycles, exposing feedstock costs to climate and agricultural commodity swings.
- Pharmacopeial divergence:Assay and impurity specification gaps between USP, EP, and ChP standards force redundant quality testing for multi-territory suppliers.
- Plant-derived vitamin D2 substitution:Ergocalciferol from UV-treated yeast competes in vegan-positioned dietary supplements, pressuring D3 share in ethical consumer segments.
Strategic Opportunities
- Pediatric liquid formulation white space:Swallowing compliance gaps in geriatric and infant populations create premium positioning for dropper-dose delivery systems.
- India's Schedule H channel bifurcation:CDSCO prescription strength constraints separate regulated pharmaceutical dosages from over-the-counter supplements, enabling dual-brand strategies.
- Continuous manufacturing integration:Real-time release testing and process analytical technology convergence promise to compress batch cycle times for crystallization-dependent production.
Industry Challenges
- Pharmacopeial chemist scarcity:Specialized expertise in secosteroid prohormone assay methodology limits quality control staffing for EP/BP/USP certification maintenance.
- Legacy batch record systems:Paper-based manufacturing execution platforms in established crystallization facilities impede FDA Current Good Manufacturing Practice data integrity audits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colecalciferol Market |
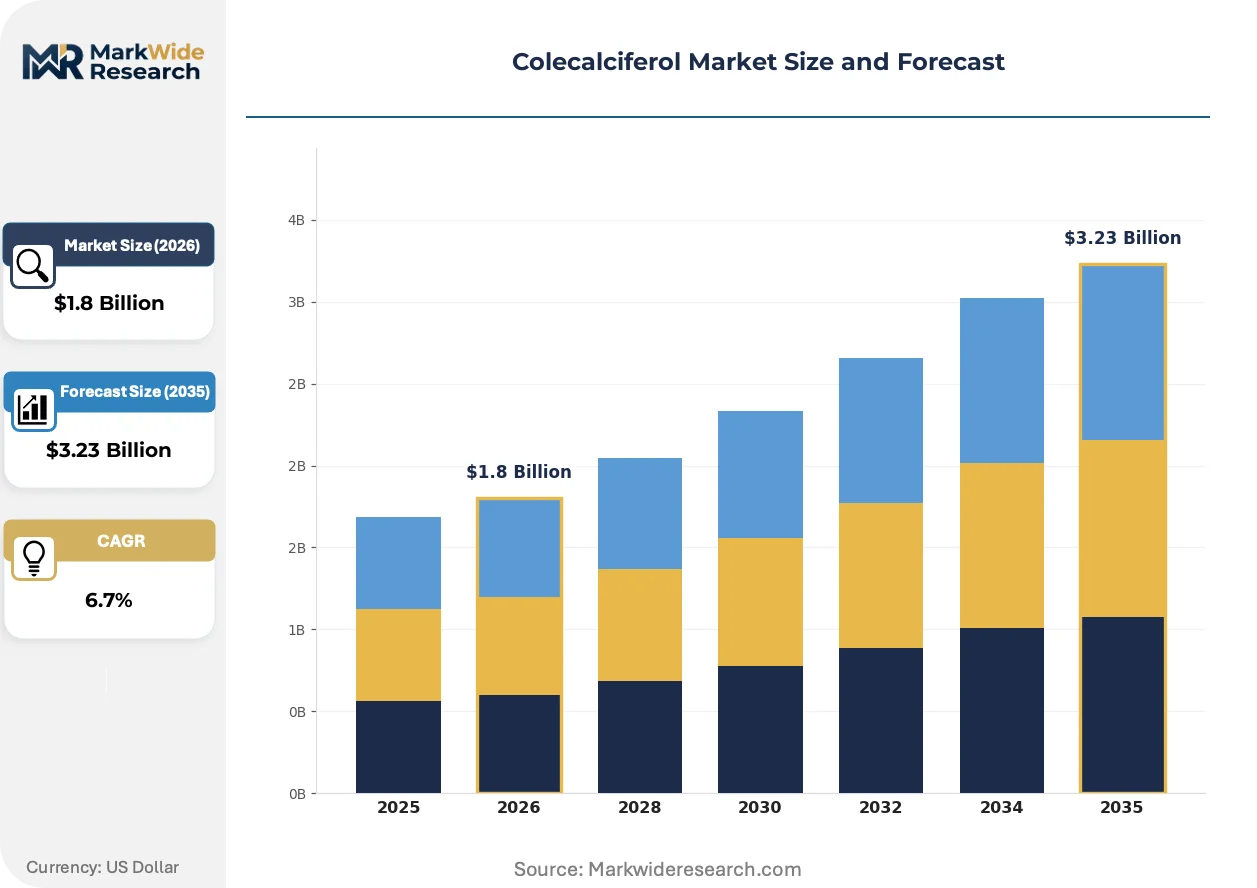
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Tablets, Powder, Liquid Application: Dietary Supplements, Pharmaceuticals, Cosmetics, Animal Feed End User: Retail Consumers, Healthcare Institutions, Animal Care, Pharmacies Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Health Shops |
| Companies Covered | DSM-Firmenich, BASF, Zhejiang Garden Biochemical High-Tech, NHU, Fermenta Biotech, Kingdomway, Zhejiang Medicine, Taizhou Hisound Pharmaceutical, Xiamen Kingdomway Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colecalciferol Market Trends and Innovations
Formulation science and process intensification are compressing development timelines while regulatory convergence pressures create competitive separation between quality-tiered supply streams.
Microfluidic crystallization platforms are hybridizing traditional batch-wise secosteroid precipitation with continuous flow chemistry. European contract manufacturers serving pharmaceutical channels are piloting these systems for impurity profile control. The technology is hybridizing quality assurance protocols by embedding real-time particle size monitoring directly into production lines, collapsing the gap between synthesis and release testing.
REACH substance registration requirements for vitamin D3 intermediates are tightening documentation burdens on lanolin derivative importers. Chemical manufacturers must now submit extended safety data sets for 7-dehydrocholesterol derivatives crossing European customs. German generics producers are responding by consolidating supplier relationships with backward-integrated fermentation houses capable of providing complete substance identity portfolios.
Healthcare procurement departments are unbundling after-sales technical support from bulk chemical contracts. Hospital pharmacy buyers now separately negotiate formulation guidance, stability testing protocols, and regulatory filing assistance. This behavior is most visible in North American institutional purchasing, where group purchasing organizations are driving service componentization to benchmark hidden cost pools.
Colecalciferol Market Segmentation
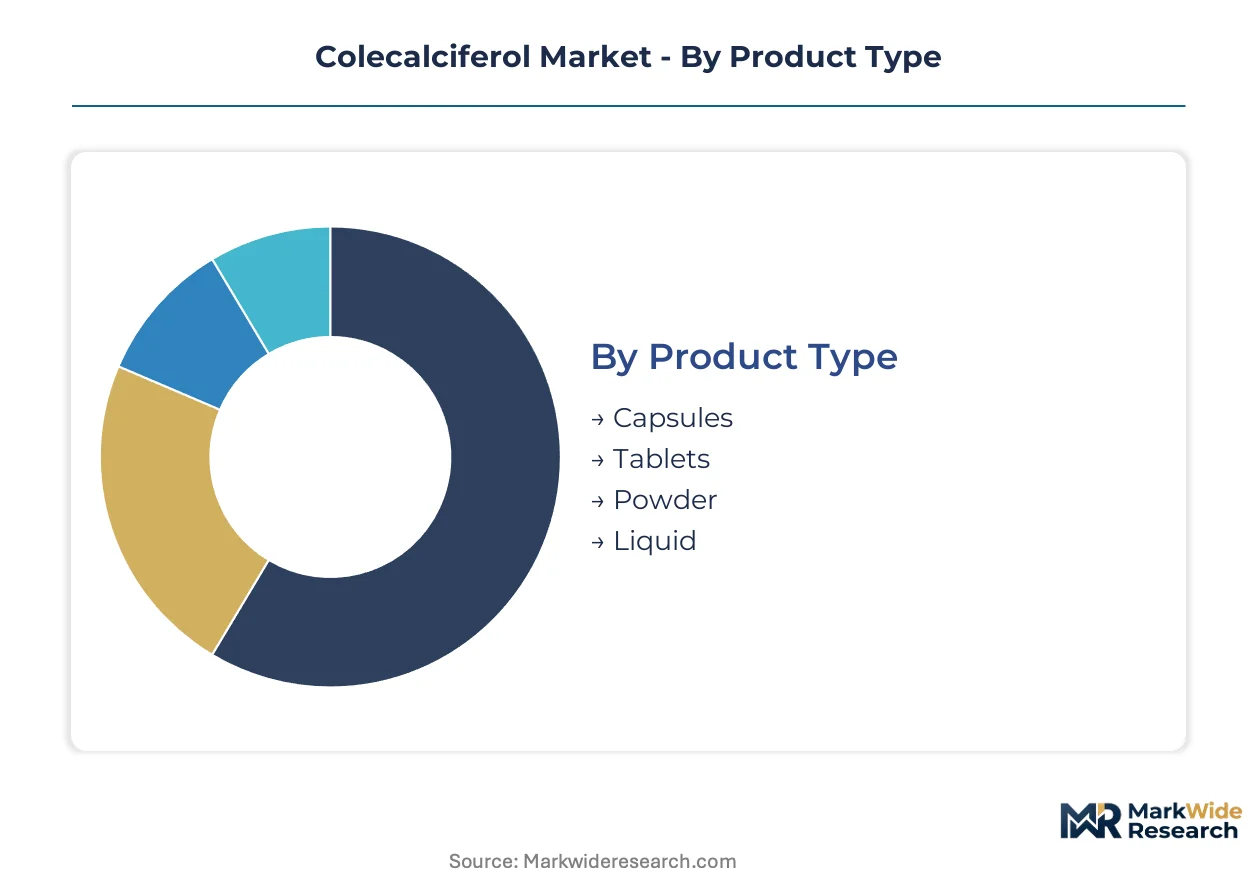
Product form, application channel, and end-user sophistication create distinct margin tiers in Colecalciferol supply. Each dimension carries regulatory and technical requirements that fragment manufacturing capabilities across the value chain.
Product Type:
Cost tier structures the manufacturing footprint, with crystallization complexity and formulation science driving margin stratification across solid and liquid delivery systems.
- Capsules:Gelatin or vegetable-based shells encapsulate oil suspensions of Colecalciferol for enhanced bioavailability and gastric protection. Demand concentrates in North American supplement brands seeking dosage precision for adult wellness protocols, with softgel flexibility from Kingdomway and similar contract manufacturers anchoring supply.
- Tablets:Compressed solid dosage forms containing crystalline Colecalciferol with excipient matrices for stability and disintegration control. European generics producers in Germany's precision nutrition cluster drive volume, as EMA pharmacopeial standards mandate dissolution profile consistency for osteoporosis therapeutics.
- Powder:Micronized crystalline grades for bulk blending into premixes and dry formulations. Animal feed compounders and mass-market supplement manufacturers represent the primary uptake channel.
- Liquid:Oil-based or emulsified solutions enabling dropper dosing for pediatric and geriatric populations with swallowing compliance challenges. Premium positioning in institutional pharmacy procurement supports margin expansion.
Tablets command the established base. The steepest expansion runs through liquid formulations.
Application:
End-use regulatory intensity separates pharmaceutical-grade supply from commodity dietary supplement channels, with certification requirements determining accessible market tiers.
- Dietary Supplements:Over-the-counter wellness products spanning multivitamins to standalone vitamin D3 formulations. FDA Current Good Manufacturing Practice compliance shapes quality thresholds for US market access.
- Pharmaceuticals:Prescription-grade formulations for osteoporosis, rickets, and hypoparathyroidism management requiring EP/BP/USP pharmacopeial certification. EMA active substance master file registration enables European generics production.
- Cosmetics:Topical and dermal applications leveraging vitamin D3 for skin barrier function claims. REACH substance registration requirements tighten documentation for lanolin-derived intermediates entering European cosmetic supply chains.
- Animal Feed:Feed-grade premixes for livestock calcium metabolism and poultry bone development. Mature margin pool with limited growth upside compared to pharmaceutical and human supplement channels.
Pharmaceuticals anchor value concentration. Dietary supplements are climbing the fastest.
End User:
Customer procurement sophistication determines service bundling requirements, with institutional buyers unbundling technical support from bulk chemical contracts.
- Retail Consumers:Individual purchasers through direct-to-consumer and retail channels, price-sensitive and brand-loyalty driven.
- Healthcare Institutions:Hospital pharmacy departments and clinical networks expanding prophylactic vitamin D3 protocols for aging populations with elevated fracture risk profiles.
- Animal Care:Livestock operations and veterinary supply chains integrating Colecalciferol into feed optimization programs.
- Pharmacies:Community and institutional dispensaries navigating India's CDSCO Schedule H constraints that bifurcate prescription-strength from over-the-counter supply.
Healthcare institutions command the established base. Pharmacies are gaining share fastest.
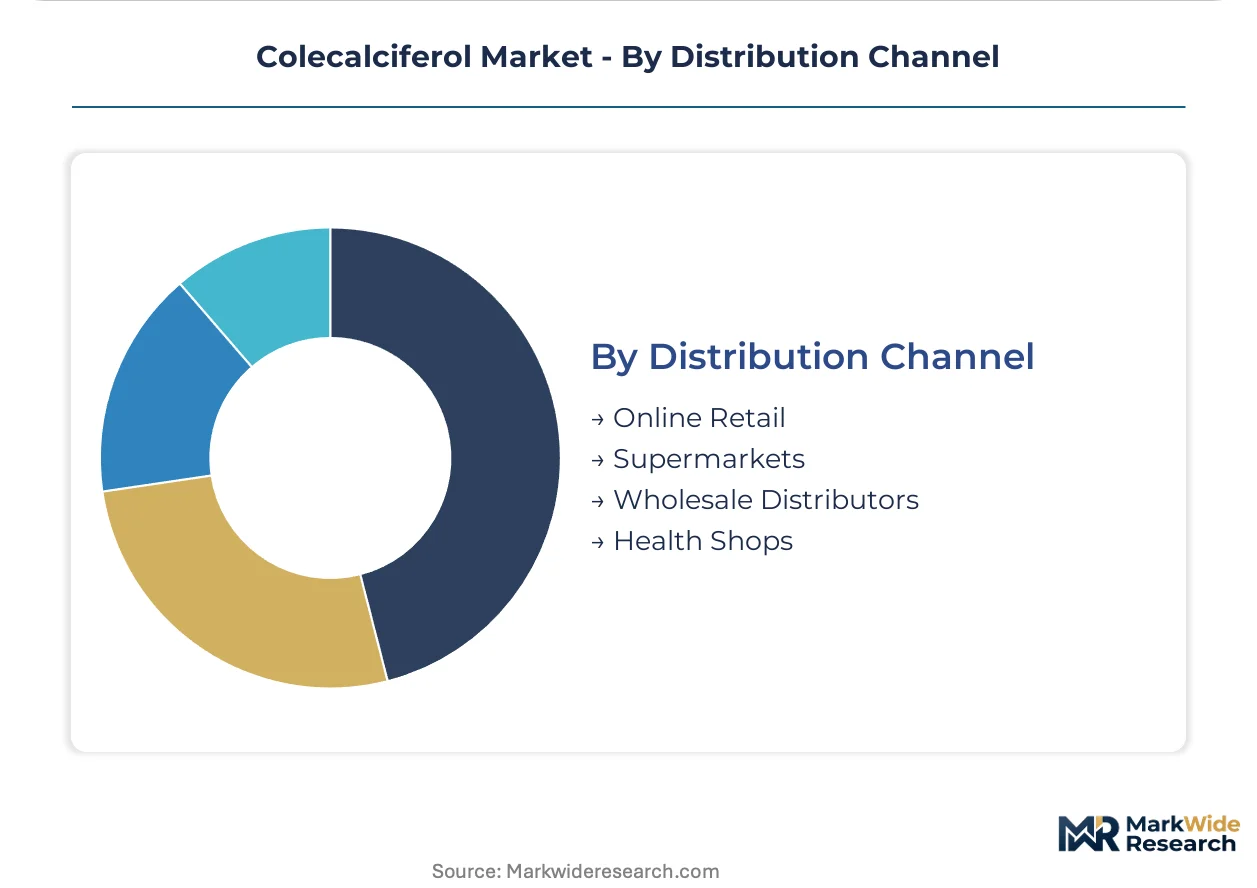
Distribution Channel:
Volume scale and customer touchpoint intensity fragment logistics requirements, with digital channels compressing traditional retail margins.
- Online Retail:Direct-to-consumer platforms and marketplace aggregators enabling subscription models and personalized dosing regimens.
- Supermarkets:Mass-market shelf presence for commodity supplement SKUs with high inventory velocity and promotional pricing pressure.
- Wholesale Distributors:Bulk supply intermediaries serving pharmacies, healthcare institutions, and compounders with lot traceability and cold chain capabilities where required.
- Health Shops:Specialty retailers curating premium-positioned formulations for ethical consumer segments, including vegan-positioned alternatives competing with plant-derived vitamin D2.
Wholesale distributors command the established base. Online retail is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crystallization-grade capacity clusters among German chemical manufacturers and Chinese fermentation houses, with regulatory filing requirements fragmenting accessible market tiers across jurisdictions.
United States
FDA Current Good Manufacturing Practice audits shape quality thresholds for dietary supplement and pharmaceutical channels. Hospital pharmacy procurement departments unbundle technical support from bulk chemical contracts, driving service componentization. Greater Boston's contract manufacturing corridor anchors softgel encapsulation capacity for North American wellness brands.
Germany
EMA active substance master file registration enables streamlined multi-territory pathways for European generics producers. REACH substance documentation requirements tighten on lanolin derivative importers. Bavaria's precision nutrition cluster concentrates pharmaceutical-grade formulation science serving osteoporosis therapeutics.
China
NMPA pharmacopeial standards and GB certification requirements govern domestic production and export eligibility. CDSCO Schedule H constraints on prescription strength create channel bifurcation opportunities for Indian market access. Zhejiang province anchors crystallization capacity feeding European generics supply chains.
India
CDSCO prescription strength regulations separate regulated pharmaceutical dosages from over-the-counter supplement channels, enabling dual-brand positioning. FSSAI fortification standards expand food-grade applications. Maharashtra's pharmaceutical manufacturing belt concentrates contract formulation capacity for domestic and export markets.
Japan
METI industrial policy supports biotechnology advances in 7-dehydrocholesterol fermentation feedstocks. PMDA pharmacopeial alignment with EP/USP standards reduces redundant quality testing burdens. Kanto region's chemical synthesis infrastructure secures ultraviolet-B irradiation process consistency for pharmaceutical-grade output.
Colecalciferol Market Competitive Landscape
Backward-integrated fermentation houses and specialized crystallization manufacturers split the market into asymmetric supply tiers. Three to four chemical producers concentrate pharmaceutical-grade capacity, creating cascading bargaining power through contract manufacturing networks. Two dominant competitive moves are reshaping positioning: biotechnology investments in lanolin-alternative feedstock biosynthesis, and real-time release testing integration for batch cycle compression.
Among European chemical conglomerates, DSM-Firmenich exemplifies backward-integrated fermentation architecture securing precursor consistency. Zhejiang Garden Biochemical High-Tech occupies a position anchoring crystallization supply for generics producers. Kingdomway represents dosage-form flexibility specialization in softgel encapsulation, serving supplement brand contract requirements.
| Leading Market Players |
|---|
| DSM-Firmenich |
| BASF |
| Zhejiang Garden Biochemical High-Tech |
| NHU |
| Fermenta Biotech |
| Kingdomway |
| Zhejiang Medicine |
| Taizhou Hisound Pharmaceutical |
| Xiamen Kingdomway Group |
| Others |
Pricing and Supply Chain Analysis
Zhejiang province's crystallization capacity concentration anchors pharmaceutical-grade supply, feeding margin pools downstream into German generics producers and North American softgel contract manufacturers. Lanolin-derived 7-dehydrocholesterol fermentation tightens feedstock control among backward-integrated houses, compressing margin capture for non-integrated formulators.
Pricing Analysis
EMA Active Substance Master File requirements dictate the pricing tier structure across European supply channels. Three-tier pricing structure across pharmacopeial-grade, food-grade, and feed-grade levels separates EP/BP/USP-certified crystalline product from commodity powder grades. Price differentiation stems from certification investment burdens and batch release testing intensity. Cost compression in feed-grade tiers intensifies because animal nutrition compounders prioritize volume scale over purity premiums. Hospital pharmacy procurement teams exhibit the lowest price sensitivity, while mass-market supplement brands face acute margin pressure from private-label competition.
Supply Chain Analysis
REACH substance registration documentation requirements restrict 7-dehydrocholesterol derivative flows into European customs, forcing importers to submit extended safety data sets. Geographic supply concentration centers on China for crystallization capacity, Germany for precision nutrition formulation, and India for contract manufacturing serving dual-brand pharmaceutical and supplement channels. Raw material dependencies draw from Australian and New Zealand wool grease extraction, ultraviolet-B irradiation equipment, and gelatin or vegetable-derived encapsulation materials. Single-source vulnerability runs through lanolin feedstock exposure to climate-driven agricultural commodity swings. Distribution runs through wholesale distributors with lot traceability capabilities, though online retail channels are compressing traditional margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in secosteroid prohormone assay methodology represents the binding constraint across quality control staffing, limiting EP/BP/USP certification maintenance capacity and fragmenting competitive tiers between certified and non-certified producers.
For Market Incumbents: Insulate pharmacopeial-grade positioning through captive 7-dehydrocholesterol fermentation capacity or exclusive supply agreements with Australian wool grease processors. Plant-derived vitamin D2 substitution from UV-treated yeast erodes D3 share in vegan-positioned segments; counter by embedding real-time release testing to compress batch cycle times and defend formulation science premiums in liquid pediatric delivery systems. For New Entrants and Emerging Players: Pediatric liquid formulation white space in institutional pharmacy procurement represents the most penetrable entry point, as swallowing compliance gaps in geriatric and infant populations sustain premium positioning. India's Schedule H channel bifurcation enables dual-brand strategies separating regulated pharmaceutical dosages from over-the-counter supplements. Target contract manufacturing relationships with North American wellness brands seeking dosage-form flexibility rather than competing directly with crystallization-scale incumbents. For Investors and Strategic Acquirers: Capital is best deployed toward backward-integrated fermentation houses with complete substance identity portfolios satisfying REACH documentation requirements. Long-term viability across the projection horizon hinges on regulatory filing assistance capabilities and stability testing protocol bundling. Monitor pharmacopeial harmonization progress between USP, EP, and ChP standards as the inflection signal; convergence would compress redundant quality testing burdens and reward multi-territory registration scale.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fermentation Feedstock | DSM-Firmenich's 7-dehydrocholesterol biosynthesis secures precursor consistency against wool grease volatility. |
| Continuous Manufacturing Technology Adoption | Microfluidic crystallization platforms embedding real-time particle size monitoring collapse synthesis-to-release testing gaps. |
| Dual-Brand Channel Strategy | CDSCO Schedule H bifurcation enables separate positioning for prescription-strength and over-the-counter vitamin D3 supply. |
| Pediatric Liquid Formulation Development | Dropper-dose delivery systems command premium positioning in hospital pharmacy procurement for swallowing compliance populations. |
| Pharmacopeial Certification Investment | EMA Active Substance Master File registration streamlines multi-territory pathways for European generics producers. |
Research Methodology
A standing panel of pharmaceutical quality control directors, contract manufacturing procurement leads, regulatory affairs specialists, and hospital pharmacy buyers provided ongoing calibration across the primary research phase. This input combined with secondary validation from FDA Current Good Manufacturing Practice guidance documents, EMA active substance master file databases, EP/BP/USP pharmacopeial monographs, and REACH substance registration filings. Bottom-up crystallization capacity estimates and top-down dietary supplement market sizing were triangulated to anchor volume assumptions.
Scenario-bracketing around pharmacopeial harmonization outcomes and lanolin supply volatility shaped the analytical framework across the modeling period. Segmentation dimensions modeled include product form, application channel, end-user sophistication, and regional regulatory cluster. CAGRs were derived from intensity-of-use trajectories in osteoporosis management protocols and pediatric supplementation penetration. Forecast inputs incorporated EMA registration pathway timelines and CDSCO prescription strength constraint evolution.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, healthcare procurement budget cycles, or currency fluctuations affecting API import costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory convergence pace and biotechnology feedstock substitution timelines. Cross-checking against customs trade data for 7-dehydrocholesterol derivative flows and hospital pharmaceutical purchasing surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vitamin Fortified
Food Fortification Market
Vitamin Fortified
North America Vitamin a Market
Vitamin Fortified
Europe Food Fortifying Agents Market
Vitamin Fortified
Water Soluble Vitamins Market
Vitamin Fortified
High Calcium Fortified Food Market
Vitamin Fortified
Vitamin E Market
Vitamin Fortified
Food Fortifying Agents Market
Vitamin Fortified
Middle East Feed Vitamins Market
Vitamin Fortified
Fortified Beverages Market
Vitamin Fortified
South America Food Fortifying Agents Market
Vitamin Fortified
Africa Vitamin Fortified and Mineral Enriched Food and Beverage Market
Vitamin Fortified
Global Mixed Tocopherol Market
Vitamin Fortified
Fortified Food Market
Vitamin Fortified
Global Adult Vitamin Gummies Market
Vitamin Fortified
Fortified Breakfast Spreads Market
Vitamin Fortified
Vitamin B Complex Market