
 Pharmaceutical Filtration Market | 2026-2036
Pharmaceutical Filtration Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Filtration Market Intelligence
Good Manufacturing Practice (GMP) validation for sterile filtration systems is collapsing the time-to-market for new biologics. Danaher Corporation leverages its extensive portfolio of life sciences brands to offer integrated solutions from upstream to downstream processing. Sartorius AG specializes in single-use technologies and bioprocess solutions, commanding a strong position in the European market. Merck KGaA differentiates through its advanced membrane chemistries and comprehensive validation support services for global drug manufacturers.
Pharmaceutical filtration involves separating particles and microorganisms from fluid streams during drug manufacturing using membranes with specific pore size ratings. This process is critical for achieving product purity and sterility, particularly for parenteral drugs. Ultrafiltration products dominate sales for bioprocessing applications, while single-use cartridge filters are rapidly gaining share from traditional systems within biotechnology firms and contract manufacturing organizations.
Regulatory frameworks from the US FDA and the European Medicines Agency (EMA) define stringent requirements for filter validation and extractables and leachables testing. These regulations, alongside guidelines from Japan's PMDA, mandate comprehensive documentation, driving demand for high-performance, well-characterized filtration products. Future competitive advantage will depend on a vendor's ability to provide robust supply chain assurance and technical support for navigating evolving global regulatory standards.
Market Dynamics
The industry-wide migration to single-use filtration systems defines the market's core dynamic. This transition, driven by the need to eliminate cross-contamination risks and increase operational flexibility in bioprocessing, is fundamentally altering capital expenditure models and vendor relationships.
Growth Catalysts
- Monoclonal Antibody Production:Expanding pipelines for monoclonal antibodies and other biologics create sustained demand for high-purity filtration, particularly ultrafiltration products used in downstream concentration and purification steps.
- Biopharma Hub Investment:Concentrated investment in new biopharmaceutical manufacturing facilities within specialized clusters, including those in Ireland, Singapore, and South Korea, directly accelerates regional adoption of advanced filtration technologies.
- GMP Validation Acceleration:The application of Good Manufacturing Practice (GMP) principles to the validation of sterile filtration systems is shortening the development and approval timelines for new biologic drugs, encouraging faster technology uptake.
Market Restraints
- Extractables and Leachables (E&L) Risk:The potential for compounds to leach from single-use plastic components into the final drug product creates a significant regulatory and technical hurdle, requiring extensive and costly validation studies.
- Polymer Supply Chain Volatility:The supply of specialized, medical-grade polymers required for single-use filter manufacturing is highly concentrated, creating vulnerability to price fluctuations and supply disruptions for filter vendors.
- High Consumable Costs:While single-use systems reduce initial capital outlay compared to stainless steel, the high recurring cost of disposable filter cartridges and assemblies can be a significant financial restraint for smaller biotech firms and academic labs.
Strategic Opportunities
- Cell and Gene Therapy Applications:The rise of cell and gene therapies presents a new frontier, requiring novel, small-scale, and highly specialized filtration solutions for viral vector purification and cell processing that are currently underserved.
- Emerging Market Biomanufacturing:Building out local biomanufacturing capabilities in countries like Brazil and India, supported by regulators like ANVISA and CDSCO, opens new geographic markets for filtration vendors offering comprehensive validation support.
- Advanced Membrane Chemistries:Developing and commercializing new membrane materials with lower E&L profiles and higher capacities offers a clear path to product differentiation and capturing premium pricing from risk-averse drug manufacturers.
Industry Challenges
- Regulatory Divergence:Navigating the distinct and evolving requirements for filter validation and documentation set by the US FDA, EMA in Europe, and Japan's PMDA complicates global product launches for both filter suppliers and drug makers.
- Specialized Talent Scarcity:A shortage of technical personnel with expertise in filtration validation, implementation, and troubleshooting within biomanufacturing facilities creates an execution bottleneck for adopting new systems.
- Component Standardization Gaps:A lack of universal standards for connectors and fittings on single-use systems can lead to vendor lock-in, limiting flexibility and creating integration challenges for end-users.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Filtration Market |
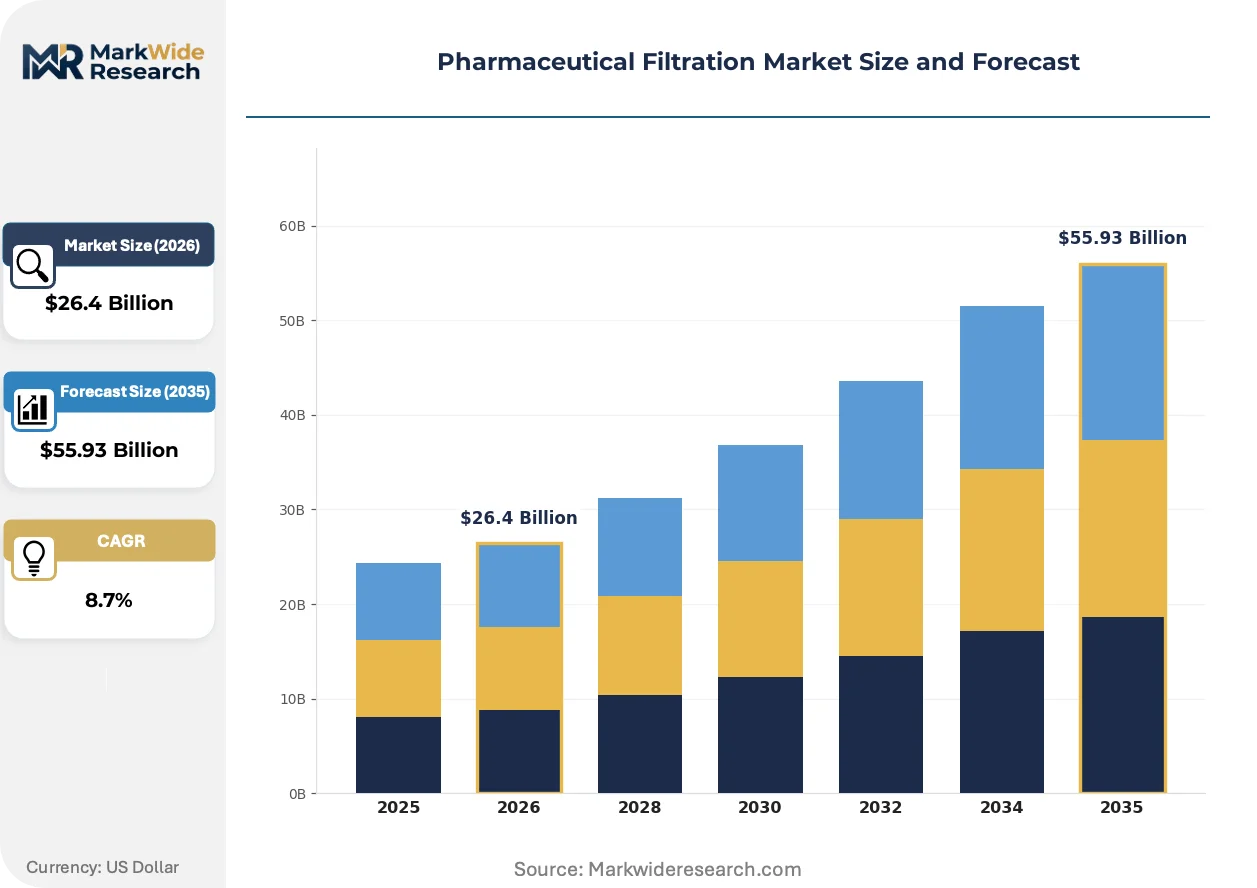
| Market Size in 2026 | $26.4 Billion |
| Market Size in 2035 | $55.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfiltration, Ultrafiltration, Nanofiltration, Reverse Osmosis Application: Bioprocessing, Water Purification, Blood Filtration, Drug Manufacturing End User: Pharmaceutical Companies, Biotechnology Firms, Hospitals, Contract Manufacturing Organizations Technology: Filtration Membranes, Sterilizing Filters, Depth Filters, Cartridge Filters |
| Companies Covered | Danaher Corporation, Sartorius AG, Merck KGaA, 3M Company, Parker Hannifin Corporation, Eaton Corporation plc, Thermo Fisher Scientific, Meissner Filtration Products Inc, Graver Technologies LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Filtration Market Strategic Shifts & Innovations
The convergence of material science innovations and process analytical technology (PAT) is reshaping the competitive landscape. This drives a move away from static components toward intelligent, data-generating filtration systems that enhance process control and regulatory compliance in real-time.
Smart filtration assemblies integrated with single-use sensors are gaining traction. These systems provide continuous, real-time monitoring of critical process parameters like pressure, flow rate, and temperature directly at the point of filtration. Biopharmaceutical manufacturers, particularly in continuous bioprocessing, are early adopters. This integration of data with the physical filter is decomposing the traditional, siloed approach to process monitoring into a unified, holistic control strategy.
The European Medicines Agency's (EMA) revised Annex 1 guidelines for sterile product manufacturing are forcing a re-evaluation of contamination control strategies. This regulation places increased emphasis on risk-based approaches and mandates more rigorous integrity testing, such as pre-use post-sterilization integrity testing (PUPSIT). Filter vendors are directly impacted, now required to provide more extensive validation packages and automated integrity test instruments to help drug manufacturers in the EU comply.
A notable behavioral shift involves drug manufacturers prioritizing supply chain assurance over unit price for critical filtration consumables. This trend marks a departure from transactional procurement towards establishing strategic partnerships with vendors who can demonstrate global manufacturing redundancy and robust quality systems. This pattern is most pronounced among large biopharmaceutical companies with operations in the United States and across the European Union, where supply continuity is paramount.
Pharmaceutical Filtration Market Segmentation
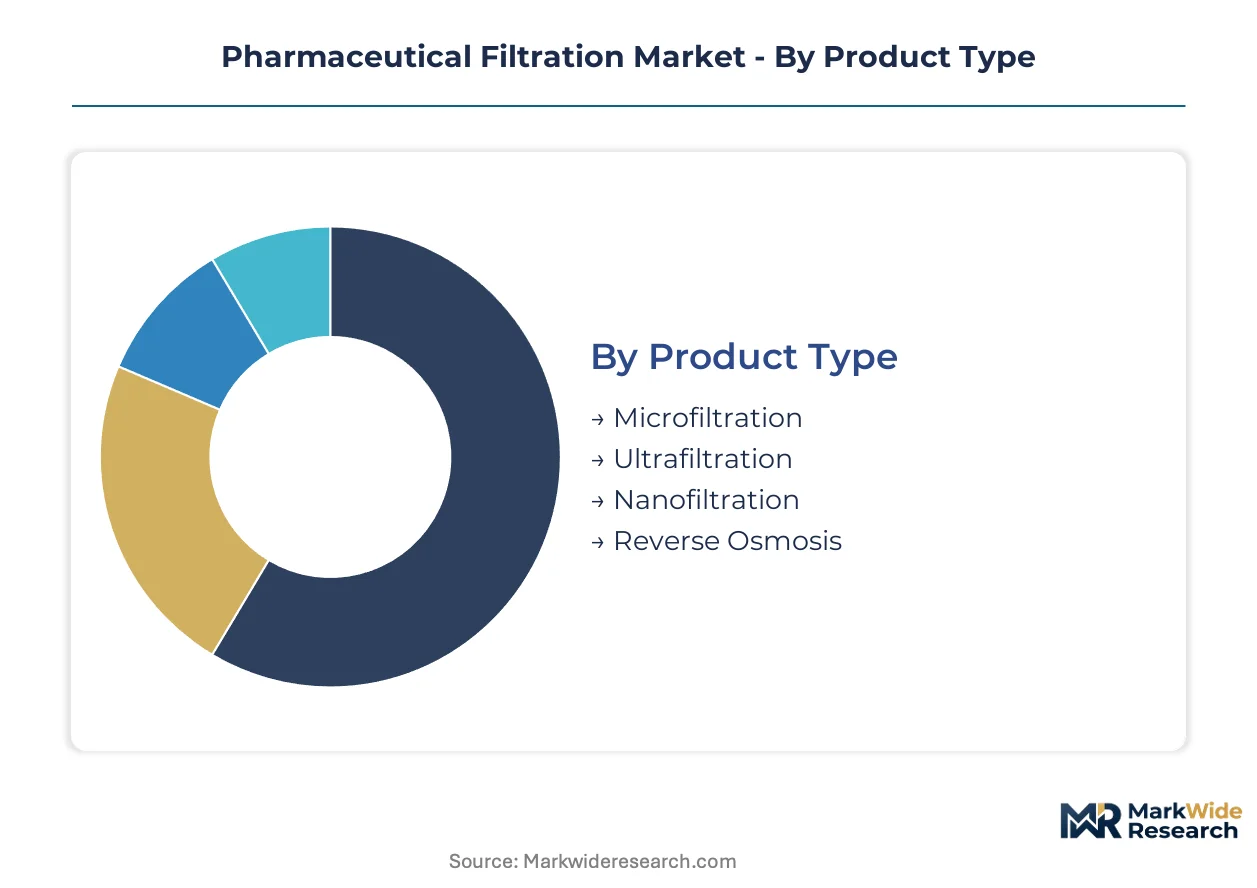
Segmenting the pharmaceutical filtration market provides a granular understanding of how diverse product types, applications, end-users, and technologies interact to meet the stringent demands of drug manufacturing. This detailed view helps stakeholders identify pockets of innovation and areas of concentrated demand across the global biopharmaceutical landscape.
Product Type:
The geographic footprint of pharmaceutical filtration product types reflects varying levels of regulatory maturity and biopharmaceutical manufacturing infrastructure across regions.
- Ultrafiltration:These membranes separate macromolecules like proteins and viruses from solutions based on size exclusion, typically with pore sizes between 0.001 and 0.1 micrometers. Demand concentrates in biopharmaceutical manufacturing clusters in Ireland and Singapore for monoclonal antibody purification, driven by high product purity requirements.
- Microfiltration:Microfiltration systems remove particles and microorganisms larger than 0.1 micrometers, often used for sterile filtration of liquids and gases in pharmaceutical production. Global demand is high across all pharmaceutical manufacturing hubs, including those in the US and Germany, due to its essential role in pre-filtration and final sterile processing.
- Nanofiltration:These filters remove smaller molecules and viruses, offering a critical step in viral clearance for biologics, particularly in European bioprocessing facilities.
- Reverse Osmosis:Reverse osmosis systems provide highly purified water for pharmaceutical manufacturing, essential for injectables and active pharmaceutical ingredient synthesis, particularly in Asian markets.
Microfiltration commands the established base. The steepest expansion runs through Ultrafiltration.
Application:
The maturity of pharmaceutical filtration applications varies significantly, with some representing long-standing industry practices and others emerging as critical new frontiers.
- Bioprocessing:This application involves filtration steps throughout the production of biologics, from cell culture media preparation to final product purification and viral clearance. Bioprocessing demand is accelerating in South Korea and the US, fueled by expanding pipelines of advanced therapies and increased investment in biomanufacturing capacity.
- Drug Manufacturing:This broad application encompasses filtration across small molecule drug synthesis, excipient purification, and sterile filling of various pharmaceutical formulations. Demand for drug manufacturing filtration remains consistently high across established pharmaceutical markets like Germany and Japan, driven by stringent quality control standards.
- Water Purification:Filtration for water purification ensures compliance with pharmacopeial standards for water for injection (WFI) and purified water in pharmaceutical facilities, especially in India and China.
- Blood Filtration:This application focuses on removing leukocytes and other contaminants from blood products, crucial for transfusion safety in hospital settings globally.
Drug Manufacturing applications form the traditional core. Bioprocessing exhibits the fastest-growing trajectory.
End User:
The supply concentration for pharmaceutical filtration products often aligns with the purchasing power and technical requirements of specific end-user segments.
- Biotechnology Firms:These firms require specialized filtration solutions for upstream and downstream processing of biologics, often favoring single-use systems for flexibility and contamination control. Demand from biotechnology firms is particularly strong in emerging biopharma clusters like those in Ireland and Massachusetts, driven by new drug development.
- Pharmaceutical Companies:Large pharmaceutical companies utilize a wide array of filtration technologies for both small molecule and biologic production, demanding robust supply chain assurance and validation support. Demand from pharmaceutical companies spans global markets, with significant procurement volumes observed in established manufacturing bases across Europe and the United States.
- Contract Manufacturing Organizations:CMOs increasingly adopt single-use filtration to manage diverse client projects and accelerate time-to-market for new therapies, especially in Europe.
- Hospitals:Hospitals use filtration primarily for sterile preparation of compounded drugs, water purification for medical devices, and blood product processing, adhering to local health regulations.
Pharmaceutical Companies represent the largest established customer base. Biotechnology Firms are gaining share fastest.
Technology:
The technological evolution in pharmaceutical filtration is closely tied to the specific application challenges and performance demands of modern drug manufacturing.
- Cartridge Filters:These filters consist of pleated membrane or depth media housed within a disposable cartridge, offering ease of use and reduced cleaning validation in bioprocessing. Adoption of cartridge filters, particularly single-use variants, is accelerating among biotechnology firms and CMOs in the US and Europe to mitigate cross-contamination risks.
- Filtration Membranes:Filtration membranes are the functional heart of most filtration systems, characterized by specific pore sizes and material chemistries (e.g., PES, PVDF) dictating separation efficiency. Innovations in membrane chemistries with lower extractables and leachables profiles are highly sought after by drug manufacturers globally, driving demand for advanced materials.
- Sterilizing Filters:These filters, typically 0.22 micron pore size, provide absolute removal of bacteria, ensuring sterility for parenteral drugs and critical process fluids, mandated by the US FDA.
- Depth Filters:Depth filters capture particles throughout a tortuous path within a thick matrix, commonly used for clarification and pre-filtration steps in large-volume bioprocessing streams.
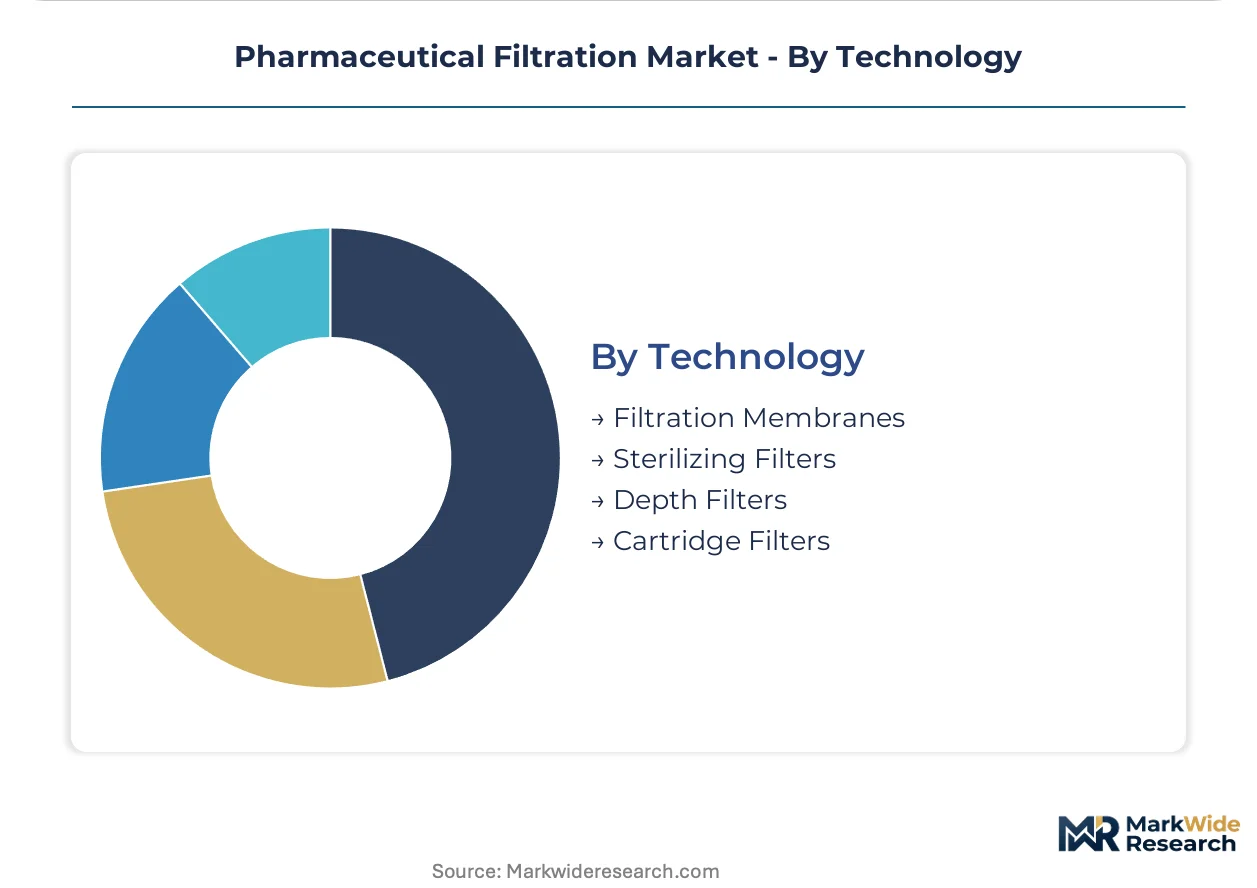
Filtration Membranes form the fundamental technological core. Cartridge Filters are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory frameworks from the US FDA and European Medicines Agency define stringent requirements for filter validation, driving demand across key pharmaceutical manufacturing hubs. These regulations mandate comprehensive documentation, accelerating technology uptake. Government incentives also support biopharmaceutical facility investments globally.
United States
Demand for filtration systems in the United States is spurred by expanding biopharmaceutical pipelines, particularly for advanced therapies. The US FDA mandates rigorous validation for sterile filtration and extractables and leachables testing. Major biopharma clusters in Massachusetts and North Carolina are seeing accelerated adoption of single-use technologies.
Germany
European Medicines Agency guidelines, especially revised Annex 1, emphasize contamination control strategies in Germany. This drives manufacturers to adopt high-performance filtration solutions with enhanced integrity testing. The Rhine-Main region, a pharmaceutical hub, focuses on advanced membrane chemistries and comprehensive validation support.
Singapore
Investment in new biopharmaceutical manufacturing facilities in Singapore creates sustained demand for high-purity filtration. Singapore's Health Sciences Authority (HSA) aligns with international standards for drug product quality and safety. The Tuas Biomedical Park concentrates on monoclonal antibody production, requiring advanced ultrafiltration products.
South Korea
South Korea's expanding biomanufacturing capacity for biologics fuels demand for specialized filtration, particularly in bioprocessing. The Ministry of Food and Drug Safety (MFDS) enforces strict regulatory compliance for pharmaceutical production. Incheon Biocluster is experiencing rapid growth, driven by investments in single-use filtration systems for vaccine and antibody manufacturing.
India
Building local biomanufacturing capabilities in India, supported by regulators like CDSCO, opens new geographic markets. The Indian Pharmacopoeia mandates stringent water purification standards for pharmaceutical production. Hyderabad and Bengaluru are emerging as significant pharmaceutical manufacturing centers, increasing the need for high-performance filtration.
Pharmaceutical Filtration Market Key Industry Players
Player mix skews toward large, diversified life sciences conglomerates and specialized filtration technology providers. The market exhibits a tiered structure, with global leaders offering integrated solutions alongside niche innovators. Key strategic archetypes include full-spectrum solution providers and material science specialists. Dominant competitive moves involve portfolio diversification and strategic partnerships.
Within the integrated solutions archetype, Danaher Corporation represents a major force, leveraging its extensive portfolio of life sciences brands to offer comprehensive support across the bioprocessing workflow. Germany-based Sartorius AG exemplifies a strong position in the European market, focusing on single-use technologies and advanced bioprocess solutions that address flexibility and contamination control needs. Merck KGaA, another German entity, anchors its market stance through its differentiation in advanced membrane chemistries and comprehensive validation support services, catering to the exacting demands of global drug manufacturers for high-performance products.
| Leading Market Players |
|---|
| Danaher Corporation |
| Sartorius AG |
| Merck KGaA |
| 3M Company |
| Parker Hannifin Corporation |
| Eaton Corporation plc |
| Thermo Fisher Scientific |
| Meissner Filtration Products Inc |
| Graver Technologies LLC |
| Others |
Cost & Logistics Intelligence
Single-use filtration systems displacing traditional stainless steel equipment reshapes both supply geography and pricing economics in pharmaceutical manufacturing. This transition concentrates demand for specialized polymer components and influences vendor pricing strategies.
Pricing Analysis
Certification level (US FDA and EMA validation) creates the primary pricing spread for pharmaceutical filtration products. The dominant pricing model is contract-based long-term off-take, often bundled with validation support and technical services. Price differentiation stems from advanced membrane chemistries and robust supply chain assurance, with global drug manufacturers paying premiums. Pricing softness reflects intense competition for standard microfiltration products; biotechnology firms are generally less price-sensitive, prioritizing performance and validation.
Supply Chain Analysis
Inbound logistics costs, particularly for specialized polymer resins, influence the pharmaceutical filtration supply chain. Geographic supply concentrates in Germany, the United States, and Japan for advanced membrane manufacturing. This supply chain draws from critical raw materials like medical-grade polypropylene and polysulfone for filter media. Polymer supply chain volatility, stemming from concentrated production, presents a structural risk; distribution runs through a network of specialized distributors and direct sales forces to biopharmaceutical manufacturing facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
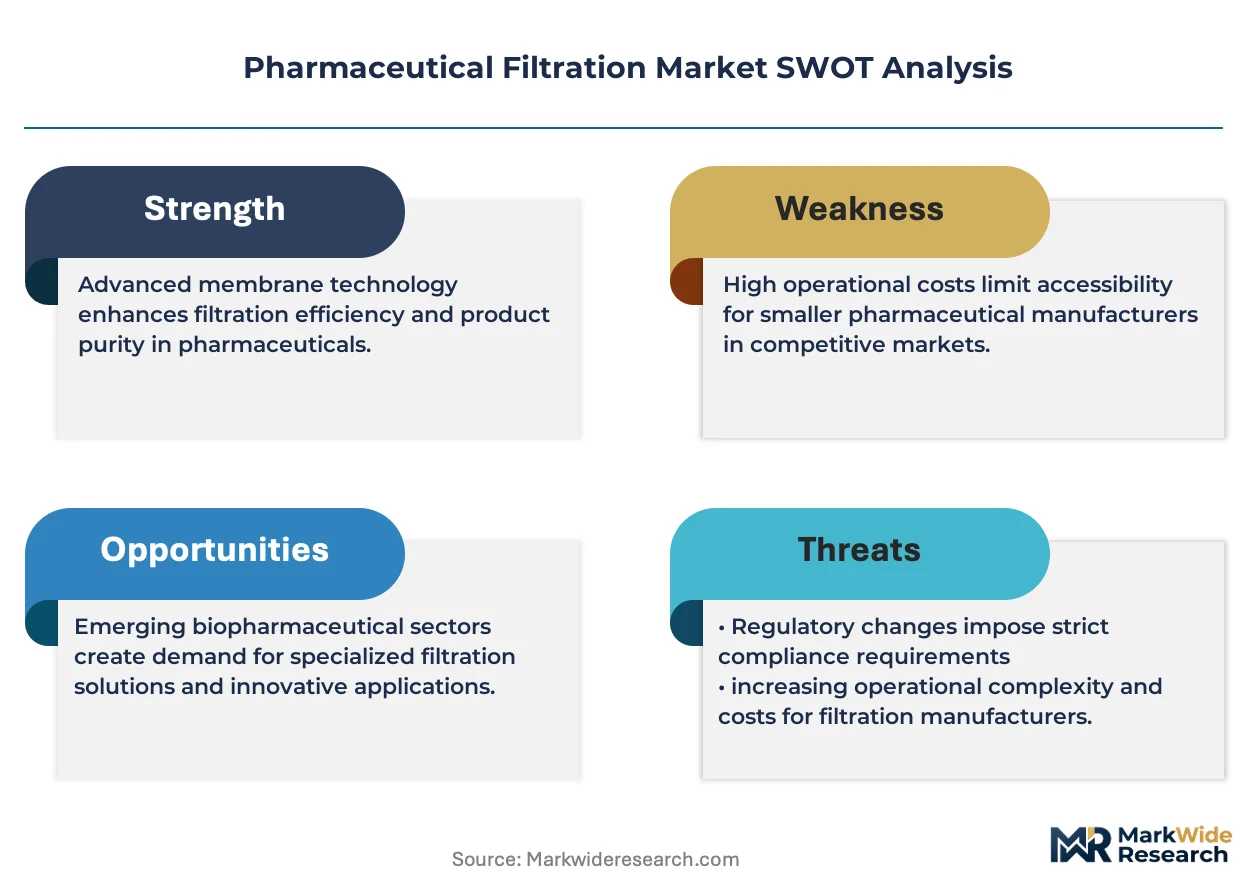
This market requires a robust substitution defense against alternative purification methods that could displace traditional filtration. Incumbents must navigate the threat of intensified chromatography or advanced centrifugation systems for biologics.
For Market Incumbents:Secure long-term supply agreements for specialized polymers to mitigate supply chain volatility. Pursue strategic acquisitions of niche membrane technology developers to expand advanced membrane chemistries and address the threat of novel separation techniques. Invest in R&D for integrated single-use sensor technologies to enhance process control and validation, reinforcing market position against emerging purification platforms.
For New Entrants and Emerging Players:Lead with specialized filtration solutions for cell and gene therapy applications, a currently underserved white space. Target emerging biomanufacturing hubs in India and Brazil, where local biomanufacturing capabilities are expanding rapidly. Offer comprehensive validation support tailored to local regulatory requirements as a key go-to-market angle, reducing adoption barriers for new facilities.
For Investors and Strategic Acquirers:EMA's revised Annex 1 guidelines reshapes the acquisition landscape for sterile filtration providers, emphasizing robust integrity testing. The long-term viability of this market over a 5-10 year window remains strong, driven by biologics growth. Target acquisition archetypes include specialized membrane manufacturers with proprietary chemistries and single-use system integrators. A signal to watch is the increasing adoption rate of continuous bioprocessing, requiring specific filtration innovations.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Membrane R&D | Developing novel membrane chemistries with lower extractables and leachables profiles differentiates product offerings for risk-averse drug manufacturers. |
| Single-Use System Integration | Integrating smart sensors into single-use filtration systems provides real-time data for biopharmaceutical manufacturers, enhancing process control. |
| Global Supply Chain Diversification | Establishing manufacturing redundancy across multiple geographies assures supply continuity for large biopharmaceutical companies in the United States and European Union. |
| Validation Support Expansion | Offering comprehensive validation support helps drug manufacturers navigate complex regulatory frameworks from the US FDA and EMA. |
| Cell & Gene Therapy Focus | Developing specialized small-scale filtration solutions addresses the unique purification needs of viral vectors for cell and gene therapies. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, industry association reports, and scientific publications. Primary interviews engaged bioprocessing engineers, regulatory affairs leads, and procurement managers from leading pharmaceutical companies. This approach ensured robust bottom-up and top-down triangulation of market data.
Product type, application, end-user, technology, and regional regulatory clusters formed the segmentation dimensions modeled across the projection horizon. The analytical framework integrated market drivers, restraints, and strategic opportunities. Compound Annual Growth Rates were derived from historical trends and anticipated technology adoption rates. Biologics pipeline expansion and single-use technology uptake served as key forecast inputs.
Forecasts assume regulatory continuity in US FDA, EMA, and PMDA regimes; material policy shifts would require re-modeling. Polymer supply chain disruptions or new extractables and leachables regulations present specific risk factors. Practitioners should keep alternative scenarios live as bioprocessing technology and global trade conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Depyrogenation Oven Market
Pharmaceutical Equipment
Europe Pharmaceutical Isolator Market
Pharmaceutical Equipment
Interlock Vials Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
North America and Europe Pharmaceutical Stability & Storage Services Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Vials and Ampoules Market
Pharmaceutical Equipment
Investigational New Drug CDMO Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market