
 China Respiratory Devices Market | 2026-2036
China Respiratory Devices Market Size, Share, and Industry Trends Forecast 2026-2036
China Respiratory Devices Market Outlook
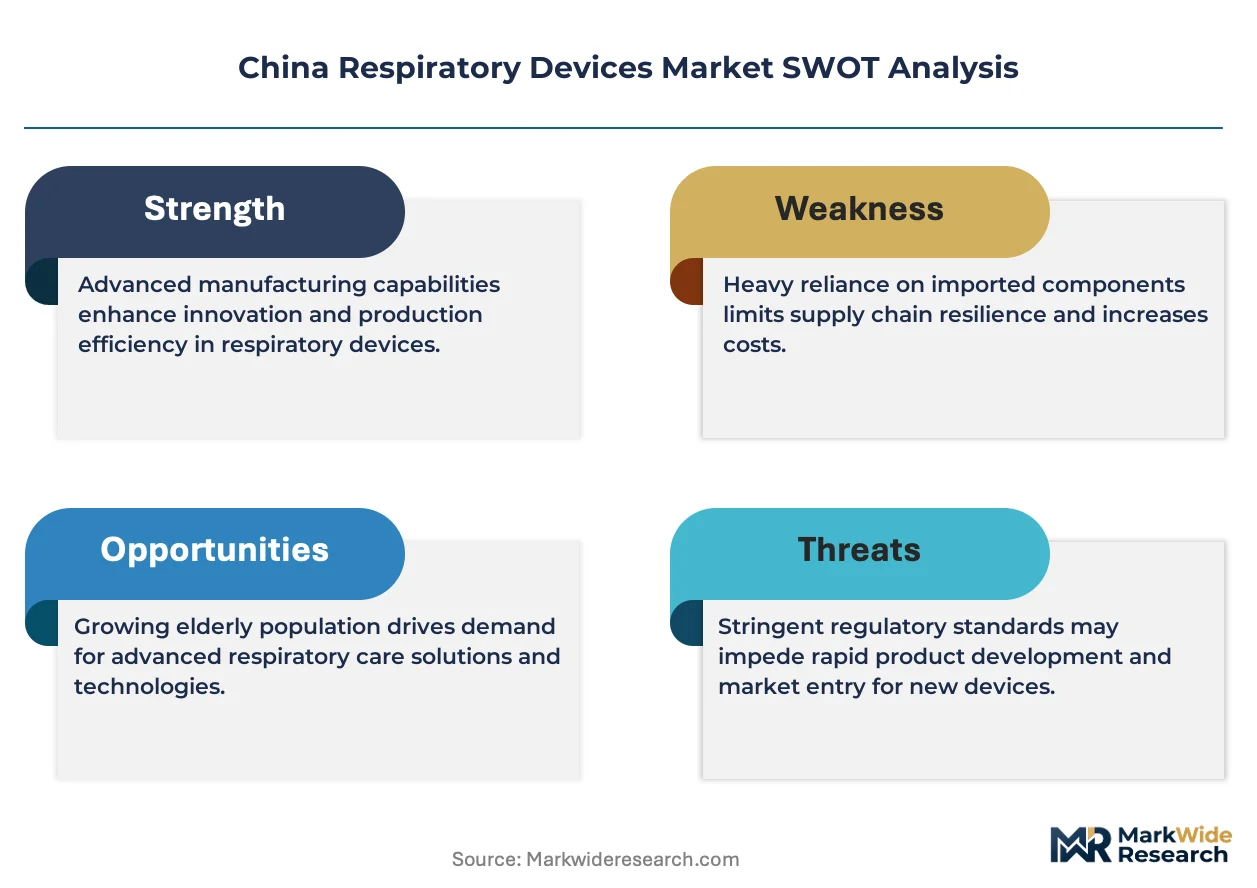
China's dual carbon goals is broadening the sustainability mandate for domestic medical device manufacturing, pushing energy-efficient production protocols across respiratory equipment supply chains. Yuwell-Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. anchors its position through deep vertical integration in Jiangsu province, controlling component sourcing through finished device assembly. Beijing Mindray Bio-Medical Electronics Co., Ltd. leverages substantial R&D intensity to compete on digital monitoring and adaptive ventilation platforms. ResMed sustains technology leadership in sleep apnea interfaces while navigating NMPA registration pathways for imported premium systems.
Respiratory devices encompass mechanical apparatus engineered to assist, control, or supplement pulmonary ventilation, typically incorporating precision flow sensors, pressure regulators, and biocompatible polymers such as medical-grade silicone or polycarbonate in critical airway interfaces, with functional parameters including tidal volume accuracy within 10% deviation and fractional inspired oxygen delivery ranging from 21% to 100%. These systems serve primary commercial purposes in acute critical care, chronic disease management, and home-based therapeutic intervention. Ventilators occupy the highest margin pool within product categories, reflecting intensive care unit dependency and technological complexity, while oxygen concentrators demonstrate the fastest structural expansion as homecare migration reduces hospital bed utilization. Sleep apnea applications within the application dimension generate disproportionate revenue concentration due to diagnostic protocol expansion and patient compliance monitoring integration.
NMPA registration requirements and GB standards enforcement shape product market access timelines and clinical validation burdens for both domestic and imported respiratory devices. China's MEE industrial emissions frameworks and SAMR quality oversight further constrain manufacturing facility certifications and supply chain environmental compliance obligations. Stakeholders must monitor NMPA's evolving equivalence determination pathways for adaptive ventilation algorithms and digital therapeutics integration, as regulatory clarity will determine competitive positioning for next-generation automated therapy platforms.
Market Dynamics
Homecare migration is compressing hospital-based respiratory device procurement cycles while NMPA equivalence pathways for algorithm-driven ventilation systems are redrawing competitive entry barriers for domestic and foreign manufacturers alike.
Growth Catalysts
- Jiangsu-Shandong industrial clustering:Dense medical device component ecosystems in these provinces enable rapid prototyping and cost-efficient scale-up for mechanical ventilators and oxygen concentrators.
- Dual carbon goals mandate:MEE emissions frameworks are accelerating energy-efficient production protocols across respiratory equipment supply chains, favoring manufacturers with certified green facilities.
- Aging demographic pressure:Chronic obstructive pulmonary disease prevalence among China's elderly population is expanding addressable demand for home-based therapeutic intervention.
Market Restraints
- Medical-grade silicone supply concentration:Polymer feedstock for biocompatible airway interfaces depends on concentrated petrochemical suppliers, exposing margin volatility to crude derivative pricing swings.
- NMPA registration timeline friction:Clinical validation requirements for Class III respiratory devices extend market access windows by 18-36 months versus comparable FDA pathways.
- Adaptive algorithm substitution risk:Software-based ventilation optimization threatens hardware refresh cycles for legacy mechanical ventilator platforms.
Strategic Opportunities
- Shandong province homecare penetration:Underdeveloped rural respiratory therapy infrastructure in this northern region presents whitespace for portable oxygen concentrator deployment.
- Digital therapeutics convergence:Integration of remote patient monitoring with continuous positive airway pressure systems is opening subscription revenue streams beyond device sales.
- GB standards harmonization:Alignment between national standards and ISO 80601-2-80 is reducing technical barriers for export-oriented domestic manufacturers.
Industry Challenges
- Embedded systems firmware talent scarcity:Adaptive ventilation algorithm development requires specialized expertise in real-time pressure sensing and control loop engineering that outstrips current graduate pipeline output.
- Legacy hospital IT integration complexity:New respiratory monitoring platforms must interface with heterogeneous electronic health record systems across tiered hospital networks, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Respiratory Devices Market |
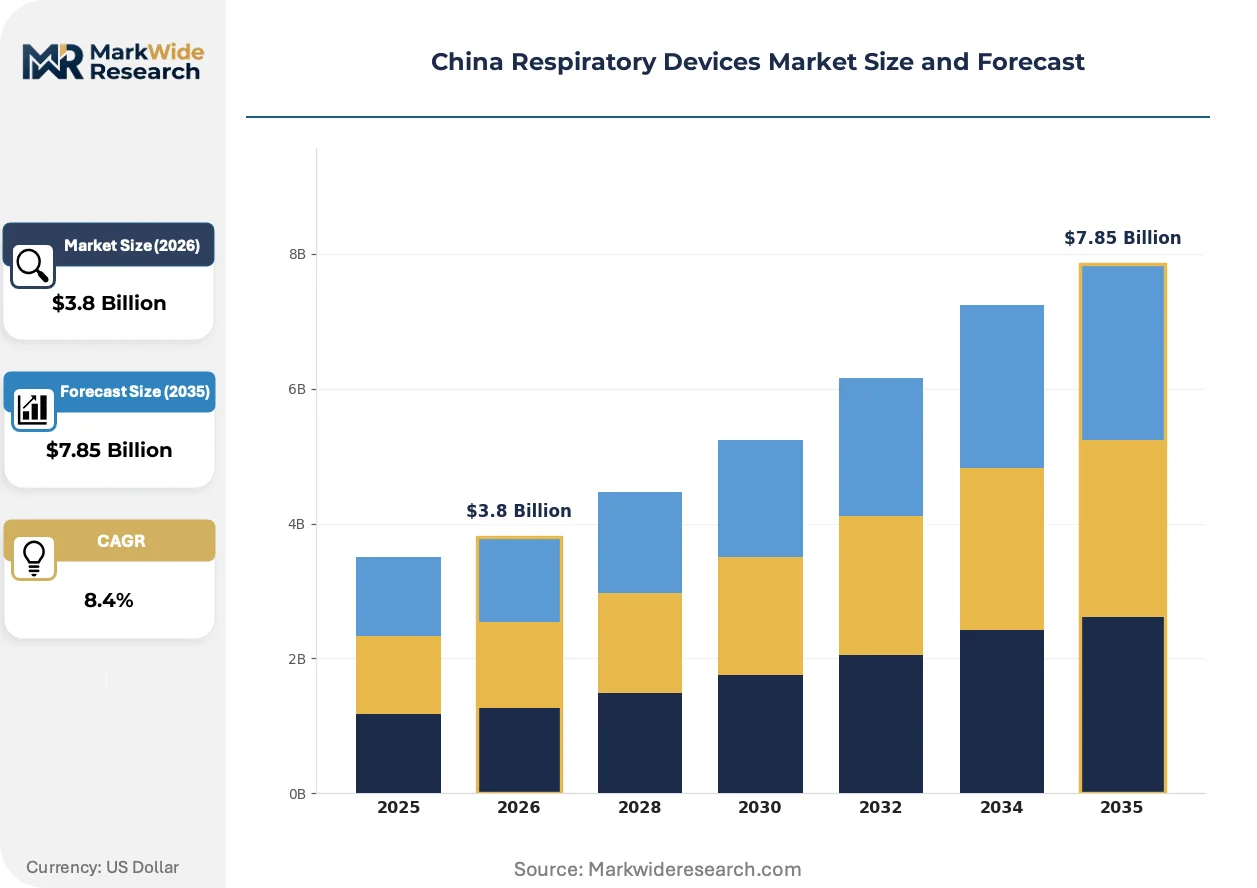
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $7.85 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ventilators, Nebulizers, CPAP Devices, Oxygen Concentrators End User: Hospitals, Homecare, Clinics, Rehabilitation Centers Technology: Adaptive Ventilation, Digital Monitoring, Portable Solutions, Automated Therapy Application: Chronic Obstructive Pulmonary Disease, Asthma, Sleep Apnea, Acute Respiratory Distress Syndrome |
| Companies Covered | Beijing Mindray Bio-Medical Electronics Co., Ltd., Shanghai Honsung Medical Instruments Co., Ltd., Shandong Weigao Group Medical Polymer Co., Ltd., Yuwell-Jiangsu Yuyue Medical Equipment & Supply Co., Ltd., Fisher & Paykel Healthcare, ResMed, Philips Respironics, Drägerwerk, Medtronic, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Respiratory Devices Market Strategic Shifts
Digital respiratory therapeutics are converging with remote care infrastructure, compressing the traditional boundary between acute hospital ventilation and chronic home management while forcing hardware manufacturers to develop software service capabilities.
Turbine-based oxygen concentrator architectures are electrifying portable device categories by replacing legacy compressor systems with brushless DC motor arrays that reduce weight and acoustic signatures. Homecare distributors in Jiangsu province are prioritizing these platforms for elderly patient discharge protocols. The technology is electrifying competitive positioning by enabling same-day delivery logistics previously impossible with heavier legacy units.
NMPA's draft guidance on software-as-a-medical-device for respiratory algorithms is tightening clinical evidence requirements for machine learning-enabled ventilation parameter adjustment. Domestic manufacturers with established GB standard compliance records are accelerating regulatory dossier preparation. Imported premium systems face extended validation timelines as equivalence determinations for adaptive pressure support modes remain unresolved.
Hospital procurement committees are unbundling ventilator hardware from multi-year service contracts, forcing manufacturers to compete on discrete capital expenditure bids rather than bundled lifecycle pricing. This pattern concentrates in tertiary hospitals in Beijing and Shanghai where centralized purchasing authority has consolidated. Distributors respond by developing independent technical service capabilities to capture aftermarket revenue separated from initial equipment sales.
China Respiratory Devices Market Segmentation
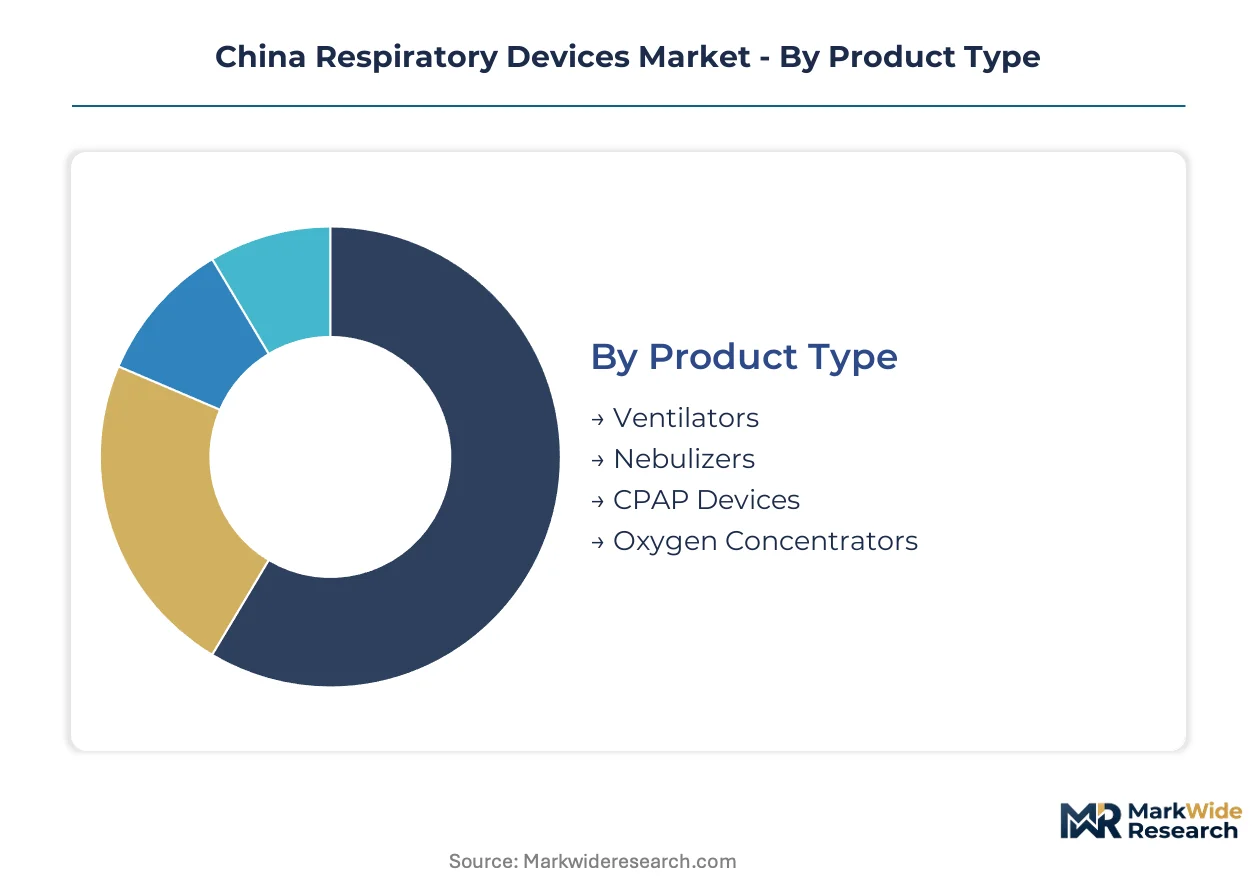
Respiratory device manufacturers in China deploy distinct capital allocation strategies across product architectures, with ventilator platforms demanding precision machining investments while oxygen concentrator assembly favors modular outsourcing. Understanding where fixed costs concentrate versus where variable scale dominates clarifies entry economics for domestic and imported competitors alike.
Product Type:
Ventilator manufacturing anchors the highest capital intensity, requiring cleanroom assembly lines and pneumatic testing infrastructure that oxygen concentrator production can bypass through supplier networks.
- Ventilators:Critical care platforms integrate turbine blowers, proportional solenoid valves, and pressure transducers calibrated to ISO 80601-2-80 tolerances. Tertiary hospitals in Beijing and Shanghai concentrate procurement authority for these systems, though NMPA Class III registration timelines extend 18-36 months.
- Oxygen Concentrators:Molecular sieve beds and compressor assemblies dominate bill-of-materials costs, with portable variants electrifying through brushless DC motor adoption. Homecare distributors in Jiangsu province prioritize these units for elderly discharge protocols, compressing delivery logistics timelines.
- Nebulizers:Piezoelectric mesh and jet compressor variants serve pediatric asthma management in tier-2 city clinics.
- CPAP Devices:Continuous positive airway pressure systems integrate flow sensors with humidification modules for sleep apnea therapy.
Ventilators absorb the bulk of installed capacity; oxygen concentrators are expanding most quickly.
End User:
Customer procurement patterns diverge sharply, with hospitals demanding integrated service contracts while homecare channels prioritize discrete price points and logistics flexibility.
- Hospitals:Tertiary facilities in Beijing and Shanghai unbundle hardware from multi-year service agreements, forcing discrete capital expenditure competition. Centralized purchasing committees now separate initial equipment bids from aftermarket technical support.
- Homecare:Aging demographics and COPD prevalence shift therapeutic settings, with Shandong province presenting underpenetrated rural infrastructure for portable oxygen deployment.
- Clinics:Outpatient respiratory therapy centers in Jiangsu industrial clusters favor nebulizer and diagnostic device procurement.
- Rehabilitation Centers:Post-acute care facilities integrate ventilator weaning protocols with physical therapy programs.
Hospitals command the steepest revenue per account; homecare channels are climbing the fastest.
Technology:
Software-enabled functionality is redrawing competitive moats, with algorithm development talent scarcity constraining domestic manufacturer advancement in adaptive systems.
- Adaptive Ventilation:Real-time pressure support algorithms adjust to patient respiratory mechanics using closed-loop control systems. NMPA draft guidance on software-as-a-medical-device tightens clinical evidence requirements for machine learning-enabled parameter adjustment.
- Digital Monitoring:Remote patient data transmission integrates with hospital electronic health record systems, though heterogeneous IT infrastructure across tiered networks delays deployment timelines.
- Portable Solutions:Battery-powered architectures reduce weight and acoustic signatures for ambulatory patient use.
- Automated Therapy:Self-adjusting CPAP systems optimize pressure delivery without manual titration.
Digital monitoring captures the largest installed base; adaptive ventilation is gaining share fastest.
Application:
Disease-specific device configurations align with reimbursement pathways and clinical workflow integration requirements across Chinese healthcare tiers.
- Chronic Obstructive Pulmonary Disease:Long-term oxygen therapy and non-invasive ventilation dominate device utilization for China's elderly population, with homecare migration reducing hospital bed dependency.
- Sleep Apnea:Diagnostic protocol expansion and compliance monitoring integration generate disproportionate revenue concentration. ResMed and domestic competitors compete on mask interface comfort and data platform connectivity.
- Asthma:Pediatric and adult management relies heavily on nebulizer delivery systems in outpatient settings.
- Acute Respiratory Distress Syndrome:ICU ventilator dependency drives highest-margin hardware procurement with most intensive technical service requirements.
COPD applications anchor the largest device installed base; sleep apnea is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu province anchors China's respiratory device manufacturing through dense medical device industrial clusters in Suzhou and Nanjing, where component ecosystems enable rapid prototyping and cost-efficient scale-up for mechanical ventilators and oxygen concentrators.
Jiangsu Province
Elderly discharge protocols and homecare distributor networks drive portable oxygen concentrator demand across Suzhou and Nanjing medical corridors. NMPA Class III registration requirements extend market access timelines for imported systems. Yuwell-Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. controls component sourcing through finished device assembly within this cluster.
Shandong Province
Underpenetrated rural respiratory therapy infrastructure generates whitespace for portable oxygen deployment in northern municipalities. Shandong Weigao Group Medical Polymer Co., Ltd. leverages regional polymer processing capabilities for biocompatible airway interfaces. MEE emissions frameworks accelerate energy-efficient production protocol adoption across Weihai and Qingdao manufacturing zones.
Beijing-Tianjin-Hebei
Tertiary hospital procurement committees in Beijing unbundle ventilator hardware from multi-year service contracts, forcing discrete capital expenditure competition. SAMR quality oversight constrains manufacturing facility certifications for Class III respiratory devices. Beijing Mindray Bio-Medical Electronics Co., Ltd. anchors R&D intensity for digital monitoring platforms within this corridor.
Shanghai
Centralized purchasing authority in Shanghai tertiary hospitals concentrates procurement decisions for premium imported systems. NMPA equivalence pathways for adaptive ventilation algorithms remain unresolved for foreign manufacturers. Shanghai Honsung Medical Instruments Co., Ltd. occupies mid-tier positioning through domestic nebulizer and diagnostic device production.
China Respiratory Devices Market Competitive Environment
The competitive structure tilts toward vertically integrated domestic specialists competing against technology-leading foreign premium platforms. Jiangsu and Shandong industrial clusters concentrate manufacturing capacity for cost-efficient oxygen concentrator scale-up. Three archetypes dominate: provincial champions with backward integration into component supply, multinational premium technology providers navigating extended NMPA timelines, and mid-tier assemblers sourcing modular subsystems. Capacity expansion and regulatory dossier preparation for software-as-a-medical-device equivalence represent the dominant competitive moves.
Among Jiangsu-based fabricators, Yuwell-Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. exemplifies the vertically integrated provincial champion archetype through captive control of manufacturing inputs. Beijing Mindray Bio-Medical Electronics Co., Ltd. represents domestic R&D-intensive competition on digital therapeutics convergence. ResMed occupies the foreign premium technology tier, navigating NMPA registration pathways for algorithm-driven ventilation systems while sustaining sleep apnea interface leadership.
| Leading Market Players |
|---|
| Beijing Mindray Bio-Medical Electronics Co., Ltd. |
| Shanghai Honsung Medical Instruments Co., Ltd. |
| Shandong Weigao Group Medical Polymer Co., Ltd. |
| Yuwell-Jiangsu Yuyue Medical Equipment & Supply Co., Ltd. |
| Fisher & Paykel Healthcare |
| ResMed |
| Philips Respironics |
| Drägerwerk |
| Medtronic |
| Others |
Value Chain & Pricing Dynamics
Tertiary hospital procurement committees in Beijing and Shanghai concentrate purchasing authority for Class III respiratory devices, forcing manufacturers toward discrete capital expenditure bidding rather than bundled lifecycle contracts. This buyer concentration compresses margin pools for imported premium systems while rewarding domestic competitors with certified green facilities under MEE emissions frameworks.
Pricing Analysis
Outcome-based contracting anchored to patient weaning success rates is emerging in Beijing's ICU procurement protocols, though transactional per-unit bidding still dominates oxygen concentrator sales. Price differentiation separates NMPA Class III certified systems from Class II equivalents, with adaptive ventilation algorithms commanding technology premiums. Pricing pressure stems from hospital procurement unbundling that separates hardware from multi-year service agreements. Homecare distributors in Jiangsu province exhibit highest price sensitivity due to elderly patient out-of-pocket burdens, while tertiary ICU committees prioritize technical specifications over unit cost.
Supply Chain Analysis
GB standards compliance and NMPA facility certification requirements gate component sourcing for biocompatible airway interfaces, constraining supplier qualification to Jiangsu and Shandong polymer processors. Medical-grade silicone and polycarbonate feedstocks draw from petrochemical suppliers concentrated in Shandong's Weihai and Qingdao zones, with molecular sieve beds for oxygen concentrators sourcing from domestic mineral processors. Single-source vulnerability concentrates in precision pressure transducer supply, where ISO 80601-2-80 calibration capabilities remain limited. Distribution runs through provincial medical device industrial clusters to hospital procurement committees and homecare distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
NMPA Class III registration timelines and GB standards enforcement create a cost-of-compliance moat that rewards manufacturers with established regulatory dossiers and certified green facilities. SAMR quality oversight and MEE emissions frameworks further deepen barriers for undercapitalized entrants.
For Market Incumbents: Acquire embedded systems firmware development capabilities to secure adaptive ventilation algorithm talent scarce in China's graduate pipeline. Consolidate control over medical-grade polymer supply relationships in Shandong province before feedstock volatility spreads. Defend against software-as-a-medical-device substitution threats by accelerating NMPA equivalence pathway preparation for machine learning-enabled pressure support modes. For New Entrants and Emerging Players: Rural homecare distributors in northern Shandong municipalities represent an underserved buyer archetype with whitespace for portable oxygen concentrator deployment. Target nebulizer procurement in Jiangsu tier-2 city clinics where centralized Beijing-Shanghai purchasing authority weakens. Pursue direct relationships with elderly discharge protocol coordinators rather than competing for tertiary hospital ventilator contracts. For Investors and Strategic Acquirers: The window for entry favors vertically integrated domestic specialists with backward control over component sourcing and established GB standard compliance records. Long-term viability hinges on regulatory dossier depth rather than hardware manufacturing scale alone. Watch NMPA draft guidance finalization on software-as-a-medical-device as the signal indicating which algorithm-driven platforms will secure accelerated market access.| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Class III Registration Acceleration | Compresses 18-36 month timelines for adaptive ventilation systems through pre-submission engagement with NMPA reviewers. |
| Software-as-a-Medical-Device Dossier Preparation | Positions manufacturers for equivalence determinations on machine learning-enabled pressure support algorithms. |
| Green Facility Certification Investment | Aligns production protocols with MEE emissions frameworks under China's dual carbon goals mandate. |
| Homecare Distributor Network Expansion | Captures elderly discharge protocol demand in underpenetrated Shandong rural municipalities. |
| Embedded Systems Firmware Acquisition | Secures scarce real-time pressure sensing and control loop engineering expertise for adaptive ventilation development. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with hospital purchasing committee directors, biomedical engineers at tertiary facilities, GPO contracts managers, homecare distributor operators, and NMPA regulatory affairs specialists. China Association for Medical Devices Industry statistics, SAMR quality oversight disclosures, MEE emissions framework documentation, and Jiangsu-Shandong customs export records provided demand-side validation. Bottom-up oxygen concentrator shipment data and top-down healthcare expenditure trends were triangulated against ventilator procurement records from Beijing and Shanghai hospital systems.
Data-stream reconciliation across product type, end user, technology, and application dimensions generated volume and value outputs across the projection horizon. Segmentation modeling incorporated COPD prevalence demographics, sleep apnea diagnostic protocol expansion rates, and homecare migration patterns as industry-specific forecast inputs. CAGRs were derived from trend extrapolation of historical shipment data adjusted for NMPA registration timeline impacts and MEE certification adoption curves.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to NMPA software-as-a-medical-device guidance finalization and embedded systems firmware talent pipeline constraints. Forecasts reflect assumptions about regulatory pathway stability and polymer feedstock pricing continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Embolization Plugs Market
Medical Devices
Solar Surgical Light Market
Medical Devices
Medical Device Manufacturing Outsourcing Market
Medical Devices
North America Wearable Medical Devices Market
Medical Devices
Smart Vision Aids Market
Medical Devices
Smart Lenses Market
Medical Devices
Catheter Introducer Sheaths Market
Medical Devices
Indwelling Catheter Market
Medical Devices
Intraoral Scanners Market
Medical Devices
Spinal Fusion Bone Graft Substitutes Market
Medical Devices
Elbow Fixators Market
Medical Devices
Ultra-Large Volume Wearable Injectors Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Anesthesia Circuits Market
Medical Devices
Global Positive Airway Pressure Devices Market
Medical Devices
South Africa Anti-Blue Ray Myopia Lenses Market