
 Closed Funnel Ampoules Market | 2026-2036
Closed Funnel Ampoules Market Size, Share, and Industry Trends Forecast 2026-2036
Closed Funnel Ampoules Market Outlook
The EU Green Deal is broadening compliance obligations across European pharmaceutical packaging supply chains, compelling glass ampoule manufacturers to decarbonize melting furnaces and reduce carbon footprints. Gerresheimer AG leverages captive glass-forming technology and vertical furnace control to sustain cost leadership in high-volume parenteral formats. SCHOTT Pharma AG & Co. KGaA anchors its position through pharmaceutical-grade borosilicate specialization and cleanroom finishing capabilities. Stevanato Group differentiates by integrating secondary packaging and device assembly adjacent to primary glass production.
Closed funnel ampoules are sealed glass or plastic vessels with a constricted neck designed for aseptic filling and single-point withdrawal of injectable solutions, typically manufactured from Type I borosilicate glass or cyclic olefin polymer through tubular or molded forming processes. Glass variants dominate vaccine packaging applications where inertness and thermal stability prevent drug-container interaction, while plastic formats compete in diagnostic sample transport where breakage resistance matters. Pharmaceutical companies represent the deepest end-user margin pool due to validated supply requirements and long-term contract structures, whereas contract manufacturers represent the fastest-growing demand segment as outsourcing of fill-finish operations expands.
The European Medicines Agency enforces strict extractables and leachables standards for primary packaging materials, while the FDA mandates container closure integrity verification for all sterile injectable products, and ISO 9187 governs dimensional tolerances for ampoule neck and funnel geometries. These frameworks elevate barriers for unvalidated suppliers and concentrate procurement among certified manufacturers. Stakeholders must monitor evolving pharmacopeial standards for glass delamination and particle limits, as tightening thresholds will reshape qualification timelines and capital deployment priorities.
Market Dynamics
Pharmaceutical fill-finish outsourcing is compressing procurement cycles and concentrating volume among contract manufacturers with validated sterile packaging supply chains, forcing primary glass suppliers to co-locate forming operations adjacent to biologics manufacturing clusters.
Growth Catalysts
- EU Green Deal compliance mandates:The F-Gas Regulation and decarbonization targets for glass melting furnaces are accelerating capital redeployment toward electric and hybrid furnace technologies across European manufacturing sites.
- Biologics pipeline expansion:Monoclonal antibody and mRNA vaccine volumes are amplifying demand for Type I borosilicate ampoules with demonstrated container closure integrity and minimal extractables profiles.
- German glass packaging cluster density:Concentrated specialized forming expertise in the Mainz-Düsseldorf corridor enables rapid qualification cycles and just-in-time supply to parenteral drug manufacturers.
Market Restraints
- Energy cost volatility:Natural gas and electricity price spikes in European manufacturing regions are eroding margin structures for energy-intensive tubular glass forming processes.
- Specialized furnace equipment concentration:Limited suppliers of pharmaceutical-grade borosilicate melting and forming equipment create single-source dependency risks for capacity expansion.
- Plastic ampoule substitution:Cyclic olefin polymer alternatives are capturing diagnostic and sample transport applications where breakage resistance outweighs thermal stability requirements.
Strategic Opportunities
- Indian parenteral manufacturing expansion:CDSCO regulatory alignment with ICH standards and PLI scheme incentives for active pharmaceutical ingredients are drawing fill-finish investment and creating localized ampoule demand.
- Pre-filled syringe-ampoule hybrid formats:Convergence of ready-to-use container systems with integrated needle safety mechanisms is opening premium positioning in self-injection therapeutics.
- Secondary packaging integration:Adjacent assembly of device components and serialization-ready labeling at primary forming sites is compressing total cost of ownership for pharmaceutical buyers.
Industry Challenges
- Glass delamination expertise scarcity:Qualified analytical chemists capable of executing USP <1660> surface glass test protocols and interpreting ion release profiles remain in short supply across quality control functions.
- Qualification timeline compression:EMA and FDA dual filing requirements for container closure integrity and extractables documentation are extending new supplier onboarding cycles beyond 18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Closed Funnel Ampoules Market |
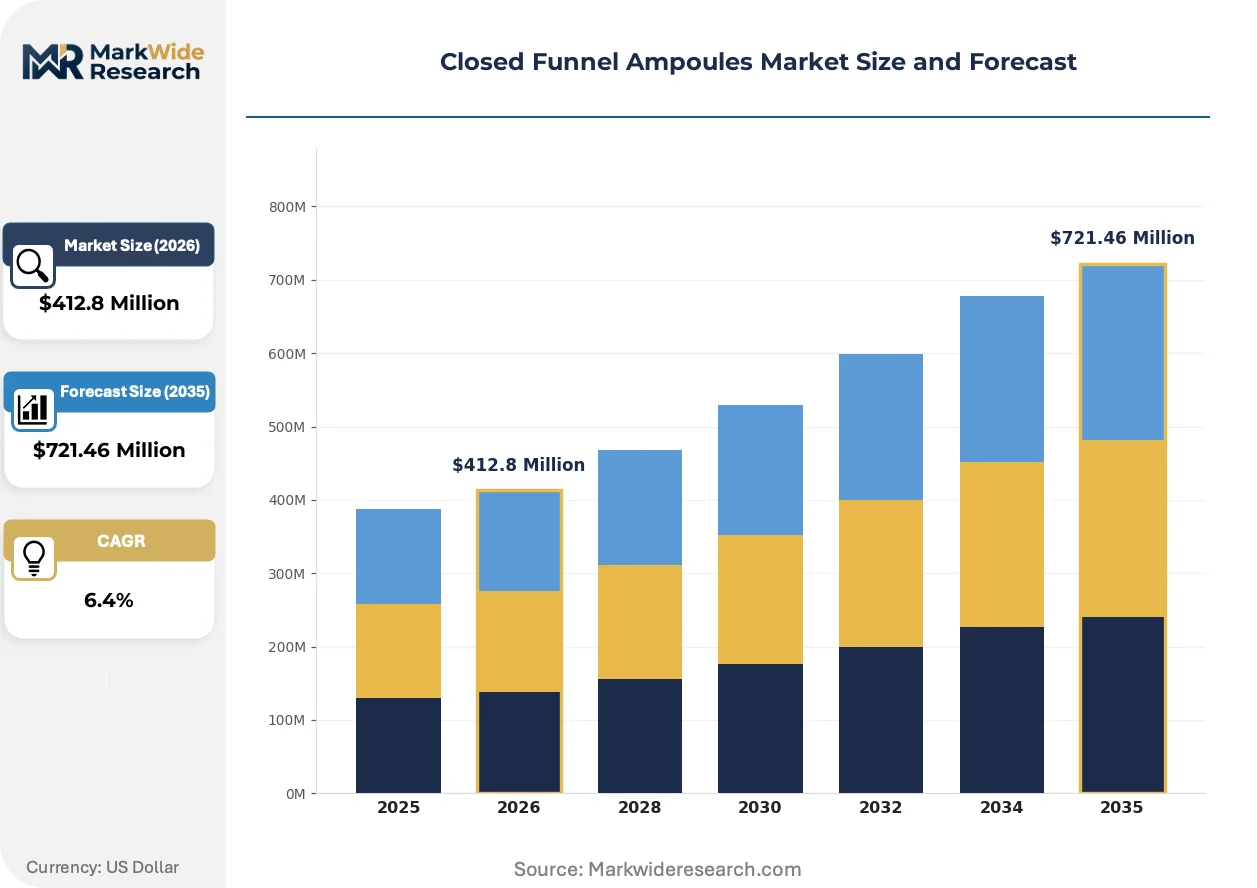
| Market Size in 2026 | $412.8 Million |
| Market Size in 2035 | $721.46 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastic, Glass, Sterile, Non-Sterile End User: Pharmaceutical Companies, Research Laboratories, Hospitals, Contract Manufacturers Application: Vaccine Packaging, Chemical Storage, Diagnostic Samples, Biological Hazard Transportation Size: 1ml, 5ml, 10ml, 20ml |
| Companies Covered | Gerresheimer AG, SCHOTT Pharma AG & Co. KGaA, Stevanato Group, Nipro Corporation, SGD Pharma, James Alexander Corporation, SANNER, Indian Scientific Glass Industries, ESSCO Glass, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Closed Funnel Ampoules Market Strategic Shifts
Material science advances and regulatory stringency are converging to redefine performance benchmarks for primary parenteral packaging, with sustainability metrics now embedded alongside functional qualification criteria in supplier selection protocols.
Ready-to-use (RTU) sterile ampoules processed through nested container handling systems are expanding into high-potency biologics manufacturing workflows where human intervention minimization governs contamination control strategy. Contract development and manufacturing organizations are adopting RTU formats at accelerating rates to reduce line clearance times and eliminate depyrogenation tunnel capital expenditure. This shift is expanding into the market for integrated fill-finish solutions that bundle primary container supply with validated handling equipment.
The EU F-Gas Regulation phase-down schedules for hydrofluorocarbons are compelling glass manufacturers to retrofit melting furnaces with oxy-fuel or electric boosting technologies to eliminate process emissions. Industrial consequence includes stranded asset risk for conventional regenerative furnace configurations and accelerated depreciation timelines for non-compliant capacity. German and French manufacturing sites face the most compressed compliance deadlines, with several facilities pursuing hybrid furnace rebuilds to maintain pharmaceutical qualification status while meeting 2030 emission reduction targets.
Consolidated procurement frameworks are displacing fragmented multi-supplier sourcing as pharmaceutical quality organizations centralize vendor qualification to reduce audit burden and standardize container closure integrity testing protocols. Large molecule drug manufacturers are consolidating primary packaging spend among two to three validated suppliers with global manufacturing footprints. This concentration is most visible in North American and European biologics manufacturing networks where supply assurance and regulatory consistency outweigh unit cost minimization in sourcing decisions.
Closed Funnel Ampoules Market Segmentation
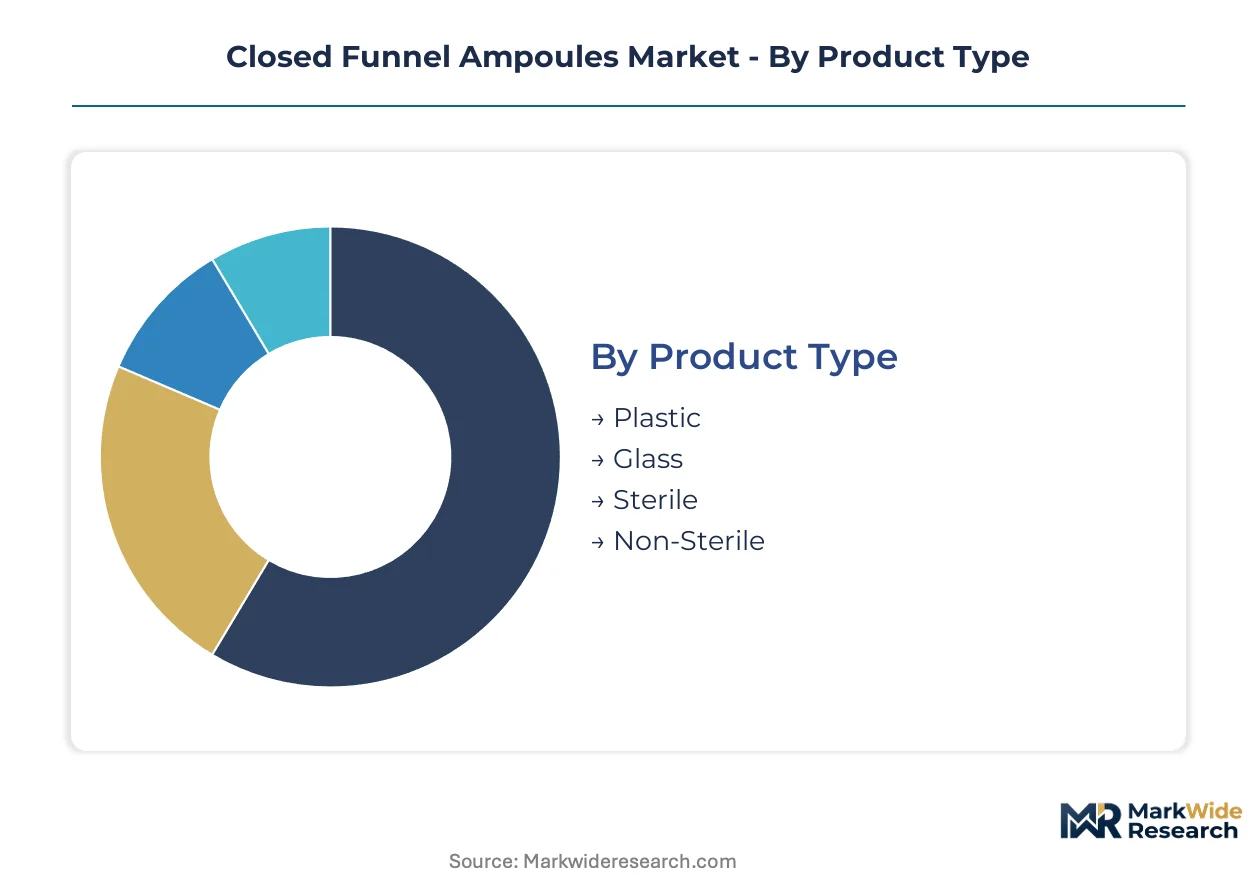
Segmentation in closed funnel ampoules reveals divergent technical requirements between pharmaceutical-grade borosilicate applications and diagnostic plastic formats. Procurement patterns vary sharply by end-user validation burden and regulatory filing complexity across product categories.
Product Type:
Material selection hinges on thermal stability needs versus breakage risk tolerance in the target application environment.
- Glass:Type I borosilicate formulations dominate vaccine packaging where USP <660> compliance and delamination resistance govern supplier qualification. Demand concentrates among German and French parenteral drug manufacturers facing EMA extractables scrutiny.
- Plastic:Cyclic olefin polymer variants capture diagnostic sample transport and point-of-care applications where drop resistance outweighs autoclave compatibility. CDSCO-aligned Indian laboratories are adopting plastic formats for field-based collection workflows.
- Sterile:Ready-to-use formats processed through nested container handling systems eliminate depyrogenation tunnel capital expenditure for contract manufacturers.
- Non-Sterile:Bulk formats serve research laboratories with in-house sterilization capabilities and lower validation requirements.
Volume sits with Glass; growth tilts toward Plastic.
End User:
Procurement authority and validation burden determine pricing power and contract structure across buyer categories.
- Pharmaceutical Companies:Deep margin pools and long-term supply agreements characterize this segment. FDA container closure integrity mandates and EMA dual filing requirements extend supplier onboarding beyond eighteen months.
- Contract Manufacturers:Outsourced fill-finish expansion is compressing procurement cycles and concentrating volume among validated sterile packaging supply chains. Indian CDSCO-aligned CDMOs represent the steepest expansion trajectory.
- Research Laboratories:Lower validation thresholds and spot-buying patterns dominate academic and government research procurement.
- Hospitals:Compounding pharmacies and centralized sterile preparation facilities drive demand for ready-to-use formats with integrated labeling.
Revenue concentrates with Pharmaceutical Companies; qualification speed favors Contract Manufacturers.
Application:
Functional performance requirements and regulatory exposure shape material specification and supplier selection.
- Vaccine Packaging:mRNA and viral vector platforms demand Type I borosilicate with demonstrated container closure integrity and minimal ion release profiles under thermal cycling stress.
- Diagnostic Samples:Plastic ampoules with breakage resistance and temperature stability from -80°C to ambient capture molecular diagnostics and transport media applications.
- Chemical Storage:Inertness specifications for reactive reagents favor borosilicate glass with sulfur-treated surfaces to prevent alkali leaching.
- Biological Hazard Transportation:Triple-packaging compliance with UN 3373 and IATA Dangerous Goods regulations governs primary container selection for infectious substance shipping.
Validation intensity peaks with Vaccine Packaging; volume flexibility characterizes Diagnostic Samples.
Size:
Fill-volume requirements and dosing precision determine dimensional tolerance specifications and forming process selection.
- 1ml:High-potency biologics and pediatric vaccines require tight neck geometry control for accurate dosing and minimal dead volume.
- 5ml:Standard antibiotic and analgesic presentations balance manufacturing throughput with clinical dosing flexibility.
- 10ml:Large-volume parenteral and diluent applications favor molded glass processes over tubular forming for dimensional consistency.
- 20ml:Bulk diagnostic reagents and contrast media storage drive demand for wide-mouth funnel geometries with enhanced pour characteristics.
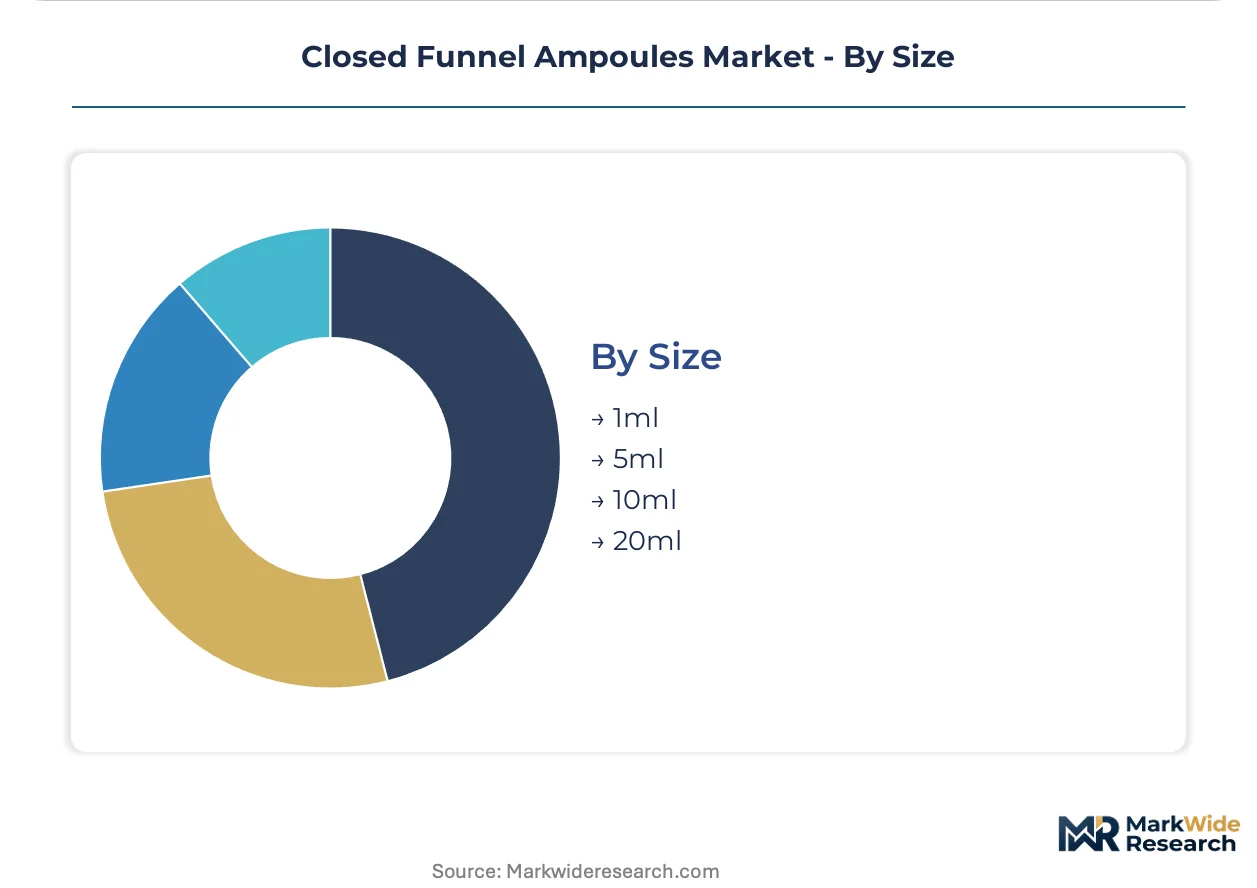
Unit economics favor 5ml; customization premiums attach to 1ml.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Mainz-Düsseldorf corridor anchors European glass ampoule production, with specialized forming expertise clustering along the Rhine-Ruhr industrial belt to serve parenteral drug manufacturers with rapid qualification cycles and just-in-time supply.
Germany
Pharmaceutical-grade borosilicate demand concentrates among parenteral drug manufacturers facing EMA extractables scrutiny and EU Green Deal decarbonization mandates. The F-Gas Regulation compels furnace retrofits toward oxy-fuel or electric boosting technologies. Gerresheimer and SCHOTT Pharma anchor specialized glass packaging clusters in Mainz and Mülheim an der Ruhr.
United States
FDA container closure integrity verification requirements and biologics pipeline expansion drive Type I borosilicate procurement among monoclonal antibody manufacturers. The Inflation Reduction Act provisions on domestic pharmaceutical manufacturing reinforce localized supply chain preferences. New Jersey and Massachusetts biopharma corridors concentrate fill-finish outsourcing demand.
India
CDSCO regulatory alignment with ICH standards and PLI scheme incentives for active pharmaceutical ingredients draw fill-finish investment and create localized ampoule demand. Contract development and manufacturing organizations adopt ready-to-use formats to reduce capital expenditure. Gujarat and Maharashtra pharmaceutical clusters represent the steepest expansion trajectory.
China
NMPA pharmacopeial standards for glass delamination and particle limits reshape qualification timelines for domestic and imported packaging materials. Dual carbon goals accelerate electric furnace adoption in glass manufacturing. Yangtze River Delta pharmaceutical manufacturing zones concentrate parenteral drug production and associated primary packaging procurement.
France
ANSM enforcement of extractables and leachables standards elevates barriers for unvalidated suppliers and concentrates procurement among certified manufacturers. EU MDR compliance timelines compress supplier onboarding cycles for medical device-drug combination products. Paris-Saclay biopharma cluster drives demand for high-integrity container systems.
Closed Funnel Ampoules Market Competitive Environment
Premium-margin players sit above commodity-margin players across validation burden and regulatory filing complexity, with certified borosilicate specialists commanding pricing power through eighteen-month qualification cycles and captive furnace control. The vendor base stratifies into three archetypes: integrated glass-forming specialists with vertical furnace ownership, diversified packaging conglomerates with pharmaceutical division carve-outs, and regional fabricators serving diagnostic and research laboratory spot demand. Dominant competitive moves include hybrid furnace rebuilds to meet EU F-Gas Regulation phase-down schedules and co-location of forming operations adjacent to biologics manufacturing clusters.
Within the integrated specialist tier, Gerresheimer AG and SCHOTT Pharma AG & Co. KGaA exemplify archetypes defined by captive glass-forming technology and pharmaceutical-grade borosilicate specialization, while Stevanato Group occupies a position representing secondary packaging integration adjacent to primary glass production.
| Leading Market Players |
|---|
| Gerresheimer AG |
| SCHOTT Pharma AG & Co. KGaA |
| Stevanato Group |
| Nipro Corporation |
| SGD Pharma |
| James Alexander Corporation |
| SANNER |
| Indian Scientific Glass Industries |
| ESSCO Glass |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between EMA-validated borosilicate specialists and unqualified regional fabricators manifests in eighteen-month qualification premiums for pharmaceutical buyers and just-in-time supply configurations that cluster forming operations adjacent to German parenteral manufacturing corridors. This bifurcation concentrates procurement authority among buyers with dual-filing capabilities while compressing margins for spot-market suppliers serving diagnostic laboratories with lower validation thresholds.
Pricing Analysis
Yield-guarantee pricing anchors pharmaceutical contracts where container closure integrity failures trigger batch recalls costing millions in lost biologics output. Three-tier pricing structure across premium, standard, and economy levels separates EMA-FDA dual-filed suppliers from single-jurisdiction qualifiers and unvalidated commodity producers. Cost compression in standard-tier tubular glass is intensifying because German energy price volatility erodes furnace economics. Contract manufacturers exhibit highest price sensitivity due to compressed procurement cycles, while large molecule drug developers prioritize supply assurance over unit cost minimization.
Supply Chain Analysis
Direct-to-pharma channels handle validated sterile packaging demand from monoclonal antibody manufacturers with long-term offtake agreements, while distributor-mediated supply serves research laboratories with spot-buying patterns. Geographic concentration centers on Germany, France, and India, with the Mainz-Düsseldorf corridor anchoring European borosilicate expertise and Gujarat-Maharashtra clusters emerging for CDSCO-aligned contract manufacturing. Raw material dependencies rest on high-purity sand deposits, pharmaceutical-grade boron sources, and specialized refractory equipment for furnace construction. Single-source vulnerability in pharmaceutical-grade melting equipment creates stranded asset risk for capacity expansion timelines. Distribution runs through validated cold-chain logistics for ready-to-use sterile formats.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized furnace equipment scarcity constrains capacity expansion timelines, propping pricing power for validated suppliers with captive forming technology and eighteen-month qualification backlogs that lock in buyer relationships.
For Market Incumbents: Anticipate cyclic olefin polymer substitution threats in diagnostic applications by accelerating hybrid furnace rebuilds to meet EU F-Gas Regulation phase-down schedules while securing oxy-fuel equipment slots from limited specialized suppliers. Backward integration into high-purity sand sourcing reduces exposure to commodity volatility. Channel control through co-location adjacent to Indian CDMO clusters defends margin position against emerging regional fabricators. For New Entrants and Emerging Players: Contract manufacturing organizations in Gujarat and Maharashtra represent the most penetrable entry point given CDSCO regulatory alignment with ICH standards and PLI scheme incentives drawing fill-finish investment. Diagnostic sample transport applications with lower validation thresholds offer faster revenue traction than pharmaceutical qualification cycles. A go-to-market angle bundling ready-to-use sterile formats with nested container handling equipment addresses capital expenditure constraints among mid-scale CDMOs. For Investors and Strategic Acquirers: Re-rating potential sits with integrated glass-forming specialists possessing pharmaceutical-grade borosilicate specialization and vertical furnace ownership given EU Green Deal compliance mandates accelerating industry consolidation. Long-term viability over the next decade hinges on electric furnace technology transition completion and Indian manufacturing footprint establishment. Acquisition targets should demonstrate captive forming technology and existing EMA validation status. The signal to watch is hybrid furnace order backlog accumulation at specialized equipment suppliers as an inflection indicator for compliance-driven capacity restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Furnace Rebuild Program | EU F-Gas Regulation compliance secures pharmaceutical qualification status for German manufacturing sites. |
| Indian Manufacturing Footprint Expansion | CDSCO-aligned production captures PLI scheme incentives and localized fill-finish demand growth. |
| Ready-to-Use Format Portfolio Development | Eliminates depyrogenation tunnel capital expenditure for contract manufacturing organization buyers. |
| Secondary Packaging Integration | Adjacent device assembly and serialization-ready labeling compresses total cost of ownership for pharmaceutical procurement. |
| Pre-filled Syringe-Ampoule Hybrid Launch | Integrated needle safety mechanisms open premium positioning in self-injection therapeutics segments. |
Study Parameters
Document review covered EMA regulatory filings, FDA container closure integrity guidance, ISO 9187 dimensional standards, and EU F-Gas Regulation implementation schedules, complemented by interviews with pharmaceutical packaging procurement directors, quality assurance leads at parenteral drug manufacturers, glass-forming plant managers, and contract development manufacturing organization executives. Secondary validation drew from customs trade data, pharmaceutical industry association reports, and SEC filings of publicly traded packaging companies. Bottom-up demand modeling across end-user segments and top-down supply capacity assessment enabled triangulation of market sizing.
Segment-level outputs across material type, sterility status, end-user category, application, and fill volume were developed over the projection horizon. CAGRs were derived from regression analysis of historical pharmaceutical production trends, parenteral drug pipeline advancement rates, and regulatory compliance investment cycles. Industry-specific forecast inputs incorporated biologics manufacturing capacity expansion timelines and electric furnace technology adoption curves under EU decarbonization mandates.
Several conditions sit outside the modeled scope, including unforeseen pharmacopeial standard revisions for glass delamination thresholds, abrupt energy price shocks affecting European furnace economics, and trade policy disruptions impacting Indian pharmaceutical export flows. Forecasts reflect assumptions regarding sustained regulatory stringency and gradual technology transition timelines. Periodic stress-testing of base assumptions is recommended given qualification timeline compression risks and single-source equipment dependencies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Pharmaceutical Contract Manufacturing and Contract Research Market
Pharmaceutical Equipment
Pharmaceutical Incubators Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Flip Top Vials Market
Pharmaceutical Equipment
Global Pharmaceutical Isolator Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Asia-Pacific Pharmaceutical Isolator Market
Pharmaceutical Equipment
Lyophilization Equipment and Services Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Formulation Development Outsourcing Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
Pharmaceutical Track and Trace Systems Market
Pharmaceutical Equipment
Sterile Injectable Contract Manufacturing Market
Pharmaceutical Equipment
Radiochemical Synthesizers Market
Pharmaceutical Equipment
Sterile Fill-Finish Process Simulation and Media Fill Test Equipment Market