
 Middle East and Africa Sperm Separation Devices Market | 2026-2036
Middle East and Africa Sperm Separation Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Sperm Separation Devices Market Foresight
Microfluidic chip integration is narrowing the performance gap between high-throughput clinical systems and portable diagnostic platforms across the Middle East and Africa. Hamilton Thorne leverages its North American R&D base to supply gradient centrifugation workstations into Gulf fertility networks. FUJIFILM Irvine Scientific anchors regional distribution through Dubai-based cold-chain logistics for media and separation consumables. Vitrolife competes on cryopreservation-compatible separation protocols that sustain embryo viability rates in hot-climate storage conditions.
Sperm separation devices isolate motile, morphologically normal spermatozoa from seminal plasma using density gradient centrifugation, swim-up migration, or magnetic-activated cell sorting, typically achieving 90-95% motile sperm recovery for intracytoplasmic sperm injection procedures. Microfluidic chips now capture premium positioning in urban fertility hubs where clinics prioritize minimal sperm DNA fragmentation and reduced oxidative stress during processing. Gradient centrifugation sustains volume leadership across price-sensitive hospital laboratories in North Africa where capital equipment replacement cycles stretch across seven to ten years. Magnetic-activated cell sorting occupies a narrowing but technically defensible niche for genetic testing applications requiring HLA-compatible sperm selection.
South Africa's SAHPRA and Saudi Arabia's SFDA enforce CE-marked or FDA-cleared device registration pathways that filter non-compliant suppliers from formal procurement channels. The UAE's MOHAP operates a parallel but converging regulatory framework through Dubai Health Authority and Abu Dhabi Department of Health dual jurisdiction. Egypt's national pharmaceutical regulator maintains less stringent import licensing, creating variable quality tiers across the Nile Delta clinic corridor. Stakeholders must monitor harmonization pressures between Gulf Cooperation Council medical device directives and national sovereignty over reproductive technology approvals.
Market Dynamics
Microfluidic chip platforms are compressing the performance advantage of legacy centrifugation systems across fertility networks in the Middle East and Africa, forcing incumbents to defend installed base through service bundling and consumable lock-in strategies.
Growth Catalysts
- SFDA Device Registration Pathways:Saudi Arabia's tightened quality standards for in vitro fertilization consumables are filtering non-compliant suppliers from formal procurement channels, concentrating demand among CE-marked and FDA-cleared manufacturers.
- Medical Tourism Infrastructure:Dubai Health Authority's fertility hub certification program is attracting cross-border patients from sub-Saharan Africa and South Asia, expanding addressable procedure volumes for equipped clinics.
- Swim-Up Migration Protocols:Cost-sensitive hospital laboratories across North Africa are adopting simplified sperm preparation methods that reduce per-procedure consumable expenditure while maintaining acceptable clinical outcomes.
Market Restraints
- Capital Equipment Replacement Cycles:North African public hospital laboratories stretch gradient centrifugation workstation replacement across seven to ten years, delaying uptake of microfluidic alternatives.
- Cold-Chain Logistics Concentration:Temperature-sensitive media and separation consumables depend on Dubai-based distribution nodes, creating vulnerability to regional shipping disruptions.
- Magnetic-Activated Cell Sorting Limitations:HLA-compatible sperm selection applications remain technically narrow, constraining addressable market expansion beyond specialized genetic testing centers.
Strategic Opportunities
- Egypt's Nile Delta Clinic Corridor:Less stringent import licensing compared to Gulf Cooperation Council jurisdictions creates first-mover positioning for quality-tier suppliers willing to navigate variable regulatory enforcement.
- MOHAP-DHA Harmonization Pressures:Convergence between UAE federal and emirate-level reproductive technology approvals may simplify multi-jurisdiction market access for compliant device manufacturers.
- Oxidative Stress Reduction Protocols:Hot-climate storage conditions across the Gulf states are driving demand for cryopreservation-compatible separation methods that sustain embryo viability rates.
Industry Challenges
- Embryologist Training Pipeline:Microfluidic chip operation requires specialized technical competency that outpaces regional clinical education program output, constraining deployment velocity in secondary cities.
- Dual Jurisdiction Compliance:Fertility clinics operating across Dubai Health Authority and Abu Dhabi Department of Health regulatory boundaries face duplicated quality system audits and documentation requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Sperm Separation Devices Market |
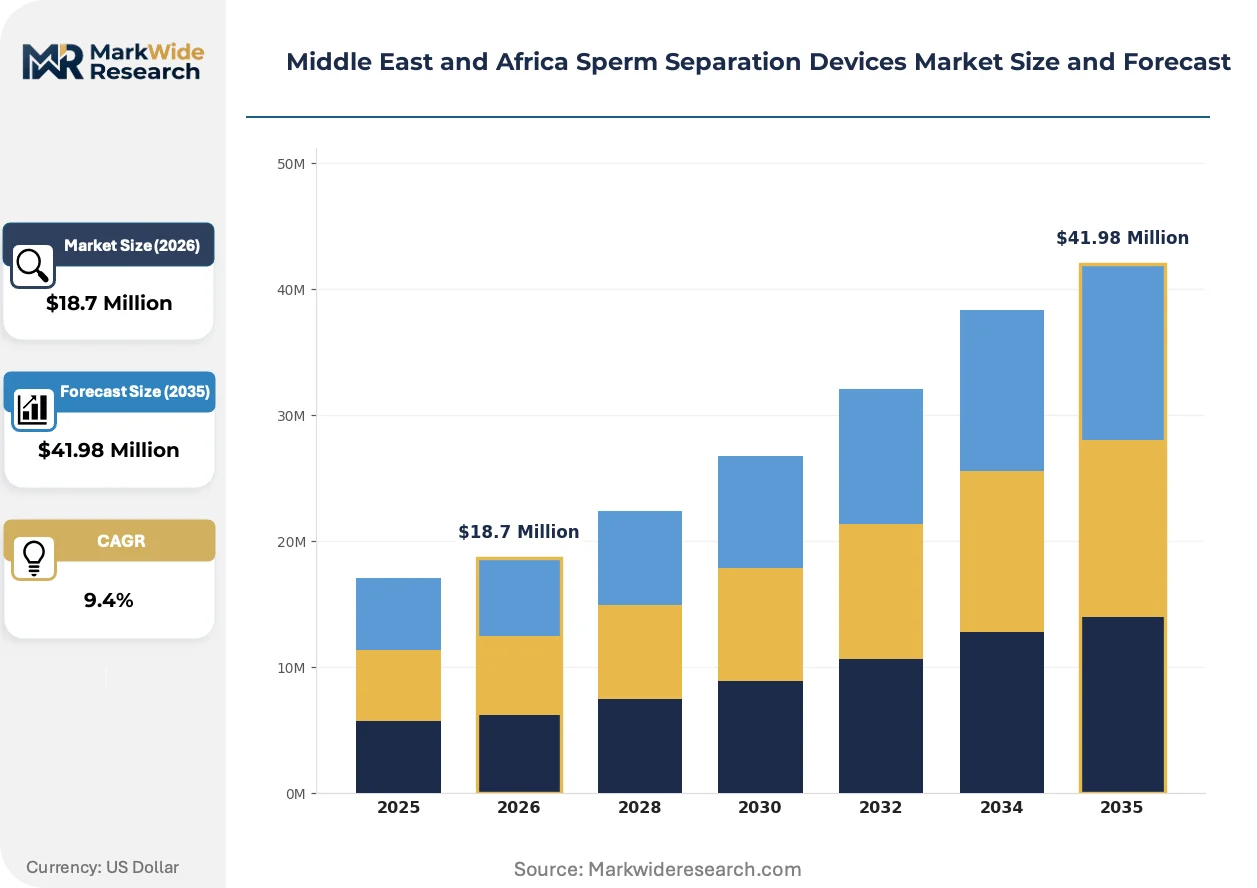
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.98 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microfluidic Devices, Centrifuges, Filtration Systems, Magnetic Separation Devices Technology: Gradient Centrifugation, Swim-up Technique, Magnetic-Activated Cell Sorting, Microfluidic Chips End User: Fertility Clinics, Hospitals, Research Laboratories, Diagnostic Centers Application: In Vitro Fertilization, Genetic Testing, Sperm Banking, Research Studies |
| Companies Covered | Hamilton Thorne, FUJIFILM Irvine Scientific, Memphasys, Kitazato Corporation, Trivector Biomed LLP, Merck KGaA, Nidacon Laboratories AB, Cook Medical, Vitrolife, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Sperm Separation Devices Market Shifts & Advancements
Device architecture across the Middle East and Africa is bifurcating between premium microfluidic platforms in urban fertility hubs and durable centrifugation workstations in price-constrained public health systems.
Density gradient centrifugation remains the dominant sperm separation modality for high-volume hospital laboratories, achieving 90-95% motile sperm recovery for intracytoplasmic sperm injection procedures. Urban fertility hubs in Johannesburg, Riyadh, and Dubai are migrating from these legacy systems toward microfluidic chips that minimize sperm DNA fragmentation during processing. This migration is compressing the addressable market for new centrifugation workstation placements while expanding recurring consumable revenue pools for chip manufacturers.
SAHPRA in South Africa and SFDA in Saudi Arabia are converging on CE-marked or FDA-cleared device registration as mandatory preconditions for formal procurement channel access. This regulatory alignment is excluding non-compliant suppliers from government and private insurance reimbursement pathways. Gulf Cooperation Council medical device directive harmonization pressures are accelerating quality standard elevation across the region's fertility clinic networks.
Fertility clinic procurement patterns are fragmenting between bundled service contracts from multinational distributors and direct manufacturer relationships for consumable replenishment. Large clinic chains in the UAE and South Africa are consolidating purchasing power through group procurement organizations, squeezing distributor margins. This consolidation is most visible in Johannesburg and Cape Town, where multi-site fertility networks negotiate annual volume commitments in exchange for preferential pricing tiers.
Middle East and Africa Sperm Separation Devices Market Segmentation
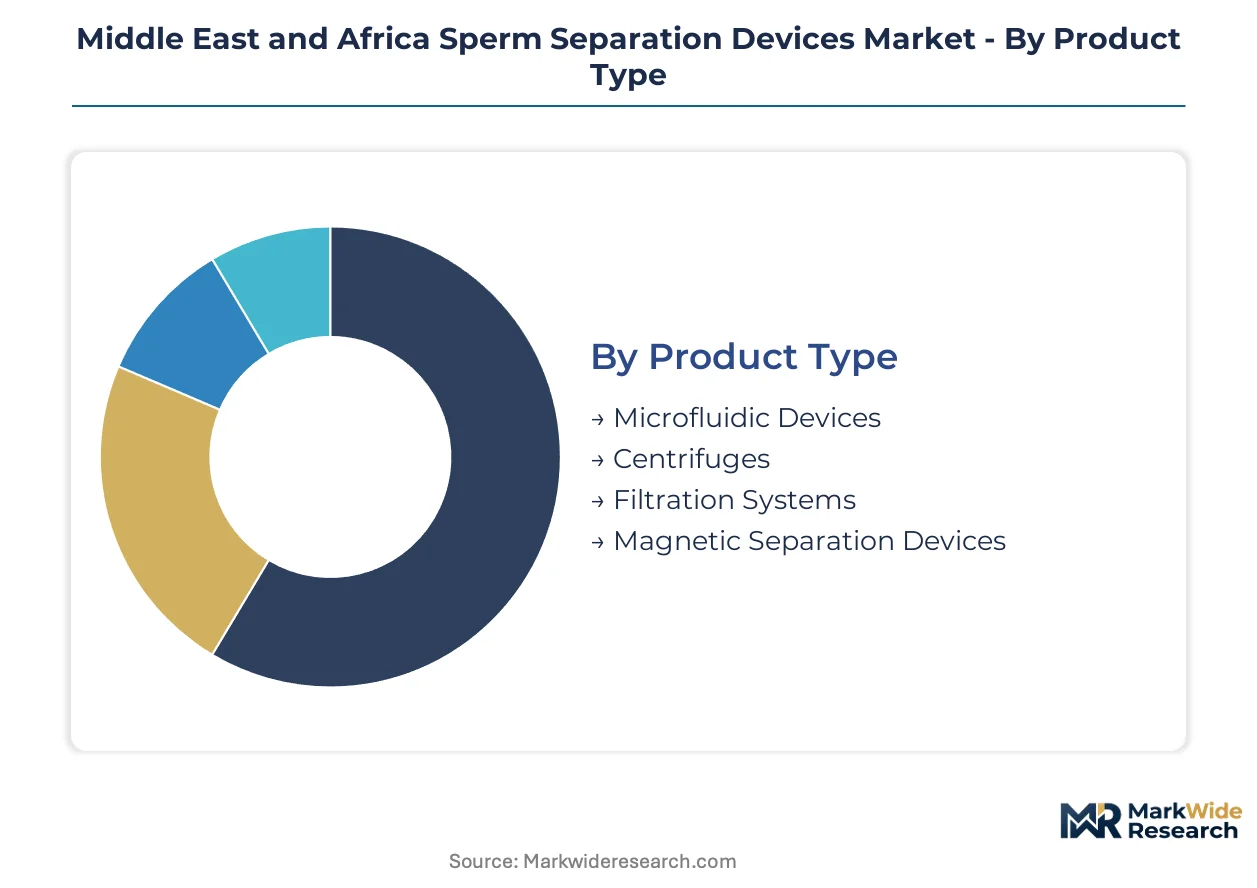
Sperm separation device procurement across the Middle East and Africa fragments sharply by capital intensity and technical sophistication. Cycle times for consumable replenishment outpace equipment replacement by orders of magnitude, concentrating margin capture in recurring revenue streams rather than one-time placements.
Product Type:
Equipment refresh cycles stretch from three years for microfluidic platforms to over a decade for heavy centrifugation workstations, creating divergent cash flow profiles across supplier portfolios.
- Microfluidic Devices:These platforms employ laminar flow channels to isolate motile sperm with minimal oxidative stress. Demand concentrates in Dubai and Riyadh fertility hubs where SAHPRA and SFDA quality standards filter out lower-tier alternatives, though embryologist training bottlenecks constrain deployment velocity in secondary cities.
- Centrifuges:Density gradient centrifugation workstations dominate high-volume hospital laboratories across North Africa. Cairo and Casablanca public health systems stretch replacement cycles across seven to ten years, delaying uptake of chip-based alternatives despite superior DNA integrity outcomes.
- Filtration Systems:Membrane-based separation offers intermediate cost positioning for mid-tier fertility clinics in Johannesburg and Cape Town.
- Magnetic Separation Devices:HLA-compatible sperm selection applications occupy narrow genetic testing niches in Abu Dhabi and Doha specialized centers.
Centrifuges dominate installed base across North African hospital networks. Microfluidic devices are where expansion concentrates in Gulf Cooperation Council urban fertility hubs.
Technology:
Technical differentiation maps directly onto reimbursement tier and regulatory clearance burden, with CE-marked and FDA-cleared protocols commanding premium positioning in formal procurement channels.
- Gradient Centrifugation:This legacy modality achieves 90-95% motile sperm recovery through layered density media separation. Volume leadership persists in price-sensitive Egyptian and Moroccan public laboratories where capital constraints override performance advantages of newer methods.
- Microfluidic Chips:Silicon or polymer substrates exploit sperm motility differentials without centrifugal force. Premium positioning in Dubai Health Authority-certified fertility hubs attracts medical tourism flows from sub-Saharan Africa and South Asia, expanding addressable procedure volumes.
- Swim-up Technique:Simplified migration protocols reduce per-procedure consumable expenditure in Tunisia and Algeria cost-constrained settings.
- Magnetic-Activated Cell Sorting:Antibody-conjugated bead selection enables genetic compatibility screening for specialized preimplantation testing applications.
Gradient centrifugation sustains volume leadership in public hospital procurement. Microfluidic chips are gaining share fastest in private fertility network expansion.
End User:
Customer concentration patterns split between consolidated multi-site fertility chains negotiating group procurement contracts and fragmented hospital laboratories purchasing through distributor intermediaries.
- Fertility Clinics:Specialized reproductive medicine centers in Johannesburg, Riyadh, and Dubai drive premium technology uptake. These facilities prioritize sperm DNA integrity metrics and minimal oxidative stress protocols to sustain embryo viability rates in hot-climate storage conditions.
- Hospitals:General medical center laboratories across the Nile Delta and North African public health systems prioritize equipment durability and low per-procedure cost over technical sophistication.
- Research Laboratories:Academic and institutional research settings in South Africa and the UAE generate demand for protocol flexibility and publication-grade validation data.
- Diagnostic Centers:Standalone andrology testing facilities in Saudi secondary cities are emerging as a volume channel for initial sperm quality assessment before referral.
Hospitals anchor equipment installed base through extended replacement cycles. Fertility clinics concentrate margin expansion through consumable-intensive microfluidic adoption.
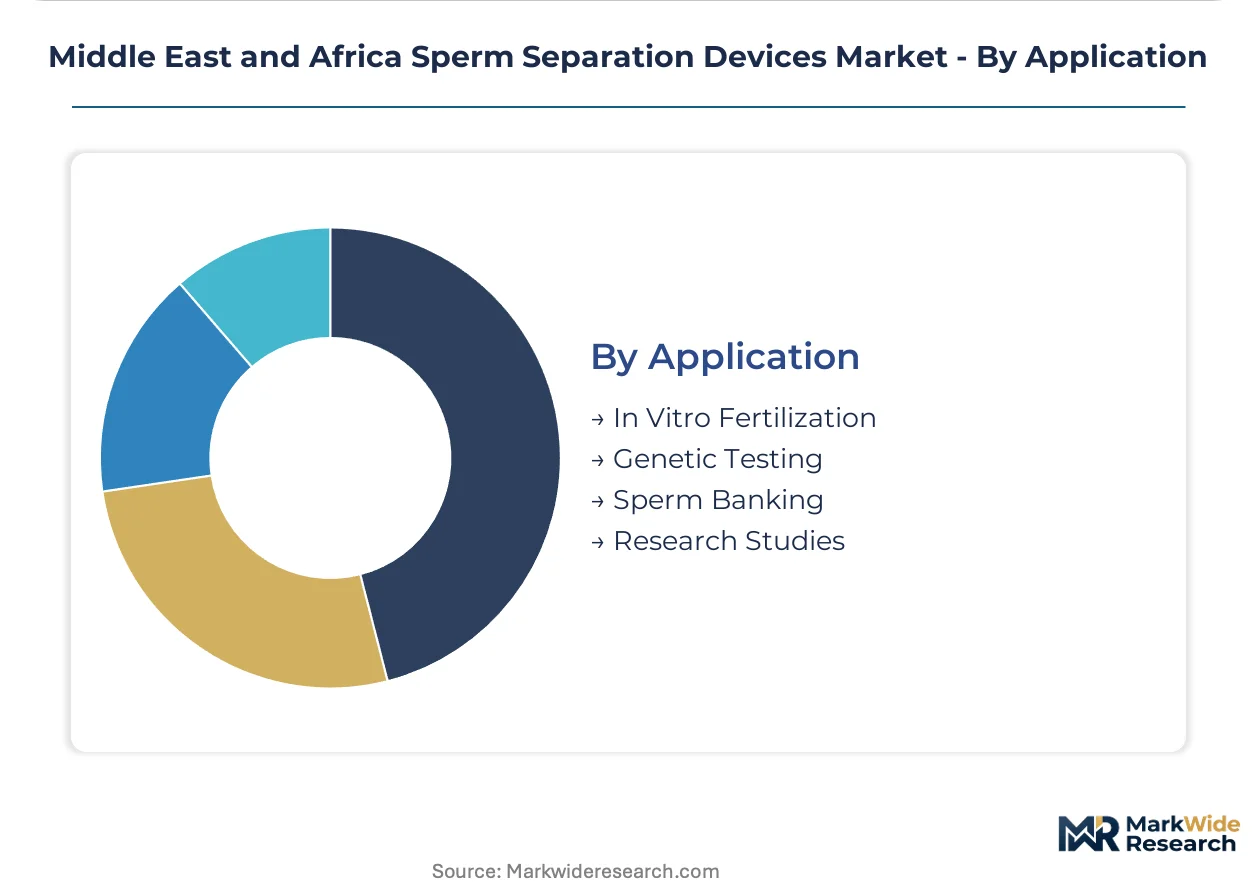
Application:
Clinical outcome requirements vary dramatically by use case, with genetic testing applications demanding HLA compatibility precision that standard IVF preparation protocols cannot deliver.
- In Vitro Fertilization:Standard ART procedures constitute the core demand driver across all geographies. ICSI-compatible sperm preparation dominates workflow design in Gulf state fertility hubs where medical tourism certification requirements elevate quality thresholds.
- Genetic Testing:Preimplantation genetic diagnosis and HLA-matching applications require magnetic-activated selection precision. This technically narrow segment concentrates in Abu Dhabi and Doha specialized centers with advanced embryology capabilities.
- Sperm Banking:Cryopreservation-compatible separation protocols sustain demand in hot-climate storage environments across Saudi Arabia and the UAE.
- Research Studies:Academic and pharmaceutical investigation protocols generate intermittent demand for customizable separation parameters and publication-grade documentation.
In vitro fertilization commands the broadest addressable market. Genetic testing represents the steepest expansion trajectory as preimplantation screening protocols diffuse beyond Gulf specialist centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fertility clinic procurement across the Middle East and Africa clusters in three buyer archetypes: Gulf Cooperation Council private chains prioritizing premium technology, South African hospital networks navigating reimbursement constraints, and North African public laboratories extending equipment lifecycles.
Saudi Arabia
SFDA device registration pathways now mandate CE-marked or FDA-cleared sperm separation platforms for formal procurement access. Riyadh's King Faisal Specialist Hospital anchors demand for microfluidic-compatible protocols that minimize oxidative stress during hot-climate storage. The Eastern Province fertility corridor is expanding ICSI procedure volumes through medical tourism coordination with Gulf neighbors.
United Arab Emirates
Dubai Health Authority fertility hub certification attracts cross-border patients from sub-Saharan Africa and South Asia, elevating quality thresholds for equipped clinics. MOHAP operates parallel federal oversight that converges with emirate-level DHA and Abu Dhabi Department of Health requirements. Dubai's healthcare free zones concentrate cold-chain logistics infrastructure for temperature-sensitive media distribution.
South Africa
SAHPRA enforces stringent IVF consumable quality standards that filter non-compliant suppliers from government and private insurance reimbursement channels. Johannesburg and Cape Town multi-site fertility networks consolidate purchasing through group procurement organizations. The Western Cape academic medical centers generate protocol validation demand for publication-grade separation methods.
Egypt
The national pharmaceutical regulator maintains less stringent import licensing than Gulf Cooperation Council jurisdictions, creating variable quality tiers across the Nile Delta clinic corridor. Cairo public hospital laboratories stretch gradient centrifugation replacement cycles across seven to ten years. Alexandria's private fertility centers are emerging as mid-tier technology adopters between premium Gulf hubs and price-constrained public systems.
Morocco
Casablanca's hospital network prioritizes equipment durability and low per-procedure cost over technical sophistication in sperm preparation workflows. The national health ministry procurement channels favor established centrifugation modalities with proven field service infrastructure. Rabat's emerging private fertility sector is testing swim-up migration protocols as cost-sensitive alternatives to microfluidic platforms.
Middle East and Africa Sperm Separation Devices Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent procurement pathways in the Middle East and Africa sperm separation devices market. Large clinic chains in the UAE and South Africa negotiate annual volume commitments that squeeze distributor margins, while North African public systems purchase through intermediaries with extended payment terms. Three archetypes dominate: multinational life science conglomerates with integrated media portfolios, dedicated reproductive technology specialists with embryology workflow expertise, and regional distributors controlling cold-chain logistics nodes. Competitive moves center on service bundling to defend installed centrifugation bases and direct manufacturer relationships to capture consumable replenishment revenue.
Within the multinational conglomerate tier, FUJIFILM Irvine Scientific and Merck KGaA exemplify players anchoring regional distribution through integrated media and separation consumable portfolios. Hamilton Thorne occupies a position representing North American R&D-driven specialists supplying gradient centrifugation workstations into Gulf fertility networks. Among dedicated reproductive technology players, Vitrolife and Kitazato Corporation sit within the cryopreservation-compatible protocol segment, addressing hot-climate storage conditions that sustain embryo viability rates across Saudi Arabia and the UAE.
| Leading Market Players |
|---|
| Hamilton Thorne |
| FUJIFILM Irvine Scientific |
| Memphasys |
| Kitazato Corporation |
| Trivector Biomed LLP |
| Merck KGaA |
| Nidacon Laboratories AB |
| Cook Medical |
| Vitrolife |
| Others |
Supply & Pricing Matrix
Undercapacity in Dubai-based cold-chain logistics nodes compresses margin capture for temperature-sensitive media, forcing suppliers to bundle service premiums into consumable pricing while Gulf fertility networks absorb higher per-procedure costs. This utilization squeeze propagates downstream, concentrating pricing power among distributors controlling validated shipping lanes while North African public laboratories face extended payment terms that stretch supplier working capital cycles.
Pricing Analysis
Cost-plus contracts with annual CPI indexation dominate procurement between South African group purchasing organizations and multinational consumable suppliers. Pricing stratifies across CE-marked premium tiers, FDA-cleared standard tiers, and non-certified economy tiers, with quality grade and certification level commanding 40-60% spreads. Pricing pressure stems from Johannesburg and Cape Town clinic chains consolidating annual volume commitments in exchange for preferential tiers. Public hospital laboratories across Egypt and Morocco exhibit highest price sensitivity, while Dubai Health Authority-certified fertility hubs prioritize DNA integrity outcomes over per-procedure cost.
Supply Chain Analysis
Upstream silicone wafer and polymer substrate production centers on Germany, Japan, and the United States, with microfluidic chip fabrication drawing from these concentrated semiconductor-grade material sources. Density gradient media formulations rest on bovine serum albumin suppliers in New Zealand and Australia, while cold-chain packaging materials hinge on specialized foam manufacturers in Belgium and the Netherlands. Single-source vulnerability runs through Dubai's Jebel Ali free zone, where temperature-controlled warehousing concentration creates chokepoint exposure for Gulf state clinic networks. Distribution runs through manufacturer-direct relationships for large fertility chains and regional distributor intermediaries for fragmented North African hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory enforcement tiers creates positioning niches for quality-differentiated suppliers, as Egypt's variable import standards and Gulf Cooperation Council harmonization pressures split the addressable market into divergent compliance pathways.
For Market Incumbents: Insulate installed centrifugation bases through service bundling and consumable lock-in contracts with seven-to-ten-year replacement cycle guarantees, countering microfluidic displacement threats in North African public laboratories. Deepen backward integration into cold-chain logistics nodes to defend margin compression from Dubai distribution concentration, while accelerating SAHPRA and SFDA certification investments to filter emerging competitors from formal reimbursement channels. For New Entrants and Emerging Players: Egypt's Nile Delta clinic corridor represents the most penetrable entry point, where less stringent import licensing creates first-mover positioning for quality-tier suppliers willing to navigate variable regulatory enforcement. Secondary cities in Saudi Arabia's Eastern Province and Algeria's coastal fertility networks offer mid-market microfluidic adoption gaps constrained by embryologist training bottlenecks. A direct manufacturer relationship model bypassing distributor margins captures consumable replenishment revenue from consolidating South African group purchasing organizations. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among cryopreservation-compatible protocol specialists serving hot-climate Gulf storage environments, where consumable attachment rates sustain predictable cash flow profiles across replacement cycles. Long-term viability favors acquisition targets with dual CE-marked and FDA-cleared regulatory portfolios that unlock Gulf Cooperation Council procurement channels. Monitor SFDA-MOHAP regulatory harmonization progress as an inflection signal for quality-tier supplier consolidation opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | SFDA recognition of CE-marked devices accelerates Saudi market access for compliant manufacturers. |
| Hospital System Partnership | Multi-site fertility chains in Johannesburg negotiate annual volume commitments that squeeze distributor margins. |
| Software Companion Development | Embryologist training platforms for microfluidic operation address deployment velocity constraints in secondary cities. |
| Reimbursement Strategy | SAHPRA quality standard alignment unlocks South African government and private insurance procurement channels. |
| Geographic Expansion | Dubai Health Authority fertility hub certification attracts cross-border medical tourism from sub-Saharan Africa. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA device registration databases, SAHPRA IVF consumable quality standards, and Dubai Health Authority fertility hub certification records. Primary interviews engaged reproductive endocrinologists, biomedical engineers at Gulf fertility networks, GPO contracts managers in South Africa, and cold-chain logistics operators at Jebel Ali free zone facilities. Secondary validation drew from hospital procurement databases, CE marking directories, and customs trade data for separation media imports. Bottom-up clinic-level procedure volume estimates triangulated against top-down national ART registry aggregates.
Forecast inputs span product type segmentation across microfluidic devices, centrifuges, filtration systems, and magnetic separation platforms; technology differentiation between gradient centrifugation, microfluidic chips, swim-up protocols, and magnetic-activated cell sorting; and end-user splits among fertility clinics, hospitals, research laboratories, and diagnostic centers. CAGRs were derived from procedure volume elasticity to medical tourism flows, regulatory harmonization timelines, and equipment replacement cycle compression patterns across public versus private procurement channels. Modeled inputs include embryologist training pipeline output rates and cold-chain infrastructure expansion capex disclosures.
Practitioners should monitor SFDA-MOHAP regulatory convergence negotiations, Egypt's national pharmaceutical regulator enforcement variability, and Dubai cold-chain capacity utilization rates for early signals of competitive positioning shifts. Forecasts reflect assumptions around Gulf Cooperation Council medical device directive implementation pace and South African group purchasing organization consolidation trajectories. Quarterly review of SAHPRA registration approval timelines and SFDA quality standard updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
China Minimally Invasive Surgery Devices Market
Medical Devices
Electronic Pediatric Nebulizer Market
Medical Devices
Capsulotomy Market
Medical Devices
Spinal Machined Bone Allograft Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
Global Vaginal Speculum Market
Medical Devices
Ligament Stabilizers Market
Medical Devices
Global ECG Cable and ECG Lead Wires Market
Medical Devices
Brazil Cardiac Pacemakers Market
Medical Devices
Global Pathological Microscopes Market
Medical Devices
Next Generation Implants (NGI) Market
Medical Devices
Europe Arthroscopy Devices Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Veterinary Catheters Market
Medical Devices
Intra-Abdominal Pressure Measurement Devices (IPMD) Market
Medical Devices
Global Defibrillators Market