
 North America and Europe Pharmaceutical Stability & Storage Services Market | 2026-2036
North America and Europe Pharmaceutical Stability & Storage Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America and Europe Pharmaceutical Stability & Storage Services Market Analytics
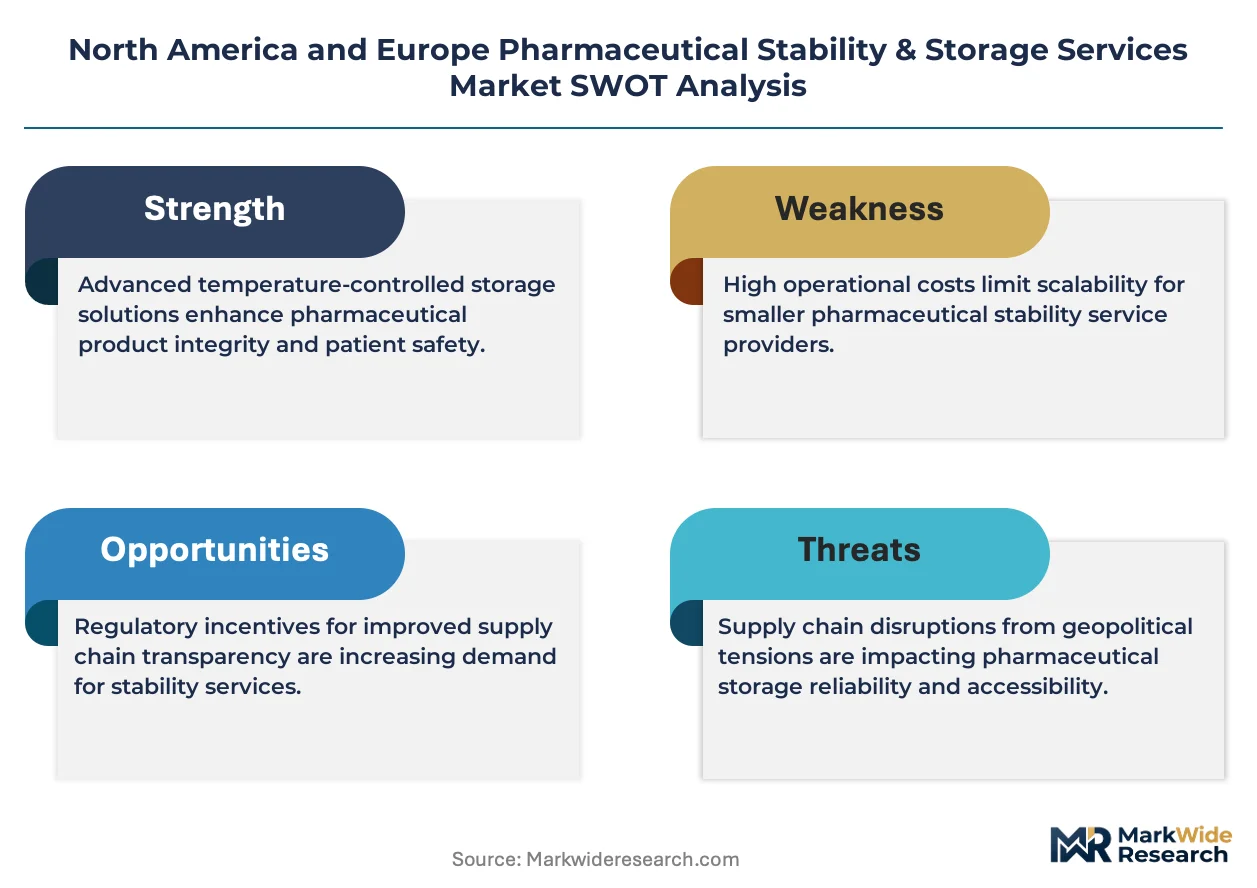
Automated environmental monitoring systems is reconfiguring how pharmaceutical stability programs manage real-time data capture and deviation response across North American and European facilities. Eurofins Scientific leverages its distributed laboratory network to anchor large-scale stability testing contracts with multinational drug sponsors. Catalent, Inc. dominates integrated clinical-to-commercial storage pathways through captive capacity in both the United States and United Kingdom. Almac Group differentiates via specialized cold chain management services that support cell and gene therapy developers with stringent temperature band requirements.
Pharmaceutical stability and storage services encompass controlled-environment holding, accelerated and long-term stability testing, sample retention, and cold chain logistics for drug substances and finished products, typically maintained within validated temperature ranges of 2-8°C, -20°C, -80°C, or cryogenic conditions depending on molecule sensitivity. The primary commercial purpose centers on generating regulatory-compliant data packages that demonstrate product integrity across shelf-life claims for FDA, EMA, and national health authority submissions. Stability testing and cold chain management segments command the deepest margin pools as biologics proliferation drives complexity in protocol design and excursion investigation. Controlled storage services remain the volume foundation, while quality assurance layers around temperature monitoring and validation services are expanding fastest as regulators demand continuous rather than point-in-time compliance evidence.
FDA stability guidance and EMA Good Manufacturing Practice Annex 15 together shape facility qualification standards, forcing service providers to maintain redundant monitoring infrastructure and documented corrective action protocols. The EPA and OSHA frameworks in the United States, alongside REACH chemical safety obligations in Europe, further constrain material selection for storage equipment and facility construction. Stakeholders must monitor how emerging EU AI Act provisions and FDA digital data integrity expectations will reshape electronic record-keeping requirements for distributed stability networks.
Market Dynamics
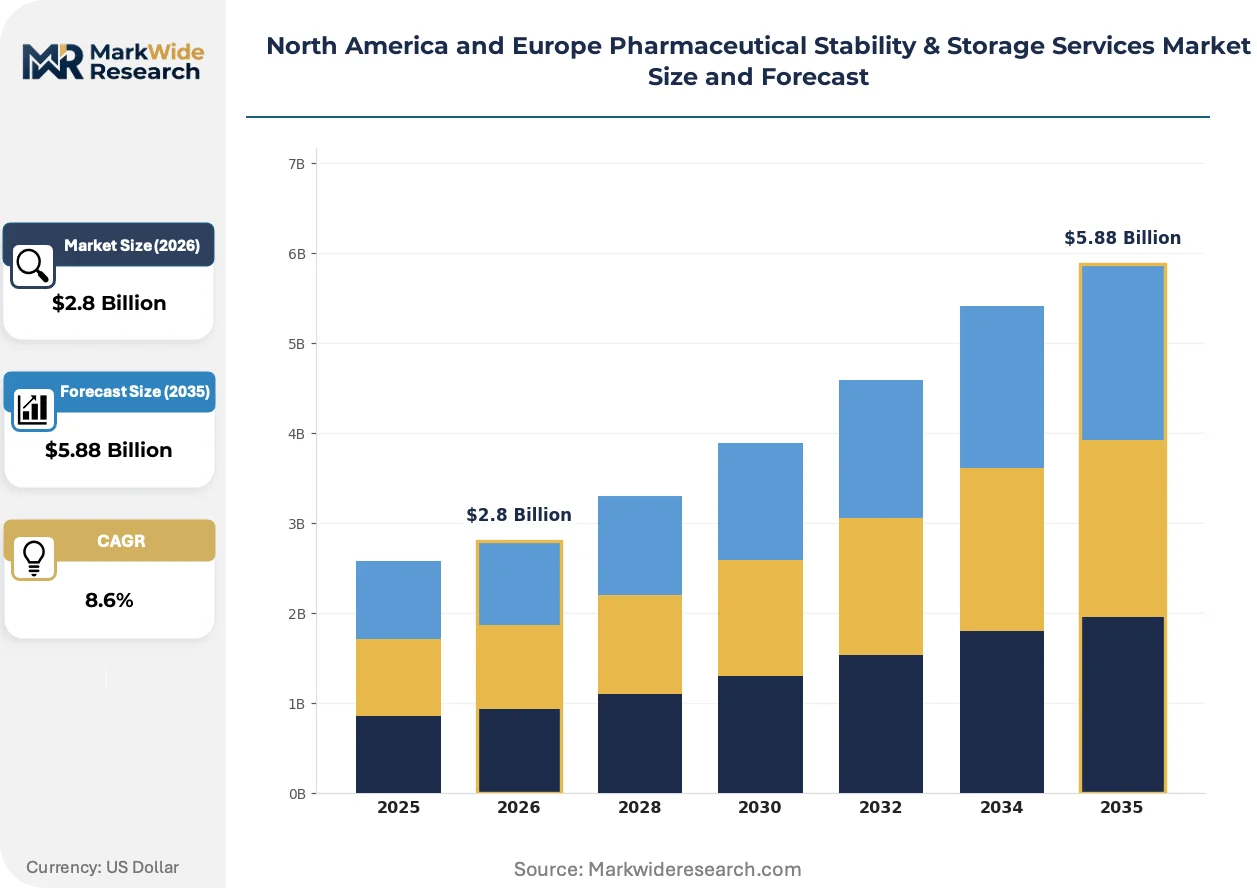
Biologics proliferation is compressing stability protocol timelines while EMA and FDA validation requirements force redundant cold chain infrastructure investments across North American and European facilities.
Growth Catalysts
- EMA Annex 15 tightening:Facility qualification standards now mandate continuous temperature monitoring rather than point-in-time checks, expanding contract demand for validated storage services.
- Cell therapy commercialization:Cryogenic supply chains for CAR-T and gene therapies require specialized -150°C to -196°C infrastructure that developers rarely maintain in-house.
- Rhine-Ruhr cluster concentration:Germany's pharmaceutical manufacturing density creates geographic pull for integrated stability testing and regional distribution services.
Market Restraints
- Redundant monitoring capex:FDA 21 CFR Part 11 compliance requires duplicate sensor networks and backup power systems that inflate facility buildout costs by 40-60%.
- Qualified personnel scarcity:Stability study directors with combined GMP and cold chain logistics expertise command premium wages that compress service provider margins.
- Energy price volatility:Ultra-low temperature storage facilities face input cost swings from European natural gas markets and US electricity grid instability.
Strategic Opportunities
- EU AI Act compliance services:Automated deviation detection algorithms for stability data will require validation documentation, creating advisory revenue streams.
- UK post-Brexit divergence:Separate MHRA registration pathways incentivize dedicated British Isles storage capacity for sponsors seeking regulatory optionality.
- Real-time release testing integration:Converging IoT sensors with statistical process control enables continuous stability verification rather than discrete timepoint testing.
Industry Challenges
- Legacy LIMS integration:Electronic data capture systems from the 2010s lack API connectivity with modern environmental monitoring platforms, forcing costly middleware development.
- Deviation investigation timelines:Temperature excursion root-cause analysis must conclude within 24-48 hours per FDA guidance, straining quality assurance staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America and Europe Pharmaceutical Stability & Storage Services Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.88 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Stability Testing, Controlled Storage, Cold Chain Management, Sample Retention End User: Pharmaceutical Manufacturers, Biotechnology Firms, Research Institutions, Hospitals Storage Type: Warehouse Facilities, Refrigerated Units, Freezer Storage, Ambient Storage Quality Assurance: Temperature Monitoring, Humidity Control, Compliance Audits, Validation Services |
| Companies Covered | Alcami Corporation, Element Materials Technology, Eurofins Scientific, BioLife Solutions, Inc., Almac Group, Intertek Group plc, Lucideon Limited, Q1 Scientific, Catalent, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America and Europe Pharmaceutical Stability & Storage Services Market Evolving Landscape
Automated systems are compressing the gap between deviation occurrence and corrective action across pharmaceutical storage networks. Three forces are reconfiguring how stability data is captured, validated, and transmitted to regulators.
Wireless sensor networks with blockchain-anchored data integrity are digitizing temperature records for FDA submission packages. Large molecule sponsors in Massachusetts and Baden-Württemberg are deploying these systems at commercial scale. The technology is digitizing audit trails that previously required manual transcription and wet-ink signatures.
REACH chemical safety obligations are restricting insulation materials and refrigerants in European cold chain equipment. Equipment manufacturers must reformulate foam compositions and transition to lower-GWP cooling agents. German and Dutch storage providers are absorbing compliance costs through accelerated depreciation schedules.
Biologics developers are unbundling stability testing from integrated CDMO contracts to access specialized temperature-band expertise. Mid-size gene therapy sponsors in North Carolina and Bavaria now source -80°C storage from dedicated logistics firms while retaining formulation services elsewhere. This pattern concentrates most visibly among cell therapy developers with complex multi-site manufacturing footprints.
North America and Europe Pharmaceutical Stability & Storage Services Market Segmentation
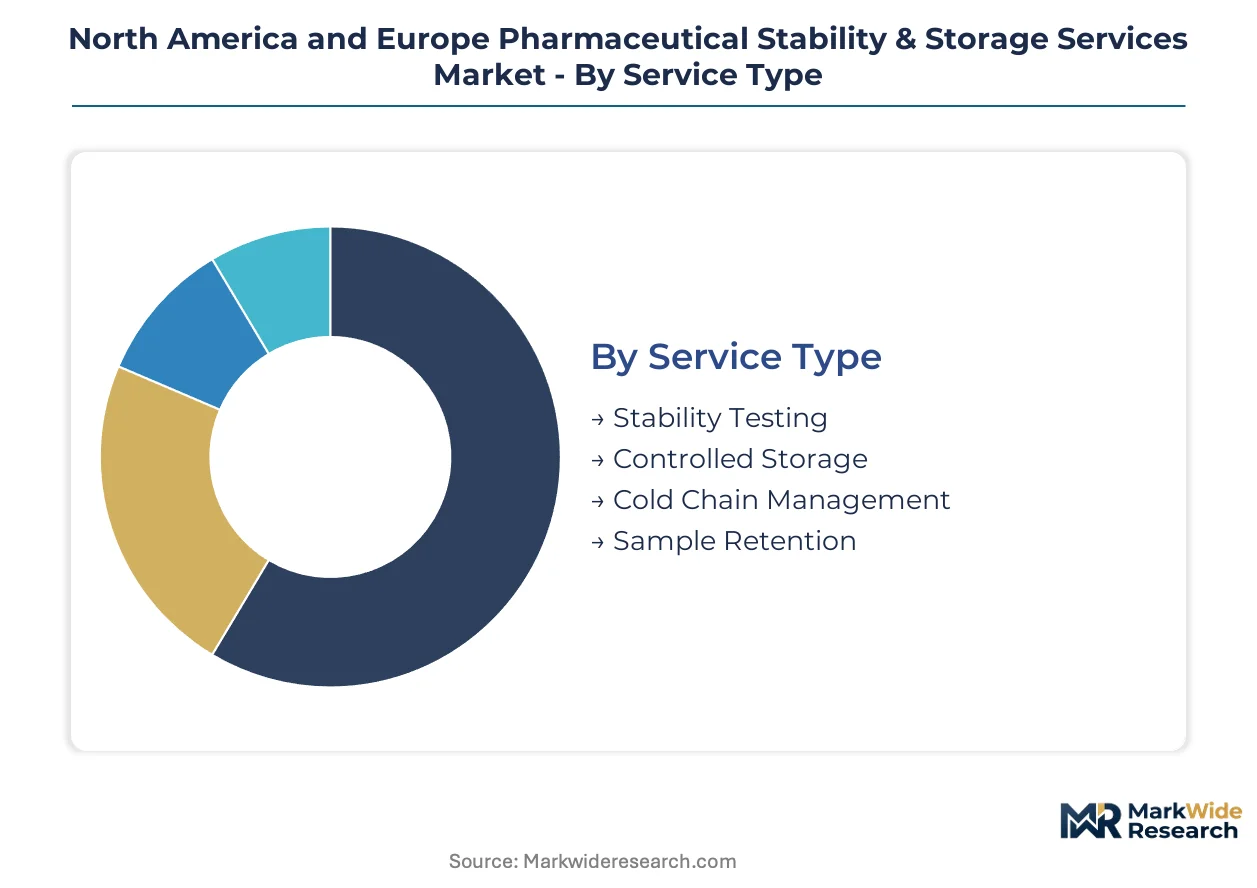
Service differentiation in pharmaceutical stability and storage determines contract value and regulatory defensibility. Segment boundaries increasingly blur as integrated providers bundle testing with logistics to capture biologics workflows.
Service Type:
Cost tier separates commoditized holding from premium protocol design and excursion investigation.
- Stability Testing:Accelerated and long-term studies generate shelf-life data packages for FDA and EMA submissions. Protocol complexity is climbing fastest among cell therapy developers in Massachusetts and Bavaria who require multi-temperature-band studies.
- Controlled Storage:Validated 2-8°C and -20°C environments hold commercial inventory and clinical supplies under continuous monitoring. The Rhine-Ruhr cluster and Northeastern United States concentrate demand from sponsors maintaining regional distribution hubs.
- Cold Chain Management:End-to-end temperature-controlled logistics with deviation response protocols.
- Sample Retention:Archive storage for regulatory inspection and retrospective analysis.
Controlled storage commands the established base. The steepest expansion runs through cold chain management.
End User:
Customer type dictates service bundling preferences and qualification rigor.
- Pharmaceutical Manufacturers:Large molecule sponsors demand integrated stability-to-distribution contracts with redundant monitoring. German and US-based manufacturers are unbundling storage from CDMO relationships to access specialized -80°C and cryogenic infrastructure.
- Biotechnology Firms:Gene therapy developers with limited in-house cold chain expertise outsource entire stability programs. CAR-T sponsors in North Carolina and Baden-Württemberg drive demand for -150°C to -196°C capabilities.
- Research Institutions:Academic and government labs require flexible, small-batch stability support.
- Hospitals:Clinical trial sites and pharmacy operations need point-of-use temperature verification.
Pharmaceutical manufacturers anchor contract volumes. Biotechnology firms are gaining share fastest as cell therapy pipelines mature.
Storage Type:
Facility configuration determines capital intensity and regulatory exposure.
- Warehouse Facilities:Large-scale ambient and controlled-temperature distribution centers serve commercial launch volumes. Buildout costs in the United States and Germany are inflating 40-60% due to FDA 21 CFR Part 11 and EMA Annex 15 redundant sensor requirements.
- Refrigerated Units:Modular 2-8°C systems support clinical trial material flexibility. Demand concentrates around decentralized storage networks for multi-site gene therapy manufacturing.
- Freezer Storage:-20°C and -80°C infrastructure for biologics and mRNA products.
- Ambient Storage:15-25°C holding for stable small molecules and packaging materials.
Warehouse facilities represent the volume foundation. Refrigerated units are climbing the fastest as distributed clinical supply chains proliferate.
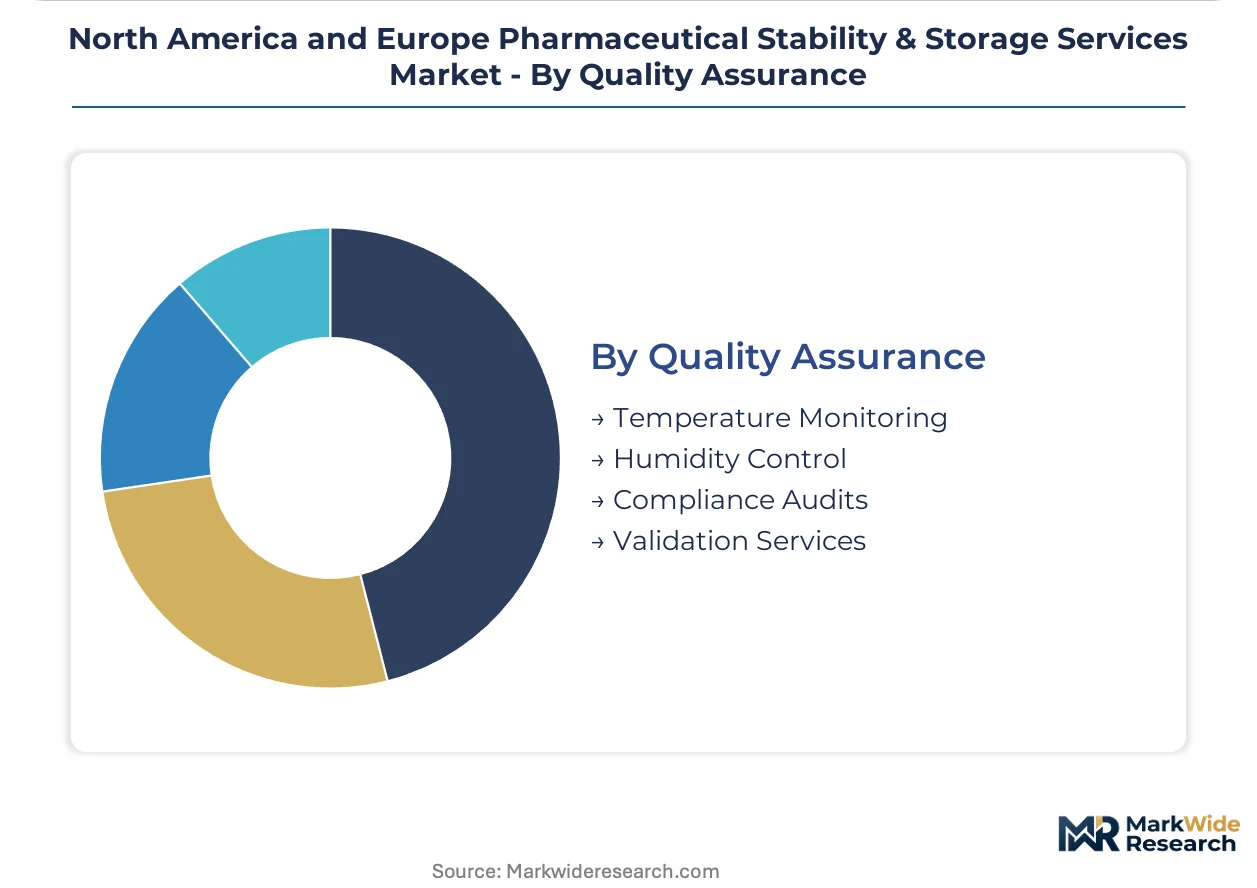
Quality Assurance:
Margin structure varies sharply between monitoring hardware and advisory validation services.
- Temperature Monitoring:Continuous sensor networks with automated alerting and blockchain-anchored data integrity. Sponsors in Massachusetts and the Netherlands are deploying wireless systems to compress deviation response from hours to minutes.
- Humidity Control:Moisture management for moisture-sensitive APIs and finished products. German storage providers face REACH reformulation costs for insulation materials while absorbing compliance through accelerated depreciation.
- Compliance Audits:Third-party qualification and re-qualification of storage infrastructure.
- Validation Services:Protocol design, execution, and documentation for regulatory submission.
Temperature monitoring commands the established base. Validation services are expanding most quickly as EMA and FDA demand continuous rather than point-in-time compliance evidence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in pharmaceutical stability services reflect asymmetric infrastructure development. The United States and Germany generate net service exports through specialized cold chain expertise, while smaller European markets rely on cross-border storage capacity. Regulatory divergence post-Brexit is fragmenting previously integrated supply chains.
United States
Massachusetts and North Carolina biotech clusters drive demand for cryogenic storage infrastructure. FDA 21 CFR Part 11 mandates redundant sensor networks that inflate facility buildout costs. The Greater Boston area concentrates CAR-T developers outsourcing -150°C to -196°C stability programs.
Germany
The Rhine-Ruhr pharmaceutical manufacturing density creates geographic pull for integrated stability testing services. EMA Annex 15 facility qualification standards force continuous temperature monitoring investments. Baden-Württemberg hosts specialized cold chain providers serving cell therapy sponsors.
United Kingdom
Post-Brexit MHRA registration pathways incentivize dedicated British Isles storage capacity. Separate regulatory frameworks from EMA create compliance complexity for multinational sponsors. The Southeast England corridor anchors contract demand from gene therapy developers seeking regulatory optionality.
Netherlands
Rotterdam-Antwerp logistics positioning attracts European distribution hub investments. REACH chemical safety obligations restrict insulation materials in cold chain equipment. Dutch storage providers absorb compliance costs through accelerated depreciation schedules.
Switzerland
Swissmedic alignment with EMA standards maintains regulatory continuity for continental European access. Basel's pharmaceutical manufacturing concentration generates stability testing demand. The country's neutrality attracts sponsors seeking geopolitical risk mitigation in storage location decisions.
North America and Europe Pharmaceutical Stability & Storage Services Market Competitive Landscape
On the supply side, the industry is consolidating around integrated service portfolios that span testing through distribution. Tiered competitive dynamics separate global laboratory networks from regional specialists and single-capacity providers. Three archetypes dominate: distributed laboratory networks, integrated CDMO-storage hybrids, and dedicated cold chain logistics specialists. Capacity expansion in cryogenic infrastructure and strategic partnerships for real-time monitoring technology represent the dominant competitive moves.
Within the distributed laboratory network tier, Eurofins Scientific exemplifies scale-driven coverage across multiple jurisdictions. Catalent, Inc. occupies a position as an integrated hybrid anchoring clinical-to-commercial pathways in both the United States and United Kingdom. Almac Group represents the specialized cold chain archetype with concentrated expertise in cell and gene therapy temperature-band requirements.
| Leading Market Players |
|---|
| Alcami Corporation |
| Element Materials Technology |
| Eurofins Scientific |
| BioLife Solutions, Inc. |
| Almac Group |
| Intertek Group plc |
| Lucideon Limited |
| Q1 Scientific |
| Catalent, Inc. |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoint exposure through FDA 21 CFR Part 11 and EMA Annex 15 compliance costs determines both pricing tier spreads and supply chain shape across pharmaceutical stability services. Redundant sensor infrastructure requirements inflate facility buildout expenditures by 40-60%, compressing margins at the economy tier while premium providers capture validation advisory premiums.
Pricing Analysis
Prior-generation wired monitoring systems trade at commoditized rates against current-generation wireless sensor networks with blockchain-anchored data integrity commanding 25-35% premiums. Three-tier pricing structure across premium, standard, and economy levels separates full-protocol stability testing from controlled storage from basic sample retention. Cost compression in the economy tier is intensifying because German and Dutch providers absorb REACH reformulation costs through accelerated depreciation. Biotechnology firms with cryogenic requirements exhibit lowest price sensitivity, while research institutions negotiate aggressively on small-batch stability support.
Supply Chain Analysis
Dual-use technology controls on cryogenic equipment and automated monitoring systems limit cross-border flows of -150°C to -196°C infrastructure between the United States and Germany. Supply concentration centers on the United States, Germany, and Switzerland for specialized cold chain equipment, with sensor hardware sourcing from the Netherlands and Denmark. Raw material dependencies span medical-grade refrigerants, phase-change materials, and validated insulation foams facing REACH substitution mandates. Single-source vulnerability runs through qualified stability study directors with combined GMP and cold chain logistics expertise. Distribution runs through regional hub-and-spoke configurations anchored in the Northeastern United States and the Rhine-Ruhr cluster.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Interoperability between IoT environmental monitoring platforms and legacy LIMS systems is reconfiguring competitive advantage toward API-native providers. This platform shift rewards sponsors who can compress deviation response from hours to minutes.
For Market Incumbents: Entrench market position through captive cryogenic capacity additions in Massachusetts and Baden-Württemberg where CAR-T developers concentrate. Deepen backward integration into sensor hardware supply through strategic partnerships with Dutch equipment manufacturers. Regulatory divergence between EMA and MHRA post-Brexit threatens integrated European contracts; establish dedicated British Isles qualification pathways to defend against fragmentation. For New Entrants and Emerging Players: Mid-market gene therapy sponsors in North Carolina and Bavaria represent the most penetrable entry point, as these developers unbundle storage from integrated CDMO relationships. Specialized -80°C and cryogenic infrastructure services for cell therapy multi-site manufacturing footprints offer white-space access. Go-to-market execution should emphasize 24-48 hour deviation investigation capabilities with documented corrective action protocols. For Investors and Strategic Acquirers: Regional cold chain specialists with EMA Annex 15 qualification expertise and established relationships with Rhine-Ruhr pharmaceutical manufacturers present attractive acquisition targets. Long-term viability hinges on exposure to biologics proliferation rather than small molecule stability commoditization. Monitor FDA digital data integrity guidance evolution as the inflection signal for electronic record-keeping platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Cryogenic Infrastructure Expansion | Captures CAR-T and gene therapy commercialization demand in Massachusetts and Baden-Württemberg. |
| Real-Time Monitoring Platform Integration | Compresses deviation response timelines through wireless sensor networks with blockchain-anchored data integrity. |
| Regulatory Optionality Capacity | Dedicated British Isles storage addresses post-Brexit MHRA divergence from EMA standards. |
| Legacy LIMS API Development | Middleware connectivity resolves 2010s electronic data capture system obsolescence for continuous compliance. |
| Qualified Personnel Pipeline Investment | Addresses scarcity of stability study directors with combined GMP and cold chain logistics expertise. |
Research Methodology
A standing panel of drug development executives, regulatory affairs leads, quality assurance directors, and cold chain logistics managers provided ongoing calibration across primary interview programs. Secondary validation drew from FDA guidance documents, EMA Annex 15 revisions, ClinicalTrials.gov stability protocol registrations, and REACH chemical safety obligation updates. Bottom-up service provider capacity assessments triangulated against top-down sponsor outsourcing spend estimates.
Scenario-bracketing around regulatory enforcement intensity and biologics pipeline maturation shaped the analytical framework across the analysis window. Segmentation dimensions modeled encompassed service type, end-user category, storage temperature band, and regional regulatory cluster. CAGRs derived from capacity expansion announcements, facility qualification timelines, and sponsor contract award patterns. Cryogenic infrastructure deployment rates and EMA Annex 15 compliance investment cycles served as industry-specific forecast inputs.
Practitioners should monitor FDA digital data integrity guidance finalization and EU AI Act validation documentation requirements for early signals of forecast revision. Forecasts reflect assumptions regarding continued biologics proliferation and stable regulatory enforcement intensity across the projection horizon. Material shifts in European natural gas pricing volatility or qualified personnel wage inflation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Coating Equipment Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
Europe Pharmaceutical Vials Market
Pharmaceutical Equipment
Radiopharmaceutical Synthesizer Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Aseptic Negative Pressure Pharmaceutical Isolators Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market
Pharmaceutical Equipment
Pharmaceutical Hot Melt Extrusion Equipment Market
Pharmaceutical Equipment
Small Molecule CDMO Market
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Drug Infusion System Market
Pharmaceutical Equipment
Pharmaceutical Storage and Material Handling Equipment Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Pharmaceutical Equipment Market