
 Pharmaceutical Refrigerators and Freezers Market | 2026-2036
Pharmaceutical Refrigerators and Freezers Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Refrigerators and Freezers Market Analytics
A widening capability gap between high-capex precision manufacturers and assembly-focused competitors is reorganizing competitive tiers in pharmaceutical cold storage. Thermo Fisher Scientific leverages its integrated life sciences platform to bundle storage with analytical workflows. Eppendorf AG anchors its position through deep specialization in laboratory-grade ultralow freezers for research applications. Haier Biomedical competes on manufacturing scale and cost-optimized production for emerging market hospital networks.
Pharmaceutical refrigerators and freezers are engineered thermal containment systems maintaining precise temperature bands between cryogenic ranges and controlled ambient conditions, typically employing cascade refrigeration or liquid nitrogen backup systems to preserve drug efficacy, vaccine potency, and biological sample integrity. Upright refrigerators dominate hospital pharmacy installations where floor-space efficiency and inventory accessibility matter, while cryogenic technology commands premium positioning in cell therapy and biobank applications where -150°C preservation prevents nucleic acid degradation. Laboratory freezers sustain steady replacement demand from research laboratories, though magnetic refrigeration remains nascent with limited commercial penetration beyond pilot installations.
FDA 21 CFR Part 11, EU GDP guidelines, and WHO PQS prequalification standards collectively mandate continuous temperature monitoring, alarm redundancy, and documented calibration protocols that elevate equipment specifications and exclude uncertified suppliers. The EU MDR and forthcoming FDA modernization rules will tighten traceability requirements for cold-chain equipment used in clinical distribution. Stakeholders must evaluate whether their validation documentation and remote monitoring architectures satisfy the next wave of cross-border pharmaceutical quality audits.
Market Dynamics
Biopharmaceutical cold-chain capacity expansion is compressing replacement cycles for storage equipment as manufacturers race to secure temperature-controlled infrastructure for cell therapies and mRNA platforms. This infrastructure pull is reshaping supplier-customer relationships around validation documentation and remote monitoring architectures rather than hardware specifications alone.
Growth Catalysts
- EU MDR traceability mandates:Medical device regulations now classify cold-storage equipment as critical infrastructure, forcing hospitals and distributors to upgrade to certified systems with continuous data logging capabilities.
- mRNA manufacturing scale-up:Commercial production of lipid nanoparticle formulations requires ultralow freezer capacity at -80°C for raw material stability, creating dedicated demand from contract development organizations.
- WHO PQS prequalification:National immunization programs in low- and middle-income countries must source PQS-certified equipment for Gavi and UNICEF procurement, funneling volume toward validated suppliers.
Market Restraints
- Compressor supply concentration:Precision cascade refrigeration systems depend on specialized hermetic compressors manufactured in Germany and Japan, creating lead time vulnerability for tier-two equipment assemblers.
- EU F-Gas phasedown:Restrictions on hydrofluorocarbon refrigerants are forcing redesign cycles before alternative working fluids achieve equivalent thermodynamic efficiency in cryogenic applications.
- Liquid nitrogen infrastructure gaps:Vapor-phase cryogenic storage below -150°C requires reliable LN2 supply chains that remain underdeveloped outside major metropolitan hospital networks and research clusters.
Strategic Opportunities
- India hospital network modernization:Government health infrastructure programs and private hospital chains are replacing aging cold-chain equipment, creating volume demand for cost-optimized units with local service coverage.
- Cell therapy logistics integration:Autologous CAR-T manufacturing requires cryogenic chain-of-identity tracking from apheresis through infusion, opening equipment-plus-software bundles for specialized logistics providers.
- Magnetic refrigeration convergence:Solid-state cooling based on magnetocaloric materials eliminates compressor maintenance and refrigerant compliance, positioning early commercializers for premium positioning in biobank applications.
Industry Challenges
- Validation engineering talent scarcity:Equipment manufacturers struggle to hire specialists capable of executing IQ/OQ/PQ protocols for FDA 21 CFR Part 11 compliance, extending project timelines for biopharmaceutical customers.
- Legacy BMS integration complexity:New storage units must communicate with existing building management systems through proprietary protocols, forcing custom middleware development for hospital installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Refrigerators and Freezers Market |
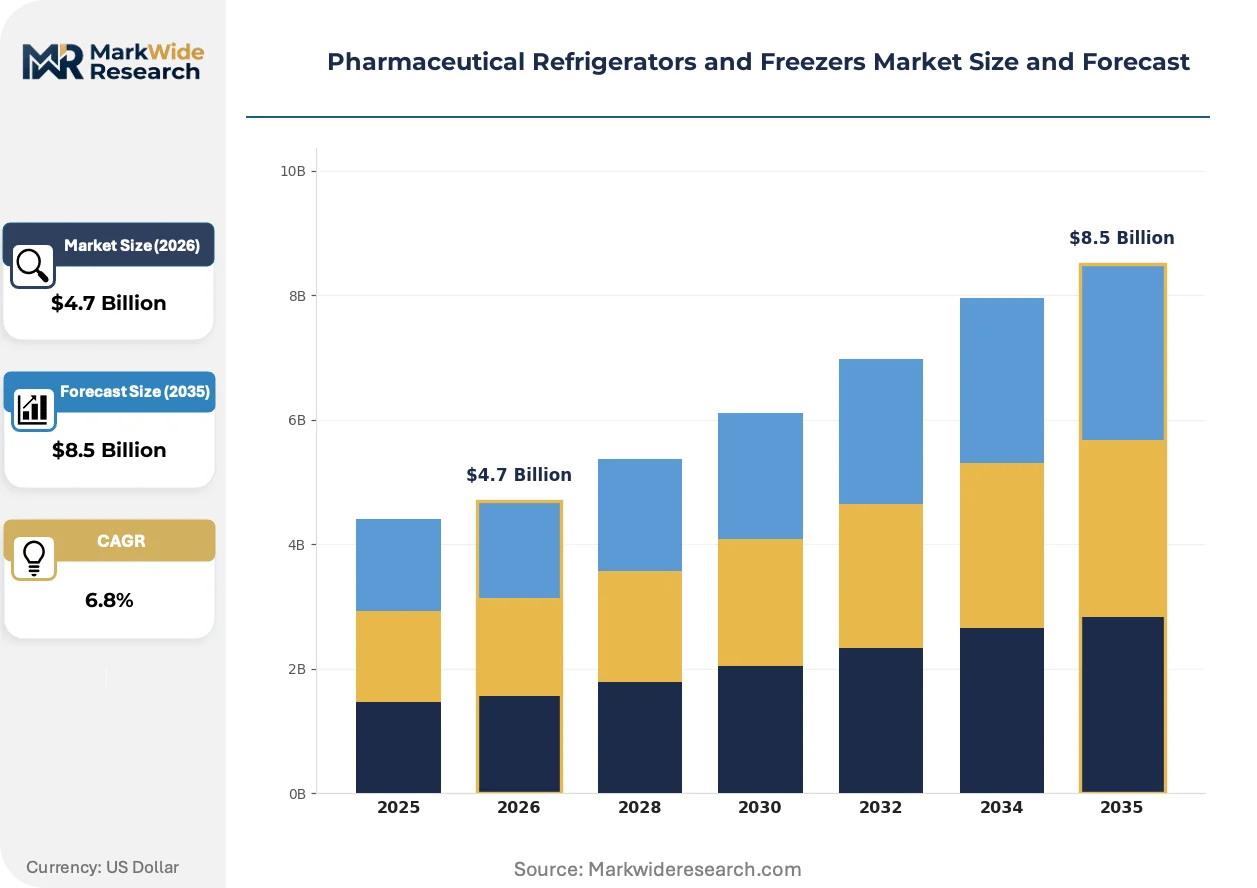
| Market Size in 2026 | $4.7 Billion |
| Market Size in 2035 | $8.5 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Upright Refrigerators, Chest Freezers, Undercounter Refrigerators, Laboratory Freezers End User: Pharmacies, Hospitals, Research Laboratories, Biotechnology Companies Temperature Range: 0°C to 10°C, -1°C to -25°C, -40°C to -86°C, Cryogenic Technology: Conventional Cooling, Thermoelectric, Cryogenic Technology, Magnetic Refrigeration |
| Companies Covered | Haier Biomedical, Eppendorf AG, Thermo Fisher Scientific, Standex International Corporation, B Medical Systems, PHC Corporation, Arctiko A/S, So-Low Environmental Equipment, Helmer Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Refrigerators and Freezers Market Evolving Landscape
Cascade refrigeration architectures are giving way to hybrid thermal management systems as end-users demand energy efficiency alongside temperature uniformity. Equipment differentiation is migrating from hardware specifications toward integrated data integrity and predictive maintenance capabilities.
Magnetic refrigeration is decomposing the traditional compressor-dominated cost structure in ultralow freezer segments. Early adopters at biobanks and cell therapy manufacturers are piloting magnetocaloric units for -80°C applications. This solid-state approach is decomposing maintenance revenue streams for incumbent service organizations while compressing total cost of ownership calculations for capital-intensive research facilities.
EU F-Gas Regulation phasedown schedules are accelerating refrigerant transition timelines for equipment placed on the European market. Manufacturers must certify alternative working fluids for cascade systems before 2030 restrictions take full effect. Biopharmaceutical manufacturers with pan-European footprints are prioritizing equipment with future-proof refrigerant architectures to avoid stranded asset risk.
Service contract unbundling is fragmenting how hospital pharmacies acquire cold storage capability. Large health systems are separating equipment procurement from validation and calibration services, awarding multi-site maintenance to specialized third-party metrology firms. This purchasing pattern is most pronounced in Germany and the United States, where consolidated hospital networks possess sufficient scale to negotiate disaggregated vendor relationships.
Pharmaceutical Refrigerators and Freezers Market Segmentation
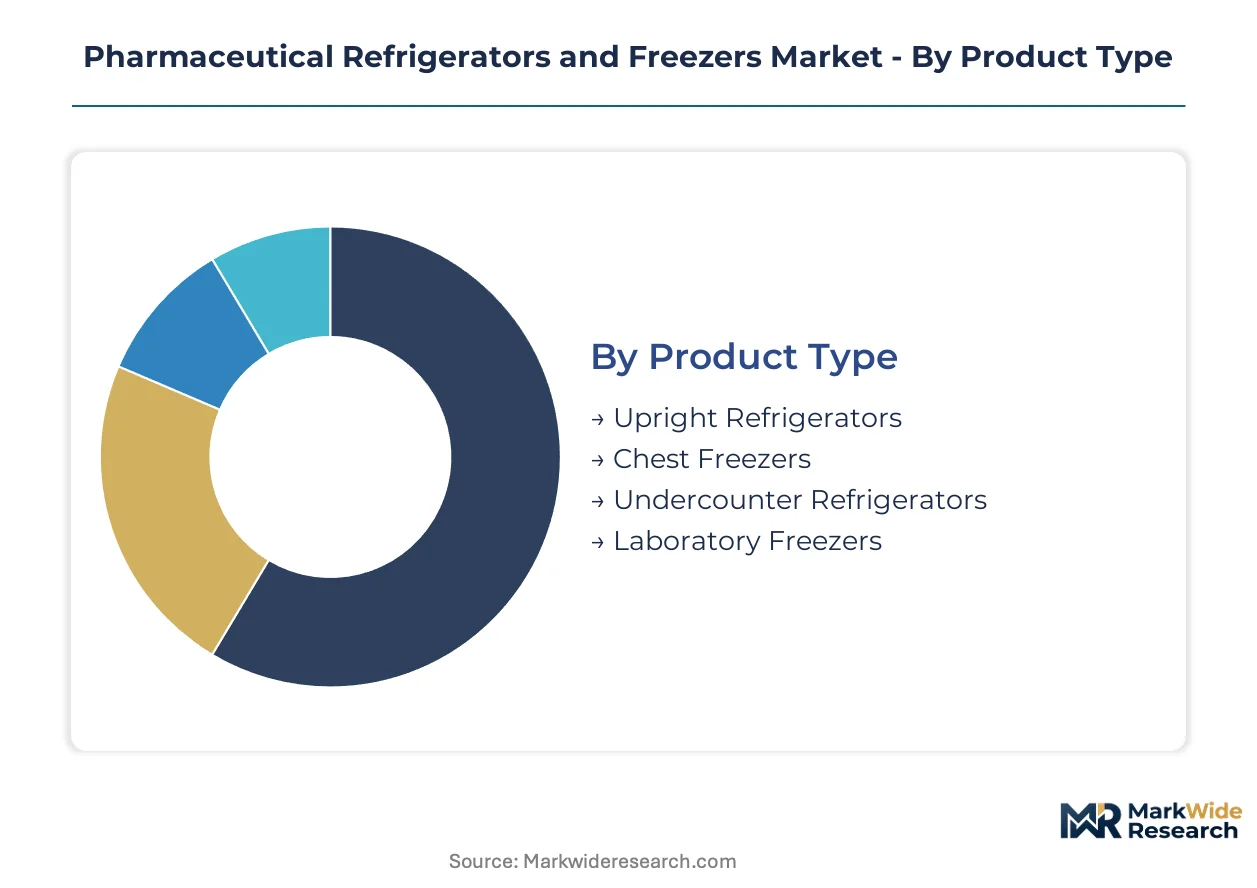
Segmentation in pharmaceutical cold storage reveals how equipment specifications align with distinct validation requirements and procurement channels. Each dimension—product form, end-use setting, thermal specification, and cooling architecture—channels demand through different supplier relationships and compliance pathways.
Product Type:
Hospital pharmacies and retail chains source through divergent fulfillment models, with consolidated health systems favoring multi-site framework agreements while independent pharmacies purchase through distribution intermediaries.
- Upright Refrigerators:Vertical cabinet designs maximize floor-space efficiency in congested pharmacy environments. Hospital networks in Germany and the United States deploy these units for high-turnover vaccine and insulin storage, driven by inventory accessibility requirements and EU MDR traceability mandates for continuous temperature logging.
- Chest Freezers:Horizontal top-opening configurations deliver superior thermal stability during access events. Research biobanks and cell therapy manufacturers prioritize these units for long-term sample preservation, constrained by floor-space limitations in urban laboratory facilities.
- Undercounter Refrigerators:Compact built-in units integrate beneath pharmacy workstations in space-constrained clinical settings. These serve point-of-care medication preparation areas in Japan and South Korea.
- Laboratory Freezers:Purpose-built units with validated alarm systems and redundant cooling circuits. Academic research clusters and CRO facilities drive replacement cycles.
Upright refrigerators dominate installed base. Chest freezers are where expansion concentrates for biobank and cell therapy applications.
End User:
Procurement sophistication varies sharply across customer types, with biotechnology companies negotiating equipment-plus-software bundles while hospital pharmacies separate capital purchases from validation services.
- Pharmacies:Retail and hospital dispensaries require compact units with rapid door-recovery times. Community pharmacy chains in India modernize aging cold-chain infrastructure under government health programs.
- Hospitals:Integrated delivery networks demand enterprise-grade monitoring platforms with building management system integration. These facilities face legacy BMS protocol compatibility challenges.
- Research Laboratories:Academic and government research centers sustain steady replacement demand. Validation documentation for FDA 21 CFR Part 11 compliance extends procurement timelines.
- Biotechnology Companies:Cell therapy and mRNA manufacturers drive premium demand for ultralow and cryogenic systems. These end-users specify chain-of-identity tracking capabilities from apheresis through infusion.
Hospitals anchor volume demand through consolidated procurement. Biotechnology companies represent the steepest expansion trajectory for specialized cryogenic equipment.
Temperature Range:
Specification requirements cascade from ambient-controlled storage through cryogenic preservation, with each band demanding distinct refrigeration architectures and backup system configurations.
- 0°C to 10°C:Standard pharmaceutical refrigeration for vaccines, insulin, and biologics requiring controlled ambient conditions. Hospital pharmacies and primary care clinics across Brazil and Mexico deploy these units under WHO PQS prequalification standards for national immunization programs.
- -1°C to -25°C:Standard freezer range for plasma, enzymes, and diagnostic reagents. Blood banking facilities and clinical laboratories concentrate demand.
- -40°C to -86°C:Ultralow storage for mRNA raw materials, viral vectors, and long-term biological samples. Contract development organizations scale capacity for lipid nanoparticle formulation stability.
- Cryogenic:Vapor-phase liquid nitrogen systems below -150°C for cell therapy, stem cells, and nucleic acid preservation. Infrastructure gaps outside major metropolitan research clusters constrain deployment.
Standard refrigeration dominates installed base. Ultralow and cryogenic ranges are where capacity expansion concentrates for biopharmaceutical manufacturing.
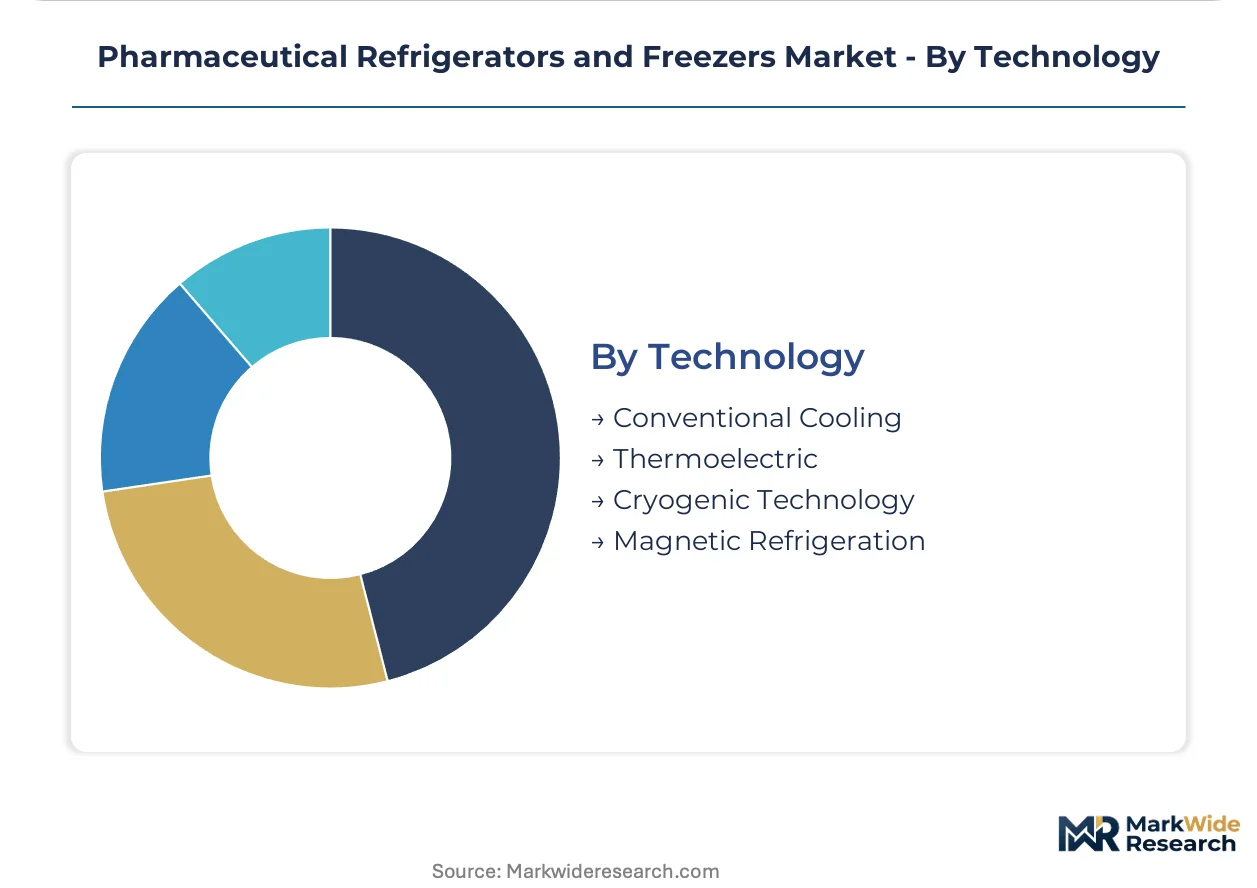
Technology:
Cooling architecture selection involves trade-offs between thermodynamic efficiency, maintenance burden, refrigerant compliance, and capital cost structure.
- Conventional Cooling:Vapor-compression systems with cascade refrigeration for ultralow applications. These units face EU F-Gas Regulation phasedown pressures forcing refrigerant transition timelines before 2030 restrictions.
- Thermoelectric:Solid-state Peltier devices for compact, vibration-sensitive storage. Point-of-care diagnostic manufacturers and small-format pharmacy units favor these for silent operation.
- Cryogenic Technology:Liquid nitrogen vapor-phase or liquid-phase systems for preservation below -150°C. Cell therapy logistics providers integrate these with automated chain-of-identity tracking.
- Magnetic Refrigeration:Magnetocaloric solid-state cooling eliminating compressors and refrigerants. Early commercial pilots at biobanks target maintenance cost reduction and regulatory future-proofing.
Conventional cooling dominates installed base. Magnetic refrigeration is where technology investment concentrates for next-generation biobank deployments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement contexts. Hospital networks in mature markets prioritize validation documentation over capital cost, while emerging market buyers face hard budget constraints that favor locally serviceable equipment.
United States
Consolidated hospital systems drive multi-site framework agreements for enterprise-grade monitoring platforms. FDA 21 CFR Part 11 compliance requirements extend procurement timelines for biopharmaceutical manufacturers. The Greater Boston research cluster sustains replacement demand from cell therapy developers and academic medical centers.
Germany
Pharmaceutical production clusters around Frankfurt and Ludwigshafen compress replacement cycles for validated storage systems. EU MDR traceability mandates classify cold-storage equipment as critical infrastructure requiring continuous data logging. The country's specialized compressor manufacturing base creates supply concentration for precision cascade refrigeration systems.
India
Government health infrastructure programs and private hospital chains modernize aging cold-chain equipment under cost constraints. CDSCO quality guidelines for pharmaceutical storage tighten validation requirements for imported equipment. Maharashtra and Karnataka host expanding biopharma manufacturing zones that drive demand for mid-tier validated units.
Japan
Point-of-care medication preparation areas in urban hospitals favor compact undercounter configurations. METI energy efficiency standards accelerate replacement of aging vapor-compression systems. The Kansai region's diagnostic reagent manufacturers sustain steady demand for laboratory-grade freezer capacity.
Brazil
National immunization programs under WHO PQS prequalification standards funnel procurement toward certified suppliers. ANVISA pharmaceutical distribution regulations mandate temperature monitoring for vaccine storage networks. São Paulo's hospital pharmacy consolidation creates volume demand for upright refrigerator configurations.
Pharmaceutical Refrigerators and Freezers Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in pharmaceutical cold storage. Integrated life sciences platforms bundle storage hardware with analytical workflows and validation services. Specialist manufacturers anchor positions through deep ultralow freezer expertise or manufacturing scale. Dominant competitive moves include portfolio diversification into remote monitoring architectures and strategic partnerships for refrigerant transition compliance.
Among integrated platform providers, Thermo Fisher Scientific exemplifies the bundled hardware-plus-software archetype. Eppendorf AG and Haier Biomedical occupy distinct specialist positions—one anchored in laboratory-grade precision manufacturing, the other in cost-optimized production scale for emerging market networks. These three represent how competitive positioning diverges across validation sophistication, geographic reach, and capital structure.
| Leading Market Players |
|---|
| Haier Biomedical |
| Eppendorf AG |
| Thermo Fisher Scientific |
| Standex International Corporation |
| B Medical Systems |
| PHC Corporation |
| Arctiko A/S |
| So-Low Environmental Equipment |
| Helmer Scientific |
| Others |
Value Network & Pricing Analysis
Compressor manufacturing scale in Germany and Japan anchors cost structures for precision cascade refrigeration systems, concentrating supply-side leverage among specialized hermetic compressor producers while elevating price floors for tier-two equipment assemblers facing extended lead times. This concentration feeds into buyer procurement patterns where consolidated hospital networks separate capital equipment purchases from validation services, fragmenting traditional bundled pricing models.
Pricing Analysis
Service contract revenue and multi-year calibration agreements drive lifetime value capture for equipment manufacturers, with three-tier pricing structure across premium, standard, and economy levels separating validated ultralow systems from basic hospital pharmacy units. Price differentiation rests on FDA 21 CFR Part 11 certification grade and EU MDR traceability compliance, with biotechnology companies showing least price sensitivity for cryogenic chain-of-identity systems while Indian government health programs face hard budget constraints. Cost compression in mid-tier laboratory freezers is intensifying because emerging market buyers prioritize locally serviceable units over premium validation documentation.
Supply Chain Analysis
German and Japanese compressor manufacturing clusters create single-source vulnerability for precision hermetic components used in cascade refrigeration architectures, with vapor-compression systems drawing from specialized steel alloys and electronic control modules. Distribution runs through consolidated health system procurement offices in the United States and Germany alongside distribution intermediaries serving independent pharmacies in India and Brazil. Regulatory restriction from EU F-Gas phasedown schedules forces refrigerant transition timelines before alternative working fluids achieve equivalent thermodynamic efficiency.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pharmaceutical cold storage is entering a cyclical upswing driven by biopharmaceutical manufacturing capacity expansion for mRNA and cell therapy platforms, compressing replacement cycles and elevating validation service demand.
For Market Incumbents: Shield installed base relationships by embedding predictive maintenance architectures that raise switching costs for hospital networks, while securing backward integration into compressor supply through long-term offtake agreements with German and Japanese manufacturers to mitigate lead time vulnerability from emerging Asian competitors. For New Entrants and Emerging Players: Anchor in India's hospital network modernization wave by offering cost-optimized units with localized service coverage, targeting Maharashtra and Karnataka biopharma zones with CDSCO-compliant validation documentation bundled through domestic distribution partnerships rather than direct enterprise sales. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated platform providers combining hardware with remote monitoring software, positioning specialized metrology service firms and magnetic refrigeration technology developers as attractive acquisition targets; watch for FDA modernization rule implementation as inflection indicator for validation documentation demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Transition Compliance | EU F-Gas Regulation mandates alternative working fluid certification before 2030 restrictions strand conventional cascade assets. |
| Remote Monitoring Platform Integration | FDA 21 CFR Part 11 compliance requirements elevate enterprise-grade data logging capabilities above hardware specifications. |
| Cell Therapy Logistics Partnership | Autologous CAR-T manufacturing requires cryogenic chain-of-identity tracking from apheresis through infusion. |
| Magnetic Refrigeration Commercialization | Magnetocaloric solid-state cooling eliminates compressor maintenance and refrigerant compliance for biobank applications. |
| India Local Service Coverage Expansion | CDSCO quality guidelines and government health infrastructure programs create volume demand for validated mid-tier units. |
Research Methodology
Operator-level perspectives from biomedical engineers, hospital procurement managers, GPO contracts managers, and regulatory affairs specialists anchored the qualitative base, combining structured primary interviews with secondary validation from FDA filings, EMA submissions, hospital procurement databases, and WHO PQS prequalification records. Bottom-up equipment shipment analysis and top-down biopharmaceutical manufacturing capacity expansion assessment provided cross-verification.
Sensitivity analysis across temperature range, end-user sophistication, and cooling architecture dimensions shaped the analytical framework over the projection horizon, with CAGRs derived from replacement cycle compression and cold-chain capacity build-out trajectories. Modeled inputs included mRNA manufacturing scale-up rates, EU MDR implementation timelines, and magnetic refrigeration pilot adoption curves.
Decision-makers should treat outputs as directional under base assumptions of sustained biologics pipeline growth and regulatory tightening; material deviation in compressor supply availability or refrigerant transition feasibility would warrant model refresh. Practitioners should keep alternative scenarios live as EU F-Gas phasedown enforcement and FDA modernization rule finalization evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Pharmaceutical Cleaning Validation Market
Pharmaceutical Equipment
Pharmerging Contract Manufacturing Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Equipment Testing Market
Pharmaceutical Equipment
Global Pharmaceutical Granulation Equipment Market
Pharmaceutical Equipment
Inhalation CDMO Market
Pharmaceutical Equipment
Asia-Pacific CDMO Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
mRNA Vaccine Formulation Stability and Stress Test Systems Market
Pharmaceutical Equipment
North America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Automated Radiosynthesis Modules Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Serum Vials Market
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Global Rotary Tablet Press Market