
 Malaysia Pharmacy Automation Market | 2026-2036
Malaysia Pharmacy Automation Market Size, Share, and Industry Trends Forecast 2026-2036
Malaysia Pharmacy Automation Market Foresight
A widening capital-intensity divergence between integrated platform vendors and point-solution suppliers is rotating competitive dynamics toward full-stack providers. Omnicell, Inc. leverages its end-to-end automation architecture to anchor large hospital contracts in Penang and Kuala Lumpur. Becton, Dickinson and Company sustains R&D intensity across barcode-enabled dispensing workflows. Swisslog Healthcare competes through robotics specialization in high-throughput central pharmacy installations.
Pharmacy automation encompasses electromechanical systems, software platforms, and robotic modules engineered to dispense, package, verify, and track medications with precision measured in single-dose accuracy. These systems integrate barcode scanning, weight verification, and image recognition to eliminate manual dispensing errors in high-volume clinical settings. Automated dispensing systems dominate current procurement budgets as hospital pharmacies prioritize patient safety infrastructure, while AI-based automation represents the fastest-expanding technology segment as Malaysian facilities pilot predictive inventory algorithms. Cloud-based solutions are capturing margin pools through subscription recurring revenue models that reduce upfront capital barriers for mid-sized retail chains.
Malaysia's Medical Device Authority enforces registration and quality standards under the Medical Device Act, shaping product compliance requirements for imported automation equipment. The Ministry of Health's pharmacy practice guidelines and the country's national digital health blueprint are accelerating standards for traceability and electronic prescription integration. Stakeholders must monitor how impending updates to medical device classification rules reshape market access timelines for robotics and software platforms.
Market Dynamics
Hospital pharmacy consolidation across the Klang Valley corridor is concentrating procurement authority into fewer decision-makers, amplifying contract scale and tilting vendor selection toward integrated platform architectures over modular point solutions.
Growth Catalysts
- Medical Device Act Registration Streamlining:Malaysia's Medical Device Authority has compressed approval timelines for Class B and C automation equipment, reducing market entry barriers for robotic dispensing systems.
- Private Hospital Infrastructure Modernization:Chains operating in Penang and Kuala Lumpur are mandating barcode-enabled medication verification as standard procurement specifications.
- AI-Enabled Predictive Inventory:Machine learning algorithms for stock optimization are penetrating tertiary hospital central pharmacies, reducing waste from expired pharmaceuticals.
Market Restraints
- Import Dependency for Precision Components:Servo motors and optical sensors rely on concentrated East Asian supply chains, exposing Malaysian installers to lead time volatility.
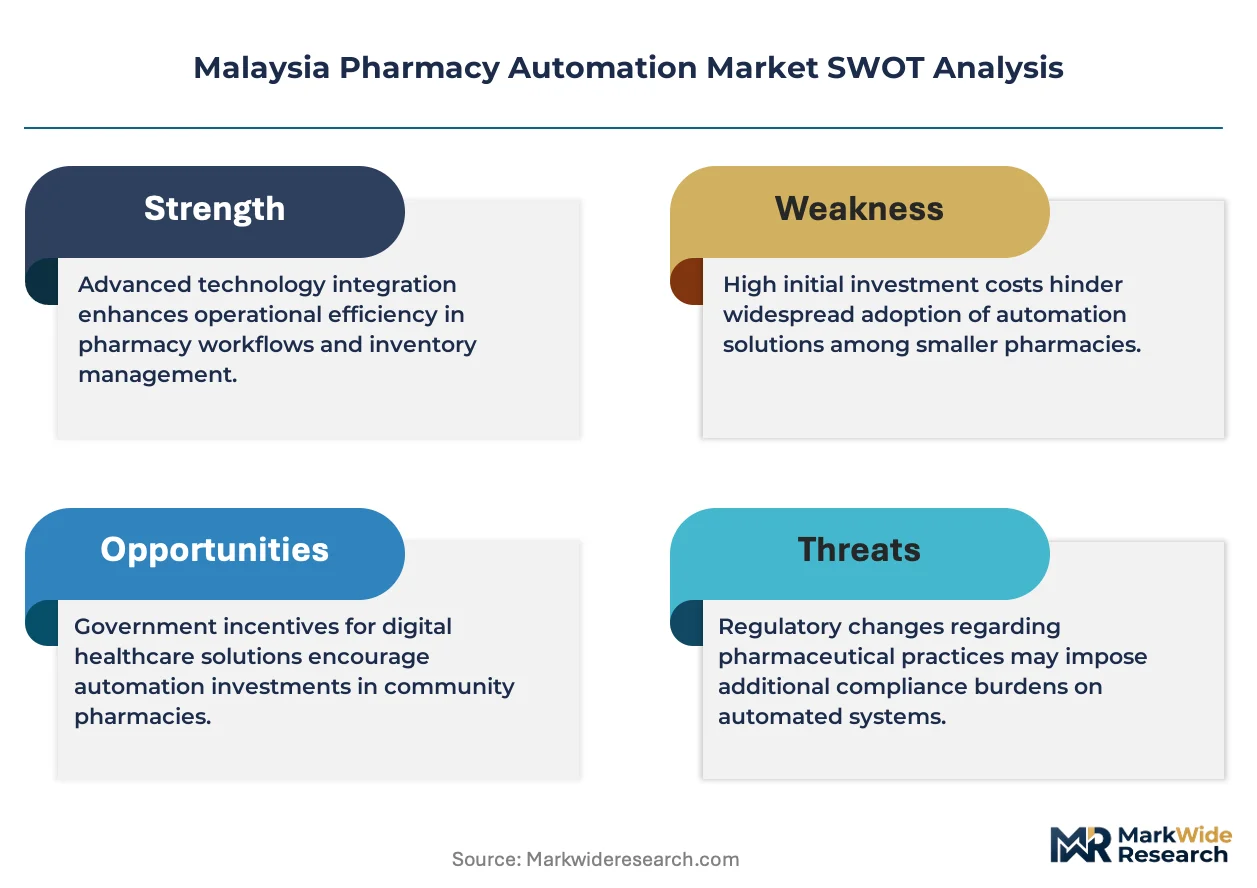
- Medical Device Classification Uncertainty:Pending MDA rule updates create hesitation in robotics and software platform investment cycles.
- High Capital Intensity of Central Pharmacy Robots:Unit economics favor institutions with annual dispensing volumes exceeding 500,000 doses, excluding smaller regional hospitals.
Strategic Opportunities
- Cloud-Based Subscription Models:Mid-sized retail pharmacy chains in Johor Bahru and Ipoh are adopting software-as-a-service inventory management, bypassing upfront hardware expenditure.
- National Digital Health Blueprint Integration:Electronic prescription interoperability mandates are creating pull-through demand for automated dispensing cabinets with native EMR connectivity.
- Robotics-Workflow Convergence:Combination of autonomous mobile robots for medication transport with dispensing automation is opening greenfield installations in new hospital constructions.
Industry Challenges
- Biomedical Engineering Talent Scarcity:Maintenance of electromechanical systems requires hybrid skill sets spanning robotics, pharmacy operations, and MDA compliance documentation.
- Legacy System Integration Complexity:Older hospital information systems in secondary care facilities lack API architectures, forcing expensive middleware development for automation connectivity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Malaysia Pharmacy Automation Market |
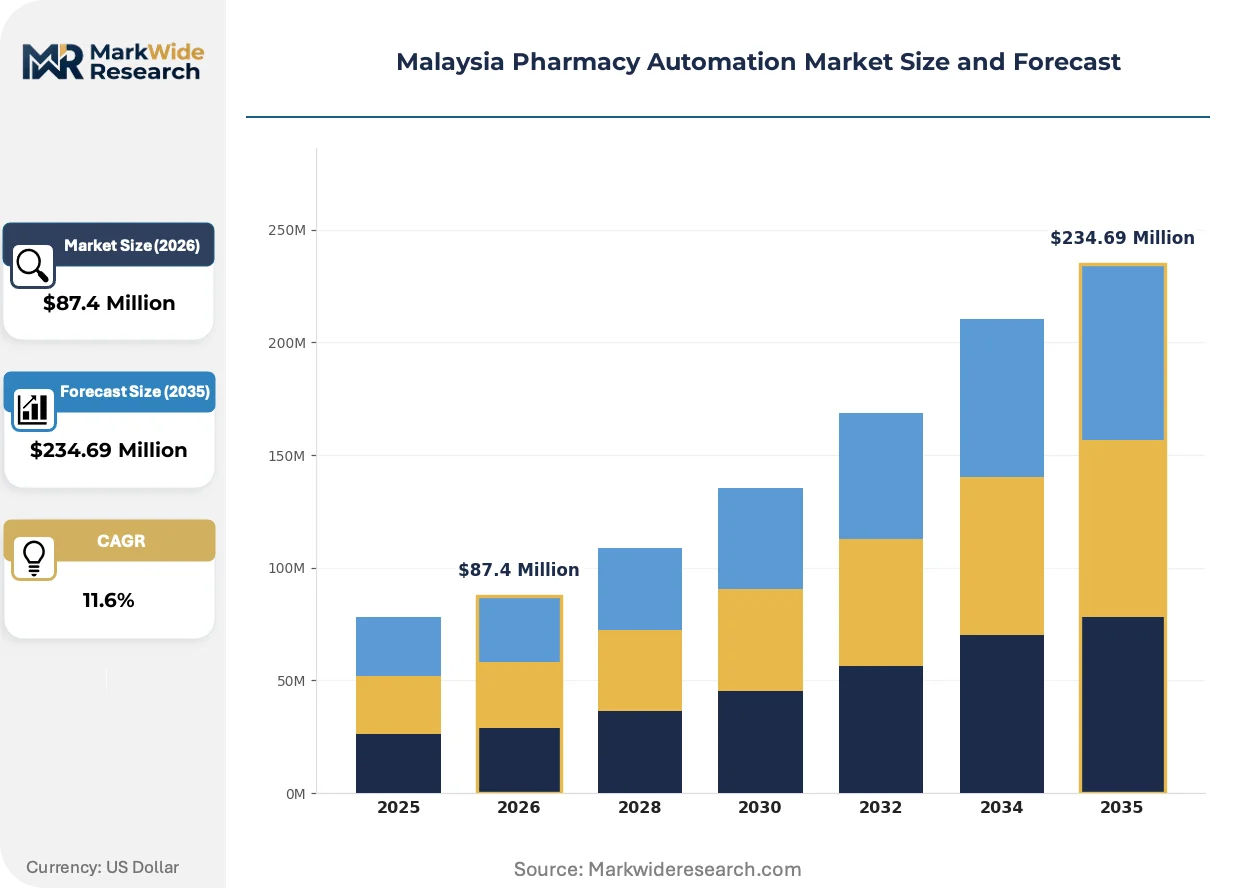
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $234.69 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Dispensing Systems, Robotics, Software Solutions, Inventory Management Tools End User: Retail Pharmacies, Hospital Pharmacies, Long-term Care Facilities, Clinic Pharmacies Technology: Barcode Systems, RFID Technology, AI-based Automation, Cloud-based Solutions Installation Type: On-premise Solutions, Cloud-hosted Systems, Hybrid Installations, Managed Services |
| Companies Covered | Omnicell, Inc., Becton, Dickinson and Company, Baxter International Inc., Capsa Healthcare, McKesson Corporation, Swisslog Healthcare, Yuyama Co., Ltd., ScriptPro LLC, Rxsafe LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Malaysia Pharmacy Automation Market Shifts & Advancements
Automation architecture decisions in Malaysian hospital pharmacies are pivoting from standalone dispensing units toward orchestrated ecosystems where hardware, software, and data layers interoperate seamlessly.
Automated dispensing cabinets with integrated biometric authentication and real-time inventory tracking are displacing traditional manual vault systems in high-acuity wards. Private hospital chains in Kuala Lumpur are deploying these units at replacement cycles of 18-24 months, compressing legacy equipment amortization schedules and reshaping vendor revenue recognition toward recurring software licensing.
Malaysia's Medical Device Authority is tightening traceability requirements under evolving Medical Device Act guidelines, compelling automation suppliers to embed unique device identification capabilities directly into dispensing hardware. This regulatory pressure is accelerating retrofit demand for older installations while disadvantaging importers without localized technical support infrastructure.
Consolidated procurement through group purchasing organizations is displacing hospital-level vendor negotiations across the Klang Valley and Penang Island. These buying collectives are unbundling after-sales service contracts from hardware acquisition, creating transparent pricing benchmarks and compressing margins for distributors lacking direct manufacturer relationships.
Malaysia Pharmacy Automation Market Segmentation
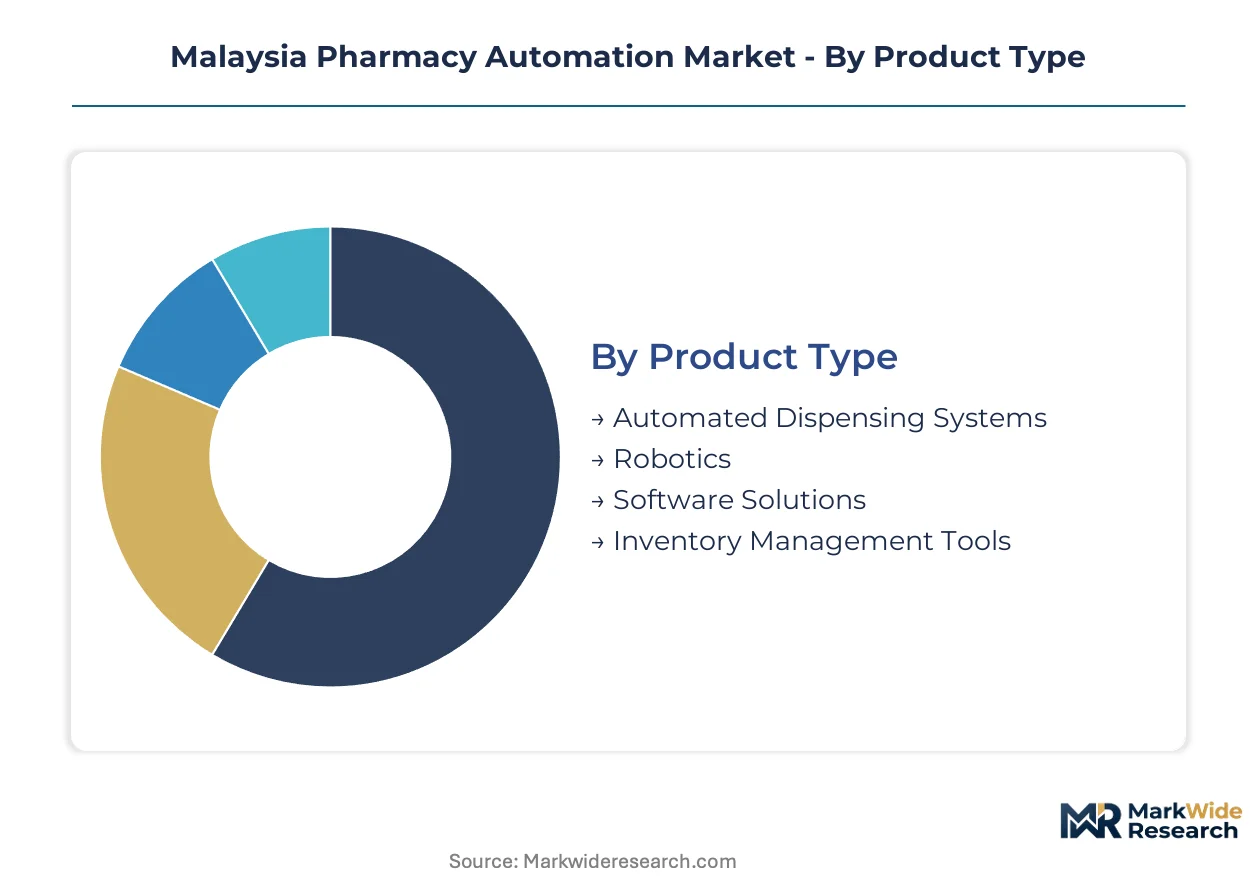
Segmentation in Malaysia's pharmacy automation market reveals distinct procurement patterns across product architectures and deployment models. Channel dynamics vary sharply between capital-intensive hospital installations and subscription-driven retail pharmacy adoption.
Product Type:
Automated dispensing systems flow through direct manufacturer-hospital contracts, while software and inventory tools reach retail chains via distributor networks and SaaS marketplaces.
- Automated Dispensing Systems:Electromechanical cabinets with biometric authentication and real-time inventory tracking dominate hospital pharmacy capital budgets in Kuala Lumpur and Penang. Klang Valley private hospital chains are mandating barcode-enabled verification as standard procurement specifications, compressing replacement cycles to 18-24 months.
- Robotics:High-throughput central pharmacy robots integrate servo-driven dispensing arms with weight verification modules for single-dose accuracy. Unit economics favor institutions exceeding 500,000 annual doses, concentrating demand in tertiary facilities across Selangor and Johor.
- Software Solutions:Middleware platforms enabling EMR connectivity and electronic prescription interoperability.
- Inventory Management Tools:Predictive algorithms for stock optimization and expiry reduction.
By volume, automated dispensing systems lead. By growth pace, software solutions are climbing the fastest.
End User:
Customer scale determines solution architecture—enterprise hospitals demand integrated platforms while smaller facilities prioritize modular point solutions.
- Hospital Pharmacies:Consolidated procurement authority across Klang Valley corridor concentrates contract scale into integrated automation architectures. Malaysia's Medical Device Authority registration requirements under the Medical Device Act shape compliance documentation for imported electromechanical systems.
- Retail Pharmacies:Mid-sized chains in Johor Bahru and Ipoh are bypassing upfront hardware expenditure through cloud-based subscription models for inventory management.
- Long-term Care Facilities:Medication adherence packaging and unit-dose dispensing for resident populations.
- Clinic Pharmacies:Compact dispensing units serving outpatient prescription volumes.
Hospital pharmacies command the highest contract values. Retail pharmacies are expanding most quickly as SaaS penetration accelerates.
Technology:
Technology selection tracks regulatory pressure and data infrastructure maturity across Malaysian healthcare facilities.
- Barcode Systems:Standardized medication verification workflows integrated with hospital information systems. Private hospital infrastructure modernization mandates are embedding barcode-enabled dispensing as baseline procurement specifications.
- AI-based Automation:Machine learning algorithms for predictive inventory and demand forecasting are penetrating tertiary hospital central pharmacies, reducing pharmaceutical waste from expired stock.
- RFID Technology:Real-time location tracking for high-value pharmaceuticals and controlled substances.
- Cloud-based Solutions:Subscription recurring revenue models reducing capital barriers for mid-sized retail chains.
Barcode systems maintain installed base dominance. AI-based automation shows the steepest expansion trajectory.
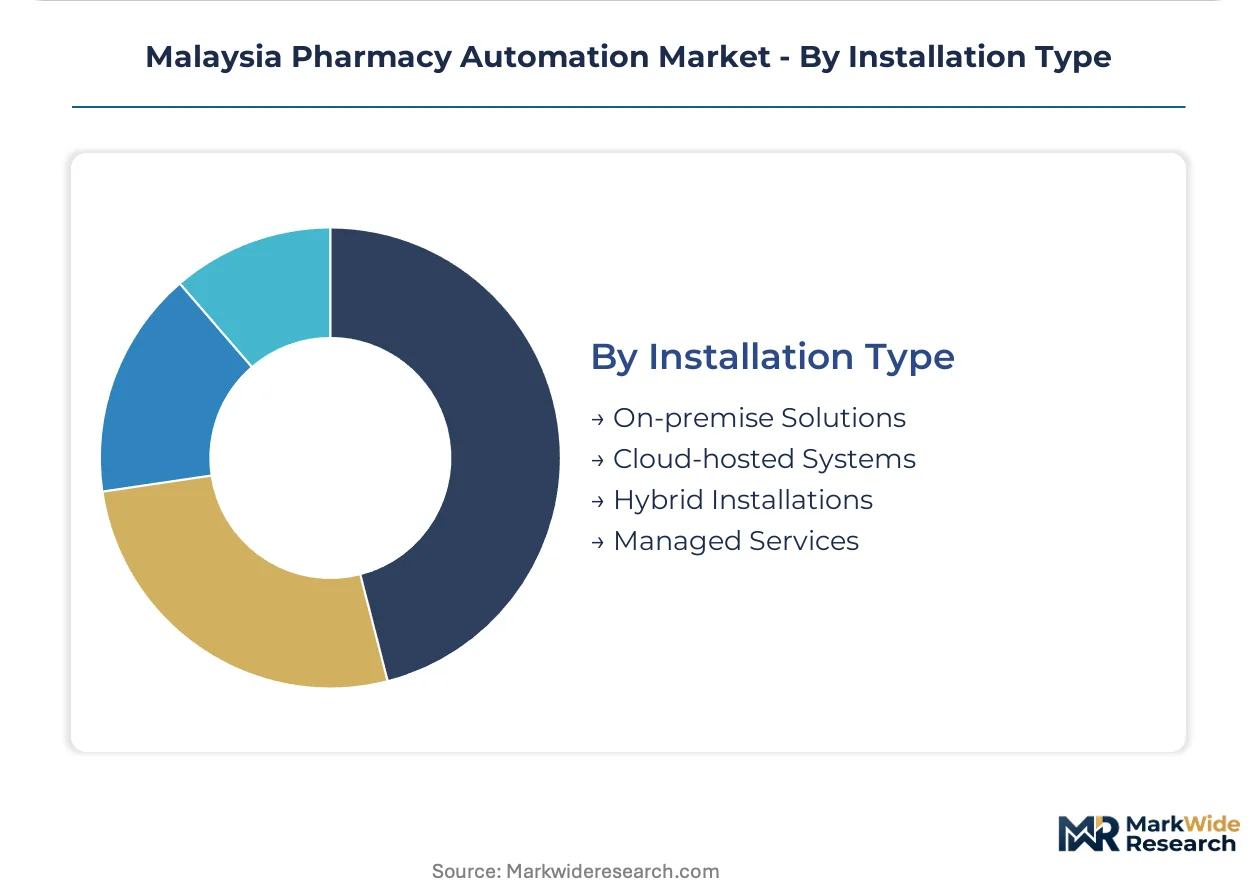
Installation Type:
Deployment architecture reflects data sovereignty requirements and legacy system integration constraints.
- On-premise Solutions:Local hardware installations with dedicated server infrastructure for high-acuity wards requiring sub-second medication retrieval. Older hospital information systems in secondary care facilities lack API architectures, forcing expensive middleware development.
- Hybrid Installations:Edge computing with cloud analytics combining local dispensing control with centralized data lakes. Robotics-workflow convergence in new hospital constructions pairs autonomous mobile robots with hybrid automation architectures.
- Cloud-hosted Systems:Fully managed SaaS platforms with browser-based inventory dashboards.
- Managed Services:Outsourced maintenance and compliance documentation for biomedical engineering talent-scarce facilities.
On-premise solutions retain majority share. Hybrid installations are gaining share fastest as greenfield hospital projects multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across Malaysian sub-regions, with private hospital chains in Greater Kuala Lumpur absorbing premium automation costs while smaller facilities in East Malaysia prioritize modular point solutions.
Greater Kuala Lumpur
Private hospital consolidation in the Klang Valley corridor concentrates procurement authority into integrated platform architectures. Malaysia's Medical Device Authority registration requirements under the Medical Device Act streamline approval pathways for Class B and C automation equipment. IHH Healthcare and KPJ Healthcare chains in Petaling Jaya and Ampang are mandating barcode-enabled medication verification as baseline specifications.
Penang Island
Medical tourism hubs in George Town and Bayan Lepas drive demand for high-throughput central pharmacy robots serving international patient volumes. The Ministry of Health's pharmacy practice guidelines enforce traceability standards for dispensing workflows. Island Hospital and Gleneagles Penang anchor procurement clusters where replacement cycles compress to 18-24 months.
Johor Bahru
Mid-sized retail pharmacy chains bypass upfront capital barriers through cloud-based subscription models for inventory management. The Iskandar Malaysia economic corridor attracts healthcare infrastructure investment with tax incentives for digital health adoption. KPJ Bandar Dato Onn Specialist Hospital exemplifies hybrid installation architectures pairing local dispensing control with centralized analytics.
Selangor State
Tertiary facilities in Shah Alam and Subang Jaya pilot AI-enabled predictive inventory algorithms to reduce pharmaceutical waste from expired stock. The national digital health blueprint accelerates electronic prescription interoperability mandates. Sunway Medical Centre and Columbia Asia Hospital anchor robotics-workflow convergence installations in greenfield constructions.
East Malaysia
Sarawak and Sabah secondary care facilities face biomedical engineering talent scarcity that favors managed service contracts over in-house maintenance. General hospital networks in Kuching and Kota Kinabalu rely on distributor networks for technical support infrastructure. Procurement concentrates on compact dispensing units with simplified middleware requirements for legacy hospital information systems.
Malaysia Pharmacy Automation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where integrated platform vendors capture large hospital contracts while point-solution suppliers serve price-sensitive retail segments. The vendor base clusters around three strategic archetypes: full-stack automation architects, robotics specialists, and software-centric middleware providers. M&A activity concentrates on acquiring localized technical support capabilities, while portfolio diversification moves target cloud-based subscription revenue models.
Within the full-stack automation tier, Omnicell, Inc. and Becton, Dickinson and Company occupy positions exemplifying end-to-end platform dominance in Penang and Kuala Lumpur hospital installations. Swisslog Healthcare represents the robotics specialization archetype, anchoring high-throughput central pharmacy deployments through servo-driven system architectures. These three entities collectively illustrate how competitive positioning in Malaysia's pharmacy automation market depends on regulatory compliance depth, localized service infrastructure, and recurring revenue model maturity rather than hardware specifications alone.
| Leading Market Players |
|---|
| Omnicell, Inc. |
| Becton, Dickinson and Company |
| Baxter International Inc. |
| Capsa Healthcare |
| McKesson Corporation |
| Swisslog Healthcare |
| Yuyama Co., Ltd. |
| ScriptPro LLC |
| Rxsafe LLC |
| Others |
Supply & Pricing Matrix
Sixty-to-ninety-day lead times for servo motors and optical sensors concentrate pricing power with East Asian component suppliers, forcing Malaysian installers to absorb cost volatility or extend replacement cycles for precision dispensing equipment.
Pricing Analysis
After-sales service contracts now drive lifetime value, with software licensing and preventive maintenance bundles capturing recurring revenue streams that hardware margins alone cannot sustain. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification tier under Medical Device Act classifications and after-sales bundling depth. Pricing pressure stems from group purchasing organizations unbundling service contracts from hardware acquisition, compressing distributor margins. Mid-sized retail pharmacy chains in Johor Bahru and Ipoh exhibit highest price sensitivity, while Klang Valley private hospital chains absorb premium costs for integrated platform architectures.
Supply Chain Analysis
Japan and Germany anchor precision servo motor manufacturing, while Taiwan and South Korea dominate optical sensor fabrication for pharmacy automation systems. Malaysian installers draw from concentrated East Asian supply chains for electromechanical components, control modules, and barcode verification hardware. Single-source vulnerability in high-precision dispensing arms exposes procurement timelines to geopolitical friction and shipping chokepoint congestion. Distribution runs through authorized distributor networks with localized technical support infrastructure, bypassing direct manufacturer relationships for smaller regional hospitals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from cloud-native SaaS inventory platforms that bypass capital-intensive hardware procurement for mid-sized retail chains.
For Market Incumbents: Fortify recurring revenue moats by embedding software licensing into hardware contracts and acquiring localized biomedical engineering talent pools. Omnicell, Inc. and Becton, Dickinson and Company exemplify platform consolidation that locks out modular point-solution competitors. Certification investment under evolving Medical Device Act classification rules serves as the priority defensive lever.
For New Entrants and Emerging Players: Differentiate on AI-enabled predictive inventory algorithms targeting tertiary hospital central pharmacies in Selangor and Johor where incumbent robotics specialization leaves workflow-software gaps. Mid-sized retail pharmacy chains in Ipoh represent the most penetrable white-space segment. A SaaS-first go-to-market angle bypasses upfront capital barriers that exclude hardware-centric competitors.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-based subscription segments, compressing returns for hardware-heavy business models while expanding software margin pools. Acquisition targets should exhibit localized technical support infrastructure and Medical Device Authority compliance documentation capabilities. Watch for Medical Device Act classification rule finalization as the signal to reassess robotics versus software platform viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Companion Development | Native EMR connectivity meets Ministry of Health electronic prescription interoperability mandates. |
| Hospital System Partnership | Klang Valley consolidation concentrates procurement authority into fewer decision-makers. |
| CE Marking Pathway | European certification accelerates Medical Device Authority registration for imported robotics. |
| Backward Integration into Servo Motors | Captive supply of precision components insulates against East Asian lead time volatility. |
| Geographic Expansion into Johor Bahru | Iskandar Malaysia tax incentives reduce digital health adoption barriers for mid-sized chains. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with hospital pharmacy directors, biomedical engineers, Medical Device Authority registration specialists, and group purchasing organization contract managers; and secondary validation against hospital procurement databases, GPO contract filings, Medical Device Act regulatory notices, and Ministry of Health digital health blueprint documents. Bottom-up and top-down triangulation reconciled facility-level installation data with aggregate market sizing.
Across the analysis window, the forecast framework modeled product type segmentation, end-user scale tiers, technology adoption curves, and installation architecture preferences. CAGRs derived from weighted average growth rates across segment-level demand projections, incorporating AI penetration assumptions for predictive inventory and cloud subscription adoption trajectories in retail pharmacy chains.
Decision-makers should treat outputs as directional under stable Medical Device Act classification assumptions and continued private hospital infrastructure modernization; material deviation in regulatory timelines or import tariff regimes would warrant model refresh. Recalibration cycles align with material shifts in Medical Device Authority rulemaking and Klang Valley hospital consolidation announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Global Contract Development and Manufacturing Organization (CDMO) Outsourcing Market
Pharmaceutical Equipment
Pharmaceutical Filtration Market
Pharmaceutical Equipment
Global Central Fill Pharmacy Automation Market
Pharmaceutical Equipment
Pharmaceutical Processing Equipment Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
US Pharmaceutical Isolators Market
Pharmaceutical Equipment
Pharmaceutical Refrigerators and Freezers Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Pharmaceutical Stability and Storage Services Market
Pharmaceutical Equipment
US Depyrogenated Sterile Empty Vials Market
Pharmaceutical Equipment
Shell Vials Market
Pharmaceutical Equipment
Pharmacy Automation Market
Pharmaceutical Equipment
Medication Dispenser Market
Pharmaceutical Equipment
Japan Contract Development and Manufacturing Organization Market
Pharmaceutical Equipment
Interlock Vials Market