
 Mexico Ophthalmic Devices Market | 2026-2036
Mexico Ophthalmic Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Ophthalmic Devices Market Foresight
China is rewriting ophthalmic device supply dynamics as Mexican distributors diversify procurement sources beyond traditional North American channels. EssilorLuxottica leverages its vertically integrated lens manufacturing to dominate Mexico's vision correction retail segment. Alcon Inc anchors the surgical instruments category through established relationships with major hospital chains. Topcon Corporation specializes in diagnostic imaging platforms that serve both metropolitan clinics and regional ophthalmology centers.
Ophthalmic devices encompass precision instruments, implants, and diagnostic systems engineered to refractive tolerances within 0.25 diopters and biocompatible materials such as hydrophobic acrylic and silicone hydrogel, designed to restore, correct, or monitor visual function across clinical and surgical settings. Intraocular lenses capture the largest value pool due to Mexico's aging demographic profile and expanding cataract surgery volumes in public health institutions. Optical coherence tomography represents the fastest-growing technology segment as retinal screening protocols expand beyond tertiary hospitals into ambulatory surgical centers. Contact lenses maintain steady penetration among younger demographics in urban corridors, though margin compression from private-label alternatives constrains premium positioning.
COFEPRIS governs medical device registration and post-market surveillance, requiring ISO 13485 quality management certification for all imported ophthalmic products and enforcing labeling standards that shape product localization investments by foreign manufacturers. NOM-240-SSA1-2012 establishes technical specifications for optical establishments, directly influencing equipment procurement criteria across eye clinics and hospital ophthalmology departments. Stakeholders must monitor pending harmonization between Mexican medical device regulations and FDA recognition agreements, as alignment shifts would accelerate market entry timelines for US-origin surgical platforms and diagnostic systems.
Market Dynamics
COFEPRIS registration tightening is forcing Mexican distributors to rebuild qualification pipelines for imported surgical platforms, while cataract surgery volume expansion in public hospitals pulls capital toward intraocular lens procurement.
Growth Catalysts
- NOM-240-SSA1-2012 compliance mandates:Optical establishment technical specifications require diagnostic equipment upgrades across Mexico City and Guadalajara clinics, accelerating replacement cycles for fundus cameras and tonometers.
- Central Mexican cataract surgery networks:Public health institutions in Hidalgo, Puebla, and Tlaxcala are expanding operating theater capacity, generating sustained demand for phacoemulsification systems.
- Silicone hydrogel material advances:Extended-wear contact lens formulations reduce follow-up visit frequency, appealing to working-age populations in Monterrey and Querétaro urban corridors.
Market Restraints
- ISO 13485 certification bottlenecks:Third-party audit capacity constraints in Mexico delay quality management verification for Asian-manufactured diagnostic devices.
- Single-source phacoemulsification handpiece supply:German and US component suppliers dominate precision pump mechanisms, exposing procurement to transatlantic shipping volatility.
- Optical coherence tomography price compression:Refurbished Japanese systems flood secondary markets, undermining new equipment margins for metropolitan distributors.
Strategic Opportunities
- Yucatán Peninsula ambulatory expansion:Mérida and Cancún ophthalmology centers lack retinal screening density, creating whitespace for mobile OCT deployment.
- Teleophthalmology diagnostic convergence:Cloud-based image transmission paired with artificial intelligence grading algorithms enables remote cataract triage in rural Veracruz communities.
- COFEPRIS-FDA harmonization prospect:Pending mutual recognition agreement would accelerate US-origin femtosecond laser platform market entry timelines.
Industry Challenges
- Biomedical engineer scarcity:Mexico produces insufficient trained technicians for phacoemulsification system maintenance, forcing clinics to rely on expensive overseas service contracts.
- Legacy analog slit lamp integration:Hybrid digital retrofit kits generate compatibility failures with existing patient management software in established Guadalajara practices.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Ophthalmic Devices Market |
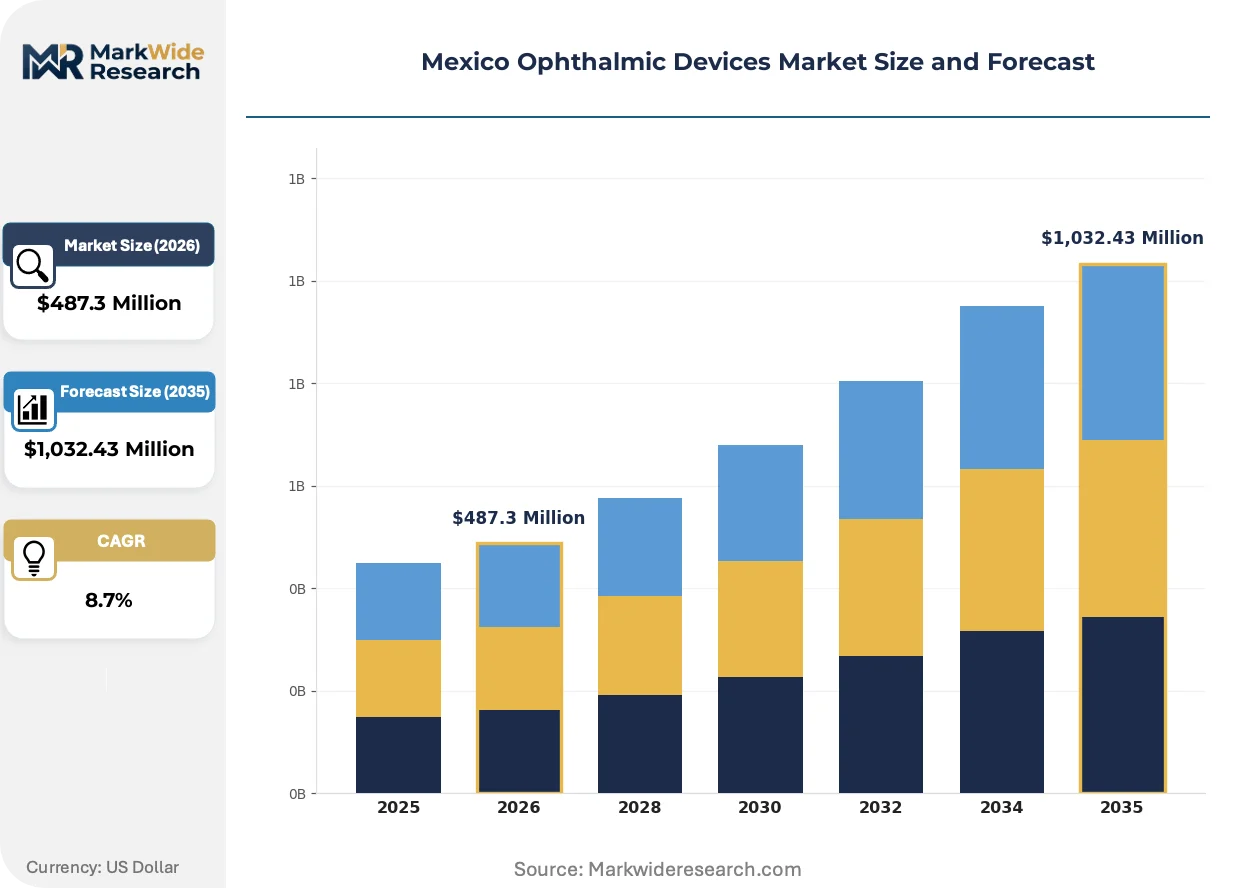
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intraocular Lenses, Contact Lenses, Diagnostic Equipment, Surgical Instruments Application: Cataract Surgery, Glaucoma Treatment, Vision Correction, Retinal Procedures End User: Hospitals, Eye Clinics, Ambulatory Surgical Centers, Research Institutions Technology: Laser Technology, Optical Coherence Tomography, Phacoemulsification, Electrophysiology |
| Companies Covered | EssilorLuxottica, Topcon Corporation, Alcon Inc, HOYA Corporation, Nidek Co Ltd, Bausch + Lomb Corporation, Carl Zeiss Meditec AG, HAAG-Streit Group, Johnson & Johnson Vision Care, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Ophthalmic Devices Market Shifts & Advancements
Diagnostic workflows are fragmenting across physical and virtual layers, with Mexican clinics reassessing capital allocation between in-house imaging capacity and outsourced interpretation services.
Optical coherence tomography angiography is virtualizing retinal vascular assessment by generating depth-resolved blood flow maps without dye injection. Tertiary hospitals in Mexico City adopt these platforms rapidly, while regional centers delay purchases pending reimbursement clarity. The technology is virtualizing traditional fluorescein angiography volumes and compressing referral pathways to academic medical centers.
COFEPRIS post-market surveillance expansion requires adverse event reporting for all Class II and III ophthalmic implants, mirroring FDA MedWatch protocols. Manufacturers now maintain Mexican territory-specific vigilance systems, adding compliance overhead but reducing liability exposure. Surgical instrument importers bear the heaviest documentation burden, reshaping distributor selection criteria toward established regulatory affairs capabilities.
Hospital purchasing cooperatives in Jalisco and Nuevo León consolidate procurement for high-value diagnostic platforms, displacing individual clinic negotiations. Group contracting shifts supplier relationships toward national distribution agreements with volume tier structures. This concentration is most visible in Monterrey's private hospital cluster, where three buying groups control phacoemulsification system acquisition.
Mexico Ophthalmic Devices Market Segmentation
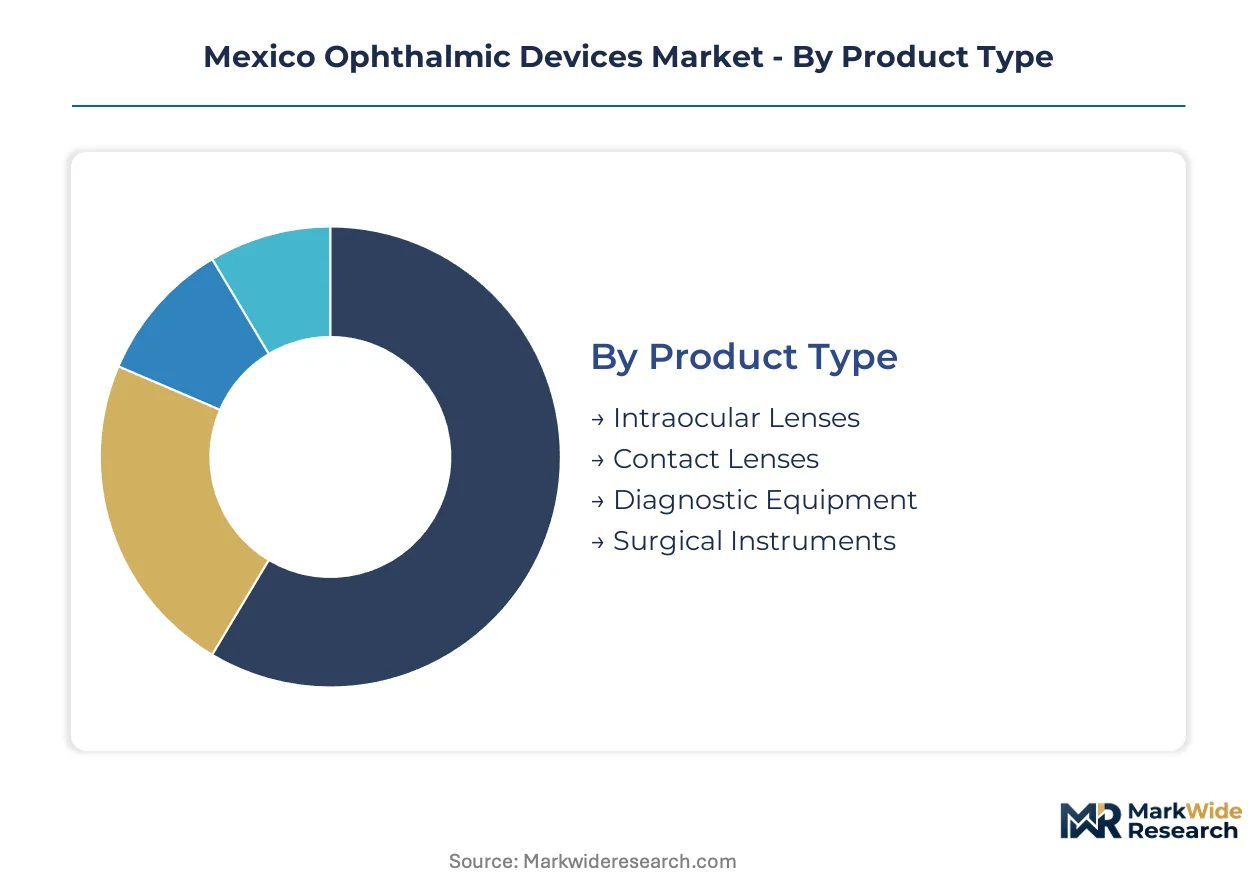
Mexico's ophthalmic device market segments reflect distinct procurement rhythms and clinical priorities. Understanding these divisions reveals where capital concentrates and which technologies face replacement pressure.
Product Type:
Replacement cycles vary dramatically across product categories, with consumables turning over in months while capital equipment persists for years.
- Intraocular Lenses:Hydrophobic acrylic and silicone hydrogel implants engineered to refractive tolerances within 0.25 diopters. Public hospitals in Hidalgo, Puebla, and Tlaxcala are expanding cataract surgery networks, pulling procurement volume toward premium aspheric and toric formulations despite budget constraints.
- Contact Lenses:Silicone hydrogel extended-wear formulations reduce follow-up visit frequency for working-age populations in Monterrey and Querétaro. Margin compression from private-label alternatives constrains premium positioning among younger urban demographics.
- Diagnostic Equipment:Fundus cameras and tonometers face accelerated replacement cycles under NOM-240-SSA1-2012 compliance mandates across Mexico City and Guadalajara clinics.
- Surgical Instruments:Phacoemulsification handpieces depend on German and US precision pump mechanisms, exposing procurement to transatlantic shipping volatility.
Intraocular lenses dominate installed base. Diagnostic equipment is where expansion concentrates.
Application:
Procedure volume distribution shapes supplier relationships, with high-throughput applications commanding dedicated service infrastructure.
- Cataract Surgery:Central Mexican states anchor public health institution expansion, generating sustained demand for phacoemulsification systems and premium IOLs. Operating theater capacity builds in Hidalgo and Tlaxcala pull capital from equipment into consumables.
- Retinal Procedures:OCT angiography platforms are virtualizing traditional fluorescein angiography volumes across Mexico City tertiary hospitals. Regional centers delay purchases pending reimbursement clarity, compressing referral pathways to academic medical centers.
- Glaucoma Treatment:Diagnostic screening protocols expand beyond tertiary hospitals into ambulatory surgical centers, driving tonometer and visual field analyzer procurement.
- Vision Correction:Urban corridors in Monterrey and Guadalajara concentrate demand for refractive surgery platforms and premium contact lens fittings.
Cataract surgery commands the deepest supplier relationships. Retinal procedures are climbing the fastest in technology investment intensity.
End User:
Facility type determines procurement scale and regulatory exposure, from institutional tender processes to individual practice decisions.
- Hospitals:Public health institutions in central Mexican states expand cataract surgery networks with capital allocated through federal procurement channels. COFEPRIS registration tightening forces qualification pipeline rebuilds for imported surgical platforms.
- Eye Clinics:Private practices in Mexico City and Guadalajara face NOM-240-SSA1-2012 compliance mandates requiring diagnostic equipment upgrades.
- Ambulatory Surgical Centers:Mérida and Cancún ophthalmology centers lack retinal screening density, creating whitespace for mobile OCT deployment across the Yucatán Peninsula.
- Research Institutions:Limited procurement volume concentrates in Mexico City academic medical centers with established regulatory affairs capabilities.
Hospitals anchor volume commitments. Ambulatory surgical centers are where geographic expansion concentrates.
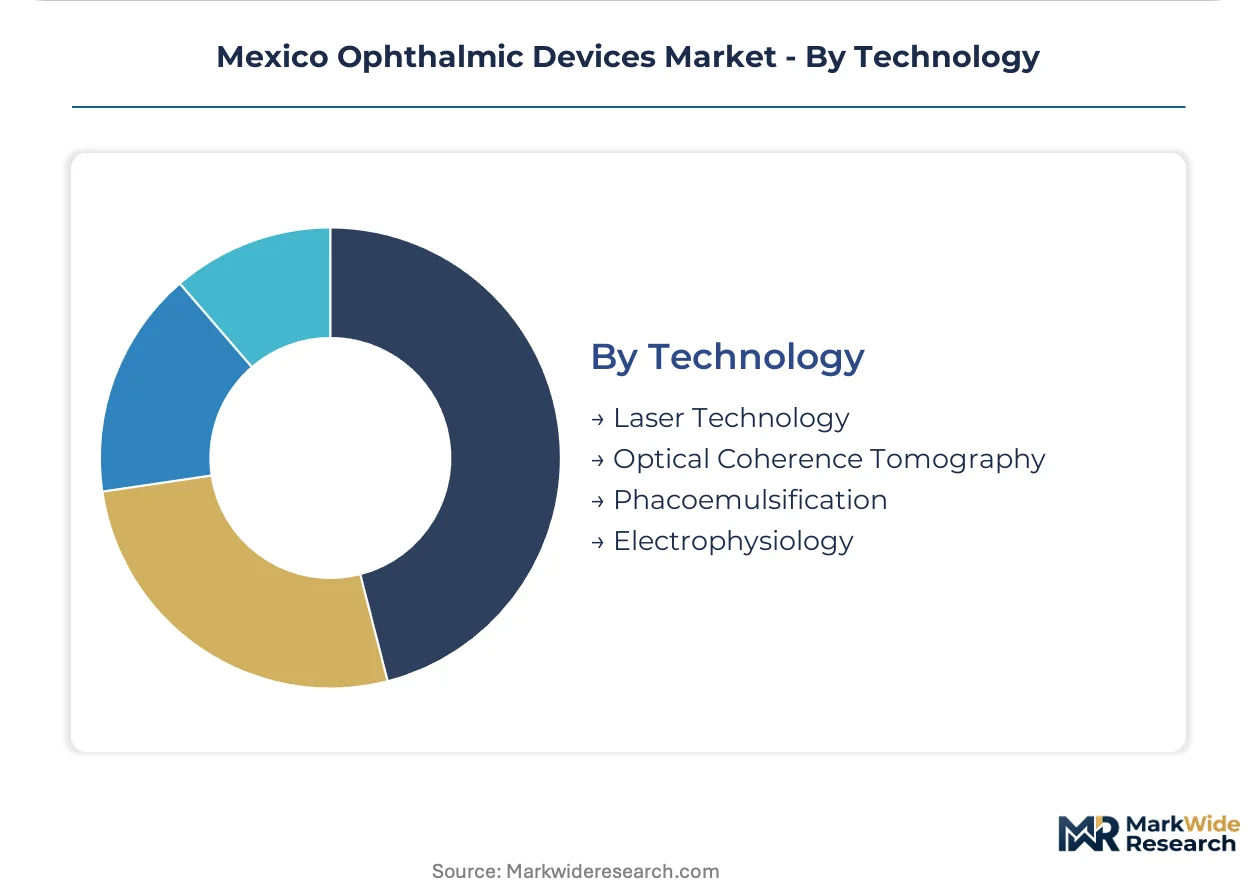
Technology:
Technology maturity curves determine whether procurement favors established platforms or experimental adoption.
- Optical Coherence Tomography:Retinal screening protocols expand beyond tertiary hospitals into ambulatory surgical centers. Refurbished Japanese systems flood secondary markets, undermining new equipment margins for metropolitan distributors.
- Phacoemulsification:Precision pump mechanisms from German and US component suppliers dominate, exposing procurement to transatlantic shipping volatility.
- Laser Technology:Femtosecond laser platforms await accelerated market entry timelines pending COFEPRIS-FDA harmonization.
- Electrophysiology:Specialized diagnostic applications concentrate in tertiary referral centers with trained interpretation staff.
Phacoemulsification dominates installed surgical platform base. Optical coherence tomography is gaining share fastest in diagnostic capital allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Phacoemulsification system suppliers concentrate service infrastructure around Mexico City and Guadalajara, while diagnostic equipment distributors build secondary hubs in Monterrey and Mérida to capture ambulatory surgical center expansion.
Mexico City Metro
Tertiary hospitals and private eye clinics drive demand for OCT angiography platforms and premium intraocular lenses. COFEPRIS registration requirements for imported surgical equipment shape procurement timelines for metropolitan distributors. The Polanco and Santa Fe medical corridors host concentrated diagnostic imaging capacity serving central Mexican referral networks.
Nuevo León
Monterrey's private hospital cluster consolidates phacoemulsification system acquisition through three dominant purchasing cooperatives. NOM-240-SSA1-2012 compliance mandates accelerate fundus camera replacement cycles across established ophthalmology practices. San Pedro Garza García anchors premium vision correction service delivery for working-age populations in northern Mexico.
Jalisco
Guadalajara's eye clinics expand diagnostic capabilities under optical establishment technical specifications requiring equipment upgrades. ISO 13485 certification bottlenecks delay quality management verification for Asian-manufactured tonometers entering the regional market. The metropolitan zone serves as procurement gateway for Pacific coast ambulatory surgical centers.
Bajío Region
Public health institutions in Hidalgo, Puebla, and Tlaxcala expand cataract surgery networks with federal procurement channel allocation. Operating theater capacity builds pull capital from equipment into consumables, particularly hydrophobic acrylic intraocular lenses. Querétaro's urban corridor generates steady contact lens demand among younger demographics seeking extended-wear silicone hydrogel formulations.
Yucatán Peninsula
Mérida and Cancún ophthalmology centers lack retinal screening density, creating whitespace for mobile OCT deployment across southeastern Mexico. Teleophthalmology diagnostic convergence enables remote cataract triage in rural Campeche and Quintana Roo communities. The region's medical tourism infrastructure attracts refractive surgery platform investments targeting North American patient flows.
Mexico Ophthalmic Devices Market Competitive Landscape
Vertically integrated ophthalmic multinationals and specialized diagnostic equipment manufacturers split the market across vision correction retail and surgical platform categories. Consolidation pressure concentrates procurement relationships around established regulatory affairs capabilities. Three archetypes dominate: lens manufacturers with captive distribution networks, precision surgical instrument suppliers with hospital chain partnerships, and diagnostic imaging specialists with service-intensive regional coverage. Competitive moves center on COFEPRIS registration pipeline expansion and purchasing cooperative volume tier negotiations.
Among the integrated multinational tier, EssilorLuxottica and Alcon Inc exemplify divergent strategic positions—one leveraging vertical control over lens manufacturing and retail channels, the other anchoring surgical instrument categories through institutional relationships. Topcon Corporation occupies a diagnostic imaging specialist position serving both metropolitan clinics and regional ophthalmology centers with platform-dependent service contracts. These three companies represent distinct archetypes rather than direct substitutes, with procurement decisions often splitting across their respective category strongholds.
| Leading Market Players |
|---|
| EssilorLuxottica |
| Topcon Corporation |
| Alcon Inc |
| HOYA Corporation |
| Nidek Co Ltd |
| Bausch + Lomb Corporation |
| Carl Zeiss Meditec AG |
| HAAG-Streit Group |
| Johnson & Johnson Vision Care, Inc. |
| Others |
Supply & Pricing Matrix
Monterrey's private hospital cluster concentrates phacoemulsification system procurement through three dominant purchasing cooperatives, translating volume aggregation into downward price pressure on surgical platform suppliers while squeezing margins for metropolitan distributors serving smaller clinics.
Pricing Analysis
NOM-240-SSA1-2012 dictates the pricing tier structure across Mexico's optical establishments, separating COFEPRIS-registered premium equipment from uncertified economy alternatives in diagnostic categories. Certification grade and after-sales service bundling drive price differentiation between metropolitan Mexico City suppliers and regional distributors. Cost compression in refurbished OCT systems is intensifying because Japanese secondary market inventory floods procurement channels. Public hospital procurement committees exhibit highest price sensitivity, while private eye clinics in Polanco and Santa Fe corridors prioritize service responsiveness over unit economics.
Supply Chain Analysis
Extended payment terms from German and US precision pump mechanism suppliers now stretch 90-120 days for phacoemulsification handpiece procurement, straining Mexican distributor working capital. Manufacturing concentrates in Germany, the United States, and Japan for surgical instrument components, while China supplies refurbished diagnostic platforms. Raw material dependencies include hydrophobic acrylic polymers, silicone hydrogel formulations, and precision optical glass. Single-source vulnerability for phacoemulsification pump mechanisms exposes procurement to transatlantic shipping volatility. Distribution runs through COFEPRIS-authorized import channels with regional hub structures in Mexico City, Guadalajara, and Monterrey.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through hospital purchasing cooperatives in Jalisco and Nuevo León, fragmenting individual clinic negotiation leverage and forcing suppliers toward volume-tiered national distribution agreements.
For Market Incumbents: Insulate service infrastructure investments in Mexico City and Guadalajara against refurbished Japanese OCT platform encroachment by embedding proprietary software companion tools that lock clinics into upgrade cycles. Deepen backward integration into hydrophobic acrylic IOL material supply to defend margin position against Asian polymer cost advantages. COFEPRIS registration pipeline expansion remains the priority certification lever for sustaining hospital chain relationships. For New Entrants and Emerging Players: The Yucatán Peninsula's retinal screening density gap offers whitespace for mobile OCT deployment targeting Mérida and Cancún ambulatory surgical centers with cloud-based image transmission bundled into per-scan pricing models. Teleophthalmology diagnostic convergence in rural Veracruz communities presents the most penetrable application layer, enabling remote cataract triage partnerships with federal health institutions. Target purchasing cooperative qualification as the fastest channel to procurement access. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-affairs-capability play because COFEPRIS registration tightening and post-market surveillance expansion favor established distributors with Mexican territory-specific vigilance systems over capital-light entrants. Acquisition targets should display ISO 13485 certification infrastructure and existing hospital system contracts rather than pure technology assets. Watch COFEPRIS-FDA harmonization progress as the signal indicating accelerated US-origin platform market entry timelines.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Registration Pipeline Expansion | Accelerates market access for imported surgical platforms under tightened quality management requirements. |
| Hospital System Partnership | Locks procurement volume through Jalisco and Nuevo León purchasing cooperative tier structures. |
| Software Companion Development | Differentiates diagnostic platforms from refurbished Japanese systems flooding secondary markets. |
| Reimbursement Strategy | Positions OCT angiography platforms for adoption pending clarity in regional center payment protocols. |
| Geographic Expansion | Captures Yucatán Peninsula whitespace through mobile retinal screening deployment in Mérida and Cancún. |
Research Methodology
Desk research of COFEPRIS registration databases, hospital procurement records, and optical establishment compliance filings preceded structured interviews with biomedical engineers, ophthalmology department heads, GPO contracts managers, and distributor regulatory affairs leads. Secondary validation drew from NOM-240-SSA1-2012 technical specifications, ISO 13485 certification registries, and import customs data for ophthalmic device categories. Bottom-up facility-level equipment counts triangulated against top-down manufacturer shipment reports.
Assumptions held COFEPRIS regulatory trajectory and cataract surgery volume expansion in central Mexican states as fixed baseline conditions, while varying reimbursement clarity timelines for OCT angiography and teleophthalmology adoption curves across the sensitivity range. Segmentation dimensions modeled include product type, application, end user, and technology maturity tier alongside regional procurement channel structure. CAGRs were derived from installed base replacement cycles and procedure volume growth trajectories. Forecast inputs incorporated phacoemulsification system service contract renewal rates and silicone hydrogel contact lens penetration in urban corridors.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, public health budget allocations, or transatlantic shipping costs would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory harmonization progress and hospital purchasing cooperative consolidation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Corneal Surgery Devices Market
Medical Devices
Global Breast Implants Market
Medical Devices
Middle East and Africa C-Arms Market
Medical Devices
Pelvic Electro-Stimulators Market
Medical Devices
India Anesthesia Devices Market
Medical Devices
Global Brachytherapy Devices Market
Medical Devices
Cellular Encapsulation Market
Medical Devices
Incubator Devices Market
Medical Devices
SPG Microstimulator System Market
Medical Devices
Compression Therapy Devices Market
Medical Devices
Left Atrial Appendage (LAA) Closure Device Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Mexico Artificial Organs and Bionic Implants Market
Medical Devices
Electroceutical Devices Market
Medical Devices
Baby Warmer Devices Market
Medical Devices
Surgical Loupes and Cameras Market