
 Pharmaceutical Continuous Manufacturing Market | 2026-2036
Pharmaceutical Continuous Manufacturing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Continuous Manufacturing Market Intelligence
The replacement of discrete batch processing with integrated, continuous material flows is decoupling production scale from facility footprint, altering the core economics of drug manufacturing. GEA Group leverages its extensive portfolio in process engineering to offer end-to-end systems for this transition. Thermo Fisher Scientific specializes in providing advanced analytical instruments for real-time process monitoring. Siemens Healthineers integrates automation and digitalization solutions to enhance process control and data integrity for pharmaceutical clients.
Pharmaceutical continuous manufacturing refers to an integrated, end-to-end production methodology where raw materials are continuously fed and transformed into finished products. The process relies heavily on Process Analytical Technology (PAT) for real-time monitoring and control of critical quality attributes, ensuring consistency. While implementation for Oral Solid Dosage applications is mature, the development of systems for Biologics represents the fastest-growing frontier. Finished Dosage Forms command a significant share, driven by efficiency gains in high-volume drug production.
Regulatory bodies including the US FDA, the European Medicines Agency (EMA), and Japan's PMDA actively support the adoption of continuous manufacturing. Their guidance on Quality by Design (QbD) and advanced manufacturing streamlines the approval pathway for drugs made with these methods. This regulatory alignment reduces market entry barriers for innovators. Stakeholders must now decide between retrofitting existing batch facilities or investing in new, purpose-built continuous production lines to maintain a competitive edge.
Market Dynamics
The core economic and operational models of drug production are being fundamentally altered by regulatory encouragement for process modernization. This shift, championed by frameworks like Quality by Design, prioritizes process understanding and control over traditional batch-based testing and validation.
Growth Catalysts
- Regulatory Harmonization:Guidance from the US FDA, EMA, and PMDA on Quality by Design (QbD) streamlines the validation and approval process for drugs produced via continuous methods, reducing barriers for pharmaceutical innovators.
- Process Analytical Technology (PAT):The maturation of PAT enables real-time monitoring and control of critical quality attributes. This ensures product consistency and significantly reduces the risk of batch failure, a key value proposition for manufacturers.
- CMO Adoption:Contract Manufacturing Organizations are increasingly investing in continuous manufacturing platforms to offer more efficient, flexible, and cost-effective services, thereby gaining a competitive advantage in the outsourced pharmaceutical production market.
Market Restraints
- High Capital Investment:The substantial upfront cost of acquiring continuous manufacturing equipment and retrofitting existing facilities represents a significant financial barrier, particularly for smaller pharmaceutical companies with limited capital budgets.
- Process Development Complexity:Developing and validating a robust continuous process, especially for complex biologics, is technically challenging and resource-intensive, requiring a deep level of specialized process engineering expertise.
- Limited Vendor Pool:A relatively small number of suppliers offer fully integrated, end-to-end continuous manufacturing systems, leading to limited choice, potential for vendor lock-in, and supply chain bottlenecks for specialized components.
Strategic Opportunities
- Biologics Manufacturing:Applying continuous principles to the production of monoclonal antibodies and other biologics represents a major growth frontier, promising significant reductions in facility footprint and cost of goods for these high-value therapies.
- Emerging Market Leapfrogging:Pharmaceutical manufacturers in emerging economies like India and Brazil can build new, purpose-built continuous facilities, bypassing the legacy constraints of batch production common in mature markets.
- AI and Digital Twin Integration:The convergence of PAT with artificial intelligence and digital twin models offers the potential for predictive process control, enabling self-optimizing production lines that minimize deviations and maximize yield.
Industry Challenges
- Specialized Talent Gap:A shortage exists of scientists and engineers with the cross-functional expertise in chemistry, process engineering, automation, and data analytics required to operate and maintain continuous manufacturing systems.
- System Integration Hurdles:Integrating modular continuous processing skids from different vendors with existing site infrastructure and enterprise resource planning systems presents significant technical and data compatibility challenges for operators.
- Standardization Deficit:The absence of industry-wide standards for equipment connectivity, data protocols, and control system architecture complicates the design and implementation of multi-vendor continuous manufacturing lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Continuous Manufacturing Market |
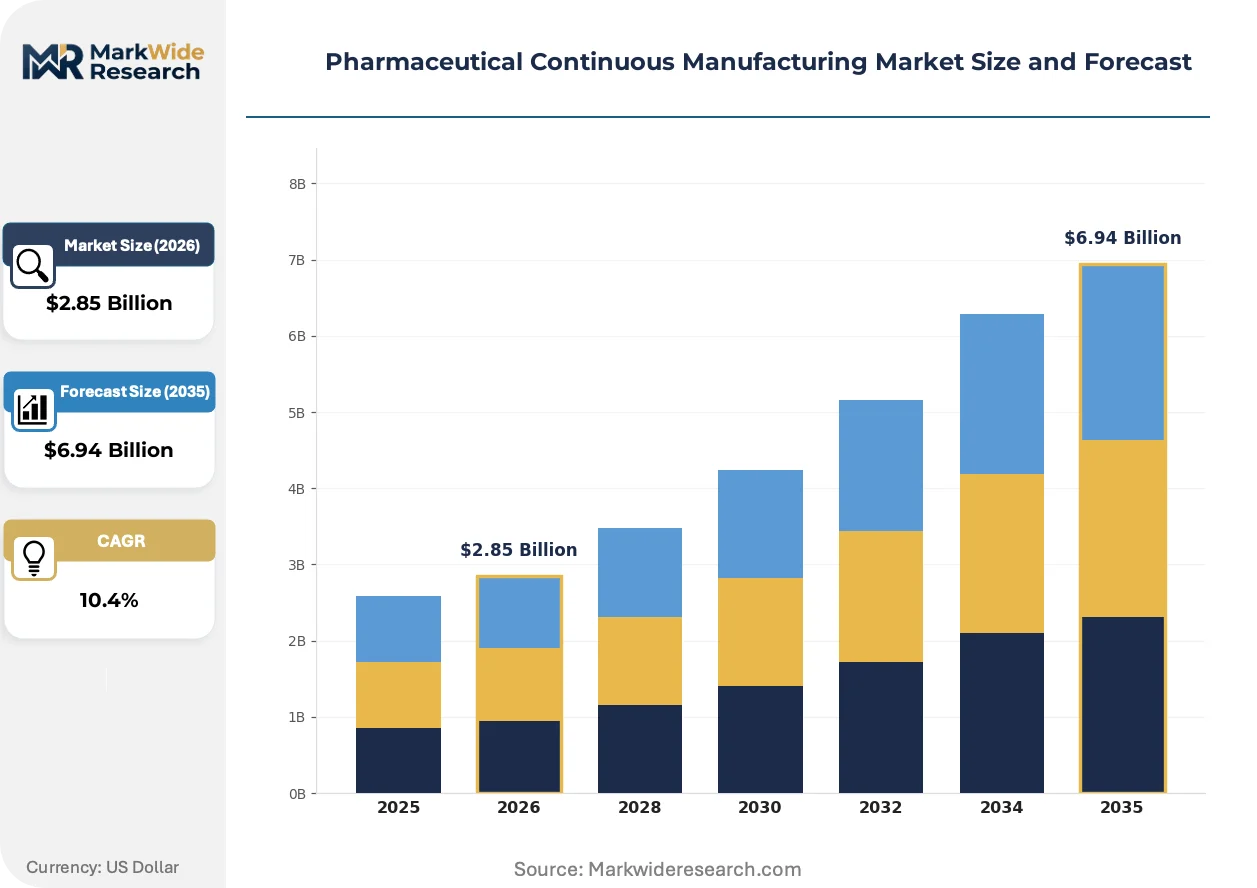
| Market Size in 2026 | $2.85 Billion |
| Market Size in 2035 | $6.94 Billion |
| CAGR (2026 – 2036) | 10.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Tubular Reactor, Rotary Granulator, Inline Blender, Continuous Spray Dryer, Oscillatory Flow Reactor Product Type: Active Pharmaceutical Ingredients, Excipients, Finished Dosage Forms, Biologics, Vaccines Application: Oral Solid Dosage, Parenteral Products, Inhalation Products, Transdermal Systems, Ophthalmic Preparations End User: Contract Manufacturing Organizations, Pharmaceutical Formulators, Biotechnology Firms, Research Laboratories, Quality Control Units |
| Companies Covered | Glatt, KORSCH AG, GEA Group, Robert Bosch Packaging Technology, Hosokawa Micron Corporation, Siemens Healthineers, Coperion GmbH, L.B. Bohle Maschinen + Verfahren, Thermo Fisher Scientific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Continuous Manufacturing Market Strategic Shifts & Innovations
The evolution towards more agile and data-intensive production is reshaping the industry's physical and economic structure. This transition favors flexible, modular systems over large, monolithic plants, enabling a more decentralized approach to pharmaceutical supply chains.
Integrated end-to-end platforms combine multiple unit operations, such as reaction, purification, and formulation, into a single, continuous flow. Both large pharmaceutical firms and contract manufacturers are adopting these systems to shorten development cycles and accelerate speed to market. This level of integration is rewriting the fundamental economics of facility design and scale-up, allowing for smaller, more adaptable manufacturing footprints.
Japan's Pharmaceuticals and Medical Devices Agency (PMDA) is actively encouraging the use of advanced manufacturing through its regulatory science initiatives. This support provides a clearer, more predictable pathway for the approval of drugs developed using continuous processes. Originator drug companies seeking access to the Japanese market are now more incentivized to invest in this technology and include continuous manufacturing data in their regulatory submissions.
A shift is underway from transactional, volume-based contracts to more strategic, long-term partnerships for manufacturing capacity. This evolution challenges the traditional contract manufacturing organization model, creating an advantage for service providers who offer integrated development and production services. This trend is particularly visible in the North American and European markets, where intense pressure exists to optimize drug development costs and supply chain resilience.
Pharmaceutical Continuous Manufacturing Market Segmentation
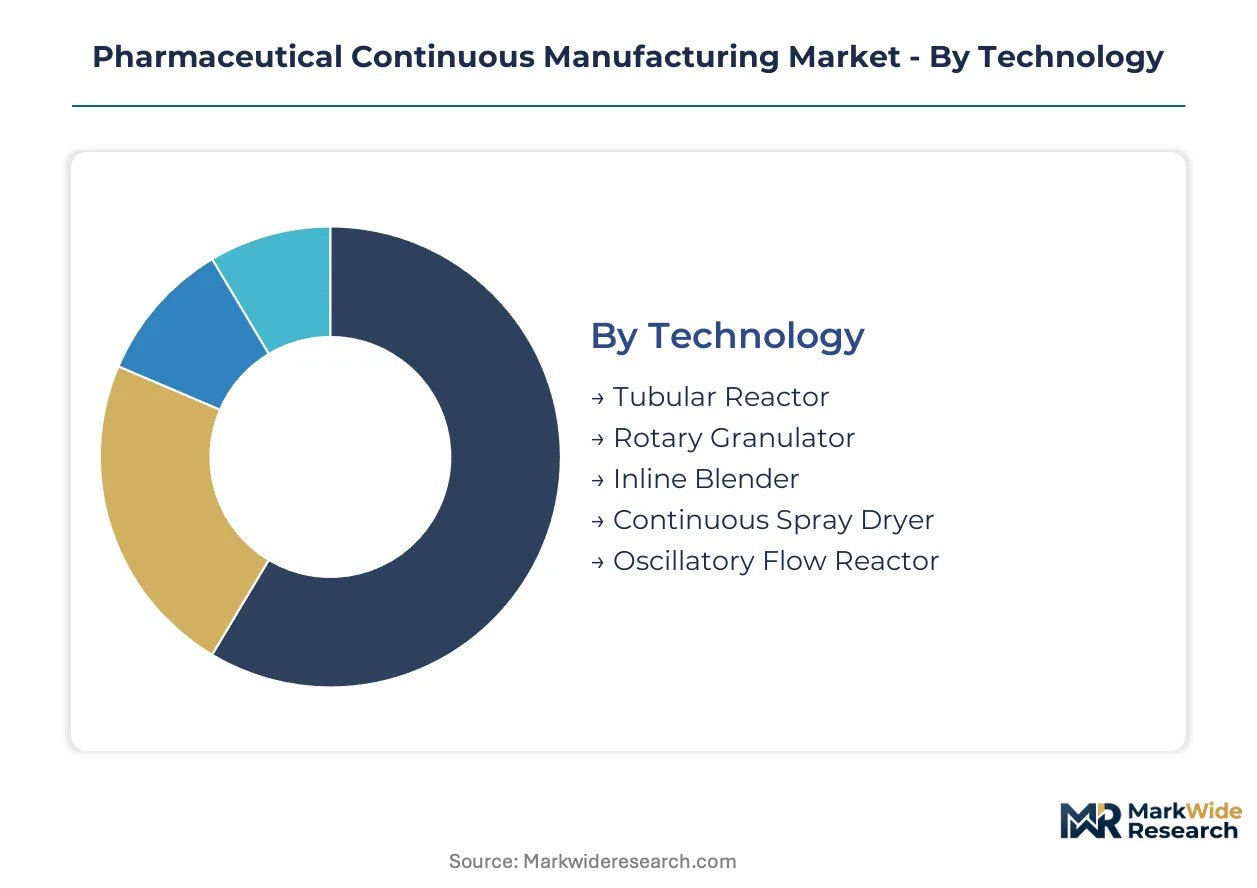
The Pharmaceutical Continuous Manufacturing Market segmentation provides a granular view of the diverse technologies, product types, applications, and end-user adoption patterns shaping this evolving industry. Understanding these distinctions is crucial for stakeholders to identify specific investment opportunities and tailor solutions for distinct market needs.
Technology:
Buyers in the continuous manufacturing technology segment are primarily differentiated by their specific process requirements and the scale of their operations.
- Tubular Reactor:This technology facilitates continuous chemical reactions with precise residence time control, often used for active pharmaceutical ingredient synthesis and fine chemical production where reaction kinetics are critical. Demand concentrates in API manufacturing, driven by the need for enhanced yield and product consistency.
- Continuous Spray Dryer:This system transforms liquid feeds into dry powder, enabling precise particle size distribution and efficient solvent removal, essential for producing finished dosage forms and moisture-sensitive APIs. Its adoption is significant in formulations requiring amorphous solid dispersions for improved bioavailability.
- Rotary Granulator:These systems are employed for continuous wet granulation processes, forming granules for tablet manufacturing and enhancing powder flow properties.
- Inline Blender:Inline blenders provide real-time, continuous mixing of powders or liquids, crucial for maintaining homogeneity in continuous formulation processes.
- Oscillatory Flow Reactor:These reactors offer enhanced mixing and heat transfer characteristics, making them suitable for challenging reactions and crystallization processes in various pharmaceutical applications.
Volume sits with Tubular Reactor systems; growth tilts toward Continuous Spray Dryer applications.
Product Type:
Differentiation in product type largely stems from the molecule's complexity and its intended formulation, dictating specific processing requirements.
- Finished Dosage Forms:These represent the final drug products, including tablets, capsules, and oral liquids, produced through continuous processes for high-volume manufacturing efficiency and reduced batch failures. Global generic drug producers increasingly adopt continuous lines for cost reduction and faster market supply.
- Biologics:This segment involves the continuous production of large, complex biological molecules such as monoclonal antibodies and therapeutic proteins, leveraging process intensification to reduce facility footprint and cost of goods. Biotechnology firms are investing in these systems for improved yield and quality.
- Active Pharmaceutical Ingredients:Continuous manufacturing of APIs focuses on the synthesis and purification of the drug substance, offering improved reaction control and safety over traditional batch methods.
- Excipients:Continuous processes are applied to the production of inactive ingredients used in drug formulations, ensuring consistent quality and supply for pharmaceutical manufacturers.
- Vaccines:The continuous production of vaccines involves complex biological processes and sterile manufacturing, aiming for greater efficiency and scalability in response to global health demands.
The segment seeing the most significant investment is Biologics, while Finished Dosage Forms maintain their foundational role.
Application:
Patient delivery method and therapeutic area primarily define the continuous manufacturing application segment.
- Oral Solid Dosage:This application encompasses continuous manufacturing of tablets, capsules, and powders intended for oral administration, representing the most mature and widely adopted area due to high demand and established process understanding. Efficiency gains for chronic disease medications are particularly impactful.
- Parenteral Products:Continuous manufacturing for injectable solutions and other sterile products demands stringent aseptic processing and real-time quality control, crucial for biologics and critical care medicines. This area sees significant investment for process intensification and improved sterility assurance.
- Inhalation Products:This application involves the continuous production of formulations for respiratory therapies, focusing on precise particle size control and consistent drug delivery.
- Transdermal Systems:Continuous processes are utilized for manufacturing drug patches and other transdermal delivery systems, ensuring uniform drug loading and controlled release profiles.
- Ophthalmic Preparations:This segment applies continuous manufacturing to sterile eye drops and other ocular formulations, emphasizing aseptic conditions and product stability.
Commercial viability is strongest in Oral Solid Dosage, with Parenteral Products showing considerable expansion.
End User:
Operational focus and internal capabilities largely differentiate the end-user segments for continuous manufacturing technologies.
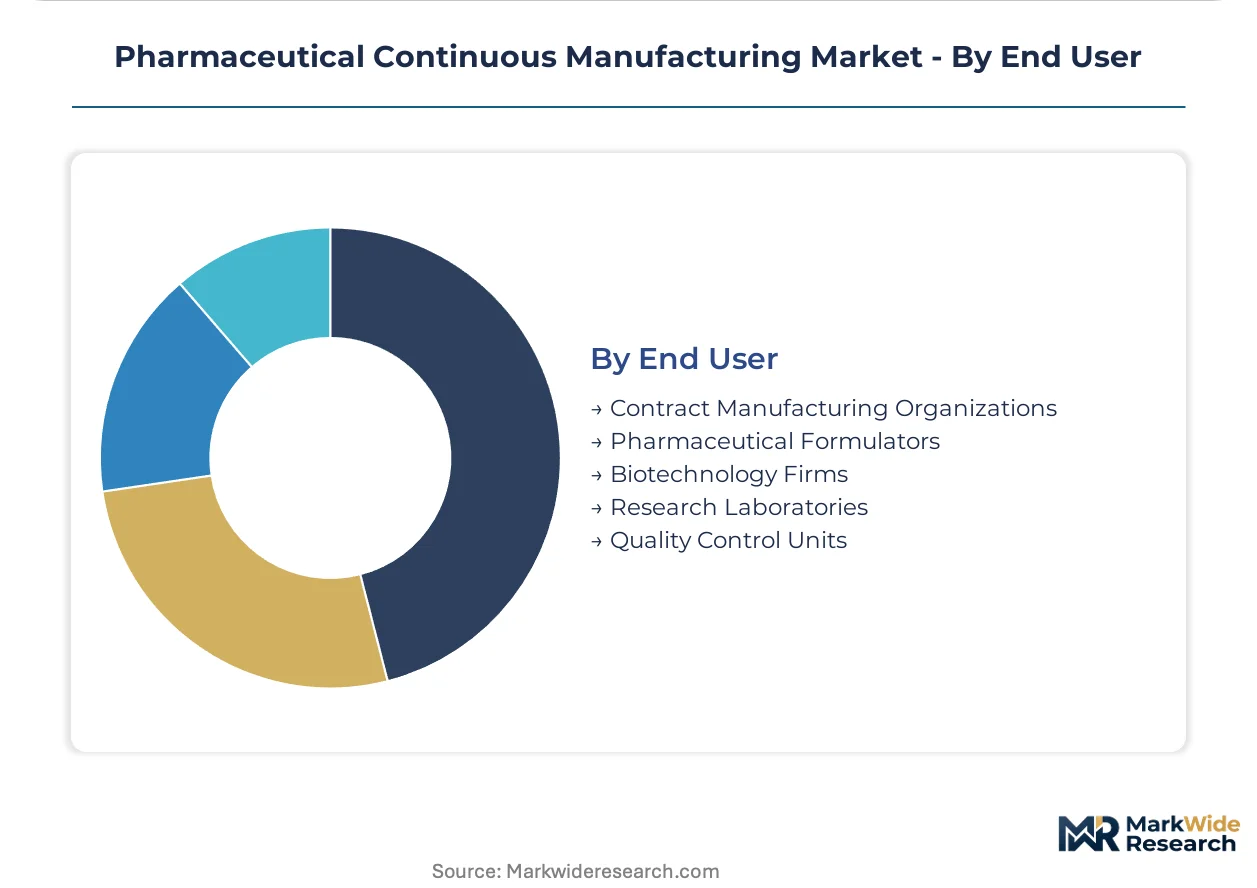
- Contract Manufacturing Organizations:CMOs adopt continuous manufacturing platforms to offer advanced, efficient, and flexible production services to multiple pharmaceutical clients, gaining a competitive edge in outsourced drug production. These organizations are critical for widespread technology adoption.
- Pharmaceutical Formulators:These end users, typically innovator pharmaceutical companies, integrate continuous manufacturing into their in-house production lines to accelerate drug development, improve process control, and reduce manufacturing costs for proprietary products. Speed to market is a primary driver for these firms.
- Biotechnology Firms:These companies leverage continuous manufacturing for the production of biologics and advanced therapies, seeking to optimize yields and reduce the footprint of their often complex processes.
- Research Laboratories:Research institutions and academic labs utilize continuous manufacturing equipment for process development, optimization studies, and small-scale production of novel compounds.
- Quality Control Units:These units integrate Process Analytical Technology (PAT) and real-time monitoring solutions within continuous manufacturing setups to ensure product quality and regulatory compliance.
The largest direct implementers are Pharmaceutical Formulators, while Quality Control Units represent a critical support function.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones and government incentives in countries like Ireland attract significant investment into pharmaceutical continuous manufacturing. These strategic locations foster advanced production capabilities and process optimization for drug manufacturers. Such concentrated efforts accelerate technology adoption and global supply chain resilience.
United States
The United States market drives demand for continuous manufacturing, especially for high-volume finished dosage forms and complex biologics. The US FDA actively supports adoption through Quality by Design initiatives, streamlining approval pathways. In the Greater Boston area, pharmaceutical companies collaborate on advanced manufacturing techniques.
Germany
Germany exhibits strong demand for continuous manufacturing systems, especially for API synthesis and process engineering solutions. The European Medicines Agency (EMA) provides regulatory frameworks encouraging this transition. Engineering firms in Bavaria and North Rhine-Westphalia develop integrated systems for pharmaceutical clients.
Ireland
Ireland has become a key hub for pharmaceutical continuous manufacturing, driven by strong contract manufacturing organization (CMO) adoption. Irish government policies attract substantial foreign direct investment in biopharmaceutical production. Major pharmaceutical companies in Dublin and Cork are expanding their continuous manufacturing footprints.
Japan
Japan emphasizes advanced manufacturing techniques for originator drugs, fostering innovation in continuous processes. The Pharmaceuticals and Medical Devices Agency (PMDA) actively supports the use of these advanced methods. In the Kanto region, pharmaceutical firms integrate continuous lines to accelerate drug development and market access.
India
India presents a significant opportunity for continuous manufacturing adoption, particularly for generic drug producers. The country's national pharmaceutical regulator supports process modernization to enhance quality and reduce production costs. Pharmaceutical clusters in Gujarat and Telangana are exploring new, purpose-built continuous facilities.
Pharmaceutical Continuous Manufacturing Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the pharmaceutical continuous manufacturing market. This market exhibits a tiered structure, with established engineering conglomerates and specialized equipment providers forming distinct archetypes. Technology providers focus on integrated solutions for end-to-end continuous processes. Strategic partnerships between technology vendors and pharmaceutical formulators are common, alongside continued capacity expansion and portfolio diversification as dominant competitive moves among market participants.
Within the integrated solutions archetype, GEA Group exemplifies providers of end-to-end systems for continuous process engineering. Siemens Healthineers represents a key player integrating automation and digitalization solutions to enhance process control for pharmaceutical clients. Thermo Fisher Scientific occupies a position as a specialist in advanced analytical instruments crucial for real-time process monitoring. These entities focus on delivering robust and compliant continuous manufacturing technologies, serving both large pharmaceutical firms and contract manufacturing organizations.
| Leading Market Players |
|---|
| Glatt |
| KORSCH AG |
| GEA Group |
| Robert Bosch Packaging Technology |
| Hosokawa Micron Corporation |
| Siemens Healthineers |
| Coperion GmbH |
| L.B. Bohle Maschinen + Verfahren |
| Thermo Fisher Scientific |
| Others |
Cost & Logistics Intelligence
Specialized equipment acquisition costs for continuous manufacturing systems, particularly for advanced analytical instruments, influence the final pricing of integrated solutions for pharmaceutical clients. This upstream input affects downstream service pricing offered by Contract Manufacturing Organizations.
Pricing Analysis
Short lead time delivery of customized continuous manufacturing solutions commands a premium in the market. The dominant pricing model is project-based, often incorporating long-term service contracts for maintenance and upgrades. Price differentiation stems from the level of customization required for specific drug formulations and the after-sales support package. Pricing pressure stems from the increasing competition among Contract Manufacturing Organizations to offer cost-effective services. Smaller pharmaceutical companies exhibit higher price sensitivity, particularly for initial capital outlays.
Supply Chain Analysis
Regional distribution centers for complex process engineering components and analytical instruments support the pharmaceutical continuous manufacturing market. Geographic supply concentration for core equipment centers in Germany and for specialized automation software in Switzerland. The supply chain relies on a limited pool of highly specialized component manufacturers, creating a single-source vulnerability for certain critical parts. Regulatory restrictions on cross-border technology transfer can also pose risks. Direct sales and specialized integrators form the dominant distribution model, often supported by regional service hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents a consolidation play, as the substantial upfront capital investment required for continuous manufacturing systems forces smaller, less capitalized players out of the competition.
For Market Incumbents:Extend end-to-end solution capabilities by integrating advanced Process Analytical Technology with artificial intelligence for predictive process control. This move counters the threat from specialized technology entrants and addresses the growing demand for self-optimizing production lines. Investment in R&D for continuous biologics manufacturing will capture the fastest-growing segment, particularly in established pharmaceutical production centers like Ireland.
For New Entrants and Emerging Players:Modular, scalable continuous manufacturing skids represent a technology-first wedge into the market. Target the underpenetrated segment of smaller pharmaceutical companies in emerging economies like India, which seek to bypass legacy batch constraints. Offering comprehensive integration support and training services can provide a strong go-to-market angle, reducing technical barriers for new adopters.
For Investors and Strategic Acquirers:Increased regulatory approvals for continuously manufactured biologics is the leading indicator that validates this market's long-term growth trajectory. Target specialized technology providers offering advanced PAT or AI-driven process optimization solutions, or niche Contract Manufacturing Organizations with proven continuous manufacturing lines. These investments offer exposure to a foundational shift in pharmaceutical production. Decision-makers should treat outputs as directional within the stated assumption set.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Biologics | Major pharmaceutical companies will reduce cost of goods for high-value therapies. |
| Platform Integration of AI/ML | Technology providers will enhance predictive process control and minimize deviations. |
| Strategic Partnerships with CMOs | Innovator firms will accelerate drug development and market access. |
| Acquisition of PAT Specialists | Incumbent equipment manufacturers will gain advanced real-time monitoring capabilities. |
| R&D in Advanced Formulation | Pharmaceutical formulators will enable continuous production of complex drug products. |
Research Approach
US FDA filings, European Medicines Agency submissions, and specialized industry reports formed the secondary backbone for this analysis. This was augmented by primary interviews with process engineers, regulatory affairs specialists, R&D directors, and procurement managers across pharmaceutical and Contract Manufacturing Organizations. Bottom-up data collection was triangulated with top-down market validation to ensure accuracy.
A bottom-up analytical lens was applied to size the market by technology, product type, application, and end-user, with top-down validation against overall pharmaceutical industry trends. Segmentation dimensions also included regional regulatory environments and capital investment cycles. Compound annual growth rates were derived from historical trends, identified market drivers, and expert projections. Key forecast inputs included pharmaceutical R&D spending and continuous manufacturing adoption rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under conditions of unforeseen regulatory shifts or major capital investment reluctance. Forecasts reflect assumptions regarding technological advancements and industry adoption rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Equipment
Flexible Manufacturing Systems for Pharmaceutical Industry Market
Pharmaceutical Equipment
Pharmaceutical Automation Market
Pharmaceutical Equipment
Sterile Vials Market
Pharmaceutical Equipment
Europe Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
CMO/CDMO Market
Pharmaceutical Equipment
US and Europe Pharmaceutical Manufacturing Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Latin America Pharmaceutical Glass Packaging Market
Pharmaceutical Equipment
Pharmaceutical Glass Vials and Ampoules Market
Pharmaceutical Equipment
Global Pharmaceutical Membrane Filtration Market
Pharmaceutical Equipment
Asia-Pacific Pharmacy Automation Market
Pharmaceutical Equipment
North America Pharmaceutical Isolator Market
Pharmaceutical Equipment
Global Fill Finish Manufacturing Market
Pharmaceutical Equipment
Vial Adaptors for Reconstitution Drug Market
Pharmaceutical Equipment
ASEAN Contract Development and Manufacturing Organization (CDMO) Market
Pharmaceutical Equipment
Fill-Finish Pharmaceutical Contract Manufacturing Market