
 North America Telecom Power Systems Market | 2026-2036
North America Telecom Power Systems Market Size, Share, and Industry Trends Forecast 2026-2036
North America Telecom Power Systems Market Intelligence
Telecom power engineering talent is bifurcating between legacy AC-diesel expertise and DC-microgrid digital design, creating a workforce gap that equipment vendors must address through training partnerships. Eaton Corp PLC leverages its North American service network to sustain long-term maintenance contracts across rural cell tower portfolios. Cummins Inc. competes by anchoring hybrid generator-battery solutions for remote installations where grid reliability remains uneven. Schneider Electric SE differentiates through integrated software layers that optimize energy dispatch across multi-technology sites.
North America telecom power systems encompass the electrical infrastructure purpose-built to ensure uninterrupted operation of communication networks, typically delivering -48 V DC to radio access equipment or conditioned AC to switching centers with uptime requirements exceeding 99.999%. These systems integrate rectifiers, battery banks, generators, and increasingly fuel cells to bridge grid outages and manage peak loads across geographically dispersed assets. DC Power Systems retain the largest installed base across legacy copper and fiber exchanges, yet Hybrid Power Systems are expanding fastest at greenfield 5G macro sites where renewable coupling and fuel cell integration reduce diesel dependency. Battery Technologies command the deepest margin pools as cell operators negotiate decade-long service agreements for lithium-ion and emerging solid-state replacements.
The Federal Communications Commission shapes tower backup mandates through network reliability directives, while the EPA enforces emissions thresholds that accelerate diesel displacement across California and Texas buildouts. NERC reliability standards and provincial regulators in Ontario and Quebec impose parallel grid-interconnection requirements that favor smart inverter architectures. Stakeholders must monitor how state-level clean energy procurement rules and interconnection queue reforms reshape total cost of ownership calculations for distributed versus centralized power architectures.
Market Dynamics
The North America telecom power systems market is restructuring around 5G densification mandates that require distributed DC power architectures at every macro and small cell site, forcing equipment vendors to abandon centralized rectifier designs in favor of modular, edge-deployable systems.
Growth Catalysts
- FCC Network Reliability Directives:Backup power mandates for wireless infrastructure are accelerating fuel cell and battery deployments across hurricane-prone Gulf Coast corridors and wildfire-vulnerable California counties.
- Hyperscale Data Center Expansion:Cloud operators in Phoenix, Dallas-Fort Worth, and Northern Virginia are commissioning dedicated telecom-grade substations that require synchronized DC power conditioning and thermal management systems.
- Solid-State Battery Maturation:Lithium-metal and ceramic electrolyte chemistries are extending cycle life for remote cell towers, reducing truck-roll maintenance frequency in the Rocky Mountain West and rural Texas.
Market Restraints
- Copper and Lithium Price Volatility:Battery bank and busbar material costs fluctuate with Chilean and Australian mining output, compressing margins on fixed-price ten-year service contracts.
- Generator Set Supply Concentration:Diesel and natural gas genset engine blocks are concentrated among three Midwest manufacturing clusters, creating vulnerability to regional weather disruptions or labor actions.
- Interconnection Queue Delays:ERCOT and CAISO grid connection timelines now exceed 18 months for new substations, delaying powered-shelter deployments and forcing interim mobile generator reliance.
Strategic Opportunities
- Mexico Nearshoring Corridors:Tijuana-Monterrey manufacturing zones lack redundant telecom power infrastructure, creating first-mover openings for integrated fuel cell-battery hybrid systems serving maquiladora operations.
- EPA Diesel Phase-Out Incentives:Emissions reduction credits in California and Texas are subsidizing hydrogen fuel cell retrofits at existing cell tower sites, shortening payback periods for clean power investments.
- AI-Driven Predictive Maintenance:Machine learning models trained on rectifier and battery telemetry are converging with digital twin platforms, enabling condition-based service contracts that replace fixed-interval maintenance schedules.
Industry Challenges
- DC Microgrid Engineering Scarcity:Power electronics specialists fluent in 380V DC bus architectures and silicon carbide inverter design command premium wages, constraining vendor expansion timelines.
- Multi-Technology Site Integration:Hybrid sites combining solar, fuel cell, battery, and legacy diesel require harmonized control systems that interface with disparate vendor SCADA protocols, extending commissioning cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Telecom Power Systems Market |
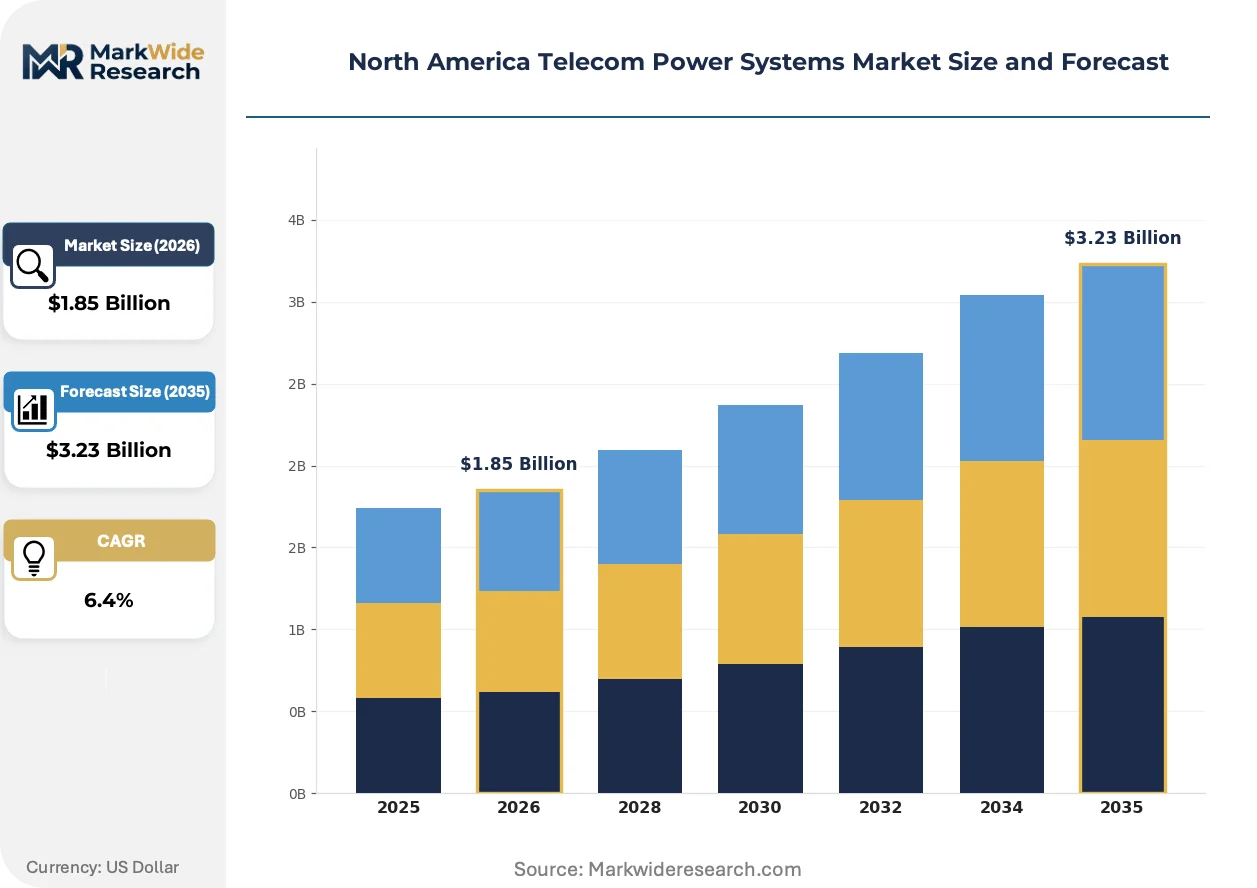
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DC Power Systems, AC Power Systems, Hybrid Power Systems, UPS Systems End User: Telecom Operators, Internet Service Providers, Data Centers, Enterprises Technology: Battery Technologies, Fuel Cells, Inverters, Smart Grid Solutions Deployment: On-Premises, Cloud-Based, Distributed, Centralized |
| Companies Covered | Eaton Corp PLC, Cummins Inc., Ascot Group, ABB Group, Delta Group, Alpha Technologies, Schneider Electric SE, Corning Incorporated, General Electric, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Telecom Power Systems Market Strategic Shifts & Innovations
Modular power electronics and software-defined energy management are converging to collapse the traditional boundary between telecom power and grid-scale storage, enabling cell sites to function as bidirectional grid assets rather than passive loads.
Lithium iron phosphate battery racks with integrated battery management systems are decomposing the legacy -48V DC plant architecture into containerized, hot-swappable modules. Verizon and T-Mobile are specifying these for greenfield 5G builds in the Southwest, where ambient temperatures degrade conventional valve-regulated lead-acid batteries. This modularity is compressing site engineering timelines from weeks to days while enabling remote capacity upgrades without truck rolls.
California's SB 100 clean electricity mandates and accompanying CPUC rulings are prohibiting new diesel generator permits for telecom facilities in designated air quality management districts. The industrial consequence is a forced technology pivot toward hydrogen fuel cells and extended-duration battery storage at switching centers in Los Angeles and San Diego metro areas. Rural carriers in the Central Valley are responding by clustering sites to share centralized fuel cell installations, creating mini-grids that reduce per-site capital requirements.
Carrier procurement teams are consolidating vendor relationships around integrated power-thermal-software stacks rather than discrete component sourcing. Tier-1 mobile network operators now require single-contract accountability for rectifiers, batteries, cooling, and energy management platforms, displacing the historical practice of separate awards for each subsystem. This concentration is most visible in AT&T and Bell Canada RFPs for edge compute node deployments, where thermal and electrical performance guarantees are bundled under unified service level agreements.
North America Telecom Power Systems Market Segmentation
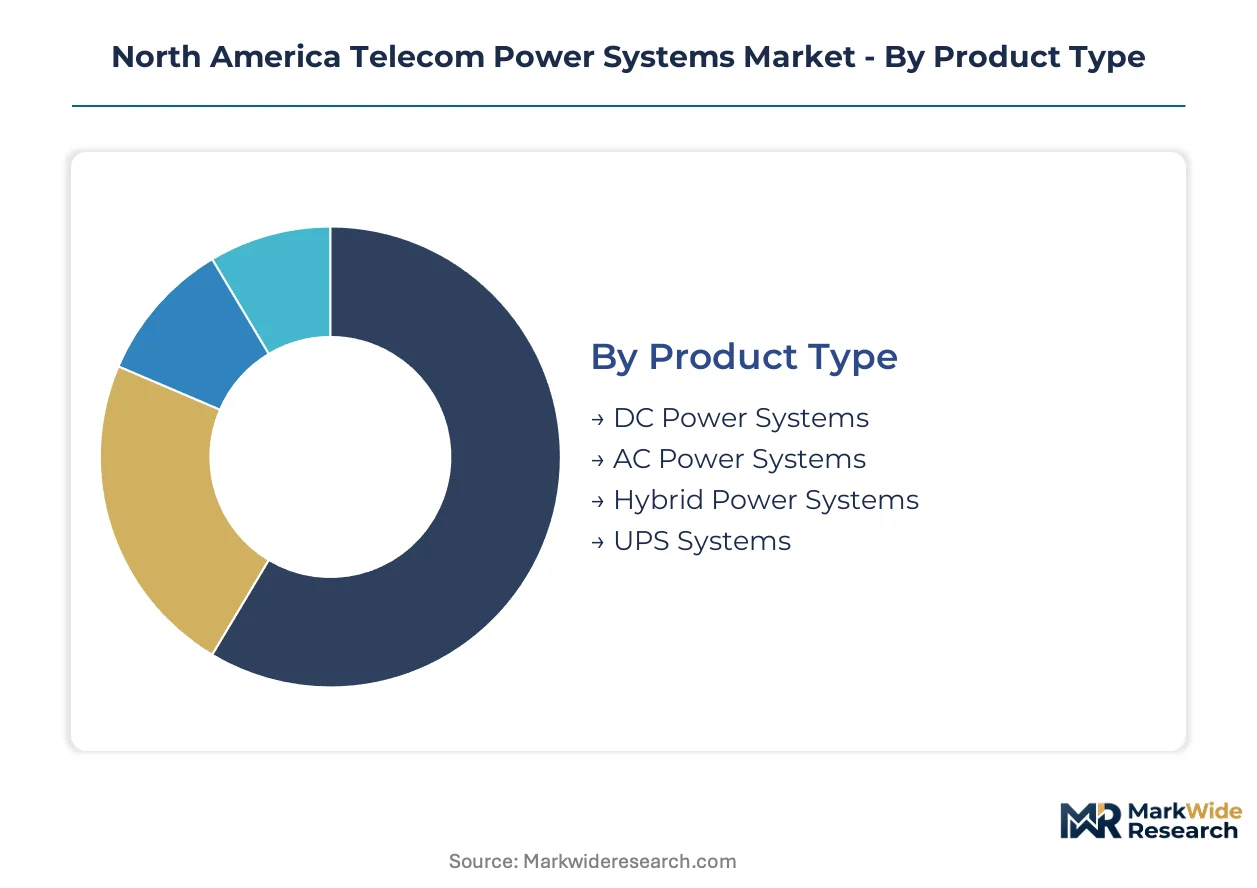
Telecom power systems in North America fragment across competing architectures that carriers must reconcile with legacy infrastructure, 5G densification mandates, and carbon reduction timelines. Understanding segment boundaries reveals where substitution pressure is strongest and where incumbent technologies retain defensive moats.
Product Type:
Hybrid Power Systems face the most acute substitution pressure as fuel cells and extended-duration batteries displace diesel generators at greenfield sites, while DC Power Systems defend their installed base through sunk cost inertia in legacy central offices.
- DC Power Systems:These -48V DC rectifier-battery plants deliver uninterruptible power to radio access equipment and copper/fiber exchanges. Demand concentrates in legacy central offices across the Great Lakes region and northeastern United States, where carriers amortize decades-old infrastructure rather than rip-and-replace.
- Hybrid Power Systems:Integrated solar-fuel cell-battery-diesel architectures optimize dispatch across variable renewable output. Southwestern deployments in Arizona and Texas lead adoption as carriers pursue EPA emissions compliance and diesel phase-out incentives.
- AC Power Systems:Conditioned alternating current for switching centers and data halls.
- UPS Systems:Double-conversion and line-interactive topologies for enterprise colocation facilities.
DC Power Systems anchor the volume base while Hybrid Power Systems gain share at the steepest rate.
End User:
Cost tier segmentation separates capital-rich hyperscale deployers from margin-constrained rural carriers, with procurement patterns diverging most sharply between data center operators seeking unified power-thermal stacks and enterprises buying discrete components.
- Telecom Operators:Verizon, AT&T, T-Mobile, and Bell Canada drive specification standards through decade-long service contracts. Their 5G macro site buildouts in California, Texas, and Florida concentrate demand for modular, truck-roll-minimizing architectures.
- Data Centers:Hyperscale cloud operators in Phoenix, Dallas-Fort Worth, and Northern Virginia commission dedicated telecom-grade substations requiring synchronized DC conditioning and thermal management.
- Internet Service Providers:Regional fiber overbuilders and cable operators with distributed hub requirements.
- Enterprises:Private networks and campus installations with lower uptime tier requirements.
Telecom Operators command the specification authority while Data Centers expand capacity most aggressively.
Technology:
Technology segmentation tracks the shift from electrochemical storage to hydrogen-based generation, with margin pools migrating toward battery management systems and fuel cell balance-of-plant as hardware commoditizes.
- Battery Technologies:Lithium iron phosphate dominates new deployments for thermal tolerance in southwestern climates, while lithium-metal chemistries promise extended cycle life for remote Rocky Mountain towers. Solid-state electrolyte development is compressing maintenance intervals.
- Fuel Cells:Proton-exchange membrane and solid oxide systems bridge multi-day outages without diesel emissions. California's SB 100 mandates and EPA incentives accelerate adoption in Los Angeles and San Diego air quality districts.
- Inverters:Silicon carbide power electronics enabling 380V DC bus architectures.
- Smart Grid Solutions:Software-defined energy management and bidirectional grid interconnection.
Battery Technologies retain the deepest installed base while Fuel Cells climb the fastest adoption curve.
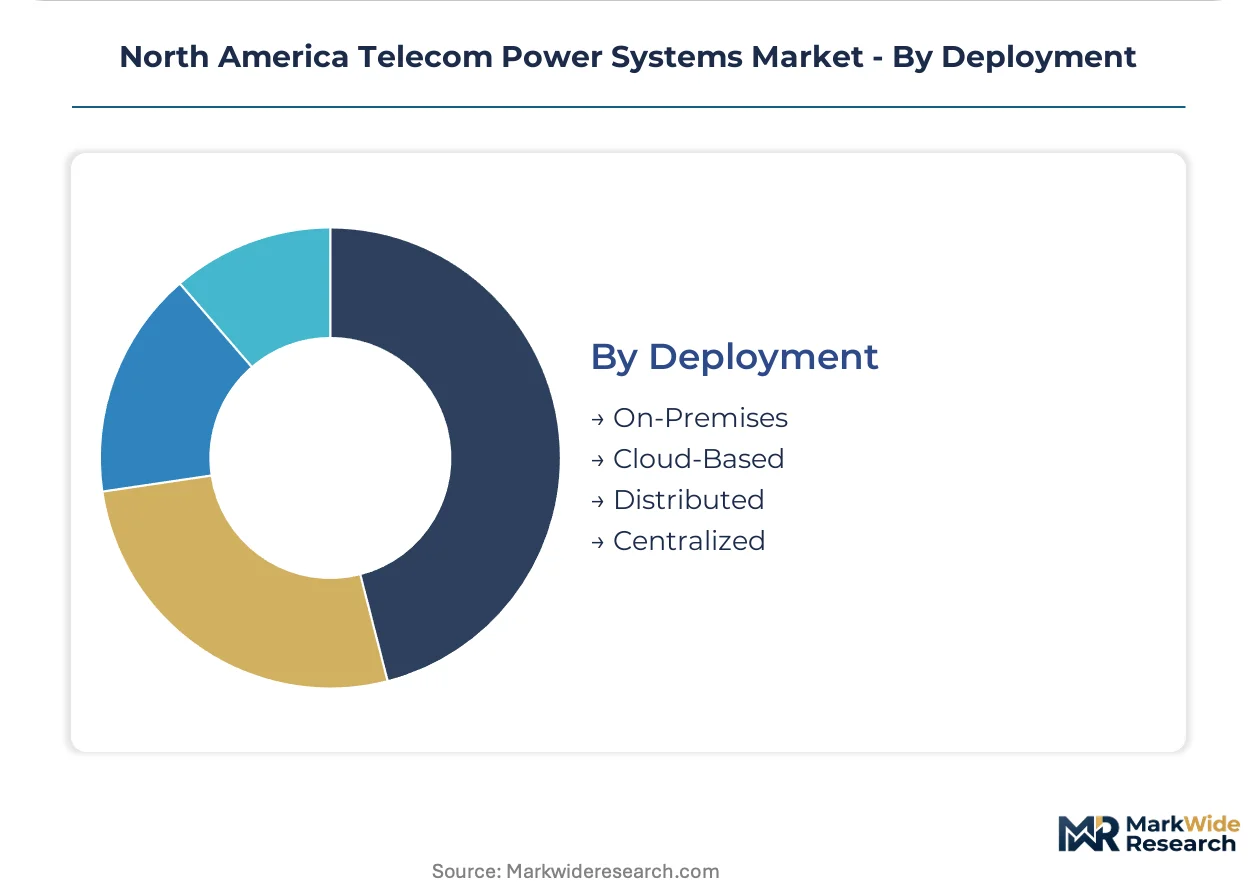
Deployment:
Deployment mode segmentation reflects the tension between centralized efficiency and edge resilience, with distributed architectures gaining ground as interconnection queues delay centralized substation builds.
- Distributed:Containerized power modules at cell towers and edge nodes reduce single points of failure. ERCOT and CAISO interconnection delays exceeding 18 months force carriers toward distributed generation rather than grid-dependent centralized designs.
- On-Premises:Dedicated power plants within carrier facilities or on tower sites.
- Cloud-Based:Remote monitoring and predictive maintenance platforms overlaying physical infrastructure.
- Centralized:Shared substations serving clustered sites in urban corridors.
On-Premises deployment retains the largest footprint while Distributed configurations expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States consumes telecom power systems through hyperscale data center clusters and 5G macro site densification, while Canada and Mexico prioritize rural connectivity and nearshoring corridor infrastructure respectively.
United States
Hyperscale cloud operators in Phoenix, Dallas-Fort Worth, and Northern Virginia commission dedicated telecom-grade substations requiring synchronized DC conditioning. The FCC enforces backup power mandates for wireless infrastructure across hurricane-prone Gulf Coast corridors. Los Angeles and San Diego metro areas pivot toward hydrogen fuel cells as California's SB 100 prohibits new diesel generator permits in designated air quality districts.
Canada
Bell Canada drives specification standards through decade-long service contracts for modular, truck-roll-minimizing architectures. Provincial regulators in Ontario and Quebec impose grid-interconnection requirements favoring smart inverter architectures. Toronto and Vancouver concentrate demand as carriers amortize legacy central office infrastructure rather than rip-and-replace.
Mexico
Tijuana-Monterrey manufacturing zones lack redundant telecom power infrastructure, creating openings for integrated fuel cell-battery hybrid systems. The country's national telecommunications regulator shapes tower backup requirements through network reliability directives. Maquiladora operations in Baja California and Nuevo León spur first-mover deployments of containerized power modules.
Southwest United States
Edge compute nodes and hyperscale data center clusters in Arizona and Texas require dedicated telecom-grade power conditioning and thermal management. The EPA enforces emissions thresholds accelerating diesel displacement across California and Texas buildouts. Rural carriers in the Central Valley respond by clustering sites to share centralized fuel cell installations, creating mini-grids.
North America Telecom Power Systems Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding unified power-thermal-software stacks and the lower tier competing on discrete component sourcing. The structure reflects carrier procurement consolidation around single-contract accountability. Three archetypes dominate: full-stack integrators, hybrid generator-battery specialists, and modular DC power fabricators. Competitive moves concentrate on strategic partnerships for workforce training and portfolio diversification into predictive maintenance platforms.
Among integrated electrical infrastructure providers, Eaton Corp PLC and Schneider Electric SE exemplify the full-stack archetype, anchoring positions through North American service networks and software-defined energy management layers. Cummins Inc. occupies a specialist position representing the hybrid generator-battery segment for remote installations. These three demonstrate how vendor relationships consolidate around bundled performance guarantees rather than discrete subsystem awards.
| Leading Market Players |
|---|
| Eaton Corp PLC |
| Cummins Inc. |
| Ascot Group |
| ABB Group |
| Delta Group |
| Alpha Technologies |
| Schneider Electric SE |
| Corning Incorporated |
| General Electric |
| Others |
Cost & Logistics Intelligence
Capacity utilization at Midwest genset manufacturing clusters shapes price floors across the North America telecom power systems market, concentrating supply leverage among legacy engine block producers while lithium-ion cell imports from South Korean and Chinese gigafactories introduce cost volatility into battery bank pricing.
Pricing Analysis
Long-term service contracts dominate procurement, with carriers like Verizon and AT&T negotiating decade-long agreements that lock in maintenance-inclusive pricing for modular DC power systems. Price differentiation rests on thermal performance certification tiers and geographic service density, with Southwest deployments commanding premiums for ambient-temperature-rated lithium iron phosphate racks. Cost compression in battery technologies is intensifying because Chilean and Australian mining output fluctuates, squeezing margins on fixed-price agreements. Rural carriers exhibit highest price sensitivity, while hyperscale data center operators absorb premium pricing for unified power-thermal-software stacks.
Supply Chain Analysis
Inbound logistics costs through the Port of Long Beach and Vancouver gateway terminals constrain just-in-time delivery of silicon carbide power electronics from Taiwanese foundries. Manufacturing concentration in China, South Korea, and Japan feeds lithium-ion cell and battery management system production. Copper busbar and rare earth magnet dependencies rest on Chilean mining and Chinese refining operations. Single-source vulnerability concentrates in semiconductor-grade silicon carbide substrates. Distribution runs through carrier-direct procurement channels and integrated equipment vendor service networks rather than traditional distributor tiers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics now governs competitive advantage as carriers consolidate vendor relationships around interoperable energy management software layers rather than discrete hardware sourcing.
For Market Incumbents: Consolidate service network density across rural tower portfolios to defend against modular DC power fabricators offering remote predictive maintenance platforms. Deepen backward integration into battery management system firmware development to capture margin pools migrating from hardware commoditization. Prioritize UL 9540A certification investment for lithium-ion thermal runaway testing to maintain specification authority in California SB 100 compliance zones. For New Entrants and Emerging Players: UL 1973 certification fast-tracks market entry for solid-state battery startups targeting Rocky Mountain West cell towers where extended cycle life reduces truck-roll frequency. White-space concentrates in Mexico's Tijuana-Monterrey corridor where maquiladora operations lack redundant telecom infrastructure. Target distributed fuel cell-battery hybrid deployments at clustered edge compute nodes. Pursue direct OEM partnerships with tower companies rather than carrier procurement channels to bypass incumbent service contract lock-in. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-stack integrators with decade-long maintenance contracts across Southwest 5G buildouts. Long-term viability favors vendors with software-defined energy management layers that enable bidirectional grid interconnection revenue streams. Acquisition targets should demonstrate fuel cell balance-of-plant integration capabilities and NERC CIP cybersecurity certification. Monitor EPA diesel phase-out incentive allocation velocity as inflection signal for clean power investment payback compression.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Energy Management Platform | Enables AT&T and Bell Canada to optimize dispatch across solar-fuel cell-battery-diesel hybrid sites through unified SCADA interfaces. |
| Fuel Cell Balance-of-Plant Integration | Positions vendors for California SB 100 compliance mandates prohibiting new diesel generator permits in Los Angeles air quality districts. |
| Predictive Maintenance Service Contract | Replaces fixed-interval truck rolls with AI-driven telemetry analytics for Verizon's Southwest lithium iron phosphate deployments. |
| Solid-State Battery Thermal Certification | Accelerates UL 9540A testing investment to capture extended-cycle-life specifications for remote Rocky Mountain towers. |
| Mexico Nearshoring Corridor Infrastructure | Addresses redundant power gaps at Tijuana-Monterrey maquiladora clusters through containerized fuel cell-battery hybrid modules. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FCC network reliability directives, EPA emissions filings, and carrier procurement disclosures, with input from telecom power engineering directors, tower company procurement leads, EPC contractors specializing in distributed generation, and battery system integration specialists. Bottom-up equipment shipment data triangulates against top-down carrier capex allocation patterns tracked through SEC filings and hyperscaler infrastructure spend disclosures.
Segmentation dimensions modeled span product architecture, end-user tier, electrochemical versus hydrogen-based generation technology, and deployment mode across the projection horizon. CAGRs derive from installed base replacement cycles, 5G densification mandates, and diesel phase-out regulatory timelines. Forecast inputs incorporate ERCOT and CAISO interconnection queue dynamics, lithium carbonate price volatility indices, and solid-state battery commercialization trajectories.
Underlying assumptions cover sustained FCC backup power enforcement, EPA emissions threshold tightening, and carrier carbon reduction commitment durability, with deviation risk concentrated in interconnection queue reform timing and fuel cell hydrogen supply chain maturation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power Systems
Power Electronics Market
Power Systems
Global Plasma Generators Market
Power Systems
Asia-Pacific IGBT and Super Junction MOSFET Market
Power Systems
Thermoelectric Assemblies Market
Power Systems
HVDC Converters Market
Power Systems
Integrated Gate Commutated Thyristors (IGCT) Market
Power Systems
High Voltage Direct Current Power Supply Market
Power Systems
Embedded Power Generation Market
Power Systems
DC Stabilized Power Supply Market
Power Systems
Battery Cyclers Market
Power Systems
Medium Voltage Drives Market
Power Systems
Global DC Power Supply Module Market
Power Systems
Global Rugged Power Supply Market
Power Systems
Series Reactor Market
Power Systems
Pulse Generator Market
Power Systems
Global Uninterruptible Power Supply (UPS) Market