
 Memory Integrated Circuits (IC) Market | 2026-2036
Memory Integrated Circuits (IC) Market Size, Share, and Industry Trends Forecast 2026-2036
Memory Integrated Circuits (IC) Market Foresight
The capital-intensity divergence between foundry-dependent and vertically integrated players is redrawing competitive boundaries in memory manufacturing. Samsung Electronics leverages captive wafer supply to sustain margin control across DRAM and NAND flash cycles. SK Hynix anchors its position through advanced packaging investments in South Korea. Micron Technology competes via U.S.-based fab expansion and technology leadership in high-bandwidth memory architectures.
Memory integrated circuits are semiconductor devices that store digital data through charge retention in capacitors or floating-gate transistors, with specifications ranging from nanosecond access times in SRAM to multi-bit-per-cell density in 3D NAND flash. These components serve as the primary data retention layer in computing systems, enabling real-time processing, persistent storage, and cache hierarchies across electronic devices. DRAM remains the dominant revenue pool in data center and consumer computing applications, while flash memory commands premium positioning in automotive and enterprise storage segments where density and endurance requirements are escalating. The application split between consumer electronics and automotive is widening as vehicle architectures adopt zonal computing with localized memory subsystems.
The U.S. CHIPS and Science Act, South Korea's K-Semiconductor Belt strategy, and China's dual carbon goals are reshaping where memory fabrication capacity localizes and how equipment procurement flows across borders. REACH and RoHS compliance in Europe constrain material selections in packaging and substrate manufacturing, adding qualification overhead for suppliers serving EU automotive OEMs. Stakeholders must monitor how export control classifications on deposition and etching equipment redirect capacity buildout timelines across competing geographies.
Market Dynamics
High-bandwidth memory architectures are compressing design cycles and forcing foundry-dependent players to accelerate packaging co-investment or surrender margin control to vertically integrated competitors with captive wafer supply.
Growth Catalysts
- AI Inference Workloads:Data center operators are expanding memory deployments to support generative AI model serving, creating sustained pull for high-capacity DRAM modules and HBM stacks.
- K-Semiconductor Belt:South Korea's national strategy channels public capital into advanced packaging R&D and cleanroom infrastructure, reinforcing Seoul's memory fabrication leadership.
- EU Chips Act:European subsidy frameworks and local content rules are redirecting equipment procurement flows toward regional memory pilot lines and automotive-qualified packaging facilities.
Market Restraints
- Deposition Equipment Export Controls:Cross-border restrictions on atomic layer deposition and etching tools are extending capacity buildout timelines for non-domestic memory fabs.
- Fluorinated Gas Supply Concentration:Etching chemistry production clusters in East Asia create input cost volatility and supply interruption exposure for European and North American memory packaging operations.
- Cell Scaling Physics:Charge interference between adjacent floating gates in sub-15nm NAND flash is forcing costly architectural pivots toward 3D stacking without proportional bit-cost reduction.
Strategic Opportunities
- Zonal Vehicle Architectures:Automotive OEMs are localizing memory subsystems at the edge of domain controllers, opening specification windows for automotive-grade LPDDR and GDDR components.
- Advanced Packaging Convergence:Hybrid bonding and through-silicon via integration are enabling memory-logic stacking that reduces power budgets for mobile and edge AI processors.
- India PLI Scheme:Production-linked incentives for semiconductor assembly and test are attracting memory packaging investments targeting domestic electronics manufacturing and export markets.
Industry Challenges
- Process Integration Talent Gap:Shortages of engineers with combined expertise in front-end wafer processing and advanced packaging assembly are constraining yield ramp rates at new memory fabs.
- Automotive Qualification Timelines:AEC-Q100 stress testing and PPAP documentation requirements extend product approval cycles to 18-24 months, misaligning memory roadmaps with vehicle platform launches.
- Legacy DDR Migration Friction:Data center operators face socket compatibility and validation overhead when transitioning from DDR4 to DDR5 infrastructure, slowing refresh cadences.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Memory Integrated Circuits (IC) Market |
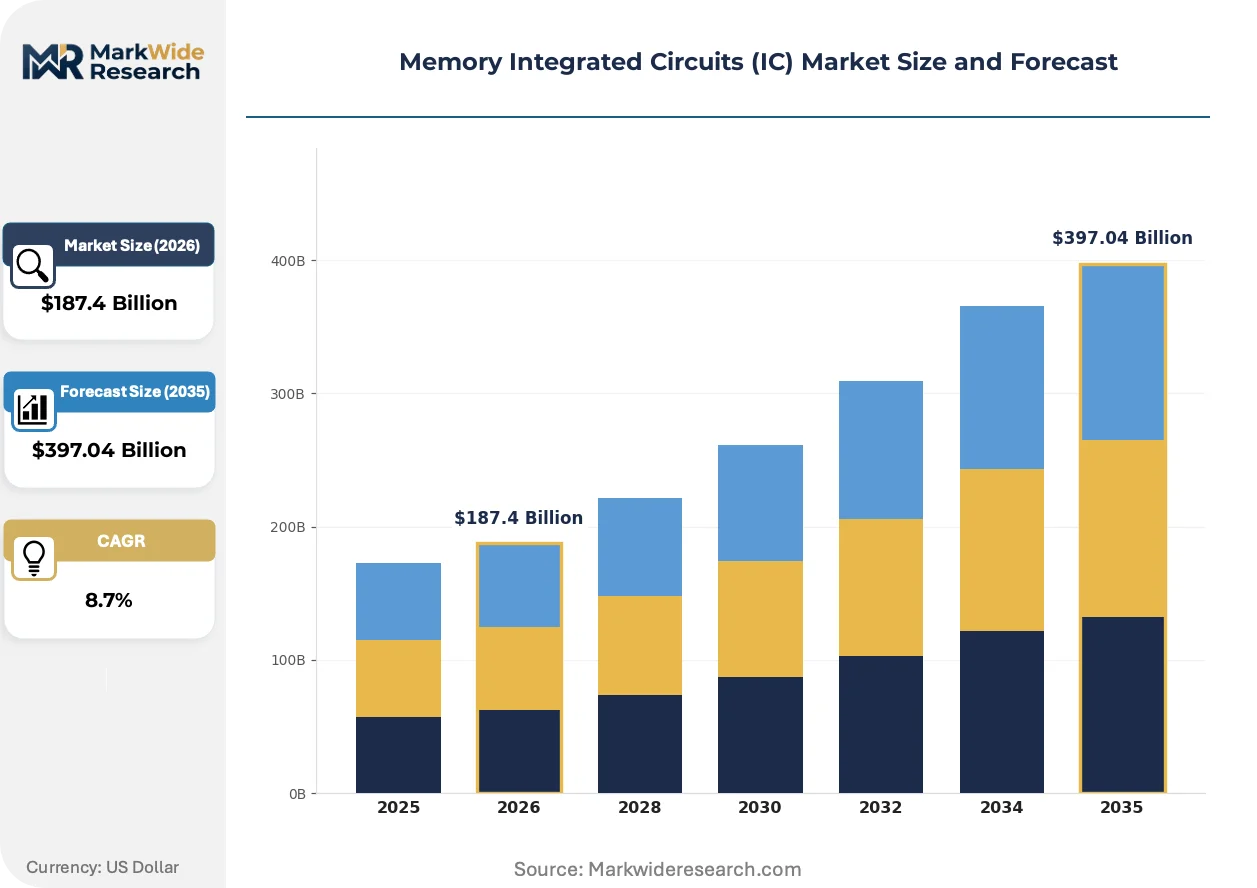
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: DRAM, SRAM, Flash Memory, EEPROM Technology: CMOS, BiCMOS, Semiconductor, Hybrid Application: Consumer Electronics, Automotive, Telecommunications, Computing End User: OEMs, Data Centers, Retailers, Telecom Providers |
| Companies Covered | Samsung Electronics, SK Hynix, Micron Technology, Kioxia Holdings Corporation, Western Digital, Intel Corporation, Nanya Technology Corporation, Macronix International, Winbond Electronics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Memory Integrated Circuits (IC) Market Shifts & Advancements
Memory technology trajectories are diverging between density-maximizing 3D NAND architectures and bandwidth-optimized HBM stacks, with packaging innovation becoming the primary competitive battlefield.
3D NAND flash is miniaturizing through vertical layer stacking rather than lateral cell shrinking, with manufacturers now exceeding 200 active layers per die. Enterprise storage arrays and cloud object storage tiers are absorbing these higher-density components at accelerated procurement cadences. This vertical scaling is miniaturizing the physical footprint of petabyte-scale storage systems while compressing cost-per-bit curves for archival workloads.
REACH and RoHS compliance frameworks in Europe are constraining substrate material selections and solder alloy compositions in memory module manufacturing. Automotive OEMs serving EU markets must document full material declarations through supply chain tiers, adding qualification overhead for memory suppliers. Packaging houses are responding by migrating to halogen-free substrates and tin-silver-copper bump metallurgies that satisfy ECHA substance restrictions.
Hyperscale buyers are consolidating procurement authority into centralized technical sourcing functions that negotiate direct with memory manufacturers rather than through distribution intermediaries. Channel partners serving mid-market enterprise and industrial segments are losing volume tier pricing access as a result. This concentration is most visible in North American and Western European data center buildouts, where three to five cloud operators now direct the majority of high-capacity DRAM demand.
Memory Integrated Circuits (IC) Market Segmentation
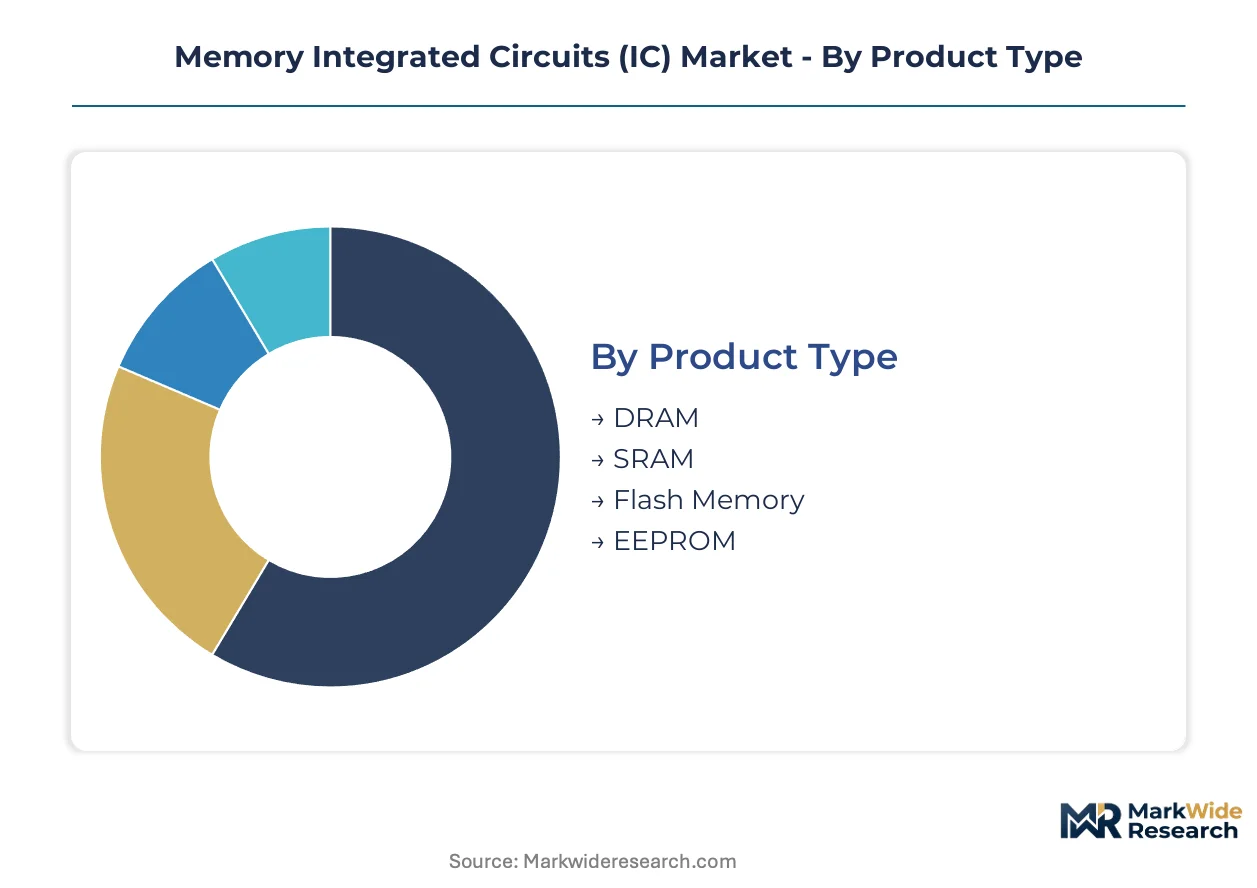
Memory IC segmentation reveals how margin pools shift between commodity DRAM cycles and premium HBM architectures. Understanding these divides exposes where technology leadership translates into pricing power versus where volume scale dominates competitive position.
Product Type:
Margin concentration sits in high-bandwidth memory stacks where packaging complexity creates defensible differentiation, while commodity NAND and DRAM operate on wafer cost efficiency.
- DRAM:Dynamic random-access memory stores each bit in a separate capacitor-transistor pair, refreshing charge thousands of times per second to retain data. Data center operators in South Korea and the United States are expanding deployments for AI inference clusters, though DDR5 migration friction and socket incompatibility slow refresh cycles.
- Flash Memory:Non-volatile storage using floating-gate transistors retains data without power, with 3D NAND architectures now exceeding 200 vertical layers per die. Enterprise storage arrays and cloud object storage tiers in Germany and Japan absorb these higher-density components at accelerated procurement cadences despite cell scaling physics challenges below 15nm.
- SRAM:Static RAM uses six-transistor bistable latching circuits for nanosecond access speeds without refresh overhead. Cache hierarchies in high-performance computing processors and network switches in Singapore and Taiwan drive specialized demand for these low-density, high-speed cells.
- EEPROM:Electrically erasable programmable read-only memory enables byte-level write endurance for configuration storage. Automotive ECUs and industrial control systems across France and Italy specify these components for firmware retention through power cycles.
The dominant share belongs to DRAM, while Flash Memory is closing the gap fastest through 3D layer stacking density gains.
Technology:
Process node distribution determines capital efficiency, with mature CMOS nodes serving high-volume segments and hybrid integrations capturing premium mobile and AI processor sockets.
- CMOS:Complementary metal-oxide-semiconductor technology pairs n-type and p-type MOSFETs for low static power consumption, dominating mainstream memory fabrication. Foundries in South Korea and the United States run these processes at maximum wafer throughput for commodity DRAM and NAND output.
- Semiconductor:Broad category encompassing silicon-based memory fabrication with doped substrates and epitaxial growth. Legacy production lines in Japan and Malaysia continue serving industrial and automotive qualified memory at extended lifecycles.
- BiCMOS:Bipolar-CMOS integration combines high-speed bipolar transistors with CMOS density for specialized interface applications. RF front-end modules and high-speed SerDes in telecommunications infrastructure specify BiCMOS-integrated memory buffers.
- Hybrid:Heterogeneous integration stacks memory dies with logic through through-silicon vias and hybrid bonding. Advanced packaging houses in South Korea and the United States are expanding capacity for HBM and mobile processor memory-logic combinations.
CMOS commands the installed base, though Hybrid integration is expanding most quickly through AI accelerator memory stacking requirements.
Application:
Automotive qualification timelines and zonal architecture shifts are restructuring demand patterns away from consumer electronics concentration toward vehicle-edge computing specifications.
- Automotive:Zonal computing architectures localize memory subsystems at domain controller edges, requiring AEC-Q100 qualified components. OEMs in Germany and Japan specify automotive-grade LPDDR and GDDR for ADAS and infotainment clusters, though 18-24 month PPAP documentation cycles misalign roadmaps with platform launches.
- Computing:Data center and enterprise server infrastructure consumes high-capacity DIMMs and persistent memory modules. Hyperscale operators in the United States and Ireland negotiate direct procurement contracts, bypassing distribution intermediaries for volume tier pricing access.
- Consumer Electronics:Smartphones, tablets, and wearables drive mobile LPDDR and embedded flash demand. Assembly operations in Vietnam and India absorb these components for export manufacturing, though handset refresh cycles have elongated post-pandemic.
- Telecommunications:Baseband processing and routing infrastructure requires high-reliability memory for 5G and fiber backhaul. Network equipment deployments in Finland and Sweden emphasize extended temperature range specifications for outdoor installations.
Computing retains the largest revenue pool, while Automotive is gaining share fastest through electrification and software-defined vehicle transitions.
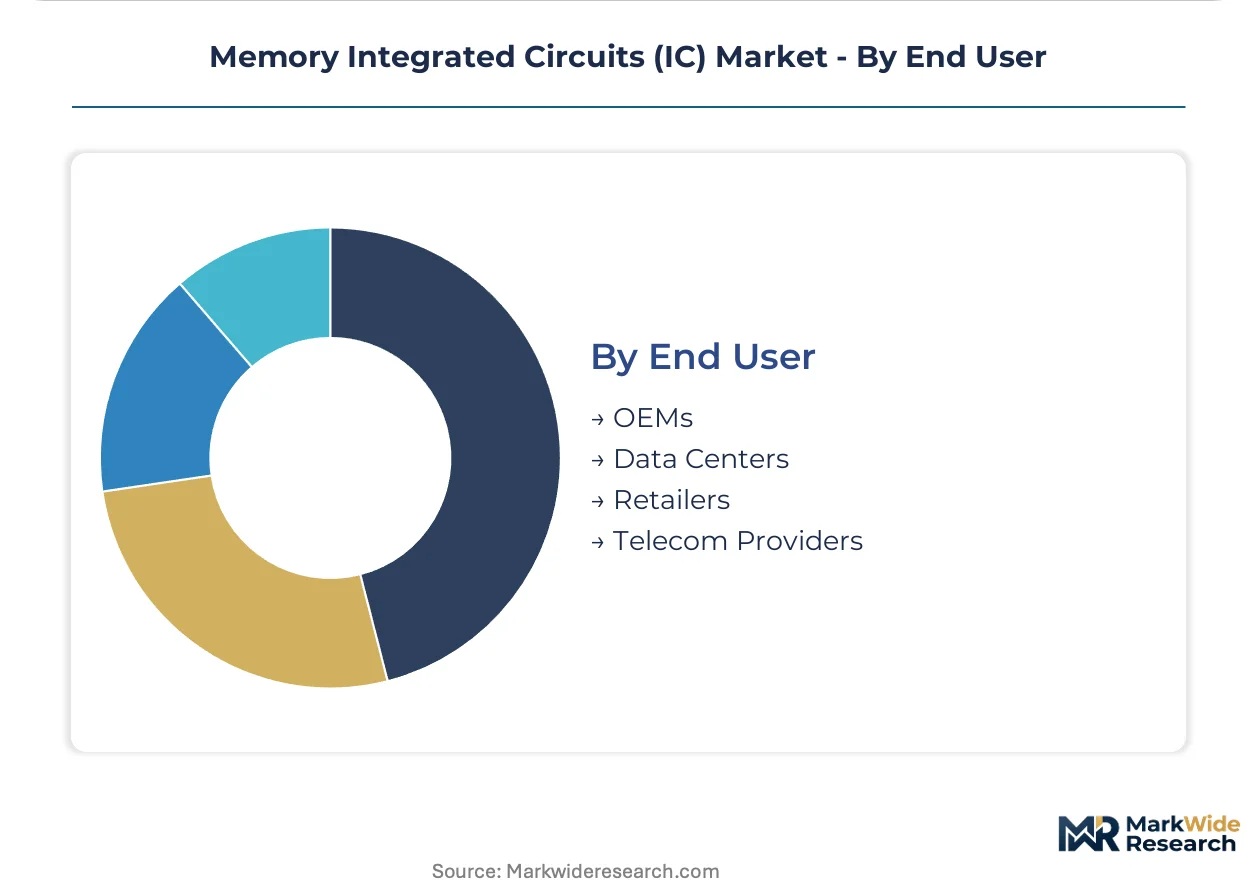
End User:
Procurement authority consolidation into technical sourcing functions has fragmented channel access, with direct manufacturer relationships displacing traditional distribution for high-volume segments.
- Data Centers:Hyperscale and colocation operators command customized memory configurations with direct thermal and power specifications. Facilities in Virginia, Texas, and Frankfurt specify high-capacity DDR5 and HBM2E for AI training and inference workloads.
- OEMs:Original equipment manufacturers across server, automotive, and industrial verticals negotiate long-term supply agreements with qualification requirements. Japanese and German OEMs enforce strict change notification protocols for automotive and medical device memory sockets.
- Telecom Providers:Network operators specify memory for base stations, core routers, and edge computing nodes. 5G infrastructure buildouts in South Korea and Australia drive demand for industrial temperature grade components with decade-long supply commitments.
- Retailers:Distribution and e-commerce channels serve upgrade markets and mid-market enterprise segments. Channel partners in the United Kingdom and Canada face compressed margins as hyperscale direct procurement concentrates volume pricing authority upstream.
Data Centers hold the dominant procurement volume, while OEMs are tightening supplier integration fastest through co-development partnerships for next-generation vehicle and server platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in South Korean fabrication clusters while U.S.-based expansion absorbs subsidy inflows without matching cost structures. Memory procurement authority tilts toward data center operators in Virginia and Frankfurt, compressing margin capture for packaging houses in Southeast Asia.
United States
Hyperscale data center buildouts in Virginia and Texas drive HBM and DDR5 procurement at volume tiers. The CHIPS and Science Act channels federal capital into domestic cleanroom infrastructure, extending depreciation timelines for new fabrication assets. Micron Technology anchors advanced packaging expansion in Idaho and New York, targeting AI accelerator memory sockets with captive wafer supply.
South Korea
Samsung Electronics and SK Hynix command global DRAM and NAND output through vertically integrated Pyeongtaek and Icheon complexes. Seoul's K-Semiconductor Belt strategy fuses public R&D funding with tax incentives for hybrid bonding equipment procurement. The Seoul Capital Area concentrates advanced packaging capacity for HBM3E stacks serving NVIDIA and AMD accelerator demand.
China
Yangtze Memory Technologies and ChangXin Memory Technologies expand domestic 3D NAND and DRAM output despite deposition equipment access constraints. Beijing's dual carbon goals impose energy intensity caps on new fabrication facilities, redirecting capacity toward renewable-powered zones. The Yangtze River Delta cluster around Shanghai maintains legacy packaging operations for consumer electronics assembly.
Japan
Kioxia Holdings anchors 3D NAND production in Yokkaichi and Kitakami through joint venture structures with Western Digital. METI's semiconductor revitalization subsidies target memory-specific etching chemistry and wafer bonding equipment procurement. The Kyushu region hosts specialized foundry capacity for automotive-qualified EEPROM and embedded flash components.
Germany
Automotive OEMs in Stuttgart and Munich specify AEC-Q100 qualified LPDDR for zonal computing architectures. The EU Chips Act redirects subsidy eligibility toward automotive-grade memory packaging and test facilities. Dresden's Silicon Saxony cluster attracts backend investments for European data center DIMM module assembly.
Memory Integrated Circuits (IC) Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with vertically integrated fabricators controlling wafer cost structures while foundry-dependent competitors surrender margin to packaging co-investment demands. The market consolidates around three memory categories—DRAM, NAND flash, and specialty non-volatile—each with distinct capital intensity thresholds. Two strategic archetypes dominate: captive wafer producers with in-house packaging, and fabless designers outsourcing front-end fabrication. Capacity expansion and advanced packaging co-investment represent the dominant competitive moves, with players racing to secure hybrid bonding and through-silicon via capacity before supply constraints harden.
Among vertically integrated fabricators, Samsung Electronics, SK Hynix, and Micron Technology occupy positions that exemplify the technology-cost bifurcation. Samsung Electronics represents the archetype of captive wafer supply sustaining margin control across memory cycles. SK Hynix anchors advanced packaging specialization within the HBM tier. Micron Technology exemplifies geographic diversification strategy through U.S.-based fab expansion targeting subsidy-qualified capacity.
| Leading Market Players |
|---|
| Samsung Electronics |
| SK Hynix |
| Micron Technology |
| Kioxia Holdings Corporation |
| Western Digital |
| Intel Corporation |
| Nanya Technology Corporation |
| Macronix International |
| Winbond Electronics Corporation |
| Others |
Supply & Pricing Matrix
Wafer-scale economies at Pyeongtaek and Icheon complexes compress marginal production costs for vertically integrated fabricators, concentrating supply-side pricing power in South Korean DRAM and NAND output while forcing foundry-dependent competitors into packaging co-investment or margin surrender.
Pricing Analysis
The customization-premium spread between configured-to-order HBM stacks and standard DDR5 modules operates on contract-based long-term offtake structures with volume tier discounts. Price differentiation hinges on AEC-Q100 automotive certification grade and hyperscale direct procurement scale, with cloud operators negotiating the steepest discounts. Cost compression in commodity NAND is intensifying because 3D layer stacking has outpaced bit-cost reduction curves. Data center operators exhibit the lowest price sensitivity due to captive infrastructure requirements, while mid-market retailers face compressed margins from channel bypass.
Supply Chain Analysis
South Korea and Taiwan anchor wafer fabrication for advanced DRAM and logic-on-memory integration, while Japan and the United States supply specialized etching equipment and wafer bonding tools. The chain draws from fluorinated gas chemistries, silicon wafers, and hybrid bonding equipment as critical inputs. Single-source vulnerability concentrates in East Asian etching chemistry production clusters, exposing European and North American packaging operations to supply interruption. Distribution runs through direct manufacturer relationships with hyperscale data center operators, displacing traditional channel intermediaries for high-volume segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The memory IC market sits in a cyclical recovery phase, with AI inference workload expansion absorbing excess inventory and tightening wafer supply-demand balances through the projection horizon.
For Market Incumbents: Consolidate advanced packaging capacity in South Korea and the United States before hybrid bonding equipment lead times extend further. Deepen captive wafer supply control through Idaho and New York fab expansions to defend margin position against SK Hynix HBM specialization. Prioritize AEC-Q100 qualification pipelines to capture automotive zonal architecture specifications ahead of 18-24 month PPAP cycles.
For New Entrants and Emerging Players: AEC-Q100 certification fast-track through partnerships with German automotive OEMs opens the most penetrable white-space in automotive-grade LPDDR for zonal computing. Target India's PLI scheme for semiconductor assembly and test to access domestic electronics manufacturing demand and export markets. Pursue co-development agreements with edge AI processor designers as the primary go-to-market angle for memory-logic stacking specialization.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated fabricators with captive wafer supply and long-term hyperscale offtake agreements. Acquisition target archetypes include advanced packaging houses with hybrid bonding capacity and automotive-qualified test facilities. Watch HBM3E supply constraints against NVIDIA and AMD accelerator demand as the inflection indicator for pricing power shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Packaging Capacity Expansion | Hybrid bonding and TSV integration enable HBM stacks for NVIDIA AI accelerators. |
| Automotive Certification Investment | AEC-Q100 qualification opens zonal computing sockets at German OEMs. |
| Geographic Manufacturing Footprint | U.S. fab expansion accesses CHIPS Act subsidies and reduces tariff exposure. |
| Long-term Supply Agreement | Direct hyperscale contracts bypass distribution intermediaries for volume pricing. |
| Backward Integration into Equipment | Etching chemistry captive supply mitigates fluorinated gas concentration risk. |
Research Methodology
A standing panel of memory fab operations directors, hyperscale data center procurement leads, automotive ECU design engineers, and advanced packaging equipment specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against SEC 10-K filings, SEMI equipment shipment data, and customs import records. Bottom-up wafer capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Consistency checks against external benchmarks validated outputs across the analysis window, with segmentation modeling across product type, technology node, application vertical, and end-user procurement archetype. CAGRs derived from equipment shipment trajectories, capital expenditure disclosures, and memory content per server unit trends incorporated AI inference workload scaling and DDR5 migration friction as industry-specific inputs.
The analysis sits within stated boundaries; outcomes outside sustained AI infrastructure investment cycles or relaxed deposition equipment export controls would require recalibration. Forecasts reflect documented assumptions about wafer yield ramp rates and hyperscale procurement consolidation. Recalibration cycles align with material shifts in memory content per accelerator, EU subsidy disbursement schedules, and automotive platform launch cadences.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
IC (Integrated Circuits)
Americas Integrated Circuit (IC) Market
IC (Integrated Circuits)
NFC Reader Ics Market
IC (Integrated Circuits)
Global Application Specific Computer Analog IC Market
IC (Integrated Circuits)
3D Integrated Circuit Market
IC (Integrated Circuits)
Japan Logic Integrated Circuit (IC) Market
IC (Integrated Circuits)
Global Application Specific Industrial Analog IC Market
IC (Integrated Circuits)
Europe Integrated Circuits Market
IC (Integrated Circuits)
Asia Pacific Logic IC Market
IC (Integrated Circuits)
China Analog IC Market
IC (Integrated Circuits)
Taiwan Analog Integrated Circuits Market
IC (Integrated Circuits)
Analog IC Market
IC (Integrated Circuits)
APAC Analog IC Market
IC (Integrated Circuits)
Global 3D Ics Market
IC (Integrated Circuits)
South Korea Integrated Circuits Market
IC (Integrated Circuits)
Global Amplifier and Comparator IC Market
IC (Integrated Circuits)
CMOS Power Amplifier Market